

Renewable Energy Contractor Market Size, Share, and Industry Trends Forecast 2026-2036
Renewable Energy Contractor Market Insights
Modular EPC bundling is restructuring buyer procurement patterns across utility-scale solar and wind deployments. ACCIONA leverages its integrated development-construction-operate model to capture full-lifecycle value on Iberian and Latin American renewables builds. Bechtel anchors its position through massive civil infrastructure capability transferred from fossil power to offshore wind foundation work. Fluor competes by sustaining engineering-intensive project delivery for complex geothermal and hybrid renewable installations in regulated North American markets.
A renewable energy contractor delivers engineered construction services for power-generating assets that harness solar irradiance, wind kinetic energy, biomass combustion, or geothermal heat, typically involving civil works, electrical interconnection, and grid synchronization to achieve commercial operation dates. Solar EPC and wind turbine installation together occupy the dominant share of contractor backlogs, while biomass plant construction retains narrower geographic relevance where feedstock logistics permit viable project economics. Operation and maintenance services within the service offering dimension are expanding faster than standalone construction as asset owners prioritize long-term performance guarantees and availability contracts over lump-sum build-only arrangements.
The US Inflation Reduction Act, administered through IRS guidance and complemented by FERC interconnection rules, mandates domestic content thresholds that reshape contractor supply chain qualification and labor sourcing. EU Green Deal implementation through revised Renewable Energy Directive targets and CE marking for electrical infrastructure sets product standards that non-European contractors must satisfy for market access. Stakeholders must monitor how evolving carbon border adjustment mechanisms and local-content mandates in multiple jurisdictions will reconfigure competitive positioning between regionally rooted contractors and internationally mobile EPC firms.
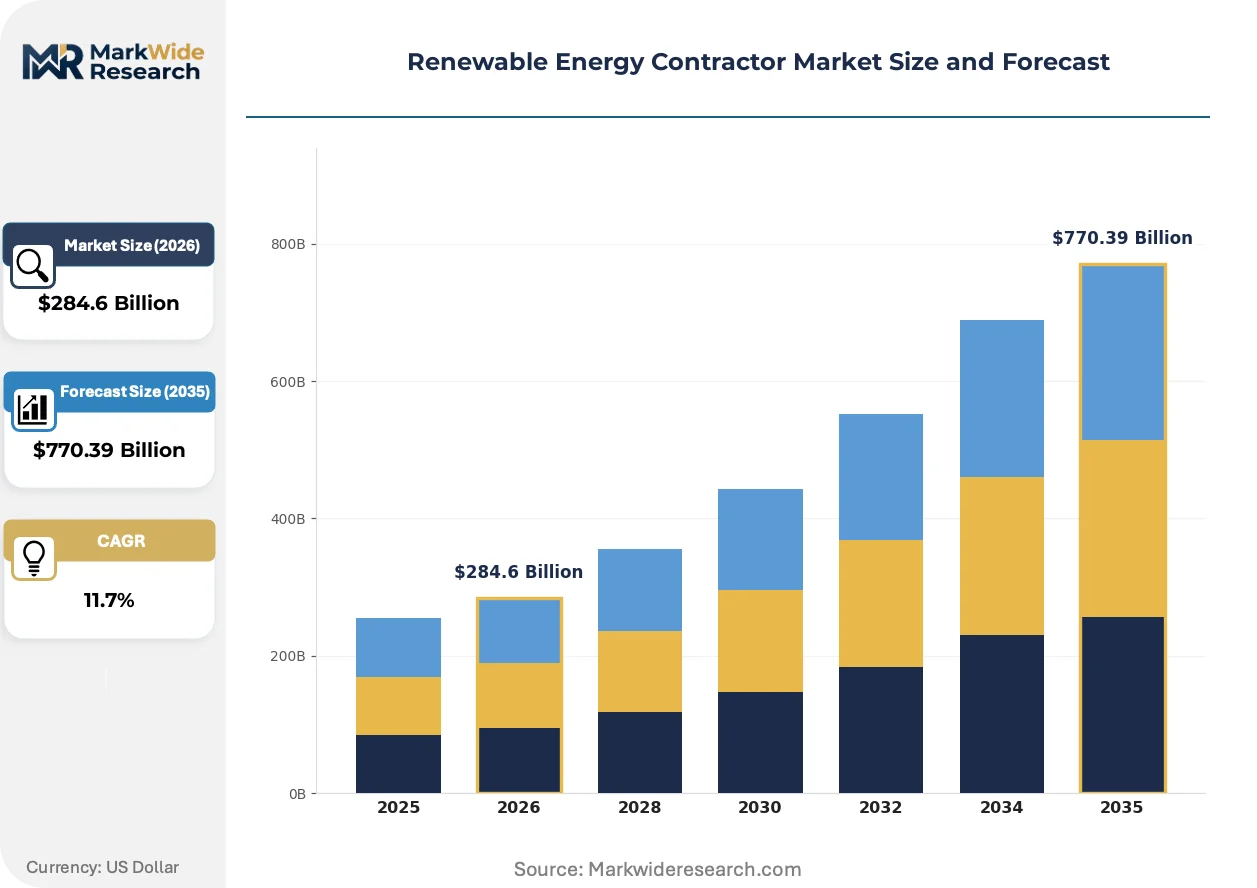
Market Dynamics
Modular EPC bundling is compressing project timelines and collapsing the traditional design-bid-build sequence into single-source accountability, forcing contractors to absorb engineering risk that owners previously retained.
Growth Catalysts
- Domestic content thresholds:The US Inflation Reduction Act's adder credits for domestic steel and manufactured products are redirecting procurement toward contractors with qualified local supply chains.
- Utility-scale solar park tenders:India's national solar mission mandates integrated EPC delivery, eliminating fragmented subcontracting and favoring turnkey-capable contractors.
- Offshore wind foundation complexity:Monopile and jacket fabrication requirements are pulling civil infrastructure specialists from fossil power into renewable marine construction.
Market Restraints
- Electrical steel supply concentration:Grain-oriented electrical steel for transformer cores concentrates in a handful of Asian mills, exposing contractors to input cost volatility and delivery uncertainty.
- Interconnection queue congestion:FERC Order 2023 reforms are not yet clearing the backlog of grid connection requests, delaying commercial operation dates and freezing contractor cash flows.
- Skilled welder scarcity:Specialized wind tower and pressure vessel fabrication requires ASME-certified welders whose training pipelines lag deployment schedules.
Strategic Opportunities
- Hybrid renewable-plus-storage:Co-located solar-wind-battery configurations require integrated EPC capabilities that pure-play solar or wind contractors lack.
- EU Green Deal implementation:Revised Renewable Energy Directive targets and CE marking requirements for electrical infrastructure create compliance service revenue streams for certified contractors.
- Performance-guarantee O&M contracts:Long-term availability warranties let contractors capture lifecycle value beyond construction margins.
Industry Challenges
- Grid code harmonization delays:Inverter and plant controller certification against evolving IEEE 1547 and grid operator interconnection standards extends commissioning timelines.
- Geotechnical uncertainty:Foundation design assumptions for offshore wind often conflict with seabed conditions discovered during piling, triggering costly change orders.
- Supply chain reconfiguration friction:Shifting qualified vendor lists to satisfy local-content mandates disrupts established procurement relationships and qualification timelines.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Renewable Energy Contractor Market Trends and Innovations
Digital twin deployment and prefabrication methods are compressing construction schedules and transferring quality control from job sites to factory floors, altering where contractors add value.
Bifacial solar modules with tracking systems are rewriting energy yield calculations for utility-scale solar EPC contracts. Developers in the southwestern United States and Iberian Peninsula are specifying these configurations to maximize generation density per hectare. This technology is rewriting contractor civil engineering scope, as tracker foundation loads and spacing requirements differ materially from fixed-tilt designs.
The EU's Carbon Border Adjustment Mechanism is imposing embodied carbon reporting requirements on imported steel and aluminum for renewable infrastructure. Contractors sourcing from non-EU mills must now document product-level emissions or face tariff adjustments. European project developers are responding by qualifying domestic and near-shore fabricators ahead of full CBAM implementation.
Asset owners are unbundling construction and O&M procurement, previously awarded as integrated packages. Institutional investors operating wind and solar portfolios are now contracting separate availability-guarantee providers post-construction. This pattern is most visible in North American markets where tax equity structures incentivize rapid asset turnover to yield-focused buyers.
Renewable Energy Contractor Market Segmentation
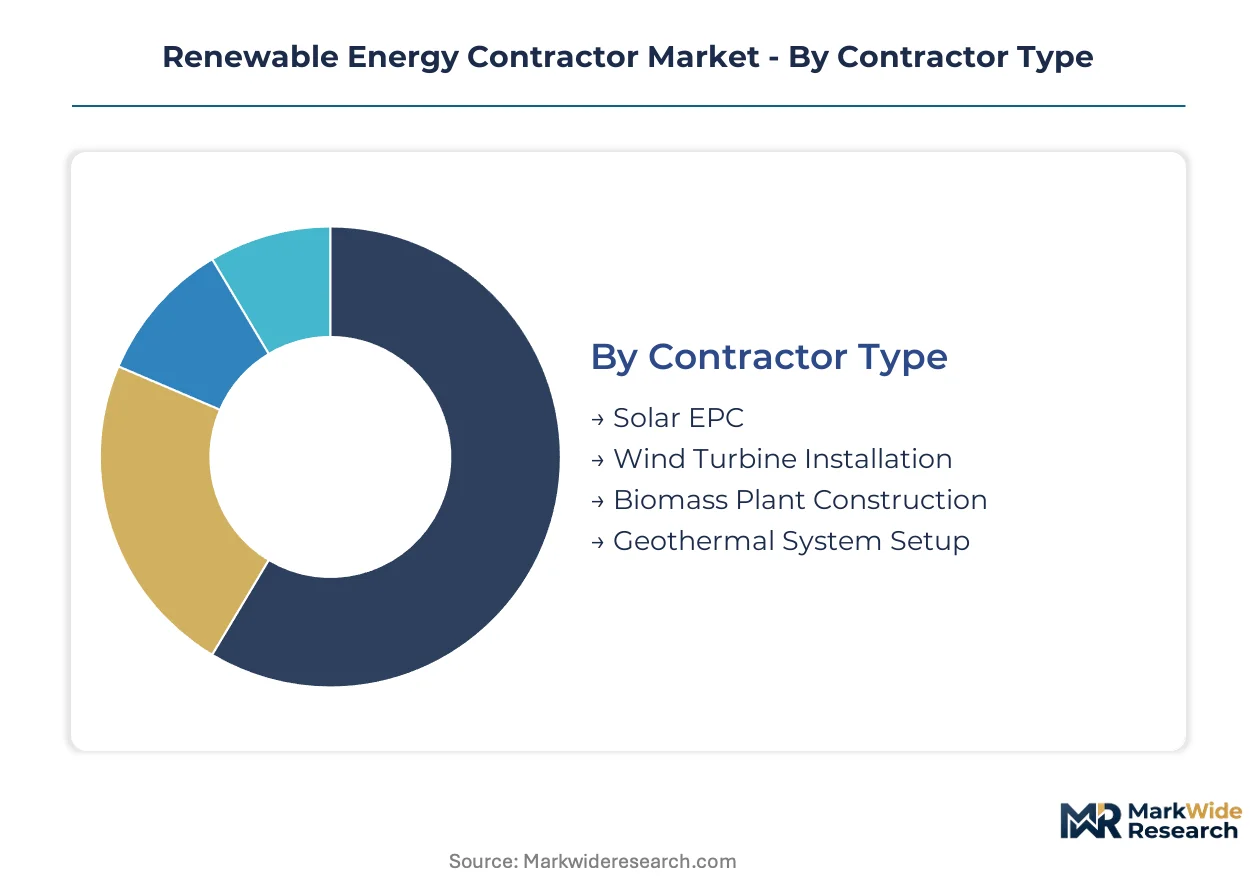
Contractor segmentation reveals how certification burdens, project complexity, and client sophistication stratify competitive positioning across the renewable build cycle. Each dimension carries distinct margin profiles and capability requirements that reshape procurement patterns.
Contractor Type:
Solar EPC and wind turbine installation contractors carry heavier IEC and UL certification loads than biomass or geothermal specialists, reflecting the volume-driven standardization of photovoltaic and onshore wind equipment.
- Solar EPC:Turnkey engineering-procurement-construction delivery for photovoltaic plants, encompassing module mounting, DC/AC conversion, and grid synchronization. Demand concentrates in India's national solar park tenders and US utility-scale procurement, where domestic content adders under the Inflation Reduction Act filter contractor qualification.
- Wind Turbine Installation:Foundation work, tower erection, nacelle placement, and electrical termination for onshore and offshore wind farms. European North Sea developments and Chinese coastal provinces drive demand, with jacket fabrication complexity pulling civil infrastructure contractors from fossil power backgrounds.
- Biomass Plant Construction:Boiler installation, fuel handling systems, and emissions control for organic feedstock combustion. Feedstock logistics constrain viable economics to agricultural belts in Brazil, Southeast Asia, and Nordic forestry regions.
- Geothermal System Setup:Reservoir drilling, binary cycle plant construction, and reinjection well completion for hydrothermal resources. Regulatory concentration around the Salton Sea in California and volcanic zones in Iceland and Kenya shapes contractor specialization.
Solar EPC sits at the top of the volume ranking, with wind turbine installation climbing the fastest as offshore foundation complexity expands addressable project scope.
Service Offering:
Service tiers separate by margin sustainability, with lifecycle contracts commanding premium pricing over transactional construction delivery.
- Design & Engineering:Front-end engineering design, geotechnical assessment, and electrical system modeling. North American utilities require IEEE 1547-compliant inverter and plant controller certification, extending study timelines.
- Procurement:Long-lead equipment sourcing, vendor qualification, and logistics coordination. EU Carbon Border Adjustment Mechanism documentation requirements for imported steel and aluminum add compliance overhead.
- Project Management:Schedule control, cost management, and subcontractor coordination. India's CEA mandates integrated project delivery for national solar tenders, collapsing traditional fragmented subcontracting.
- Operation & Maintenance:Long-term availability warranties, predictive maintenance, and performance optimization. Institutional investors in North American tax equity structures now unbundle O&M from construction, creating standalone contract opportunities.
- Consulting:Feasibility studies, permitting support, and grid interconnection strategy. FERC Order 2023 reforms around interconnection queue management reshape consulting demand timing.
Operation & Maintenance commands the highest margin expansion trajectory, with procurement absorbing the greatest cost volatility exposure.
Project Scale:
Scale determines contractor capital intensity and risk retention, with utility-scale builds requiring balance sheet capacity unavailable to smaller regional players.
- Utility-Scale:Projects exceeding 100 MW capacity with transmission-level interconnection. Bundled EPC procurement dominates as developers seek single-source accountability for commercial operation date guarantees.
- Commercial:Behind-the-meter installations for industrial and corporate offtakers. C&I solar plus storage configurations in the US Southwest drive integrated contractor capability requirements.
- Residential:Distributed rooftop systems under net metering or feed-in tariff structures. Permitting fragmentation across US state and municipal jurisdictions fragments contractor addressable markets.
- Community-Based:Shared solar or wind facilities serving multiple subscribers. Virtual net metering policy availability in states like New York and Colorado determines market viability.
- Off-Grid:Standalone systems for remote industrial sites or rural electrification. Telecommunications tower backup and mining camp power in sub-Saharan Africa and Australian outback sustain niche demand.
Utility-scale captures the dominant revenue share, with commercial-scale distributed generation gaining share fastest as corporate renewable procurement accelerates.
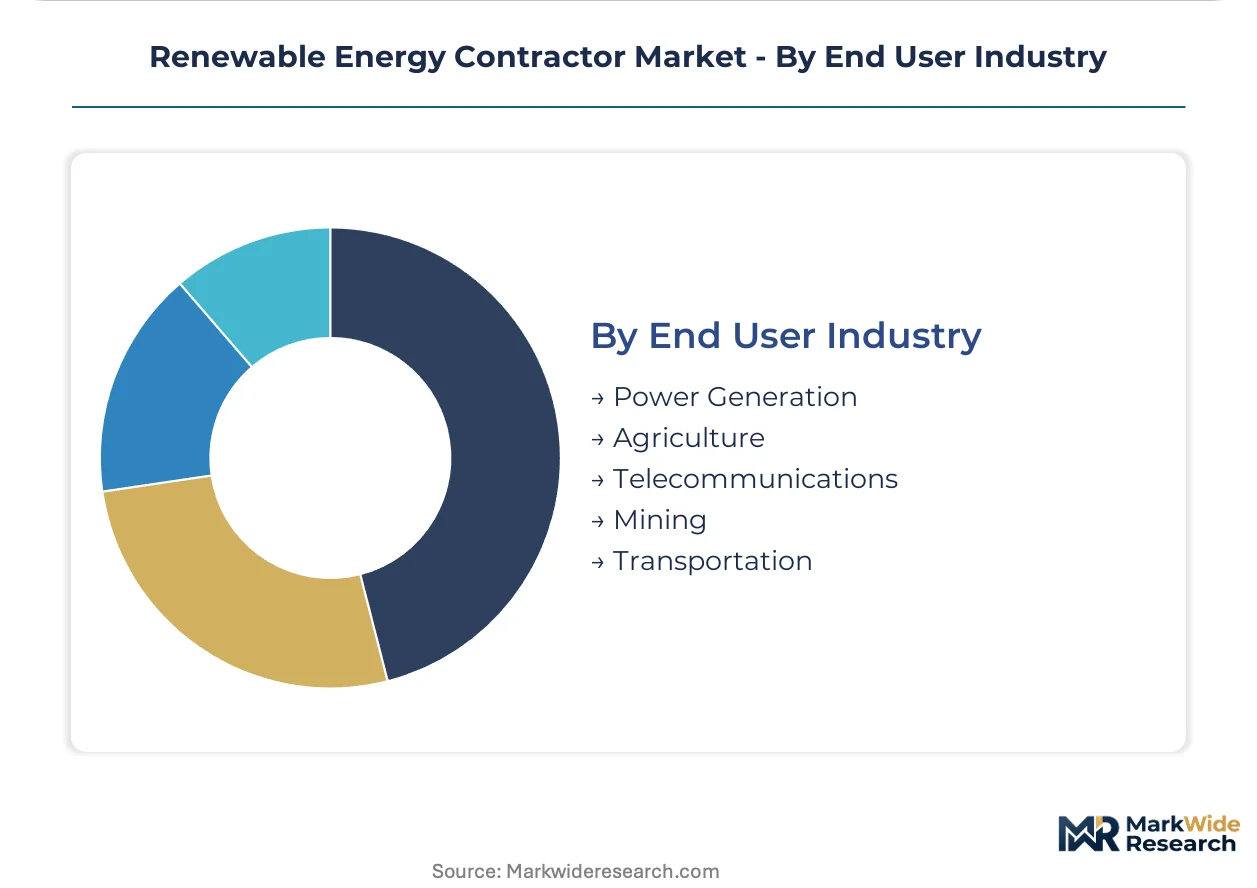
End User Industry:
Industry verticals impose distinct technical specifications and contracting norms that filter contractor suitability.
- Power Generation:Utility and independent power producer newbuild and repowering projects. Grid code harmonization delays around evolving IEEE and IEC standards extend commissioning timelines.
- Agriculture:Agrivoltaics, biogas capture, and irrigation-powered small hydro. Feed-in tariff stability in European agricultural regions and water stress in California's Central Valley shape deployment patterns.
- Telecommunications:Off-grid tower power and backup systems for remote network infrastructure. Tower operators in India and sub-Saharan Africa prioritize diesel displacement through solar-hybrid configurations.
- Mining:Remote mine electrification and renewable-powered mineral processing. Chilean copper and Australian iron ore operations drive 24/7 renewable-plus-storage specifications.
- Transportation:Electric vehicle charging infrastructure and renewable-powered rail electrification. EU Green Deal implementation through revised Renewable Energy Directive targets creates compliance-driven procurement.
Power generation anchors contractor backlogs, with transportation infrastructure emerging as the steepest expansion trajectory as fleet electrification scales charging demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The renewable energy contractor industry traces its modern scaling to Germany's Energiewende program and Spain's early solar feed-in tariffs, which established the integrated EPC model now dominant across utility-scale deployment.
United States
Utility-scale solar and offshore wind procurement drives contractor backlog expansion. The Inflation Reduction Act's domestic content adders filter qualification toward contractors with qualified local steel and manufacturing supply chains. Texas and California anchor demand concentration, with Gulf Coast fabrication yards scaling monopile production for Atlantic Coast wind developments.
China
Coastal province wind installation and western solar park construction absorb the dominant contractor workforce. MIIT industrial policy and dual carbon goals mandate integrated EPC delivery for state-backed renewable tenders. Jiangsu and Guangdong provinces concentrate offshore wind foundation fabrication, pulling civil infrastructure capacity from traditional power sectors.
India
National solar mission tenders mandate turnkey EPC accountability, eliminating fragmented subcontracting patterns. CEA regulations require integrated project delivery for utility-scale solar parks. Rajasthan and Gujarat host the densest contractor deployment, with Bhadla and Pavagada solar parks setting procurement templates.
Germany
North Sea offshore wind repowering and onshore wind turbine replacement cycles sustain contractor utilization. EU Green Deal implementation through revised Renewable Energy Directive targets and CE marking requirements filters market access. Northern coastal states and industrial clusters around Bremen and Hamburg anchor marine construction specialization.
Brazil
Wind corridor expansion in the Northeast and distributed generation acceleration in the Southeast reshape contractor geographic focus. ANEEL regulatory frameworks for distributed generation and net metering determine project viability. Ceará and Rio Grande do Norte concentrate wind EPC capacity, while São Paulo state drives commercial solar deployment.
Renewable Energy Contractor Market Competitive Landscape
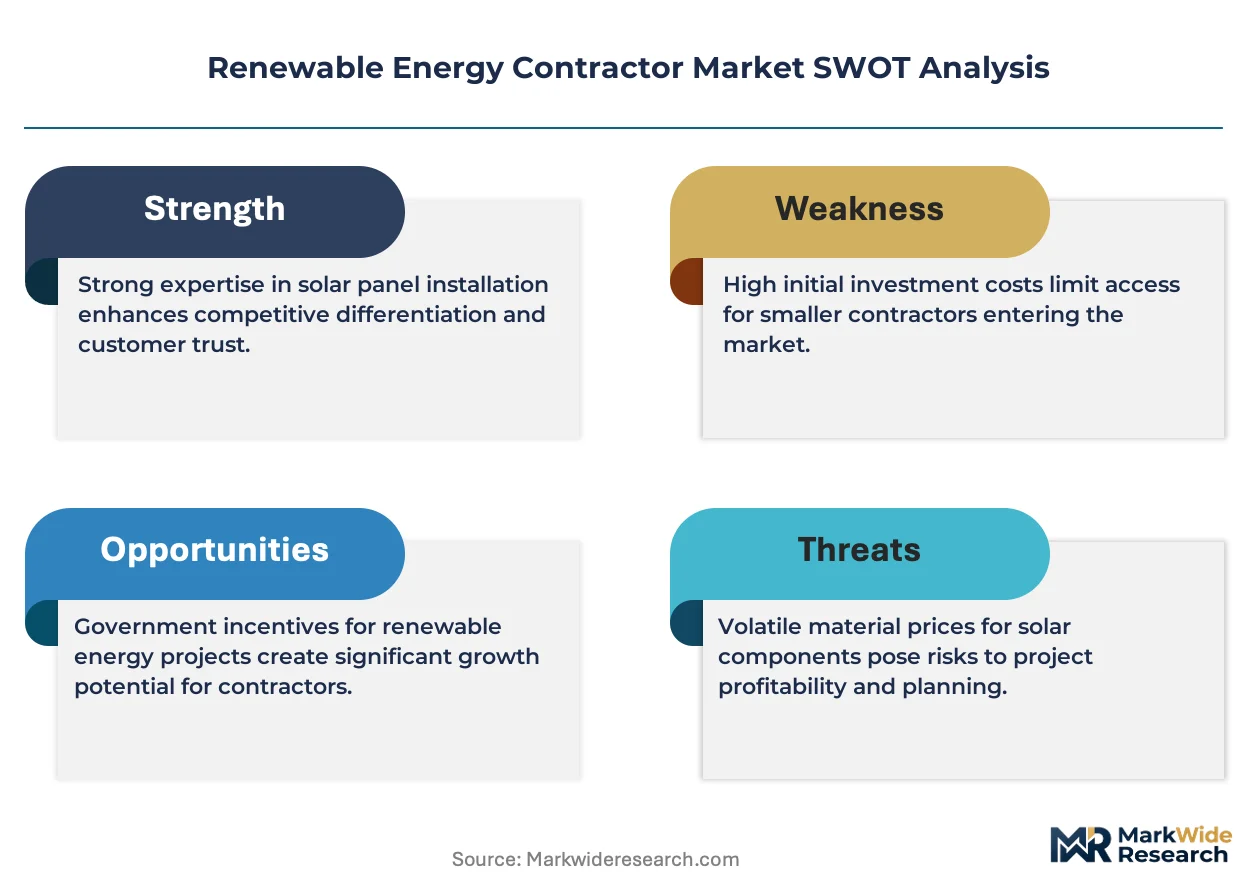
The competitive structure tilts toward diversified infrastructure conglomerates with transferable civil engineering capabilities. Engineering-intensive specialists and regional turnkey providers occupy secondary tiers, differentiated by certification depth and local supply chain qualification. Three archetypes dominate: integrated development-construction-operate platforms, fossil-to-renewable infrastructure migrators, and pure-play renewable EPC specialists. Capacity expansion and strategic partnerships represent the dominant competitive moves, as contractors seek to satisfy domestic content mandates and offshore wind foundation complexity.
Among diversified infrastructure conglomerates, Bechtel and Fluor occupy positions exemplifying the fossil-to-renewable migration archetype, leveraging massive civil construction balance sheets and project management systems originally developed for conventional power and industrial infrastructure. ACCIONA represents the integrated development-operate model, capturing full-lifecycle value through captive project origination and long-term asset management. These three anchors demonstrate how contractor competitive positioning increasingly depends on capabilities spanning development, construction, and operational phases rather than standalone build execution.
| Leading Market Players |
|---|
| ACCIONA |
| Bechtel |
| Black & Veatch |
| Bouygues Construction |
| Fluor |
| Granite Construction |
| Mortenson |
| Primoris Services |
| TIC - The Industrial Company |
| Others |
Pricing and Supply Chain Analysis
ASME-certified welder pools in the US Gulf Coast and European North Sea corridors feed directly into contractor pricing-tier spreads, with labor-cost differentials between premium-certified and standard-grade fabrication crews widening as offshore wind foundation complexity escalates.
Pricing Analysis
Fixed-price EPC contracting with performance-guarantee escalation clauses dominates utility-scale renewable builds, separating premium-tier contractors with integrated development-operate capabilities from standard-tier turnkey providers and economy-tier regional subcontractors. Price differentiation hinges on IEC 61400 wind turbine certification depth and domestic content qualification under IRA adder rules. Cost compression in the economy tier intensifies as Indian and Chinese contractors absorb engineering risk for thinner margins. Corporate offtakers with sustainability mandates show lowest price sensitivity; distributed commercial solar buyers exhibit highest.
Supply Chain Analysis
Domestic content mandates under the US Inflation Reduction Act and India's CEA regulations are reshaping contractor sourcing patterns, forcing qualification shifts away from established Asian mill relationships. Grain-oriented electrical steel draws from China, Japan, and South Korea; monopile fabrication concentrates in Germany, China, and the US Gulf Coast; photovoltaic module supply anchors in China, Vietnam, and Malaysia. Single-source vulnerability in transformer core steel exposes contractors to input cost volatility. Distribution runs through developer-EPC direct procurement with long-lead vendor qualification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Contractor market evolution reads as a late-cycle quality story, with bifacial-plus-tracking specifications and offshore wind jacket complexity filtering procurement toward premium-tier EPC platforms capable of integrated lifecycle delivery.
For Market Incumbents: Extend captive fabrication capacity into domestic-content-qualified supply chains to defend against pure-play renewable specialists capturing IRA adder value. Anchor engineering talent retention in ASME-certified welding and offshore geotechnical disciplines where capability scarcity is accelerating. Deepen backward integration into electrical steel procurement relationships to offset transformer cost volatility. For New Entrants and Emerging Players: Digital twin-enabled construction management platforms offer a technology-first wedge into the hybrid renewable-plus-storage segment, where integrated EPC capabilities remain undersupplied. Target commercial-scale C&I solar-plus-battery configurations in US Southwest states where permitting fragmentation has slowed incumbent expansion. Lead with predictive O&M analytics as a bundled construction follow-on to differentiate from build-only competitors. For Investors and Strategic Acquirers: Infrastructure conglomerates with fossil-to-renewable transferable capabilities are the most active acquirer in this space, seeking development-construction-operate platforms that compress cycle times. Long-term viability centers on contractors with balance sheet capacity for utility-scale risk retention and captive O&M revenue streams. Watch FERC interconnection queue clearance velocity as the signal for contractor cash flow normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Content Supply Chain Qualification | IRA adder capture requires qualified local steel and manufacturing vendor lists. |
| Offshore Wind Foundation Fabrication Buildout | Gulf Coast and North Sea yards scale monopile and jacket production capacity. |
| Integrated O&M Platform Acquisition | Long-term availability contracts extend contractor revenue beyond construction margins. |
| Digital Twin Construction Deployment | Prefabrication quality control transfers value from job sites to factory floors. |
| Hybrid Renewable-Plus-Storage Capability Integration | Co-located solar-wind-battery configurations demand unified EPC accountability. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with utility planning officers, IPP project developers, EPC contractors, grid operators, and electrical steel procurement specialists with secondary validation against EIA data, IEA renewable deployment reports, FERC interconnection filings, and project development databases. Bottom-up capacity build tracking and top-down policy impact modeling were triangulated against contractor backlog disclosures.
Comparable historical reference periods anchored the projection horizon, with analytical frameworks modeling segmentation across fuel source, generation capacity tier, project scale, regulatory framework, and regional grid interconnection type. CAGRs were derived from deployment pipeline velocity and policy incentive durability assessments. Forecast inputs incorporated IRA domestic content threshold evolution and EU CBAM steel tariff implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to interconnection queue reform effectiveness and electrical steel supply concentration shifts. Assumptions reflect documented policy guidance and disclosed contractor qualification patterns. A small set of named triggers—FERC Order 2023 implementation velocity, CBAM full-phase tariff rates, and ASME welder training pipeline expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.