
 China Wind Power Market | 2026-2036
China Wind Power Market Size, Share, and Industry Trends Forecast 2026-2036
China Wind Power Market Insights
The gap between premium offshore installations and commodity onshore projects is broadening. Goldwind leverages in-house blade manufacturing to control costs across both tiers. Envision anchors its position through advanced digital turbine platforms that differentiate performance at scale.
China wind power encompasses electricity generation systems converting kinetic wind energy into grid-connected power through rotor assemblies, drivetrains, and power electronics, with modern turbines exceeding 6 MW rated capacity and 150-meter rotor diameters for offshore applications. The technology serves as a baseload-competitive alternative to coal-fired generation in coastal and northern provinces. Horizontal axis configurations dominate installed capacity, while direct drive systems capture expanding share due to reduced gearbox maintenance and higher availability rates. Offshore application segments command premium pricing and attract concentrated R&D investment, whereas onshore utility scale deployment sustains volume leadership through provincial auction mechanisms.
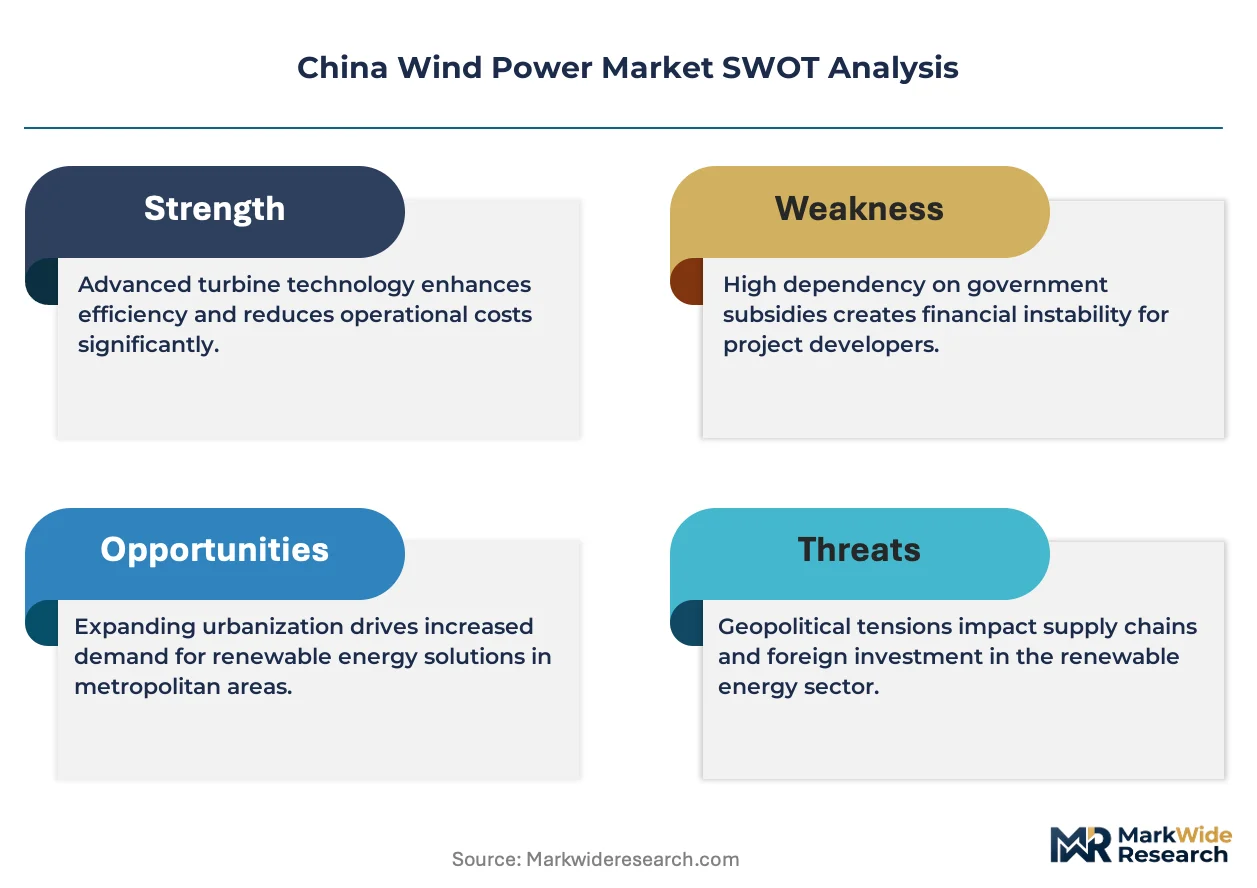
MIIT sets equipment efficiency benchmarks, while MEE enforces environmental impact assessments for new wind farms, and GB standards govern turbine structural certification and grid interconnection compliance. These frameworks elevate technical barriers for new entrants and accelerate replacement of subscale legacy turbines. Stakeholders must track provincial auction design evolution and offshore leasing round timing to align manufacturing capacity with demand geography.
Market Dynamics
MIIT efficiency mandates and GB certification standards are compressing the supplier base while accelerating replacement of subscale legacy turbines across northern and coastal provinces.
Growth Catalysts
- Dual carbon policy framework:Beijing's carbon neutrality targets mandate renewable capacity expansion, forcing provincial grids to prioritize wind interconnection over thermal generation.
- Offshore leasing rounds:Jiangsu and Fujian provincial authorities are auctioning seabed concessions with preferential tariff mechanisms that de-risk capital deployment for 10+ MW turbine platforms.
- Direct drive technology maturation:Permanent magnet generators eliminate gearbox maintenance burdens, improving availability rates above 97% and reducing lifecycle operational expenditure.
Market Restraints
- Rare earth supply concentration:Neodymium and dysprosium processing capacity concentrates in Inner Mongolia and Jiangxi, exposing turbine manufacturers to input cost volatility and export quota risks.
- Grid absorption constraints:Northern provinces including Gansu and Jilin face curtailment rates exceeding 10% due to transmission bottlenecks and coal plant dispatch priority.
- Marine construction bottlenecks:Specialized jack-up vessel availability limits annual offshore installation velocity, with only three domestic yards producing units rated above 1,200 tons.
Strategic Opportunities
- Floating foundation deployment:Deepwater sites beyond 50-meter depth contours in Guangdong and Hainan remain untapped, awaiting cost-competitive semi-submersible platform commercialization.
- Green hydrogen coupling:Offshore wind farms in Shandong are piloting electrolyzer co-location to bypass grid constraints and capture premium industrial offtake from steel and ammonia producers.
- Retrofit and repowering services:Early 1.5 MW installations from 2008-2012 vintages face blade fatigue and drivetrain obsolescence, creating aftermarket revenue pools for component suppliers.
Industry Challenges
- Blade technician shortage:Composite repair certification programs cannot match deployment velocity, with specialized climbing crews commanding wage premiums above 40% versus onshore equivalents.
- GB standard compliance timelines:Revised load case calculations and lightning protection testing protocols extend type certification cycles by 8-14 months, delaying project financial close.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Wind Power Market |
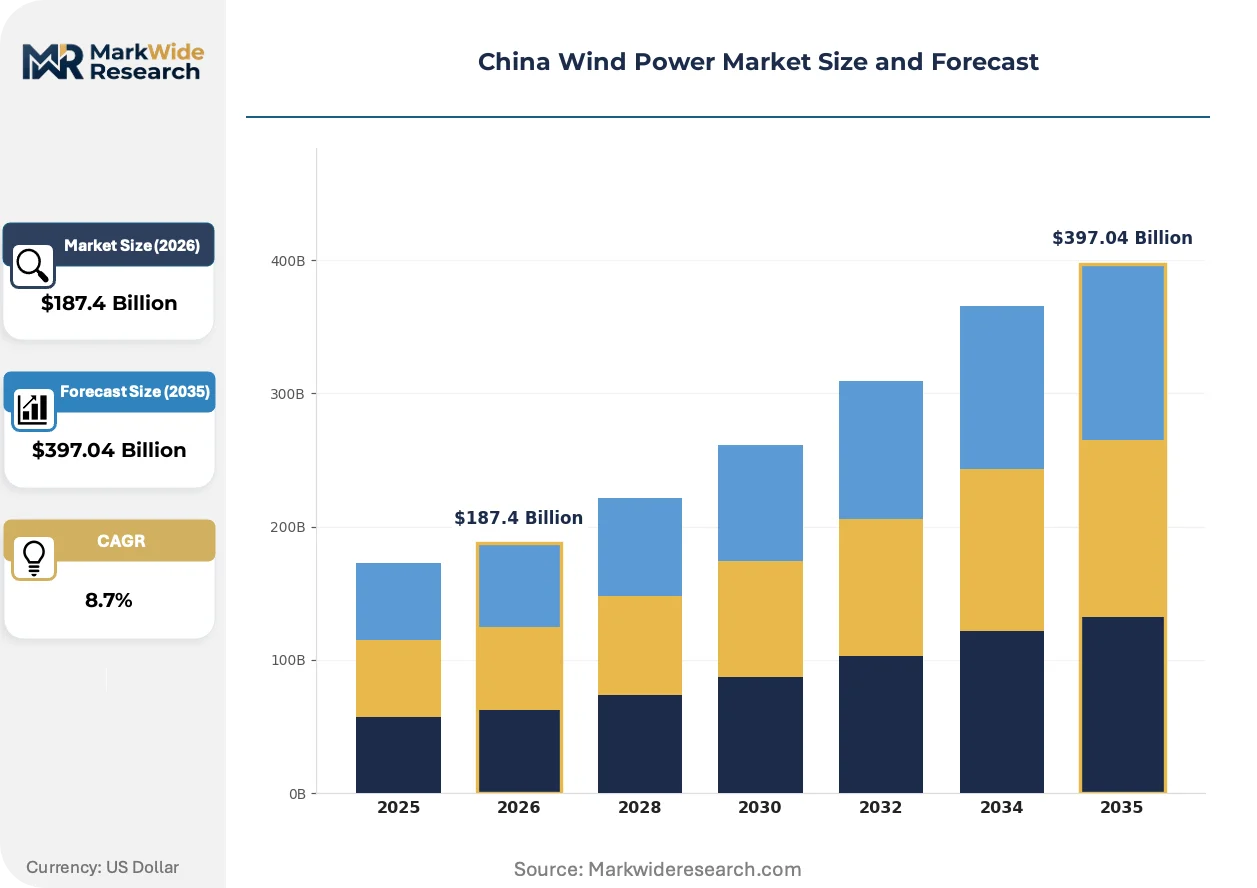
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Turbines, Controllers, Generators, Accessories Technology: Horizontal Axis, Vertical Axis, Direct Drive, Gear Drive Application: Offshore, Onshore, Hybrid, Utility Scale End User: Utilities, Industrial, Commercial, Residential |
| Companies Covered | Goldwind, Envision, Windey, Mingyang Smart Energy, Shanghai Electric, Dongfang Electric, SANY, CSIC Haizhuang, Sinovel, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Wind Power Market Trends and Innovations
Turbine scale escalation and digitalization are restructuring competitive advantage around manufacturing integration depth and predictive maintenance capabilities rather than pure hardware specification.
Direct drive permanent magnet generators are expanding into offshore installations above 8 MW rated capacity. Developers in Jiangsu and Zhejiang specify these configurations for their reduced nacelle mass and elimination of gearbox failure modes. The technology is expanding into shallow-water projects previously reserved for geared architectures, compressing supplier margins for gearbox specialists.
MIIT's 2024 equipment efficiency benchmarks mandate 200-meter rotor diameters for new onshore approvals and impose stricter power curve verification protocols. Manufacturers must redesign blade aerodynamics and pitch control systems to comply. Northern province auctions now weight technical scores above price, advantaging integrated producers with in-house blade facilities.
Power purchase agreement structures are unbundling operations and maintenance from initial equipment supply. State-owned developers in Guangdong and Fujian now procure 15-year service contracts separately, with availability guarantees replacing upfront capital discounts. This shift concentrates aftermarket revenue with turbine OEMs possessing proprietary SCADA analytics platforms and regional spare part depots.
China Wind Power Market Segmentation
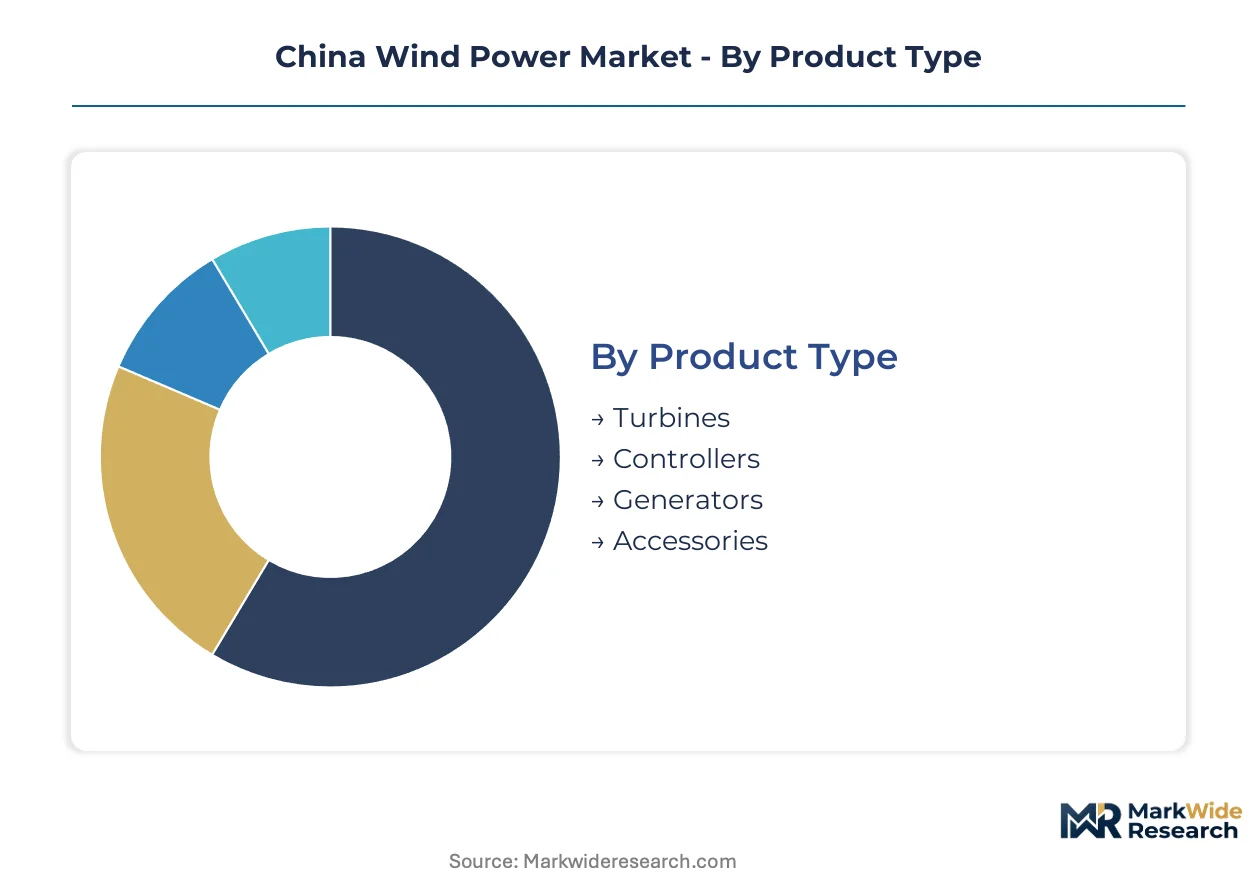
Segmentation in China wind power reveals how procurement decisions split between coastal offshore premiums and northern onshore volume plays. Equipment buyers weight technology maturity against grid interconnection economics, while end-user type dictates financing structures and O&M contract terms.
Product Type:
Capital allocation intensity drives buyer selection here, with integrated turbine supply commanding multi-year procurement cycles versus component spot markets.
- Turbines:Complete nacelle-rotor-tower assemblies exceeding 6 MW rated capacity for offshore deployment and 3-4 MW platforms for northern onshore clusters. Jiangsu and Fujian developers specify 10+ MW units for seabed installations, with MIIT efficiency mandates now requiring 200-meter rotor diameters for new approvals.
- Controllers:Pitch and yaw control systems with embedded SCADA analytics for predictive maintenance. Demand concentrates with state-owned developers in Guangdong unbundling 15-year service contracts from initial equipment supply, favoring OEMs with proprietary digital platforms.
- Generators:Permanent magnet direct drive and doubly-fed induction architectures.
- Accessories:Transformers, switchgear, and lightning protection components.
Volume sits with Turbines; growth tilts toward Controllers.
Technology:
Reliability economics and maintenance burden reshape technology adoption as availability guarantees replace upfront discounts in procurement scoring.
- Direct Drive:Permanent magnet generators eliminating gearbox failure modes and pushing availability above 97%. Expanding fastest across Jiangsu and Zhejiang shallow-water projects previously reserved for geared systems, compressing margins for gearbox specialists.
- Horizontal Axis:Upwind rotor configurations with three blades dominating installed capacity across Inner Mongolia and Xinjiang utility-scale clusters. Blade aerodynamics face redesign pressure under MIIT power curve verification protocols.
- Gear Drive:High-speed generator configurations with planetary gearboxes.
- Vertical Axis:Darrieus and Savonius designs for distributed applications.
Horizontal Axis carries installed base dominance; Direct Drive climbs the fastest as offshore deployment accelerates.
Application:
Grid absorption capacity and transmission infrastructure availability segment developer capital deployment between coastal premium zones and curtailment-constrained northern provinces.
- Offshore:Fixed-bottom installations in 20-50 meter depths and emerging floating platforms beyond. Jiangsu and Fujian seabed auctions with preferential tariffs de-risk 10+ MW turbine deployment, though jack-up vessel bottlenecks limit annual installation velocity.
- Onshore:Utility-scale clusters in Gansu, Jilin, and Inner Mongolia facing curtailment rates exceeding 10% due to coal dispatch priority and transmission constraints. Provincial auctions now weight technical scores above price.
- Utility Scale:Grid-connected projects above 50 MW capacity.
- Hybrid:Wind-solar-storage co-location configurations.
Onshore retains volume leadership; Offshore captures steepest expansion trajectory.
End User:
Balance sheet strength and offtake contract duration separate procurement behaviors between state-backed utilities and credit-constrained commercial offtakers.
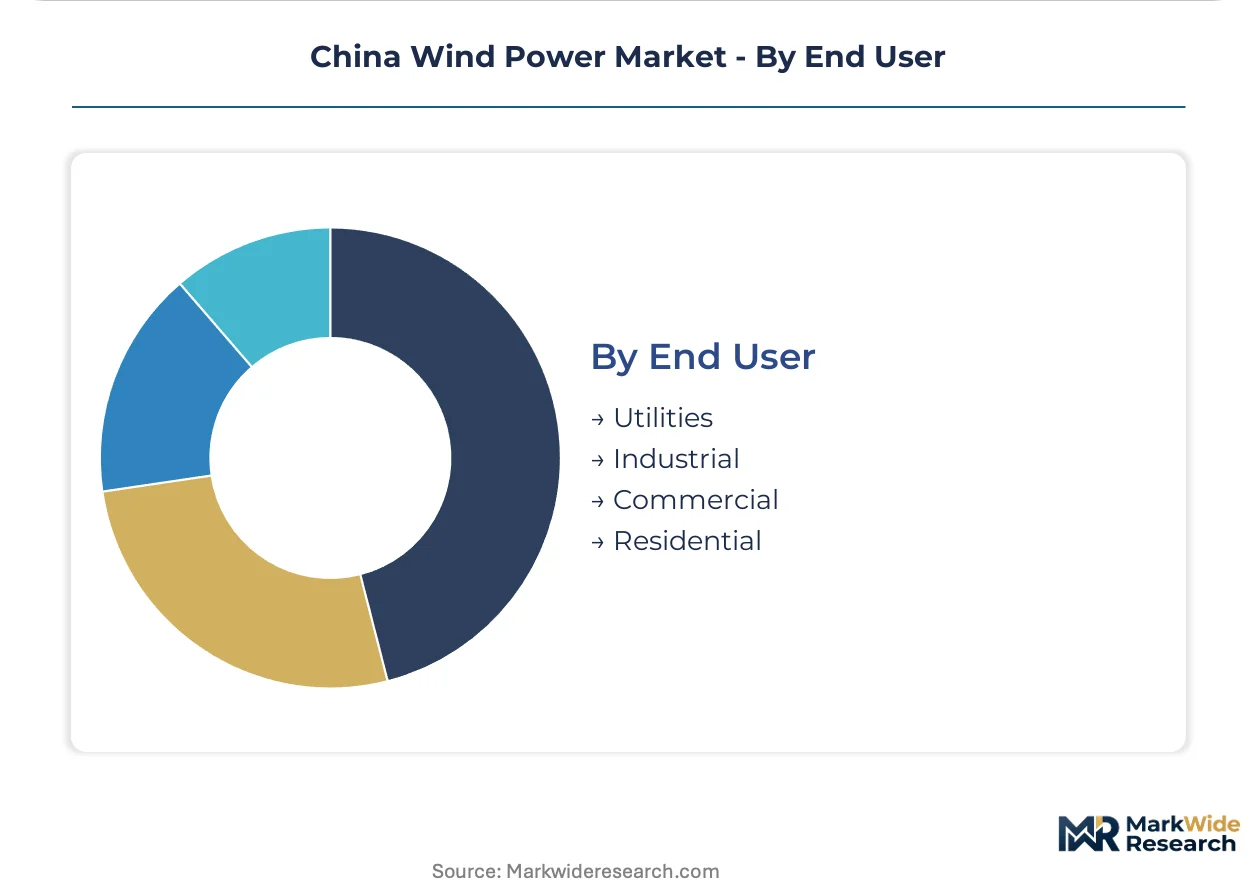
- Utilities:State Grid and provincial power generation companies with 20-25 year PPA tenors and sovereign credit backing. Shandong utilities pilot electrolyzer co-location to bypass grid constraints and capture industrial hydrogen offtake.
- Industrial:Steel, ammonia, and chemical producers seeking renewable power purchase agreements for Scope 2 emissions reduction. Green hydrogen coupling creates bypass routes around transmission bottlenecks.
- Commercial:Corporate offtakers with shorter contract preferences.
- Residential:Distributed generation below 1 MW capacity.
Utilities anchor procurement volume; Industrial segments gain share fastest as hydrogen coupling commercializes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yancheng and Nantong anchor China's offshore wind manufacturing corridor, with blade foundries and nacelle assembly plants clustering along Jiangsu's northern coastline. Provincial energy bureaus in coastal and northern regions drive divergent deployment patterns shaped by grid absorption capacity and seabed leasing schedules.
Jiangsu
Dongtai and Sheyang districts host concentrated turbine final assembly capacity serving 10+ MW offshore platforms. MIIT equipment efficiency benchmarks mandate 200-meter rotor diameters for new provincial approvals, compressing supplier margins for subscale manufacturers. State Grid Jiangsu pilots direct drive generator integration at Rudong interconnection stations.
Inner Mongolia
Xilingol and Hulunbuir grasslands sustain utility-scale onshore clusters exceeding 50 MW per site. GB turbine certification standards require revised load case calculations for high-altitude wind shear conditions. Baotou rare earth processing corridors supply neodymium permanent magnets to northern generator fabricators.
Guangdong
Zhanjiang and Yangjiang shallow-water zones advance fixed-bottom installations while semi-submersible floating platforms prototype beyond 50-meter depth contours. Provincial offshore leasing rounds incorporate preferential tariff mechanisms de-risking capital deployment. Shantou electrolyzer pilots couple offshore generation to industrial hydrogen offtake.
Fujian
Putian and Fuzhou coastal zones auction seabed concessions with technical scoring weighted above price under revised auction designs. Jack-up vessel bottlenecks limit annual installation velocity despite concentrated demand. Pingtan island clusters test typhoon-resistant blade aerodynamics under MIIT power curve verification protocols.
Xinjiang
Ham and Turpan basins face curtailment rates exceeding 10% due to coal plant dispatch priority and transmission bottlenecks to eastern load centers. Provincial auctions now prioritize grid interconnection economics over pure generation capacity. Urumqi control system integrators service predictive maintenance platforms for northern utility-scale clusters.
China Wind Power Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration depth and aftermarket service bundling. The supplier base compresses under MIIT efficiency mandates and GB certification timelines that favor integrated manufacturers with captive blade production. Three archetypes dominate: vertically integrated turbine OEMs controlling upstream component supply, digital platform specialists unbundling long-term service contracts from equipment sale, and state-owned conglomerates leveraging balance sheet scale for seabed leasing participation. Competitive moves concentrate on manufacturing capacity alignment with provincial auction geography and proprietary SCADA analytics development for availability guarantee contracting.
Within the integrated manufacturing tier, Goldwind and Envision occupy positions exemplifying divergent strategic emphases. Goldwind represents archetypal backward integration into blade production, controlling costs across offshore premium and onshore commodity deployment tiers. Envision anchors the digital platform specialist archetype, differentiating through advanced turbine SCADA systems that capture unbundled 15-year service contracts. Mingyang Smart Energy sits within the scale-driven coastal offshore segment, with corporate naming indicating concentrated exposure to seabed leasing participation in southern provincial markets.
| Leading Market Players |
|---|
| Goldwind |
| Envision |
| Windey |
| Mingyang Smart Energy |
| Shanghai Electric |
| Dongfang Electric |
| SANY |
| CSIC Haizhuang |
| Sinovel |
| Others |
Pricing and Supply Chain Analysis
Provincial auction designs weighting technical scores above price are forcing turbine OEMs to absorb certification and redesign costs while maintaining competitive bids. MIIT's 200-meter rotor diameter mandates and GB load case revisions compress margins for manufacturers lacking in-house blade production, concentrating pricing power with integrated producers.
Pricing Analysis
Availability guarantees now anchor turbine procurement economics, with state-owned developers in Guangdong and Fujian unbundling 15-year service contracts from equipment sales. Pricing stratifies across premium offshore platforms with integrated SCADA analytics, standard onshore utility configurations, and economy-tier repowering kits for legacy sites. Cost compression in onshore segments intensifies as northern province auctions prioritize grid interconnection economics over pure generation capacity. Industrial hydrogen offtakers show lowest price sensitivity due to green hydrogen coupling premiums, while utility procurement teams enforce strict capital discipline.
Supply Chain Analysis
Permanent magnet supply rests on Inner Mongolia and Jiangxi rare earth processing corridors, with neodymium and dysprosium feedstock drawing from concentrated upstream refining. Blade manufacturing clusters along Jiangsu's northern coastline feed nacelle assembly plants in Yancheng and Nantong, while specialized jack-up vessel production concentrates at three domestic yards. Single-source vulnerability runs through seabed installation equipment, with annual offshore deployment velocity capped by vessel availability. Distribution runs through state-owned developer procurement channels and provincial energy bureau auction mechanisms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GB certification timelines and MIIT efficiency mandates erect substantial compliance barriers, entrenching incumbents with established testing relationships and in-house engineering capacity. New entrants face 8-14 month certification delays absent pre-existing regulatory track records.
For Market Incumbents: To counter margin compression from technical-score-weighted provincial auctions, deepen backward integration into blade aerodynamics and pitch control systems. Prioritize captive permanent magnet supply arrangements with Baotou rare earth processors to offset input cost volatility. For New Entrants and Emerging Players: Capture aftermarket retrofit demand for 2008-2012 vintage turbine replacements, where blade fatigue and drivetrain obsolescence create service revenue pools. Target floating foundation engineering partnerships in Guangdong deepwater zones beyond 50-meter contours, leveraging design agility absent from fixed-bottom incumbents. For Investors and Strategic Acquirers: The window for entry favors digital platform specialists with proprietary SCADA analytics and regional spare part depot networks. Long-term viability hinges on unbundled service contract capture as availability guarantees displace upfront capital discounts. Watch provincial offshore leasing round timing as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Blade Manufacturing | Goldwind's captive blade production controls costs across offshore and onshore deployment tiers. |
| Digital Platform Development | Envision's SCADA analytics capture unbundled 15-year service contracts from state-owned developers. |
| Floating Foundation Commercialization | Semi-submersible platforms unlock deepwater sites beyond 50-meter contours in Guangdong and Hainan. |
| Green Hydrogen Coupling | Shandong electrolyzer pilots bypass grid constraints to capture industrial steel and ammonia offtake. |
| Retrofit and Repowering Services | Aftermarket revenue pools emerge from blade fatigue and drivetrain obsolescence in 1.5 MW vintage installations. |
Research Methodology
Independent corroboration across MIIT equipment efficiency filings, provincial energy bureau auction records, and GB certification databases underwrites the qualitative findings. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators combined with secondary validation from EIA data, IEA renewable energy reports, and customs trade records. Bottom-up project pipeline analysis triangulates against top-down provincial capacity targets.
Rate-of-change decomposition across the analysis window segments growth by turbine scale class, application depth, technology architecture, and regional grid absorption capacity. CAGRs derive from modeled deployment velocity constrained by jack-up vessel availability, seabed leasing schedules, and transmission interconnection timelines. Forecast inputs incorporate rare earth supply quota dynamics and provincial curtailment rate trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to floating foundation cost curves and green hydrogen offtake contract commercialization. Assumptions reflect current GB certification timelines and MIIT equipment benchmarks. A small set of triggers—offshore leasing round acceleration, electrolyzer scale-up commitments, and rare earth export quota shifts—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Global Organic Rankine Cycle Market
Renewable Energy
United Arab Emirates Renewable Energy Market
Renewable Energy
Ethiopia Renewable Energy Market
Renewable Energy
Solar Chair Market
Renewable Energy
Solar Home Lights Market
Renewable Energy
Europe Single-Axis Solar Tracker Market
Renewable Energy
Wind Turbine Inspection Services Market
Renewable Energy
Wind Turbine Foundation Market
Renewable Energy
Green Renewable Energy Market
Renewable Energy
Solar Thermal Water Heater Market
Renewable Energy
South Africa Solar Photovoltaic (PV) Market
Renewable Energy
South Korea Renewable Energy Market
Renewable Energy
Australia Renewable Energy Market
Renewable Energy
Kazakhstan Renewable Energy Market
Renewable Energy
Algeria Renewable Energy Market
Renewable Energy
South Asia Renewable Energy Market