
 Algeria Renewable Energy Market | 2026-2036
Algeria Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Algeria Renewable Energy Market Outlook
The divergence between premium engineering-procurement-construction contracts and commodity equipment supply is hardening in Algeria's renewable energy sector. Sonelgaz leverages its grid interconnection monopoly to anchor large-scale solar tenders in the Hauts Plateaux region. China State Construction Engineering Corporation sustains cost discipline through integrated EPC capabilities spanning module sourcing to substation commissioning. Sonatrach competes by repurposing existing pipeline corridors and brownfield land for hybrid solar installations.
Algeria renewable energy encompasses electricity generation systems that harness solar irradiance, wind kinetic energy, organic matter combustion, or hydraulic head through photovoltaic panels with typical conversion efficiencies of 18-22%, horizontal-axis wind turbines rated 1.5-3 MW, and run-of-river hydropower installations. Solar dominates capacity additions due to the country's 2,000+ annual equivalent peak sun hours across Saharan territories. Ground-mounted installations lead project pipelines because utility-scale developers prioritize land availability and simplified permitting over rooftop complexity. Off-grid solutions represent the fastest-expanding application segment as mining operators and remote agricultural processors seek independence from centralized grid reliability issues.
Algeria's Ministry of Energy Transition and Renewable Energy governs licensing under Law 09-09, while the national regulator CRE sets grid connection codes and dispatch prioritization for renewable generators. The country's national standards body certifies equipment compliance with adapted IEC frameworks for desert climate resilience. Stakeholders must monitor upcoming domestic content threshold adjustments that could reshape supplier qualification criteria and EPC partner selection.
Market Dynamics
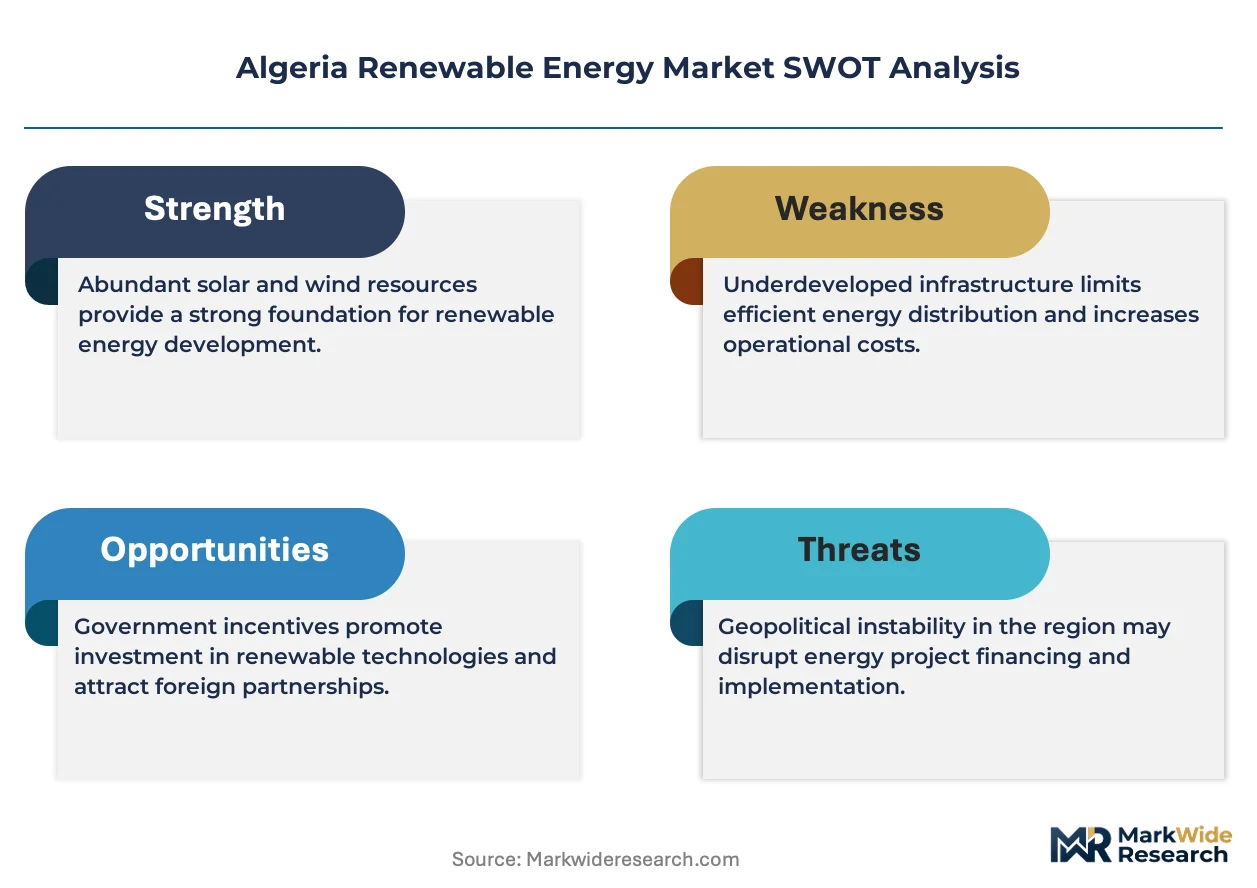
Algeria's renewable energy sector is being restructured by the Ministry of Energy Transition's feed-in tariff reforms, which redirect capital toward local manufacturing partnerships and away from pure equipment import models. This regulatory pivot is compressing margins for foreign suppliers while creating captive demand for domestic joint ventures.
Growth Catalysts
- Law 09-09 licensing framework:The national renewable energy law streamlines permitting timelines for utility-scale projects, reducing administrative friction for developers targeting Hauts Plateaux solar zones.
- Mining sector off-grid demand:Remote extraction operators in Tindouf and Illizi provinces are deploying captive solar-diesel hybrid systems to circumvent grid reliability constraints and diesel transport costs.
- Bifacial photovoltaic modules:Double-sided panel technology is capturing reflected irradiance from Saharan ground surfaces, boosting effective capacity factors in high-albedo desert installations.
Market Restraints
- Polysilicon supply concentration:Algeria's module assemblers remain dependent on Chinese polysilicon feedstock, exposing project economics to upstream price volatility and trade policy shifts.
- Transmission infrastructure gaps:The 400 kV backbone network lacks capacity to evacuate power from southern high-insolation zones to northern demand centers, forcing developers into costly grid reinforcement negotiations with Sonelgaz.
- Domestic content thresholds:Evolving local manufacturing requirements under Ministry decrees are disqualifying EPC bidders without established Algerian assembly partnerships.
Strategic Opportunities
- Agricultural processing electrification:Date palm cooperatives in Biskra and Ouargla provinces represent an untapped distributed generation segment seeking irrigation pump and cold storage power solutions.
- Green hydrogen export corridors:Sonatrach's pipeline rehabilitation programs could repurpose existing infrastructure for renewable ammonia transport to European offtakers under emerging EU Green Deal hydrogen import frameworks.
- Net metering expansion:Pending regulatory reforms to Law 09-09 may unlock behind-the-meter solar for commercial and industrial facilities currently excluded from feed-in tariff eligibility.
Industry Challenges
- Desert climate certification delays:Equipment qualification under adapted IEC frameworks for sand abrasion and thermal cycling resistance extends procurement timelines by six to twelve months.
- Grid code compliance complexity:CRE interconnection standards for voltage ride-through and frequency response require specialized inverter configurations unfamiliar to standard international suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Algeria Renewable Energy Market |
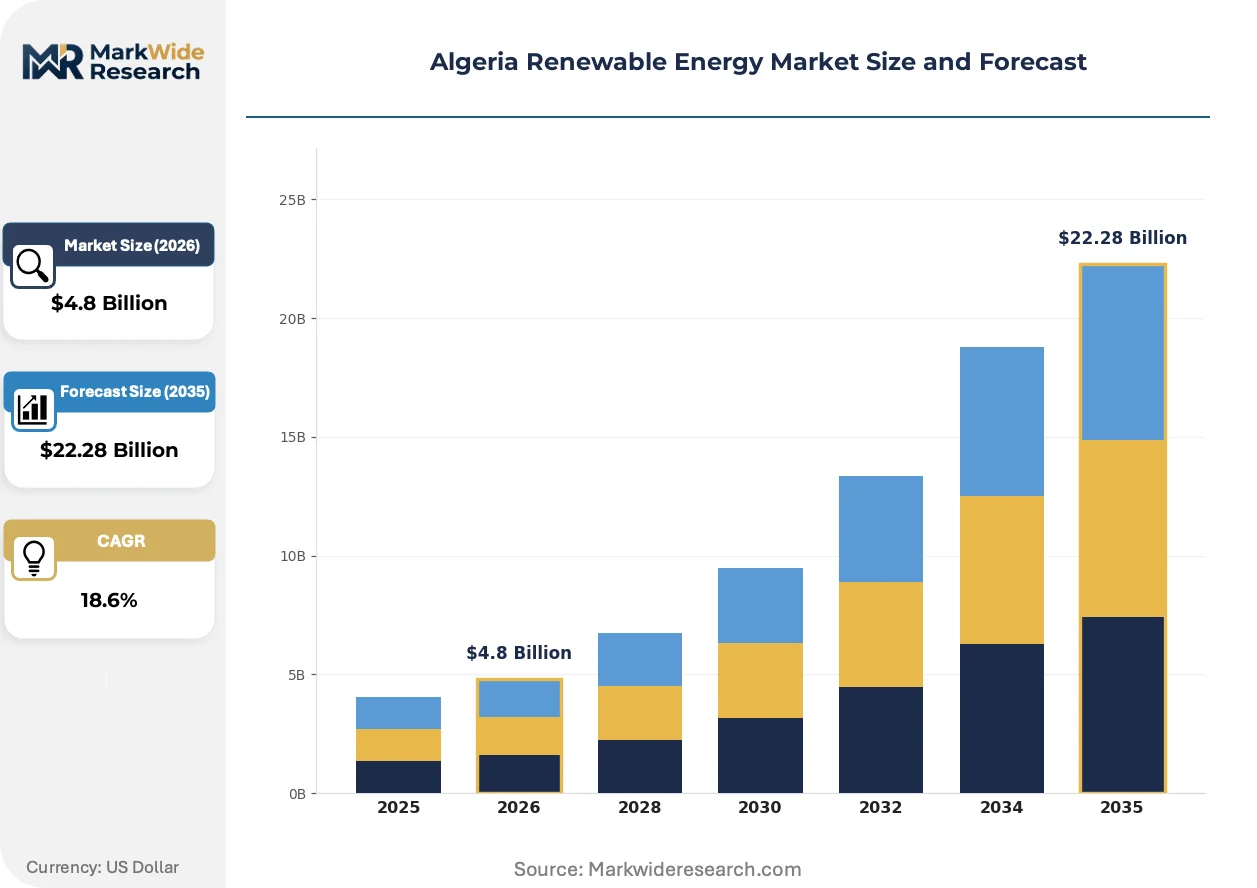
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar, Wind, Biomass, Hydropower Application: Power Generation, Water Heating, Transportation, Off-grid Solutions End User: Residential, Commercial, Industrial, Government Installation Type: Ground-mounted, Rooftop, Floating, Hybrid |
| Companies Covered | Algerian Energy Company, China State Construction Engineering Corporation, Sonelgaz, COSIDER Group, PowerChina, Sonatrach, New Energy Algeria, Özgün İnşaat, Shariket Kahraba oua Takat Moutadjadida, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Algeria Renewable Energy Market Strategic Shifts
Technology convergence and procurement model evolution are restructuring competitive positioning in Algeria's renewable energy sector. Developers are prioritizing integrated solutions that bundle generation assets with storage and grid stabilization services.
Agrivoltaic installations are absorbing land-use conflicts between solar deployment and food security priorities. Pilot projects in Ghardaia province are elevating photovoltaic arrays three meters above ground to permit continued cereal cultivation beneath panels. Agricultural cooperatives are adopting these configurations faster than pure-play solar developers, attracted by dual revenue streams from electricity sales and crop yields. The technology is absorbing opposition from rural constituencies that previously blocked utility-scale land acquisitions.
CRE's revised grid connection codes are mandating dynamic reactive power compensation for renewable generators above 10 MW capacity. This regulatory tightening is forcing inverter specification upgrades across the EPC supply chain. Projects in the 10-50 MW range are most affected, as these fall below threshold exemptions but lack economies of scale for dedicated substation infrastructure. Developers are responding by clustering adjacent projects to share compensation equipment costs.
Industrial offtakers are consolidating procurement through engineering-procurement-construction contractors rather than direct equipment purchasing. Mining operators and cement manufacturers are bundling twenty-year power purchase agreements with construction risk transfer to integrated providers. This behavior shift is marginalizing pure equipment vendors unable to offer turnkey construction and performance guarantees. The pattern is most visible in Adrar and Tamanrasset provinces, where remote project sites amplify the value of single-contractor accountability.
Algeria Renewable Energy Market Segmentation
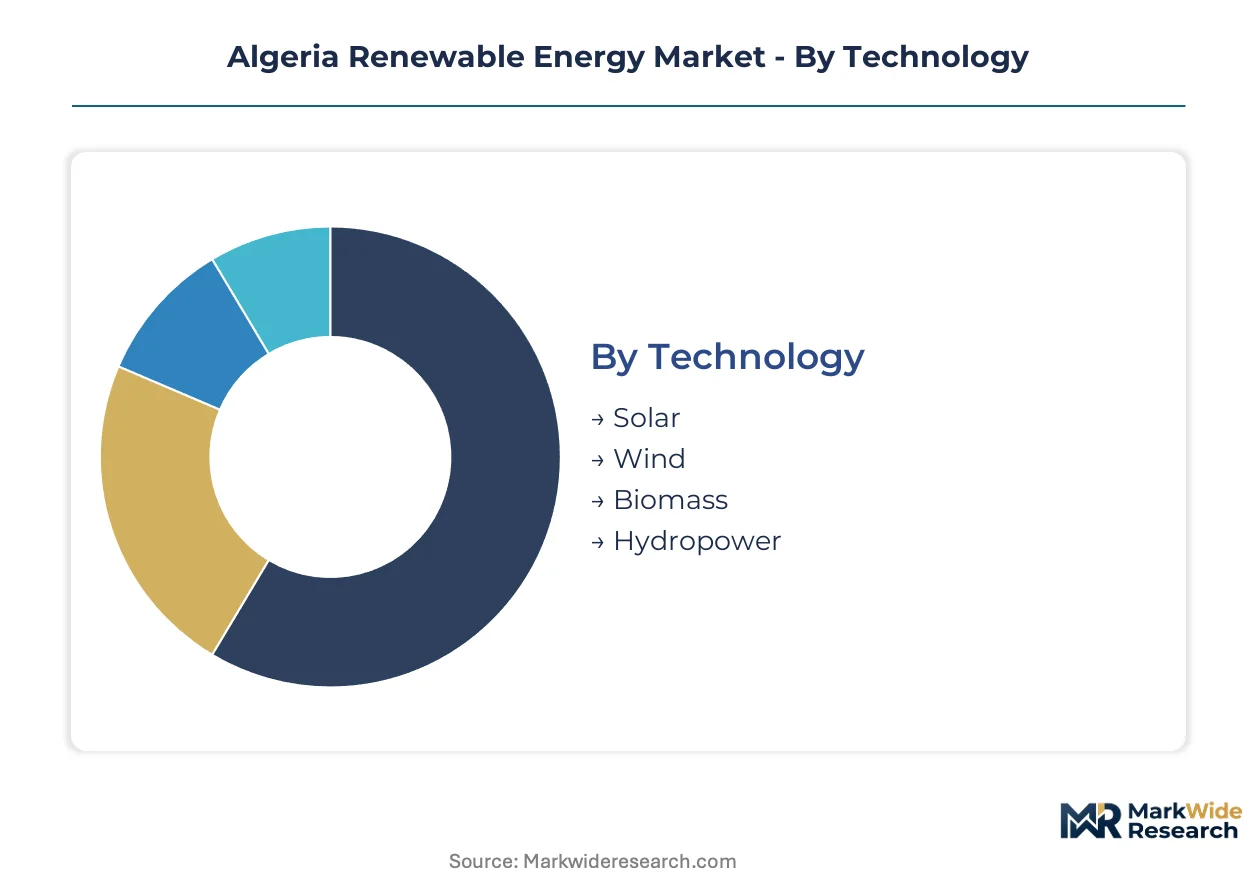
Segmentation in Algeria's renewable energy market exposes divergent regulatory burdens and infrastructure requirements across technology types and deployment contexts. Each category carries distinct certification pathways through the Ministry of Energy Transition and CRE grid codes, reshaping supplier qualification and project economics.
Technology:
Solar and wind installations face the heaviest adaptation requirements under Algeria's desert-climate IEC frameworks, while biomass and hydropower navigate less stringent but geographically constrained approval pathways.
- Solar:Photovoltaic systems with 18-22% conversion efficiencies dominate capacity additions. Ground-mounted arrays in Tindouf and Illizi provinces absorb mining sector demand for captive power, though developers endure six-to-twelve-month equipment qualification delays for sand abrasion resistance certification.
- Wind:Horizontal-axis turbines rated 1.5-3 MW concentrate in Hauts Plateaux corridors where Sonelgaz anchors transmission infrastructure. Grid code compliance for voltage ride-through capabilities forces specialized inverter configurations unfamiliar to standard international suppliers.
- Biomass:Organic matter combustion systems serve agricultural processing clusters in Biskra province, constrained by feedstock logistics and limited scale.
- Hydropower:Run-of-river installations exploit northern hydraulic head, restricted by water availability and competing irrigation demands.
Solar sits at the top of the volume ranking, with off-grid solar-diesel hybrids climbing the fastest among technology variants.
Application:
Cost tier differentiation separates utility-scale power generation from distributed behind-the-meter solutions, with off-grid commanding premium pricing for reliability premiums.
- Power Generation:Utility-scale projects feed the national grid under Law 09-09 feed-in tariffs. Sonelgaz interconnection negotiations absorb significant development overhead in southern zones lacking 400 kV backbone capacity.
- Off-grid Solutions:Captive installations for remote extraction operators bypass centralized grid reliability constraints. Mining operators in Adrar and Tamanrasset provinces consolidate procurement through integrated EPC contractors to transfer construction risk.
- Water Heating:Distributed solar thermal serves residential and commercial buildings in northern urban centers with established gas infrastructure competition.
- Transportation:Renewable-powered mobility infrastructure remains nascent, constrained by vehicle fleet turnover timelines and charging network gaps.
Power generation captures the largest project pipeline, while off-grid solutions gain share fastest as industrial offtakers desert grid-dependent models.
End User:
Customer type determines financing access and PPA structure, with industrial offtakers leveraging balance-sheet strength unavailable to residential segments.
- Industrial:Mining operators and cement manufacturers in remote provinces drive twenty-year power purchase agreement bundling with construction risk transfer. These offtakers prioritize single-contractor accountability for sites with difficult logistics.
- Residential:Behind-the-meter solar remains excluded from feed-in tariff eligibility pending Law 09-09 reforms, compressing deployment to self-consumption economics.
- Commercial:Date palm cooperatives in Ouargla province represent emerging distributed generation demand for irrigation and cold storage electrification.
- Government:Public procurement anchors large-scale tenders through Sonelgaz and Sonatrach brownfield rehabilitation programs.
Industrial demand leads absolute capacity absorption, with commercial segments expanding most quickly as agricultural processing electrification accelerates.
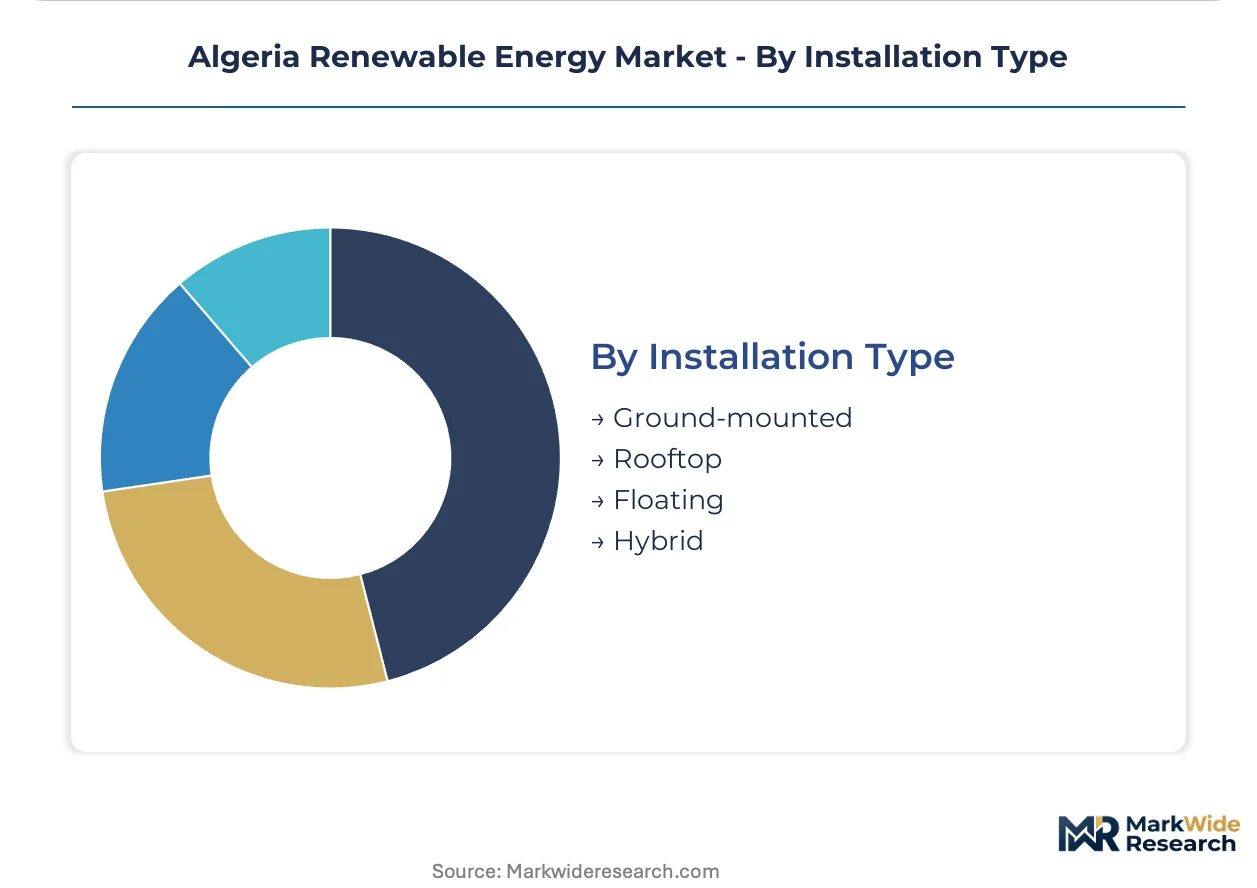
Installation Type:
Geography and land-use intensity separate ground-mounted dominance in Saharan territories from rooftop constraints in dense northern settlements.
- Ground-mounted:Utility-scale developers prioritize land availability and simplified permitting in southern high-insolation zones. Agrivoltaic pilots in Ghardaia province elevate arrays three meters above ground to permit continued cereal cultivation beneath panels.
- Rooftop:Urban density and structural load limitations restrict deployment to commercial buildings in Algiers and Oran, with residential penetration minimal due to tariff exclusion.
- Floating:Reservoir-based installations remain experimental, lacking established regulatory frameworks or proven local supply chains.
- Hybrid:Solar-diesel configurations serve mining and remote agricultural processors seeking independence from diesel transport costs and grid instability.
Ground-mounted arrays hold the volume lead, with hybrid installations posting the steepest expansion trajectory as reliability-conscious offtakers diversify supply sources.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Morocco's solar auction prices undercut Algerian feed-in tariffs, while Tunisia lags in transmission infrastructure deployment across the Maghreb corridor.
Morocco
Industrial phosphate processors in Khouribga drive captive solar demand. The Moroccan Agency for Sustainable Energy (MASEN) operates competitive bidding rounds for utility-scale projects. Noor-Ouarzazate complex anchors concentrated solar power capacity expansion.
Tunisia
Textile manufacturers in Sfax seek distributed generation to offset grid instability. The National Agency for Energy Management (ANME) administers net metering reforms for commercial installations. Gulf of Gabes wind corridors attract European development finance.
Egypt
Red Sea tourism operators deploy off-grid solar for resort electrification. The New and Renewable Energy Authority (NREA) licenses independent power producers under feed-in tariff schemes. Benban solar park in Aswan governorate concentrates photovoltaic manufacturing partnerships.
Saudi Arabia
Desalination facilities in Jubail Industrial City procure renewable power for process energy. The Ministry of Energy's National Renewable Energy Program (NREP) auctions utility-scale solar and wind capacity. NEOM megaproject integrates green hydrogen production with solar generation.
United Arab Emirates
Data center operators in Dubai Internet City seek behind-the-meter solar for cooling loads. The Dubai Electricity and Water Authority (DEWA) operates net metering for commercial distributed generation. Mohammed bin Rashid Al Maktoum Solar Park phases anchor photovoltaic module demand.
Algeria Renewable Energy Market Competitive Environment
Top-tier vendors anchor integrated EPC and utility-scale development, while mid-tier specialists concentrate on distributed generation and hybrid installations. The vendor base stratifies across three functional tiers: state-backed incumbents with grid interconnection monopolies, Chinese construction conglomerates with integrated supply chains, and regional specialists in captive power for extractive industries. Competitive positioning depends on domestic content partnerships and brownfield site access rather than pure equipment cost. M&A activity concentrates on local manufacturing joint ventures and pipeline corridor acquisitions.
Within the state-backed tier, Sonelgaz and Sonatrach occupy positions as anchor institutions with grid and land asset control. Among international EPC providers, China State Construction Engineering Corporation exemplifies integrated construction capabilities spanning module sourcing through substation commissioning. PowerChina represents the scale-driven archetype with multi-gigawatt project execution experience across desert climates. These entities illustrate how competitive advantage in Algerian renewable energy flows from construction risk absorption and regulatory relationship depth rather than technology differentiation alone.
| Leading Market Players |
|---|
| Algerian Energy Company |
| China State Construction Engineering Corporation |
| Sonelgaz |
| COSIDER Group |
| PowerChina |
| Sonatrach |
| New Energy Algeria |
| Özgün İnşaat |
| Shariket Kahraba oua Takat Moutadjadida |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal hydrogen import frameworks gate qualified supply for Algerian renewable energy projects, restricting premium-tier pricing access to developers with demonstrated domestic content partnerships and certified desert-climate equipment resilience.
Pricing Analysis
Capacity additions in Tindouf and Illizi provinces are reshaping price floors for captive solar-diesel hybrid installations. Three-tier pricing structure across premium, standard, and economy levels separates EPC-integrated offerings with performance guarantees from commodity module supply. Cost compression in standard-tier equipment is intensifying because Chinese polysilicon feedstock volatility transmits directly to Algerian assemblers. Mining operators demonstrate the least price sensitivity due to diesel transport cost avoidance, while agricultural cooperatives in Biskra province exhibit acute price responsiveness.
Supply Chain Analysis
Direct-to-EPC channels handle utility-scale and industrial offtaker demand, bypassing traditional distributor networks. Manufacturing concentrates in China for polysilicon feedstock and module assembly, with inverter sourcing from Germany and Spain for grid code compliance. Raw material dependencies center on polysilicon, aluminum framing, and specialized inverter components. Single-source vulnerability in Chinese polysilicon exposes project economics to upstream trade policy shifts. Distribution runs through integrated EPC contractors rather than component wholesalers for remote site deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Algeria's renewable energy sector functions as a regulatory compounder, with Law 09-09 feed-in tariff reforms and domestic content decrees continuously ratcheting entry barriers and redirecting capital flows toward qualified local partnerships.
For Market Incumbents: Deepen backward integration into polysilicon sourcing or captive module assembly to defend margins against Chinese supply volatility. Anchor grid interconnection relationships with Sonelgaz through early-stage transmission infrastructure commitments. Prioritize certification investment for desert climate resilience to maintain qualification under evolving Ministry of Energy Transition equipment standards. For New Entrants and Emerging Players: The price-point gap between premium EPC-integrated offerings and economy-tier equipment supply creates entry space for specialized agrivoltaic developers targeting agricultural cooperatives in Ghardaia and Ouargla provinces. Agricultural processing electrification represents the most penetrable segment, with date palm cooperatives seeking irrigation and cold storage solutions. Pursue turnkey construction bundling with performance guarantees to differentiate from commodity equipment vendors. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier EPC specialists with established Algerian assembly partnerships but limited project development pipelines. Long-term viability hinges on regulatory relationship depth and domestic content compliance rather than pure technology differentiation. Target acquisition candidates with Sonatrach brownfield site access or existing pipeline corridor rights. Monitor domestic content threshold adjustments as the primary inflection signal for supplier qualification regime shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Content Partnership Formation | Qualifies bidders for Ministry of Energy Transition procurement under evolving local manufacturing requirements. |
| Agrivoltaic Pilot Scale-Up | Absorbs land-use conflicts in Ghardaia province while unlocking dual revenue streams for agricultural cooperatives. |
| Grid Stabilization Service Bundling | Meets CRE revised connection codes for dynamic reactive power compensation above 10 MW capacity thresholds. |
| Brownfield Pipeline Corridor Acquisition | Leverages Sonatrach infrastructure rehabilitation for hybrid solar deployment with reduced permitting friction. |
| Green Hydrogen Export Certification | Positions renewable ammonia production for EU Green Deal hydrogen import framework eligibility. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with IPP project developers, EPC contractors, Sonelgaz grid planning officers, mining sector energy managers, and Ministry of Energy Transition licensing officials with secondary validation against IEA renewable energy databases, project development registries, and customs import records. Bottom-up capacity addition tracking and top-down policy impact assessment were triangulated for convergence.
Segment-weighting across technology type, application context, end-user category, and installation geography drove the analytical framework. Solar, wind, biomass, and hydropower capacity additions were modeled separately with technology-specific conversion efficiency assumptions. Project scale tiers from residential behind-the-meter through utility-scale grid-connected installations received distinct regulatory friction coefficients. CAGRs were derived from segmented growth rate blending weighted by current pipeline composition. Bifacial module adoption curves and agrivoltaic penetration rates served as technology-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for bifacial photovoltaic deployment or green hydrogen export corridor development would alter the outlook. Forecasts reflect base-case assumptions regarding domestic content threshold enforcement and transmission infrastructure buildout pacing. Commodity price volatility in polysilicon and aluminum framing represents a persistent revision risk. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
India Renewable Energy Market
Renewable Energy
East Asia Renewable Energy Market
Renewable Energy
Norway Renewable Energy Market
Renewable Energy
Israel Renewable Energy Market
Renewable Energy
Marine Energy Market
Renewable Energy
Europe Power to Gas Market
Renewable Energy
Variable Renewable Energy Market
Renewable Energy
Peru Renewable Energy Market
Renewable Energy
Turkey Renewable Energy Market
Renewable Energy
Canada Renewable Energy Market
Renewable Energy
Solar Bicycle Shed Market
Renewable Energy
Hydroelectric Cells Market
Renewable Energy
Philippines Wind Energy Market
Renewable Energy
Australia Renewable Energy Market
Renewable Energy
Solar Drying System Market
Renewable Energy
Composite Materials in Renewable Energy Market