
 Zimbabwe Renewable Energy Market | 2026-2036
Zimbabwe Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Zimbabwe Renewable Energy Market Analytics
Long-term power purchase agreements with embedded maintenance clauses is consolidating how commercial buyers procure renewable capacity in Zimbabwe. Zimbabwe Electricity Supply Authority leverages its transmission monopoly to shape wheeling terms for independent generators. Tatanga Energy anchors its position through distributed solar engineering across agricultural zones. Great Zimbabwe Hydro dominates run-of-river development in the Eastern Highlands.
Zimbabwe renewable energy encompasses solar photovoltaics, wind turbines, biomass systems, and hydro power installations that convert natural energy flows into grid-connected or off-grid electricity, with photovoltaic modules typically rated between 300W and 600W per panel and designed for tropical irradiance conditions. These systems primarily serve industrial, commercial, and rural electrification objectives where national grid coverage remains incomplete. Solar photovoltaics leads installed capacity due to modularity and declining module costs, while microgrid systems within the technology dimension captures the fastest deployment trajectory as mining and agricultural estates seek island-capable resilience. Energy storage commands the deepest margin pool because lithium-ion battery integration with solar arrays remains supply-constrained and technically specialized.
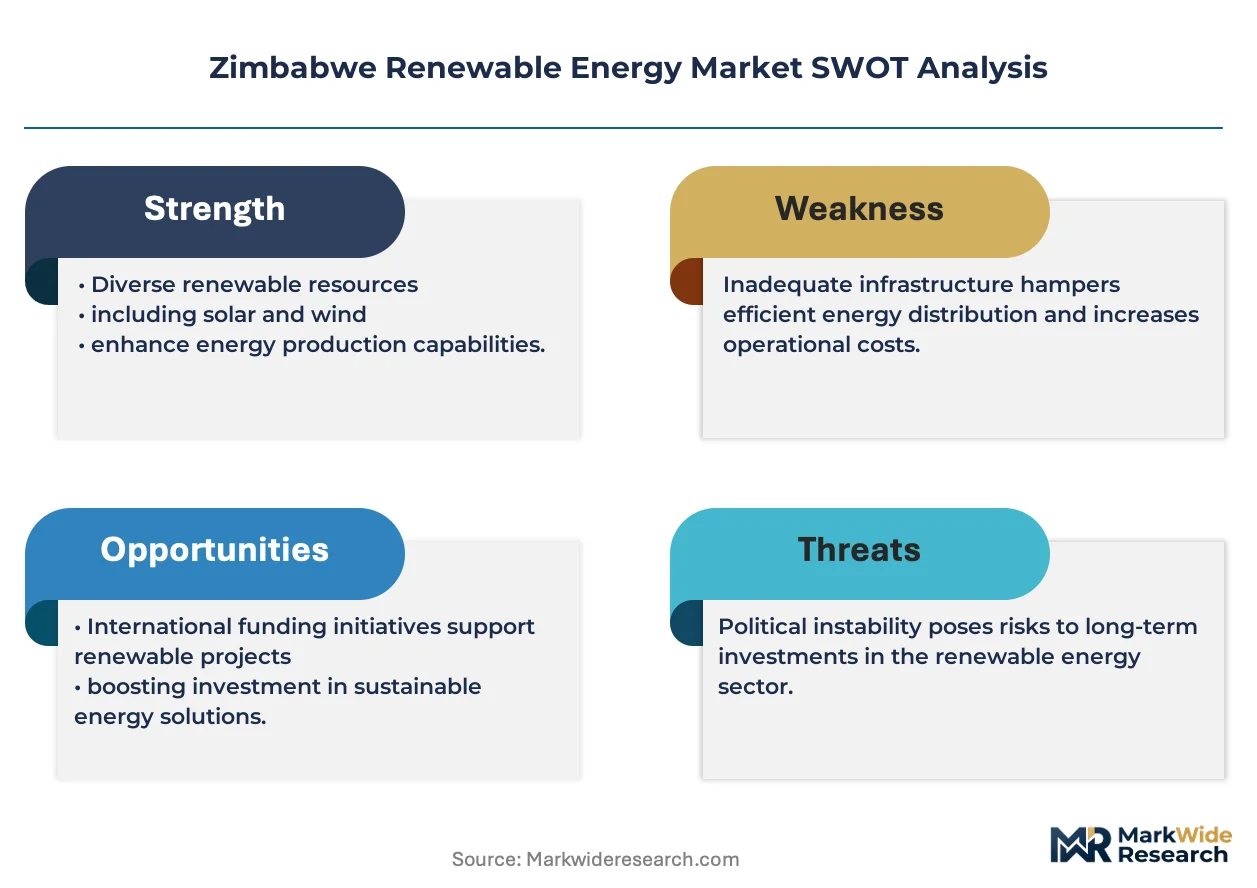
Zimbabwe Energy Regulatory Authority governs licensing and tariff setting for independent power producers, while the Rural Electrification Agency directs subsidy flows toward off-grid solar and mini-hydro schemes in unserved districts. Both frameworks shape market access by determining which projects qualify for priority dispatch and foreign currency retention privileges. The central bank's renewable energy financing facility further channels liquidity toward biomass and small hydro developers that can demonstrate bankable offtake contracts. Stakeholders must monitor how licensing backlogs and currency convertibility rules affect project commissioning timelines.
Market Dynamics
Wheeling rights granted by the Zimbabwe Energy Regulatory Authority are restructuring how independent power producers commercialize distributed generation assets across the national grid. Mining houses and agricultural estates now contract directly with solar developers rather than queuing for Zimbabwe Electricity Supply Authority allocation.
Growth Catalysts
- Grid Wheeling Liberalization:The Zimbabwe Energy Regulatory Authority now permits electricity wheeling across transmission infrastructure, unlocking revenue streams for independent generators serving dispersed industrial offtakers.
- Mining Sector Energy Security Mandates:Platinum and gold producers face operational losses from grid instability, driving captive solar procurement with island-mode capability for processing continuity.
- Manicaland Small Hydro Cluster:Run-of-river sites in the Eastern Highlands benefit from established agricultural load centers and existing distribution infrastructure.
Market Restraints
- Lithium-Ion Battery Supply Bottlenecks:Energy storage integration remains constrained by foreign currency shortages affecting importation of battery management systems and cells.
- Zimbabwe Electricity Supply Authority Transmission Monopoly:Single-entity control over wheeling tariffs and priority dispatch creates pricing opacity for independent power producers.
- Biomass Feedstock Seasonality:Sugar cane bagasse and timber waste availability fluctuates with agricultural cycles, undermining baseload reliability for cogeneration projects.
Strategic Opportunities
- Masvingo Province Electrification Gap:Unserved rural districts present mini-grid deployment potential for solar-diesel hybrid systems serving schools and health clinics.
- Central Bank Renewable Financing Facility:Biomass and small hydro developers with bankable offtake contracts access priority liquidity through this dedicated credit window.
- Solar-Storage Convergence:Declining module costs combined with lithium-ion integration enables 24-hour power supply contracts previously reserved for thermal generators.
Industry Challenges
- Licensed Electrical Artisan Shortage:Grid-tied solar installation and battery commissioning require certified technicians that training institutions produce insufficiently.
- Zimbabwe Energy Regulatory Authority Licensing Backlogs:Protracted approval timelines delay project commissioning and erode developer returns through extended capital lockup.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zimbabwe Renewable Energy Market |
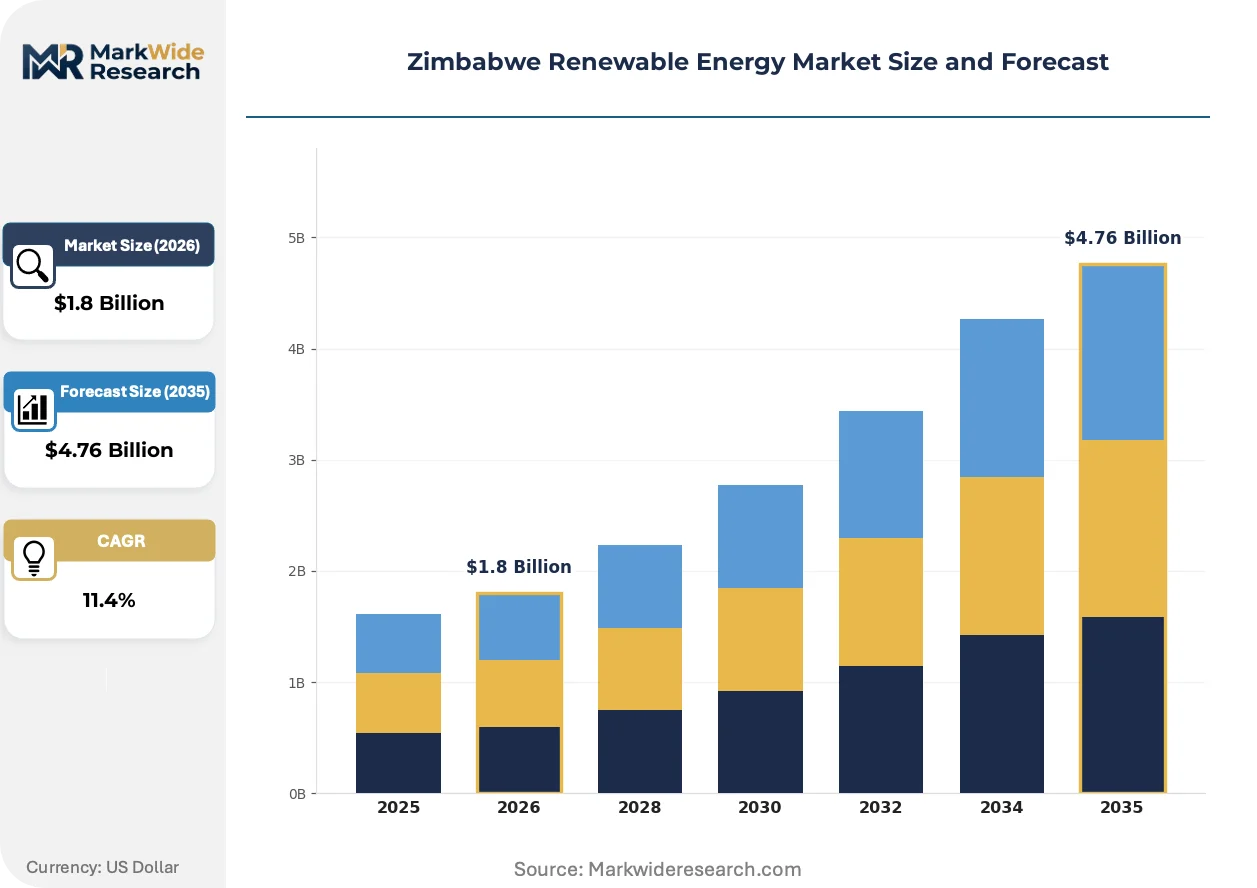
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar Photovoltaics, Wind Turbines, Biomass Systems, Hydro Power Application: Residential, Commercial, Industrial, Off-Grid Technology: Concentrated Solar Power, Microgrid Systems, Smart Inverters, Energy Storage End User: Utilities, Government, NGOs, Private Enterprises |
| Companies Covered | Solar Energy Projects, Zimbabwe Electricity Supply Authority, Tatanga Energy, Tanganda Tea Company, Zimbabwe Energy Regulatory Authority, Energywise Equipment, Great Zimbabwe Hydro, Green Hybrid Power, De-Green Rhino Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zimbabwe Renewable Energy Market Evolving Landscape
Technology convergence and procurement model evolution are compressing deployment timelines for commercial-scale renewable assets. Developers now bundle engineering, equipment supply, and long-term maintenance into unified service contracts.
Bifacial photovoltaic modules rated for tropical irradiance conditions are absorbing elevated ambient temperatures that degrade monofacial panel output in Zimbabwe's high-insolation zones. Tea estates in Manicaland are deploying these units at scale to maximize yield per hectare of installation footprint. The technology is absorbing market share from conventional crystalline silicon configurations by delivering superior performance degradation curves under sustained heat exposure.
The Rural Electrification Agency has redirected subsidy flows toward productive-use mini-grids rather than household solar kits, altering developer incentive structures. Projects must now demonstrate commercial load anchoring to qualify for capital grants. Agricultural processing cooperatives in Mashonaland Central are the primary beneficiaries, accessing cold storage and irrigation pumping through village-scale solar installations.
Power purchase agreements with embedded operations and maintenance clauses are displacing equipment-only transactions in the commercial and industrial segment. Mining houses now procure kilowatt-hours rather than kilowatts, transferring performance risk to developer balance sheets. This shift concentrates in the platinum belt along the Great Dyke, where grid instability has made energy security a board-level priority.
Zimbabwe Renewable Energy Market Segmentation
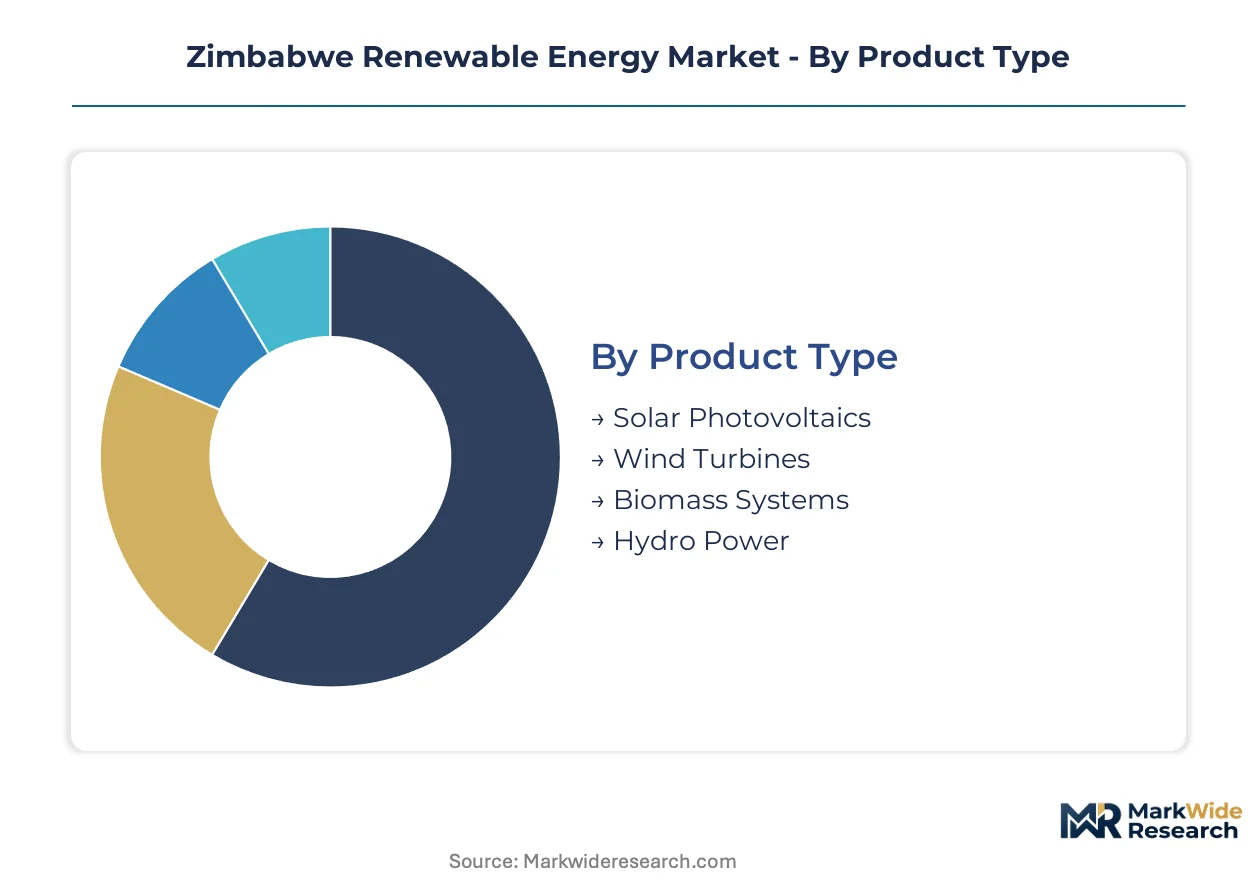
Segmentation in Zimbabwe's renewable energy market reveals how procurement patterns split between standardized utility-scale installations and customized captive systems for mining and agricultural estates. Technology selection, application scale, and end-user risk tolerance determine configuration complexity across each dimension.
Product Type:
Standardization dominates solar photovoltaics and wind turbines, while hydro power and biomass systems require site-specific engineering across Zimbabwe's varied terrain.
- Solar Photovoltaics:Modular panels rated 300W to 600W convert tropical irradiance into grid-tied or off-grid electricity. Mining houses in the Great Dyke platinum belt deploy bifacial configurations to maximize yield per hectare while hedging against grid instability.
- Hydro Power:Run-of-river installations exploit Eastern Highlands topography without reservoir construction. Manicaland province anchors development where tea estates and existing distribution infrastructure cluster around perennial streams.
- Wind Turbines:Small-scale turbines supplement solar in hybrid configurations for rural electrification. Zimbabwe Energy Regulatory Authority licensing reforms now permit independent generators to wheel wind-derived electricity across the national grid.
- Biomass Systems:Cogeneration units burn sugar cane bagasse and timber waste. Seasonal feedstock availability constrains baseload reliability for agricultural processing cooperatives in lowland districts.
Leading the category by volume: Solar Photovoltaics. Growing fastest: Hydro Power.
Application:
Scale determines procurement sophistication, with industrial buyers demanding performance guarantees and residential segments prioritizing capital accessibility.
- Industrial:Mining and agricultural estates procure kilowatt-hours rather than kilowatts, embedding operations and maintenance clauses into long-term power purchase agreements. Platinum producers require island-mode capability for processing continuity during grid failures.
- Off-Grid:Mini-grid systems serve schools, health clinics, and agricultural processing cooperatives where national coverage remains incomplete. The Rural Electrification Agency redirects subsidy flows toward productive-use installations with commercial load anchoring.
- Commercial:Retail and hospitality operators in urban centers favor grid-tied solar to reduce Zimbabwe Electricity Supply Authority dependency. Wheeling rights enable direct contracting with independent power producers.
- Residential:Household solar kits face declining subsidy priority as the Rural Electrification Agency shifts capital grants toward village-scale productive-use systems.
Industrial applications command the deepest margin pool. Off-Grid deployments are climbing the fastest as electrification gaps persist in Masvingo province.
Technology:
Integration complexity separates mature hardware from emerging system architectures requiring specialized commissioning expertise.
- Energy Storage:Lithium-ion battery integration with solar arrays enables 24-hour supply contracts previously reserved for thermal generators. Foreign currency shortages constrain importation of battery management systems and cells.
- Microgrid Systems:Island-capable architectures combine generation, storage, and control systems for mining estate resilience. The technology is expanding most quickly as energy security becomes a board-level priority.
- Smart Inverters:Grid-interactive power electronics manage voltage regulation and reactive power support. Zimbabwe Electricity Supply Authority technical standards govern interconnection compliance.
- Concentrated Solar Power:Thermal storage configurations remain pre-commercial in Zimbabwe's market, limited by capital intensity and absence of established project finance templates.
Energy Storage leads technology investment by value. Microgrid Systems are gaining share fastest among commercial and industrial buyers.
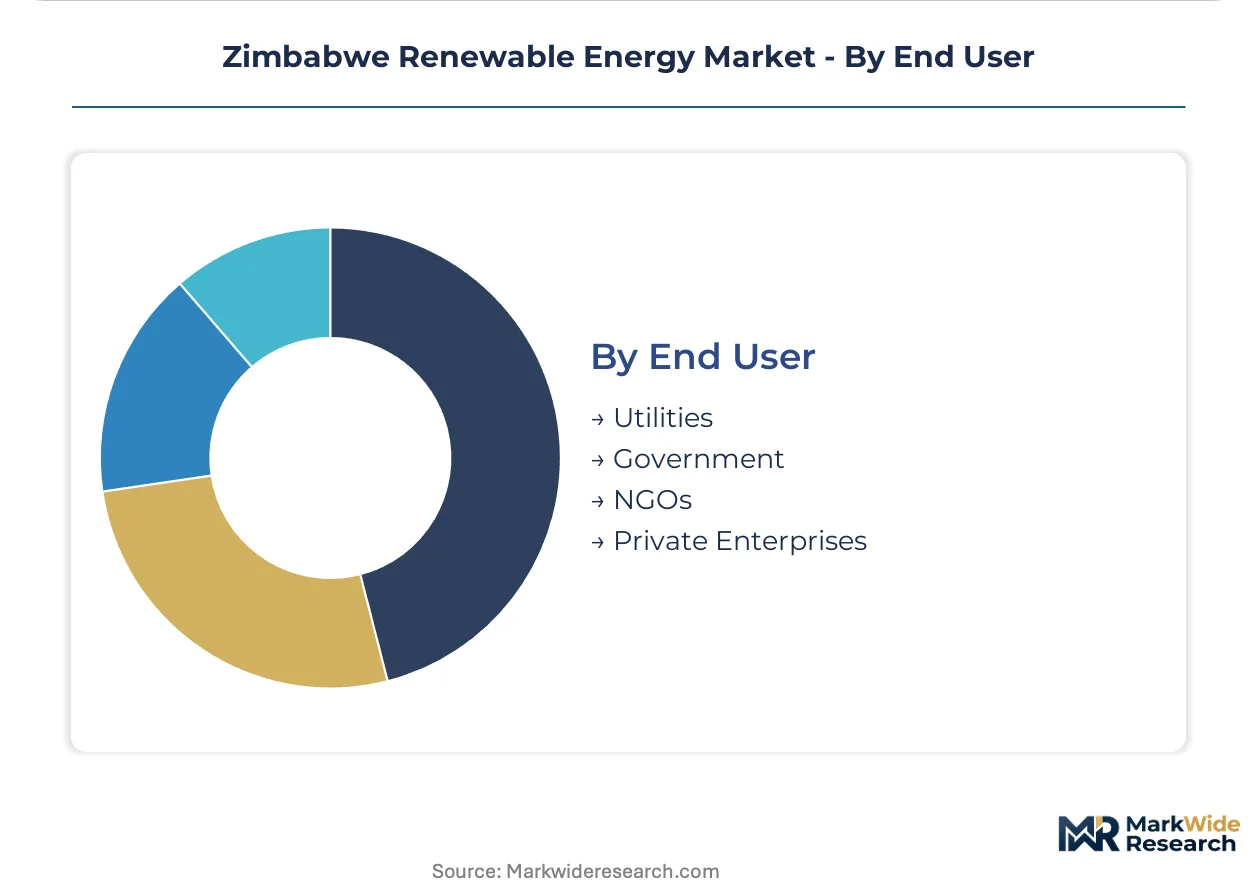
End User:
Risk tolerance and procurement sophistication vary sharply between public sector budget cycles and private sector performance contracting.
- Private Enterprises:Mining houses and agricultural estates drive captive solar deployment through direct developer relationships. Wheeling liberalization permits independent power producers to serve dispersed industrial offtakers without Zimbabwe Electricity Supply Authority allocation queues.
- Utilities:Zimbabwe Electricity Supply Authority maintains transmission monopoly and shapes wheeling tariffs for independent generators. The entity leverages grid control to influence priority dispatch and foreign currency retention privileges.
- Government:Central bank renewable energy financing facility channels liquidity toward biomass and small hydro developers with bankable offtake contracts. Ministry procurement follows public tender regulations with extended timelines.
- NGOs:Development finance institutions and international cooperatives fund rural electrification through grant and concessional debt structures. Projects must demonstrate alignment with national energy access targets.
Private Enterprises dominate capacity additions by volume. Utilities retain gatekeeper influence over grid access regardless of generation ownership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manicaland province generates the bulk of Zimbabwe's small hydro output yet consumes less than half locally, forcing wheeling arrangements across the national grid. Masvingo and Mashonaland provinces present the widest electrification gaps, redirecting subsidy flows toward productive-use mini-grids. The Rural Electrification Agency's capital grant criteria now favor commercial load anchoring over household solar kits.
Manicaland Province
Tea estates and agricultural processing cooperatives drive run-of-river hydro demand along the Eastern Highlands. The Zimbabwe Energy Regulatory Authority licenses independent power producers to wheel electricity across the national grid, unlocking revenue for distributed generators. Mutare and Chipinge cluster development where perennial streams intersect established distribution infrastructure.
Masvingo Province
Unserved rural districts present mini-grid deployment potential for solar-diesel hybrid systems serving schools and health clinics. The Rural Electrification Agency redirects subsidy flows toward productive-use installations with demonstrated commercial load anchoring. Agricultural processing cooperatives in Masvingo Central access cold storage through village-scale solar installations.
Mashonaland Central
Irrigation pumping and cold storage requirements anchor solar procurement for agricultural cooperatives in this grain-producing zone. The central bank's renewable energy financing facility channels liquidity toward developers with bankable offtake contracts. Bindura and Mount Darwin concentrate deployment where grid coverage remains incomplete.
Mashonaland West
Platinum and gold producers in the Great Dyke belt procure captive solar with island-mode capability for processing continuity. Zimbabwe Electricity Supply Authority transmission monopoly shapes wheeling tariffs for independent generators serving mining estates. Chinhoyi and Kadoma anchor development where energy security has become a board-level priority.
Midlands Province
Chrome mining and ferroalloy processing drive industrial solar demand amid persistent grid instability. The Zimbabwe Energy Regulatory Authority licensing backlog delays project commissioning and erodes developer returns through extended capital lockup. Gweru and Kwekwe concentrate procurement where mining houses contract directly with developers rather than queuing for utility allocation.
Zimbabwe Renewable Energy Market Competitive Landscape
Top-tier vendors anchor utility-scale and large captive installations, while mid-tier developers concentrate on distributed agricultural and commercial systems. The vendor base splits between integrated engineering-procurement-construction firms and specialized equipment suppliers. Three archetypes dominate: state-linked utilities controlling transmission access, independent power producers leveraging wheeling liberalization, and agricultural estate developers building captive resilience. Competitive moves center on securing priority dispatch agreements and locking in long-term power purchase contracts with embedded maintenance clauses.
Among Zimbabwe-based developers, Tatanga Energy exemplifies the distributed solar engineering archetype across agricultural zones, while Great Zimbabwe Hydro occupies the run-of-river specialist position in the Eastern Highlands. Solar Energy Projects represents the independent power producer model capitalizing on wheeling rights to serve dispersed industrial offtakers.
| Leading Market Players |
|---|
| Solar Energy Projects |
| Zimbabwe Electricity Supply Authority |
| Tatanga Energy |
| Tanganda Tea Company |
| Zimbabwe Energy Regulatory Authority |
| Energywise Equipment |
| Great Zimbabwe Hydro |
| Green Hybrid Power |
| De-Green Rhino Energy |
| Others |
Value Network & Pricing Analysis
Bifacial photovoltaic module adoption across Zimbabwe's platinum belt simultaneously compresses levelized cost of energy and concentrates procurement leverage among mining estates with scale to negotiate direct developer relationships. This technology transition reshapes both capital expenditure structures and supplier selection criteria as commercial buyers bypass traditional equipment-only transactions.
Pricing Analysis
Margin tightening in commercial and industrial solar reflects power purchase agreement proliferation with embedded operations and maintenance clauses transferring performance risk to developers. Three-tier pricing structure across premium, standard, and economy levels separates island-capable microgrid configurations from basic grid-tied installations and subsidized rural electrification kits. Cost-down pressure on energy storage accelerates because foreign currency shortages constrain lithium-ion battery importation. Mining houses exhibit lowest price sensitivity due to energy security mandates, while agricultural cooperatives in Mashonaland Central face acute capital constraints.
Supply Chain Analysis
Photovoltaic module supply rests on Chinese, Vietnamese, and Malaysian manufacturing hubs serving Zimbabwe through South African distribution channels. Lithium-ion cells, battery management systems, and bifacial glass-glass modules constitute critical input dependencies. Single-source vulnerability concentrates in inverter and power electronics sourcing where certified grid-interactive equipment faces Zimbabwe Electricity Supply Authority technical compliance requirements. Distribution runs through Johannesburg-based logistics nodes with final-mile engineering services delivered by Harare and Bulawayo contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Zimbabwe's renewable energy sector sits at a technology-transition inflection where microgrid architectures displace standalone solar installations. Battery-solar convergence enables 24-hour supply contracts previously reserved for thermal generators, rewarding developers with integrated engineering capabilities.
For Market Incumbents: Hedge against Zimbabwe Energy Regulatory Authority licensing backlog erosion by pre-securing grid interconnection agreements before capital deployment. Deepen backward integration into energy storage system assembly to circumvent foreign currency-denominated battery import bottlenecks. Prioritize long-term power purchase agreements with platinum producers in the Great Dyke belt where energy security mandates sustain premium pricing. For New Entrants and Emerging Players: Wheeling liberalization under Zimbabwe Energy Regulatory Authority reforms opens a window for independent power producers to serve dispersed agricultural estates without utility allocation queues. Target Masvingo Province mini-grid deployments where Rural Electrification Agency subsidy criteria now favor productive-use installations with commercial load anchoring. Lead with solar-diesel hybrid engineering expertise to differentiate from standardized panel suppliers. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by mining houses seeking captive energy security and by regional independent power producers expanding wheeling-enabled portfolios. Five-to-ten year viability hinges on developer ability to demonstrate bankable offtake contracts qualifying for central bank renewable energy financing facility liquidity. Watch Zimbabwe Electricity Supply Authority transmission tariff negotiations as the inflection signal determining independent generator margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Structuring | Embedded O&M clauses transfer performance risk and lock in developer revenue visibility. |
| Energy Storage Integration | Lithium-ion battery pairing with solar arrays enables baseload-equivalent supply contracts. |
| Wheeling Rights Acquisition | Zimbabwe Energy Regulatory Authority permits unlock revenue streams for distributed generators. |
| Backward Integration into BMS Assembly | In-house battery management system production mitigates foreign currency import constraints. |
| Productive-Use Mini-Grid Development | Rural Electrification Agency capital grants now require commercial load anchoring for qualification. |
Research Methodology
Multi-period observation of licensing application volumes, project commissioning timelines, and wheeling agreement registrations anchored the trend analysis, supplemented by interviews with independent power producer development officers, Zimbabwe Energy Supply Authority transmission planners, Rural Electrification Agency program managers, and mining house energy procurement leads. Secondary validation drew from Zimbabwe Energy Regulatory Authority licensing databases, central bank renewable energy financing facility disbursement records, and project developer EPC contract filings. Bottom-up capacity addition tracking and top-down macroeconomic scenario modeling provided cross-verification.
Segment-weighting across the analysis window applied technology type, application scale, end-user risk profile, and provincial regulatory framework as dimensional anchors. CAGRs derived from fitted growth curves calibrated to historical deployment trajectories and policy implementation schedules. Forecast inputs incorporated Zimbabwe Electricity Supply Authority grid stability indices and mining sector production continuity requirements.
Caveats apply where currency convertibility rule shifts or lithium-ion supply chain disruptions could materially shift the outlook. Forecasts reflect assumptions about regulatory backlog resolution and transmission infrastructure investment pacing. A small set of triggers—Zimbabwe Energy Regulatory Authority staffing expansion, central bank foreign exchange allocation priority changes, and regional battery cell manufacturing capacity announcements—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Finland Renewable Energy Market
Renewable Energy
Tidal Energy Generation Systems Market
Renewable Energy
Saudi Arabia Renewable Energy Market
Renewable Energy
Turkey Renewable Energy Market
Renewable Energy
West Europe Renewable Energy Market
Renewable Energy
Solar Traffic Light Market
Renewable Energy
Rectenna Market
Renewable Energy
Solar Tree Market
Renewable Energy
Renewable Energy Consulting Market
Renewable Energy
Wave Energy Converter Market
Renewable Energy
Peru Renewable Energy Market
Renewable Energy
Solar Bicycle Shed Market
Renewable Energy
Tunisia Renewable Energy Market
Renewable Energy
New Zealand Renewable Energy Market
Renewable Energy
Wind Turbine Inspection Drones Market
Renewable Energy
France Renewable Energy Market