
 Industrial Solar Water Heaters Market | 2026-2036
Industrial Solar Water Heaters Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Solar Water Heaters Market Outlook
Capital-intensity divergence between flat-plate collector fabricators and evacuated tube assemblers is redrawing competitive boundaries across the supply base. Apricus Solar Co. Ltd. leverages its integrated evacuated tube manufacturing to control input costs across Asia-Pacific deployments. SunEarth anchors North American project pipelines through localized absorber plate production and regional certification depth. Alternate Energy Technologies LLC differentiates via specialized glazing and frame systems tailored to commercial-scale roof loads.
Industrial solar water heaters harness solar thermal energy through flat-plate or evacuated tube collectors to generate process heat ranging from 60°C to 120°C for commercial and manufacturing operations. These systems typically incorporate insulated storage tanks, heat exchangers, and either thermosyphon or forced circulation architectures to transfer thermal energy to industrial workflows. Pumped circulation systems command the widest deployment footprint across chemical processing and textile applications where temperature precision and volume throughput outweigh capital cost sensitivity. Thermosyphon configurations retain dominance in hospitality and smaller food processing installations where passive operation reduces maintenance overhead and extends equipment lifespan. Batch heater and integral collector storage segments occupy niche positions in pre-heating applications with lower temperature setpoints and intermittent draw profiles.
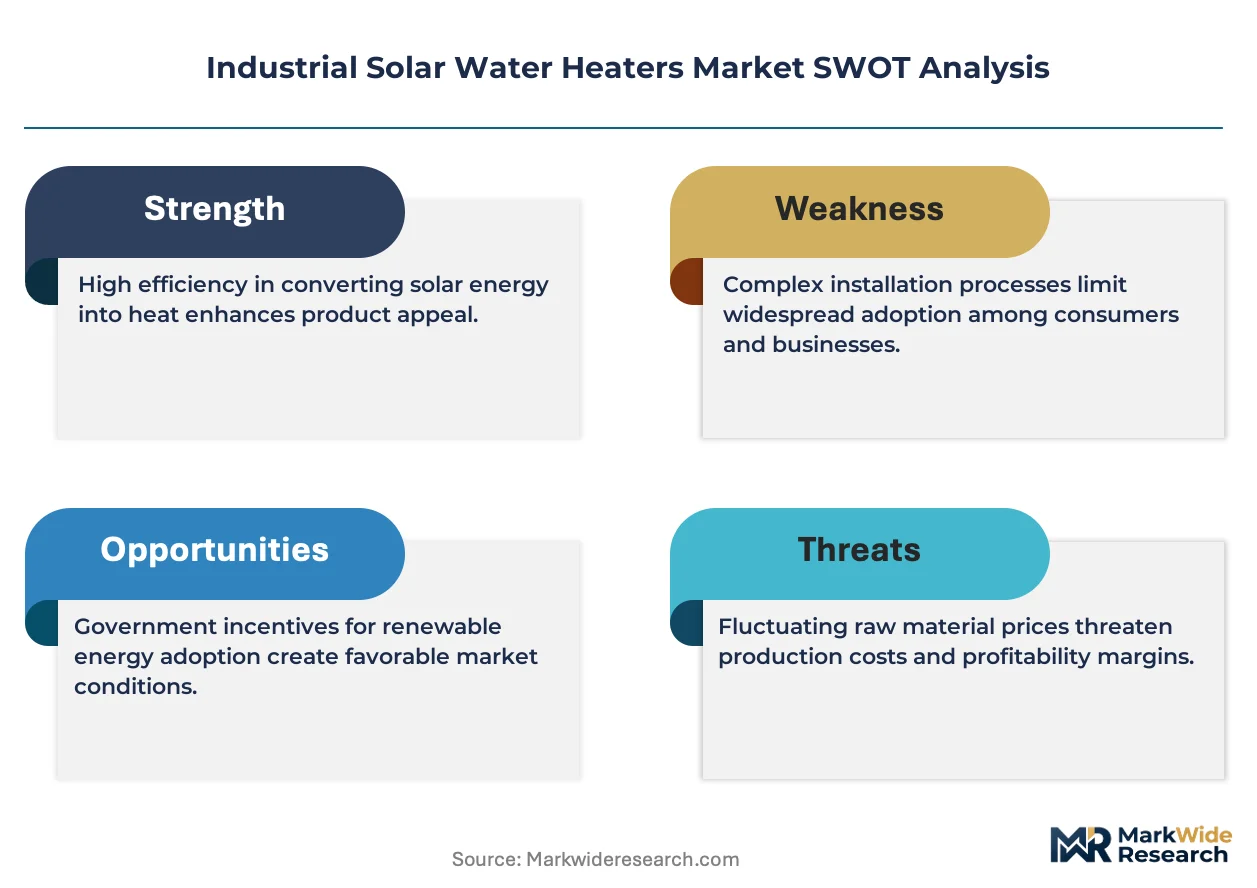
India's Bureau of Energy Efficiency mandates and the country's PLI scheme for solar thermal components are accelerating industrial adoption through capital subsidy linkage and performance-linked manufacturing incentives. The EU Green Deal and F-Gas Regulation constrain conventional heat pump alternatives in European process industries, redirecting capital toward solar thermal retrofits in Germany, Spain, and Italy. China's GB standards for solar thermal performance and dual carbon targets impose efficiency floors that filter lower-tier domestic suppliers from state-backed industrial projects. Stakeholders must monitor regulatory calibration cycles across these jurisdictions, as subsidy phase-out timelines and carbon border adjustment mechanisms will determine competitive cost positioning faster than collector technology evolution alone.
Market Dynamics
Capital-intensity divergence between flat-plate collector fabricators and evacuated tube assemblers is redrawing competitive boundaries across the supply base. This structural force concentrates procurement power among vertically integrated manufacturers while forcing modular assemblers toward niche customization or exit.
Growth Catalysts
- India's PLI scheme for solar thermal components:Performance-linked manufacturing incentives accelerate domestic production capacity for evacuated tubes and absorber plates.
- EU F-Gas Regulation constraints:Phasedown of hydrofluorocarbon-based heat pumps redirects industrial process heat capital toward solar thermal retrofits in Germany, Spain, and Italy.
- Textile belt concentration in Gujarat:State-level renewable purchase obligations and process heat requirements create clustered procurement demand for pumped circulation systems.
Market Restraints
- Copper and aluminum input volatility:Absorber plate manufacturing faces margin compression from base metal price swings in commodity markets.
- Evacuated tube supply concentration:Borosilicate glass sourcing clusters in specific Chinese provinces, creating single-point vulnerability for non-integrated assemblers.
- Seasonal output variability:Solar thermal systems deliver inconsistent thermal energy in high-latitude industrial zones during winter months.
Strategic Opportunities
- Food processing pre-heat applications:Batch heater configurations address intermittent draw profiles in dairy and beverage facilities with lower temperature setpoints.
- China's dual carbon targets:GB standards for solar thermal performance filter lower-tier suppliers from state-backed industrial projects, opening share for certified entrants.
- Direct-to-facility installation partnerships:EPC contractors bypass traditional distribution layers to capture margin in commercial-scale deployments.
Industry Challenges
- Thermal engineer scarcity:System design and integration expertise for forced circulation architectures remains concentrated among legacy specialists.
- Legacy steam infrastructure retrofit complexity:Industrial sites with existing boiler networks face integration friction when overlaying solar thermal loops.
- Regional certification fragmentation:Divergent testing protocols across North American, European, and Asian jurisdictions extend product validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Solar Water Heaters Market |
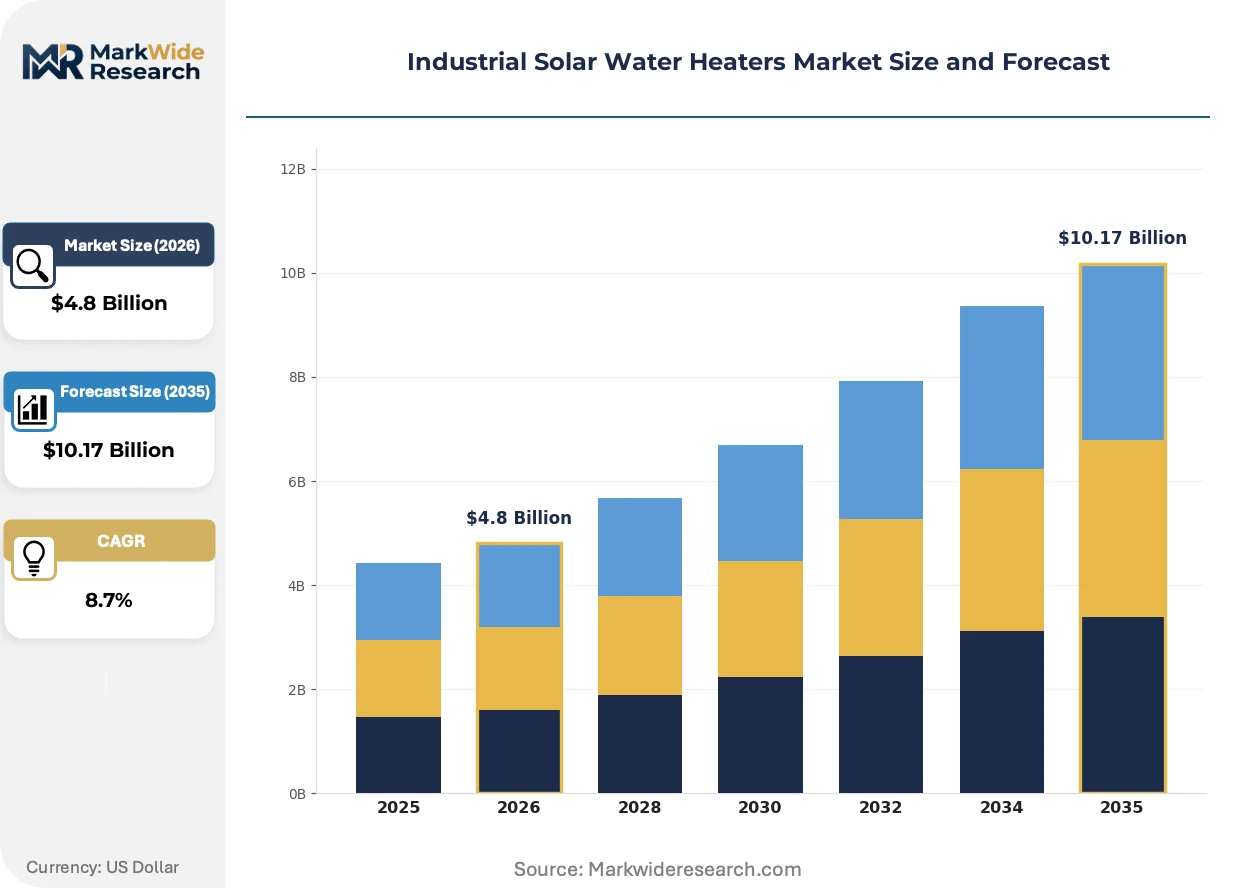
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Thermosyphon, Pumped Circulation, Batch Heater, Integral Collector Storage Application Area: Food Processing, Textile, Chemical Processing, Hospitality Installation Type: Roof-mounted, Ground-mounted, Wall-mounted, Elevated Heat Transfer Fluid: Water, Antifreeze Solutions, Oil, Others |
| Companies Covered | Apricus Solar Co. Ltd., SunEarth, Alternate Energy Technologies LLC, ATR Solar, Racold, SunMaxx Solar, Heliodyne, Inc., Chandrlok International, Greentek India Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Solar Water Heaters Market Strategic Shifts
Collector technology evolution and procurement model restructuring are compressing traditional competitive moats. Manufacturers now compete on thermal output predictability and lifecycle service bundling rather than hardware specifications alone.
Polymer-based absorber coatings are fragmenting established supply relationships in flat-plate collector manufacturing. Chemical processing facilities in Mediterranean zones adopt these lower-cost alternatives for sub-80°C applications. The technology is fragmenting procurement patterns that previously favored copper-aluminum composite absorbers.
China's GB standards for solar thermal performance impose efficiency floors that filter lower-tier domestic suppliers from state-backed industrial projects. Manufacturers must retest legacy product lines against revised thermal output metrics. State-owned chemical processors and textile conglomerates now exclude uncertified equipment from tender eligibility.
Performance-guarantee contracting is displacing upfront equipment sales in large-scale deployments. Industrial buyers in India's food processing corridor now contract thermal output volumes rather than collector arrays. This model transfers operational risk to system integrators and compresses capital recovery timelines for project developers.
Industrial Solar Water Heaters Market Segmentation
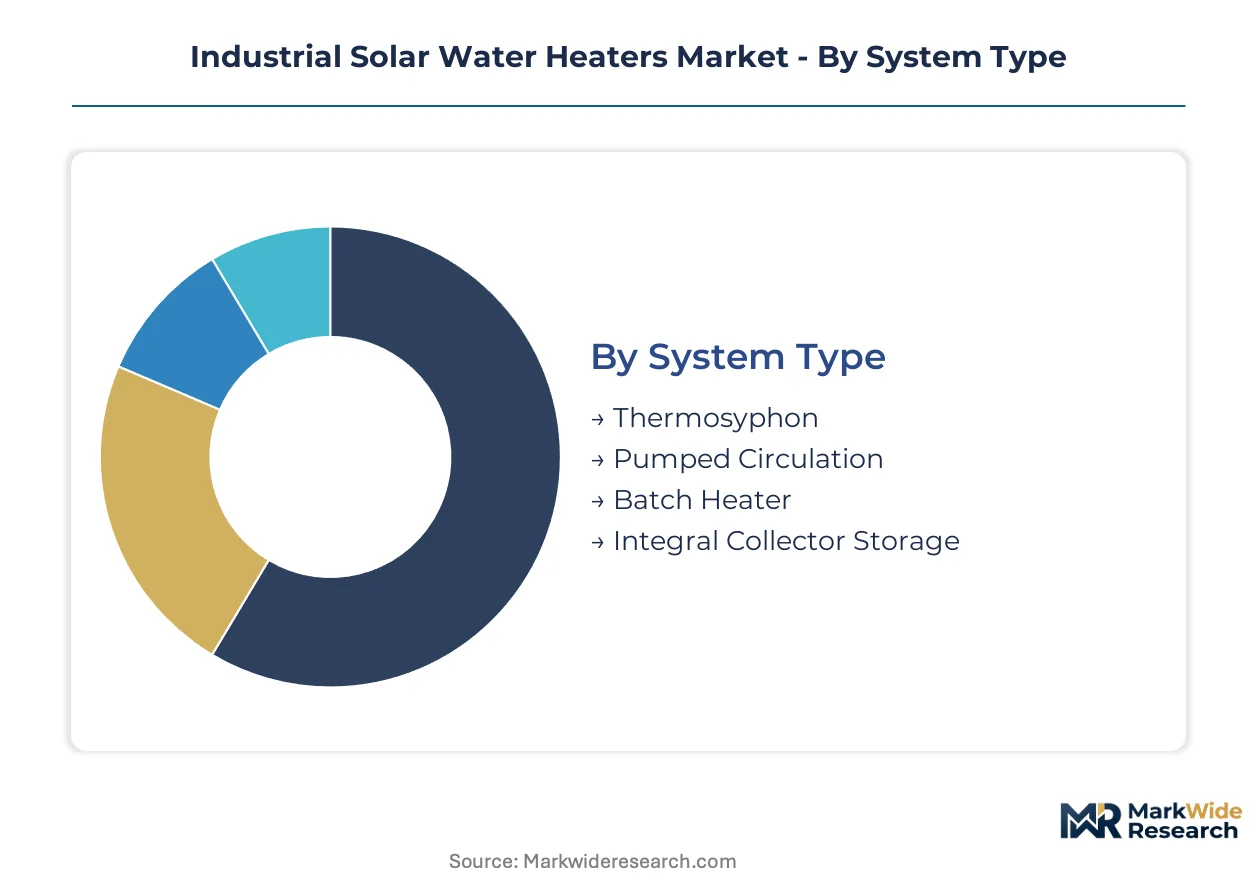
Industrial solar water heater procurement flows through distinct channel pathways shaped by system complexity and installation scale. System type determines whether projects route through specialized thermal integrators or general mechanical contractors. Application area and installation configuration further fragment distribution, with food processing and textile clusters commanding dedicated regional supply chains.
System Type:
Channel mix varies sharply across system architectures, with forced circulation designs flowing through engineering-procurement-construction consortia while passive systems reach end-users via HVAC distributors.
- Pumped Circulation:Active forced-circulation architectures deploy pumps, heat exchangers, and precision controls to deliver 60°C to 120°C process heat. Chemical processing facilities in Gujarat's industrial corridor specify these systems for continuous dyeing and bleaching operations where temperature stability overrides capital cost sensitivity.
- Thermosyphon:Passive thermosyphon configurations rely on natural convection through insulated storage tanks and collector arrays without mechanical circulation. Hospitality installations across India's resort belt favor these systems for their minimal maintenance overhead and extended operational lifespan in intermittent draw profiles.
- Batch Heater:Integral storage-collector units suit pre-heating applications with lower temperature setpoints.
- Integral Collector Storage:Combined collector-tank designs serve niche retrofit scenarios with space-constrained roof structures.
Pumped circulation dominates installed base. Thermosyphon configurations are where expansion concentrates in small-to-mid scale commercial deployments.
Application Area:
End-use concentration shapes regional manufacturing footprints, with textile and chemical processing demands pulling supply chain localization toward industrial clusters.
- Textile:Process heat requirements for dyeing, finishing, and washing operations consume the largest share of collector deployment. Gujarat's textile belt generates clustered procurement through state-level renewable purchase obligations and Bureau of Energy Efficiency mandates.
- Food Processing:Dairy pasteurization, beverage sterilization, and ingredient washing drive demand for hygienic heat transfer designs. India's PLI scheme for solar thermal components accelerates domestic manufacturing capacity to serve this segment's capital subsidy eligibility.
- Chemical Processing:Reactor heating and solvent recovery applications require corrosion-resistant materials and elevated pressure ratings.
- Hospitality:Hotels and resorts prioritize passive system architectures for laundry and kitchen hot water with minimal technical staffing.
Textile applications anchor current installed capacity. Food processing is climbing the fastest as subsidy linkage and hygiene-grade certification expand addressable market scope.
Installation Type:
Structural mounting configurations segment procurement by project scale and existing building constraints, with roof-mounted arrays flowing through commercial roofing contractors.
- Roof-mounted:Standard flat-roof and pitched-roof installations constitute the predominant deployment architecture across manufacturing facilities and commercial buildings. Alternate Energy Technologies LLC specializes in glazing and frame systems engineered for commercial-scale roof loads and wind uplift resistance.
- Ground-mounted:Field arrays on dedicated land parcels serve large thermal loads where roof area proves insufficient. Chemical processing complexes in Spain deploy these configurations for solar fraction targets exceeding fifty percent of annual process heat demand.
- Wall-mounted:Vertical collector integration addresses sites with limited horizontal surface area.
- Elevated:Raised structural platforms accommodate shading constraints or multi-level facility layouts.
Roof-mounted systems hold majority share in existing building stock. Ground-mounted installations are gaining share fastest in greenfield industrial park developments.
Heat Transfer Fluid:
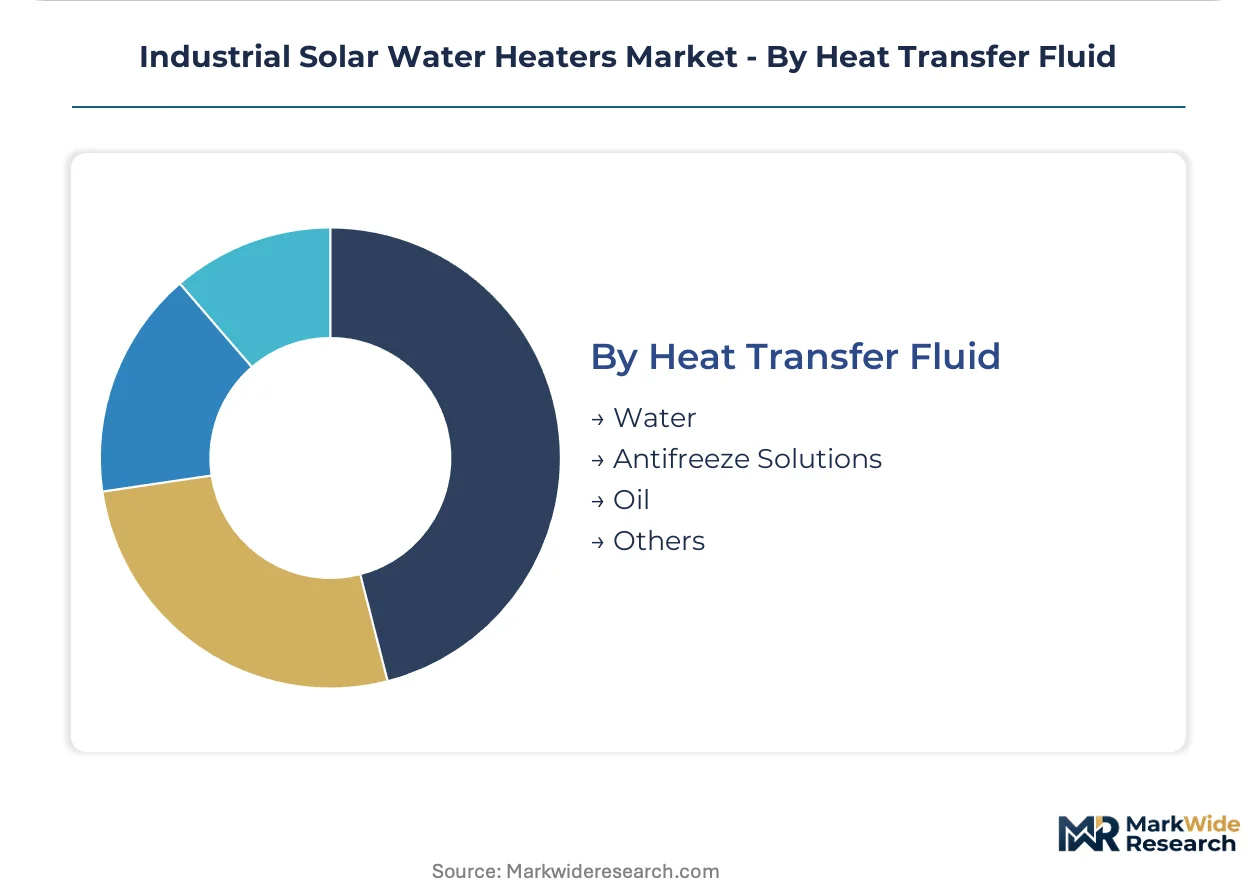
Fluid selection determines collector materials compatibility and operational temperature range, with water-based systems commanding cost-sensitive segments.
- Water:Direct water circulation through absorber plates and storage tanks serves temperate climate installations without freeze risk. Mediterranean food processing facilities adopt water-based loops for sub-80°C pre-heating applications where polymer-based absorber coatings reduce capital outlay.
- Antifreeze Solutions:Propylene glycol and ethylene glycol mixtures enable year-round operation in high-latitude industrial zones. Germany's chemical processors specify these fluids to maintain thermal output through winter months despite seasonal irradiance variability.
- Oil:Synthetic and mineral thermal oils extend operational range beyond water's boiling point for high-temperature process integration.
- Others:Emerging nanofluid formulations and ionic liquids occupy experimental niches in research-intensive deployments.
Water-based systems dominate installed base. Antifreeze configurations are where expansion concentrates as cold-climate mandates extend operational season requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in industrial solar water heaters track manufacturing capability against deployment mandates. China and India export evacuated tube assemblies to Southeast Asian processors while importing specialized glazing systems from European fabricators. Germany and Spain balance domestic collector production with Mediterranean project development.
China
GB standards for solar thermal performance filter supplier eligibility for state-backed industrial tenders. The country's dual carbon targets accelerate textile and chemical processor adoption in Shandong and Jiangsu provinces. Borosilicate glass production clusters in Hebei supply evacuated tube assemblers serving domestic and export markets.
India
Gujarat's textile belt concentrates pumped circulation system procurement through state renewable purchase obligations. The Bureau of Energy Efficiency mandates solar thermal integration in industrial plants above specified thermal load thresholds. Maharashtra's food processing corridor leverages PLI scheme subsidies for domestic absorber plate manufacturing.
Germany
The EU F-Gas Regulation phases down hydrofluorocarbon-based heat pumps in chemical processing facilities. REACH compliance requirements shape materials selection for collector glazing and frame systems. Industrial parks in North Rhine-Westphalia retrofit solar thermal loops into legacy steam infrastructure.
Spain
EU Green Deal funding channels accelerate solar thermal retrofits in Mediterranean food processing and chemical sectors. Andalusian olive oil processors deploy ground-mounted arrays to meet solar fraction targets exceeding fifty percent. Madrid-based engineering firms specialize in performance-guarantee contracting for large-scale deployments.
United States
California's Title 24 building standards drive commercial solar thermal adoption in hospitality and food processing segments. Pacific Northwest chemical processors specify antifreeze-based systems for year-round operation despite seasonal irradiance variability. Texas industrial parks integrate roof-mounted collector arrays into new manufacturing facility construction.
Industrial Solar Water Heaters Market Competitive Environment
Concentration sits with vertically integrated evacuated tube manufacturers and regional flat-plate specialists. The supply base organizes around three archetypes: integrated glass-to-collector producers, modular absorber plate fabricators, and system integration specialists. Backward integration into borosilicate glass production separates tier-one suppliers from assemblers exposed to input volatility. Geographic certification depth and localized testing capabilities constitute the primary competitive moats.
Within the integrated manufacturing tier, Apricus Solar Co. Ltd. exemplifies control over input costs through captive evacuated tube production. SunEarth anchors North American positioning through regional certification infrastructure and absorber plate fabrication. Alternate Energy Technologies LLC occupies a specialization niche in glazing and frame systems engineered for commercial roof loads. These three represent distinct strategic postures: Asia-Pacific vertical integration, North American regional depth, and component-level engineering specialization.
| Leading Market Players |
|---|
| Apricus Solar Co. Ltd. |
| SunEarth |
| Alternate Energy Technologies LLC |
| ATR Solar |
| Racold |
| SunMaxx Solar |
| Heliodyne, Inc. |
| Chandrlok International |
| Greentek India Pvt. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day lead times for borosilicate glass tubing concentrate pricing power among integrated evacuated tube manufacturers while forcing modular assemblers toward spot-market exposure. This inventory compression tightens margins for flat-plate collector fabricators facing copper and aluminum volatility.
Pricing Analysis
Configured-to-order pricing commands a 15-25% premium over standard catalog configurations for forced circulation systems with custom heat exchanger specifications. Project-based long-term contracting dominates large-scale deployments, with price differentiation driven by GB certification tier and volume scale. Cost compression in economy-tier flat-plate segments is intensifying as polymer absorber coatings displace copper-aluminum composites. Food processing buyers exhibit highest price sensitivity, while chemical processors prioritize thermal output predictability over capital outlay.
Supply Chain Analysis
China and India anchor evacuated tube and absorber plate production, with Hebei province supplying borosilicate glass to domestic and export assemblers. Manufacturing draws from copper sheet, aluminum extrusion, and low-iron tempered glass inputs. Single-source vulnerability concentrates in borosilicate glass sourcing, where Hebei production clusters create geographic chokepoint risk. Distribution runs through EPC contractor consortia for pumped circulation systems and HVAC distributors for passive thermosyphon configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial solar water heaters sit in early-cycle expansion as India's PLI scheme and EU F-Gas constraints accelerate substitution away from conventional heat pumps. Penetration remains below 15% in addressable process heat applications.
For Market Incumbents: Fortify backward integration into borosilicate glass production to neutralize input volatility from Hebei supply concentration. Deepen regional certification infrastructure in North America and EU jurisdictions to extend competitive moats against emerging Asian entrants. Prioritize captive absorber plate manufacturing to defend margin position against polymer coating substitution. For New Entrants and Emerging Players: GB certification fast-track through China's National Center for Quality Supervision and Test of Solar Heating Products unlocks state-backed tender eligibility. Target India's Maharashtra food processing corridor, where PLI-linked capital subsidies reduce customer acquisition friction. Deploy direct-to-facility EPC partnerships to bypass traditional distribution layers and capture margin in commercial-scale deployments. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across polymer absorber coating segments as manufacturing scales. Five-to-ten-year viability favors integrated glass-to-collector producers with captive borosilicate supply and multi-jurisdiction certification depth. Watch GB standard revision cycles as the signal for supplier consolidation windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Borosilicate Glass | Hebei supply concentration creates margin vulnerability for non-integrated assemblers. |
| GB Certification Fast-Track | China's revised thermal output metrics filter lower-tier suppliers from state tenders. |
| Direct-to-Facility EPC Partnerships | Bypassing HVAC distributors captures margin in Gujarat textile belt deployments. |
| Polymer Absorber Coating Scale-Up | Sub-80°C food processing applications favor lower-cost alternatives to copper-aluminum. |
| Performance-Guarantee Contracting | India's food processors now contract thermal output volumes rather than hardware arrays. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with solar thermal system integrators, EPC contractors, and plant engineers at textile and chemical processing facilities; and secondary validation against Bureau of Energy Efficiency mandate filings, EU F-Gas Regulation implementation trackers, and customs trade data for evacuated tube assemblies. Bottom-up installation counts across Gujarat, Maharashtra, Shandong, and Jiangsu provinces triangulated against top-down addressable process heat estimates.
Across the analysis window, forecasts model system type segmentation by circulation architecture, application area concentration in textile and food processing corridors, and installation configuration by mounting type. CAGRs derive from adoption curve modeling against regulatory mandate timelines and subsidy phase-out schedules. Key inputs include solar fraction targets in EU Green Deal funding channels and PLI scheme capacity addition trajectories.
Underlying assumptions cover subsidy continuity in India and EU carbon border adjustment implementation, with deviation risk concentrated in copper and aluminum commodity price swings. Recalibration cycles align with GB standard revision announcements and Bureau of Energy Efficiency mandate threshold adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Sunlight Control System Market
Solar Power Systems
Portugal Distributed Solar Energy Market
Solar Power Systems
GCC Solar Microinverter Market
Solar Power Systems
Global Rooftop Solar Photovoltaic Market
Solar Power Systems
Global Solar Panel Materials Market
Solar Power Systems
Off-Grid Solar Power Market
Solar Power Systems
CPV Solar Sales Market
Solar Power Systems
Commercial Solar Panel Market
Solar Power Systems
Solar Polysilicon Ingot Wafer Cell Module Market
Solar Power Systems
Spray-On Solar Cells Market
Solar Power Systems
Slovakia Solar Energy Market
Solar Power Systems
Amorphous Silicon PV Market
Solar Power Systems
Asia-Pacific Solar Photovoltaic (PV) Market
Solar Power Systems
United States Distributed Solar Power Generation Market
Solar Power Systems
Solar Freezer Market
Solar Power Systems
UV Solar Simulators Market