
 Middle East and Africa Solar Photovoltaic (PV) Market | 2026-2036
Middle East and Africa Solar Photovoltaic (PV) Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Solar Photovoltaic (PV) Market Analysis
A capital-intensity divergence between integrated developers and pure technology suppliers is reorganizing competitive tiers across the Middle East and Africa. ACWA Power leverages its balance-sheet scale to dominate utility-scale concessions in Saudi Arabia and Egypt. Masdar anchors its position through captive project development tied to UAE sovereign capital. JinkoSolar Holding Co Ltd competes on module cost curves and regional logistics networks.
Middle East and Africa Solar Photovoltaic (PV) systems convert solar irradiance into direct-current electricity through semiconductor junctions, with crystalline silicon modules achieving commercial efficiencies above 21 percent in desert conditions. These installations primarily displace fossil-fuel generation for grid-connected power and off-grid industrial supply. Crystalline silicon occupies the dominant product position due to proven bankability and supply chain depth. Utility-scale application leads absolute capacity additions across the region, while bifacial module technology captures growing share in high-albedo desert environments.
Saudi Arabia's National Renewable Energy Program, South Africa's REIPPPP auction rounds, and UAE net metering frameworks collectively determine project origination timelines and offtake security. Morocco's ONEE grid codes and Egypt's renewable energy regulatory authority shape interconnection standards and local content requirements. Stakeholders must monitor sovereign liquidity conditions and currency convertibility protocols before committing capital to multi-decade power purchase agreements.
Market Dynamics
Utility-scale procurement by Saudi Arabia's ACWA Power and UAE's Masdar is concentrating project pipelines around sovereign-backed developers, squeezing independent sponsors from concession rounds.
Growth Catalysts
- Morocco's renewable energy law:Feed-in tariff frameworks under ONEE supervision secure long-term offtake for private developers. Bankable revenue streams attract European debt financing.
- Desert bifacial deployment:High-albedo sand conditions boost bifacial module yields above monofacial baselines. EPC contractors now specify dual-glass architectures for Saudi and UAE megaprojects.
- Industrial off-grid demand:Mining operations across South Africa and Namibia require captive solar-diesel hybrid supply. Remote load centers bypass grid interconnection queues entirely.
Market Restraints
- Polysilicon supply concentration:Chinese ingot and wafer capacity controls 80 percent of upstream supply. African developers face currency mismatch when contracting dollar-denominated module purchases.
- Grid code fragmentation:Egypt's renewable energy regulatory authority maintains distinct interconnection standards from Morocco's ONEE. Multi-country portfolios require redundant engineering compliance.
- Land tenure complexity:Saudi Arabia's Red Sea coastal concessions compete with ecotourism zoning. Environmental impact timelines extend project origination by 18-24 months.
Strategic Opportunities
- Green hydrogen offtake:Saudi Arabia's NEOM project will anchor gigawatt-scale electrolyzer demand. Solar developers can contract directly with hydrogen exporters rather than grid utilities.
- Net metering expansion:Dubai's Shams Dubai program now permits commercial rooftop aggregation. Distributed generation bypasses transmission bottlenecks in congested urban load centers.
- Agrivoltaic convergence:Shade-tolerant crop cultivation beneath elevated arrays addresses South African land-use conflicts. Dual revenue streams improve project returns in agricultural provinces.
Industry Challenges
- Local content compliance:Egypt's renewable energy authority mandates domestic module assembly for tariff eligibility. Supply chain reconfiguration absorbs 12-18 months of pre-construction engineering.
- Grid integration latency:South Africa's Eskom transmission backlog delays commercial operation dates. IPP developers absorb carrying costs through financial close.
- Skills migration:Experienced EPC project managers relocate to Saudi gigawatt-scale sites. Smaller Moroccan and Tunisian developments face construction supervision gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Solar Photovoltaic (PV) Market |
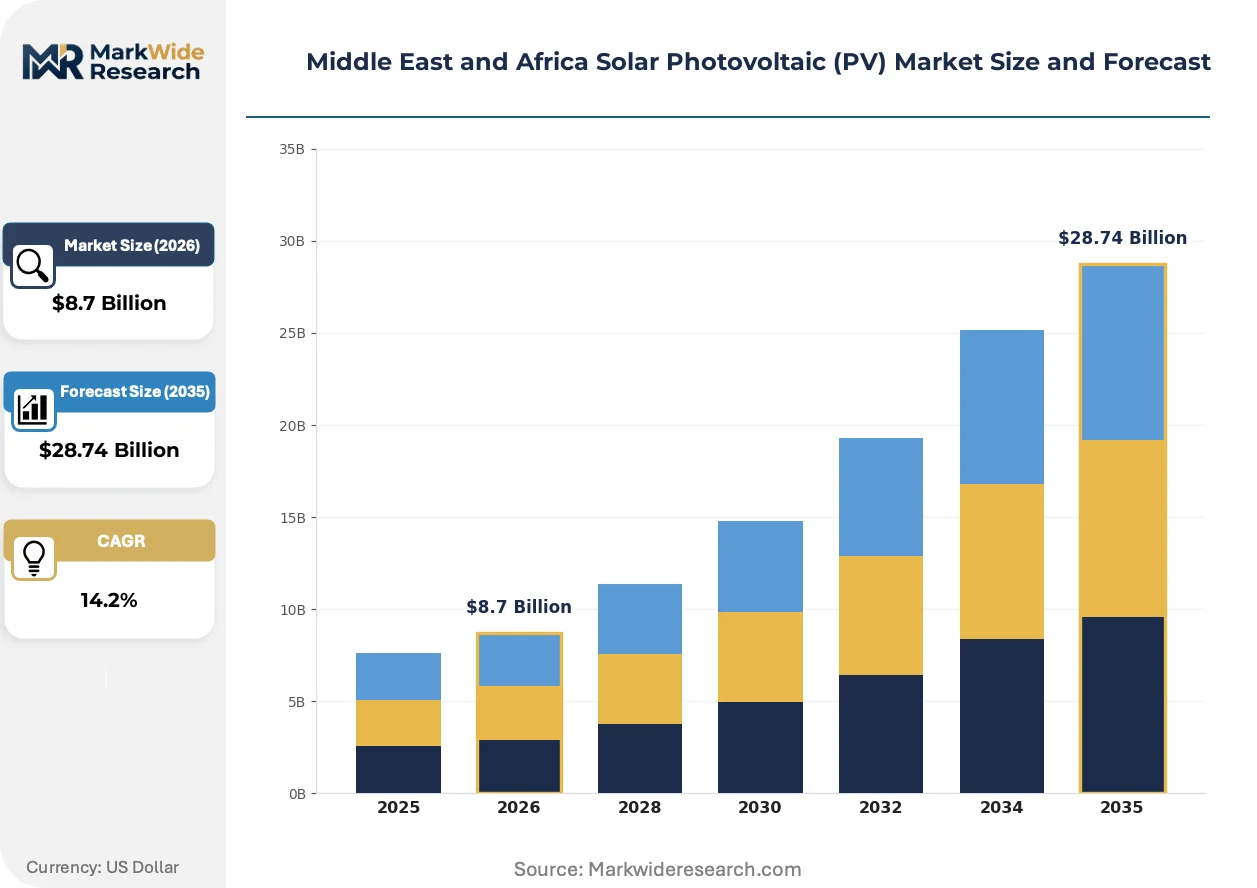
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crystalline Silicon, Thin-Film, Bifacial, Building-Integrated Application: Residential, Commercial, Industrial, Utility-Scale Technology: Conventional, Concentrated, Hybrid, Smart PV End User: Government, Private Sector, NGOs, Energy Producers |
| Companies Covered | Enerwhere Sustainable Energy DMCC, Masdar, JinkoSolar Holding Co Ltd, Juwi Solar Inc, AMEA Power, First Solar Inc, ACWA Power, Dubai Electricity & Water Authority, Canadian Solar Inc, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Solar Photovoltaic (PV) Market Emerging Trajectories
Bifacial module architecture and tracker automation are compressing levelized cost thresholds across desert solar belts, while regulatory frameworks race to accommodate merchant exposure.
Tracker automation is fragmenting the balance-of-plant procurement landscape. Single-axis tracking systems now achieve 25 percent yield gains over fixed-tilt baselines in high-DNI conditions. Saudi EPC contractors are unbundling tracker supply from module procurement, creating specialized vendor tiers for steel structure and control system integration.
South Africa's REIPPPP auction rounds are forcing tariff compression through competitive bidding. The program's seventh bid window introduced 24-hour dispatch requirements that favor solar-plus-storage configurations. Developers must now contract battery EPCs alongside PV engineering, reshaping project consortium structures.
Corporate power purchase agreements are displacing traditional utility offtakes in the UAE and Jordan. Aluminum smelters and data center operators now contract directly with solar IPPs for baseload supply. This merchant exposure concentrates in Dubai's free zones where regulatory sandbox frameworks permit bilateral contracting outside state utility tariffs.
Middle East and Africa Solar Photovoltaic (PV) Market Segmentation
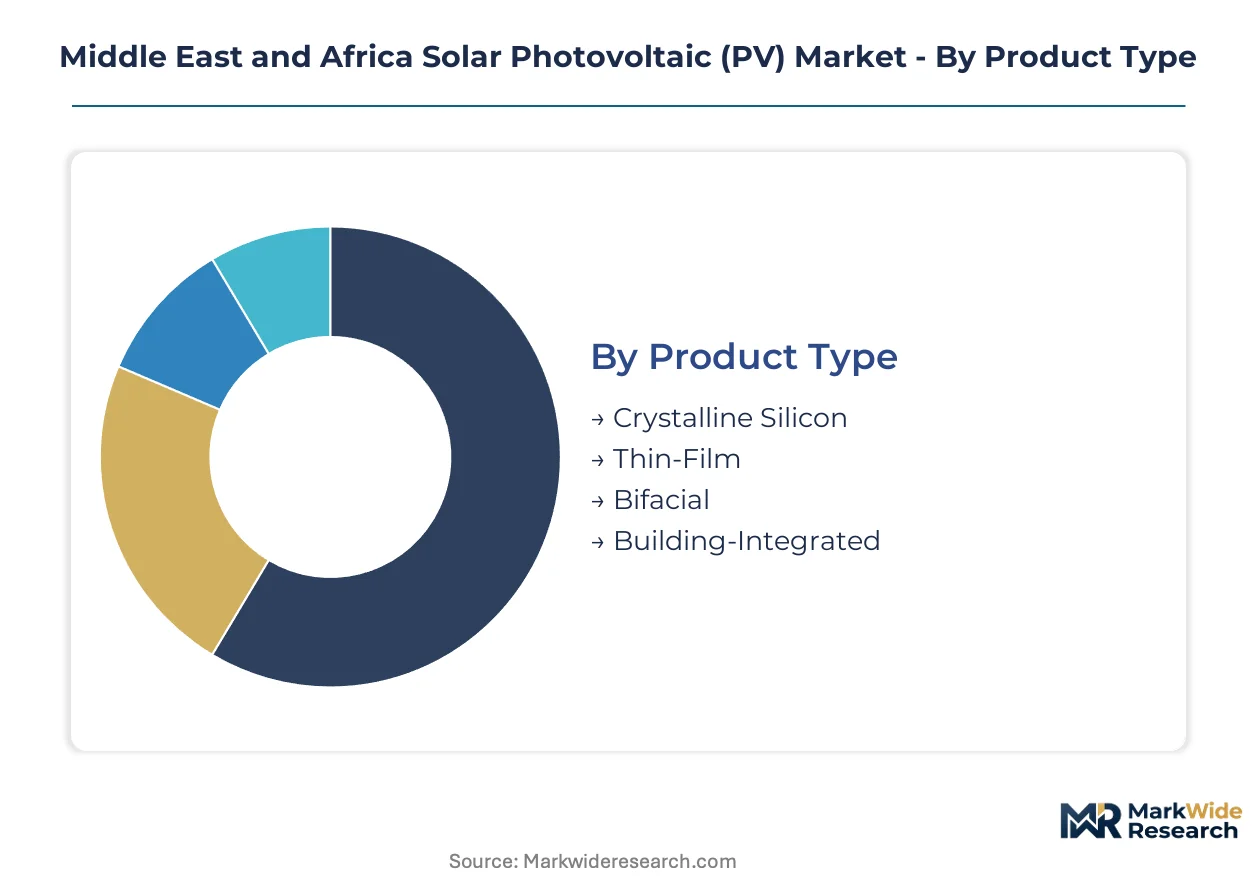
Segmentation across the Middle East and Africa Solar Photovoltaic (PV) market reveals divergent procurement channels and capital deployment patterns. Product type and application dimensions determine whether projects flow through sovereign-backed concession rounds, corporate direct contracting, or distributed installer networks.
Product Type:
Crystalline silicon and bifacial modules move through distinct supply channels—bankable utility-scale pipelines versus emerging merchant offtake structures—while thin-film and building-integrated products serve niche architectural and remote power applications.
- Crystalline Silicon:Dominant cell architecture employs monocrystalline or polycrystalline silicon wafers with commercial efficiencies exceeding 21 percent in desert conditions. Procurement concentrates through ACWA Power and Masdar utility-scale concessions in Saudi Arabia and the UAE, where proven bankability attracts European debt financing.
- Bifacial:Dual-glass modules capture reflected irradiance from high-albedo desert surfaces, yielding 25 percent gains over monofacial baselines when paired with single-axis tracking. Demand clusters in Saudi gigaprojects and UAE merchant solar developments where EPC contractors unbundle tracker supply from module procurement.
- Thin-Film:Cadmium-telluride and CIGS technologies serve distributed rooftop applications in Jordan and Morocco where weight constraints and partial shading tolerance outweigh efficiency premiums.
- Building-Integrated:Photovoltaic glazing and facade systems integrate with commercial architecture in Dubai's free zones and Cairo's new administrative capital, serving corporate sustainability mandates through net metering frameworks.
By volume, Crystalline Silicon leads. By growth pace, Bifacial is climbing the fastest.
Application:
Application segments stratify by capital intensity and offtake security, with utility-scale commanding sovereign balance sheets while residential and commercial flows depend on regulatory sandbox access.
- Utility-Scale:Ground-mounted installations exceeding 50 MW capacity anchor national renewable energy programs. Saudi Arabia's National Renewable Energy Program and South Africa's REIPPPP auction rounds concentrate procurement through sovereign-backed developers with multi-decade power purchase agreements.
- Industrial:Captive solar-diesel hybrid supply serves mining operations across Namibia and South Africa's Northern Cape, bypassing grid interconnection queues entirely through remote load center configuration.
- Commercial:Rooftop and carport installations in Dubai's Shams Dubai program and Jordan's net metering framework permit aggregation schemes that bypass transmission bottlenecks in congested urban load centers.
- Residential:Distributed generation remains nascent outside Morocco's ONEE-supervised feed-in tariff zones and Tunisia's prosumer frameworks, constrained by upfront capital requirements and limited financing channels.
Utility-Scale captures dominant capital deployment. Industrial applications show the steepest expansion trajectory as remote mining loads electrify.
Technology:
Technology segmentation tracks the shift from conventional fixed-tilt architectures toward automated tracking and hybrid configurations that meet dispatchability requirements.
- Conventional:Fixed-tilt crystalline silicon installations with string inverters remain the default for cost-sensitive markets. Deployment concentrates in Egypt's Benban solar park and Morocco's Noor-Ouarzazate complex where proven engineering reduces construction risk.
- Hybrid:Solar-plus-storage configurations combine PV arrays with lithium-ion battery systems to meet South Africa's REIPPPP seventh bid window dispatch requirements. Developers now contract battery EPCs alongside PV engineering, reshaping project consortium structures.
- Concentrated:Concentrated solar power with thermal storage occupies a declining share outside Morocco's Noor facilities, displaced by photovoltaic cost compression.
- Smart PV:Module-level power electronics and AI-driven predictive maintenance penetrate premium commercial installations in the UAE and Saudi Arabia's NEOM project where digital infrastructure integration justifies cost premiums.
Conventional technology retains installed base dominance. Hybrid configurations are gaining share fastest as grid codes mandate dispatchable renewable supply.
End User:
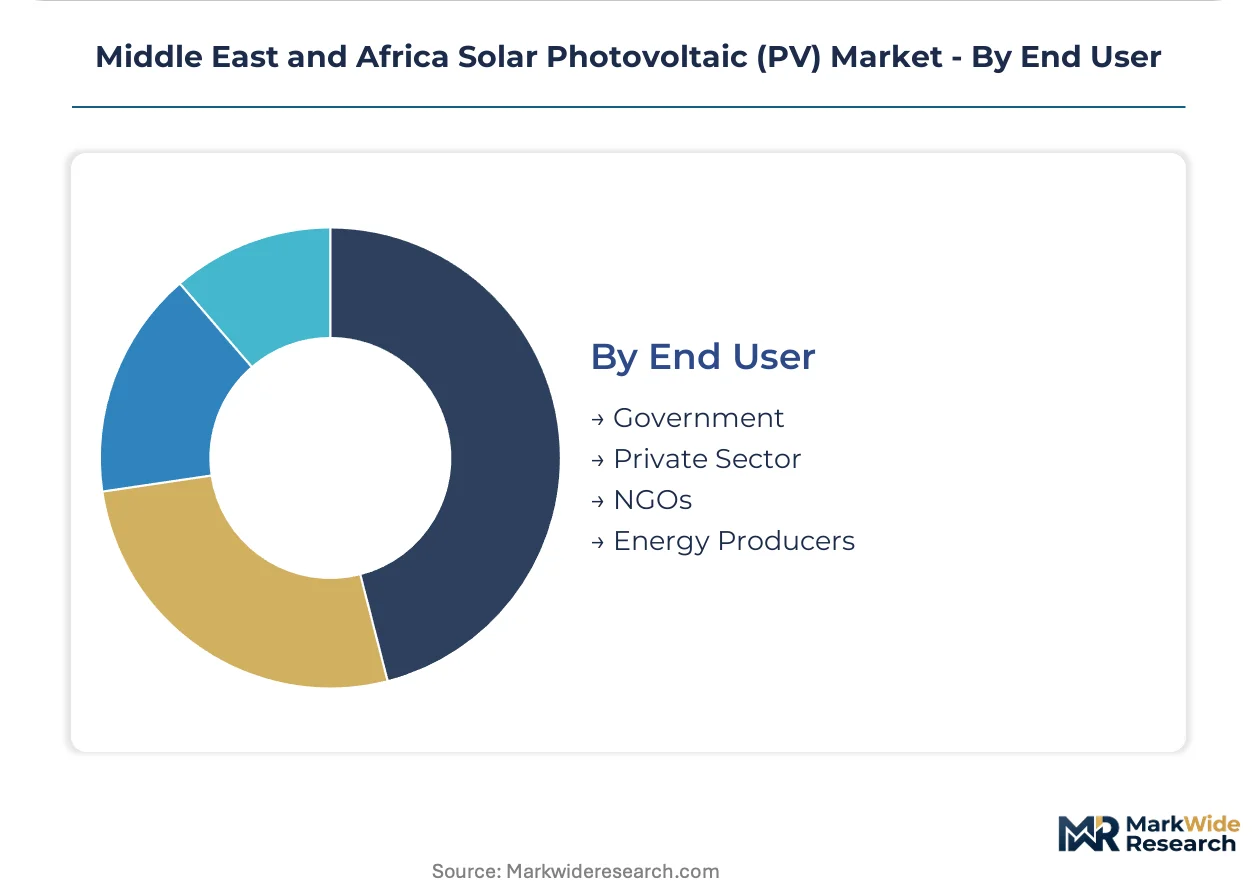
End user segmentation maps capital access hierarchies, with sovereign entities and energy producers controlling concession rounds while private sector and NGO participants navigate regulatory sandbox constraints.
- Government:National utilities and renewable energy authorities originate procurement through competitive auctions and feed-in tariff frameworks. Morocco's ONEE and Egypt's renewable energy regulatory authority shape interconnection standards and local content requirements that determine project eligibility.
- Energy Producers:IPP developers and independent power producers structure project finance around long-term offtake contracts. ACWA Power and Masdar anchor gigawatt-scale pipelines through captive balance sheet capacity and sovereign capital backing.
- Private Sector:Aluminum smelters, data center operators, and hydrogen exporters in Saudi Arabia's NEOM project now contract directly with solar developers for baseload supply, displacing traditional utility offtakes through bilateral corporate power purchase agreements.
- NGOs:Development finance institutions and multilateral lenders support rural electrification mini-grids across Sub-Saharan Africa, though currency convertibility protocols and sovereign liquidity conditions constrain capital commitment timelines.
Energy Producers lead absolute capacity additions. Private Sector direct contracting is expanding most quickly as merchant exposure concentrates in regulatory sandbox jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Module import dependency shapes deployment patterns across the Middle East and Africa. Dollar-denominated procurement from Chinese ingot and wafer suppliers creates currency mismatch risks for Egyptian and Moroccan developers. Sovereign-backed balance sheets in Saudi Arabia and the UAE absorb this exposure through captive project finance structures.
Saudi Arabia
ACWA Power originates gigawatt-scale concessions through the National Renewable Energy Program. The Saudi renewable energy regulatory authority mandates local content thresholds for tariff eligibility. NEOM anchors hydrogen-linked solar demand in the northwest corridor, with electrolyzer offtake contracting directly with developers.
United Arab Emirates
Masdar structures utility-scale pipelines around Abu Dhabi sovereign capital. Dubai's Shams Dubai net metering framework permits commercial rooftop aggregation schemes. Mohammed bin Rashid Al Maktoum Solar Park concentrates bifacial-plus-tracker deployment in the desert belt south of Dubai.
South Africa
REIPPPP auction rounds compress tariffs through competitive bidding. The seventh bid window introduced 24-hour dispatch requirements favoring solar-plus-storage configurations. The Northern Cape hosts mining-linked captive solar-diesel hybrid supply bypassing Eskom transmission queues.
Egypt
The Benban solar park exemplifies fixed-tilt crystalline silicon deployment at scale. The renewable energy regulatory authority maintains distinct grid codes from Morocco's ONEE, requiring redundant engineering compliance. Currency convertibility protocols constrain European debt financing timelines for private sponsors.
Morocco
ONEE-supervised feed-in tariffs secure long-term offtake under the renewable energy law. The Noor-Ouarzazate complex anchors concentrated solar power with thermal storage, though photovoltaic cost compression displaces this architecture. European development finance institutions channel capital through bankable revenue streams.
Middle East and Africa Solar Photovoltaic (PV) Market Vendor Landscape
Concentration sits with sovereign-backed developers and integrated technology suppliers. ACWA Power and Masdar control concession origination through captive balance sheet capacity. Three archetypes dominate: state-linked utilities deploying sovereign capital, Chinese module suppliers competing on cost curves, and European EPC contractors specializing in desert engineering. Competitive moves center on unbundling tracker procurement from module supply, and restructuring project consortia to incorporate battery EPCs alongside PV engineering.
Among sovereign-linked developers, ACWA Power and Masdar exemplify the state-capital archetype, anchoring gigawatt-scale pipelines through direct government backing. JinkoSolar Holding Co Ltd represents the technology-supplier tier, competing on regional logistics networks and module cost positioning. These three entities illustrate how capital access and supply chain integration determine competitive tiers across Middle Eastern and African solar markets.
| Leading Market Players |
|---|
| Enerwhere Sustainable Energy DMCC |
| Masdar |
| JinkoSolar Holding Co Ltd |
| Juwi Solar Inc |
| AMEA Power |
| First Solar Inc |
| ACWA Power |
| Dubai Electricity & Water Authority |
| Canadian Solar Inc |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts under Saudi Arabia's National Renewable Energy Program lock in module supply visibility and stabilize project-level pricing for IPP developers committing capital across multi-decade power purchase agreements. These structures insulate ACWA Power and Masdar from spot polysilicon volatility while exposing smaller Egyptian and Moroccan sponsors to currency mismatch when contracting dollar-denominated wafer purchases.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing structures across utility-scale concessions in Saudi Arabia and the UAE. Price differentiation rests on module efficiency tier and tracker integration complexity, with bifacial-plus-single-axis configurations commanding premiums over fixed-tilt baselines. Cost compression in crystalline silicon modules is intensifying because Chinese ingot capacity expansion outpaces regional demand absorption. Mining operators in South Africa's Northern Cape exhibit highest price sensitivity due to diesel parity calculations, while NEOM hydrogen exporters demonstrate lowest sensitivity given offtake certainty through sovereign-linked contracting.
Supply Chain Analysis
China and Malaysia anchor polysilicon ingot and wafer fabrication, feeding cell and module assembly across Southeast Asian export hubs. Polycrystalline silicon feedstock, silver paste metallization, and dual-glass encapsulation materials constitute critical input dependencies. Single-source vulnerability concentrates in Chinese ingot capacity controlling upstream supply. Distribution runs through Dubai's Jebel Ali port consolidation for Saudi and UAE megaprojects, with direct Shanghai-Mombasa routes serving East African distributed installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment through sovereign concession frameworks creates durable competitive positioning for incumbent developers with established government relationships.
For Market Incumbents: Secure captive balance sheet capacity to absorb currency mismatch exposure on dollar-denominated module procurement. Anchor pipeline origination through preemptive grid interconnection queue positioning ahead of South Africa's REIPPPP auction rounds. Vertical integration into tracker supply chains mitigates EPC contractor unbundling risks. For New Entrants and Emerging Players: Differentiate on agrivoltaic project development addressing South African land-use conflicts through dual revenue stream structuring. Target Namibia's mining-linked captive solar-diesel hybrid segment where grid bypass requirements eliminate concession competition from sovereign-backed utilities. Pursue direct corporate power purchase agreement origination with Dubai free zone aluminum smelters and data center operators outside state utility tariff frameworks. For Investors and Strategic Acquirers: Specialist EPC contractors with desert engineering expertise and established Saudi regulatory relationships represent priority acquisition targets. Long-term viability hinges on electrolyzer offtake contracting velocity at NEOM and comparable hydrogen-linked developments. Watch South Africa's Eskom transmission backlog resolution as inflection indicator for IPP commercial operation date compression and carrying cost normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Structuring | Long-term offtake contracts with NEOM hydrogen exporters bypass traditional utility intermediaries entirely. |
| Backward Integration into Tracker Supply | EPC contractors unbundle steel structure and control system procurement from module sourcing for yield optimization. |
| Green Certification Program | Morocco's ONEE feed-in tariff eligibility requires domestic content compliance reshaping supply chain footprints. |
| Technology Licensing | Bifacial module architecture licensing accelerates deployment across high-albedo Saudi desert solar belts. |
| Joint Venture | Sovereign capital partnerships with Masdar and ACWA Power anchor gigawatt-scale pipeline access for technology suppliers. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators across Saudi Arabia, the UAE, South Africa, Egypt, and Morocco; and secondary validation through IEA renewable energy databases, FERC-style regulatory filings, project development tracking databases, and customs trade records. Bottom-up capacity installation tallies triangulated against top-down policy target assessments.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning product architecture, application scale, technology configuration, and end-user capital access tier. CAGRs derived from installed base progression curves and policy-mandated auction timelines. Forecast inputs incorporated polysilicon cost trajectory assumptions and sovereign liquidity condition scenarios affecting multi-decade power purchase agreement bankability.
Forecasts assume regulatory continuity in Saudi Arabia's renewable energy regulatory authority frameworks, Morocco's ONEE-supervised feed-in tariff regimes, and South Africa's REIPPPP auction structures; material policy shifts would require re-modeling. Specific risks include currency convertibility protocol suspensions, grid code fragmentation escalation, and polysilicon supply chain disruption. Recalibration cycles align with material shifts in auction round announcements, electrolyzer offtake contracting velocity, and transmission infrastructure commissioning timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Asia-Pacific Distributed Solar Power Generation Market
Solar Power Systems
France Distributed Solar Power Generation Market
Solar Power Systems
Indonesia Renewable Energy Market
Solar Power Systems
Fixed Tilt Solar PV Market
Solar Power Systems
Solar Transparent Backsheet Market
Solar Power Systems
Middle-East and Africa Distributed Solar Power Generation Market
Solar Power Systems
US Solar Power Meters Market
Solar Power Systems
Asia Pacific Solar Backsheet Market
Solar Power Systems
Solar Encapsulation Market
Solar Power Systems
Global Micro Solar Inverter Market
Solar Power Systems
Canada Solar Energy Market
Solar Power Systems
Solar Panel Cleaning System Market
Solar Power Systems
Smart Solar Solutions Market
Solar Power Systems
Half-Cell Solar Module Market
Solar Power Systems
Solar Photovoltaic (PV) Market
Solar Power Systems
Global Rooftop Solar Photovoltaic Market