
 Residential Fuel Cell Market | 2026-2036
Residential Fuel Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Fuel Cell Market Insights
Buyer concentration among property developers is shifting as fragmented homeowner demand accelerates across retrofit and new-build segments. Panasonic Holdings Corporation leverages its integrated appliance-channel control to dominate Japanese residential deployments. Bloom Energy Corporation anchors utility-scale expertise while competing in premium single-family installations through solid oxide technology leadership.
Residential fuel cells electrochemically convert hydrogen or natural gas-derived reformate into electricity and usable heat, typically operating at 700 to 1,000 degrees Celsius for solid oxide variants with electrical efficiencies reaching 50 to 60 percent. Their primary purpose is on-site combined heat and power generation that reduces grid dependency and carbon intensity for dwellings. Polymer electrolyte membrane systems lead in deployment volume due to lower operating temperatures and faster startup profiles suited to residential cycling patterns, while solid oxide configurations capture margin pools where high heat-to-power ratios serve larger dwellings or multi-unit buildings. Grid-tied technology dominates current installations, though off-grid and microgrid architectures represent the fastest-expanding deployment category as resilience-motivated buyers seek islanding capability.
FDA oversight of hydrogen storage materials, EPA emissions thresholds for distributed generation, and Japan's METI certification standards collectively shape product design cycles and market access requirements for residential fuel cell manufacturers. South Korea's MFDS and KTL safety standards impose additional testing burdens that favor established suppliers with dedicated certification infrastructure. Stakeholders must monitor evolving hydrogen purity specifications and building code integrations that will determine which technology platforms achieve scalable permitting pathways.
Market Dynamics
Japan's NEDO subsidy framework and South Korea's renewable portfolio standards are compressing payback periods for polymer electrolyte membrane systems, pulling residential fuel cells from utility-scale margins into mass-market single-family deployments.
Growth Catalysts
- Net-zero building mandates:East Asian urban corridors enforce decarbonization timelines that favor on-site combined heat and power. Tokyo and Seoul municipal codes now require low-carbon baseload for new residential construction.
- Japan's METI certification standards:Streamlined safety protocols reduce manufacturer testing cycles. Certified systems qualify for accelerated grid interconnection and preferential feed-in tariff treatment.
- Polymer electrolyte membrane advances:Lower operating temperatures enable faster cold-start sequences. Single-family homeowners accept shorter cycling intervals that match intermittent renewable generation patterns.
Market Restraints
- Platinum catalyst cost volatility:Polymer electrolyte membrane stacks require iridium and platinum loadings that track precious metal commodity swings. Input cost spikes compress OEM margins without corresponding price elasticity in residential channels.
- South Korean supply concentration:Membrane electrode assembly production clusters around Seoul-Incheon industrial corridors. Geographic concentration risk amplifies disruption exposure from regional logistics constraints or labor actions.
- Solid oxide thermal cycling limitations:Ceramic stack materials degrade under rapid temperature fluctuations. Technical constraints restrict deployment in climates with wide diurnal temperature ranges or frequent start-stop duty cycles.
Strategic Opportunities
- Retrofit channel penetration:Existing single-family housing stock in Osaka and Busan remains underpenetrated. Aging gas infrastructure replacement cycles create installation windows for behind-the-meter fuel cell retrofits.
- Hydrogen-ready reformer convergence:Dual-fuel systems blending natural gas reformate with hydrogen blending are attracting R&D investment. Technology convergence positions residential units for fuel-switching without stack replacement.
- South Korea's MFDS fast-track pathway:Streamlined safety certification for established suppliers reduces time-to-market for next-generation systems. Regulatory tailwind favors incumbents with dedicated testing infrastructure.
Industry Challenges
- Electrolyzer stack assembly skill scarcity:Precision welding and thin-film coating expertise concentrates among semiconductor industry veterans. Talent migration from adjacent sectors intensifies wage pressure for specialized manufacturing roles.
- Building code integration complexity:Fire suppression and ventilation requirements vary across prefecture and municipal jurisdictions. Certification timeline fragmentation forces product variant proliferation that strains engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Fuel Cell Market |
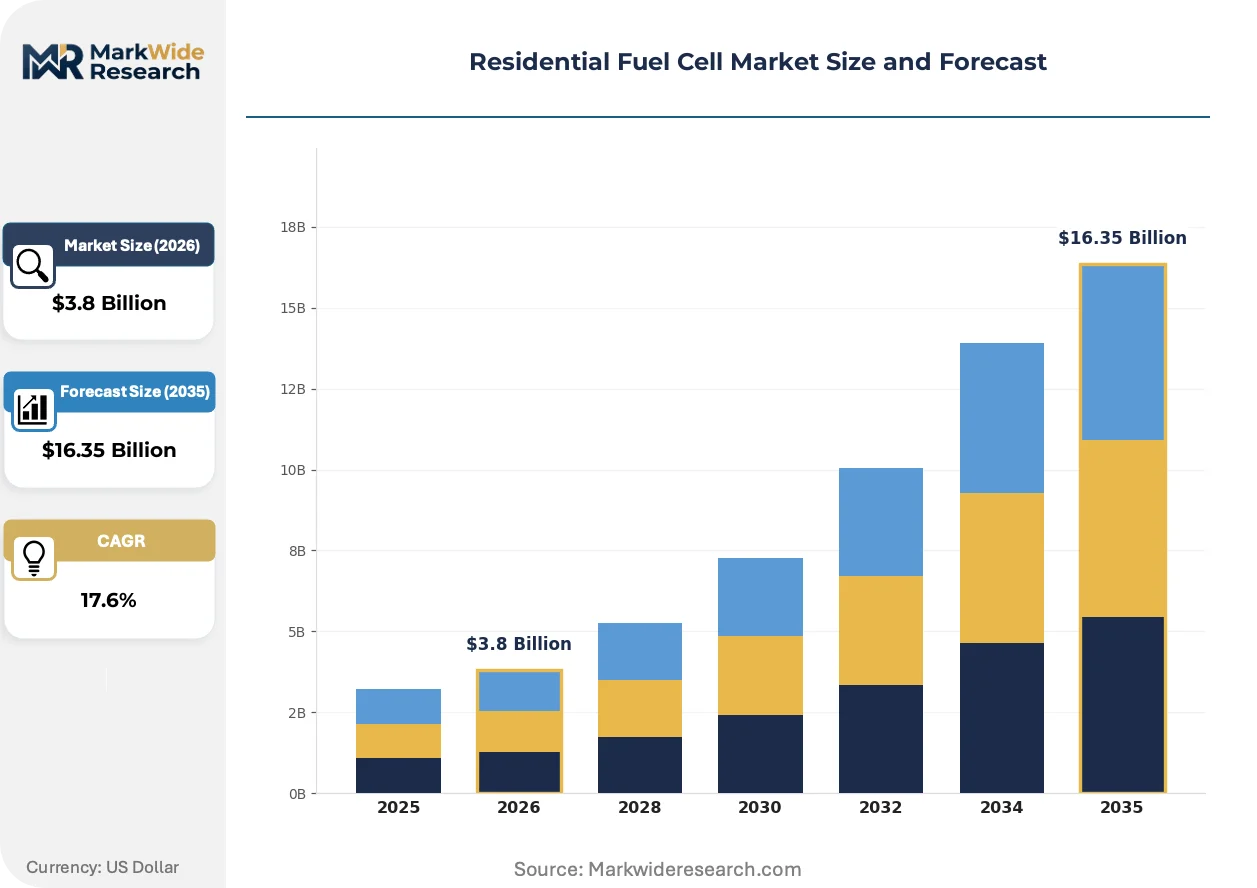
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $16.35 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Electrolyte Membrane, Solid Oxide, Alkaline, Phosphoric Acid End User: Homeowners, Property Developers, Installers, Energy Providers Technology: Combined Heat and Power, Grid-Tied, Off-Grid, Microgrid Deployment: Residential Buildings, Apartments, Retirement Communities, Smart Homes |
| Companies Covered | Panasonic Holdings Corporation, Bloom Energy Corporation, AISIN Corporation, Plug Power Inc., FuelCell Energy Inc., Nedstack Fuel Cell Technology B.V., Ceres Power Holdings PLC, Adaptive Energy LLC, Loop Energy Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Fuel Cell Market Trends and Innovations
Residential fuel cell development is pivoting toward modular architectures that decouple power output from thermal capture ratios. Manufacturers are reconfiguring stack designs to accommodate hydrogen blending trajectories without full system replacement.
Solid oxide fuel cell technology is automating thermal management sequences that previously required manual calibration cycles. Japanese single-family installers are adopting self-diagnostic control systems that reduce commissioning time from days to hours. The technology is automating fault detection protocols that compress service call frequency and extend maintenance intervals for remote installations.
South Korea's MFDS and KTL safety standards are tightening hydrogen purity specifications for residential reformate streams. Industrial consequence includes mandatory filtration upgrades that add component cost but reduce catalyst degradation. Premium single-family segments absorb compliance premiums most readily, while mass-market deployments await scaled filtration supply chains.
Homeowner procurement patterns are fragmenting across direct OEM channels, utility bundling programs, and property developer bulk purchasing. Traditional appliance retail networks in Japan face disintermediation from integrated energy service contracts. Channel disruption concentrates in Tokyo and Osaka metropolitan zones where gas utilities actively cross-sell fuel cell leases alongside existing customer relationships.
Residential Fuel Cell Market Segmentation
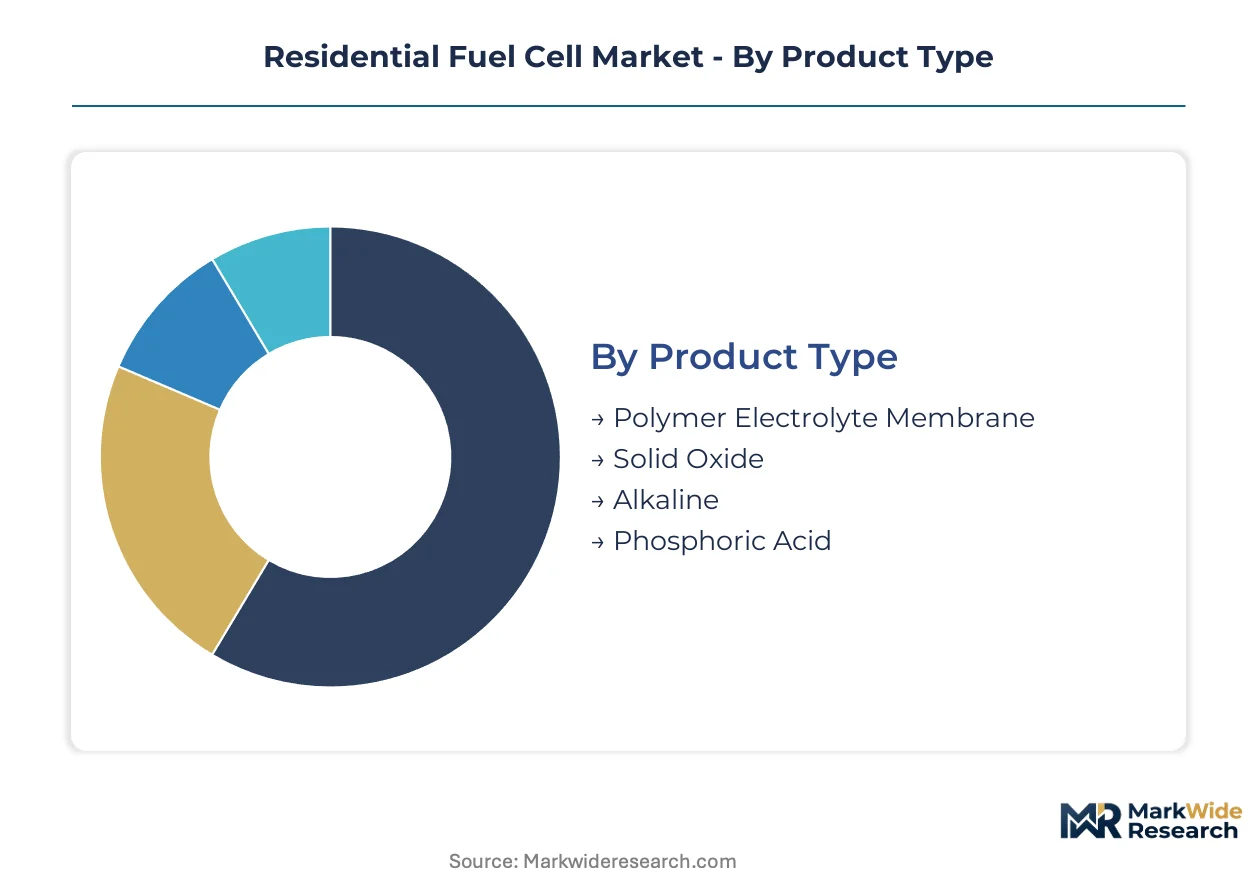
Technology-platform choices in residential fuel cells cascade through installation complexity, maintenance cadence, and regulatory compliance burden. Segment boundaries increasingly blur as manufacturers engineer crossover capabilities between polymer electrolyte membrane and solid oxide architectures.
Product Type:
Standalone fuel cell systems dominate Japanese single-family retrofits where space constraints favor modular footprints, while embedded combined heat and power configurations penetrate South Korean new-build apartments through developer-specified packages.
- Polymer Electrolyte Membrane:Electrochemical conversion occurs at sub-100°C operating temperatures using platinum-iridium catalyst layers on perfluorinated sulfonic acid membranes. Single-family homeowners in Tokyo and Osaka prefectures favor rapid cold-start sequences that match intermittent solar generation patterns. Japan's NEDO subsidy framework compresses payback periods for sub-kilowatt residential units.
- Solid Oxide:Yttria-stabilized zirconia electrolyte ceramics enable 700-1,000°C operation with 50-60% electrical efficiency and high-grade heat recovery. Premium single-family dwellings in Seoul's Gangnam district specify solid oxide systems where thermal-to-electric ratios exceed 1.5:1 for hydronic heating integration.
- Alkaline:Liquid potassium hydroxide electrolyte configurations achieve cost parity in utility-managed rental programs where maintenance centralization offsets stack replacement frequency.
- Phosphoric Acid:Molten phosphoric acid electrolyte systems concentrate in retirement community microgrids where continuous baseload operation minimizes thermal cycling degradation.
Polymer electrolyte membrane leads volumes today; solid oxide is gaining share fastest.
End User:
Cost tier stratification separates premium direct purchasers from mass-market utility-leased subscribers, with installer networks capturing service-margin pools that OEMs struggle to retain.
- Homeowners:Individual purchasers in Japan's Kanto region drive specification diversity through direct channel engagement with Panasonic and Toshiba Energy Systems. Retrofit demand concentrates among 15-25 year old detached housing stock where gas boiler replacement cycles coincide with subsidy eligibility windows.
- Property Developers:Bulk procurement agreements in South Korea's Sejong City smart district standardize polymer electrolyte membrane specifications across 500+ unit developments. Vertical integration into construction scheduling accelerates commissioning timelines.
- Installers:Certified technician networks in Osaka Prefecture capture recurring maintenance contracts that extend customer lifetime value beyond equipment margins.
- Energy Providers:Tokyo Gas and Osaka Gas bundle fuel cell leases with existing customer relationships, disintermediating traditional appliance retail channels.
Homeowners anchor current revenue; property developers are expanding most quickly.
Technology:
Application-specific architectures differentiate grid-synchronized systems from island-capable configurations, with hybrid microgrids emerging as the convergence point for resilience-motivated demand.
- Combined Heat and Power:Cogeneration systems capture 80-90% combined efficiency by routing exhaust heat to domestic hot water and space conditioning circuits. South Korean apartment complexes mandate CHP compliance under renewable portfolio standards.
- Grid-Tied:Synchronized inverters dominate current installations where net metering policies value electricity export. Japan's feed-in tariff reduction is compressing grid-tied economics.
- Off-Grid:Battery-coupled fuel cells penetrate rural Hokkaido prefecture where transmission infrastructure extension costs exceed distributed generation capital.
- Microgrid:Islanding-capable architectures with automatic transfer switches serve retirement communities in Kyushu seeking resilience against typhoon-related grid failures.
Grid-tied configurations dominate installed base; microgrid systems are climbing the fastest.
Deployment:
Customer-type concentration varies sharply between detached single-family penetration and multi-unit vertical construction where centralized thermal distribution reshapes unit economics.
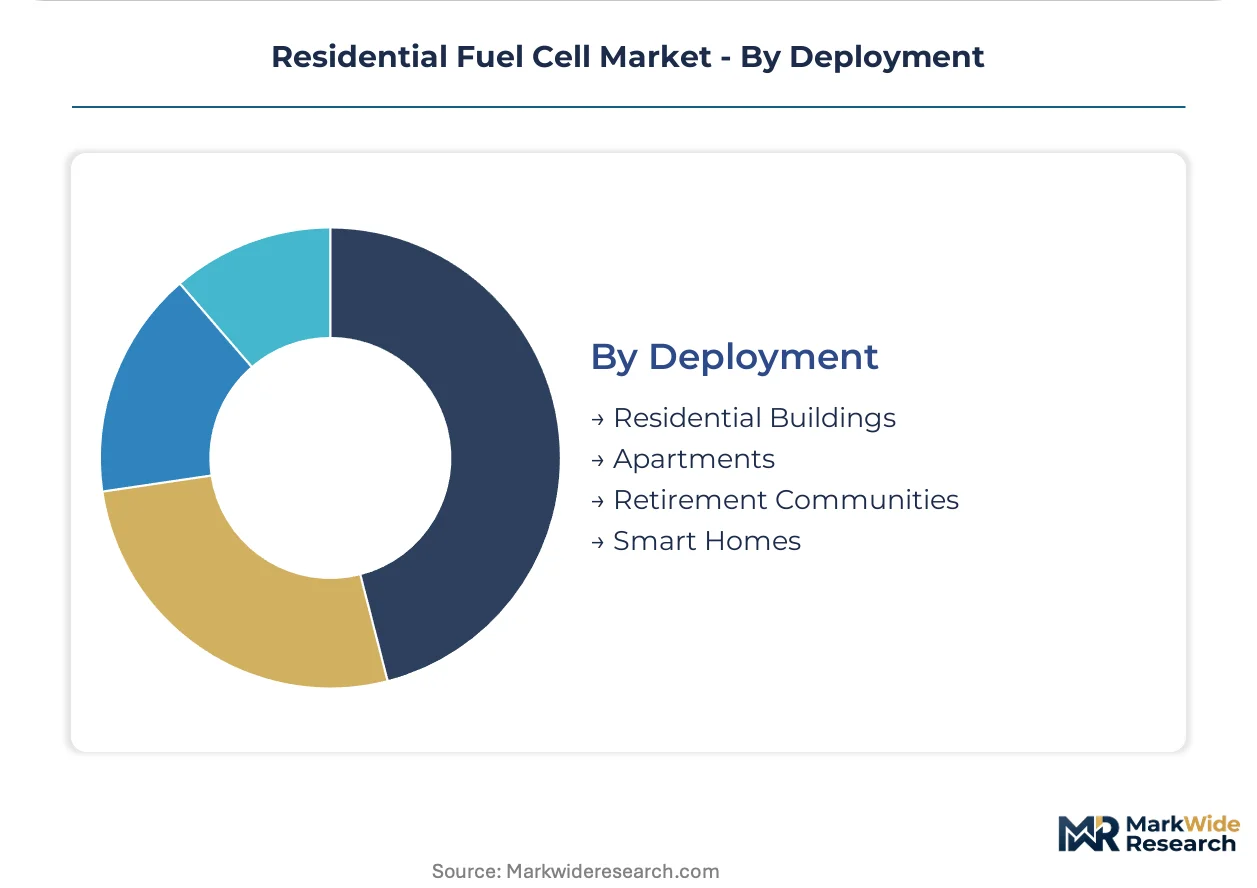
- Residential Buildings:Detached single-family dwellings in Japan represent the historical core deployment category with standardized 700W-1kW unit specifications.
- Apartments:Multi-unit buildings in Seoul's Songdo district deploy centralized solid oxide systems with district heating distribution, achieving economies of scale unavailable to individual unit installations.
- Retirement Communities:Continuous operation requirements in assisted living facilities match fuel cell duty cycles while backup power mandates drive microgrid specification.
- Smart Homes:IoT-integrated fuel cells with predictive maintenance algorithms penetrate premium new-build segments in Tokyo's Minato ward where energy management system interoperability commands price premiums.
Residential buildings retain volume leadership; smart home deployments are expanding most steeply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan commands the largest installed base of residential fuel cells, while South Korea's deployment velocity now outpaces legacy markets. Germany and the United States represent nascent demand centers where policy frameworks remain under construction.
Japan
Single-family homeowners in Tokyo and Osaka prefectures drive polymer electrolyte membrane installations through NEDO subsidy windows. METI certification standards compress grid interconnection timelines for certified systems. The Kanto corridor hosts dense installer networks that capture recurring maintenance contracts.
South Korea
Seoul Capital Area property developers specify embedded combined heat and power systems across multi-unit new-build projects. MFDS fast-track certification reduces time-to-market for established suppliers with dedicated testing infrastructure. Busan-Ulsan industrial corridors concentrate membrane electrode assembly production capacity.
Germany
Residential retrofits in Bavaria and North Rhine-Westphalia test solid oxide configurations for hydronic heating integration. EU Green Deal national implementation funds channel investment into building-sector decarbonization. The Eindhoven-Aachen technology corridor supplies ceramic stack components to German system integrators.
United States
California and Northeast corridor utilities pilot fuel cell lease programs for premium single-family segments. IRA tax credits for clean hydrogen production indirectly support residential reformer economics. Greater Boston hosts solid oxide R&D clusters focused on thermal cycling durability.
United Kingdom
Scotland and Northern England rural dwellings adopt off-grid battery-coupled systems where transmission extension costs prove prohibitive. Ofgem regulatory consultations explore distributed generation tariff structures. Midlands manufacturing zones supply precision welding equipment for stack assembly operations.
Residential Fuel Cell Market Competitive Landscape
Japanese producers anchor one tier; South Korean and European specialists hold differentiated positions in component supply and ceramic stack technology. The vendor base clusters around three strategic archetypes: integrated appliance manufacturers controlling distribution channels, pure-play fuel cell technology developers, and industrial conglomerates leveraging captive energy service relationships. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms seek to secure membrane electrode assembly supply and installer certification capacity.
Among Japan-based integrated manufacturers, Panasonic Holdings Corporation and AISIN Corporation exemplify the appliance-channel archetype, leveraging existing customer relationships and service infrastructure to compress customer acquisition costs. Bloom Energy Corporation occupies a position bridging utility-scale expertise with premium residential deployment, representing the technology-specialist tier that competes on solid oxide efficiency metrics. Ceres Power Holdings PLC anchors the European specialist segment, focusing on licensing architectures rather than direct manufacturing scale.
| Leading Market Players |
|---|
| Panasonic Holdings Corporation |
| Bloom Energy Corporation |
| AISIN Corporation |
| Plug Power Inc. |
| FuelCell Energy Inc. |
| Nedstack Fuel Cell Technology B.V. |
| Ceres Power Holdings PLC |
| Adaptive Energy LLC |
| Loop Energy Inc. |
| Others |
Pricing and Supply Chain Analysis
Captive membrane electrode assembly production in South Korea's Busan-Ulsan corridor anchors supplier pricing power while compressing margins for foreign OEMs dependent on import channels. Japanese incumbents leverage backward integration into platinum catalyst sourcing to buffer against precious metal volatility that otherwise destabilizes polymer electrolyte membrane stack economics.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for membrane electrode assemblies as domestic suppliers scale output for NEDO-subsidized Japanese deployments. Three-tier pricing structure across premium solid oxide, standard polymer electrolyte membrane, and economy alkaline configurations stratifies buyer segments, with METI certification grade and after-sales service bundling as primary differentiation drivers. Cost compression in mass-market polymer electrolyte membrane tiers intensifies because platinum-iridium loadings resist substitution, squeezing OEM margins without corresponding price elasticity. Property developers in Seoul's new-build projects exhibit lowest price sensitivity through bulk procurement, while individual homeowners in Osaka's retrofit channel absorb compliance premiums most reluctantly.
Supply Chain Analysis
Direct-to-installer channels handle single-family homeowner demand across Japan's Kanto corridor, while utility bundling programs aggregate volume for energy provider procurement. Geographic supply concentration centers on South Korea for membrane electrode assemblies, Japan for precision welding equipment, and Germany for ceramic stack components. Raw material dependencies rest on South African platinum, Russian iridium, and Chinese rare earth elements for catalyst substrates. Single-source vulnerability in hydrogen-ready reformer filtration modules creates disruption exposure as MFDS purity specifications tighten. Distribution runs through certified technician networks that capture recurring maintenance contracts beyond equipment margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where homeowner procurement shifts toward hydrogen-ready specifications and extended warranty bundling. Premium solid oxide deployments in Seoul's Gangnam district demonstrate willingness to absorb certification premiums that mass-market polymer electrolyte membrane buyers resist.
For Market Incumbents: Deploy captive membrane electrode assembly capacity to defend against South Korean supply concentration risk. Panasonic and AISIN should deepen backward integration into platinum catalyst recycling to offset precious metal volatility that threatens polymer electrolyte membrane margins. Certification investment in MFDS fast-track pathways preserves time-to-market advantage against emerging European licensors. For New Entrants and Emerging Players: Launch via utility lease bundling programs in Japan's Kanto corridor where Tokyo Gas and Osaka Gas actively disintermediate traditional appliance retail. Target underpenetrated retrofit stock in Osaka Prefecture's 15-25 year old detached housing where gas boiler replacement cycles align with subsidy windows. Prioritize hydrogen-ready reformer convergence as the go-to-market differentiator enabling fuel-switching without stack replacement. For Investors and Strategic Acquirers: Consolidation pressure builds where membrane electrode assembly production clusters around Seoul-Incheon corridors and electrolyzer stack assembly skill scarcity intensifies wage pressure. Long-term viability favors vertically integrated appliance-channel controllers with captive installer certification infrastructure over pure-play technology licensors dependent on manufacturing partners. Monitor South Korea's renewable portfolio standard enforcement as the inflection signal for developer-specified deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Electrode Assembly Capacity Buildout | South Korean suppliers scaling Busan-Ulsan output capture NEDO subsidy-driven Japanese demand. |
| Hydrogen-Ready Reformer Certification | MFDS fast-track pathways reward established suppliers with dedicated testing infrastructure. |
| Installer Network Certification Expansion | Osaka Prefecture technician density determines maintenance contract capture and customer lifetime value. |
| Platinum Catalyst Recycling Integration | Backward control over precious metal recovery buffers polymer electrolyte membrane margin volatility. |
| Smart Home IoT Platform Partnership | Tokyo's Minato ward premium segments command interoperability premiums for predictive maintenance algorithms. |
Research Methodology
Bottom-up homeowner deployment modeling reconciled against top-down membrane electrode assembly production tracking forms the analytical core. Primary interviews with fuel cell system integrators, METI certification officers, property development procurement leads, and certified installation technicians combined with secondary validation against NEDO subsidy disbursement records, MFDS safety filing databases, and utility lease program disclosures. Trade data from Japan Customs and South Korean import-export statistics triangulate against bottom-up unit estimates.
Input-output matrices map polymer electrolyte membrane and solid oxide stack shipments through deployment channel segmentation across technology platform, end-user archetype, and grid interconnection architecture. CAGRs derive from segment-level unit economics modeling incorporating subsidy phase-out trajectories and hydrogen blending infrastructure buildout assumptions. Forecast inputs include platinum group metal price scenarios and municipal building code adoption timelines for net-zero mandates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under precious metal price spikes or MFDS certification delays. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
Germany Fuel Cell Market
Fuel Cell Technology
Asia-Pacific Direct Methanol Fuel Cell Market
Fuel Cell Technology
PEM Electrolyzer Market
Fuel Cell Technology
Fuel Cells for CHP Application Market
Fuel Cell Technology
Direct Methanol Fuel Cell Market
Fuel Cell Technology
Helium Recovery Systems Market
Fuel Cell Technology
High-Performance Fuel Cells Market
Fuel Cell Technology
Hydrogen Fuel Cell Stack and Membrane Recycling for EU Mobility Market
Fuel Cell Technology
Europe Direct Methanol Fuel Cell Market
Fuel Cell Technology
Aircraft Fuel Cell Market
Fuel Cell Technology
Fuel Cell for Stationary Power Market
Fuel Cell Technology
France Fuel Cell Market
Fuel Cell Technology
Hydrogen Fuel Cell Vehicle Market
Fuel Cell Technology
Protonic Ceramic Fuel Cell (PCFC) Market
Fuel Cell Technology
North America Microbial Fuel Cell Market
Fuel Cell Technology
China Fuel Cell Market