
 Global Pressure Relief Valves Market | 2026-2036
Global Pressure Relief Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pressure Relief Valves Market Foresight
The pressure relief valves market is recalibrating around a widening gap between API-certified premium systems and generic commodity valves. Emerson Electric Co. leverages its Fisher brand dominance in spring-loaded safety valves for upstream hydrocarbons. IMI plc anchors its position through specialized severe-service designs for high-temperature refinery applications. LESER GmbH & Co. KG competes on German-engineered precision and broad global certification coverage.
Pressure relief valves are automatic actuated devices designed to open at predetermined set pressures, typically constructed from stainless steel or alloy bodies with spring, pilot, or bellows actuation mechanisms, and function to protect pressurized vessels and piping systems from overpressure events. Spring-loaded variants dominate installed base volumes across oil and gas and chemical processing verticals due to mechanical simplicity and fail-safe operation. Electronic pressure relief systems represent the fastest-expanding segment as digital integration enables remote monitoring and predictive diagnostics in power generation and water treatment facilities.
API standards in the United States, ISO 4126 series frameworks, and the EU Pressure Equipment Directive collectively mandate certified manufacturing, periodic recertification, and traceable material sourcing. These compliance layers elevate barriers for uncertified suppliers while creating sustained replacement demand in regulated end-use sectors. Stakeholders must weigh capital allocation between conventional mechanical portfolios and sensor-integrated electronic platforms as facility operators prioritize uptime guarantees and predictive maintenance integration.
Market Dynamics
API 520/521 and ISO 4126-1 compliance mandates are compressing supplier margins while fragmenting procurement between certified premium systems and uncertified commodity alternatives. This regulatory divergence is forcing capital reallocation across manufacturing footprints and testing infrastructure.
Growth Catalysts
- Petrochemical capacity expansions:Refinery upgrades in the United States, China, and Germany are generating replacement demand for severe-service relief systems in high-temperature cracking units.
- API 521 thermal relief mandates:Updated fire-sizing calculations for offshore platforms in the Gulf of Mexico are accelerating procurement of pilot-operated valves with enhanced seat tightness.
- Digital valve positioners:Integration of wireless HART protocols is enabling remote set-pressure verification in power generation facilities, reducing manual inspection cycles.
Market Restraints
- Alloy material cost volatility:Inconel 625 and Hastelloy C-276 price swings are compressing margins for severe-service valve manufacturers serving sour gas applications.
- Foundry capacity concentration:Specialized casting capabilities for large-bore pressure relief valves cluster in Germany and Japan, creating supply bottlenecks during demand surges.
- Spring fatigue limitations:Mechanical spring-loaded designs face set-pressure drift above 500°F, restricting deployment in high-temperature refinery reactor loops.
Strategic Opportunities
- Water treatment infrastructure:Desalination plant construction in Saudi Arabia and the UAE is creating demand for corrosion-resistant duplex stainless steel relief systems.
- EU Green Deal industrial decarbonization:Hydrogen pipeline certification requirements under the EU Pressure Equipment Directive are mandating new valve designs for embrittlement-resistant materials.
- Predictive maintenance convergence:Machine learning algorithms paired with acoustic emission sensors are enabling condition-based replacement scheduling in chemical processing facilities.
Industry Challenges
- Third-party certification timelines:National Board (NB) registration and ASME UV stamp acquisition require 12-18 month validation cycles, delaying new product commercialization.
- Legacy system integration friction:Electronic pressure relief systems face retrofit compatibility barriers with existing mechanical piping configurations in brownfield refineries.
- Specialized welding technician scarcity:Narrow-gap TIG qualification for superalloy valve bodies limits production scaling during demand spikes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pressure Relief Valves Market |
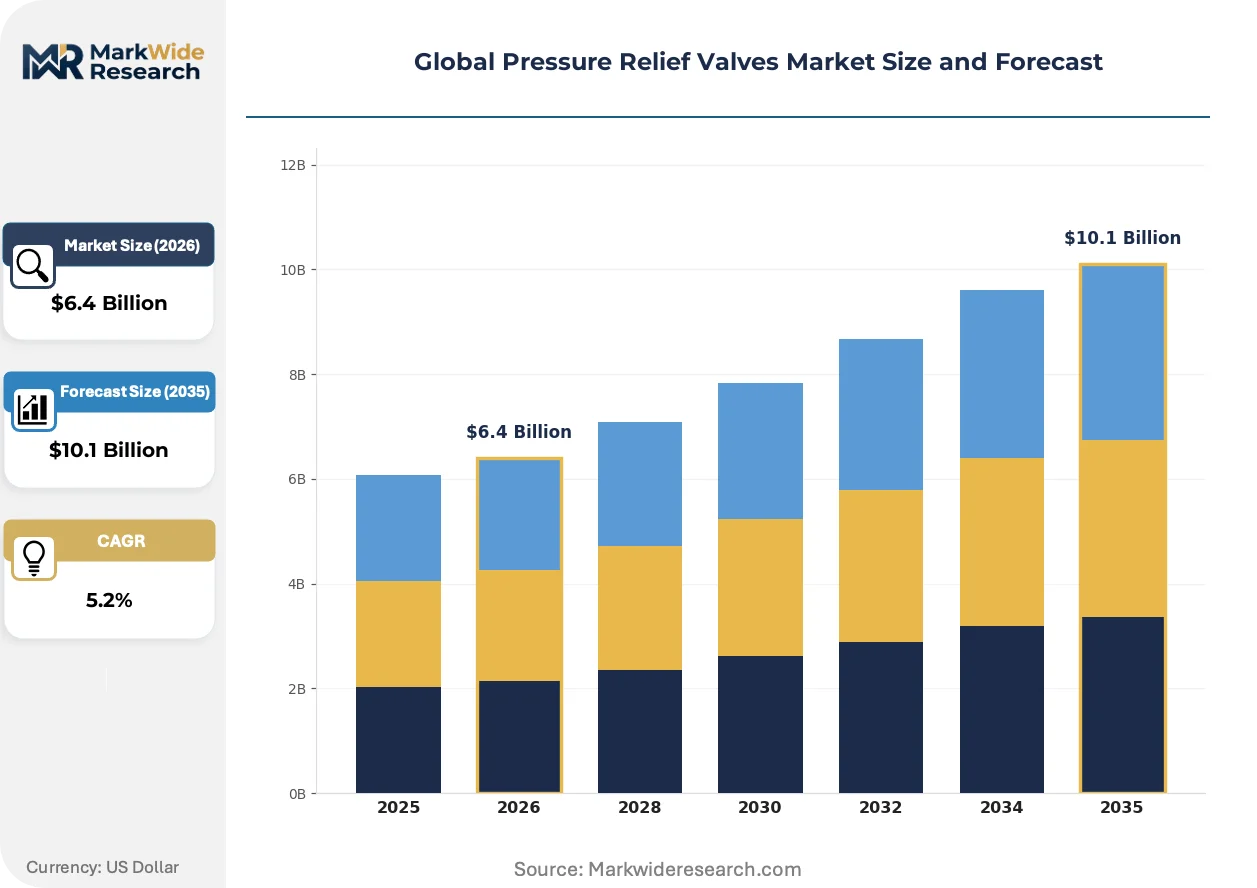
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $10.1 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
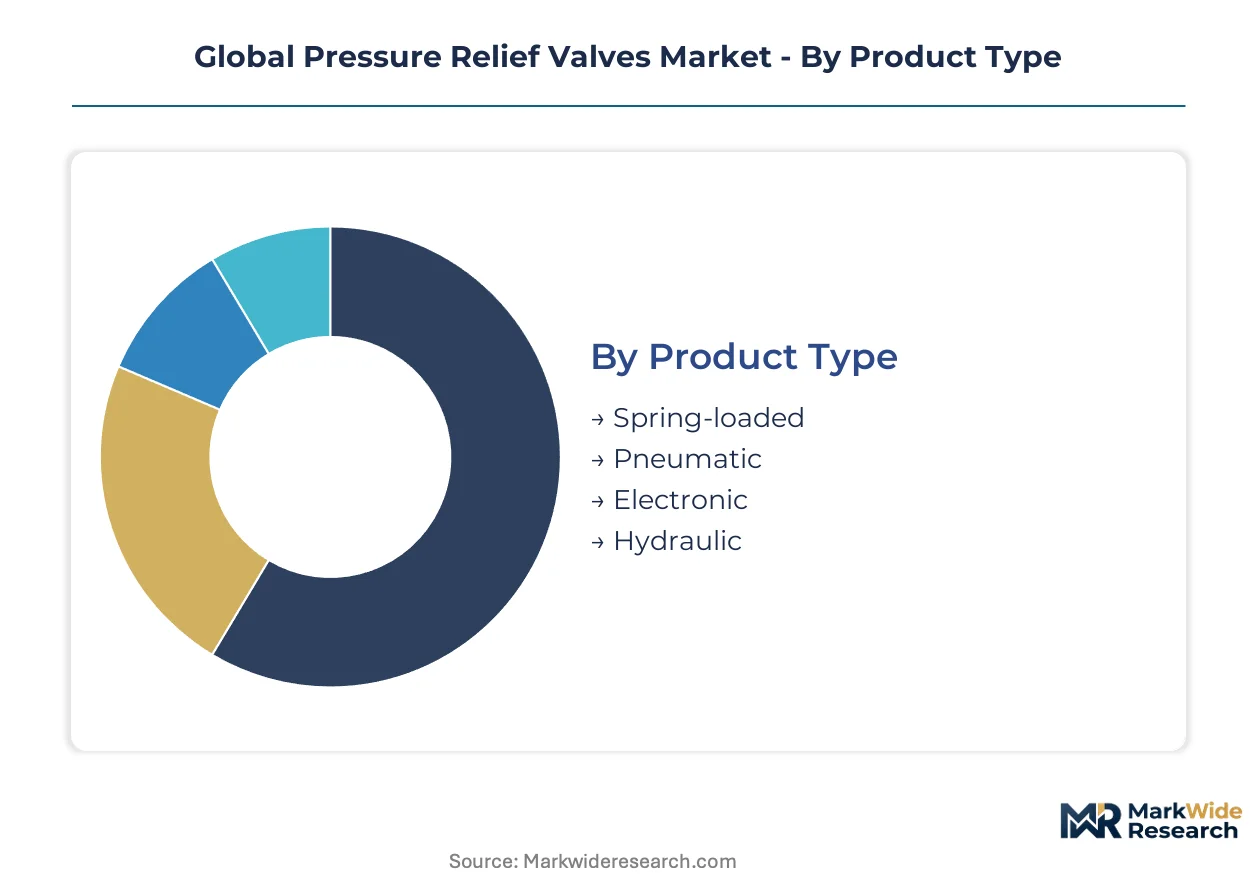
| Segmentation | Product Type: Spring-loaded, Pneumatic, Electronic, Hydraulic Industry Vertical: Oil & Gas, Chemical Processing, Water Treatment, Power Generation End User: Manufacturing Plants, Refineries, Municipalities, Power Plants Installation: Onshore, Offshore, Stationary, Mobile |
| Companies Covered | Emerson Electric Co., Curtiss-Wright Corp., General Electric Company, IMI plc, Alfa Laval AB, Watts Water Technologies, Inc., The Weir Group PLC, LESER GmbH & Co. KG, Flowserve Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pressure Relief Valves Market Shifts & Advancements
Electrification of actuation mechanisms and sensor integration are displacing purely mechanical architectures across critical infrastructure. These shifts are compressing replacement cycles while elevating service contract value capture.
Modular pilot-operated valve architectures with field-replaceable trim components are decentralizing maintenance authority from centralized OEM service networks to facility engineering teams. Downstream chemical operators in the US Gulf Coast are adopting these configurations to reduce turnaround downtime. This decentralization is compressing aftermarket revenue concentration among incumbent suppliers while elevating spare parts logistics requirements.
REACH substance restrictions on chromium VI compounds are forcing coating system transitions for valve springs and internal components. Manufacturers serving European petrochemical clients are qualifying zinc-flake and aluminum-based alternatives to hexavalent chromate passivation. Spring-loaded safety valves for offshore North Sea platforms face the most acute compliance pressure given salt-spray corrosion requirements.
Long-term service agreements bundling valve replacement, recertification, and predictive diagnostics are displacing transactional spare parts purchasing in LNG liquefaction facilities. QatarEnergy and US Gulf Coast export terminal operators are consolidating vendor relationships around integrated asset management contracts. This concentration is most visible in cryogenic butterfly relief valve applications where unplanned release consequences carry catastrophic liability exposure.
Global Pressure Relief Valves Market Segmentation
Pressure relief valve procurement patterns diverge sharply between integrated process systems and standalone safety installations. Understanding these deployment contexts clarifies why specification requirements, certification burdens, and replacement cycles vary dramatically across customer segments.
Product Type:
Standalone mechanical systems dominate maintenance-heavy environments, while embedded electronic architectures penetrate digitally mature facilities seeking predictive capabilities.
- Spring-loaded:Mechanical compression springs trigger valve lift at set pressures without external power dependencies. Refineries in Texas and Louisiana specify these for reactor protection loops where electrical failure risks exceed overpressure risks. API 520 certification mandates elevate procurement costs but ensure traceable material sourcing for sour service.
- Electronic:Sensor-integrated actuation enables remote set-pressure adjustment and continuous position monitoring. Power generation facilities in Germany integrate these with distributed control systems to eliminate manual inspection rounds during turbine protection validation.
- Pneumatic:Instrument air-driven actuation suits explosion-classified zones where electrical ignition sources face restriction. Chemical processing plants in Belgium deploy these for solvent vapor recovery systems.
- Hydraulic:Fluid-pressure amplification delivers rapid full-bore opening for liquid thermal expansion scenarios. Offshore platforms in Norway specify these for subsea pipeline protection.
Spring-loaded designs anchor installed base volumes; electronic variants are gaining share fastest in greenfield power infrastructure.
Industry Vertical:
Margin structures align with process criticality — continuous operations command premium pricing against batch chemical environments.
- Oil & Gas:Upstream exploration, midstream transmission, and downstream refining impose distinct specification regimes. Gulf of Mexico offshore operators prioritize fire-safe certification per API 521 thermal radiation calculations. Sour gas fields in Alberta require NACE MR0175-compliant metallurgy for hydrogen sulfide exposure.
- Chemical Processing:Batch and continuous reaction systems demand corrosion-resistant trim materials for aggressive intermediates. BASF's Ludwigshafen complex exemplifies severe-service procurement for high-temperature cracking operations.
- Water Treatment:Desalination reverse osmosis systems and municipal distribution networks require duplex stainless steel construction for chloride resistance. Saudi Arabia's SWCC facilities drive specification tightening for seawater exposure.
- Power Generation:Steam turbine protection and boiler safety applications balance response speed with seat tightness requirements. Combined cycle plants in South Korea integrate electronic relief systems with plant-wide asset management platforms.
Oil and Gas commands revenue concentration today; Water Treatment demonstrates steepest expansion trajectory amid desalination buildouts.
End User:
Ownership models differentiate procurement authority — integrated operators consolidate vendor relationships while municipalities fragment purchasing across engineering consultants.
- Refineries:Integrated downstream operators like Marathon Petroleum and Valero Energy centralize relief valve specifications across multiple facilities. Turnaround scheduling drives concentrated replacement demand in 4-6 year cycles.
- Power Plants:Utility and independent power producers prioritize unsparing availability guarantees. Duke Energy's Carolinas fleet exemplifies long-term service agreement structures bundling hardware and predictive diagnostics.
- Manufacturing Plants:Discrete and process manufacturing operations embed relief protection within compressed air and hydraulic utility systems. Automotive stamping facilities in Michigan specify compact spring-loaded designs for press safety circuits.
- Municipalities:Public water and wastewater authorities procure through engineer-specified bidding processes. California's Metropolitan Water District exemplifies corrosion-resistant specification for coastal infrastructure.
Refineries dominate aftermarket value capture; Power Plants are expanding fastest through digital retrofit programs.
Installation:
Mobility requirements dictate weight constraints and packaging durability — stationary systems optimize for performance while mobile units prioritize shock resistance.
- Onshore:Fixed facility installations dominate volume, with piping configuration flexibility enabling optimized valve sizing. Permian Basin gathering systems exemplify high-count deployments for wellhead protection.
- Offshore:Platform and subsea installations impose space constraints, weight limitations, and marine corrosion exposure. North Sea operators specify superduplex bodies for splash zone durability.
- Stationary:Permanent infrastructure across all verticals constitutes baseline demand. Petrochemical complexes in China's Zhejiang province anchor regional procurement volumes.
- Mobile:Trailer-mounted process equipment and temporary power units require compact, vibration-resistant designs. Frac pump trucks in West Texas deploy hydraulic relief systems for rapid pressure cycling.
Stationary installations anchor revenue today; Offshore applications are climbing fastest amid deepwater project reactivations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized welding technicians for superalloy valve bodies cluster in Germany and Japan, creating supply bottlenecks that shape regional procurement patterns. Foundry capacity for large-bore castings concentrates in these same geographies, forcing end-users in other markets to navigate extended lead times or qualify secondary suppliers.
United States
Gulf of Mexico offshore operators are expanding procurement of API 521-certified pilot-operated valves with enhanced seat tightness. OSHA process safety management requirements and EPA risk management plan mandates tighten inspection frequencies for high-pressure systems. Houston anchors the largest concentration of valve service contractors, with turnaround specialists supporting refinery clusters along the Texas and Louisiana coasts.
Germany
REACH substance restrictions on chromium VI compounds are forcing coating system transitions for valve springs serving European petrochemical clients. The EU Pressure Equipment Directive mandates traceable material sourcing and periodic recertification for hydrogen pipeline applications. The Ruhr industrial corridor and Ludwigshafen chemical complex anchor severe-service demand for high-temperature refinery reactor protection.
China
Petrochemical capacity additions in Zhejiang province are accelerating procurement of spring-loaded safety valves for reactor protection loops. GB standards administered by SAMR establish certification requirements parallel to API 520/521 frameworks. The Yangtze River Delta petrochemical cluster is driving specification tightening for sour gas metallurgy compliant with NACE MR0175.
Saudi Arabia
Desalination plant construction by SWCC is creating demand for corrosion-resistant duplex stainless steel relief systems in seawater exposure applications. The country's national standards body mandates compliance with ISO 4126-1 testing protocols for critical infrastructure. The Eastern Province industrial zone around Jubail anchors the heaviest concentration of water treatment and petrochemical valve procurement.
Japan
Combined cycle power plants are integrating electronic relief systems with plant-wide asset management platforms under METI energy efficiency guidelines. JIS standards for pressure equipment establish certification frameworks that elevate barriers for uncertified imports. The Chubu region around Nagoya hosts specialized foundry capacity for large-bore superalloy castings serving sour gas applications.
Global Pressure Relief Valves Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a market structure that fragments between certified premium systems and commodity alternatives. Tier-one suppliers anchor positions through National Board registration and ASME UV stamp holdings that require 12-18 month validation cycles. Three archetypes dominate: integrated industrial conglomerates with broad energy portfolios, specialized valve manufacturers with severe-service engineering depth, and regional fabricators serving uncertified replacement demand. Competitive moves concentrate on long-term service agreement bundling and predictive diagnostics integration rather than pure hardware pricing.
Within the premium engineering tier, LESER GmbH & Co. KG represents German precision manufacturing with broad global certification coverage, while IMI plc exemplifies specialized severe-service design capabilities for high-temperature applications. Emerson Electric Co. anchors the integrated conglomerate vector through its Fisher brand presence in upstream hydrocarbons. These three occupy positions that reflect divergent strategic bets between mechanical simplicity and sensor-integrated electronic platforms.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Curtiss-Wright Corp. |
| General Electric Company |
| IMI plc |
| Alfa Laval AB |
| Watts Water Technologies, Inc. |
| The Weir Group PLC |
| LESER GmbH & Co. KG |
| Flowserve Corporation |
| Others |
Supply & Pricing Matrix
API 521 thermal relief mandates for Gulf of Mexico offshore platforms are compressing procurement timelines and forcing buyers toward pre-certified premium systems, which elevates supplier pricing power while squeezing margin flexibility for uncertified fabricators.
Pricing Analysis
Bundled long-term service agreements versus unbundled transactional spare parts purchases define the pricing landscape. Three-tier pricing structure across premium, standard, and economy levels separates National Board-certified severe-service valves from generic mechanical alternatives. Price differentiation hinges on ASME UV stamp certification and alloy material grade. Cost compression in commodity spring-loaded valves is intensifying because foundry capacity bottlenecks in Germany and Japan limit supply elasticity. Municipal water authorities exhibit highest price sensitivity; LNG export terminal operators demonstrate lowest sensitivity due to catastrophic liability exposure.
Supply Chain Analysis
Dual-sourcing requirements mandated by major refinery operators and power utilities are fragmenting procurement across certified premium suppliers and qualified secondary vendors. Specialized foundry capacity concentrates in Germany, Japan, and the United States for large-bore superalloy castings. Raw material dependencies center on Inconel 625, Hastelloy C-276, and duplex stainless steel bar stock. Single-source vulnerability persists for narrow-gap TIG welding technicians qualified on superalloy valve bodies. Distribution runs through OEM-authorized service networks and independent valve repair contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential in this market rests on the shift from transactional hardware sales toward predictive diagnostics-integrated service contracts, which capture recurring revenue while reducing customer total cost of ownership.
For Market Incumbents: Acquire specialized welding technician training programs and narrow-gap TIG qualification infrastructure to defend against superalloy foundry capacity constraints. Consolidate aftermarket service networks in the US Gulf Coast refinery corridor to capture turnaround-driven replacement demand. Electronic pressure relief system entrants threaten mechanical portfolio incumbents; counter by embedding sensor diagnostics into legacy spring-loaded platforms through retrofit partnerships. For New Entrants and Emerging Players: Machine learning algorithms paired with acoustic emission sensors offer a technology-first wedge into predictive maintenance contracts at chemical processing facilities. Target desalination plant operators in Saudi Arabia and the UAE with corrosion-resistant duplex stainless steel designs as the most penetrable white-space segment. Pursue qualification under ISO 4126-1 and EU Pressure Equipment Directive as the primary go-to-market credential. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized severe-service valve designers holding National Board registration and ASME UV stamps. Long-term viability over a multi-year horizon favors asset-light engineering firms with deep metallurgy expertise over capital-intensive foundry operators. Watch hydrogen pipeline certification requirements under EU industrial decarbonization mandates as the inflection signal for embrittlement-resistant material demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Superalloy Foundry Capacity | Captures margin from Inconel 625 casting bottlenecks serving sour gas applications. |
| Predictive Diagnostics Platform Integration | Enables Duke Energy-style long-term service agreements bundling hardware and remote monitoring. |
| Hydrogen Pipeline Valve Certification | Positions suppliers for EU Green Deal infrastructure under Pressure Equipment Directive mandates. |
| Modular Pilot-Operated Valve Architecture | Decentralizes maintenance authority to BASF Ludwigshafen-style facility engineering teams. |
| Desalination Corridor Distribution Partnership | Secures SWCC procurement channels for duplex stainless steel seawater exposure systems. |
Research Methodology
Direct dialogue with plant engineers at Texas and Louisiana refineries, maintenance directors at Saudi desalination facilities, procurement leads at German chemical complexes, and aftermarket service heads at valve OEMs grounded qualitative findings. Secondary validation drew from API 520/521 technical standards documentation, National Board registration databases, SEC 10-K filings of listed industrial conglomerates, and customs trade data on alloy material imports. Bottom-up and top-down triangulation reconciled facility-level procurement patterns with aggregate capacity expansion announcements.
Bottom-up modeling of installed base replacement cycles and top-down validation against petrochemical capacity addition pipelines shaped the analytical lens. Segmentation dimensions span actuation mechanism, industry vertical, end-user ownership model, and installation mobility type. CAGRs were derived from regression analysis of historical procurement volumes against regulatory mandate implementation timelines. Forecast inputs incorporated API certification lag effects and REACH substance restriction compliance cost pass-through.
The model holds under stable regulatory enforcement of API 521 and ISO 4126-1 standards; deviation in alloy material price volatility or foundry capacity expansion rates would shift replacement demand timing materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Refrigeration Valves Market
Valves
Servo Valves Market
Valves
Industrial Hydraulic Filters Market
Valves
Europe Medium Voltage Switchgear Market
Valves
Bend Restrictors and Stiffeners Market
Valves
Electrohydraulic Servo Valves (Ehsvs) Market
Valves
Choke and Kill Manifold Market
Valves
Global Pipeline Safety Market
Valves
Flare Stack Monitoring Systems Market
Valves
Hydraulic Valves Market
Valves
Industrial Safety Valves Market
Valves
Isolator Valves Market
Valves
Industrial Valves and Actuators Market
Valves
Thermal Power Valve Market
Valves
Global Plug Valve Market
Valves
Valve Cover Gasket Market