
 Digital Water Meters Market | 2026-2036
Digital Water Meters Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Water Meters Market Insights
ISO 4064 certification for cold potable water meters is redrawing the competitive landscape for precision metrology suppliers. Badger Meter leverages its vertically integrated manufacturing footprint in Wisconsin to sustain domestic certification compliance and rapid fulfillment cycles. Kamstrup A/S anchors its position through intensive R&D allocation toward ultrasonic flow measurement, while Diehl Metering GmbH competes on channel depth across German municipal procurement frameworks.
Digital water meters are electromechanical or solid-state devices that measure volumetric flow through ultrasonic time-of-flight, electromagnetic induction, or encoded mechanical turbine principles, typically achieving accuracy classes of R800 or higher for residential applications and transmitting consumption data via integrated radio or cellular modules to utility billing systems. Ultrasonic meter types command premium positioning due to their absence of moving parts and extended calibration stability, whereas NB-IoT deployment within the communication technology layer is displacing proprietary mesh networks as utilities prioritize interoperability and reduced base station density. Smart meter categories within the meter type dimension concentrate margin pools where firmware-enabled leak detection and pressure management create recurring service attachments beyond hardware shipment.
The US EPA Lead and Copper Rule revisions and the EU Water Framework Directive collectively tighten accuracy and reporting obligations for municipal end users, while the FCC in the United States governs radio transmission power limits for embedded cellular and LoRaWAN modules. China's MIIT issues network access licenses for NB-IoT devices, creating a fragmented but navigable compliance map for manufacturers with multi-country product strategies. Stakeholders must monitor evolving cybersecurity certification requirements for connected infrastructure as regulatory bodies on both sides of the Atlantic draft mandatory vulnerability disclosure timelines for critical utility assets.
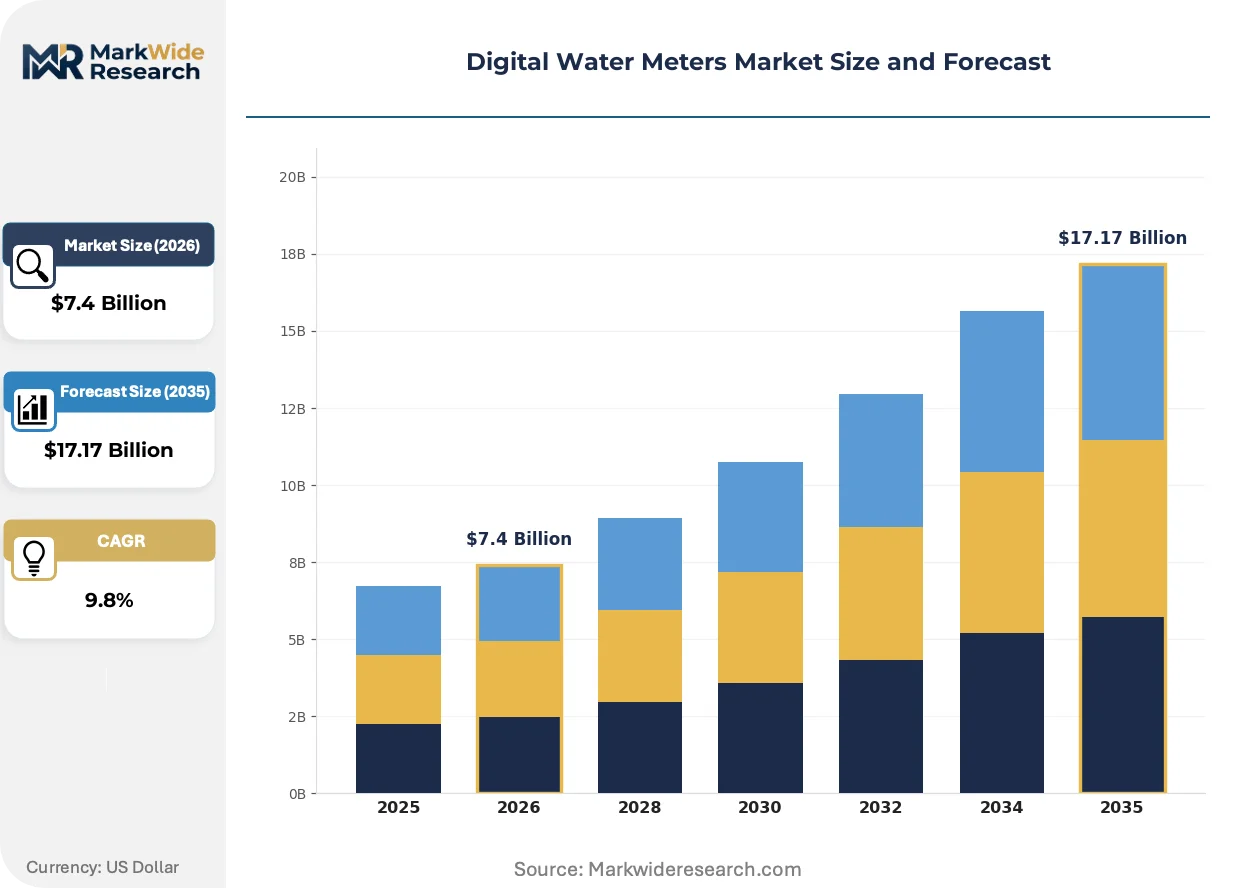
Market Dynamics
NB-IoT communication protocols are compressing deployment timelines for municipal utilities while ultrasonic measurement cores displace mechanical turbine assemblies in residential meter refresh cycles.
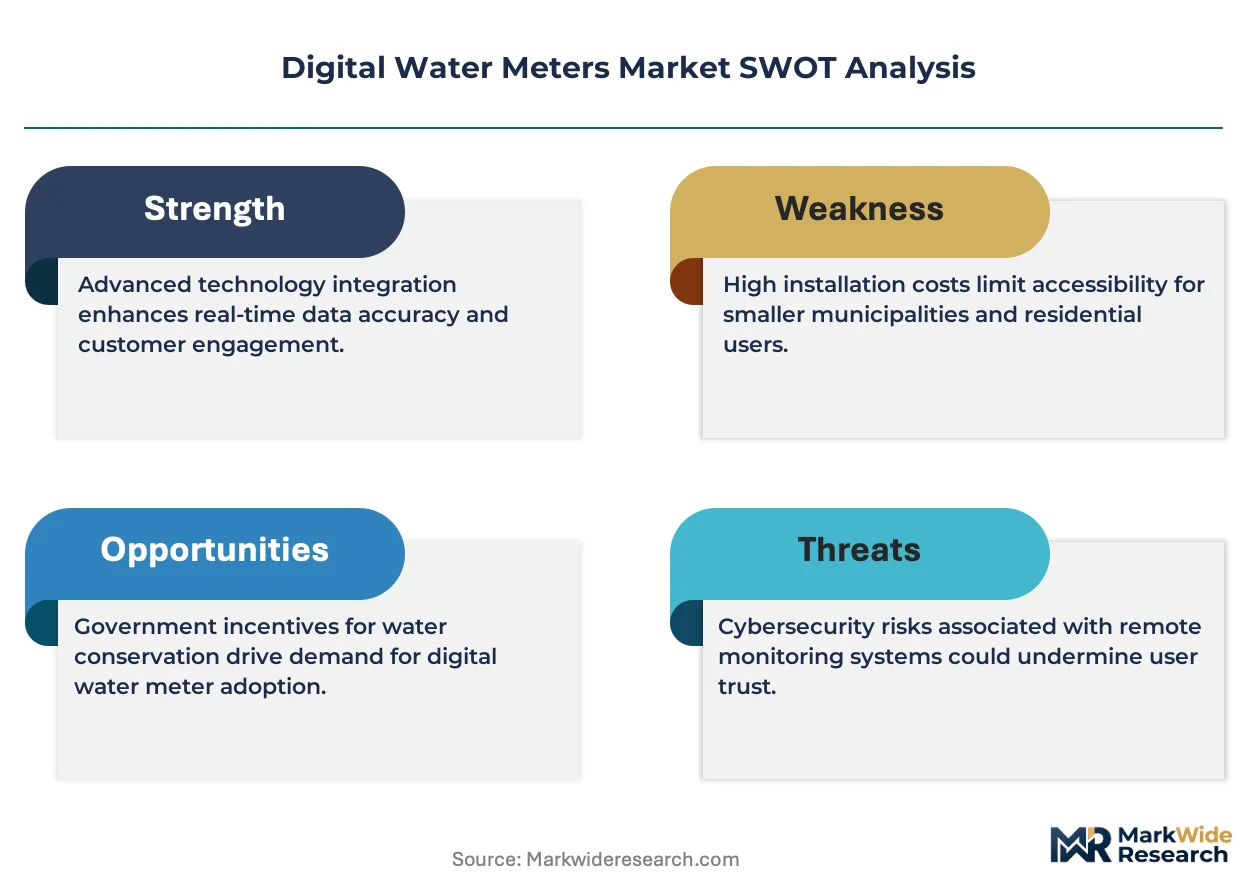
Growth Catalysts
- EU Water Framework Directive:Municipal utilities across Germany, France, and the Netherlands face mandatory non-revenue water reduction targets, forcing accelerated smart meter procurement schedules.
- Ultrasonic time-of-flight measurement:Solid-state flow sensors eliminate mechanical wear components, extending calibration intervals and reducing field service call density for water authorities.
- Carrier-grade NB-IoT networks:Deutsche Telekom, Vodafone, and Orange have activated national low-power wide-area coverage, removing proprietary base station infrastructure requirements for utilities.
Market Restraints
- Semiconductor component concentration:Ultrasonic transducer ASICs and cellular modem chipsets concentrate in Taiwanese and South Korean fabrication facilities, exposing meter OEMs to supply volatility.
- Battery chemistry limitations:Primary lithium thionyl chloride cells power 15-year residential deployments, but extreme temperature cycling degrades capacity in Nordic and Mediterranean climates.
- Cybersecurity certification friction:The EU Cybersecurity Act's Common Criteria evaluation timelines add 8-14 months to product launch schedules for connected meter platforms.
Strategic Opportunities
- Pressure management as-a-service:Firmware-enabled leak detection algorithms create recurring revenue attachments beyond hardware shipment, with German utilities piloting subscription-based district monitoring.
- India's Smart Cities Mission:AMRUT 2.0 funding channels direct capital toward digital water infrastructure in Bengaluru, Chennai, and Pune, opening procurement windows for certified meter suppliers.
- LoRaWAN-NB-IoT hybrid architectures:Converged radio stacks allow utilities to bridge proprietary mesh legacy with carrier-managed backhaul, preserving sunk infrastructure investment.
Industry Challenges
- Metrology firmware validation:OIML R49 certification requires traceable algorithm testing across temperature and flow profile matrices, compressing engineering resource availability.
- Legacy billing system integration:SAP-ISU and Oracle CC&B implementations demand custom middleware development for AMI data ingestion, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Water Meters Market |
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $17.17 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Meter Type: Ultrasonic, Electromagnetic, Mechanical, Smart Deployment Model: Cloud-based, On-premise, Hybrid, Remote End User: Municipalities, Industrial Users, Residential Users, Commercial Establishments Communication Technology: LoRaWAN, NB-IoT, Zigbee, Cellular |
| Companies Covered | Badger Meter, Inc., Xylem Inc., Itron, Inc., Diehl Metering GmbH, Neptune Technology Group, Inc., Kamstrup A/S, Landis+Gyr, Mueller Water Products, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Water Meters Market Trends and Innovations
Measurement hardware and communication modules are decoupling as utilities prioritize interoperability, while service business models detach from device shipment economics.
Ultrasonic flow measurement is bifurcating the residential meter category. Time-of-flight sensors eliminate magnetic coupling and mechanical gearing, reducing drift susceptibility. German and Dutch water utilities now specify R800 accuracy class as baseline for new procurement. Solid-state architectures compress total cost of ownership curves against encoded mechanical alternatives.
REACH restrictions on lead-bearing alloys in brass meter bodies are accelerating polymer composite adoption. The European Chemicals Agency's 2024 sunset date for certain copper alloy compositions forces housing material redesign. Meter OEMs with polymer injection molding capabilities capture specification share in Scandinavian tender processes.
After-sales service unbundling is restructuring vendor-customer relationships. French and Belgian utilities now separately procure meter hardware, installation labor, and data analytics platforms. This disaggregation pressures integrated suppliers to defend attachment rates through firmware differentiation rather than bundled pricing. Channel partners with field service networks capture installation and commissioning margins previously retained by manufacturers.
Digital Water Meters Market Segmentation
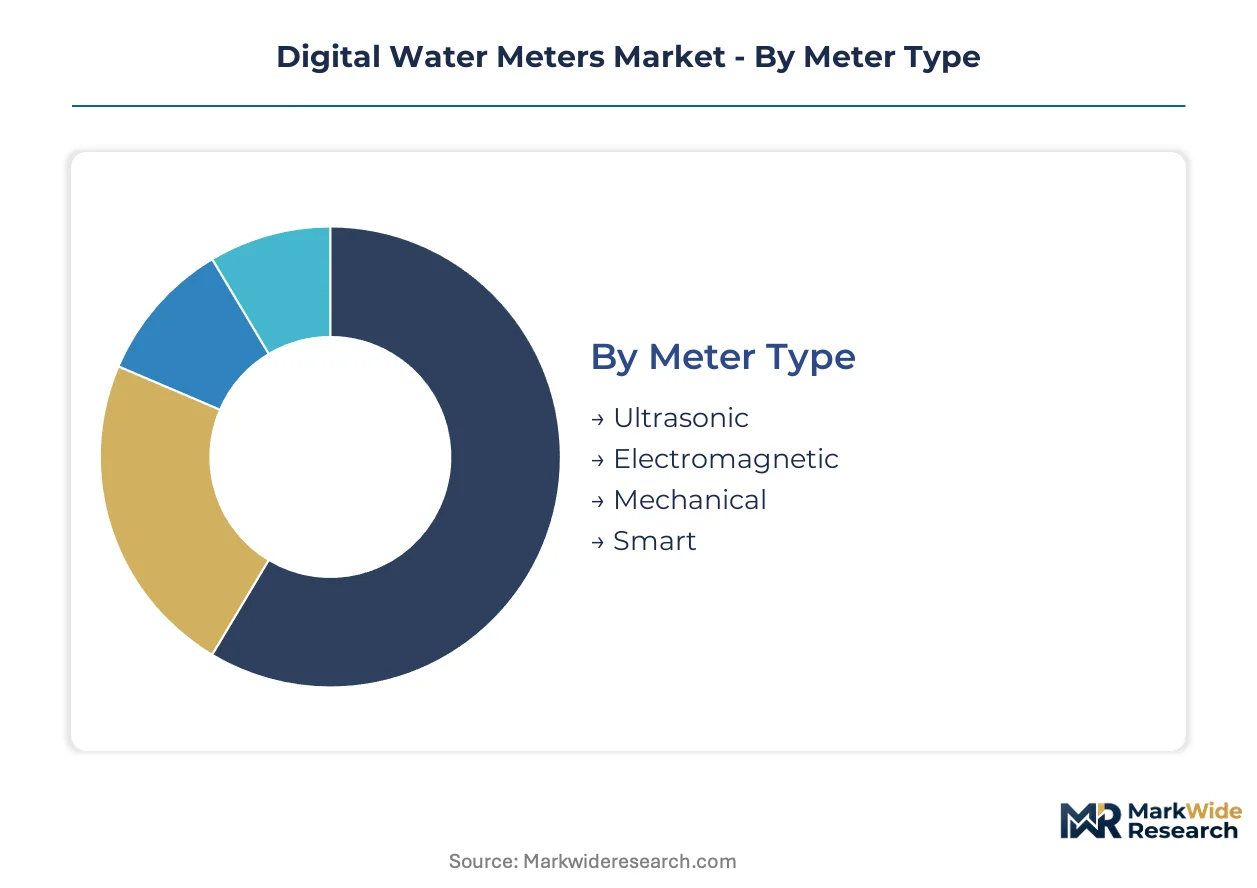
Segmentation in digital water metering reveals where procurement budgets concentrate and which technology combinations command premium positioning. Utility buyers structure tenders around meter accuracy classes, communication protocols, and deployment architectures that minimize total cost of ownership across fifteen-year asset lifecycles.
Meter Type:
Margin pools concentrate in solid-state architectures that reduce field service density and extend calibration intervals beyond mechanical alternatives.
- Ultrasonic:Time-of-flight sensors measure transit time differentials across dual acoustic paths, eliminating magnetic couplings and turbine wear. German and Dutch utilities now specify R800 accuracy class as procurement baseline, displacing encoded mechanical meters in residential refresh cycles. Solid-state designs compress lifecycle cost curves through reduced drift susceptibility.
- Smart:Firmware-enabled platforms integrate leak detection algorithms and pressure management modules, creating recurring service attachments beyond hardware shipment. French utilities pilot subscription-based district monitoring, unbundling data analytics from device procurement.
- Electromagnetic:Faraday induction coils suit high-velocity industrial applications with conductive fluids. Chemical processing plants in Belgium specify electromagnetic cores for abrasive slurry measurement.
- Mechanical:Encoded turbine assemblies retain cost-sensitive replacement demand in legacy housing stock. Spanish municipalities with constrained capital budgets continue bulk procurement of mechanical units for non-critical distribution branches.
Ultrasonic meters hold installed capacity across Northern European tenders. Smart meters are rotating up the share rankings through firmware-enabled service unbundling.
Deployment Model:
Architecture selection tracks utility IT maturity and regulatory data sovereignty requirements across national frameworks.
- Cloud-based:Carrier-managed platforms eliminate on-site server maintenance, appealing to mid-size French and Belgian water authorities with limited internal IT staffing. Deutsche Telekom and Vodafone offer meter-data-as-a-service packages that compress procurement-to-activation timelines.
- Hybrid:Edge processing with cloud backhaul balances latency-sensitive leak alerts against long-term analytics storage. Dutch utilities deploying NB-IoT backhaul retain local gateways for pressure transient detection.
- On-premise:Air-gapped installations persist in German critical infrastructure designations requiring IEC 62443 compliance. Municipal utilities in Bavaria maintain captive data centers for cybersecurity certification.
- Remote:Satellite or cellular backhaul serves dispersed rural networks where fiber penetration is insufficient. Scottish Water pilots remote architectures for Highland and Island district metering areas.
Cloud-based deployments are climbing fastest among utilities without legacy AMI sunk costs. Hybrid architectures hold installed capacity through convergence with existing mesh infrastructure.
End User:
Procurement scale and specification complexity diverge sharply between centralized municipal tenders and fragmented commercial installations.
- Municipalities:Bulk procurement frameworks across German municipal associations specify OIML R49 certification and fifteen-year battery life. Non-revenue water reduction mandates under the EU Water Framework Directive accelerate refresh schedules.
- Industrial Users:Process-critical applications demand redundant measurement chains and SIL-rated safety integration. Chemical manufacturers in the Port of Antwerp specify electromagnetic meters with HART protocol compatibility.
- Residential Users:Single-family and multi-unit housing drives volume concentration in utility-managed AMI rollouts. Danish utilities achieve penetration rates above ninety percent through regulatory-enabled remote reading mandates.
- Commercial Establishments:Retail and hospitality segments prioritize sub-metering for tenant billing allocation. Shopping center operators in Madrid deploy ultrasonic meters with integrated valve shutoff for leak containment.
Municipalities hold installed capacity through consolidated procurement frameworks. Industrial users are rotating up the share rankings through specification premiums for process-critical accuracy.
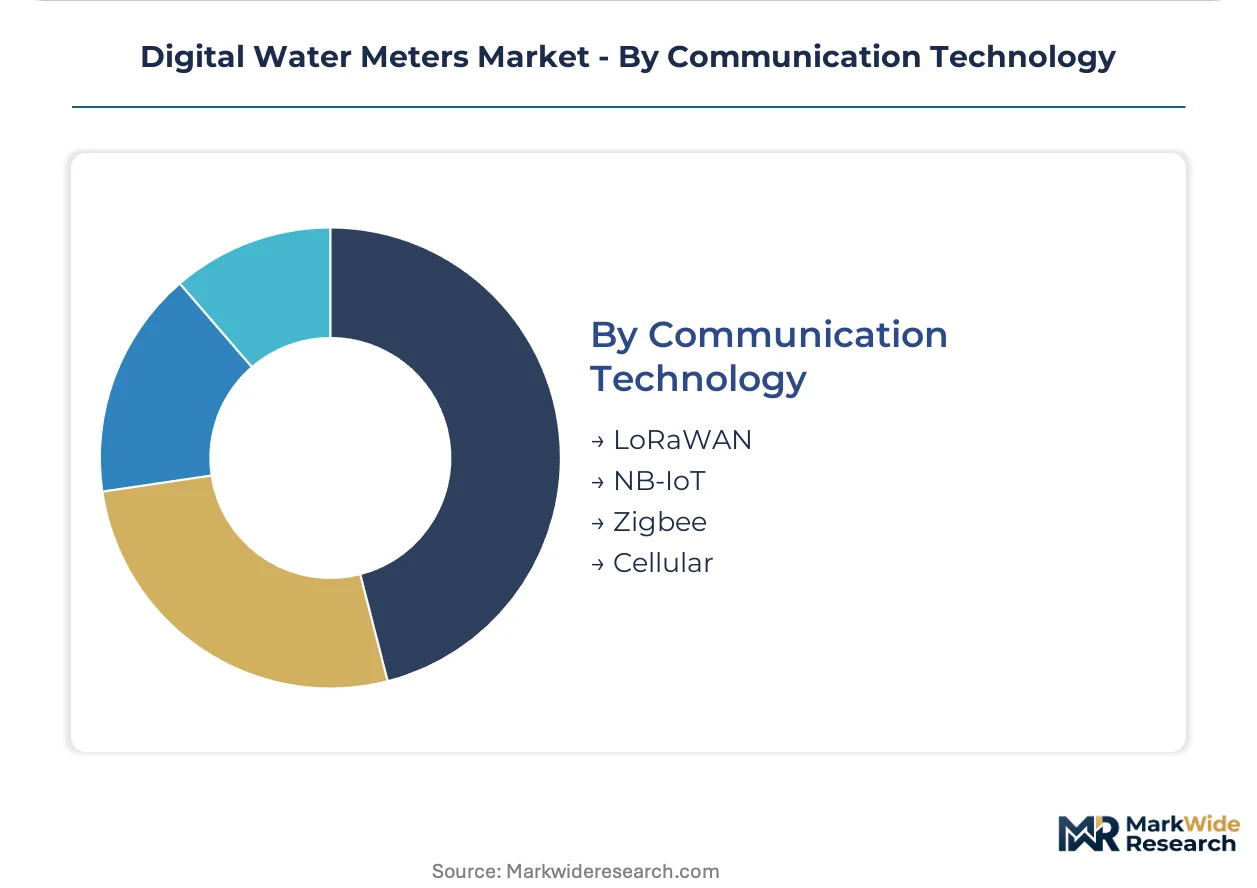
Communication Technology:
Protocol selection determines infrastructure overhead and interoperability with legacy AMI investments.
- NB-IoT:Licensed spectrum operation through Deutsche Telekom, Vodafone, and Orange removes proprietary base station requirements. German utilities prioritize NB-IoT for national coverage uniformity and reduced field engineering.
- LoRaWAN:Unlicensed sub-GHz bands enable private network deployment for utilities seeking data sovereignty. French water authorities in rural departments retain LoRaWAN for district-level autonomy.
- Cellular:4G LTE modules suit high-bandwidth applications requiring firmware over-the-air updates. Italian utilities specify cellular backhaul for smart city integration with traffic and lighting systems.
- Zigbee:Mesh networking persists in legacy AMI installations with proprietary protocol stacks. Belgian utilities bridge Zigbee collectors to NB-IoT backhaul through hybrid gateway architectures.
NB-IoT holds installed capacity through carrier national coverage commitments. LoRaWAN is rotating up the share rankings among utilities prioritizing unlicensed spectrum autonomy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal water utilities in Germany, the United States, and China dominate procurement volumes for ultrasonic and smart meter systems. Industrial process operators in Belgium and Japan add specification premiums for electromagnetic cores in high-velocity applications.
Germany
Municipal associations specify OIML R49 certification and fifteen-year battery life in bulk tenders. The EU Water Framework Directive mandates non-revenue water reduction targets that accelerate refresh schedules. Bavarian utilities maintain captive data centers for IEC 62443 cybersecurity compliance in air-gapped installations.
United States
EPA Lead and Copper Rule revisions tighten accuracy and reporting obligations for municipal end users. The FCC governs radio transmission power limits for embedded cellular and LoRaWAN modules. Wisconsin-based manufacturers leverage vertically integrated production for domestic certification compliance and rapid fulfillment cycles.
China
MIIT issues network access licenses for NB-IoT devices, creating a navigable compliance map for multi-country product strategies. Smart Cities Mission funding channels capital toward digital water infrastructure in major metropolitan areas. Domestic meter OEMs concentrate polymer injection molding capabilities for REACH-compliant housing designs.
Belgium
Chemical processing plants in the Port of Antwerp specify electromagnetic meters with HART protocol compatibility for abrasive slurry measurement. The EU Cybersecurity Act's Common Criteria evaluation timelines extend product launch schedules for connected platforms. Brussels-based utilities pilot subscription-based district monitoring with firmware-enabled leak detection.
Japan
METI standards govern precision metrology requirements for residential and industrial flow measurement applications. Process-critical installations demand redundant measurement chains with SIL-rated safety integration. Osaka-area utilities specify R800 accuracy class as procurement baseline for residential refresh cycles.
Digital Water Meters Market Competitive Landscape
Player mix skews toward precision metrology specialists with captive ultrasonic transducer capabilities and vertically integrated manufacturing footprints. The competitive set organizes into three tiers: multinational instrumentation conglomerates with broad utility automation portfolios, regional specialists focused on municipal procurement frameworks, and component suppliers seeking downstream integration into meter assembly. Dominant competitive moves include geographic expansion through municipal tender participation and technology licensing for NB-IoT communication module integration.
Among North American instrumentation providers, Badger Meter, Inc. and Xylem Inc. exemplify the scale-driven tier with established utility relationships. European specialists Diehl Metering GmbH and Kamstrup A/S occupy positions anchored in German and Danish municipal procurement frameworks respectively. Honeywell International Inc. represents the diversified industrial conglomerate archetype with cross-sector automation capabilities. These named entities serve as anchors for understanding how competitive positioning distributes across geographic and technological vectors.
| Leading Market Players |
|---|
| Badger Meter, Inc. |
| Xylem Inc. |
| Itron, Inc. |
| Diehl Metering GmbH |
| Neptune Technology Group, Inc. |
| Kamstrup A/S |
| Landis+Gyr |
| Mueller Water Products |
| Honeywell International Inc. |
| Others |
Pricing and Supply Chain Analysis
OIML R49 certification gates both supplier qualification and price differentiation in municipal procurement frameworks, compressing margins for uncertified entrants while enabling premium positioning for precision metrology specialists with validated firmware algorithms. German and Dutch water authorities now specify R800 accuracy class as tender baseline, forcing housing material redesign and transducer ASIC sourcing decisions that cascade through final unit economics.
Pricing Analysis
Cost-plus contracts with semiconductor indexation dominate municipal utility procurement, tying final unit pricing to Taiwanese foundry output costs and lithium thionyl chloride cell commodity curves. Pricing stratifies across premium, standard, and economy tiers based on accuracy certification grade and after-sales service bundling, with ultrasonic solid-state meters commanding hardware premiums over encoded mechanical alternatives. Cost compression in the mechanical tier intensifies as Spanish municipalities with constrained capital budgets consolidate volume for non-critical distribution branches. Residential end users exhibit highest price sensitivity through utility-managed AMI rollouts, while industrial process operators in Belgium's Port of Antwerp absorb specification premiums for SIL-rated safety integration.
Supply Chain Analysis
Inventory lead times for ultrasonic transducer ASICs and cellular modem chipsets now stretch eighteen to twenty-four months, forcing meter OEMs into strategic stockpiling commitments. Manufacturing concentrates in Taiwan, South Korea, and Germany for precision metrology components, with polymer injection molding capabilities anchoring in China and Scandinavia for REACH-compliant housing designs. The supply chain rests on single-source vulnerability for NB-IoT baseband processors and specialized battery chemistries. Distribution runs through municipal procurement frameworks in Germany and France, channel partners with field service networks in Belgium, and direct utility relationships in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NB-IoT protocol standardization is accelerating market disruption as carrier-grade networks eliminate proprietary infrastructure requirements, creating acquisition windows for precision metrology assets with validated firmware platforms.
For Market Incumbents: Fortify metrology firmware validation capabilities to defend against Asian component suppliers seeking downstream integration into meter assembly. Invest in captive ultrasonic transducer production to offset Taiwanese foundry concentration risk. Deepen backward integration into polymer composite housing manufacturing ahead of ECHA's copper alloy sunset deadlines. For New Entrants and Emerging Players: Differentiate on firmware-enabled leak detection algorithms to capture subscription-based district monitoring pilots in French and Belgian utilities. Target India's AMRUT 2.0 funding channels in Bengaluru and Chennai where certification requirements remain less stringent than EU frameworks. Pursue channel partnerships with German municipal associations rather than direct tender participation. For Investors and Strategic Acquirers: The EU Cybersecurity Act's Common Criteria evaluation timelines reshape the acquisition landscape toward platforms with existing certification rather than development-stage assets. Five-to-ten year viability favors precision metrology specialists with OIML R49 validation and NB-IoT module integration already completed. Watch for German municipal tender announcements with fifteen-year battery life specifications as inflection indicators for solid-state meter demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| NB-IoT Module Integration | Carrier-grade certification through Deutsche Telekom and Vodafone compresses deployment timelines for municipal utilities. |
| Ultrasonic Transducer Backward Integration | In-house production of time-of-flight sensors reduces dependency on Taiwanese ASIC foundries and extends margin capture. |
| Polymer Composite Housing Transition | REACH-compliant material redesign ahead of ECHA copper alloy sunset dates captures Scandinavian tender specifications. |
| Firmware-as-a-Service Unbundling | Subscription-based leak detection algorithms create recurring revenue attachments beyond hardware shipment economics. |
| Hybrid LoRaWAN-NB-IoT Architecture Development | Converged radio stacks preserve sunk infrastructure investment while enabling carrier-managed backhaul migration. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of utility procurement databases, OIML certification registries, and carrier network coverage disclosures. Interviews with municipal water authority planning officers, AMI program managers at German municipal associations, and precision metrology R&D directors informed demand-side assumptions. Secondary validation drew from ECHA regulatory filings, Deutsche Telekom IoT platform disclosures, and EU Water Framework Directive implementation reports. Bottom-up unit economics triangulated against top-down municipal capital expenditure patterns across the analysis window.
Segmentation dimensions modeled include meter type, communication protocol, deployment architecture, and end-user category throughout the forecast period. CAGRs derived from utility refresh cycle timing, regulatory mandate enforcement schedules, and carrier network rollout commitments. Industry-specific inputs incorporated ultrasonic transducer cost curves, lithium thionyl chloride battery chemistry degradation profiles, and firmware validation timeline benchmarks.
Decision-makers should treat outputs as directional under assumptions of sustained NB-IoT carrier coverage expansion and stable semiconductor foundry capacity; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
North America Smart Meter Data Management Market
Smart Meters
Residential Smart Water Metering Market
Smart Meters
Europe Smart Water Meter Market
Smart Meters
Smart Utility Solutions Market
Smart Meters
Smart Gas Meter Market
Smart Meters
Power Quality Meter Market
Smart Meters
Smart Meter Data Management Market
Smart Meters
Europe Smart Meters Market
Smart Meters
Residential Water Submetering Market
Smart Meters
Middle East Distribution Meter Market
Smart Meters
Smart Meter Antenna Market
Smart Meters
South and Central America Smart Metering Market
Smart Meters
Residential RF Smart Electric Meter Market
Smart Meters
Smart Metering Systems Market
Smart Meters
Smart Meter Battery Market
Smart Meters
LNG Metering Skids Market