
 Asia-Pacific Bifacial Solar Market | 2026-2036
Asia-Pacific Bifacial Solar Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Bifacial Solar Market Insights
Utility buyer concentration in the Asia-Pacific bifacial solar sector is broadening as state-backed power developers in Vietnam, Indonesia, and the Philippines diversify procurement beyond Chinese state-owned enterprises. LONGi leverages its integrated polysilicon-to-module chain to control cost structures across the value chain. Trinasolar anchors its competitive position through vertical manufacturing scale in Jiangsu and Changzhou. JA Solar Technology Co., Ltd. specializes in high-efficiency PERC bifacial designs for humid subtropical climates.
Bifacial solar photovoltaic systems capture irradiance from both front and rear surfaces through transparent backsheet or dual-glass construction, typically achieving 5-30% additional energy yield depending on albedo and mounting height; the technology serves utility-scale and commercial installations seeking levelized cost of electricity reduction. Monocrystalline technology leads module shipments across the Asia-Pacific region due to superior conversion efficiency in space-constrained deployments. Ground-mounted applications command the largest addressable volume as tracking infrastructure spreads across Australia's arid interior and India's Rajasthan desert. Utility end users concentrate procurement power through centralized tenders exceeding 500 MW capacity.
China's National Energy Administration and India's Central Electricity Authority shape deployment trajectories through renewable purchase obligations and grid interconnection standards that increasingly specify bifacial performance testing. Australia's Clean Energy Council mandates IEC 61215 certification for module eligibility in accredited installations. Japan's METI adjusts feed-in premium calculations to reflect bifacial gain coefficients in mountainous terrain. Stakeholders must monitor evolving albedo measurement protocols and rear-side irradiance testing methodologies as banks and insurers refine performance guarantees.
Market Dynamics
Feed-in tariff recalibration across Southeast Asia is compressing payback periods for utility-scale bifacial projects, redirecting procurement flows from monofacial legacy contracts toward dual-glass module tenders that capture elevated rear-side irradiance in high-albedo terrain.
Growth Catalysts
- Renewable Purchase Obligations:India's Central Electricity Authority mandates distribution utilities to source specified percentages from solar, with bifacial modules qualifying for bonus renewable energy certificates in Rajasthan and Gujarat.
- Albedo-Optimized Tracking:Single-axis trackers paired with elevated bifacial mounting are automating yield optimization across Australia's Pilbara and Queensland solar corridors.
- Vietnam Feed-In Tariff Revision:The Ministry of Industry and Trade's adjusted pricing framework for solar projects commissioned after 2024 explicitly incorporates bifacial gain coefficients into tariff calculations.
Market Restraints
- Polysilicon Supply Concentration:Xinjiang and Inner Mongolia polysilicon smelters supply over 80% of regional wafer feedstock, creating geographic concentration risk for module cost structures.
- Rear-Side Performance Uncertainty:Lack of standardized albedo measurement protocols complicates bankability assessments for bifacial projects in variable terrain.
- Dual-Glass Weight Penalty:2.0mm heat-strengthened glass construction increases logistics costs and imposes structural load requirements that exclude certain rooftop segments.
Strategic Opportunities
- Agrivoltaic Integration:Elevated bifacial arrays in Japan's Chubu and Kanto regions enable simultaneous crop cultivation and energy generation, unlocking rural land-use premiums.
- Floating Solar Deployment:Water surface albedo exceeding 0.10 on Indonesian reservoirs and Thai irrigation ponds creates ideal conditions for bifacial gain capture.
- Indonesia PLN Tender Expansion:State electricity utility Perusahaan Listrik Negara's 2024-2028 procurement roadmap specifies bifacial eligibility for 3.5 GW of utility-scale capacity.
Industry Challenges
- IEC 61215 Certification Bottlenecks:Testing laboratory capacity constraints in the region extend module qualification timelines by 8-14 weeks, delaying project financial close.
- Rear-Side Soiling Expertise Gap:Limited field data on dust accumulation patterns in monsoon climates complicates O&M contract structuring for Indonesian and Philippine developers.
- Grid Interconnection Queue Delays:Vietnam's National Load Dispatch Center processing backlogs stall commercial operation dates for completed bifacial installations in Binh Thuan and Ninh Thuan provinces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Bifacial Solar Market |
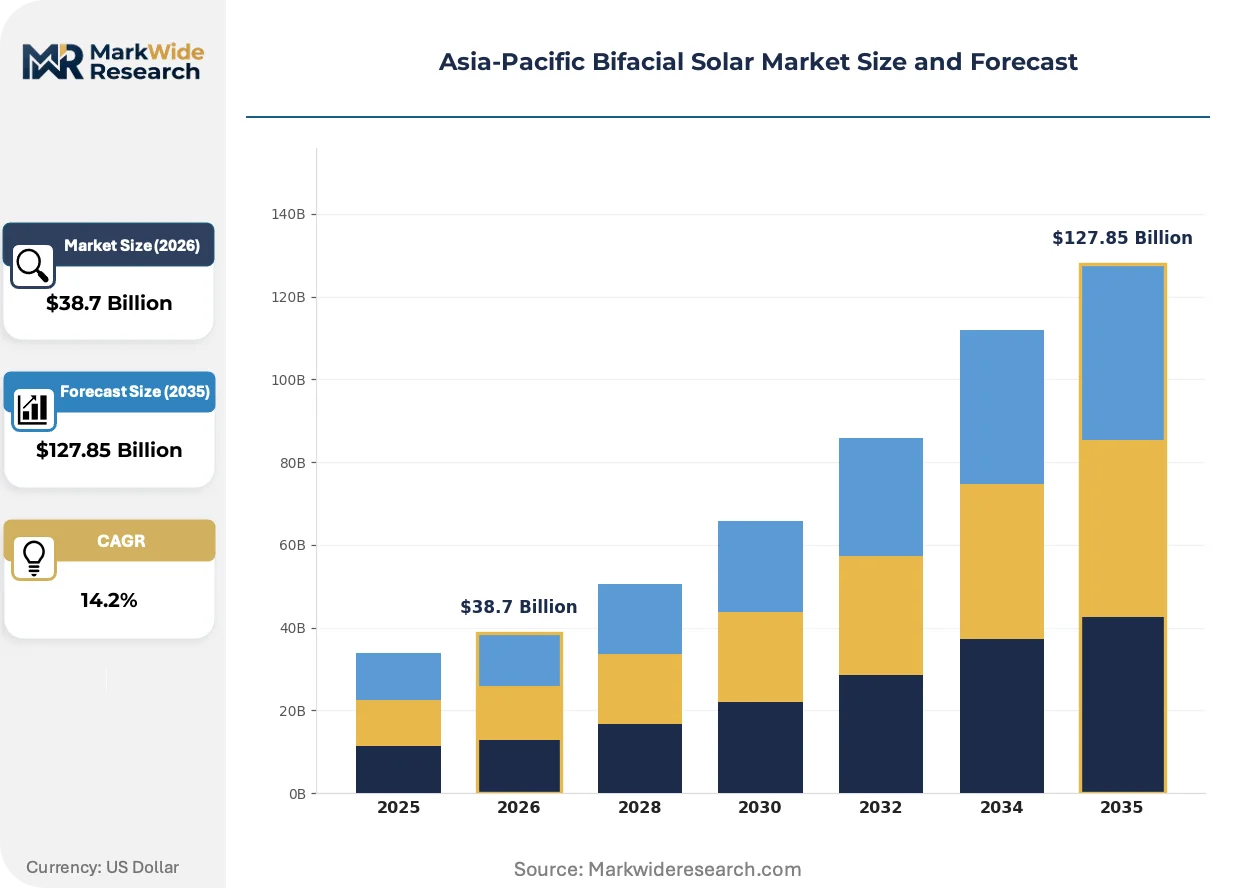
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar Panels, Inverters, Installation Kits, Racking Systems End User: Residential, Commercial, Industrial, Utility Technology: Monocrystalline, Polycrystalline, Thin Film, PERC Application: Grid-Connected, Off-Grid, Building Integrated, Ground Mounted |
| Companies Covered | LONGi, Trinasolar, JA Solar Technology Co., Ltd., Jinko Solar, Canadian Solar, Risen Energy, Huasun Energy, TW Solar, Hanwha Q Cells, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Bifacial Solar Market Trends and Innovations
Module architecture is bifurcating between glass-glass durability and transparent backsheet lightweighting, while automated manufacturing lines compress cell-to-module throughput times. Regulatory frameworks are maturing to capture bifacial performance characteristics in tariff design and grid codes.
TOPCon cell metallization is automating conversion efficiency gains beyond 25% in mass production. Chinese cell manufacturers in Anhui and Zhejiang are retrofitting PERC lines to tunnel oxide passivated contact architecture at 2-3 GW monthly conversion rates. This process automation is compressing the cost gap between bifacial TOPCon and legacy mono-PERC modules to under $0.008 per watt.
Japan's METI has recalculated feed-in premium structures to reflect bifacial gain coefficients in mountainous prefectures. The revised ordinance requires project developers to submit terrain-specific albedo assessments for tariff tier qualification. Hokkaido and Nagano prefectures are experiencing accelerated permitting for bifacial installations that demonstrate validated rear-side irradiance capture.
Utility procurement committees are consolidating module qualification lists around bankable testing standards. State-backed developers in Vietnam and the Philippines now require IEC 61215:2021 certification with bifacial-specific thermal cycling sequences prior to tender participation. This certification-driven selection is marginalizing second-tier module suppliers lacking accredited laboratory partnerships.
Asia-Pacific Bifacial Solar Market Segmentation
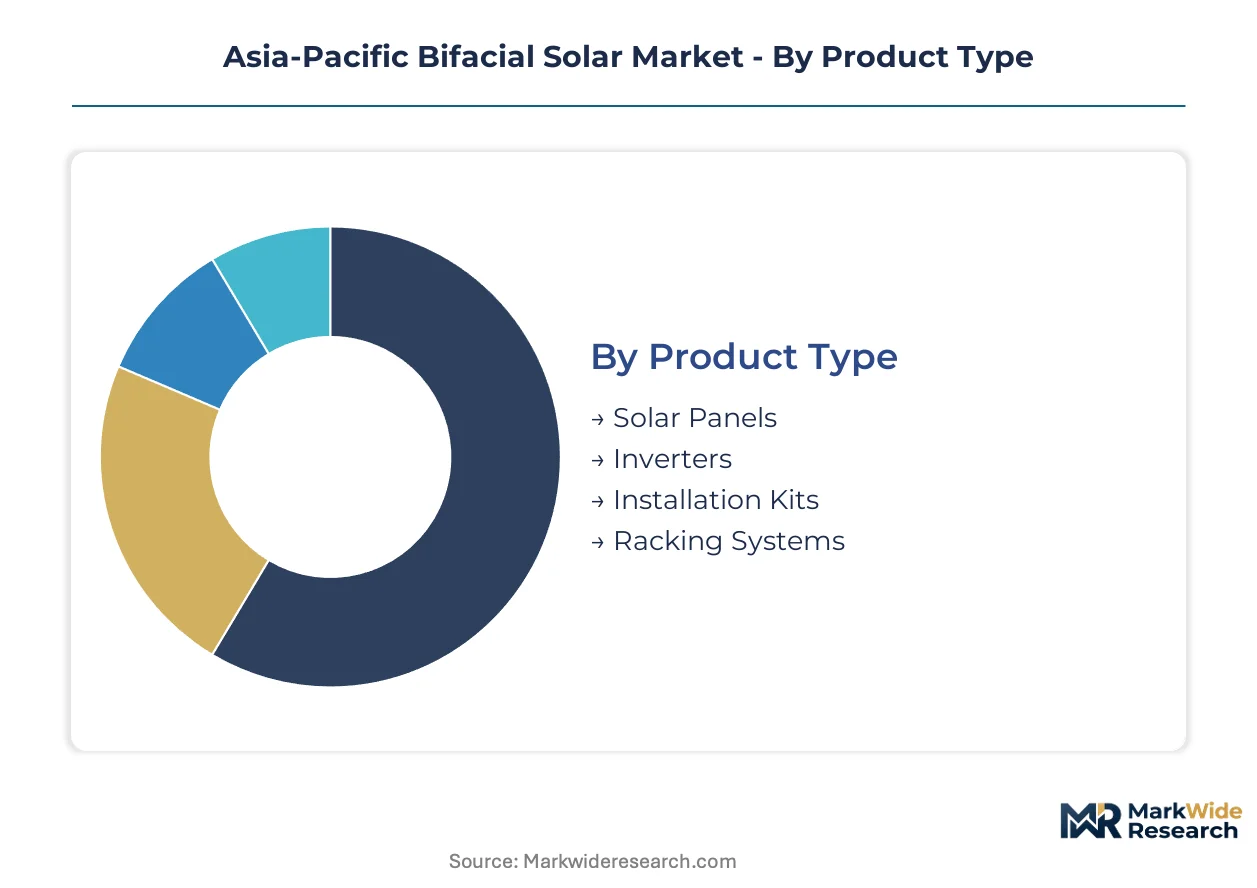
Bifacial solar deployment patterns diverge sharply across product architectures, customer scale, and grid integration models. Understanding these segment boundaries illuminates where procurement budgets concentrate and which technical specifications command premium positioning.
Product Type:
Technology specification determines warranty terms, logistics complexity, and balance-of-system integration requirements across the value chain.
- Solar Panels:Dual-glass and transparent backsheet constructions dominate procurement specifications, with rear-side irradiance capture driving yield premiums in high-albedo terrain. Chinese coastal provinces and Australia's Pilbara region concentrate demand for glass-glass durability in utility-scale parks.
- Inverters:String and central inverter architectures with bifacial-optimized maximum power point tracking algorithms accommodate variable rear-side current injection. Procurement concentrates among state-backed developers in Vietnam and Indonesia seeking grid compliance certification.
- Installation Kits:Elevated mounting hardware and cabling systems engineered for rear-side clearance specifications.
- Racking Systems:Single-axis tracking infrastructure paired with bifacial elevation protocols.
Mature deployment sits with Solar Panels. Newer deployment is concentrated in Racking Systems.
End User:
Customer scale dictates financing structures, procurement aggregation power, and O&M contract sophistication.
- Utility:Centralized tenders exceeding 500 MW capacity leverage concentrated procurement power to enforce IEC 61215:2021 certification with bifacial-specific thermal cycling sequences. Vietnam's National Load Dispatch Center and Indonesia's PLN anchor regional demand through state-backed power purchase agreements.
- Commercial:C&I rooftops and carport installations in Japan's Chubu and Kanto regions exploit elevated bifacial arrays for agrivoltaic land-use premiums.
- Industrial:Captive power consumers in India's Rajasthan and Gujarat industrial corridors.
- Residential:Distributed rooftop segments constrained by dual-glass weight penalties and structural load limitations.
Procurement volume clusters in Utility. Margin expansion potential sits with Commercial.
Technology:
Cell architecture selection determines conversion efficiency thresholds and manufacturing cost trajectories.
- Monocrystalline:Superior conversion efficiency in space-constrained deployments drives shipment leadership across the region. Anhui and Zhejiang manufacturers are retrofitting PERC lines to tunnel oxide passivated contact architecture, compressing the cost gap with legacy mono-PERC modules.
- PERC:Passivated emitter and rear contact designs optimized for bifacial current collection in humid subtropical climates.
- Polycrystalline:Cost-sensitive applications with lower efficiency requirements.
- Thin Film:Niche flexible substrate deployments for building-integrated configurations.
Manufacturing scale concentrates in Monocrystalline. Technology transition momentum sits with PERC.
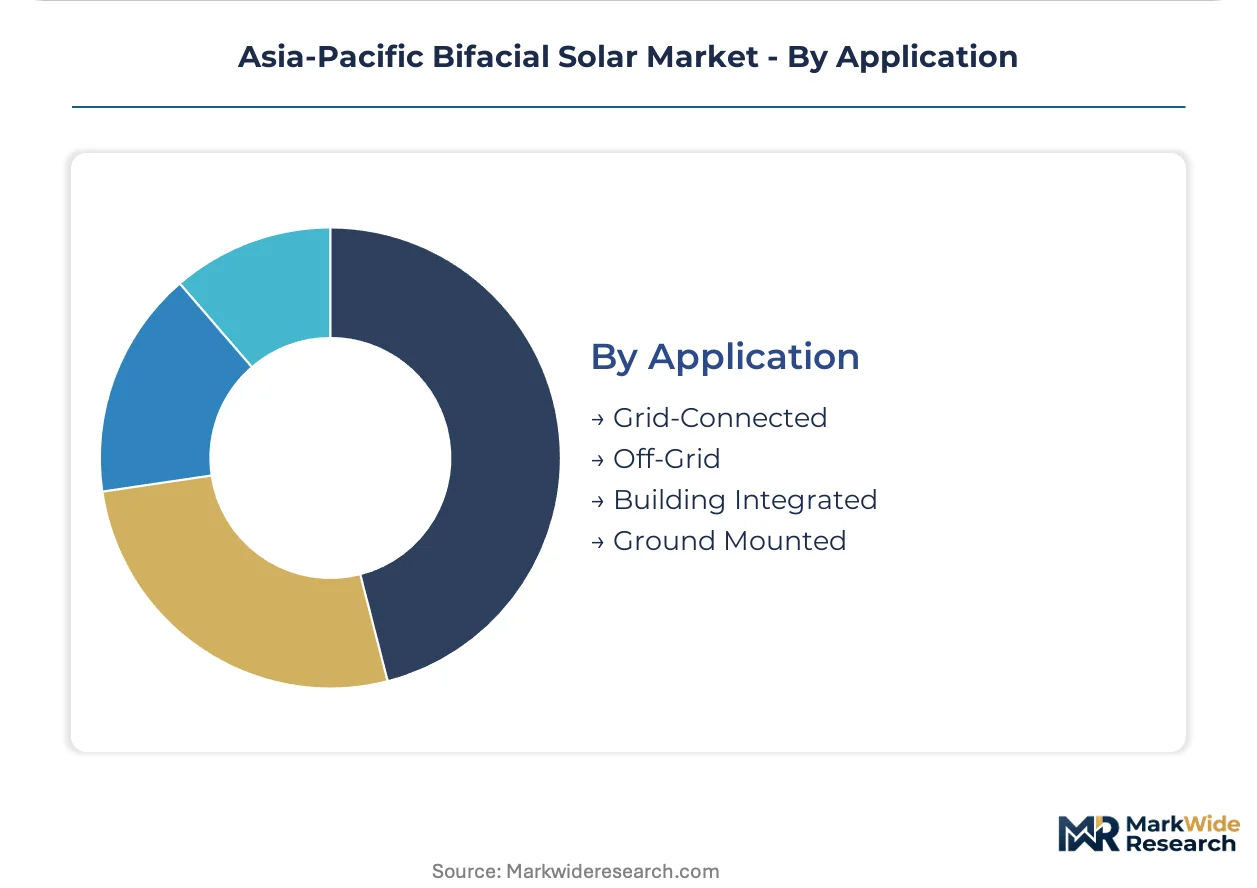
Application:
Grid integration topology shapes albedo exploitation potential and interconnection queue positioning.
- Ground Mounted:Tracking infrastructure spreads across Australia's arid interior and India's Rajasthan desert, commanding the largest addressable volume through single-axis automation paired with elevated bifacial mounting.
- Grid-Connected:Utility-scale parks in Vietnam's Binh Thuan and Ninh Thuan provinces face interconnection queue delays at the National Load Dispatch Center despite completed installations.
- Building Integrated:Facade and rooftop BIPV with bifacial glass-glass construction.
- Off-Grid:Remote mining and island electrification in Indonesian archipelago territories.
Yield optimization technology concentrates in Ground Mounted. Regulatory complexity clusters in Grid-Connected.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Xinjiang's polysilicon smelters anchor raw material flows for module assembly across coastal manufacturing belts. The region's metallurgical-grade silicon purification capacity feeds wafer production in Jiangsu and Anhui provinces.
China
Gigawatt-scale solar parks in Shandong and Jiangsu provinces integrate bifacial panels with single-axis tracking systems to maximize albedo capture from coastal terrain. The National Energy Administration's renewable purchase obligations mandate distribution utilities to source specified solar percentages. Changzhou and Hefei manufacturing clusters house automated cell-to-module production lines retrofitting PERC capacity to tunnel oxide passivated contact architecture.
India
Rajasthan and Gujarat industrial corridors concentrate utility-scale procurement through centralized tenders exceeding 500 MW capacity. The Central Electricity Authority mandates distribution utilities to source specified percentages from solar, with bifacial modules qualifying for bonus renewable energy certificates. Bhadla and Pavagada solar parks deploy elevated bifacial mounting across high-albedo desert terrain.
Vietnam
Binh Thuan and Ninh Thuan provinces host completed bifacial installations awaiting grid interconnection clearance from the National Load Dispatch Center. The Ministry of Industry and Trade's adjusted pricing framework for projects commissioned after 2024 explicitly incorporates bifacial gain coefficients into tariff calculations. State-backed power developers diversify procurement beyond Chinese state-owned enterprises.
Australia
The Pilbara and Queensland solar corridors automate yield optimization through single-axis trackers paired with elevated bifacial mounting. The Clean Energy Council mandates IEC 61215 certification for module eligibility in accredited installations. Arid interior regions command the largest addressable volume through ground-mounted tracking infrastructure.
Japan
Chubu and Kanto regions experience accelerated permitting for bifacial installations demonstrating validated rear-side irradiance capture in mountainous terrain. METI has recalculated feed-in premium structures to reflect bifacial gain coefficients, requiring terrain-specific albedo assessments for tariff tier qualification. Agrivoltaic deployments enable simultaneous crop cultivation and energy generation.
Asia-Pacific Bifacial Solar Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized cell architectures and regional certification pathways. The vendor base stratifies between integrated polysilicon-to-module chains and specialist cell manufacturers. Three archetypes dominate: backward-integrated material controllers, scale-driven module assemblers, and efficiency-focused technology licensors. Competitive moves concentrate on manufacturing line retrofits and accredited laboratory partnerships for IEC certification.
Among Chinese integrated manufacturers, LONGi and Trinasolar exemplify the material-control archetype through captive polysilicon sourcing. JA Solar Technology Co., Ltd. occupies a position within the efficiency-specialist tier, representing PERC-to-TOPCon transition strategies for humid subtropical climates. These three anchors illustrate how competitive positioning bifurcates between cost-structure control and conversion-efficiency leadership.
| Leading Market Players |
|---|
| LONGi |
| Trinasolar |
| JA Solar Technology Co., Ltd. |
| Jinko Solar |
| Canadian Solar |
| Risen Energy |
| Huasun Energy |
| TW Solar |
| Hanwha Q Cells |
| Others |
Pricing and Supply Chain Analysis
China's dual carbon goals gate qualified supply and premium-tier pricing access, bifurcating the module market between IEC 61215:2021-certified producers commanding tariff premiums and uncertified suppliers competing on spot pricing for non-accredited installations.
Pricing Analysis
Volume procurement concentrates among state-backed utilities in Vietnam and Indonesia, while margin expansion sits with commercial agrivoltaic developers in Japan's Chubu region. Price differentiation separates IEC-certified premium tiers from standard-grade modules lacking bifacial-specific thermal cycling validation. Cost compression in standard-grade segments is intensifying as TOPCon retrofitting compresses the gap with legacy mono-PERC. Utility buyers exhibit lowest price sensitivity due to long-term PPA structures, while residential rooftop installers face acute pressure from dual-glass weight penalties.
Supply Chain Analysis
Freight costs from Xinjiang and Inner Mongolia polysilicon smelters to coastal module assembly hubs in Jiangsu and Anhui shape landed cost structures for regional buyers. Raw material flows draw from metallurgical-grade silicon purification, tunnel oxide passivated contact cell metallization, and 2.0mm heat-strengthened glass sheet production. Single-source vulnerability concentrates in Xinjiang polysilicon feedstock, where over four-fifths of regional wafer supply originates. Distribution runs through state-backed tender platforms in Vietnam's National Load Dispatch Center and Indonesia's PLN procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around certification-compliant producers, with IEC 61215:2021 bottlenecks forcing weaker players lacking accredited laboratory partnerships toward insolvency or acquisition.
For Market Incumbents: To counter second-tier suppliers undercutting on non-certified spot volumes, deepen backward integration into Xinjiang polysilicon sourcing and accelerate PERC-to-TOPCon line retrofits in Anhui and Zhejiang manufacturing clusters. Secure exclusive partnerships with TÜV Rheinland or Intertek testing facilities to compress qualification timelines.
For New Entrants and Emerging Players: Begin with Indonesia's PLN tender expansion for 3.5 GW of bifacial-eligible capacity, where state-backed procurement diversification creates white-space beyond Chinese SOE incumbents. Target floating solar deployment on Thai irrigation ponds and Indonesian reservoirs, exploiting water surface albedo exceeding 0.10 with specialized elevated mounting hardware.
For Investors and Strategic Acquirers: Vietnam's Ministry of Industry and Trade feed-in tariff revision incorporating bifacial gain coefficients is the leading indicator that bankable project pipelines will concentrate among certified-module developers. Target acquisition archetypes are mid-scale EPC contractors with established National Load Dispatch Center interconnection relationships and validated albedo assessment capabilities. Watch for PLN tender award announcements as inflection signals of procurement flow redirection.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Line Retrofit | TOPCon conversion in Anhui and Zhejiang compresses cost gaps with legacy PERC modules. |
| Accredited Laboratory Partnership | IEC 61215:2021 certification with bifacial-specific thermal cycling unlocks tender eligibility. |
| Agrivoltaic Deployment | Elevated bifacial arrays in Japan's Kanto region unlock rural land-use premiums. |
| Floating Solar Expansion | Water surface albedo on Indonesian reservoirs maximizes bifacial gain capture. |
| Polysilicon Supply Security | Captive Xinjiang and Inner Mongolia feedstock insulates against geographic concentration risk. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators across Vietnam, Indonesia, and Australia. Secondary validation drew from China's National Energy Administration deployment statistics, India's Central Electricity Authority renewable purchase obligation reports, Vietnam's Ministry of Industry and Trade tariff revision documents, and Australia's Clean Energy Council accreditation databases. Bottom-up module shipment aggregation and top-down policy impact modeling were reconciled through cross-reference triangulation.
Data-stream reconciliation across installation capacity, module pricing indices, and policy implementation timelines shaped the analytical framework. Segmentation dimensions modeled include product architecture, end-user scale, cell technology, and application topology across the projection horizon. CAGRs were derived from regression analysis of historical deployment trajectories against feed-in tariff elasticity and renewable purchase obligation stringency. Forecast inputs incorporated albedo measurement protocol maturation and rear-side irradiance testing standardization.
Underlying measurement precision varies by segment; utility-scale ground-mounted deployments carry tighter precision than distributed rooftop installations due to centralized reporting requirements. Forecasts reflect assumptions regarding grid interconnection queue processing rates and certification laboratory capacity expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Photovoltaic (PV) Panel Market
Solar Power Systems
United Kingdom Solar Power Market
Solar Power Systems
Asia-Pacific Rooftop Solar Market
Solar Power Systems
Mexico Rooftop Solar Market
Solar Power Systems
Solar Kiosk Market
Solar Power Systems
Photovoltaic Coating Market
Solar Power Systems
Grid-Connected Solar Microinverter Market
Solar Power Systems
Thin Film Photovoltaic Modules Market
Solar Power Systems
Solar Shed Light Market
Solar Power Systems
Global Ultra Efficient Solar Power Market
Solar Power Systems
Solar Panel Bracket Market
Solar Power Systems
On-Site Photovoltaic Solar Power for Data Centers Market
Solar Power Systems
Solar Power Tracker Market
Solar Power Systems
Kuwait Solar Energy Market
Solar Power Systems
PV Solar Data Logger Market
Solar Power Systems
Solar Laminator Market