
 Spray-On Solar Cells Market | 2026-2036
Spray-On Solar Cells Market Size, Share, and Industry Trends Forecast 2026-2036
Spray-On Solar Cells Market Analytics
Perovskite ink formulation is tilting photovoltaic manufacturing away from rigid silicon wafer processing toward solution-based deposition. Swift Solar leverages roll-to-roll coating expertise to sustain cost advantages in lightweight module production. Oxford PV anchors its position through tandem cell architectures that stack perovskite layers atop conventional substrates. Heliatek competes in the organic photovoltaic segment with vacuum-deposited small-molecule films for building-integrated applications.
Spray-on solar cells comprise photovoltaic active layers deposited from liquid or aerosol precursors onto flexible or curved substrates, typically achieving absorber thicknesses below one micrometer through low-temperature processing. The technology enables conformal coating of irregular surfaces for building-integrated generation, portable power, and automotive integration where rigid panels prove impractical. Perovskite solar cells command the fastest expansion trajectory due to rapid efficiency gains and simplified ink-based fabrication. Organic photovoltaics occupy established niches in indoor and low-light energy harvesting where manufacturing scale already exists. Roll-to-roll processing dominates production economics for volume applications, while inkjet printing enables precise patterning for consumer electronics integration.
REACH chemical registration in Europe governs perovskite precursor materials and solvent formulations, constraining supply chain choices for manufacturers serving EU building markets. The EU Green Deal's building performance standards create direct procurement pull for integrated renewable surfaces in renovation projects. Japan's METI oversees photovoltaic certification protocols that determine grid access eligibility for novel thin-film products. Stakeholders must track evolving perovskite stability testing protocols and cadmium-free composition requirements as these standards crystallize across jurisdictions.
Market Dynamics
Perovskite ink chemistry is compressing manufacturing capital requirements and opening fabrication to non-semiconductor entrants, fundamentally restructuring who can produce photovoltaic material.
Growth Catalysts
- EU Green Deal building mandates:Renovation requirements for commercial structures create direct procurement pathways for lightweight integrated solar surfaces across Germany, France, and Italy.
- Roll-to-roll coating scale-up:Continuous processing lines achieve throughput economics previously reserved for silicon ingot production, collapsing unit costs for flexible module output.
- Automotive curved surface integration:Electric vehicle roof and hood applications demand conformal photovoltaics that rigid crystalline cells cannot satisfy.
Market Restraints
- Lead content regulatory friction:REACH authorization processes for lead-based perovskite precursors extend formulation approval timelines and constrain EU market entry for conventional chemistries.
- Encapsulation material supply concentration:High-barrier polymer films for moisture protection concentrate among Japanese and Korean specialty chemical suppliers, creating input vulnerability.
- Indoor organic photovoltaic substitution:Amorphous silicon and dye-sensitized alternatives already occupy low-light energy harvesting niches, limiting spray-on organic cell pricing power.
Strategic Opportunities
- Australian distributed generation retrofit:Residential rooftop renovation rates and solar penetration headroom create demand for lightweight overlay products that avoid structural reinforcement.
- Tandem perovskite-silicon convergence:Stacked architectures combining spray-deposited top layers with existing silicon infrastructure enable efficiency breakthroughs without full manufacturing replacement.
- Japan METI certification pathway expansion:Streamlined thin-film grid access protocols reduce time-to-market for novel formulations targeting building-integrated deployment.
Industry Challenges
- Solution-process engineering talent scarcity:Roll-to-roll coating optimization and ink rheology control require skill sets concentrated in packaging and display industries, not traditional solar manufacturing.
- Accelerated degradation testing protocols:IEC stability standards for perovskite cells remain under development, forcing manufacturers to fund proprietary validation programs ahead of harmonized requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spray-On Solar Cells Market |
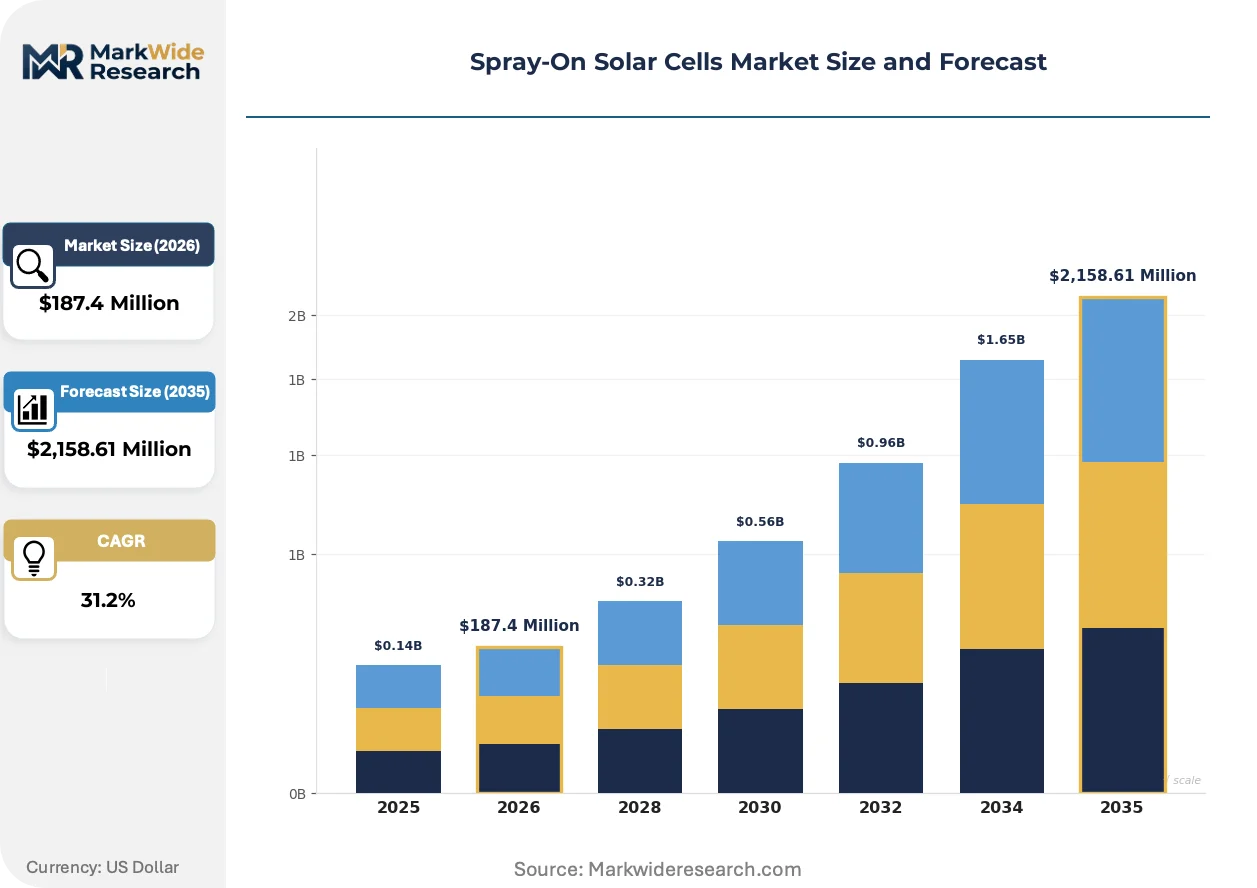
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $2,158.61 Million |
| CAGR (2026 – 2036) | 31.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Photovoltaics, Perovskite Solar Cells, Thin-Film Solar Cells, Dye-Sensitized Solar Cells End User: Residential, Commercial, Industrial, Transportation Application: Building-Integrated, Portable Devices, Automotive, Consumer Electronics Technology: Low-Temperature Deposition, Inkjet Printing, Roll-to-Roll Processing, Vacuum Deposition |
| Companies Covered | Swift Solar, Nanoco Technologies, Oxford PV, Tesla, Nanosolar, Heliatek, SolarWindow Technologies, GreatCell Energy, Saule Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spray-On Solar Cells Market Evolving Landscape
Photovoltaic manufacturing is shedding its semiconductor heritage as solution-based deposition methods enable new substrate classes and fabrication locations.
Perovskite absorber formulation is migrating from laboratory spin-coating toward slot-die and inkjet printing methods compatible with continuous web processing. Building-integrated photovoltaic developers in Germany and Japan adopt these techniques to coat architectural glass and metal roofing at production speeds exceeding one meter per minute. This migration from batch wafer processing to roll-to-roll fabrication collapses capital intensity thresholds and invites packaging industry players into solar supply chains.
REACH chemical registration in Europe tightens oversight of organometallic precursors and polar aprotic solvents used in perovskite synthesis. Manufacturers must submit full toxicological dossiers for methylammonium lead iodide variants and N-methyl-2-pyrrolidone carriers before commercial distribution. German formulators respond by accelerating cadmium-free and lead-reduced composition development to preempt authorization denials.
Architects and construction procurement teams now specify building-integrated photovoltaics during schematic design rather than adding renewable systems post-hoc. This front-loaded selection process favors thin-film and spray-on products that merge with envelope functions rather than overlaying conventional panels. The shift concentrates in commercial new-build and deep retrofit segments across France, the Netherlands, and urban Australian markets where aesthetic integration carries premium weighting.
Spray-On Solar Cells Market Segmentation
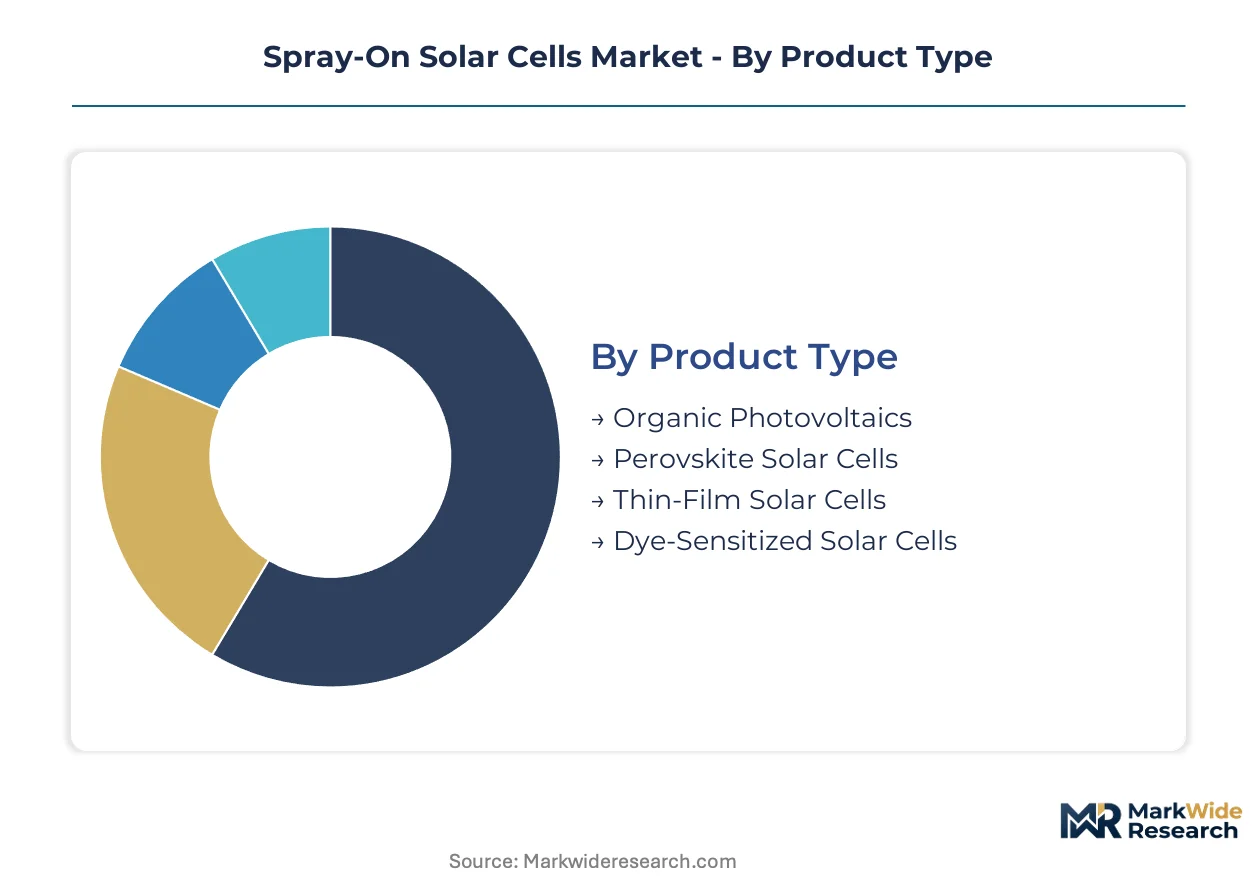
Spray-on solar cell deployment varies sharply across technology platforms and end-use environments. Product chemistry determines efficiency ceilings and regulatory pathways, while fabrication method shapes capital requirements and geographic manufacturing feasibility.
Product Type:
Mature silicon alternatives coexist with emerging solution-processed chemistries, each occupying distinct performance-cost niches.
- Perovskite Solar Cells:Lead-halide or tin-based absorber layers deposited from solution achieve power conversion efficiencies exceeding twenty-five percent in laboratory tandem configurations. Germany's building-integrated procurement and Japan's METI certification pathway concentrate near-term demand for this chemistry.
- Organic Photovoltaics:Carbon-based donor-acceptor blends processed at low temperature excel in indoor and diffuse-light harvesting where silicon underperforms. Heliatek's vacuum-deposited small-molecule films already serve architectural glass installations across France and the Netherlands.
- Thin-Film Solar Cells:Cadmium telluride and copper indium gallium selenide layers sputtered onto flexible metal foils provide proven durability for commercial rooftop retrofits.
- Dye-Sensitized Solar Cells:Ruthenium-complex sensitizers on titanium dioxide nanoparticles offer transparency-tunable aesthetics for facade integration in Australian urban construction.
Perovskite formulations handle the majority of throughput; organic photovoltaics is the fastest mover on share.
End User:
Customer type segmentation tracks structural load tolerance and aesthetic integration requirements across built environments.
- Commercial:Office towers and retail structures in Germany, France, and Italy drive procurement under EU Green Deal renovation mandates, prioritizing lightweight films that avoid roof reinforcement. Building-integrated specifications now enter schematic design phases rather than post-hoc additions.
- Residential:Australian distributed generation retrofits favor spray-on overlays for aging rooftops unable to bear conventional panel ballast, with residential renovation rates creating sustained demand pull.
- Industrial:Warehouse and manufacturing facilities with expansive flat roofs deploy roll-to-roll coated sheets for behind-the-meter generation, though amorphous silicon competition limits pricing power.
- Transportation:Electric vehicle curved surface applications in Japan and Germany demand conformal photovoltaics for roof and hood integration that rigid crystalline cells cannot satisfy.
Commercial procurement absorbs the largest volume; residential retrofit is expanding most quickly.
Application:
Use case segmentation reveals where substrate flexibility creates irreplaceable value versus incremental improvement.
- Building-Integrated:Architectural glass, metal roofing, and facade cladding in German and Japanese markets merge generation with envelope functions. Front-loaded design-phase selection now favors thin-film products that substitute for conventional construction materials.
- Automotive:Conformal coating of curved EV surfaces requires spray-on deposition methods; Japan's automotive OEMs pilot perovskite integration for supplemental cabin power.
- Portable Devices:Flexible charging solutions for outdoor and emergency use exploit lightweight roll-to-roll output.
- Consumer Electronics:Indoor energy harvesting for IoT sensors leverages organic photovoltaic efficiency under artificial lighting.
Building-integrated deployment dominates throughput; automotive applications are climbing the fastest.
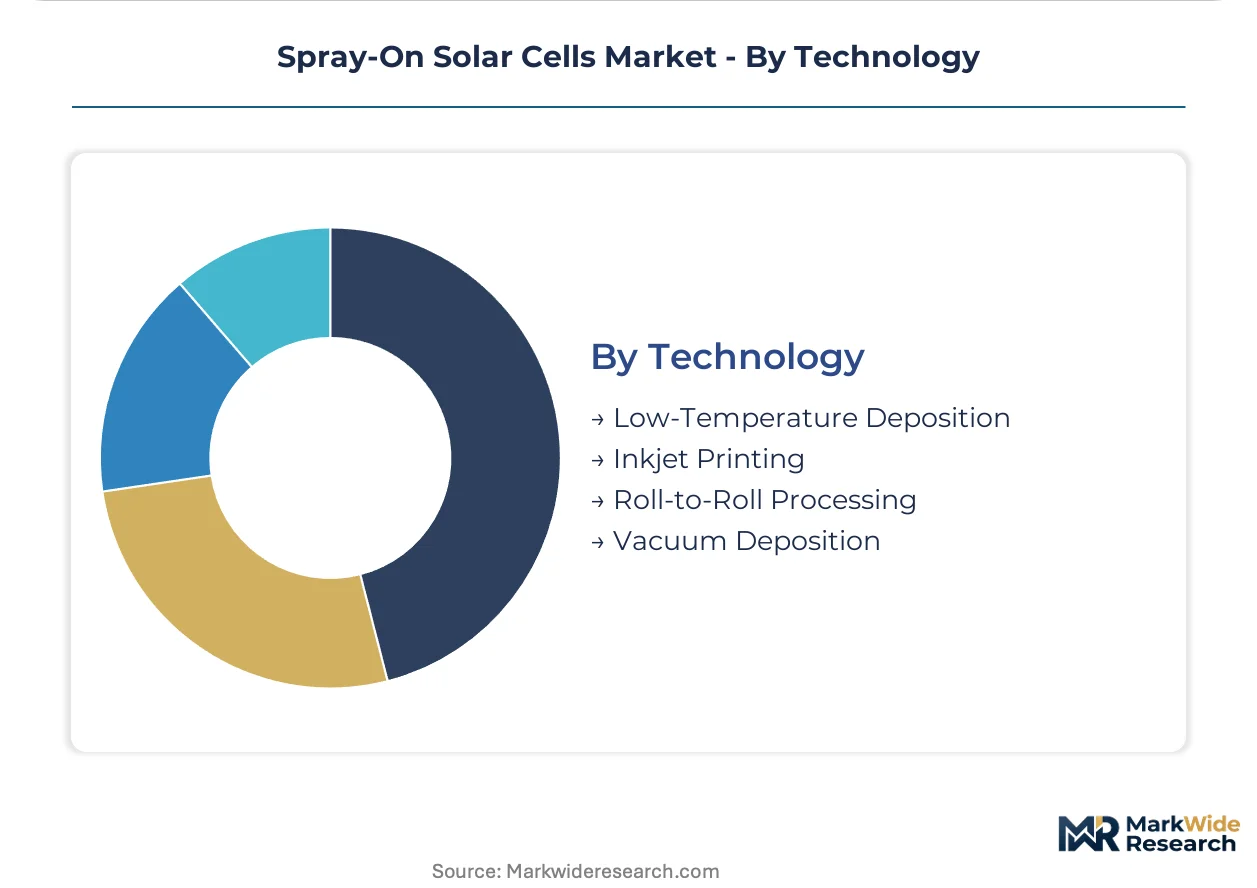
Technology:
Fabrication method determines throughput economics, pattern precision, and the industrial heritage of equipment suppliers.
- Roll-to-Roll Processing:Continuous web coating at speeds exceeding one meter per minute collapses capital intensity thresholds and invites packaging industry players into solar supply chains. Swift Solar leverages this expertise for lightweight module cost advantages.
- Inkjet Printing:Piezoelectric drop-on-demand systems enable precise patterning for consumer electronics integration and architectural customization where pixel-level control justifies slower throughput.
- Low-Temperature Deposition:Solution processing below one hundred fifty degrees celsius permits plastic substrate compatibility for portable and wearable applications.
- Vacuum Deposition:Thermal evaporation of small-molecule organics delivers film uniformity for high-efficiency building-integrated segments, though batch processing limits scale economies.
Roll-to-roll processing carries the bulk of manufacturing volume; inkjet printing is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics for spray-on solar cells currently favor technology-importing markets with strong building renovation mandates. Manufacturing scale concentrates in economies with established roll-to-roll coating infrastructure, while demand pull centers on jurisdictions with aggressive decarbonization timelines for commercial structures.
Germany
Commercial building-integrated photovoltaics procurement drives demand under EU Green Deal renovation requirements. REACH chemical registration governs perovskite precursor materials and constrains lead-based formulation distribution. The Rhine-Ruhr metropolitan corridor hosts formulators accelerating cadmium-free composition development to preempt authorization denials.
Japan
Automotive curved surface integration for electric vehicles creates conformal photovoltaics demand that rigid silicon cannot satisfy. METI oversees photovoltaic certification protocols determining grid access eligibility for novel thin-film products. The Kansai region around Osaka anchors pilot production for perovskite layers targeting building-integrated deployment.
Australia
Residential rooftop renovation rates generate sustained demand for lightweight overlay products avoiding structural reinforcement. The country's national building energy efficiency standards create procurement pull for integrated renewable surfaces. New South Wales and Victoria concentrate distributed generation retrofit activity among aging housing stock.
United States
Research-stage perovskite development receives federal support through the Inflation Reduction Act's advanced manufacturing tax credits. EPA chemical oversight applies to solvent formulations used in spray deposition processes. The San Francisco Bay Area and Boston metropolitan clusters host venture-backed ventures advancing tandem cell architectures.
France
Commercial new-build and deep retrofit segments prioritize aesthetic integration of thin-film products merging with envelope functions. EU Green Deal building performance standards create direct procurement pathways for integrated renewable surfaces. The Île-de-France region around Paris concentrates architectural specification activity during schematic design phases.
Spray-On Solar Cells Market Competitive Landscape
On the supply side, the industry is fragmenting across distinct technology platforms rather than consolidating around a single chemistry. Roll-to-roll coating specialists, vacuum deposition houses, and inkjet printing integrators occupy parallel competitive lanes with limited overlap. Three strategic archetypes dominate: perovskite tandem developers, organic photovoltaic specialists, and building-integrated facade solution providers. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms secure encapsulation material supply and coating line access.
Among perovskite-focused developers, Oxford PV and Swift Solar exemplify the tandem architecture and roll-to-roll coating archetypes respectively. Heliatek occupies a position within the organic photovoltaic specialist tier, representing vacuum-deposited small-molecule approaches for architectural applications. These three entities anchor distinct competitive vectors without overlapping core process technologies.
| Leading Market Players |
|---|
| Swift Solar |
| Nanoco Technologies |
| Oxford PV |
| Tesla |
| Nanosolar |
| Heliatek |
| SolarWindow Technologies |
| GreatCell Energy |
| Saule Technologies |
| Others |
Value Network & Pricing Analysis
Roll-to-roll coating line undercapacity in Japan is driving equipment lead-time extensions and selective supplier prioritization, compressing margins for new entrants while rewarding incumbents with locked-in capacity contracts. This utilization squeeze simultaneously elevates upfront capital requirements and shifts pricing power toward established formulators with secured production slots.
Pricing Analysis
Perovskite-to-organic photovoltaic pricing gaps currently separate laboratory-validated tandem cells from commercial organic films by roughly three performance tiers. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with METI-certified Japanese modules commanding substantial premiums over uncertified alternatives. Cost compression in standard-tier roll-to-roll output is intensifying because packaging industry entrants are repurposing existing coating infrastructure. Commercial building-integrated procurement teams exhibit the lowest price sensitivity due to EU Green Deal mandate compliance deadlines, while residential Australian retrofit buyers remain highly elastic.
Supply Chain Analysis
Export control regimes restricting advanced coating equipment and precursor synthesis technology are fragmenting equipment supplier relationships between Japanese, German, and South Korean vendors. High-barrier polymer film supply concentrates in Japan and South Korea, while perovskite precursor refinement anchors in Germany and China. The supply chain draws from methylammonium iodide salts, lead or tin halides, and polar aprotic solvents as critical inputs. Single-source vulnerability around Japanese encapsulation film suppliers creates structural risk for European formulators. Distribution runs through building materials distributors and specialized photovoltaic integrators rather than conventional solar panel channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spray-on solar cells face substitution pressure from conventional silicon modules in rooftop applications where structural load tolerance permits rigid installation, forcing differentiation through building-integrated and conformal surface deployment.
For Market Incumbents: Build formulation IP moats around lead-reduced and cadmium-free perovskite compositions to preempt REACH authorization denials. Secure long-term encapsulation film supply agreements with Japanese and Korean specialty chemical suppliers before capacity allocation tightens further. Expand roll-to-roll coating capacity in the Rhine-Ruhr corridor to capture EU Green Deal procurement pull. For New Entrants and Emerging Players: Pursue Australian residential retrofit segments where lightweight overlay demand outpaces incumbent supply capacity and structural reinforcement avoidance creates irreplaceable value. Target building-integrated facade specification during schematic design phases in French and Dutch commercial new-build markets. Deploy inkjet printing capabilities for architectural customization as a differentiated go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among building-integrated facade solution providers with multi-year maintenance contracts and performance guarantees. Long-term viability hinges on stability validation completion and certification pathway navigation across METI and emerging IEC protocols. Monitor perovskite tandem cell efficiency announcements as the critical inflection signal for manufacturing scale commitment.| Strategic Initiative | Industry Significance |
|---|---|
| Perovskite Stability Validation Program | IEC protocol alignment accelerates METI grid access eligibility for novel formulations. |
| Encapsulation Film Supply Agreement | Japanese and Korean supplier commitments mitigate moisture protection input vulnerability. |
| Roll-to-Roll Coating Scale-Up | Rhine-Ruhr capacity expansion captures EU Green Deal commercial renovation procurement. |
| Lead-Reduced Formulation Development | REACH preemption secures European market access before authorization timelines extend. |
| Automotive OEM Pilot Partnership | Japan METI certification pathway streamlines curved EV surface integration deployment. |
Research Methodology
The analysis maps perovskite ink formulation, organic photovoltaic deposition, roll-to-roll processing equipment, and building-integrated system integration, each validated through photovoltaic R&D directors, architectural specification consultants, coating line engineers, and building materials procurement managers. Primary interview findings triangulate against METI certification databases, ECHA REACH registration filings, EU Green Deal implementation progress reports, and Australian Clean Energy Council installation statistics. Bottom-up capacity estimates and top-down demand projections reconcile through segment-level cross-validation.
Assumptions held fixed include current REACH authorization timelines for lead-based precursors and existing METI thin-film certification protocols, while perovskite efficiency trajectories and roll-to-roll coating speed improvements were varied across sensitivity scenarios. The forecast framework models technology platform, end-user segment, application environment, and fabrication method as core segmentation dimensions. CAGRs derive from installed capacity build-out curves and procurement mandate compliance schedules. Industry-specific inputs include building renovation rate projections under EU Green Deal and Australian distributed generation retrofit penetration assumptions.
Sensitivities concentrate around perovskite stability test protocol finalization, REACH authorization decisions on methylammonium lead iodide variants, and Japanese encapsulation film capacity allocation shifts. Forecasts reflect these assumptions without claiming predictive certainty. Material shifts in IEC standard crystallization timelines or EU chemical authorization scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Panel Laminator Market
Solar Power Systems
Solar Skin Market
Solar Power Systems
Global EV Solar Modules Market
Solar Power Systems
India Solar Inverter Market
Solar Power Systems
Israel Solar Energy Market
Solar Power Systems
Europe Bifacial Solar Market
Solar Power Systems
Italy Solar Energy Market
Solar Power Systems
Philippines Solar Energy Market
Solar Power Systems
Solar Photovoltaics Wafer Market
Solar Power Systems
France Distributed Solar Power Generation Market
Solar Power Systems
India Solar Tracker Market
Solar Power Systems
Europe Solar Blanket Market
Solar Power Systems
Smart Solar Tracker Market
Solar Power Systems
United States Fixed-Tilt Solar PV Market
Solar Power Systems
Europe Solar Concentrator Market
Solar Power Systems
Turkey Solar Energy Market