
 Clear Brine Fluids Market | 2026-2036
Clear Brine Fluids Market Size, Share, and Industry Trends Forecast 2026-2036
Clear Brine Fluids Market Analysis
Deepwater exploration is realigning the Clear Brine Fluids Market toward higher-performance formulations. Albemarle Corporation leverages its bromine derivatives portfolio to dominate specialty brine supply for Gulf of Mexico operators. Halliburton Company sustains integrated service bundles that combine clear brine fluids with completion hardware. ICL Group Ltd. anchors European supply through Dead Sea-sourced magnesium and potassium chloride operations.
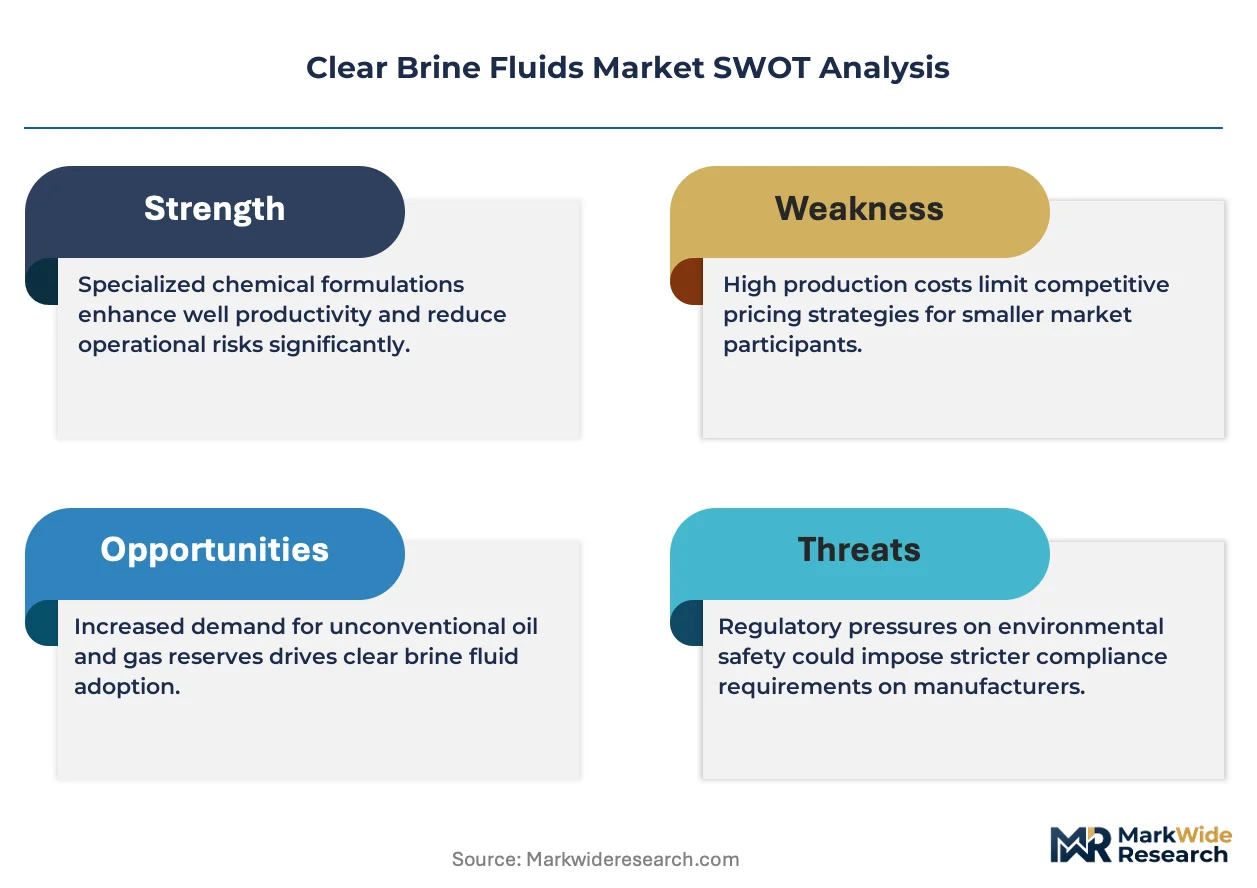
Clear brine fluids are aqueous solutions of single or mixed halide salts, formulated to densities between 8.4 and 19.2 pounds per gallon, that maintain crystallization clarity to prevent formation damage during well intervention. Their primary purpose is to balance reservoir pressure while eliminating solids that could plug permeable zones. Calcium chloride occupies the largest volume position in drilling fluid applications due to cost accessibility and established supply chains. Sodium bromide leads margin pools in completion fluids for high-temperature HPHT wells where thermal stability commands premium pricing. Potassium chloride competes in workover fluids across mature North American shale basins where clay swelling inhibition determines product selection.
EPA effluent limitations under the Clean Water Act shape formulation choices for offshore discharge in United States waters. MEE technical standards in China restrict chloride discharge concentrations from chemical processing facilities. ISO 13500 drilling fluid standards govern product quality benchmarks for international operators. Stakeholders must monitor regulatory divergence between jurisdictions to align product registration strategies with evolving environmental compliance thresholds.
Market Dynamics
Deepwater drilling economics are compressing the acceptable performance-cost window for clear brine fluids, forcing formulators to deliver HPHT stability at calcium chloride price points. Operators now specify single-salt systems that eliminate blend complexity without sacrificing density range.
Growth Catalysts
- Pre-salt development in Brazil:Petrobras-led campaigns in the Santos Basin consume high-density completion fluids for wells exceeding 6,000 meters true vertical depth.
- EPA effluent limitations:The Clean Water Act's stricter chloride discharge thresholds in the Gulf of Mexico are accelerating adoption of closed-loop brine recovery systems.
- Thermally stable bromide chemistry:Sodium bromide formulations now withstand bottom-hole temperatures above 400°F, displacing zinc bromide in ultra-HPHT completions.
Market Restraints
- Bromine supply concentration:Dead Sea extraction operations and Arkansas brine reserves control 80% of global elemental bromine feedstock.
- Calcium chloride price volatility:Chlor-alkali capacity fluctuations and road de-icing demand spikes create input cost instability.
- MEE wastewater standards in China:The Ministry of Ecology and Environment's chloride concentration limits restrict halide-based fluid discharge from chemical processing facilities.
Strategic Opportunities
- West African deepwater:Senegal-Mauritania basin developments lack established brine supply infrastructure, creating first-mover positioning for integrated service providers.
- Closed-loop filtration integration:Brine recovery systems paired with solids control equipment reduce fluid loss ratios below 5% in extended-reach drilling.
- ISO 13500 certification expansion:Quality standard harmonization opens procurement pathways for Dead Sea-sourced potassium chloride into Latin American national oil companies.
Industry Challenges
- HPHT fluid engineering talent scarcity:Formulation chemists with simultaneous expertise in crystallization kinetics and reservoir compatibility command premium compensation.
- Multi-jurisdiction product registration:Divergent environmental release permits between the US EPA, Brazil's IBAMA, and Norway's PSA extend commercialization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clear Brine Fluids Market |
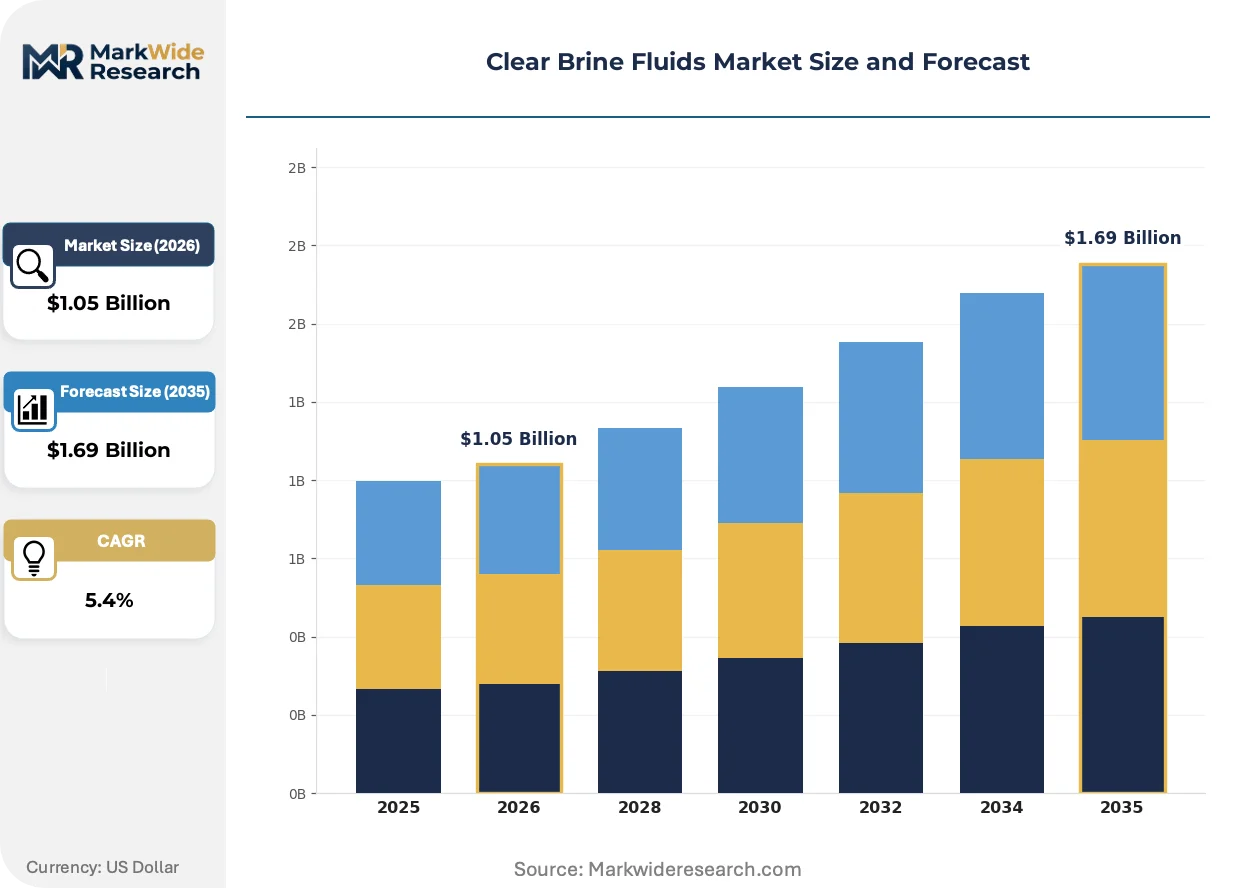
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.69 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Chloride, Sodium Bromide, Potassium Chloride, Magnesium Chloride End User: Oil & Gas, Water Treatment, Chemical Processing, Mining Grade: Industrial Grade, Food Grade, Laboratory Grade, Pharmaceutical Grade Application: Drilling Fluids, Completion Fluids, Workover Fluids, Waste Management |
| Companies Covered | Newpark Resources, Inc., Albemarle Corporation, Halliburton Company, ICL Group Ltd., Clements Fluids, Schlumberger Limited, Tetra Technologies, Inc., Solvay SA, Baker Hughes Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clear Brine Fluids Market Emerging Trajectories
Digital density monitoring and real-time crystallization prediction are compressing the feedback loop between laboratory formulation and field deployment. These capabilities are reshaping how operators specify and contract brine fluid supply.
Microencapsulated corrosion inhibitors are converging with high-density brine matrices to deliver sustained protection in CO2-rich reservoirs. Gulf of Mexico operators are piloting these systems in high-pressure, high-temperature wells where conventional batch treatments fail. The technology is converging with automated injection skids to reduce rig-site chemical handling.
REACH authorization requirements for zinc compounds are restricting zinc bromide use in European offshore waters. Formulators are substituting cesium formate and sodium bromide blends to maintain density without SVHC classification. North Sea completions are driving fastest adoption of these alternative chemistries.
Integrated service contracting is consolidating procurement decisions under drilling contractors rather than operator direct purchase. Shelf Drilling and Valaris are bundling clear brine fluids with managed pressure drilling packages in the Mediterranean and Southeast Asia. This shift compresses standalone chemical supplier margins while expanding volume commitments.
Clear Brine Fluids Market Segmentation
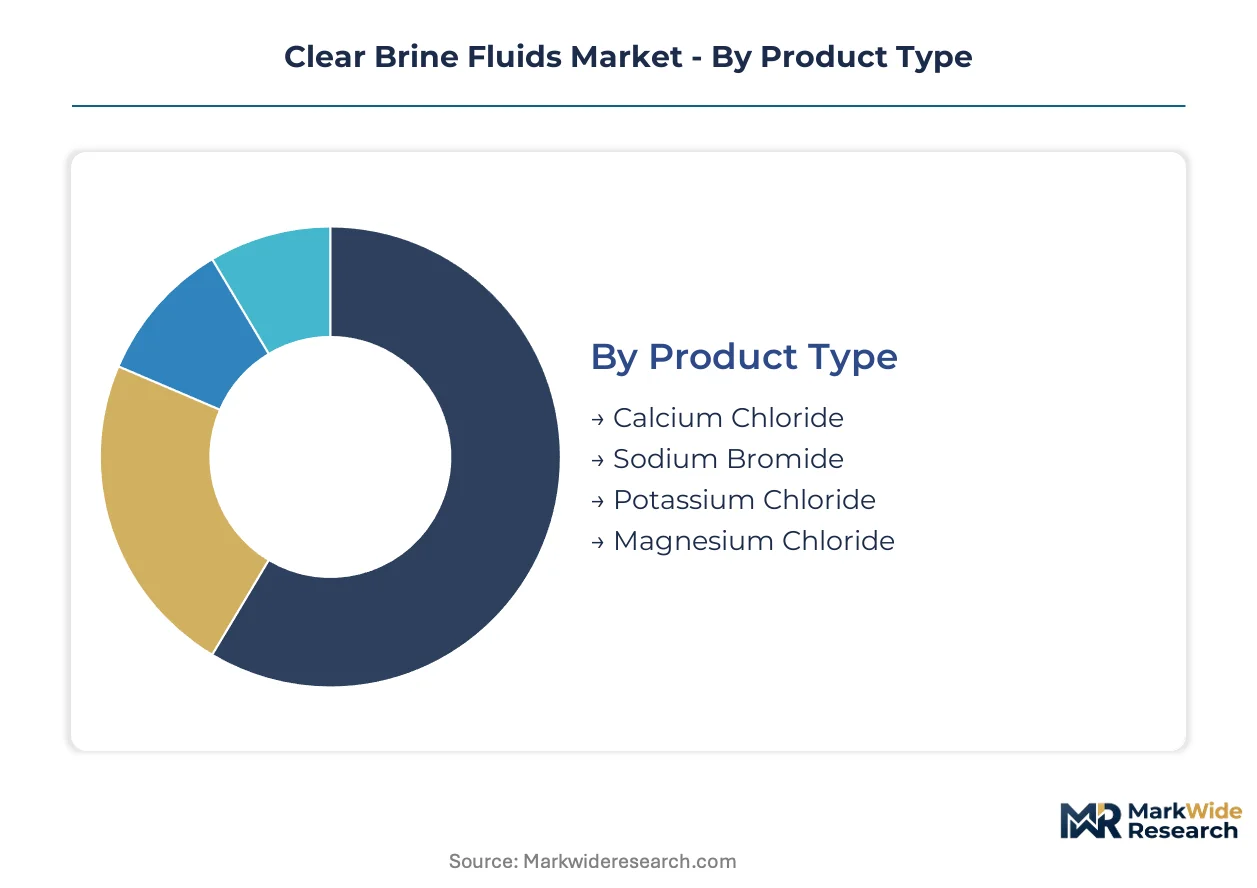
Clear brine fluids serve distinct operational requirements across density ranges, thermal stability thresholds, and regulatory jurisdictions. Product selection hinges on crystallization temperature, formation compatibility, and discharge permitting rather than commodity pricing alone.
Product Type:
Upgrade cycles in deepwater drilling are displacing lower-density formulations with thermally stable alternatives capable of withstanding HPHT bottom-hole conditions.
- Calcium Chloride:Aqueous solutions deliver densities to 11.6 pounds per gallon through cost-effective chlor-alkali supply chains. Onshore Permian Basin operators specify calcium chloride for routine drilling where thermal demands stay below 300°F and formation sensitivity permits halide exposure.
- Sodium Bromide:Premium-priced formulations achieve 12.5 pounds per gallon with crystallization points below 0°F, enabling ultra-HPHT completions where bottom-hole temperatures exceed 400°F. Gulf of Mexico pre-salt campaigns specify sodium bromide to eliminate zinc bromide under EPA discharge scrutiny.
- Potassium Chloride:Clay-stabilizing chemistry dominates workover applications in mature North American shale basins where swelling inhibition determines product selection.
- Magnesium Chloride:Dead Sea-sourced supply anchors European completion fluid demand with intermediate density positioning between calcium and bromide systems.
Calcium chloride sits at the top of the volume ranking, with sodium bromide climbing the fastest as HPHT well counts expand.
End User:
Customer procurement sophistication varies sharply across sectors, with oilfield service companies demanding integrated supply contracts while industrial buyers prioritize spot-market flexibility.
- Oil & Gas:Integrated operators and drilling contractors specify clear brine fluids through multi-year framework agreements tied to completion hardware bundles. Brazil's pre-salt developments consume high-density completion fluids for wells exceeding 6,000 meters true vertical depth.
- Water Treatment:Municipal and industrial desalination facilities employ brine solutions for membrane cleaning and ion exchange regeneration, with procurement driven by chloride discharge permits under the Clean Water Act.
- Chemical Processing:Chlor-alkali and bromine derivative manufacturers utilize clear brine fluids as process feedstock and heat transfer media, subject to MEE wastewater standards in China.
- Mining:Solution mining and ore flotation applications specify density-controlled brines for selective mineral separation, with demand concentrated in potash extraction operations.
Oil & Gas commands the dominant revenue share, while Water Treatment applications are gaining share fastest as membrane desalination capacity expands.
Grade:
Certification tiers separate commodity supply from specialty formulations commanding substantial price premiums in regulated applications.
- Industrial Grade:Bulk supply for drilling and completion operations where ISO 13500 quality benchmarks govern product acceptance without food-contact or pharmaceutical purity requirements.
- Food Grade:Purified formulations meeting FDA food additive specifications for brine solutions used in food processing and packaging applications.
- Laboratory Grade:Controlled-impurity products for analytical and research applications requiring documented trace metal content and batch certification.
- Pharmaceutical Grade:Highest-purity supply subject to USP or EP monograph compliance for medical device manufacturing and parenteral preparation.
Industrial Grade maintains volume leadership, with Pharmaceutical Grade expanding most quickly as medical device manufacturing quality requirements tighten.
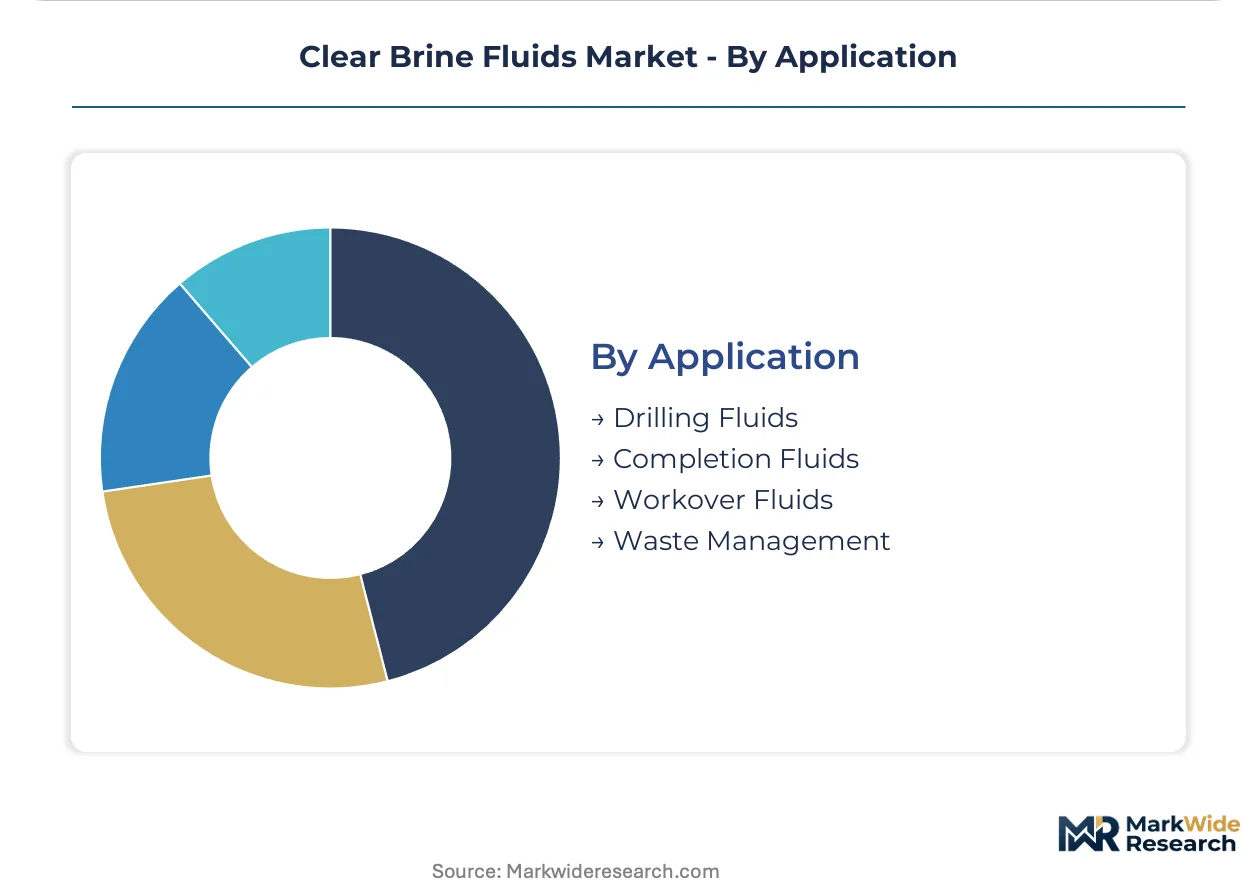
Application:
Operational phase determines fluid specification, with drilling prioritizing cost efficiency while completion and workover demand premium thermal stability.
- Drilling Fluids:Density-controlled systems balance formation pressure during bit penetration, with calcium chloride dominating onshore operations and bromide blends specified for high-temperature intervals.
- Completion Fluids:Solids-free clarity prevents permanent formation damage during perforation and gravel pack operations, commanding the highest price points in the product spectrum.
- Workover Fluids:Remedial well intervention employs potassium chloride for clay stabilization in mature producing zones requiring permeability restoration.
- Waste Management:Brine recovery and solids control systems reduce fluid loss ratios below 5% in extended-reach drilling, with closed-loop filtration integration accelerating adoption.
Drilling Fluids holds the volume position, while Completion Fluids demonstrate the steepest expansion trajectory as deepwater well complexity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf of Mexico basin anchors global clear brine fluids consumption through deepwater drilling intensity and HPHT well complexity. Brazil's pre-salt developments and China's chemical processing expansion reshape regional supply priorities.
United States
EPA effluent limitations under the Clean Water Act drive closed-loop brine recovery adoption across Gulf of Mexico offshore operations. Operators specify thermally stable sodium bromide formulations to meet discharge thresholds while maintaining density performance. Houston anchors the largest concentration of completion fluid service providers and integrated supply networks.
Brazil
Petrobras-led pre-salt campaigns in the Santos Basin consume high-density completion fluids for wells exceeding 6,000 meters true vertical depth. IBAMA environmental licensing requirements shape formulation registration timelines for offshore discharge. Macaé serves as the primary logistics hub for brine fluid staging and supply vessel operations.
China
MEE wastewater standards restrict chloride discharge concentrations from chemical processing facilities employing halide-based fluids. Domestic chlor-alkali capacity fluctuations create input cost volatility for calcium chloride production. Shandong Province hosts the largest concentration of bromine derivative manufacturing and brine processing infrastructure.
Norway
PSA regulatory frameworks and REACH authorization requirements accelerate substitution of zinc bromide with cesium formate blends in North Sea completions. Operators prioritize thermally stable alternatives to avoid SVHC classification. Stavanger anchors the regional supply chain for HPHT completion fluid engineering and technical services.
United Arab Emirates
ADNOC offshore expansion programs specify clear brine fluids for high-pressure carbonate formations in the Upper Zakum and Umm Shaif fields. Local content requirements under In-Country Value programs influence procurement decisions for drilling contractors. Abu Dhabi hosts integrated supply hubs serving Arabian Gulf deepwater developments.
Clear Brine Fluids Market Vendor Landscape
Integrated service bundling dominates the current landscape as drilling contractors consolidate procurement decisions under single-source contracts. The vendor base organizes around three tiers: global oilfield service conglomerates with captive chemical supply, specialty chemical producers with Dead Sea or Arkansas bromine access, and regional blending operations serving spot-market demand. Strategic archetypes include backward-integrated bromine miners, formulation-technology licensors, and logistics-heavy service bundlers. Capacity expansion in West African supply infrastructure and M&A activity among North American regional blenders represent the dominant competitive vectors.
Among integrated service providers, Halliburton Company and Schlumberger Limited exemplify the bundling archetype that combines clear brine fluids with completion hardware and managed pressure drilling systems. Albemarle Corporation anchors the specialty chemical tier through its Arkansas bromine derivatives portfolio and Gulf of Mexico operator relationships. These three entities occupy distinct competitive positions: service integration at scale, upstream chemical feedstock control, and regional logistics dominance respectively.
| Leading Market Players |
|---|
| Newpark Resources, Inc. |
| Albemarle Corporation |
| Halliburton Company |
| ICL Group Ltd. |
| Clements Fluids |
| Schlumberger Limited |
| Tetra Technologies, Inc. |
| Solvay SA |
| Baker Hughes Company |
| Others |
Supply Flow & Price Mechanics
Backward integration into bromine feedstock anchors pricing power for Dead Sea and Arkansas operators, while spot-market calcium chloride suppliers absorb volatility from chlor-alkali capacity swings. This structural divide separates premium sodium bromide margins from commodity-grade calcium chloride compression.
Pricing Analysis
Input-cost pass-through from elemental bromine and chlor-alkali caustic soda drives tiered pricing stratification across Industrial, Food, and Pharmaceutical grades. Price differentiation hinges on ISO 13500 certification attainment and volume-scale contracting with integrated drilling contractors. Cost compression in calcium chloride formulations is intensifying because road de-icing demand spikes absorb available chlor-alkali capacity. National oil companies exhibit lowest price sensitivity due to operational risk premiums, while regional blending operations face acute margin pressure.
Supply Chain Analysis
ISO 13500 certification gating restricts qualified supply to established producers with documented batch traceability and crystallization temperature validation. Geographic supply concentrates in Israel, the United States, and China. Raw material dependencies draw from Dead Sea bromine reserves, Arkansas brine fields, and Shandong Province chlor-alkali output. Single-source vulnerability concentrates in Dead Sea extraction operations controlling majority global bromine feedstock. Distribution runs through Houston and Macaé supply hubs serving Gulf of Mexico and Brazil deepwater corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clear brine fluids function as a stable compounder anchored by irreversible deepwater drilling complexity that mandates thermally stable formulation demand regardless of commodity cycle position.
For Market Incumbents: To counter integrated service bundling by drilling contractors, Albemarle and ICL Group should deepen captive bromine supply control through Dead Sea capacity optimization and secure multi-year offtake agreements with Petrobras. Certification investment in ISO 13500 expansion for Latin American national oil companies preserves margin position against regional blenders. For New Entrants and Emerging Players: Begin with West African supply infrastructure gaps, specifically Senegal-Mauritania basin developments lacking established brine staging capabilities. Target closed-loop filtration integration partnerships with extended-reach drilling contractors as the most penetrable entry vector. A technical service-led go-to-market approach bypasses capital-intensive backward integration requirements. For Investors and Strategic Acquirers: Roll-up economics work for regional North American blending operations because fragmented spot-market supply lacks scale to resist integrated service bundling trends. Target mid-cap blenders with Gulf of Mexico logistics access and existing EPA discharge permitting. Watch HPHT well count trajectories in Brazil and West Africa as inflection indicators for sodium bromide demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bromine Feedstock | Captive Dead Sea or Arkansas reserves insulate margin from elemental bromine price volatility. |
| ISO 13500 Certification Expansion | Quality standard harmonization opens procurement pathways for Dead Sea potassium chloride into Latin American NOCs. |
| Closed-Loop Filtration Integration | Brine recovery systems paired with solids control equipment reduce fluid loss ratios below 5% in extended-reach drilling. |
| West African Supply Infrastructure Buildout | First-mover positioning in Senegal-Mauritania basin developments captures pre-salt analog demand growth. |
| Long-Term Framework Agreements with Drilling Contractors | Shelf Drilling and Valaris bundling patterns favor suppliers with integrated service capabilities over standalone chemical vendors. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with completion fluid engineers, drilling contractor procurement leads, bromine derivatives plant managers, and regulatory affairs specialists at EPA and IBAMA with secondary validation from SEC 10-K filings, customs and trade data, and ISO certification registries. Bottom-up volume modeling triangulated against top-down industry spend estimates.
Comparable-period anchoring linked historical consumption patterns across the projection horizon to derive segment-specific expansion rates. Segmentation dimensions modeled include product type density tier, end-use operational phase, grade certification level, and regional regulatory cluster. CAGRs were computed from annualized growth trajectory analysis. Industry-specific forecast inputs incorporated HPHT well count projections and chlor-alkali capacity utilization rates.
Several conditions sit outside the modeled scope, including unannounced regulatory amendments to MEE wastewater standards, abrupt Dead Sea extraction disruptions, and accelerated zinc bromide substitution timelines. Forecasts reflect assumptions about stable EPA effluent limitation enforcement and continued Petrobras pre-salt capital commitment. A model refresh is warranted upon material change in Gulf of Mexico drilling permit issuance velocity or Brazil IBAMA licensing timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Deepwater and Ultra-Deepwater Exploration and Production Market
Oil & Gas
Subsea Multiphase Flowmeter Market
Oil & Gas
Malaysia Oilfield Services Market
Oil & Gas
Oil Well Cement Market
Oil & Gas
Malaysia Oil and Gas Midstream Market
Oil & Gas
Proppant Market
Oil & Gas
Pipeline Pigging Services Market
Oil & Gas
Workover Rigs Market
Oil & Gas
Ecuador Oil and Gas Midstream Market
Oil & Gas
Oil and Gas Digital Rock Analysis Market
Oil & Gas
Latin America Drilling Fluids Market
Oil & Gas
LNG Bunkering Market
Oil & Gas
Desalter Market
Oil & Gas
Fracking Fluid Market
Oil & Gas
Offshore Drilling Fluid Market
Oil & Gas
Well Completion Market