
 APAC Solar Micro Inverters Market | 2026-2036
APAC Solar Micro Inverters Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Solar Micro Inverters Market Outlook
Commercial and industrial rooftop solar is recalibrating the end-use mix across APAC, pulling demand away from pure residential deployments as factories and logistics parks seek behind-the-meter generation. Enphase Energy leverages its module-level electronics expertise to anchor premium positioning in Australia's mature distributed solar segment. SMA Solar Technology competes through three-phase system specialization for larger commercial arrays across South Korea and Japan.
APAC solar micro inverters are compact DC-to-AC power conversion devices rated typically between 250W and 2,000W, designed for installation at individual photovoltaic module level to maximize energy harvest through independent maximum power point tracking and eliminate single-point string failure. Grid-tied configurations dominate current shipment volumes across the region, while hybrid architectures integrating battery backup represent the fastest-growing product category as storage attachment rates climb. Single-phase technology leads residential penetration in established markets, whereas three-phase systems command stronger margin pools in commercial and utility-scale distributed projects.
Japan's METI enforces grid interconnection standards that mandate anti-islanding protection and reactive power capability, directly shaping micro inverter firmware requirements and certification pathways for equipment suppliers. Australia's Clean Energy Council maintains an approved product list that functions as a de facto market access gate, while India's BIS certification for solar power conditioning units creates compliance barriers for uncertified imports. Stakeholders must monitor how evolving APAC grid codes for distributed energy resources reshape product specification priorities and testing investment requirements.
Market Dynamics
Module-level power electronics adoption across Southeast Asian rooftops is compressing traditional string inverter deployment timelines and forcing suppliers to reconfigure warranty and service architectures around distributed asset management platforms.
Growth Catalysts
- India's PLI scheme for solar manufacturing:Domestic assembly incentives are accelerating local production capacity for power conversion equipment, reducing import dependency for micro inverter components.
- Commercial and industrial rooftop solar:Factories and logistics parks across Vietnam's central provinces are deploying behind-the-meter generation, expanding addressable market beyond residential segments.
- Anti-islanding protection mandates:Japan's METI interconnection standards require reactive power capability and firmware-level grid support functions, creating certified product demand.
Market Restraints
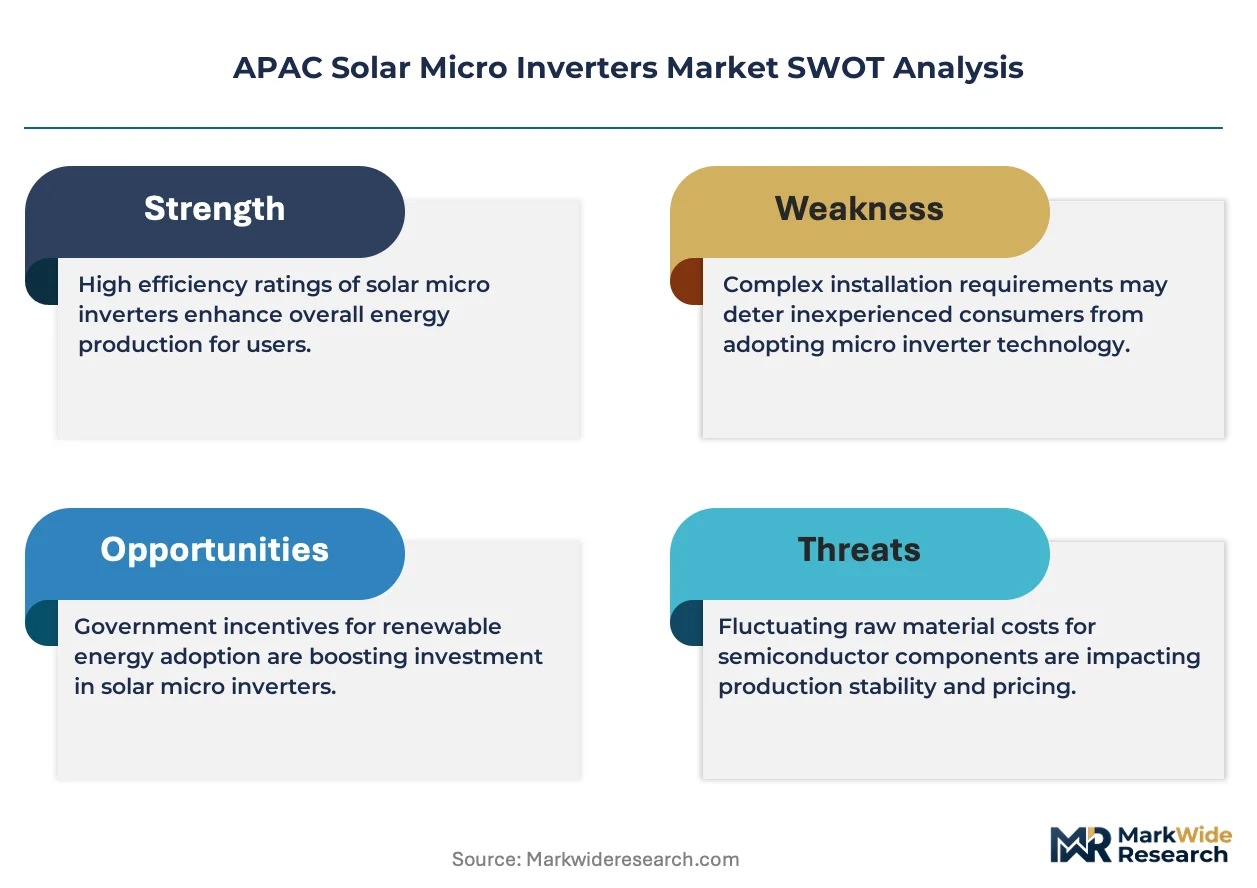
- Semiconductor input cost volatility:Power MOSFET and IGBT supply concentration in East Asian foundries exposes margins to wafer pricing swings and allocation constraints.
- BIS certification barriers:India's mandatory power conditioning unit standards create 12-18 month approval timelines that block uncertified imports from entering distribution channels.
- String inverter substitution:Three-phase string systems with module-level optimizers capture price-sensitive commercial projects in South Korea and Japan.
Strategic Opportunities
- Philippines off-grid electrification:Island communities and remote commercial facilities present unserved demand for hybrid micro inverter architectures integrating battery storage.
- Battery attachment rate expansion:Grid-tied systems are converging with lithium-ion backup units, creating bundled product categories with higher margin profiles.
- Australia Clean Energy Council listing:Approved product list status functions as market access gate for premium residential segments, rewarding early certification investment.
Industry Challenges
- Firmware certification timelines:Japan's METI grid code compliance requires extensive testing protocols that delay product launches by 6-9 months versus other APAC markets.
- Legacy string inverter installed base:Retrofit compatibility constraints limit addressable market in mature rooftop solar markets like Australia and Japan.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Solar Micro Inverters Market |
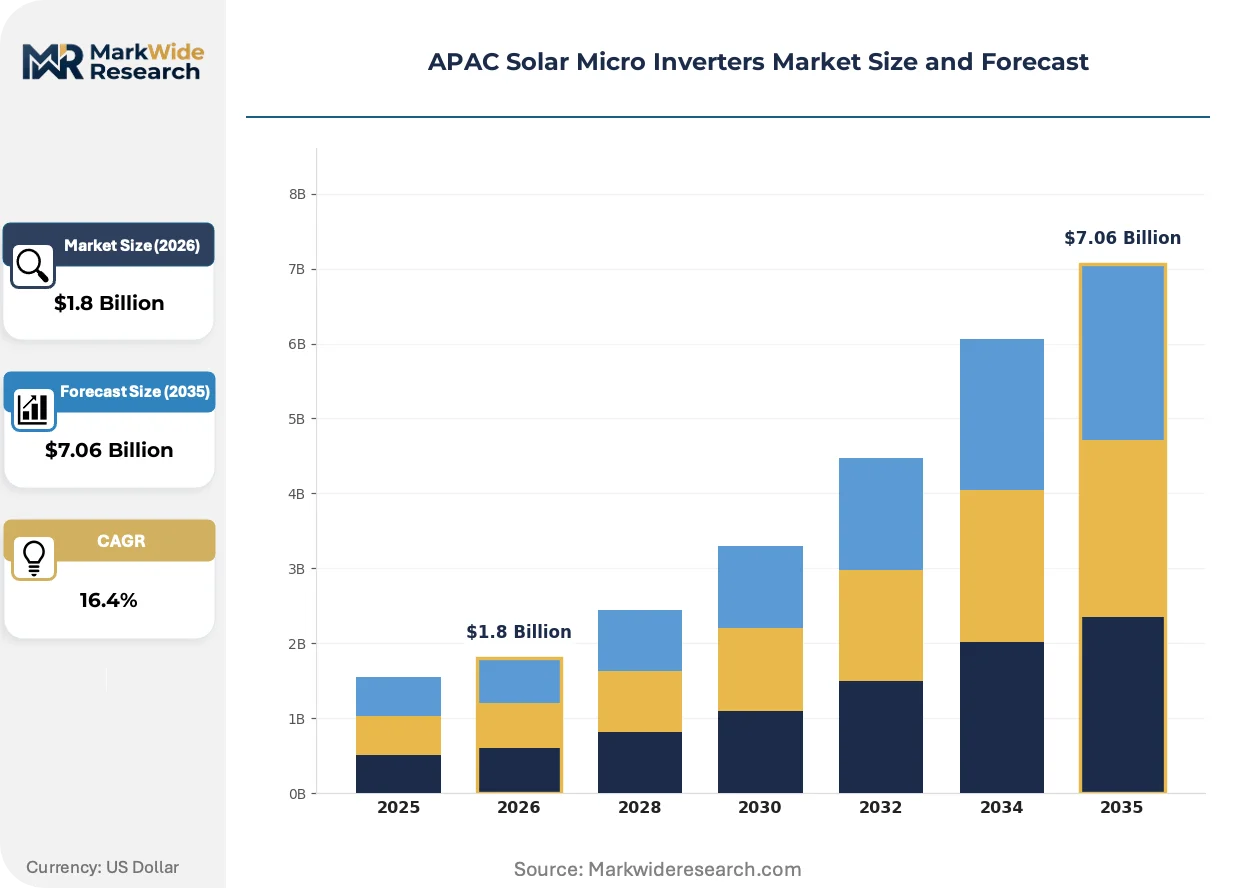
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grid-Tied, Off-Grid, Hybrid, Battery Backup End User: Residential, Commercial, Industrial, Utilities Technology: Single-Phase, Three-Phase, Smart, Conventional Installation Type: Roof Mounted, Ground Mounted, Building Integrated, Portable |
| Companies Covered | Enphase Energy, APsystems, SMA Solar Technology, Hoymiles, Altenergy Power System, Zhejiang Envertech, Darfon Electronics, Sungrow, Deye Inverter, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Solar Micro Inverters Market Strategic Shifts
Power electronics architecture is converging around intelligence at the module level, with firmware-defined functionality replacing hardware-centric designs across residential and commercial deployment scales.
Hybrid micro inverter systems is unifying DC-AC conversion with bidirectional battery charging in single-enclosure designs. Commercial installers across Vietnam and Thailand are specifying these units for C&I rooftops requiring backup resilience. The technology is unifying procurement decisions around storage-ready infrastructure rather than retrofit-later planning.
Australia's Clean Energy Council maintains an approved product list that functions as de facto market access gate for residential solar contractors. Equipment suppliers must submit inverter models for independent testing against AS/NZS standards before listing eligibility. This regulatory mechanism concentrates demand among pre-certified suppliers and compresses sales cycles for approved products.
Direct-to-installer channel strategies are displacing traditional distributor intermediaries in mature APAC markets. Enphase Energy and competitors are building captive installer networks with training certification and lead referral programs. Australia and Japan exhibit the strongest channel consolidation, with top 20 installer groups capturing disproportionate volume share.
APAC Solar Micro Inverters Market Segmentation
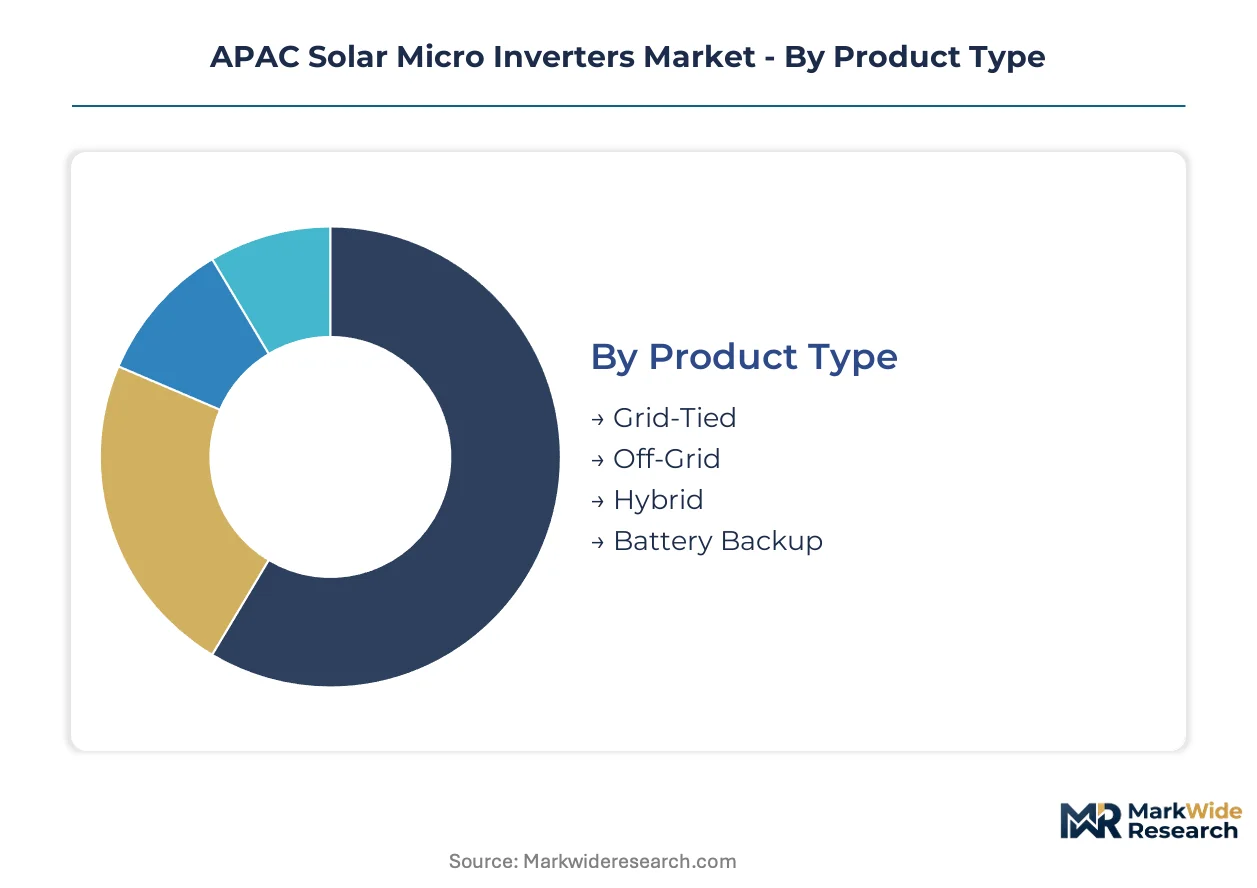
APAC solar micro inverter procurement decisions fragment across certification requirements, installation scale, and grid interconnection protocols. Module-level power electronics suppliers must align product portfolios with distinct regulatory pathways and performance specifications that vary by segment.
Product Type:
Grid-tied configurations require METI anti-islanding certification in Japan and Clean Energy Council listing in Australia, while off-grid and hybrid systems face additional battery integration standards from BIS in India.
- Grid-Tied:DC-to-AC conversion systems without energy storage capability dominate current shipment volumes across Vietnam's central provinces and South Korean commercial rooftops. Australia's approved product list concentrates demand among pre-certified suppliers, compressing sales cycles for compliant units.
- Hybrid:Bidirectional architectures unifying solar conversion with battery charging command premium positioning in Thailand and Philippine C&I installations seeking backup resilience. Firmware-defined functionality enables grid-forming capability that satisfies Japan's reactive power mandates.
- Off-Grid:Standalone systems serve island communities across the Philippines archipelago where utility interconnection remains unavailable.
- Battery Backup:Storage-integrated units target residential segments in Japan and Australia with high grid reliability expectations.
Leading the category by volume: Grid-Tied. Expanding most quickly: Hybrid.
End User:
Residential procurement flows through certified installer networks in mature markets, while commercial and industrial buyers negotiate direct manufacturer relationships for volume scale.
- Commercial:Factories and logistics parks across Vietnam's central provinces deploy behind-the-meter generation with three-phase micro inverter arrays. Procurement patterns favor storage-ready infrastructure over retrofit-later planning.
- Residential:Rooftop installations across Southeast Asia shift from string inverters to module-level electronics as households prioritize independent maximum power point tracking. Australia's top 20 installer groups capture disproportionate volume share through captive networks.
- Industrial:Heavy manufacturing facilities in South Korea specify high-capacity three-phase systems with extended warranty terms.
- Utilities:Distributed generation programs in India and Thailand incorporate micro inverters for grid stability services.
Commercial segment commands strongest margin pools. Residential delivers highest unit volumes.
Technology:
Phase configuration determines firmware complexity and certification scope, with three-phase systems requiring more extensive grid code testing than single-phase alternatives.
- Single-Phase:Compact units rated 250W to 2,000W anchor residential penetration in Australia and Japan's established distributed solar markets. Simpler interconnection standards accelerate deployment timelines relative to three-phase alternatives.
- Three-Phase:Higher-capacity systems address commercial arrays across South Korea and Japan where SMA Solar Technology competes through specialized positioning. Firmware must demonstrate reactive power capability under METI standards.
- Smart:Intelligence-enabled units with remote monitoring and predictive maintenance features.
- Conventional:Basic conversion hardware without network connectivity or advanced diagnostics.
Three-Phase technology captures premium pricing. Smart systems gain share fastest through remote asset management demand.
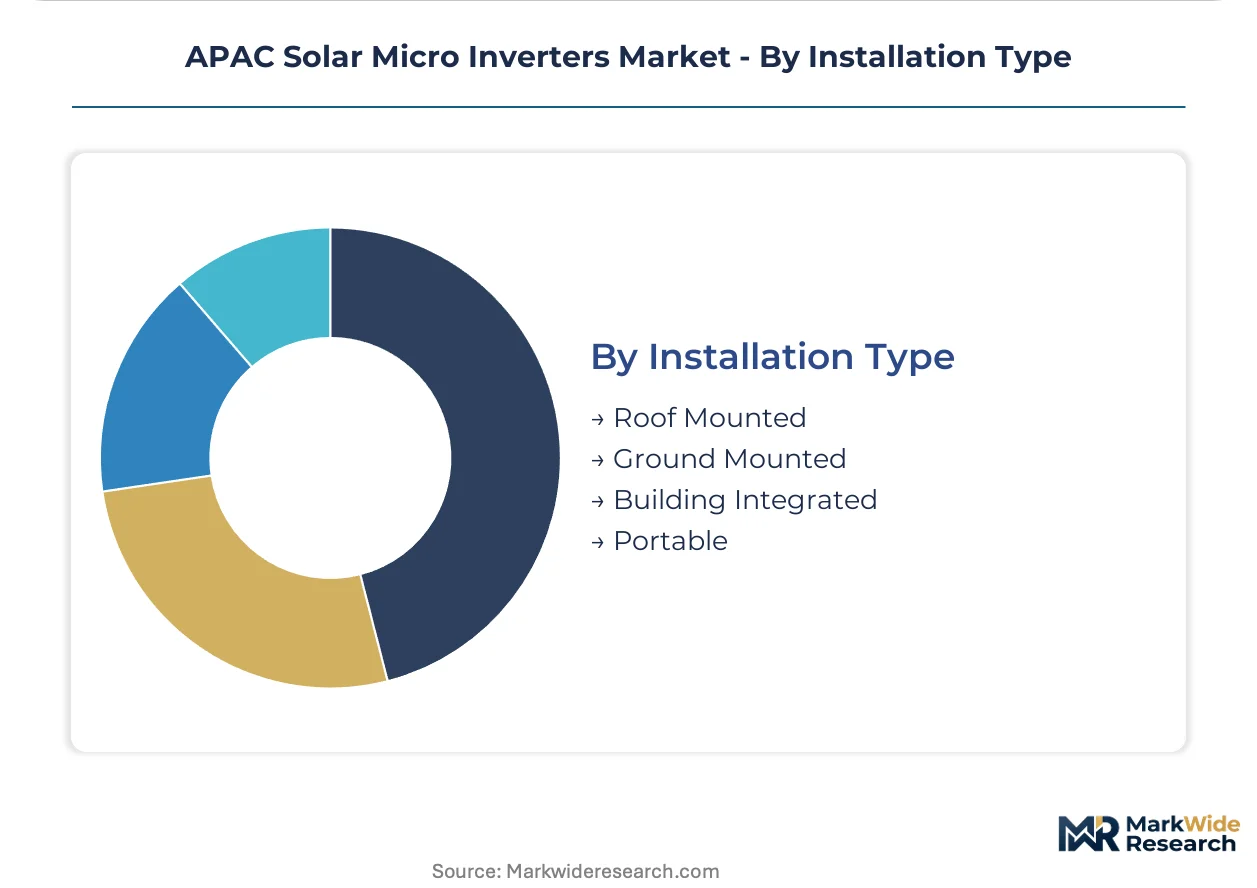
Installation Type:
Mounting configuration shapes enclosure durability requirements and thermal management specifications, with rooftop deployments dominating procurement volumes across tropical climates.
- Roof Mounted:Individual module-level attachment across residential and commercial buildings concentrates demand in Southeast Asian urban centers. Installation labor costs and structural load limits influence unit weight and form factor specifications.
- Ground Mounted:Utility-scale distributed projects in India and Thailand utilize rack-mounted arrays with centralized monitoring infrastructure.
- Building Integrated:Architectural solar facades in Japan and South Korea require specialized form factors.
- Portable:Temporary deployment systems for remote construction and disaster relief applications.
Roof Mounted leads by installed base. Building Integrated shows steepest expansion trajectory from aesthetic and space-constraint drivers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Chinese manufacturing clusters while consumption spreads across diverse national programs. Domestic assembly incentives in India and Vietnam are compressing import dependency for power conversion equipment. Regulatory fragmentation across METI standards, BIS certification, and Clean Energy Council listings shapes distinct market access pathways.
India
Domestic rooftop installations are accelerating module-level power electronics procurement as households shift from string alternatives. The PLI scheme for solar manufacturing is accelerating local assembly capacity for power conversion equipment across Gujarat and Tamil Nadu. Maharashtra's industrial corridors are seeing concentrated C&I deployments with three-phase micro inverter arrays.
Japan
Residential segments in Kanto and Kansai regions prioritize grid-tied systems with firmware-level reactive power capability. METI enforces anti-islanding protection mandates that directly shape micro inverter certification timelines and testing investment requirements. Osaka-based installer networks are consolidating around pre-certified product suppliers.
Australia
New South Wales and Victoria are driving distributed solar volume through captive installer networks with training certification programs. The Clean Energy Council maintains an approved product list that functions as de facto market access gate for residential contractors. Queensland's commercial logistics parks are specifying storage-ready hybrid architectures.
Vietnam
Central provinces including Binh Dinh and Quang Nam are targeting commercial and industrial rooftops through distributed solar programs. Factories and logistics parks are deploying behind-the-meter generation with three-phase micro inverter arrays. Domestic assembly incentives are reducing import dependency for power conversion components.
South Korea
Heavy manufacturing facilities in Busan-Ulsan and Daegu-Gyeongbuk regions specify high-capacity three-phase systems with extended warranty terms. Three-phase string systems with module-level optimizers are capturing price-sensitive commercial projects. Seoul Capital Area residential segments are shifting toward module-level electronics for independent maximum power point tracking.
APAC Solar Micro Inverters Market Competitive Environment
Top-tier vendors anchor premium positioning through certification depth and installer network captivity, while mid-tier specialists compete on price-sensitive commercial volumes. The vendor base stratifies across firmware-defined functionality providers, hardware-centric manufacturers, and storage-integrated system bundlers. Two dominant competitive moves are emerging: direct-to-installer channel strategies that displace distributor intermediaries, and hybrid architecture development that unifies DC-AC conversion with bidirectional battery charging.
Within the module-level electronics tier, Enphase Energy and SMA Solar Technology exemplify divergent strategic positioning. Enphase anchors premium residential penetration in Australia's mature distributed solar segment through captive installer networks. SMA Solar Technology occupies a position specialized for three-phase commercial arrays across South Korea and Japan. Chinese specialists including Hoymiles and Deye Inverter represent scale-driven manufacturing archetypes serving price-sensitive Southeast Asian markets.
| Leading Market Players |
|---|
| Enphase Energy |
| APsystems |
| SMA Solar Technology |
| Hoymiles |
| Altenergy Power System |
| Zhejiang Envertech |
| Darfon Electronics |
| Sungrow |
| Deye Inverter |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between Clean Energy Council-listed premium units and uncertified economy imports manifests in divergent margin structures and procurement channel configurations across the APAC solar micro inverter market. Premium-tier suppliers anchor pricing power through captive installer networks in Australia and Japan, while commodity-tier producers compete on landed cost for Southeast Asian price-sensitive commercial projects.
Pricing Analysis
Short-lead-time premiums for METI-certified units in Japan contrast with spot-inventory discounts available through Chinese trading channels serving Vietnam's C&I segment. Three-tier pricing structure across premium certification-grade, standard compliance-tier, and economy non-certified levels segments buyer archetypes. Cost compression in the economy tier is intensifying because wafer pricing volatility feeds through power semiconductor costs. Commercial installers in Vietnam's central provinces exhibit highest price sensitivity, while residential contractors in Australia's top 20 installer groups prioritize certification-grade reliability over unit economics.
Supply Chain Analysis
Power MOSFET and IGBT supply rests on Taiwanese foundry capacity and Japanese discrete semiconductor specialists, with Chinese packaging houses completing final assembly. Silicon wafer substrates, magnetic components, and enclosure-grade aluminum constitute the primary raw material dependencies. Single-source vulnerability concentrates in 300mm silicon wafer supply from East Asian producers, exposing lead times to allocation constraints. Distribution runs through direct-to-installer channels displacing traditional electrical distributors in mature markets, while project-based procurement dominates emerging Southeast Asian C&I deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor foundry capacity constraints prop pricing power for certified-tier suppliers, creating a supply-constrained market structure favoring incumbent positioning and early certification investment.
For Market Incumbents: To counter three-phase string systems with module-level optimizers capturing price-sensitive commercial projects in South Korea and Japan, deepen firmware-defined functionality differentiation and accelerate hybrid architecture development. Anchor channel control through captive installer network expansion in Australia's consolidating distribution landscape, while securing BIS certification capacity for Indian market access. For New Entrants and Emerging Players: Begin with Philippines off-grid electrification white space, where island communities and remote commercial facilities present unserved demand for hybrid micro inverter architectures integrating battery storage. Target Vietnam's central province C&I rooftop programs through direct EPC contractor relationships, bypassing established distributor hierarchies. Lead with storage-ready bundled offerings rather than retrofit-compatible grid-tied units. For Investors and Strategic Acquirers: Re-rating potential sits with firmware-defined hybrid specialists given battery attachment rate expansion across APAC distributed solar programs. Long-term viability over the projection horizon favors suppliers with METI certification depth and Clean Energy Council listing status. Monitor BIS approval timeline compression as inflection indicator for Indian market access premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Architecture Development | Unifies DC-AC conversion with bidirectional battery charging for Thailand and Philippine C&I backup resilience requirements. |
| Direct-to-Installer Channel Buildout | Displaces distributor intermediaries in Australia's mature market through training certification and lead referral programs. |
| Certification Depth Investment | METI anti-islanding compliance and Clean Energy Council listing function as de facto market access gates. |
| Domestic Assembly Capacity | India's PLI scheme incentives reduce import dependency for power conversion equipment across Gujarat and Tamil Nadu. |
| Firmware-Defined Functionality | Grid-forming capability satisfies Japan's reactive power mandates while enabling remote asset management platforms. |
Study Parameters
Multi-period observation of module-level power electronics adoption rates, certification approval timelines, and battery attachment trajectories anchored the trend analysis, supplemented by interviews with solar EPC contractors, utility interconnection officers, inverter procurement managers at C&I facilities, and regulatory compliance specialists at certification bodies. Secondary validation drew from METI technical standards documentation, Clean Energy Council approved product listings, BIS power conditioning unit notifications, IEA distributed energy resources tracking, and customs trade data for power conversion equipment. Bottom-up shipment volume modeling triangulated against top-down addressable market sizing across the analysis window.
Segment-weighting applied product type, end user, technology, and installation type dimensions with regional regulatory cluster overlays. CAGRs derived from fitted growth curves against historical penetration patterns and policy incentive trajectories. Forecast inputs incorporated PLI scheme capacity buildout schedules, grid code evolution timelines, and lithium-ion battery cost curves.
Underlying measurement precision varies by segment; grid-tied residential volumes in Australia and Japan carry tighter precision than emerging hybrid C&I deployments in Vietnam and the Philippines. Forecasts reflect documented assumptions regarding policy continuity, foundry capacity expansion, and certification pathway stability. Semiconductor supply disruption, tariff regime shifts, and grid code acceleration in India and Thailand warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Greece Renewable Energy Market
Solar Power Systems
Solar Interconnect Ribbon Market
Solar Power Systems
Indonesia Solar Energy Market
Solar Power Systems
Solar Photovoltaics Wafer Market
Solar Power Systems
Solar Cell Films Market
Solar Power Systems
Asia-Pacific Solar Tracker Market
Solar Power Systems
Amorphous Silicon PV Market
Solar Power Systems
US Solar PV Market
Solar Power Systems
Floating Solar System Market
Solar Power Systems
Asia Pacific Solar Inverter Market
Solar Power Systems
High-Efficiency Solar Modules Market
Solar Power Systems
Japan Solar Energy Market
Solar Power Systems
Southeast Asia Solar Energy Market
Solar Power Systems
Crystalline Silicon Solar PV Market
Solar Power Systems
Solar Panels for Home Market
Solar Power Systems
Solar Rack Market