
 Mexico Solar Energy Market | 2026-2036
Mexico Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Solar Energy Market Outlook
Procurement from single-source to multi-source frameworks is shifting across Mexico's utility-scale solar segment. Trina Solar leverages its integrated manufacturing scale to compete on module cost in CFE tenders. Canadian Solar anchors its position through localized supply chain partnerships and project development capabilities.
Mexico solar energy encompasses photovoltaic and concentrated solar power systems that convert electromagnetic radiation into electrical energy through semiconductor junctions or thermal cycles, typically operating at 15-22% conversion efficiency for silicon-based modules. The primary purpose is grid-connected and distributed electricity generation for residential, commercial, and industrial consumers. Photovoltaic installations dominate current capacity additions, while concentrated solar power occupies a niche in hybrid configurations with thermal storage. Ground-mounted utility projects command the largest capital deployment, though rooftop distributed generation is accelerating under net metering reforms.
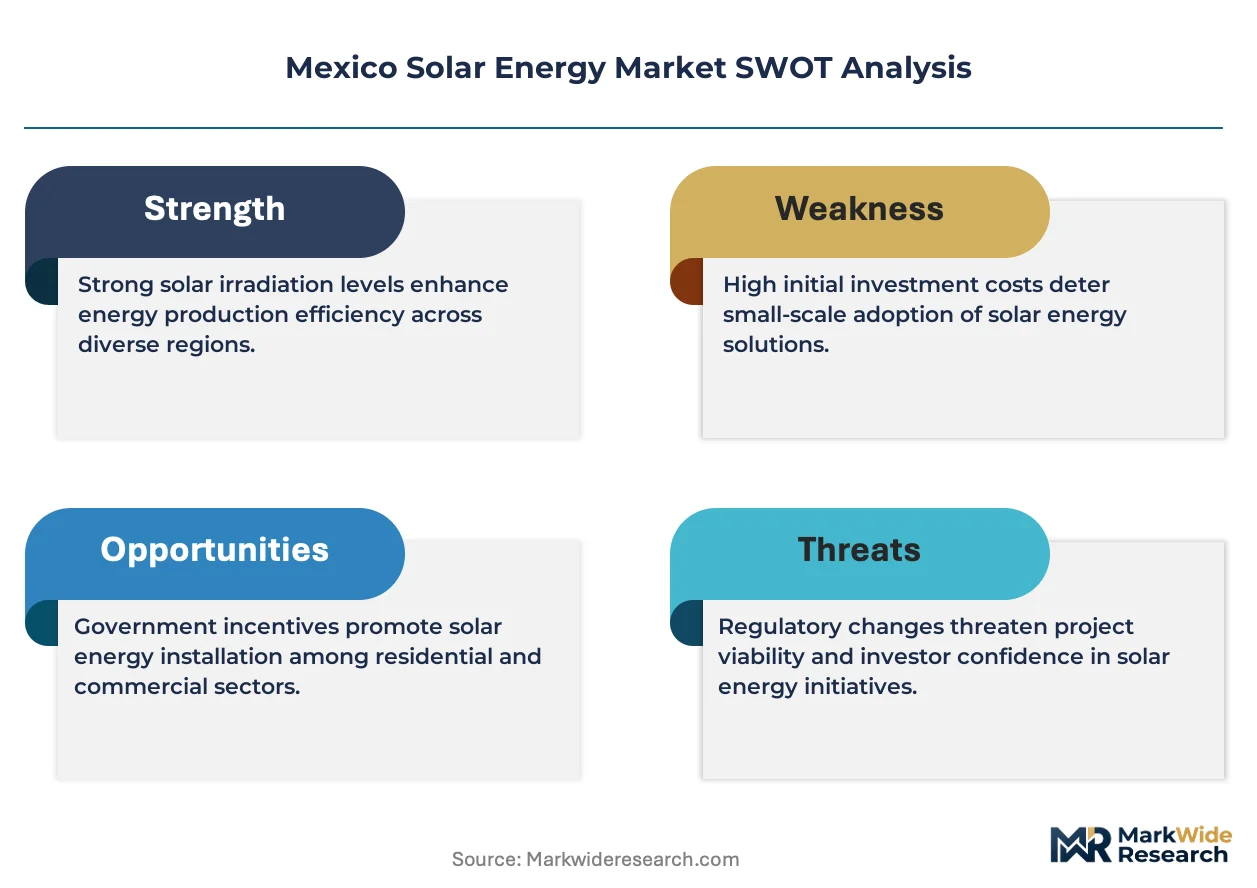
CRE licensing requirements and CFE interconnection standards shape market access timelines and technical compliance costs for project developers. Mexico's Secretariat of Energy (SENER) clean energy mandates and FIDE efficiency programs create demand pull for residential and commercial installations. Stakeholders must monitor CRE's evolving wheeling regulations and state-level permitting fragmentation to optimize project siting and offtake structuring.
Market Dynamics
CRE permitting reforms and CFE procurement diversification are compressing project development timelines while fragmenting supplier relationships across Mexico's utility-scale solar pipeline.
Growth Catalysts
- Sonora-Baja California irradiance concentration:Six-plus peak sun hours daily attract capital-intensive ground-mounted developments. Independent power producers cluster permitting applications in these states.
- Net metering reforms:SENER distributed generation rules unlock rooftop installations for commercial and industrial consumers. CFE interconnection standards now accommodate behind-the-meter capacity at scale.
- FIDE efficiency programs:Federal financing instruments reduce upfront capital barriers for residential solar adoption. These programs channel institutional capital into distributed generation asset classes.
Market Restraints
- Polysilicon supply concentration:Mexico's module supply chains depend on upstream material inputs from concentrated Asian manufacturing bases. Price volatility in this input layer compresses developer margins unpredictably.
- State-level permitting fragmentation:Municipal and state environmental clearances create timeline variability across project locations. Sonora and Baja California maintain distinct land-use regimes that delay uniform deployment.
- Grid interconnection queues:CFE transmission capacity constraints in high-irradiance zones limit project energization schedules. Thermal generation dispatch priority occasionally displaces solar offtake during peak production hours.
Strategic Opportunities
- Agrivoltaic installations:Dual-use solar arrays over agricultural land in Sinaloa and Chihuahua unlock land-constrained development. These configurations qualify for rural development incentives under SENER guidelines.
- Industrial self-supply contracting:Large manufacturing facilities in Nuevo León and Querétaro pursue direct power purchase agreements bypassing CFE retail tariffs. This channel bypasses traditional utility intermediation.
- Hybrid solar-plus-storage:Lithium-ion battery cost declines enable four-hour storage co-location with utility-scale projects. CRE wheeling regulations are evolving to recognize stored energy as distinct from intermittent generation.
Industry Challenges
- Specialized EPC talent scarcity:Utility-scale project engineering and construction expertise concentrates among a limited contractor base. Workforce development lags behind pipeline expansion in high-growth states.
- Land titling complexity:Ejido communal land structures in rural solar zones require negotiated use agreements extending project origination timelines. Legal clarity on surface rights remains inconsistent across municipalities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Solar Energy Market |
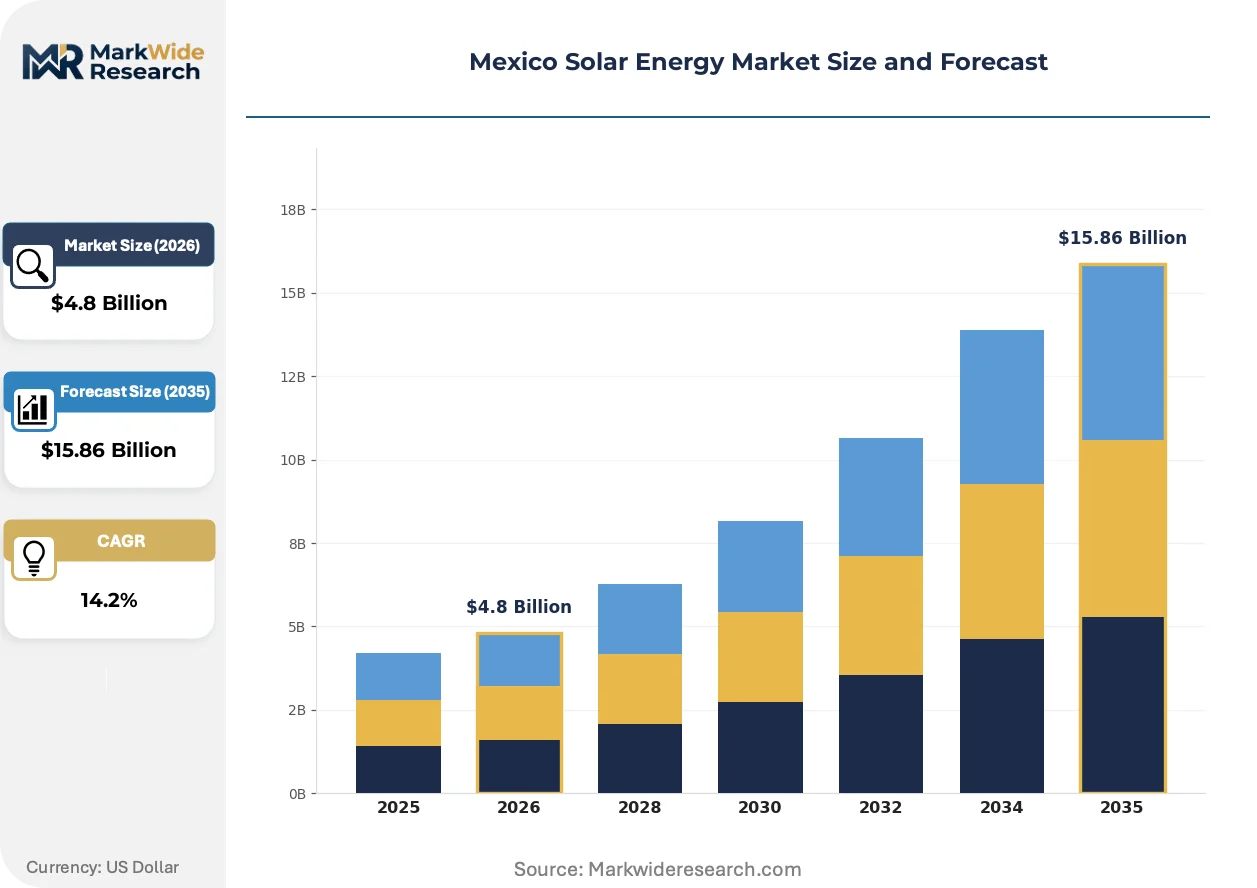
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic, Concentrated Solar Power, Hybrid Systems, Solar Water Heaters End User: Residential, Commercial, Industrial, Utilities Installation Type: Ground-mounted, Rooftop, Off-grid, On-grid Component: Solar Panels, Inverters, Mounting Structures, Batteries |
| Companies Covered | Trina Solar, Maxeon Solar, Enphase Energy, IUSASOL, Neoen Solar, Canadian Solar, Longi, Solartec, Hanwha Q Cells, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Solar Energy Market Strategic Shifts
Bifacial module technology and automated permitting platforms are compressing levelized cost trajectories while restructuring developer competitive advantages across Mexican solar markets.
Bifacial photovoltaic modules capture reflected irradiance from ground surfaces, boosting energy yield per installed watt. Large-scale independent power producers in Sonora deploy these units across albedo-optimized sites. This hardware shift is rewriting capacity factor assumptions that previously anchored project finance structures.
CRE digital permitting portals now automate environmental impact screening for sub-50-megawatt installations. These platforms reduce administrative review cycles from months to weeks. Distributed generation developers in Baja California leverage this regulatory streamlining to accelerate residential and commercial project commissioning.
Direct corporate power purchase agreements displace traditional utility intermediation for energy-intensive manufacturers. Mining and automotive assembly operations in Coahuila and Guanajuato negotiate long-term solar supply contracts with independent generators. This contracting evolution concentrates offtake risk assessment capabilities among large industrial procurement functions.
Mexico Solar Energy Market Segmentation
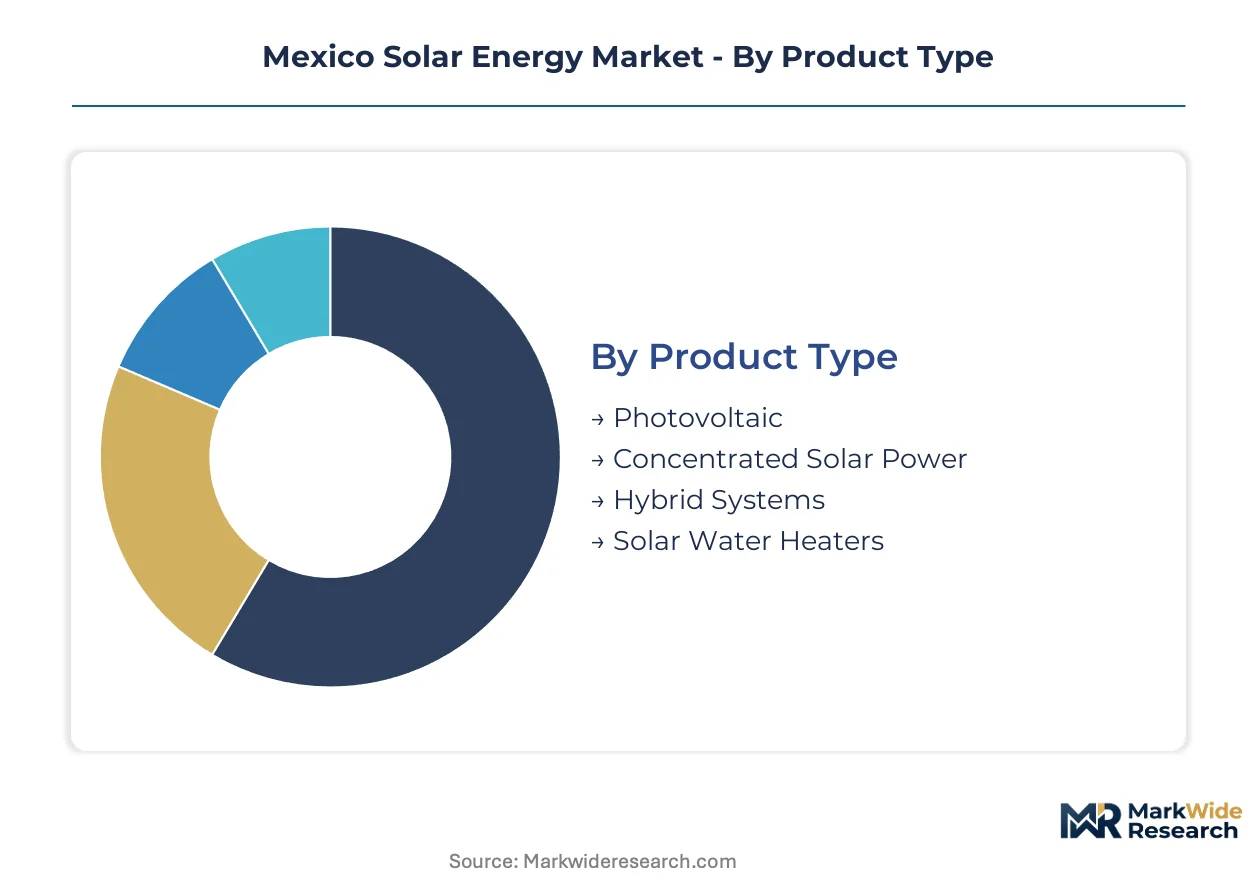
Segmentation in Mexico's solar market reveals how technology choices map to regulatory pathways and capital intensity. Each dimension—product, end user, installation mode, and component—carries distinct CRE permitting requirements and CFE interconnection protocols that shape project economics.
Product Type:
Standalone photovoltaic systems dominate utility-scale deployment, while concentrated solar power and hybrid configurations require deeper grid integration planning.
- Photovoltaic:Silicon-based semiconductor junctions convert direct and diffuse irradiance into direct current electricity at 15-22% conversion efficiency. Demand clusters in Sonora and Baja California ground-mounted installations where six-plus peak sun hours compress levelized cost trajectories. CFE procurement diversification favors this technology for rapid deployment timelines.
- Concentrated Solar Power:Parabolic troughs and solar power towers concentrate thermal energy to drive steam cycles, typically incorporating molten salt storage for dispatchable output. Industrial self-supply contracts in Nuevo León mining operations value this predictability for baseload manufacturing processes.
- Hybrid Systems:Photovoltaic-battery or solar-thermal combinations optimize capacity factors across variable irradiance conditions.
- Solar Water Heaters:Thermal collectors for residential and commercial hot water applications operate at lower technology readiness than electricity-generating systems.
Volume placements concentrate in Photovoltaic; the faster expansion belongs to Hybrid Systems.
End User:
Customer type determines financing structure, with utility procurement scaling through CFE tenders while distributed segments navigate net metering reforms.
- Residential:Behind-the-meter rooftop installations under 10 kilowatts qualify for simplified CRE interconnection standards and FIDE efficiency program financing. SENER distributed generation rules in Baja California municipalities accelerate permitting for this segment.
- Commercial:Mid-scale rooftop and carport installations serve retail, hospitality, and office facilities with 10-kilowatt to 1-megawatt capacity ranges. Querétaro automotive supplier parks leverage these systems to hedge against CFE industrial tariff volatility.
- Industrial:Large manufacturing loads in Coahuila and Guanajuato negotiate direct power purchase agreements bypassing utility intermediation.
- Utilities:CFE and independent power producers deploy utility-scale capacity under long-term contracting frameworks with multi-source procurement mandates.
Industrial offtake is climbing the fastest as manufacturing procurement functions internalize solar sourcing capabilities.
Installation Type:
Grid connection status and land use intensity create divergent development timelines across Mexico's varied terrain and transmission infrastructure.
- Ground-mounted:Utility-scale arrays on agricultural or desert land in Sonora and Chihuahua require ejido communal land negotiations that extend origination timelines. Albedo-optimized bifacial module deployment concentrates in these configurations.
- Rooftop:Distributed generation on commercial and industrial buildings bypasses land titling complexity while leveraging existing electrical infrastructure. CRE digital permitting portals accelerate commissioning for sub-50-megawatt rooftop projects in Baja California.
- Off-grid:Standalone systems serve remote agricultural operations and rural communities beyond CFE transmission reach.
- On-grid:Grid-synchronized installations dominate utility-scale and commercial segments with net metering or bilateral contracting structures.
Ground-mounted capacity dominates current pipelines; rooftop distributed generation is gaining share fastest under streamlined permitting.
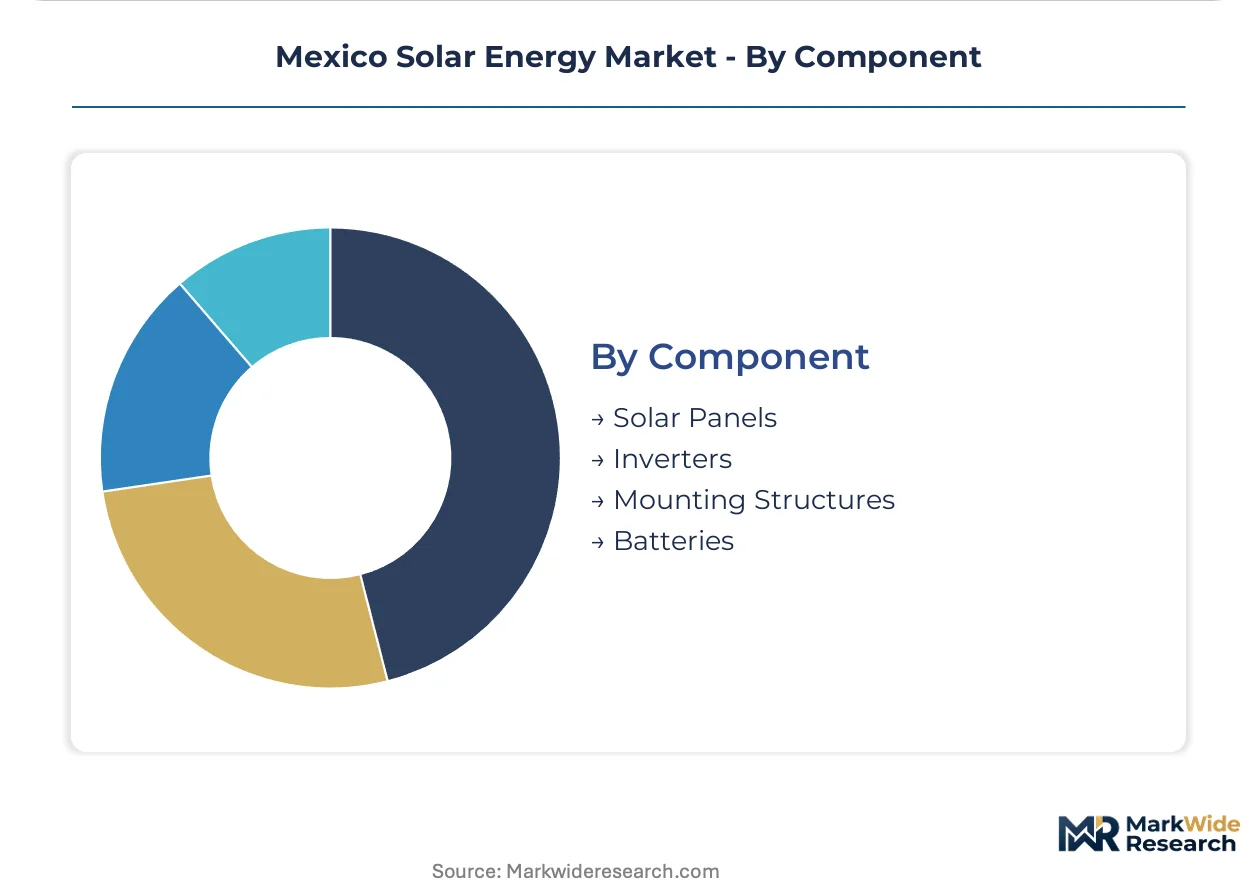
Component:
Supply chain concentration in upstream materials shapes component cost structures and localization strategies for Mexican project developers.
- Solar Panels:Crystalline silicon modules constitute the primary capital expenditure for photovoltaic installations, with bifacial technology rewriting capacity factor assumptions in Sonora ground-mounted projects. Polysilicon input price volatility compresses developer margins unpredictably.
- Inverters:Power electronics convert direct current photovoltaic output to grid-synchronized alternating current, with string inverters dominating distributed generation and central inverters serving utility-scale installations.
- Mounting Structures:Fixed-tilt and tracking systems position modules for optimal irradiance capture, with single-axis tracking penetrating utility-scale deployments in high-DNI zones.
- Batteries:Lithium-ion storage co-location enables four-hour shifting of solar output, with CRE wheeling regulations evolving to recognize stored energy as distinct from intermittent generation.
Solar Panels command the largest procurement volumes; Batteries show the steepest expansion trajectory as hybrid project structures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silica sand deposits in Sonora and copper mining tailings across the Sierra Madre Occidental anchor Mexico's solar manufacturing feedstock geography. These raw material localities concentrate project development capital in northern states with superior irradiance profiles. Federal energy policy channels investment toward sub-regions with existing transmission infrastructure and simplified land-use frameworks.
Sonora
Six-plus peak sun hours daily and vacant desert land attract utility-scale independent power producers clustering bifacial module installations. CRE streamlined environmental clearances for sub-50-megawatt projects reduce permitting timelines from months to weeks. Puerto Peñasco and Hermosillo industrial zones host ground-mounted arrays serving mining and manufacturing loads.
Baja California
Net metering reforms and FIDE efficiency program financing unlock distributed generation for commercial and residential consumers. SENER distributed generation rules accommodate behind-the-meter capacity at scale in Tijuana and Mexicali municipal zones. Maquiladora manufacturing parks leverage rooftop solar to hedge against CFE industrial tariff volatility.
Nuevo León
Automotive and steel manufacturing facilities pursue direct power purchase agreements bypassing traditional utility intermediation. Industrial self-supply contracting concentrates procurement capabilities among large manufacturing operations in Monterrey metropolitan area. CFE transmission constraints occasionally limit project energization schedules despite strong offtake demand.
Jalisco
Agrivoltaic dual-use installations over agricultural land in Guadalajara periphery qualify for rural development incentives under SENER guidelines. Ejido communal land structures require negotiated use agreements extending project origination timelines. CRE wheeling regulations evolution recognizes stored energy as distinct from intermittent generation for hybrid solar-plus-storage proposals.
Querétaro
Aerospace supplier parks and automotive component manufacturers internalize solar sourcing capabilities through corporate procurement functions. Direct corporate power purchase agreements displace traditional utility intermediation for energy-intensive precision manufacturing. State-level environmental clearances maintain distinct land-use regimes that delay uniform deployment relative to northern border states.
Mexico Solar Energy Market Competitive Environment
Global majors compete with regional champions across module supply and project development capabilities. The vendor base stratifies between integrated Chinese manufacturers with captive polysilicon supply and regional developers with localized permitting expertise. Three archetypes dominate: scale-driven module producers, distributed generation specialists with CRE digital portal fluency, and hybrid EPC-developers controlling land positions in high-irradiance zones. Competitive moves concentrate on strategic partnerships with industrial offtakers and backward integration into mounting structure fabrication.
Among integrated Chinese manufacturers, Trina Solar, Longi, and Canadian Solar exemplify the scale-driven archetype competing on module cost in CFE tenders. These entities anchor their positioning through manufacturing scale rather than project development capabilities. Regional specialists including IUSASOL and Solartec occupy positions emphasizing localized supply chain partnerships and CRE permitting navigation. The competitive dynamic pits manufacturing scale against regulatory fluency and land access.
| Leading Market Players |
|---|
| Trina Solar |
| Maxeon Solar |
| Enphase Energy |
| IUSASOL |
| Neoen Solar |
| Canadian Solar |
| Longi |
| Solartec |
| Hanwha Q Cells |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap EPC contractors dominate project origination in Sonora and Baja California, concentrating pricing power among localized developers who control land positions and CRE permitting relationships while Chinese module manufacturers compete on undifferentiated hardware margins.
Pricing Analysis
Warranty and O&M service bundling separates premium EPC offers from commodity module transactions in CFE tender responses. Project-based long-term offtake contracts anchor utility-scale economics, with price differentiation hinging on performance guarantees and localized permitting expertise versus import logistics. Pricing pressure stems from polysilicon input volatility compressing developer margins. Commercial rooftop segments demonstrate highest price sensitivity due to FIDE financing caps, while industrial self-supply buyers prioritize dispatch reliability over unit economics.
Supply Chain Analysis
Specialized solar installation workforce scarcity in Hermosillo and Mexicali manufacturing zones constrains EPC capacity expansion. Module supply draws from Chinese polysilicon ingot production, Vietnamese cell assembly, and Mexican border-zone framing operations. Raw material dependencies span metallurgical-grade silicon, silver paste, and aluminum extrusions. Single-source vulnerability concentrates in polysilicon purification stages. Distribution runs through CFE interconnection queues and independent power producer direct contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's solar market sits in a technology-transition phase where bifacial modules and lithium-ion storage are displacing legacy monofacial fixed-tilt configurations across utility-scale procurement.
For Market Incumbents: Anchor market position through backward integration into mounting structure fabrication and tracker assembly within Mexican border industrial zones. Defend against emerging distributed generation specialists by securing exclusive CRE digital portal access for sub-50-megawatt project categories. Prioritize certification investment in hybrid solar-plus-storage system integration to capture evolving wheeling regulation recognition.
For New Entrants and Emerging Players: Automated permitting platform technology offers a wedge into CRE administrative bottlenecks that delay competitor project timelines. Target agrivoltaic dual-use installations in Sinaloa and Chihuahua where rural development incentives reduce land access barriers. Pursue direct corporate power purchase agreement origination with Nuevo León automotive suppliers as the most penetrable industrial offtake channel.
For Investors and Strategic Acquirers: Distressed-cycle entries favor hybrid EPC-developers controlling ejido land positions in Sonora and Baja California high-irradiance zones. Long-term viability over a decade-plus horizon rests on regulatory fluency rather than manufacturing scale. Watch CRE wheeling regulation evolution for stored energy recognition as the inflection signal for storage co-location asset valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement | Direct corporate contracting with Coahuila mining operations bypasses CFE tariff intermediation entirely. |
| Technology Licensing | Bifacial module IP partnerships with Sonora ground-mounted developers rewrite capacity factor assumptions. |
| Vertical Integration into Storage | Lithium-ion battery assembly in Baja California qualifies projects for evolving CRE wheeling recognition. |
| Green Certification Program | SENER rural development incentives for agrivoltaic configurations unlock land-constrained development in Jalisco. |
| Capacity Buildout | Tracker manufacturing localization in Nuevo León reduces import logistics exposure for utility-scale deployments. |
Study Parameters
Document review covered CRE permitting databases, CFE interconnection filings, and SENER distributed generation rulemakings, complemented by interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators. Secondary validation drew from project development databases, customs import records, and federal efficiency program disbursements. Bottom-up project pipeline aggregation triangulated against top-down capacity installation estimates.
Historical capacity deployment patterns cross-referenced against panel input from developer origination timelines and module procurement contracts. Segmentation modeling spanned technology type, end-user category, installation mode, and component layer across the projection horizon. CAGRs derived from installed capacity trajectory analysis incorporating irradiance mapping, land availability constraints, and regulatory approval velocity. Forecast inputs included CFE procurement diversification schedules and FIDE program funding allocations.
Several conditions sit outside the modeled scope, including presidential decree reversals affecting private generation participation and transmission infrastructure buildout delays beyond CFE's capital expenditure plans. Forecasts reflect assumptions on CRE permitting reform continuity and net metering tariff stability. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Distributed Solar Power Generation System Market
Solar Power Systems
Belgium Solar Energy Market
Solar Power Systems
Solar Panels for Home Market
Solar Power Systems
Boat Solar Panel Market
Solar Power Systems
Solar Panel Laminator Market
Solar Power Systems
Solar Laminator Market
Solar Power Systems
Solar Shingles Market
Solar Power Systems
Solar Bench Market
Solar Power Systems
Philippines Solar Energy Market
Solar Power Systems
Thin Film Solar PV Market
Solar Power Systems
Solar PV Backsheet Market
Solar Power Systems
Smart Solar Tracker Market
Solar Power Systems
Global Solar Microinverter Market
Solar Power Systems
Turkey Solar Energy Market
Solar Power Systems
Building Applied Photovoltaics (BAPV) Market
Solar Power Systems
Solar Simulator Market