
 India Solar Photovoltaic (PV) Market | 2026-2036
India Solar Photovoltaic (PV) Market Size, Share, and Industry Trends Forecast 2026-2036
India Solar Photovoltaic (PV) Market Foresight
Module efficiency tier upgrades above 21 percent is unwinding legacy procurement patterns across Indian project pipelines. Waaree Energies leverages its Gujarat manufacturing base to dominate domestic module supply chains. Tata Power Solar anchors utility-scale execution through integrated EPC capabilities. Adani Solar extends vertical control from polysilicon to module assembly.
India Solar Photovoltaic (PV) denotes semiconductor-based energy conversion systems that transform incident solar radiation into direct-current electricity through p-n junction architectures, typically fabricated from crystalline silicon wafers or thin-film semiconductor deposits on glass or flexible substrates. These systems serve as dispatchable or grid-tied generation assets for electricity consumers seeking to reduce fossil fuel dependence and manage long-term energy costs. Monocrystalline modules command premium positioning in utility-scale tenders where land scarcity elevates efficiency economics. Thin-film retains niche traction in building-integrated applications where weight and aesthetic constraints override conversion efficiency priorities. Rooftop installations face persistent margin pressure from fragmented installer networks and inconsistent state-level net metering enforcement.
MNRE's ALMM (Approved List of Models and Manufacturers) mandates restrict public sector procurement to domestically certified producers, tightening market access for unlisted foreign suppliers. BIS certification requirements for module safety and performance standards filter substandard imports from Bangladesh and Southeast Asian transshipment routes. CEA grid connectivity regulations prescribe reactive power capabilities and fault ride-through parameters that shape inverter procurement specifications. Stakeholders must track ALMM list revisions and state-level open access regulations as these instruments determine competitive viability for integrated manufacturers versus pure-play module suppliers.
Market Dynamics
Module efficiency tier upgrades above 21 percent is unwinding legacy procurement patterns across Indian project pipelines. Waaree Energies leverages its Gujarat manufacturing base to dominate domestic module supply chains. Tata Power Solar anchors utility-scale execution through integrated EPC capabilities. Adani Solar extends vertical control from polysilicon to module assembly.
Growth Catalysts
- MNRE's PLI Scheme:Production-linked incentives for domestic cell and module manufacturing are pulling capacity investments into Gujarat and Tamil Nadu.
- Utility-Scale Tendering:SECI and NTPC auctions for gigawatt-scale projects are absorbing high-efficiency monocrystalline output from integrated producers.
- BIS Certification Mandates:Mandatory safety and performance standards are filtering substandard imports and elevating certified domestic suppliers.
Market Restraints
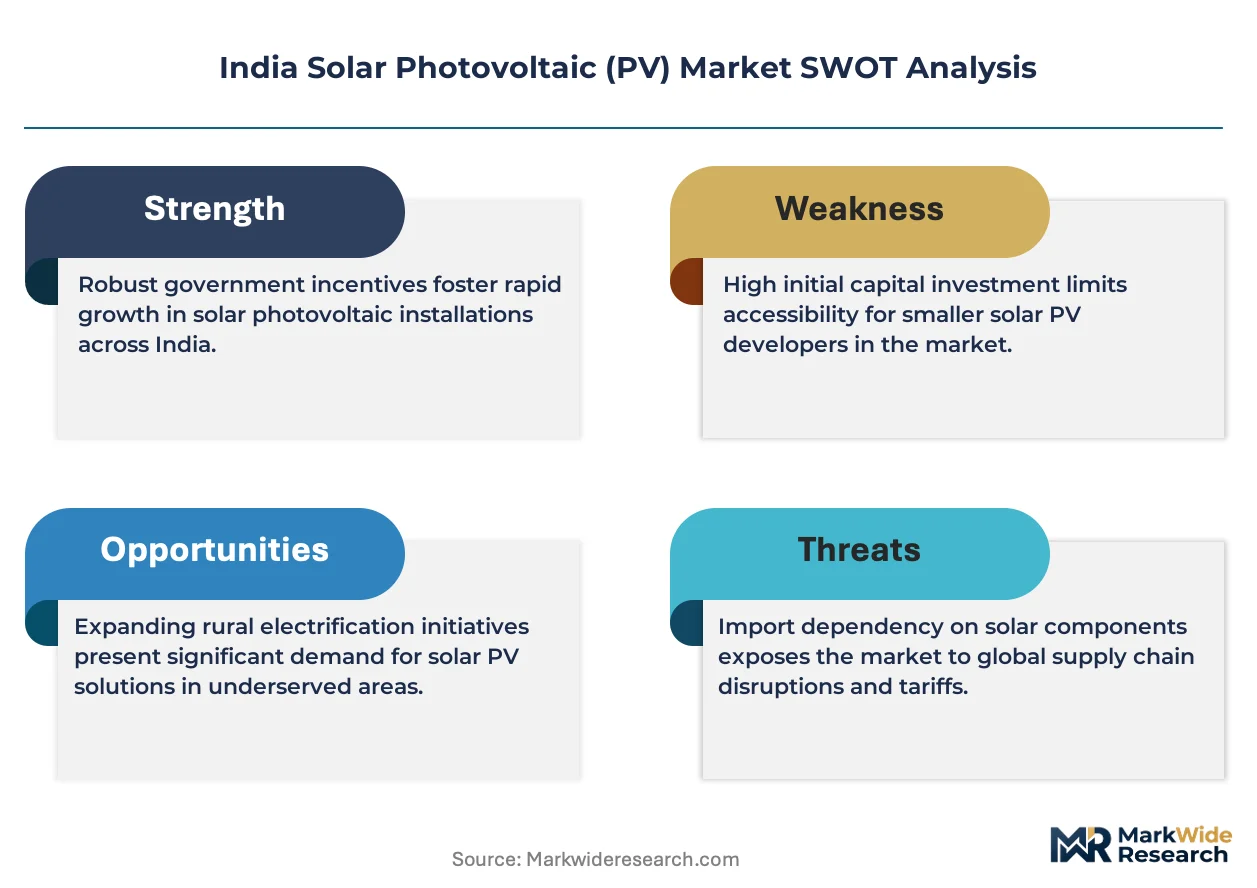
- Polysilicon Supply Concentration:China's dominance in metallurgical-grade silicon refining creates input cost volatility for Indian cell manufacturers lacking backward integration.
- Land Acquisition Friction:State-level revenue department procedures delay project commissioning in Rajasthan's desert districts despite irradiation advantages.
- Grid Integration Standards:CEA fault ride-through and reactive power mandates inflate inverter costs for developers connecting to weak rural substations.
Strategic Opportunities
- Agricultural Solar Pumping:PM-KUSUM Component B subsidies for off-grid pumps create distributed demand in Maharashtra and Karnataka farming belts.
- Floating PV Deployment:Reservoir-based installations on Gujarat and Kerala water bodies bypass land scarcity constraints entirely.
- Open Access Wheeling:Karnataka and Andhra Pradesh regulatory frameworks permitting third-party sale are attracting commercial and industrial off-takers.
Industry Challenges
- ALMM List Volatility:MNRE's periodic revision of approved manufacturers creates inventory obsolescence risk for distributors holding non-listed module stock.
- Skilled Installation Shortage:Fragmentated rooftop installer networks lack BIS-certified technicians for quality DC cable termination and earthing.
- Net Metering Enforcement:Inconsistent state electricity regulatory commission implementation leaves residential prosuners exposed to distribution company payment delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Solar Photovoltaic (PV) Market |
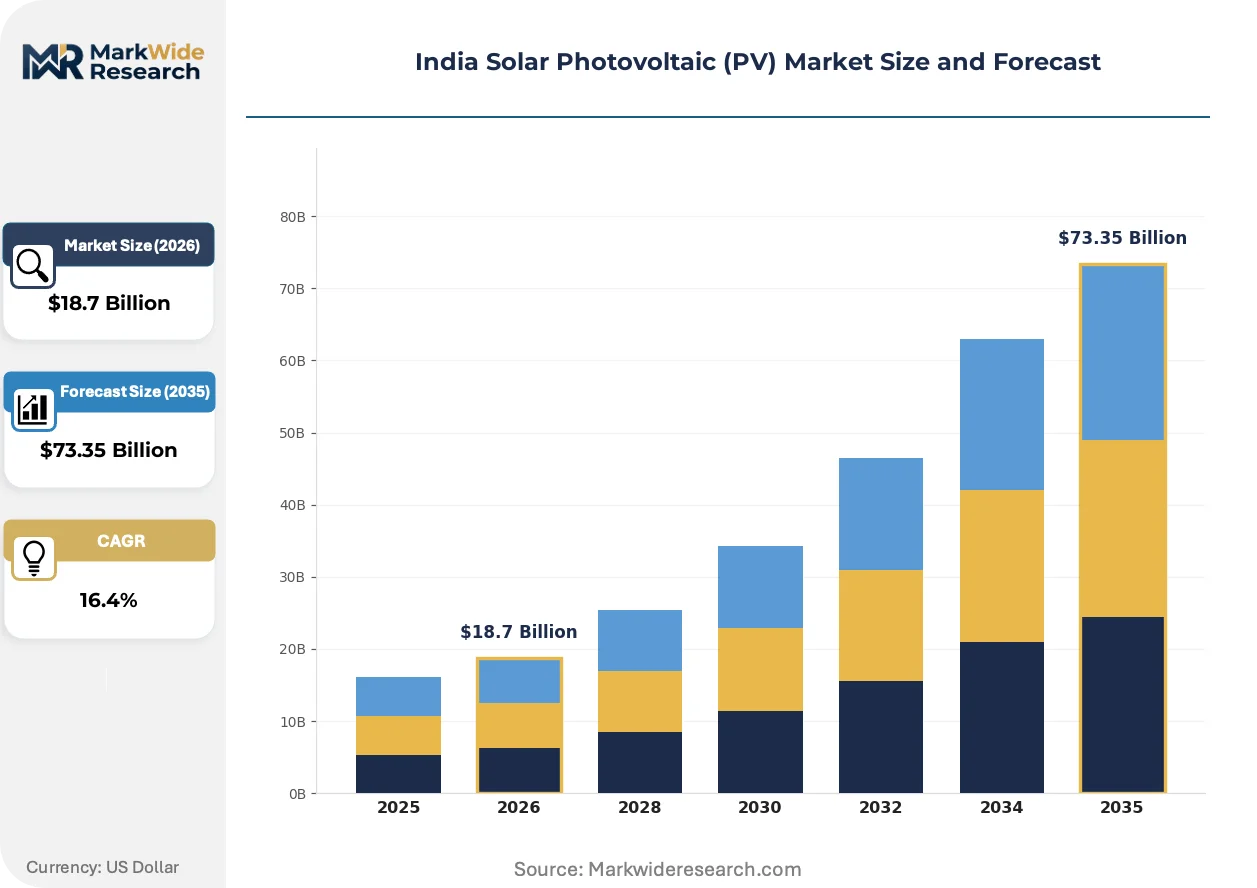
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Thin-Film, BIPV Technology: Solar Cells, Inverters, Mounting Systems, Energy Storage Application: Residential, Commercial, Industrial, Utility Scale Installation Type: Ground Mounted, Rooftop, Floating, Building Integrated |
| Companies Covered | First Solar, Premier Energies, Waaree Energies, Saatvik Green Energy, Vikram Solar, Tata Power Solar, Emmvee Photovoltaics, Goldi Solar, Adani Solar, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Solar Photovoltaic (PV) Market Shifts & Advancements
Technology trajectories and procurement protocols are actively splitting the Indian solar market into distinct efficiency tiers and buyer segments. Regulatory instruments are hardening domestic content requirements while demand patterns shift toward structured offtake arrangements.
Passivated emitter and rear contact (PERC) cell architecture is bifurcating module performance tiers at the 21 percent efficiency threshold. Discoms and IPPs with land-constrained sites in Gujarat are specifying PERC+ and TOPCon variants exclusively. Legacy multicrystalline inventory is compressing into price-sensitive agricultural and rural electrification tenders where acreage abundance offsets conversion losses.
MNRE's ALMM mandate restricts public sector procurement to domestically certified producers, tightening market access for unlisted foreign suppliers. BIS certification requirements for module safety and performance standards filter substandard imports from Bangladesh and Southeast Asian transshipment routes. Integrated manufacturers with captive cell lines are consolidating utility-scale market share as pure-play assemblers lose tender eligibility.
Power purchase agreement structures are migrating from traditional feed-in-tariff models toward open access and group captive arrangements. Commercial and industrial buyers in Karnataka and Maharashtra are bypassing state discoms through third-party wheeling agreements. This channel shift is concentrating procurement authority among energy managers at cement, textile, and automotive manufacturing clusters rather than distributed household decision-makers.
India Solar Photovoltaic (PV) Market Segmentation
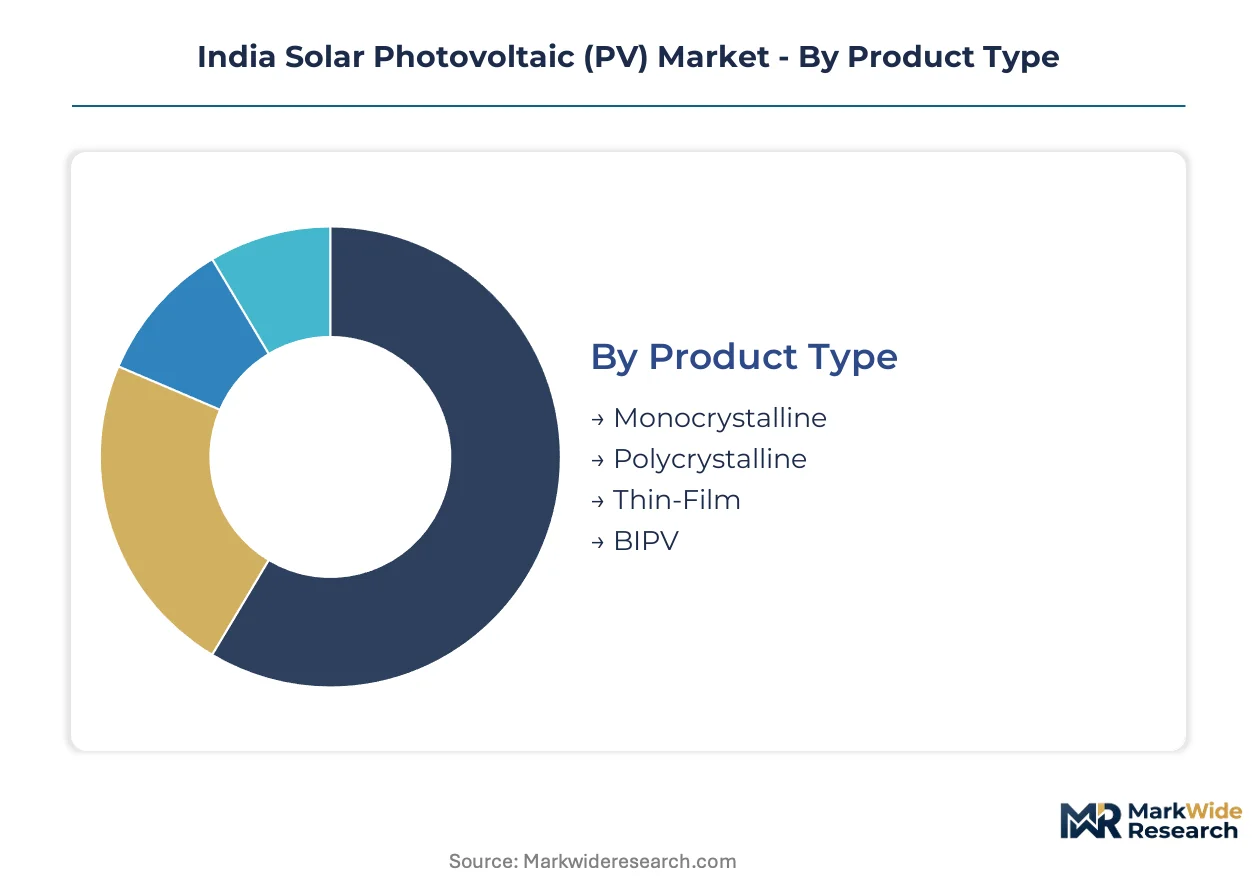
Segmentation in the Indian solar market reveals how regulatory mandates and land constraints reshape procurement patterns across distinct technology tiers. Understanding these divisions clarifies where PLI incentives concentrate manufacturing investment versus where import dependencies persist.
Product Type:
BIS certification tiers and ALMM eligibility criteria split module procurement into efficiency-based categories that determine project economics and tender competitiveness.
- Monocrystalline:PERC and TOPCon cell architectures deliver conversion efficiencies above 21 percent. Rajasthan utility-scale developers specify these variants exclusively where land scarcity elevates output-per-acre economics. MNRE's domestic content mandates favor certified monocrystalline producers with captive cell lines.
- Polycrystalline:Legacy multicrystalline technology retains cost advantages in agricultural pumping and rural electrification schemes where land abundance offsets lower conversion rates. Inventory compression is accelerating as ALMM revisions exclude sub-20 percent efficiency modules from public tenders.
- Thin-Film:Cadmium telluride and CIGS deposits on flexible substrates serve building-integrated applications where weight constraints override efficiency priorities.
- BIPV:Photovoltaic-integrated facades and roofing materials target commercial real estate in Mumbai and Bangalore where aesthetic integration commands premium positioning.
Established volume favors polycrystalline in rural subsidy programs; emerging adoption favors monocrystalline in utility-scale auctions.
Technology:
Component procurement patterns track CEA grid connectivity mandates and state-level storage incentives that reshape system architecture requirements.
- Solar Cells:Crystalline silicon p-n junction devices constitute the core energy conversion layer. Gujarat and Tamil Nadu manufacturing clusters under PLI scheme tranches are expanding mono-PERC and heterojunction cell capacity to serve domestic module assembly.
- Inverters:Power electronics with fault ride-through and reactive power capabilities prescribed by CEA regulations. String inverters dominate rooftop segments while central inverters anchor multi-megawatt ground installations in Rajasthan's solar parks.
- Mounting Systems:Fixed-tilt and single-axis tracking structures engineered for wind load and soil conditions. Tracking adoption concentrates in Gujarat's high-irradiation zones where yield gains justify mechanical complexity.
- Energy Storage:Lithium-ion battery systems paired with solar for peak shifting and grid stability. Andhra Pradesh and Karnataka regulations mandating storage co-location are accelerating procurement for evening discharge cycles.
Hardware procurement concentrates on cells and inverters; storage integration is climbing fastest as grid stability mandates expand.
Application:
Customer scale determines financing structures, regulatory jurisdiction, and whether procurement routes through state discoms or open access frameworks.
- Residential:Individual rooftop systems below 10 kW capacity. Net metering enforcement gaps across state electricity regulatory commissions create payment uncertainty for prosuners in Maharashtra and Tamil Nadu.
- Commercial:Office buildings, retail complexes, and educational institutions with 10 kW to 1 MW installations. Open access wheeling in Karnataka permits third-party power purchase agreements that bypass discom tariffs.
- Industrial:Manufacturing facilities with captive consumption above 1 MW. Cement, textile, and automotive clusters in Maharashtra and Gujarat deploy group captive structures to achieve tariff predictability.
- Utility Scale:Grid-connected solar parks above 10 MW developed by IPPs and public sector entities. SECI and NTPC auctions absorb high-efficiency module output with 25-year power purchase agreement tenors.
Utility-scale deployment commands manufacturing priority; commercial open access is gaining share fastest as regulatory frameworks mature.
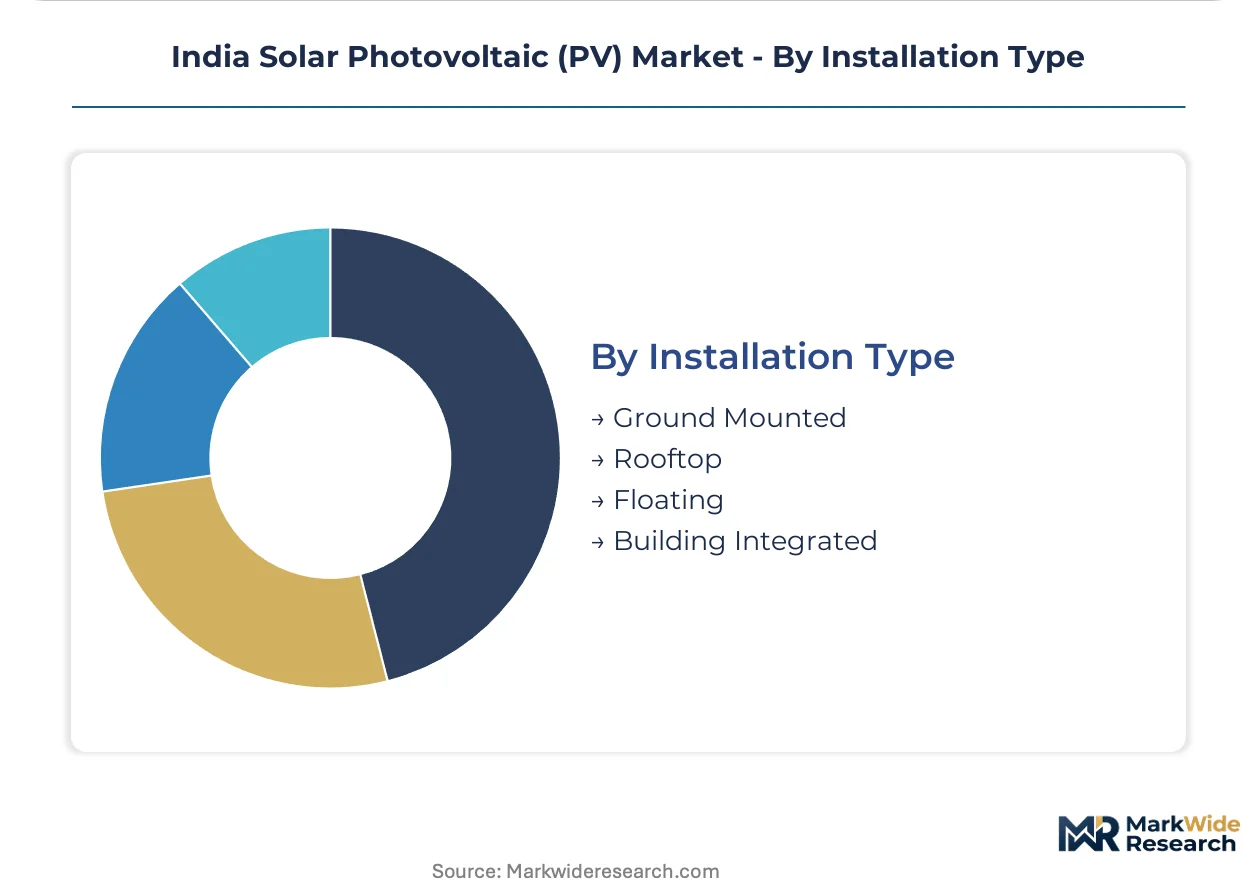
Installation Type:
Physical siting constraints and land use regulations determine where each architecture achieves economic viability across Indian states.
- Ground Mounted:Fixed-tilt and tracking arrays on acquired land parcels. Rajasthan's Barmer and Jodhpur districts host multi-gigawatt solar parks despite revenue department procedural delays.
- Rooftop:Building-surface installations across residential, commercial, and industrial premises. Fragmented installer networks and skilled technician shortages constrain quality execution in tier-2 cities.
- Floating:Reservoir-based PV systems on water bodies. Gujarat's irrigation reservoirs and Kerala's backwaters bypass land scarcity constraints entirely while reducing evaporation losses.
- Building Integrated:Photovoltaic elements replacing conventional building materials. Premium commercial developments in Hyderabad and Chennai adopt BIPV for green certification compliance.
Ground-mounted arrays dominate capacity additions; floating installations are expanding most quickly where land availability tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's solar module trade balance tilts toward import dependency for polysilicon feedstock while cell and assembly capacity localizes under PLI incentives. Western and southern states concentrate manufacturing investment; northern and eastern regions lag in industrial clustering despite irradiation potential.
Gujarat
Gandhinagar's PLI scheme tranches have anchored multi-gigawatt cell and module fabs in Mundra and Hazira port corridors. BIS certification mandates filter substandard imports through Surat customs checkpoints. Waaree Energies and Adani Solar operate vertically integrated facilities in the state's special economic zones.
Rajasthan
Barmer and Jodhpur districts host India's densest concentration of operational solar parks despite revenue department land acquisition delays. CEA grid connectivity regulations prescribe fault ride-through parameters for developers connecting to weak rural substations. SECI auctions absorb high-efficiency monocrystalline output from Rajasthan-based IPPs.
Tamil Nadu
Chennai's manufacturing belt under PLI scheme phase two is expanding heterojunction cell capacity to serve domestic module assembly. The state's electricity regulatory commission enforces open access wheeling frameworks that attract commercial and industrial off-takers. Coimbatore's industrial clusters deploy group captive structures for tariff predictability.
Karnataka
Bengaluru's electricity regulatory framework permits third-party power purchase agreements that bypass state discom tariffs. Agricultural solar pumping subsidies under PM-KUSUM Component B create distributed demand in Maharashtra-border farming belts. Floating PV deployment on Karnataka's irrigation reservoirs bypasses land scarcity constraints.
Maharashtra
Mumbai's commercial real estate sector adopts building-integrated photovoltaics for green certification compliance. Cement, textile, and automotive manufacturing clusters in Pune and Nagpur deploy open access wheeling for captive consumption above one megawatt. Net metering enforcement gaps across the state electricity regulatory commission create payment uncertainty for residential prosuners.
India Solar Photovoltaic (PV) Market Competitive Landscape
Listed leaders compete with private specialists across manufacturing scale and technology integration depth. The vendor base stratifies into three tiers: integrated cell-to-module producers with captive polysilicon linkages, pure-play assemblers dependent on imported cells, and thin-film specialists serving niche building-integrated applications. Dominant competitive moves include backward integration into polysilicon refining and strategic partnerships for inverter and storage co-location.
Among India-based integrated manufacturers, Waaree Energies, Tata Power Solar, and Adani Solar exemplify the cell-and-module archetype that dominates utility-scale tender eligibility under ALMM mandates. These entities occupy positions that align with MNRE's domestic content requirements. First Solar represents the thin-film alternative with cadmium telluride technology distinct from crystalline silicon supply chains. Premier Energies and Vikram Solar sit within the mid-tier assembly segment navigating BIS certification tiers for commercial and industrial rooftop penetration.
| Leading Market Players |
|---|
| First Solar |
| Premier Energies |
| Waaree Energies |
| Saatvik Green Energy |
| Vikram Solar |
| Tata Power Solar |
| Emmvee Photovoltaics |
| Goldi Solar |
| Adani Solar |
| Others |
Supply & Pricing Matrix
Long-term power purchase agreements lock in module procurement volumes for Indian utility-scale developers while anchoring price visibility across multi-year project tenors. These contract structures insulate integrated manufacturers from spot market volatility in polysilicon feedstock while exposing pure-play assemblers to margin compression when input costs spike.
Pricing Analysis
Industrial OEM buyers anchor procurement economics in India's solar market through group captive arrangements and open access wheeling frameworks. Pricing stratifies across ALMM-certified premium tiers, BIS compliance grades, and volume-scale procurement brackets. Cost compression in polycrystalline modules is intensifying because ALMM revisions are excluding sub-20 percent efficiency variants from public tenders. Commercial and industrial off-takers in Karnataka and Maharashtra exhibit lowest price sensitivity due to tariff predictability priorities, while agricultural pumping schemes face acute budget constraints.
Supply Chain Analysis
China dominates metallurgical-grade polysilicon refining while India concentrates cell and module assembly under PLI scheme tranches. Indian manufacturers draw from imported wafers and domestic glass, aluminum framing, and encapsulant materials. Single-source vulnerability in polysilicon feedstock creates input cost volatility for cell producers lacking backward integration. Distribution runs through EPC contractors for utility-scale deployment and fragmented installer networks for rooftop segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's solar photovoltaic market is cycling through a capital-intensive expansion phase as PLI scheme tranches pull manufacturing capacity into Gujarat and Tamil Nadu. The recovery trajectory hinges on execution velocity against land acquisition and grid integration bottlenecks.
For Market Incumbents: Consolidate utility-scale market share through captive cell line investments that satisfy ALMM eligibility criteria for SECI and NTPC auctions. Deepen backward integration into polysilicon refining to offset China's supply concentration. Channel control through integrated EPC capabilities defends margin position against pure-play assemblers losing tender access. For New Entrants and Emerging Players: Lead with floating PV deployment expertise targeting Gujarat's irrigation reservoirs and Kerala's backwaters where land scarcity constraints are bypassed entirely. Agricultural solar pumping under PM-KUSUM Component B offers the most penetrable white-space in Maharashtra and Karnataka farming belts. Third-party open access wheeling agreements provide the clearest go-to-market angle for commercial and industrial off-takers. For Investors and Strategic Acquirers: Cell-and-module producers with BIS certification and captive manufacturing lines in PLI scheme zones represent the most defensible acquisition archetype for long-term viability. Monitor ALMM list revision timing as the critical inflection signal for inventory obsolescence risk and competitive repositioning windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon | Captive feedstock supply reduces exposure to Chinese price volatility for Indian cell manufacturers. |
| ALMM Certification Investment | BIS compliance and MNRE listing unlock eligibility for public sector procurement tenders. |
| Floating PV Technology Deployment | Reservoir-based installations bypass land acquisition friction in Gujarat and Kerala. |
| Open Access Wheeling Agreements | Third-party power sales bypass state discom tariffs for Karnataka commercial off-takers. |
| Heterojunction Cell Capacity Expansion | Chennai manufacturing clusters under PLI phase two target efficiency tiers above 23 percent. |
Research Methodology
Cross-validation between MNRE deployment databases and CEA grid connectivity filings anchors the qualitative findings on manufacturing capacity localization. Primary interviews with IPP project developers, EPC contractors, state electricity regulatory commission officials, and module procurement managers combined with secondary validation from SECI auction results, BIS certification registries, and PLI scheme disbursement records. Bottom-up installation tracking and top-down manufacturing capacity assessment triangulate market sizing.
Sensitivity analysis around polysilicon price trajectories and ALMM list revision schedules shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include module efficiency tier, application scale, installation architecture, and state-level regulatory framework. CAGRs derive from weighted capacity addition pipelines and manufacturing utilization rates. Forecast inputs incorporate land acquisition clearance timelines and open access regulatory evolution in Karnataka and Andhra Pradesh.
The analysis sits within stated boundaries; outcomes outside PLI scheme continuation, BIS enforcement consistency, or state-level net metering stability would require recalibration. Forecasts reflect documented assumptions regarding module efficiency migration and import dependency reduction trajectories. Recalibration cycles align with material shifts in MNRE policy instruments and state electricity regulatory commission rulings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Bifacial Solar Cells Market
Solar Power Systems
Amorphous Silicon PV Market
Solar Power Systems
Photovoltaic (PV) Materials Market
Solar Power Systems
Solar Backsheet Market
Solar Power Systems
On-Site Photovoltaic Solar Power for Data Centers Market
Solar Power Systems
Bangladesh Solar Energy Market
Solar Power Systems
Solar Thermal Market
Solar Power Systems
India Residential Solar Inverter Market
Solar Power Systems
Solar PV Backsheet Market
Solar Power Systems
Fixed Tilt Solar PV Market
Solar Power Systems
Building-Integrated Photovoltaic (BIPV) Skylights Market
Solar Power Systems
France Distributed Solar Power Generation Market
Solar Power Systems
High Concentration Photovoltaics Market
Solar Power Systems
Distributed Solar Energy Market
Solar Power Systems
Solar EVA Market
Solar Power Systems
South Korea Solar Energy Market