
 Solar Phone Chargers Market | 2026-2036
Solar Phone Chargers Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Phone Chargers Market Insights
Perovskite-coated silicon is expanding its footprint in photovoltaic cells for portable applications, trimming unit costs while preserving conversion efficiency above twenty-one percent. Anker Innovations leverages vertically integrated battery supply chains to dominate mass-market retail channels. Goal Zero anchors its position through ruggedized designs purpose-built for expedition-grade reliability. Renogy specializes in higher-wattage foldable arrays that serve off-grid professionals and vanlife builders.
Solar phone chargers are photovoltaic-powered devices that convert sunlight into electrical energy through embedded solar cells, storing charge in lithium-polymer or lithium-ion reservoirs for subsequent transfer to mobile electronics via USB or wireless protocols. Monocrystalline panels currently command the technology segment due to superior energy density in compact form factors, though thin-film variants are gaining traction in ultra-lightweight designs where gram count governs purchasing decisions. Portable chargers and solar power banks together constitute the product backbone, while the emergency backup application is maturing fastest as disaster preparedness kits standardize renewable redundancy.
RoHS and REACH compliance in Europe, alongside FCC Part 15 electromagnetic emissions standards in the United States, collectively elevate certification burdens for cross-border sellers and filter out low-cost uncertified imports. The EU Green Deal's extended producer responsibility frameworks are pushing brands toward recyclable packaging and repairable architectures, reshaping product development roadmaps. Stakeholders must monitor how emerging right-to-repair legislation across multiple jurisdictions alters warranty structures and component sourcing strategies.
Market Dynamics
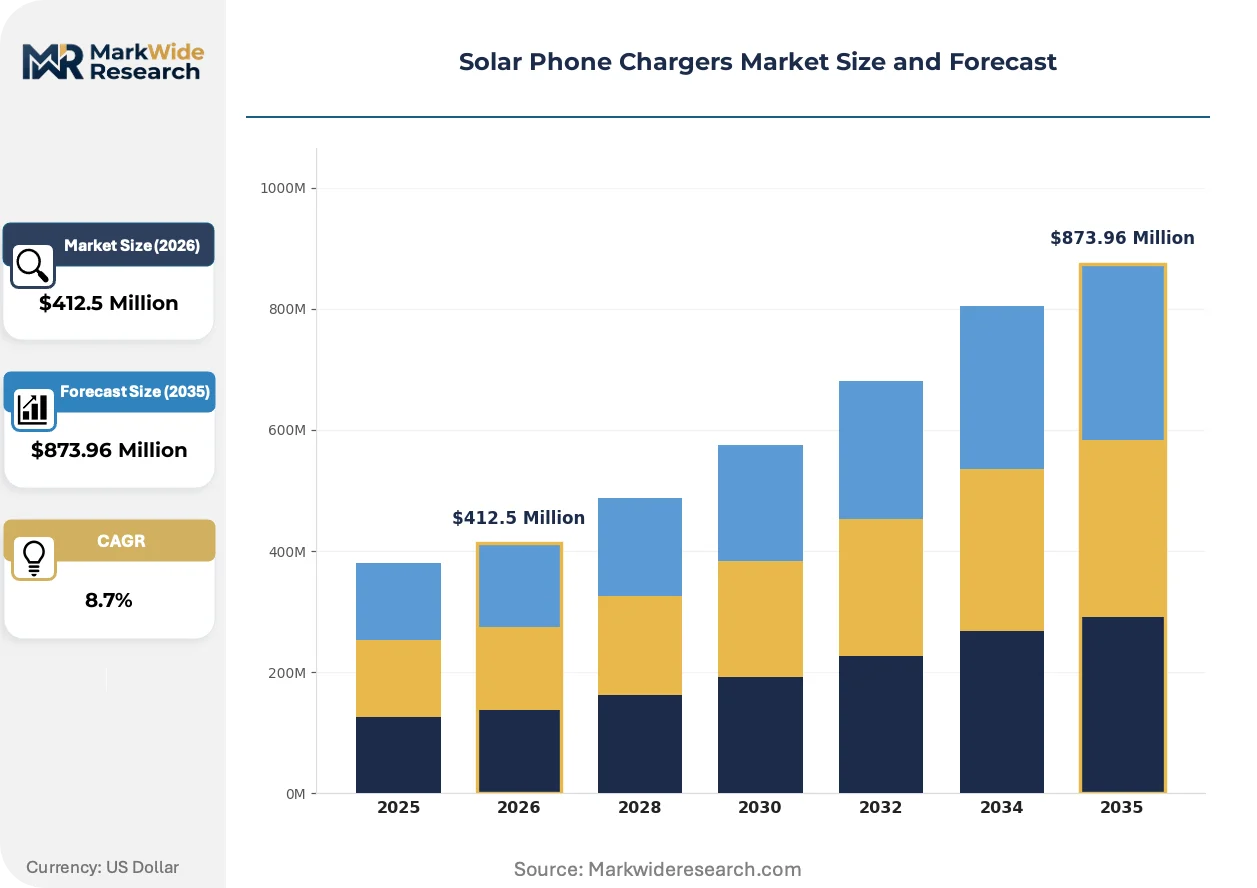
Perovskite-silicon tandem cell commercialization is compressing unit economics for portable photovoltaic devices while EU material disclosure mandates force supply chain reconfiguration across the entire category.
Growth Catalysts
- EU Ecodesign for Sustainable Products Regulation:Mandatory material passports and recyclability disclosures are accelerating brand consolidation toward compliant manufacturers with certified supply chains.
- Backpacking and trekking communities:Alpine rescue services and long-distance trail associations are standardizing solar redundancy in mandatory gear lists, creating institutional procurement pull.
- Perovskite-coated silicon:Laboratory-to-fab transfer of vapor-deposited perovskite layers is trimming cell production costs without sacrificing conversion efficiency in compact form factors.
Market Restraints
- Lithium-polymer cell supply concentration:Cathode precursor refining clusters in China's Hunan and Fujian provinces create single-source dependency risks for energy storage modules.
- Weather-dependent output variability:Northern European latitudes experience sub-optimal insolation for six-plus months, limiting year-round utility and compressing addressable demand windows.
- RoHS and REACH certification costs:European chemical substance testing and documentation burdens filter out sub-scale entrants, reducing competitive pressure at the low end.
Strategic Opportunities
- Emergency preparedness kits:Civil defense agencies in Germany and Austria are tendering for standardized renewable backup systems, creating B2G procurement channels.
- Vanlife and mobile dwelling builds:Off-grid professionals and recreational vehicle modifiers are specifying higher-wattage foldable arrays for sustained device charging without shore power.
- Right-to-repair legislation:French and German repairability index requirements are rewarding modular architectures with replaceable cells and connectors, differentiating premium positioning.
Industry Challenges
- Photovoltaic engineering talent scarcity:Thin-film deposition specialists and power electronics firmware developers command premium compensation, constraining R&D velocity for mid-tier brands.
- FCC Part 15 electromagnetic emissions certification:USB Power Delivery and wireless charging coil testing for US market entry extends product launch timelines by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Phone Chargers Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Chargers, Solar Power Banks, Solar Bags, Built-in Chargers Technology: Monocrystalline, Polycrystalline, Thin-film, Integrated Application: Camping, Outdoor Activities, Emergency Backup, Everyday Use Customer Type: General Consumers, Outdoor Enthusiasts, Tech Savvy Users, Eco-conscious Shoppers |
| Companies Covered | Anker Innovations, Renogy, Goal Zero, BigBlue, RAVPower, EcoFlow, Voltaic Systems, Powertraveller, BioLite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Phone Chargers Market Trends and Innovations
Material science breakthroughs and regulatory disclosure mandates are simultaneously compressing production costs and elevating compliance thresholds across portable solar device manufacturing.
Perovskite-coated silicon tandem architecture is absorbing incremental investment from photovoltaic research consortia and venture-backed cell manufacturers. Alpine expedition outfitters and ultralight gear specialists are adopting these cells for gram-critical applications despite early-stage durability concerns. The technology is absorbing market share from traditional monocrystalline panels in sub-100-gram product categories where energy density outweighs absolute longevity.
REACH substance restrictions and EU Green Deal extended producer responsibility frameworks are mandating recyclable packaging and repairable product architectures. Battery pack designs must now accommodate cell replacement without specialized tooling, reshaping mechanical engineering roadmaps. German outdoor retail chains are prioritizing SKUs with documented end-of-life take-back programs, filtering shelf access for non-compliant imports.
Direct-to-consumer channel expansion is displacing traditional outdoor retail intermediaries for technical solar accessories. Specialty e-commerce platforms and manufacturer-owned storefronts are capturing educated buyers who research efficiency specifications independently. This behavioral shift concentrates most visibly in Germany, where digitally native vanlife communities and trekking forum influencers drive purchase decisions through peer-validated technical reviews rather than in-store merchandising.
Solar Phone Chargers Market Segmentation
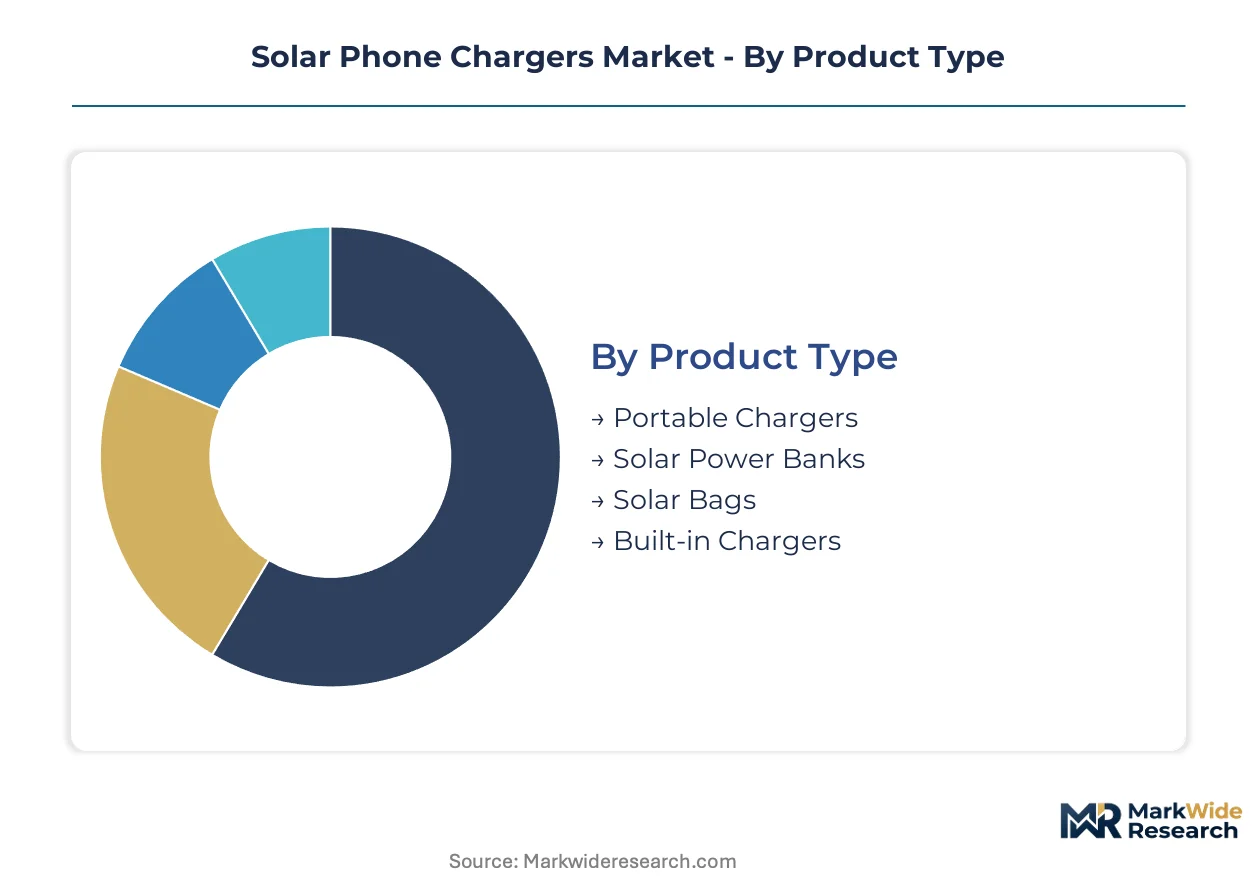
Segmentation in the solar phone charger market reveals how photovoltaic engineering, use-case intensity, and buyer sophistication create distinct commercial territories. Understanding these divides helps manufacturers align cell chemistry, form factor durability, and distribution channel selection with actual purchasing behavior rather than assumed demographics.
Product Type:
Physical configuration determines power output capacity, weather sealing requirements, and retail channel placement across portable solar devices.
- Portable Chargers:Standalone foldable panels with integrated USB outputs dominate mass-market outdoor retail. Demand concentrates in German trekking communities where gram efficiency governs purchasing decisions alongside documented IPX ratings.
- Solar Power Banks:Hybrid units combining photovoltaic input with lithium-polymer storage serve users requiring charge continuity beyond daylight hours. Alpine rescue services in Austria and Switzerland specify these for mandatory emergency gear lists.
- Solar Bags:Photovoltaic fabric integration into backpacks targets urban commuters and festival attendees prioritizing convenience over conversion efficiency. Urban mobility planners in Copenhagen and Amsterdam pilot these for municipal bike-share maintenance crews.
- Built-in Chargers:Factory-integrated solar modules in phone cases or specialty devices occupy niche positioning. Repairability index compliance in France limits adoption due to non-replaceable cell architectures.
Mature deployment sits with portable chargers. Newer deployment is concentrated in solar power banks.
Technology:
Cell architecture selection trades conversion efficiency against manufacturing cost, weight constraints, and supply chain certification burdens.
- Monocrystalline:Single-crystal silicon wafers deliver the highest energy density per square centimeter in compact form factors. German outdoor retail chains prioritize SKUs with documented monocrystalline specifications for shelf placement.
- Polycrystalline:Multi-crystal silicon construction offers moderate efficiency at reduced unit cost. Budget-conscious general consumers in Eastern European markets drive residual demand despite bulkier panel dimensions.
- Thin-film:Cadmium telluride or copper indium gallium selenide deposition enables sub-100-gram designs where absolute longevity is secondary to packability. Ultralight specialists in the Scottish Highlands and Norwegian fjord regions specify these for expedition-grade reliability.
- Integrated:Perovskite-silicon tandem architectures are absorbing incremental venture investment for next-generation portable applications. Laboratory-to-fab transfer remains constrained by moisture sensitivity and encapsulation challenges.
Conversion efficiency leadership belongs to monocrystalline. Thin-film configurations are expanding most quickly in gram-critical segments.
Application:
Use-case intensity shapes durability specifications, battery redundancy requirements, and buyer education levels across distribution channels.
- Camping:Multi-day wilderness exposure demands weather-sealed construction and foldable geometries for pack transport. Scout associations in Sweden and Finland standardize solar redundancy in youth program equipment lists.
- Outdoor Activities:Day-trip hiking and cycling applications prioritize rapid deployment and clip-on mounting systems. Norwegian national park visitor centers stock these for tourist rental programs.
- Emergency Backup:Disaster preparedness kits require stored charge capability and ruggedized housing for extended shelf life. Civil defense tenders in Germany and Austria specify standardized renewable backup systems.
- Everyday Use:Window-sill trickle charging and occasional outdoor access define this casual segment. Urban eco-conscious shoppers in Copenhagen and Vienna drive volume through direct-to-consumer channels.
Institutional procurement anchors emergency backup deployment. Vanlife builders and off-grid professionals are driving the steepest expansion trajectory in camping applications.
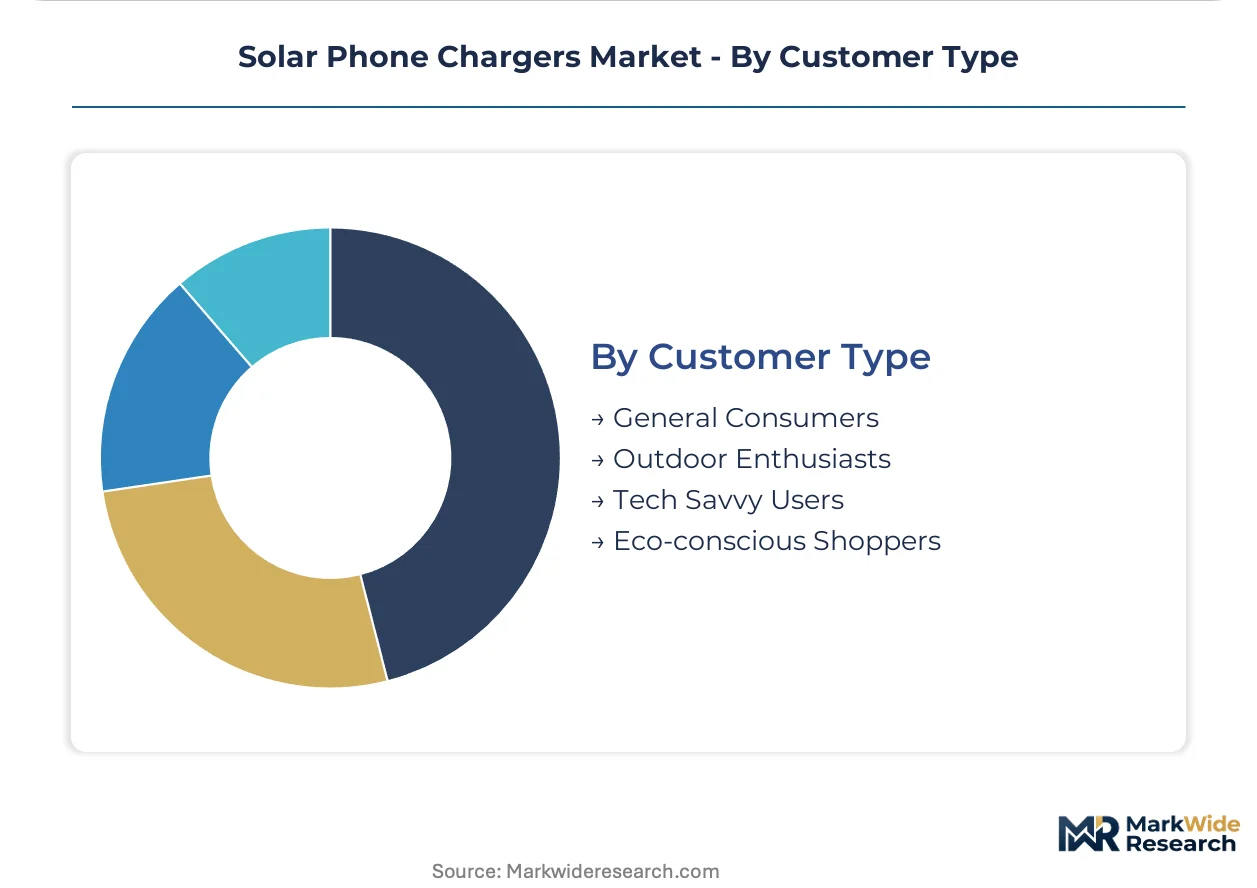
Customer Type:
Technical literacy and environmental motivation create distinct pricing tolerances and specification research behaviors.
- General Consumers:Price-sensitive buyers purchasing through mass retail or marketplace platforms with limited efficiency specification awareness. German electronics discounters capture this segment through promotional bundling.
- Outdoor Enthusiasts:Experienced trekkers and climbers researching wattage ratings, weight specifications, and weatherproofing independently. Forum-validated peer recommendations in German-language hiking communities drive brand selection.
- Tech Savvy Users:Early adopters tracking perovskite commercialization and USB Power Delivery protocol compatibility. These buyers concentrate in Berlin and Munich startup ecosystems.
- Eco-conscious Shoppers:Sustainability-motivated purchasers prioritizing repairability indices, recyclable packaging, and documented end-of-life take-back programs. French repairability scoring requirements filter shelf access for competing products.
Volume concentration rests with general consumers. Tech savvy users and eco-conscious shoppers are gaining share fastest as regulatory disclosure mandates elevate specification transparency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free economic zones in Shenzhen and Hamburg concentrate photovoltaic assembly capacity for portable electronics. These designated areas attract duty-exempt component imports and streamlined customs processing. Manufacturers cluster near these nodes to minimize landed costs for lithium-polymer cells and silicon wafers.
Germany
Alpine rescue services and national park authorities drive institutional procurement of ruggedized solar power banks. The EU Ecodesign for Sustainable Products Regulation mandates material passports and recyclability disclosures for all portable electronics sold in member states. Outdoor retail chains in Munich and Frankfurt prioritize SKUs with documented end-of-life take-back programs, filtering shelf access for compliant brands.
United States
Disaster preparedness kit standardization by FEMA and state emergency management agencies creates B2G procurement channels for stored-charge solar systems. FCC Part 15 electromagnetic emissions certification extends product launch timelines by four to six months for cross-border entrants. Vanlife builders and off-grid professionals in the Pacific Northwest specify higher-wattage foldable arrays for sustained device charging without shore power.
China
Cathode precursor refining clusters in Hunan and Fujian provinces supply lithium-polymer cells to downstream portable charger assemblers. MIIT standards for battery safety and GB certification requirements govern domestic market entry. Shenzhen-based contract manufacturers dominate mass-market production, leveraging vertically integrated supply chains for USB Power Delivery modules and wireless charging coils.
France
Repairability index requirements under French consumer protection law reward modular architectures with replaceable cells and connectors. The country's national pharmaceutical regulator has no direct jurisdiction, but ANSM guidelines on electromagnetic compatibility influence adjacent medical device standards. Paris and Lyon host specialty e-commerce platforms capturing eco-conscious shoppers prioritizing documented sustainability credentials.
Austria
Civil defense tenders for standardized renewable backup systems create institutional procurement pull for emergency-grade solar chargers. REACH substance restrictions and RoHS compliance burdens filter out sub-scale entrants from Eastern European markets. Alpine trekking associations in Tyrol and Salzburg standardize solar redundancy in mandatory gear lists, creating peer-validated demand concentration.
Solar Phone Chargers Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated battery suppliers commanding mass-market retail while ruggedized design houses anchor expedition-grade positioning. The vendor base organizes around three strategic archetypes: mass-market electronics brands leveraging supply chain scale, outdoor-specialist manufacturers emphasizing weatherproofing certifications, and emerging perovskite cell developers pursuing laboratory-to-fab commercialization. Competitive moves concentrate on M&A activity targeting thin-film deposition capabilities and strategic partnerships with alpine rescue services for institutional procurement validation.
Within the mass-market tier, Anker Innovations and RAVPower represent scale-driven positioning through captive battery supply chains and retail channel density. Among outdoor-specialist fabricators, Goal Zero and BioLite exemplify expedition-grade reliability positioning through ruggedized housing designs and IPX weatherproofing certifications. Renogy occupies a position bridging professional off-grid applications with consumer vanlife builds, anchoring the higher-wattage foldable array segment. These three archetypes—mass-market scale, outdoor durability, and professional off-grid—structure competitive differentiation across price and performance tiers.
| Leading Market Players |
|---|
| Anker Innovations |
| Renogy |
| Goal Zero |
| BigBlue |
| RAVPower |
| EcoFlow |
| Voltaic Systems |
| Powertraveller |
| BioLite |
| Others |
Pricing and Supply Chain Analysis
German outdoor retail chains and Austrian alpine rescue services concentrate procurement volume, anchoring a contract-based pricing model where expedition-grade certifications command substantial premiums over mass-market alternatives. This buyer concentration grants certified manufacturers pricing power while filtering uncertified imports from shelf placement.
Pricing Analysis
Expedition-grade lead times stretching six-plus months for RoHS and REACH certified production runs command premium positioning, while spot inventory from Shenzhen contract manufacturers trades at compressed margins. Pricing stratifies across premium, standard, and economy tiers based on IPX weatherproofing certification level and monocrystalline cell efficiency ratings. Cost compression in the economy tier is intensifying because polycrystalline alternatives from Eastern European assemblers flood marketplace channels. General consumers purchasing through electronics discounters exhibit acute price sensitivity, whereas alpine rescue procurement committees prioritize reliability specifications over unit cost.
Supply Chain Analysis
Lithium-polymer cell supply rests on cathode precursor refining clusters in China's Hunan and Fujian provinces, with silicon wafer slicing concentrated in Jiangsu and Zhejiang manufacturing hubs. Photovoltaic assembly draws from monocrystalline ingot production in Malaysia and Vietnam, while thin-film deposition equipment sources from Japanese specialty machinery producers. Single-source vulnerability pervades the lithium-polymer cell tier, where Hunan province disruptions cascade through downstream portable charger assemblers. Distribution runs through Hamburg free economic zones for European market entry, with Shenzhen duty-exempt zones serving Asia-Pacific and North American channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around compliant supply chains as EU Ecodesign material passport mandates force sub-scale brands toward exit. Regulatory compliance burdens now function as competitive moats favoring established players with certified manufacturing footprints.
For Market Incumbents: Deploy backward integration into lithium-polymer cell sourcing to secure supply continuity against Hunan province concentration risk. Incumbents should anchor market position through exclusive alpine rescue service partnerships that institutionalize procurement pull, while investing in perovskite-silicon tandem R&D to outpace thin-film competitors on conversion efficiency metrics.
For New Entrants and Emerging Players: Begin with modular repairable architectures targeting French repairability index compliance as a differentiated entry wedge. New entrants should prioritize vanlife builder communities in Germany's direct-to-consumer channels, where peer-validated technical reviews reduce traditional retail gatekeeper dependence. A sustainability credentialing go-to-market angle captures eco-conscious shopper segments underserved by incumbent mass-market positioning.
For Investors and Strategic Acquirers: The window for entry favors thin-film deposition specialists with laboratory-to-fab commercialization pipelines. Long-term viability hinges on perovskite encapsulation breakthroughs resolving moisture sensitivity constraints. Acquisition targets should demonstrate existing alpine rescue or civil defense procurement relationships. The signal to watch is EU Ecodesign enforcement intensity accelerating brand consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Perovskite-Silicon Tandem Commercialization | Laboratory transfer of vapor-deposited layers trims production costs for gram-critical portable applications. |
| EU Ecodesign Compliance Certification | Material passport documentation secures shelf access with Munich and Frankfurt outdoor retail chains. |
| Alpine Rescue Service Partnership | Institutional procurement validation from Austrian and Swiss rescue services creates mandatory gear list inclusion. |
| Modular Repairable Architecture Development | French repairability index scoring differentiates premium positioning against sealed-unit competitors. |
| Direct-to-Consumer Channel Expansion |
Research Methodology
Document review covered EU Ecodesign regulatory filings, FCC Part 15 certification databases, and alpine rescue equipment procurement tenders, complemented by interviews with outdoor retail category buyers, lithium-polymer cell procurement managers, and thin-film photovoltaic research directors. Secondary validation drew from customs trade data, RoHS compliance registries, and extended producer responsibility framework disclosures. Bottom-up segment sizing triangulated against top-down market value reconstruction across portable charger, solar power bank, and solar bag product configurations.
Unit shipment and value projections emerged from multi-dimensional modeling across technology type, application intensity, and customer sophistication segments throughout the forecast period. The analytical framework incorporated perovskite commercialization timelines, REACH substance restriction phase-ins, and right-to-repair legislative adoption curves as industry-specific forecast inputs. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion constraints.
Underlying measurement precision varies by segment; emergency backup and vanlife camping applications carry tighter precision than everyday use casual purchasing due to institutional procurement data availability. Forecasts reflect documented assumptions regarding perovskite encapsulation resolution and EU regulatory enforcement intensity. Supply chain disruption in Hunan province refining clusters, perovskite moisture sensitivity failures, and accelerated right-to-repair adoption represent specific risk factors that could revise projections. A small set of regulatory enforcement triggers and technology commercialization milestones warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
South America Rooftop Solar Market
Solar Power Systems
Tubular Solar Collector Market
Solar Power Systems
Global Solar Power Windows Market
Solar Power Systems
Solar Power Market
Solar Power Systems
China Distributed Solar Power Generation Market
Solar Power Systems
United States Distributed Solar Power Generation Market
Solar Power Systems
Thin Film Solar PV Market
Solar Power Systems
Graphene Solar Cell Market
Solar Power Systems
Solar Updraft Tower Market
Solar Power Systems
Thin Film Photovoltaic Sales Market
Solar Power Systems
Solar Power Meters Market
Solar Power Systems
Greece Solar Energy Market
Solar Power Systems
Solar Photovoltaics Wafer Market
Solar Power Systems
Portugal Solar Energy Market
Solar Power Systems
Solar Shingles Market
Solar Power Systems
Polycrystalline Solar Cell Market