
 Solar Reflective Glass Market | 2026-2036
Solar Reflective Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Reflective Glass Market Intelligence
Production capacity for high-performance coated glass in China is expanding to meet domestic and export demand. Saint-Gobain leverages its extensive R&D in thin-film coatings to offer premium low-emissivity products. AGC Inc. competes through its global manufacturing footprint and strong relationships with architectural firms. These firms anchor the high-performance segment of the market.
Solar reflective glass is a type of float glass with a metallic oxide coating that reflects a significant portion of solar radiation. This coating, often applied through sputtering or chemical vapor deposition, reduces solar heat gain while allowing visible light to pass. Coated glass products represent the largest segment, driven by new construction codes. The commercial buildings application continues to dominate, as architects specify these materials to improve energy performance.
Building energy codes and standards, such as those influenced by the US EPA and the EU's Green Deal, shape market requirements. ISO standards for glass in building provide a baseline for performance and safety testing. These regulations compel architects and contractors to specify materials that reduce cooling loads. The key decision for manufacturers will be optimizing the trade-off between solar reflectance and visible light transmission.
Market Dynamics
The central force shaping the solar reflective glass market is the global regulatory mandate for building decarbonization. Frameworks like the EU Green Deal and China's dual carbon goals are embedding energy efficiency into construction codes, making high-performance glazing a non-negotiable specification.
Growth Catalysts
- Stringent Building Codes:National policies, including China's dual carbon goals and India's Energy Conservation Building Code, are mandating lower energy consumption in new construction, directly increasing specifications for solar control glass.
- Commercial Construction Focus:The commercial building sector's pursuit of green certifications like LEED and BREEAM requires materials that reduce cooling loads, solidifying demand for advanced glazing solutions.
- Energy Performance Contracts:The adoption of contracts where building energy savings are guaranteed incentivizes developers and owners to invest in higher-performing building envelope components, including solar reflective glass.
Market Restraints
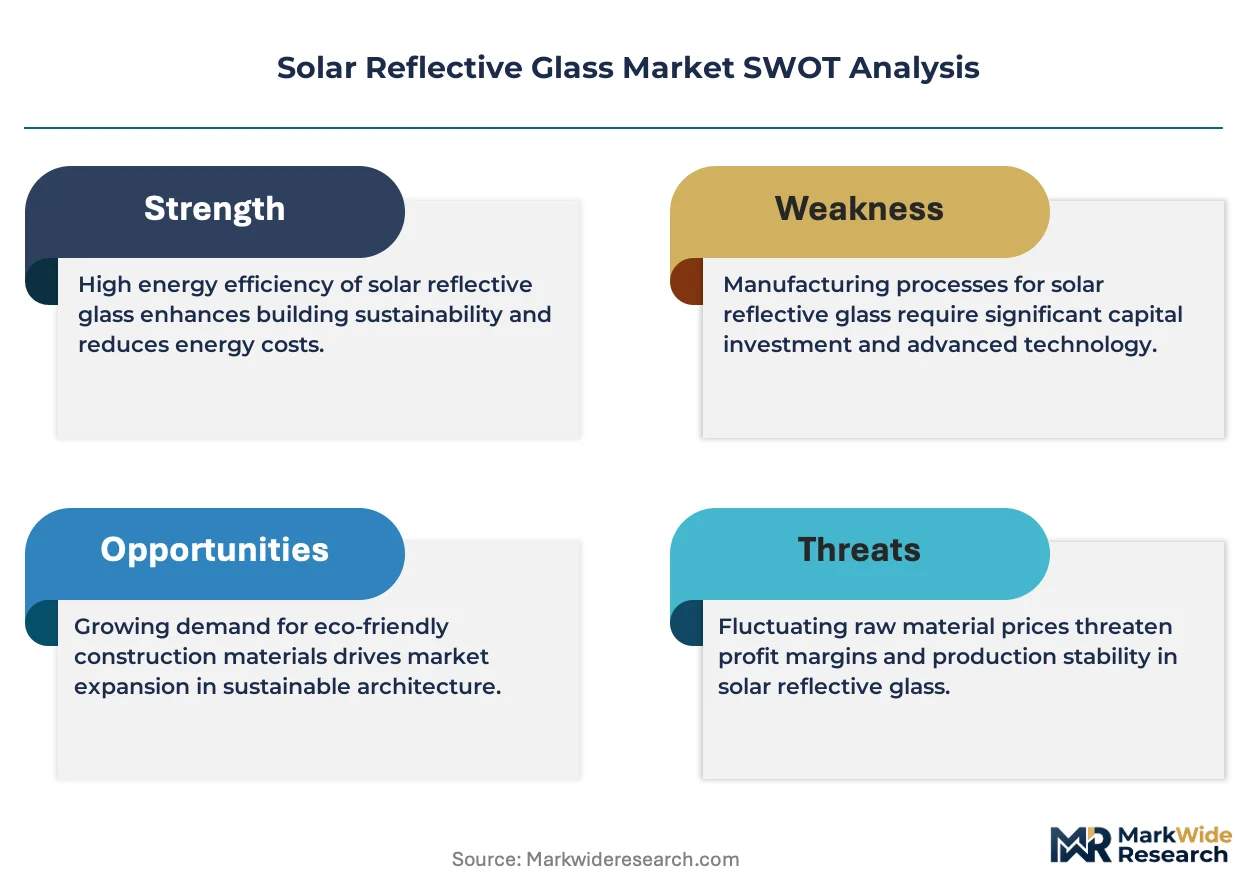
- Higher Initial Cost:The premium price of coated glass compared to standard float glass remains a significant barrier for budget-constrained construction projects, particularly in the residential sector.
- Performance Trade-offs:A fundamental technical limitation is the inverse relationship between high solar reflectance and high visible light transmission, challenging manufacturers to optimize products for both energy savings and occupant comfort.
- Raw Material Price Volatility:The cost and availability of specific metallic oxides, such as silver and titanium, used in sputter coating processes are subject to market fluctuations, impacting production costs.
Strategic Opportunities
- Building Retrofit Market:Upgrading the glazing in existing commercial buildings to comply with new energy performance standards represents a vast, underpenetrated market, particularly in Europe and North America.
- Dynamic Glazing Integration:The development of electrochromic and thermochromic technologies, which allow glass to change its tint and reflective properties on demand, offers a path to next-generation, premium products.
- Expansion in Tropical Climates:Markets in Southeast Asia, Latin America, and the Middle East with high cooling demand and modernizing building codes present significant growth potential for solar control solutions.
Industry Challenges
- Capital-Intensive Production:The high capital expenditure required to establish and maintain advanced sputtering or chemical vapor deposition (CVD) coating lines limits new market entrants and constrains capacity expansion.
- Complex Certification Pathways:Navigating the diverse and evolving landscape of international and regional building energy codes, such as those based on ISO standards, creates compliance burdens and extends time-to-market.
- Skilled Labor Scarcity:A shortage of technicians and engineers with expertise in thin-film coating processes and quality control for high-performance glass can hinder production efficiency and innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Reflective Glass Market |
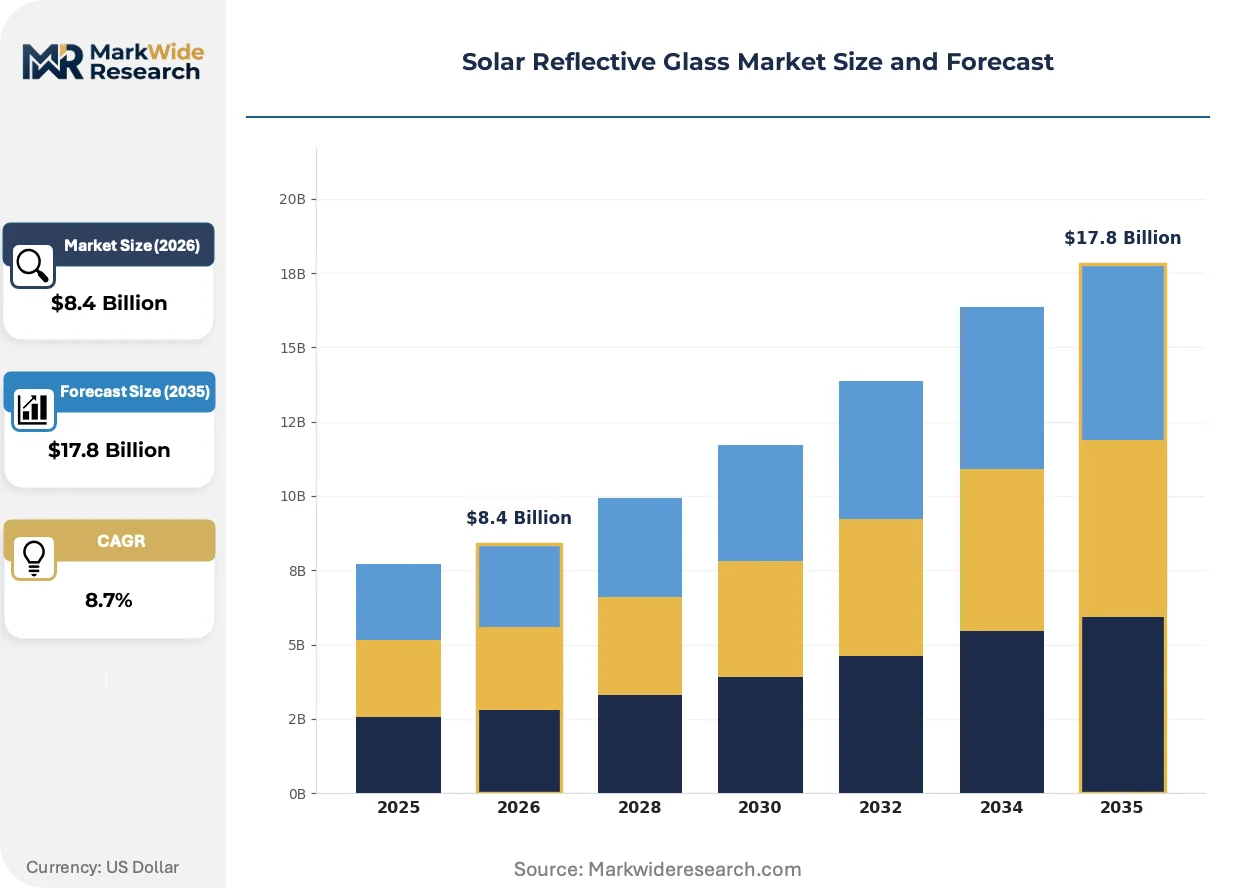
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $17.8 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-Emissivity Glass, Coated Glass, Laminated Glass, Tempered Glass Application: Commercial Buildings, Residential Buildings, Automotive, Solar Energy Systems End User: Architects, Contractors, Manufacturers, Energy Providers Distribution Channel: Direct Sales, Online Retail, Wholesalers, Specialty Stores |
| Companies Covered | Saint-Gobain, Guardian Glass, AGC Inc., NSG Group, PPG Industries, Schott AG, Viracon, Kibing Group, Xinyi Glass, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Reflective Glass Market Strategic Shifts & Innovations
Product innovation is converging with stringent building energy regulations, pushing the market toward multifunctional glazing. The emphasis is shifting from simple solar reflection to sophisticated, wavelength-specific light and heat management, redefining performance benchmarks for the architectural glass industry.
Spectrally selective coatings represent a significant product evolution, designed to filter infrared and ultraviolet radiation while maximizing visible light. Architects and developers of premium commercial towers are rapidly adopting these advanced coatings to enhance both energy efficiency and indoor environmental quality. This advanced functionality is absorbing the market share of older-generation reflective glass, which offered less precise control over the solar spectrum.
The European Union's Green Deal is a powerful regulatory driver, establishing ambitious targets for building energy efficiency and carbon reduction across the continent. This policy directly compels the use of high-performance materials in both new construction and major renovations to meet stricter Energy Performance of Buildings Directive (EPBD) requirements. Consequently, the commercial building segment in EU member states is accelerating its transition from standard glazing to advanced low-emissivity and solar control glass products.
Specification criteria are evolving as project stakeholders prioritize whole-building lifecycle performance over singular, upfront component costs. This trend shifts decision-making influence from cost-focused contractors toward energy consultants and architects who model long-term operational savings. The shift is most pronounced in North American and European projects pursuing green building certifications, where the glass specification is integral to achieving energy credits.
Solar Reflective Glass Market Segmentation
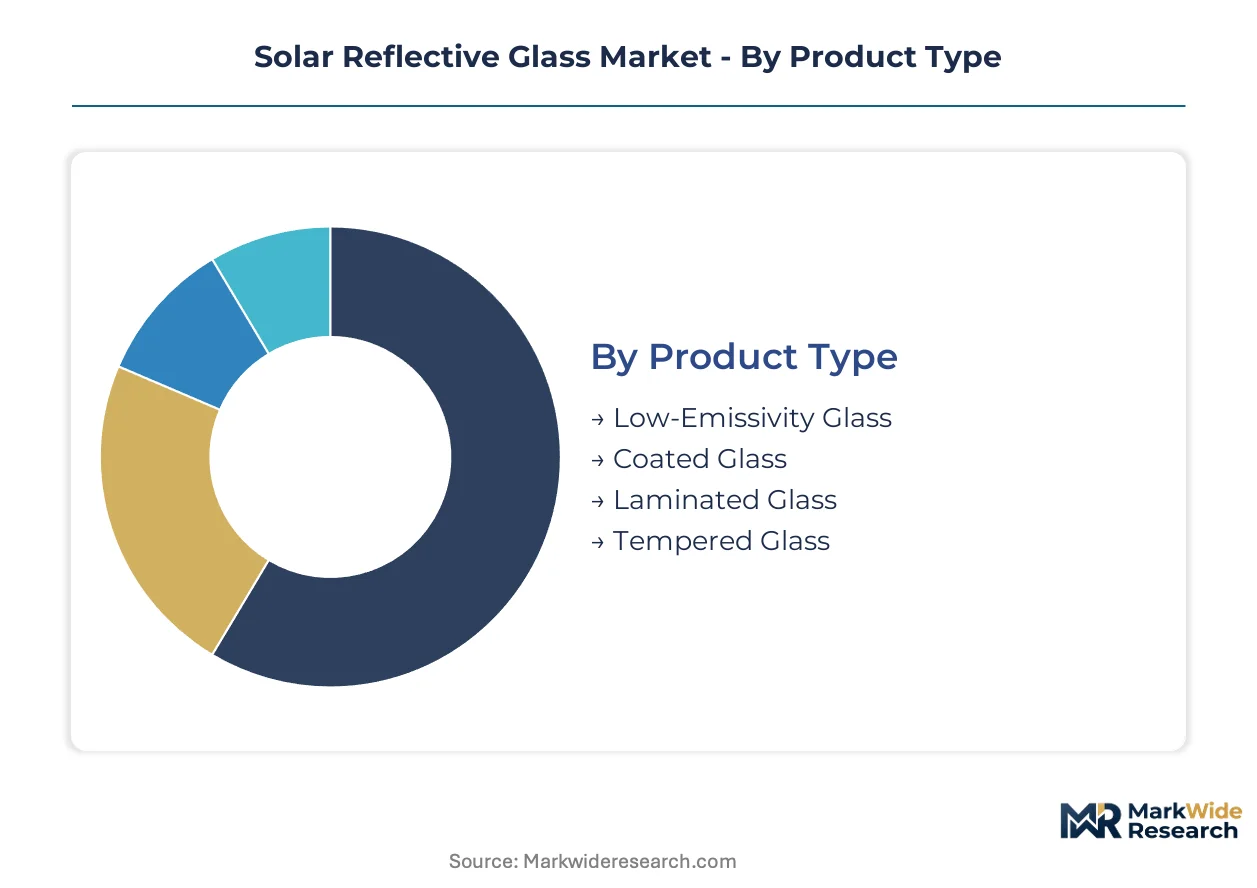
The segmentation of the solar reflective glass market reveals critical insights into product adoption patterns, end-user preferences, and strategic distribution pathways. Understanding these distinct segments helps manufacturers align their offerings with evolving demand drivers and regulatory mandates across different applications.
Product Type:
The solar reflective glass market categorizes products by their inherent properties and how they integrate into larger building or automotive systems.
- Coated Glass:This float glass features a metallic oxide coating, often applied through sputtering or chemical vapor deposition, which significantly reduces solar heat gain. Demand concentrates in new commercial construction projects, where strict building codes mandate enhanced energy performance, particularly in China.
- Low-Emissivity Glass:Characterized by ultra-thin metallic oxide layers, this glass primarily reflects infrared radiation, reducing heat transfer while allowing visible light. Regulations like the EU Green Deal and US EPA standards drive its adoption in green-certified buildings, enhancing thermal insulation properties.
- Laminated Glass:Comprising two or more glass panes bonded by an interlayer, this product offers enhanced safety and sound insulation. Its use is prevalent in applications requiring increased security and acoustic performance.
- Tempered Glass:Produced through controlled thermal or chemical treatments, this glass is significantly stronger than standard glass and shatters into small, blunt fragments for safety. It is specified for safety-critical installations in facades and balustrades.
Volume placements concentrate in Coated Glass; the faster expansion belongs to Low-Emissivity Glass.
Application:
Applications for solar reflective glass range from large-scale commercial projects to specialized energy systems, reflecting diverse volume requirements.
- Commercial Buildings:This segment includes office towers, retail complexes, and institutional structures, where large glass facades necessitate superior solar control for energy efficiency. Green building certifications like LEED and BREEAM solidify demand in major urban centers globally.
- Solar Energy Systems:This application involves using solar reflective glass in photovoltaic panels and concentrated solar power (CSP) installations to maximize energy capture and efficiency. Renewable energy targets in countries like India and Germany drive significant material specification.
- Residential Buildings:Solar reflective glass is integrated into windows and doors for homes, aiming to reduce cooling loads and improve indoor comfort. Cost sensitivity often influences material selection in this segment.
- Automotive:Used in vehicle windshields, side windows, and sunroofs, this glass helps manage cabin temperature and enhances occupant comfort by reducing solar heat penetration.
Commercial Buildings continue to dominate demand for solar reflective glass, while Solar Energy Systems exhibit significant growth potential.
End User:
End users for solar reflective glass vary significantly in their purchasing influence and technical specification requirements.
- Architects:These professionals specify solar reflective glass based on aesthetic, performance, and sustainability criteria for building designs. Their influence is paramount in projects pursuing green certifications in North America and Europe.
- Manufacturers:This group integrates solar reflective glass into finished products such as insulated glazing units, window systems, or solar panels. They focus on consistent quality and supply chain reliability.
- Contractors:Responsible for procurement and installation, contractors balance project budgets with specified performance requirements. Their purchasing decisions often influence the final product choice on a construction site.
- Energy Providers:Utilities and independent power producers use solar reflective glass in large-scale solar energy generation projects, prioritizing long-term performance and efficiency metrics.
Architects hold primary influence over initial product specification, with Manufacturers gaining importance through integrated solutions.
Distribution Channel:
The distribution channels for solar reflective glass reflect varying levels of direct engagement and supply chain complexity.
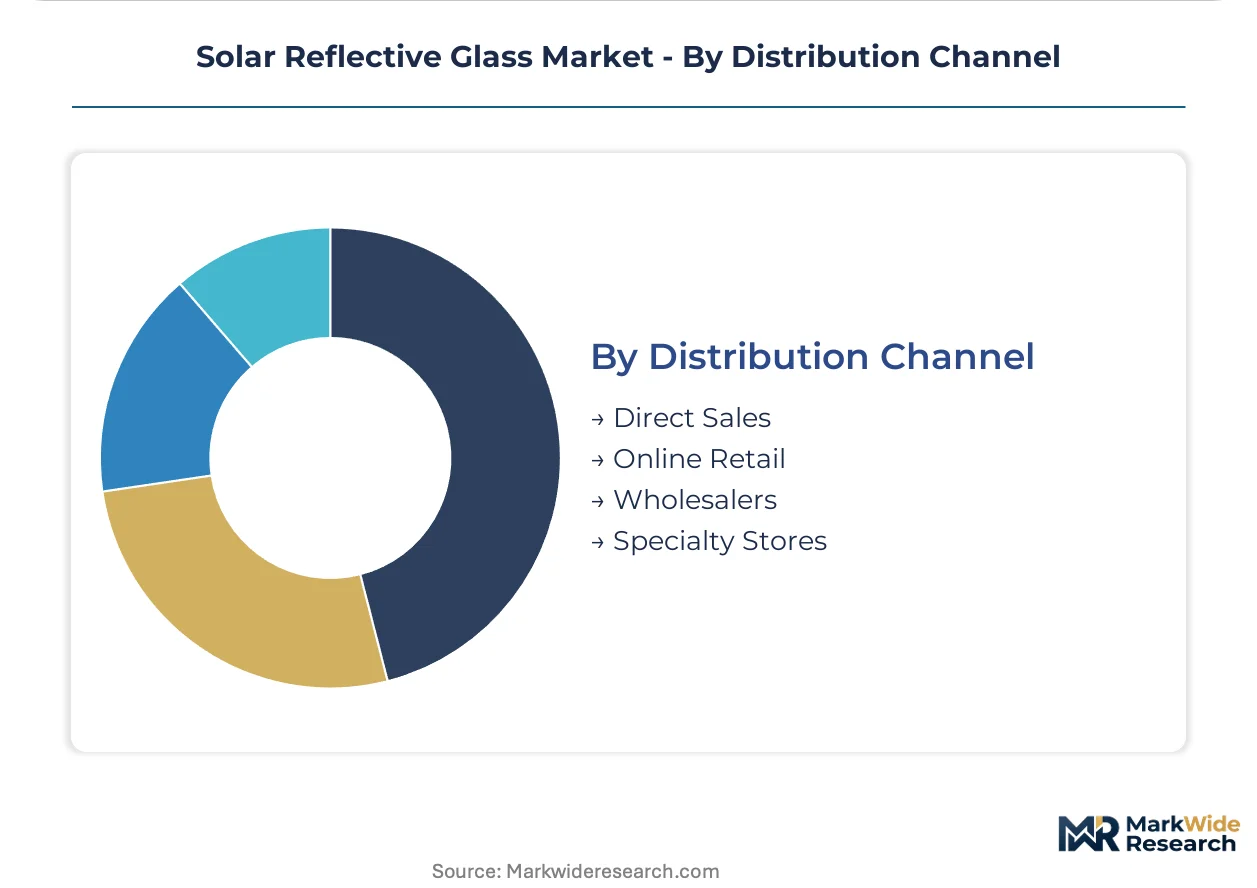
- Direct Sales:This channel involves manufacturers selling directly to large-scale commercial developers or architectural firms for major projects. It enables custom specifications and direct technical support for complex installations.
- Wholesalers:Wholesalers purchase solar reflective glass in bulk from manufacturers and distribute it to smaller contractors, fabricators, and local retailers. They provide logistical support and inventory management for regional markets.
- Online Retail:This channel facilitates the purchase of specialized or smaller quantities of solar reflective glass, often catering to niche markets or individual renovation projects. It offers convenience and broad product access.
- Specialty Stores:These outlets focus on high-end architectural glass products, offering custom cutting, fabrication, and expert advice for bespoke building projects. They serve a discerning clientele with unique requirements.
Direct Sales channels ensure efficient delivery for major projects, while Wholesalers enhance market accessibility for diverse customer bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global solar reflective glass market's regional dynamics are significantly influenced by localized raw material availability, particularly in regions with established float glass production. These production hubs often align with major construction markets, driving both supply and demand for advanced glazing solutions. Stringent energy efficiency regulations further concentrate market activity in key countries.
China
China's robust new commercial construction sector drives substantial demand for solar reflective glass, fueled by rapid urbanization. The country's dual carbon goals and GB standards mandate lower building energy consumption. The Yangtze River Delta region sees extensive adoption of high-performance glass in new skyscrapers.
India
India's expanding commercial building sector and significant solar energy projects create strong demand for advanced glazing solutions. The Energy Conservation Building Code (ECBC) and PLI scheme promote energy-efficient materials. Major metropolitan areas like Mumbai and Bengaluru integrate solar reflective glass into modern office complexes.
United States
The United States market is propelled by green building certifications like LEED and a growing retrofit segment. US EPA standards and IRA incentives encourage investment in energy-efficient building envelopes. Commercial developments in New York and Chicago prioritize spectrally selective glazing for energy credits.
Germany
Germany's market benefits from stringent building energy codes and a strong national focus on sustainability. The EU Green Deal and EPBD compel the use of advanced materials. Major urban centers like Berlin and Munich showcase low-emissivity and solar control glass in new and renovated structures.
United Arab Emirates
The United Arab Emirates experiences high demand for solar reflective glass due to intense cooling requirements and ambitious architectural projects. Local green building codes and sustainability initiatives drive material specifications. Iconic structures in Dubai and Abu Dhabi extensively use solar reflective glass to manage solar heat gain.
Solar Reflective Glass Market Key Industry Players
Global majors compete with regional champions across product innovation and market reach in the solar reflective glass market. The market exhibits a tiered structure, with a few large integrated manufacturers alongside numerous specialized fabricators. Strategic archetypes include technology-driven premium providers and cost-efficient volume producers. Dominant competitive moves involve capacity expansion to meet regional demand and strategic partnerships with architectural firms.
On the premium-tier vector, Saint-Gobain leverages its extensive R&D in thin-film coatings to offer advanced low-emissivity products for demanding architectural specifications. AGC Inc. occupies a position as a global manufacturer with a strong network of architectural relationships, serving diverse project needs across multiple continents. NSG Group also exemplifies a large-scale producer, maintaining a broad global manufacturing footprint to supply various construction markets worldwide. These companies collectively anchor the high-performance segment, focusing on sophisticated glazing solutions for commercial applications and green building initiatives globally.
| Leading Market Players |
|---|
| Saint-Gobain |
| Guardian Glass |
| AGC Inc. |
| NSG Group |
| PPG Industries |
| Schott AG |
| Viracon |
| Kibing Group |
| Xinyi Glass |
| Others |
Cost & Logistics Intelligence
Metallic oxide raw material costs significantly influence the production of solar reflective glass, flowing through sputtering processes to impact the final pricing tiers for commercial building projects. High energy consumption during manufacturing further adds to the cost burden, which is then reflected in the premium segment of the market.
Pricing Analysis
Warranty and service bundling often differentiate premium solar reflective glass products, offering architects comprehensive support beyond the basic material. Pricing follows a project-based model for large commercial installations, moving to per-unit transactional for smaller residential applications. Price differentiation hinges on performance specifications like U-value and solar heat gain coefficient, alongside brand reputation and customization levels. Pricing softness affects standard float glass due to intense competition, while specialized low-emissivity products maintain higher margins. The residential sector exhibits the highest price sensitivity, contrasting with commercial developers prioritizing long-term energy savings.
Supply Chain Analysis
Certification and qualification gating mechanisms significantly influence the solar reflective glass supply chain, ensuring product adherence to strict building codes. Geographic supply concentrates in China, driven by extensive float glass production, and Germany for specialized coating technologies. The industry depends on specific metallic oxides like silver and titanium, alongside high-purity silica sand, as key raw material inputs. Raw material price volatility represents a structural supply chain risk, impacting production costs for coated glass manufacturers. Distribution runs through direct sales channels for major architectural projects, with wholesalers serving smaller contractors and regional markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solar reflective glass market increasingly represents a vertical-integration race, with major players pursuing upstream control over thin-film coating technologies to secure competitive advantage.
For Market Incumbents:
Extend R&D investments into advanced dynamic glazing solutions to counter the threat of commoditization in standard coated glass. Consolidate market share through strategic acquisitions of specialized coating technology firms, particularly those focused on spectrally selective performance. Invest in capacity expansion in key growth regions like Southeast Asia to meet escalating demand from new construction codes. Leverage strong architectural relationships to influence early-stage project specifications and drive adoption of premium products.
For New Entrants and Emerging Players:
Begin with niche applications, targeting the underserved residential retrofit market with cost-effective, easy-to-install solar control films. Focus on underpenetrated tropical climates in Latin America and the Middle East where cooling demand is paramount. The most penetrable segment lies within mid-tier commercial projects in rapidly urbanizing regions that prioritize energy efficiency without premium budgets. Partner with local fabricators and installers to establish regional distribution networks and provide tailored solutions for diverse building types.
For Investors and Strategic Acquirers:
Widespread adoption of spectrally selective coatings in major urban developments is the leading indicator that signals sustained long-term growth in the high-performance glazing segment. The market exhibits strong viability over the next decade, driven by global decarbonization mandates and green building certifications. Acquisition targets should include mid-cap manufacturers with proprietary thin-film coating expertise or strong regional market presence in emerging economies. Monitor the integration rate of smart glass technologies as a key inflection signal for future premium product categories.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asia | Meets the rising demand from China and India's new construction projects. |
| R&D Investment in Dynamic Glazing | Differentiates products and captures the premium segment for advanced architectural designs. |
| Strategic Partnerships with Architects | Influences material specifications early in the building design and construction lifecycles. |
| Backward Integration into Metallic Oxides | Secures supply chains and mitigates raw material price volatility for coating production. |
| Certification for New Building Codes | Ensures market access and compliance in regions with stringent energy performance regulations. |
Research Approach
Document review covered building energy codes from the EU Green Deal and US EPA, ISO standards for glass in building, and company financial reports, complemented by interviews with architects, glass manufacturers, and coating specialists. This approach combined primary insights with secondary validation, employing both bottom-up market sizing and top-down validation to ensure accuracy and comprehensive coverage.
Historical market data was cross-referenced with expert panel input across the analysis window to project future market trends and growth trajectories. The analytical framework modeled market segmentation across product type, application, end user, distribution channel, and regional adoption patterns. Compound annual growth rates were derived through regression analysis and validated against industry-specific forecast inputs, including construction spending and regulatory policy implementation rates.
Underlying measurement precision varies by segment; commercial buildings and coated glass carry tighter precision than others due to established reporting structures. Forecasts reflect assumptions regarding the continued enforcement of energy efficiency regulations and sustained growth in the global construction sector. Raw material price fluctuations and geopolitical uncertainties represent specific risk factors that could revise these forecasts. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Sapphire Glass Market
Glass
Flexible Glass Market
Glass
Tempered Glass Market
Glass
Glass Mat Market
Glass
Technical Glass Market
Glass
France Silica Sand Market
Glass
Heat Resistant Glass Market
Glass
Global Energy Efficient Glass Market
Glass
Cellular Glass Market
Glass
3D Glass Market
Glass
Glass Grade Dolomite Market
Glass
Double Glazing Glass Market
Glass
3D Glass Substrate Market
Glass
Crystalware and Glassware Market
Glass
Glass Insulator Market
Glass
Global Ultra-Thin Glass Market