
 Crystalware and Glassware Market | 2026-2036
Crystalware and Glassware Market Size, Share, and Industry Trends Forecast 2026-2036
Crystalware and Glassware Market Analysis
Artisan glassblower availability is rotating toward scarcity in traditional European production clusters, constraining hand-finished crystal output and pushing automated borosilicate lines into premium-adjacent tiers. WMF Group leverages its German metallurgical heritage to dominate hotel procurement channels across the Middle East. Libbey Inc anchors North American foodservice volume through mass-market tumblers and serving lines. Schott Zwiesel AG differentiates via patented Tritan crystal technology that eliminates lead while maintaining refractive clarity.
Crystalware and glassware comprise vessels, serveware, and decorative objects fabricated from silica-based melts, with lead crystal achieving refractive indices above 1.54 through lead oxide doping and borosilicate glass tolerating thermal shock up to 165°C differential for oven-to-table applications. Wine glasses command the highest margin pool within product type segmentation, driven by sommelier-grade stemware programs in Michelin-tier restaurants. Borosilicate glass represents the fastest-expanding material category as health-conscious consumers and commercial buyers displace lead crystal from daily-use contexts. Household end users sustain volume leadership, though hotel procurement channels generate superior per-unit profitability through custom branding and replacement-cycle contracts.
EU REACH regulations restrict lead oxide content in consumer-contact crystal, compelling reformulation across heritage European manufacturers and reshaping material segmentation toward lead-free alternatives. FDA guidance on ceramic and glass food-contact surfaces governs US import compliance, while BIS certification requirements in India filter substandard soda-lime imports from unbranded Asian suppliers. Stakeholders must monitor evolving extended producer responsibility frameworks in the EU and California that will impose end-of-life collection obligations on glassware importers and distributors.
Market Dynamics
REACH compliance deadlines are forcing heritage European crystal manufacturers to eliminate lead oxide from formulations entirely, collapsing traditional material hierarchies and redistributing competitive advantage toward metallurgical innovators with proprietary glass chemistry capabilities.
Growth Catalysts
- Borosilicate thermal shock tolerance:Oven-to-table functionality at 165°C differential is capturing health-conscious household segments and commercial foodservice buyers seeking multi-use vessel durability.
- EU packaging waste directives:Extended producer responsibility frameworks are accelerating recyclability investments and favoring manufacturers with closed-loop material recovery systems.
- Middle Eastern hotel developments:Heritage German manufacturers anchor premium export channels into luxury hospitality procurement programs across Dubai, Riyadh, and Doha.
Market Restraints
- Artisan glassblower scarcity:Traditional European production clusters face rotating labor shortages, constraining hand-finished crystal output and capping premium tier supply.
- Lead crystal refractive index ceiling:REACH-mandated elimination of lead oxide doping prevents heritage formulations from achieving indices above 1.54, compressing optical differentiation.
- Soda-lime import saturation:Unbranded Asian suppliers flood price-sensitive segments with substandard certification, eroding margin pools in mass-market tumblers.
Strategic Opportunities
- India BIS certification filtering:Stringent import standards create protected channels for compliant European and North American manufacturers to capture premium household share.
- Replacement-cycle hotel contracts:Custom branding programs with fixed refresh schedules generate predictable revenue streams and superior per-unit profitability versus spot retail.
- Tritan crystal patent leverage:Lead-free formulations maintaining refractive clarity enable technology licensors to extract value from heritage brands requiring rapid reformulation.
Industry Challenges
- Reformulation capex intensity:Smaller heritage manufacturers lack balance sheet capacity to fund simultaneous lead elimination and automated borosilicate line deployment.
- REACH compliance timeline compression:Accelerated regulatory deadlines force parallel validation of new chemistries, stretching quality assurance and certification resources.
- Metallurgical talent migration:Glass chemistry expertise concentrates in German industrial clusters, leaving peripheral manufacturing regions dependent on external technical partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crystalware and Glassware Market |
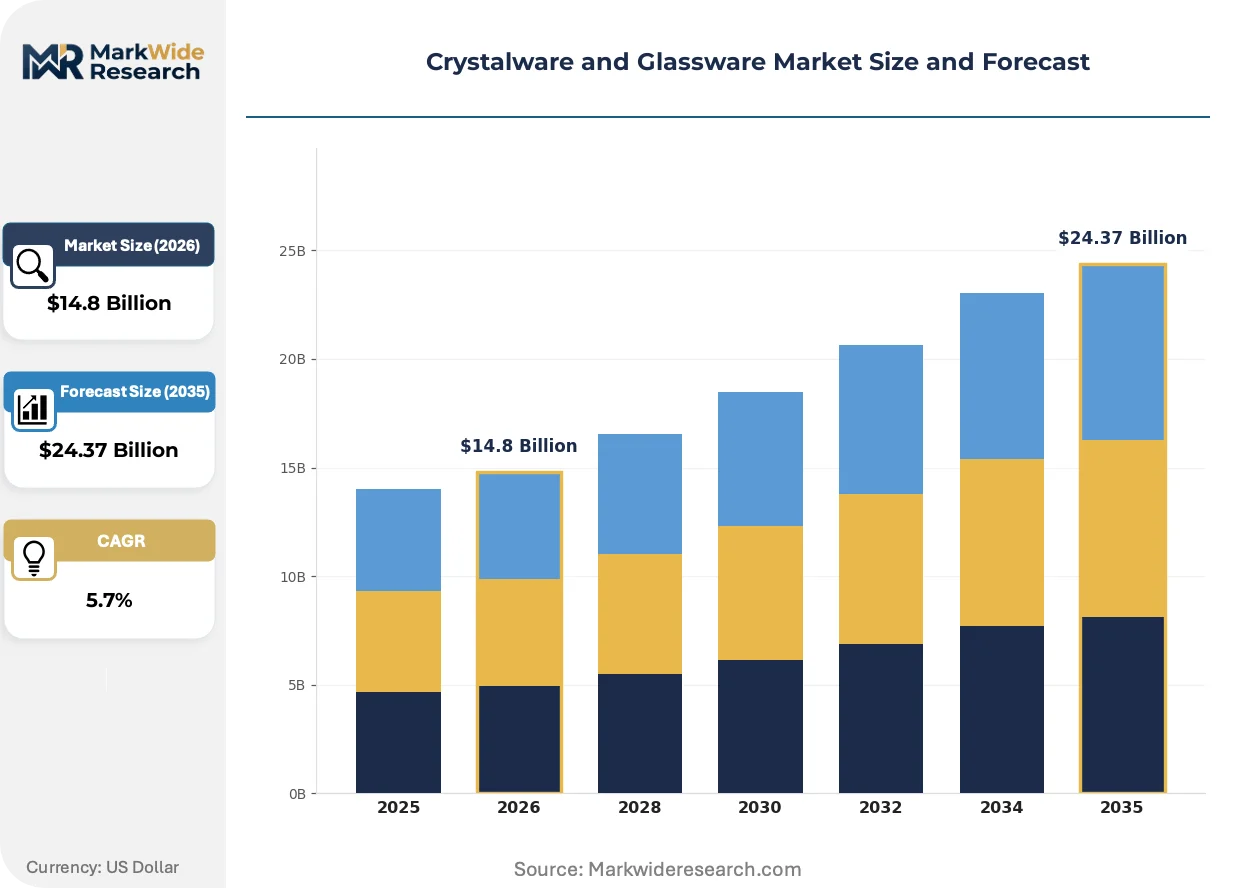
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wine Glasses, Tumblers, Serving Dishes, Mugs Material: Lead Crystal, Borosilicate Glass, Soda-lime Glass, Tempered Glass End User: Households, Restaurants, Hotels, Event Planners Design: Modern, Vintage, Artistic, Classic |
| Companies Covered | WMF Group, Noritake Co Ltd, Groupe SEB, Anchor Hocking Company, Libbey Inc, Schott Zwiesel AG, Villeroy & Boch AG, Baccarat SA, Fiskars Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crystalware and Glassware Market Emerging Trajectories
Material science breakthroughs and regulatory chemistry mandates are converging to dismantle century-old production hierarchies, while procurement rationalization in hospitality channels rewrites traditional distribution economics.
Patented Tritan crystal technology is decomposing the lead-free premium tier into refractive-performance subsegments. Sommelier-grade stemware programs at Michelin-tier restaurants are adopting these formulations at accelerated replacement cycles. The technology is decomposing the historical correlation between lead content and optical prestige, enabling new entrants to challenge heritage positioning.
EU REACH regulations restricting lead oxide in consumer-contact crystal are compelling wholesale material transitions across Bohemian and Venetian production clusters. ECHA enforcement timelines are compressing reformulation windows from decades to single-digit years. Wine glass segments face the steepest compliance costs given their dependence on refractive clarity as a quality signal.
Hotel procurement departments are consolidating tabletop program vendors and demanding integrated serveware-stemware-decorative object suites. Volume aggregation is displacing fragmented supplier relationships that dominated pre-pandemic hospitality sourcing. This concentration is most visible in German and Austrian alpine hospitality clusters, where procurement centralization now covers property portfolios spanning multiple countries.
Crystalware and Glassware Market Segmentation
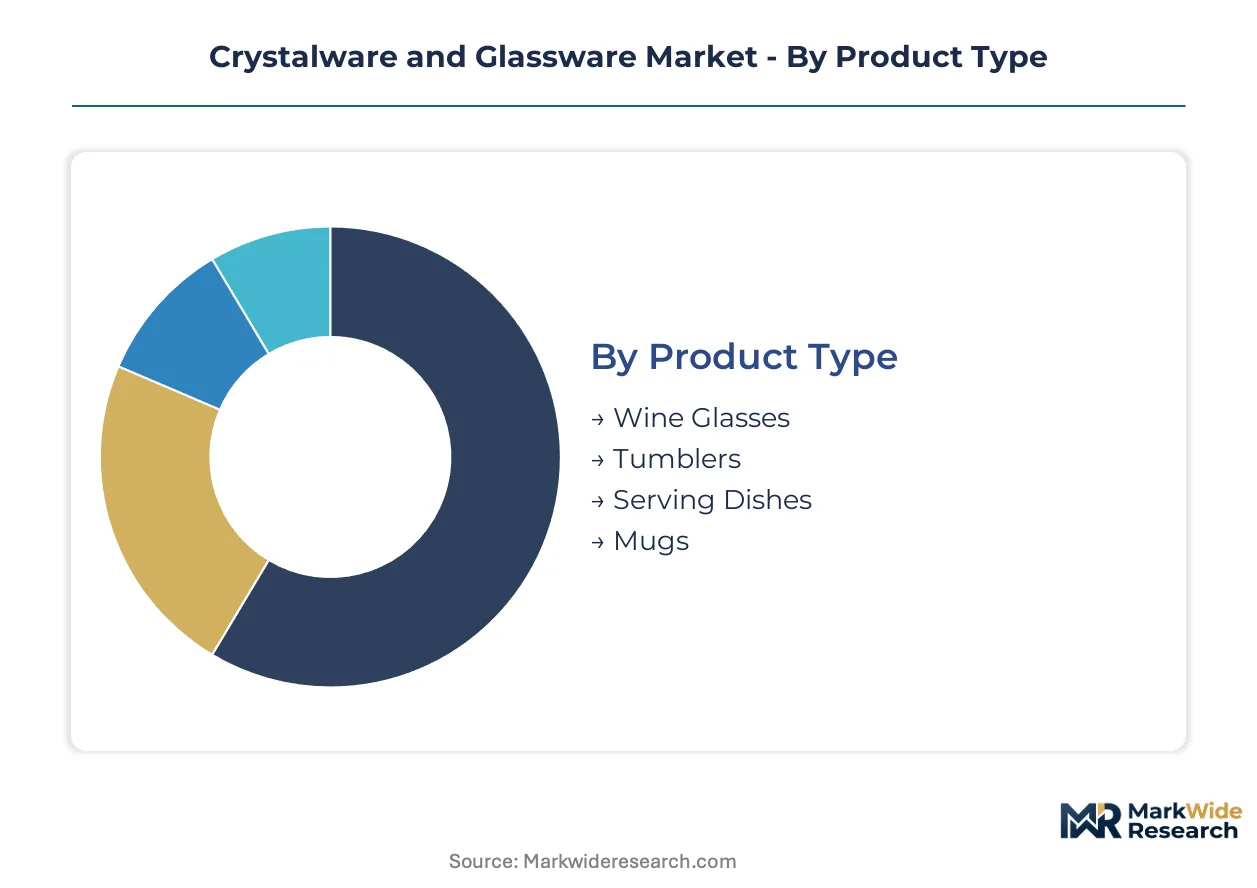
Crystalware and glassware markets fragment across material chemistry, functional application, and aesthetic positioning. Substitution dynamics between lead-based and lead-free formulations reshape competitive boundaries within each segment cluster.
Product Type:
Wine glasses face the most acute substitution pressure as REACH-mandated lead elimination forces reformulation of heritage stemware lines.
- Wine Glasses:Stemware achieves the highest refractive clarity specifications through lead oxide doping or patented Tritan crystal alternatives. Michelin-tier restaurant procurement programs in France and Germany concentrate demand for sommelier-grade bowls with thin-rolled rims and tuned resonance frequencies.
- Tumblers:These short-stem or stemless vessels serve water, spirits, and mixed drinks across commercial foodservice and residential settings. Mass-market volume concentrates in North American household channels where durability and dishwasher compatibility outweigh optical prestige.
- Serving Dishes:Oven-to-table platters and bowls leverage borosilicate thermal shock tolerance for baking and presentation functions.
- Mugs:Handle-equipped vessels for hot beverages favor tempered glass or borosilicate construction for thermal handling safety.
Tumblers anchor the volume base while wine glasses gain share at the steepest rate through premium hospitality channel expansion.
Material:
Cost tier stratification separates heritage formulations from automated production lines, with regulatory compliance costs compressing mid-tier positioning.
- Lead Crystal:Lead oxide doping achieves refractive indices above 1.54 for optical brilliance in decorative and ceremonial objects. Bohemian and Venetian production clusters face ECHA enforcement timelines compressing reformulation windows from decades to single-digit years.
- Borosilicate Glass:Silica-boron oxide matrices tolerate thermal shock differentials up to 165°C for oven-to-table and laboratory applications. German metallurgical innovators anchor premium export channels into Middle Eastern hotel developments with patented formulation control.
- Soda-lime Glass:Sodium carbonate and calcium oxide fluxes enable low-cost production of mass-market tumblers and containers.
- Tempered Glass:Thermal or chemical strengthening processes create surface compression layers for impact-resistant serveware and architectural applications.
Soda-lime glass anchors the volume base while borosilicate glass climbs the fastest as health-conscious buyers displace lead crystal from daily-use contexts.
End User:
Customer type determines pricing architecture, with procurement centralization in hospitality channels rewriting traditional distribution economics.
- Households:Residential buyers sustain volume leadership across all material tiers, though purchase frequency and per-unit spending trail commercial segments. German and Austrian alpine hospitality procurement centralization now influences residential preference formation through visible tabletop presentation standards.
- Restaurants:Foodservice operators demand integrated serveware-stemware suites with standardized replacement cycles and dishwasher durability.
- Hotels:Luxury hospitality brands in Dubai, Riyadh, and Doha generate superior per-unit profitability through custom branding programs and fixed refresh schedules.
- Event Planners:Rental and catering coordinators prioritize stackability, transport durability, and rapid inventory turnover for temporary service applications.
Households anchor the volume base while hotels expand most quickly through Middle Eastern development pipelines.
Design:
Aesthetic positioning stratifies across generational preference and regional heritage association, with artisan scarcity constraining hand-finished output.
- Modern:Minimalist geometries with thin walls and stemless profiles align with contemporary residential interiors and casual dining formats. Scandinavian and Japanese design influences concentrate demand in urban household segments prioritizing space efficiency and neutral palette compatibility.
- Vintage:Period-reproduction patterns and cut-crystal motifs serve collectors and heritage hospitality properties seeking nostalgic atmosphere. Czech and Slovak production clusters preserve hand-cutting techniques threatened by rotating artisan glassblower scarcity.
- Artistic:Limited-edition studio glass and commissioned installations command gallery-tier pricing through named maker attribution.
- Classic:Traditional stemware proportions and decorative etching maintain position in formal dining and ceremonial gift markets.
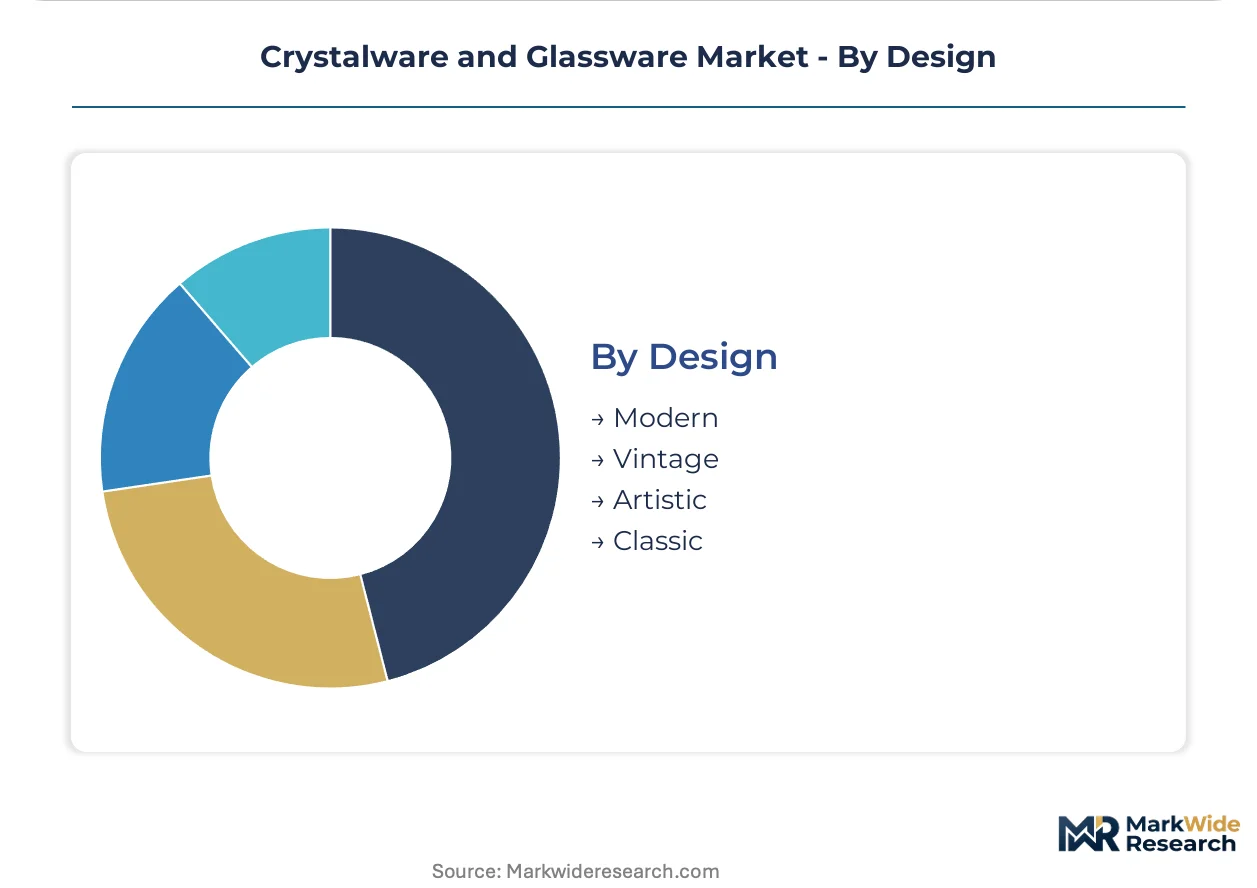
Classic design anchors the volume base while modern styling gains share at the steepest rate through hospitality procurement standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA enforcement timelines compress reformulation windows across European production clusters, while Middle Eastern hospitality procurement and Asian regulatory filtering reshape competitive geography. German metallurgical heritage anchors premium export channels. Indian certification barriers and North American foodservice standardization create distinct entry conditions.
Germany
Heritage manufacturers supply luxury hotel developments in Dubai and Riyadh through anchored export channels. REACH compliance deadlines force simultaneous lead elimination and automated line deployment. Bavarian and Baden-Württemberg industrial clusters concentrate Tritan crystal patent leverage and borosilicate formulation expertise.
India
BIS certification requirements filter substandard soda-lime imports, creating protected channels for compliant suppliers. FSSAI food-contact surface standards parallel import barriers at major ports. Maharashtra and Gujarat warehousing clusters handle European and North American premium inventory for affluent household segments.
United States
FDA guidance on ceramic and glass food-contact surfaces governs import compliance for hospitality procurement programs. Mass-market tumblers and serving lines concentrate volume through distributor networks. Ohio and Pennsylvania glassmaking heritage regions maintain specialized borosilicate capacity for laboratory and oven-to-table applications.
France
Michelin-tier restaurant procurement concentrates demand for sommelier-grade stemware with tuned resonance frequencies. ANSM food-contact material standards align with EU REACH lead restrictions. Parisian and Lyon hospitality design studios influence tabletop program standards across European alpine hotel portfolios.
United Arab Emirates
Luxury hospitality brands in Dubai and Abu Dhabi generate superior per-unit profitability through custom branding programs. MOHAP product safety standards filter import quality at port of entry. Procurement centralization across property portfolios spanning multiple GCC countries aggregates volume for premium German and Austrian suppliers.
Crystalware and Glassware Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with metallurgical innovators and automated mass-market fabricators occupying distinct competitive planes. The vendor base stratifies across heritage crystal houses, German metallurgical specialists, and North American foodservice volume players. Three archetypes dominate: patent-holding formulation innovators, hospitality procurement integrators, and scale-driven tumblers manufacturers. Technology licensing and replacement-cycle contract aggregation represent the dominant competitive moves reshaping market structure.
Among German metallurgical innovators, Schott Zwiesel AG and WMF Group exemplify the technology-licensing and hospitality-integration archetypes respectively. Libbey Inc anchors North American mass-market positioning. These three occupy positions that illustrate the divergence between premium formulation control and foodservice volume aggregation.
| Leading Market Players |
|---|
| WMF Group |
| Noritake Co Ltd |
| Groupe SEB |
| Anchor Hocking Company |
| Libbey Inc |
| Schott Zwiesel AG |
| Villeroy & Boch AG |
| Baccarat SA |
| Fiskars Group |
| Others |
Supply Flow & Price Mechanics
Ninety-day inventory cycles for hand-finished crystal stemware concentrate pricing power in Bavarian and Baden-Württemberg production clusters, while automated borosilicate lines in Czech and Slovak regions compress lead times to fourteen days and erode optical-grade premiums. This divergence between artisan scarcity and manufacturing velocity stratifies margin capture across material tiers and buyer segments.
Pricing Analysis
German-manufactured Tritan crystal commands spreads of forty to sixty percent above Asian soda-lime imports in Middle Eastern hotel procurement channels, with certification grade under EU REACH and BIS marking serving as the primary differentiation vectors. Pricing pressure intensifies downward as unbranded Asian suppliers saturate mass-market tumbler segments through port-direct distribution. Household buyers exhibit acute price sensitivity in everyday serveware, while hospitality procurement departments prioritize total cost of ownership and replacement-cycle predictability over unit economics.
Supply Chain Analysis
Strategic stockpiling of high-purity silica and boron oxide concentrates preference among German metallurgical innovators, whereas just-in-time soda-lime sheet glass procurement dominates North American foodservice fabricators. Supply concentrates in Germany, the Czech Republic, and China for raw material processing and finished goods fabrication. Borosilicate formulations draw from specialized boron deposits in Turkey and the United States. Single-source vulnerability in artisan glassblower availability constrains hand-finished output expansion. Distribution runs through hospitality procurement integrators in Dubai and Riyadh, anchored export channels for premium tiers, and mass-market distributor networks for household volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as regulatory chemistry mandates and procurement centralization simultaneously dismantle legacy hierarchies and create protected niches for compliant specialists. REACH-driven material transitions and hospitality vendor consolidation generate entry points for formulation innovators and regional procurement integrators.
For Market Incumbents: Consolidate patent leverage in lead-free crystal chemistry through exclusive licensing arrangements with heritage Bohemian and Venetian manufacturers facing reformulation deadlines. Acquire automated borosilicate capacity in Czech industrial zones to capture health-conscious household displacement of lead crystal. Channel control through replacement-cycle contract aggregation with Dubai and Riyadh hotel portfolios defends margin position against spot-market volatility.
For New Entrants and Emerging Players: Anchor in Indian premium household segments where BIS certification filters create protected channels for compliant European and North American suppliers. Target Maharashtra and Gujarat warehousing clusters for affluent residential distribution partnerships. White-space availability concentrates in Tritan crystal technology licensing to mid-tier heritage brands lacking in-house metallurgical R&D.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance arbitrage play because ECHA enforcement timelines compress reformulation windows and concentrate value in proprietary glass chemistry capabilities. Acquisition focus should center on German metallurgical specialists with patented lead-free formulations and established Middle Eastern hospitality procurement relationships. Signal to monitor: BIS certification expansion to additional Indian port authorities, which would widen protected channel access for compliant suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing Agreement | Tritan crystal patent holders extract value from heritage brands requiring rapid REACH-compliant reformulation. |
| Backward Integration into Raw Material Supply | Captive boron oxide sourcing secures formulation consistency for thermal shock-tolerant product lines. |
| Long-term Supply Agreement | Fixed-refresh hotel contracts in Dubai and Riyadh generate predictable revenue streams versus spot retail. |
| Certification Investment Program | BIS and FDA compliance spending opens protected distribution channels in India and North America. |
| Joint Venture with Artisan Clusters | Partnerships with Czech and Slovak glassblowers preserve hand-finishing capacity against labor scarcity. |
Methodological Framework
A spread of perspectives from German metallurgical R&D directors, Dubai hospitality procurement executives, Indian import compliance officers, and Czech artisan glassblower cooperatives converged on the working assumptions driving material substitution forecasts. Primary fieldwork combined structured interviews with secondary validation through ECHA regulatory filings, BIS certification databases, customs trade records, and SEC disclosures from listed glassware manufacturers. Bottom-up volume builds across product type and material segments triangulated against top-down market sizing from hospitality procurement spend analysis.
Segmentation dimensions modeled include material chemistry, functional application, end-user category, and aesthetic positioning across the projection horizon. CAGRs derived from weighted average of historical volume trajectories, regulatory-driven substitution elasticities, and hospitality development pipeline tracking. Industry-specific forecast inputs encompass REACH compliance deadline phasing and Middle Eastern hotel construction permit data.
Decision-makers should treat outputs as directional under assumptions of sustained ECHA enforcement intensity and continued GCC hospitality investment; material deviation would warrant model refresh. Revision becomes warranted when artisan glassblower availability or boron oxide commodity pricing crosses thresholds that alter substitution economics between lead-free crystal and borosilicate alternatives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Soda Feldspar Market
Glass
Solar Control Glass Market
Glass
Global Flat Glass Market
Glass
Laboratory Glass Container Market
Glass
Laboratory Glassware Market
Glass
Insulating Glass Market
Glass
Optical Lens Material Market
Glass
Glass Product Market
Glass
North America Industrial Silica Sand Market
Glass
Birefringent Crystals Market
Glass
Antibacterial Glass Market
Glass
Silica Sand Market
Glass
Glass Mat Thermoplastic Market
Glass
Global Energy Efficient Glass Market
Glass
North America and Australia Silica Market
Glass
Latin America Flat Glass Market