
 Global Ultra-Thin Glass Market | 2026-2036
Global Ultra-Thin Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ultra-Thin Glass Market Foresight
Sub-100-micron thickness grades is reorganizing competitive dynamics across the ultra-thin glass value chain. Corning Incorporated leverages its fusion-draw expertise to dominate chemically strengthened cover glass for premium device tiers. Schott AG anchors European supply through precision-drawn borosilicate substrates for semiconductor packaging applications. AGC Inc. competes aggressively in Asian display substrate markets with float-process thin glass optimized for OLED encapsulation.
Ultra-thin glass denotes silica-based sheet material manufactured below 0.7 mm thickness, typically produced through down-draw, overflow fusion, or float processes with subsequent chemical strengthening via potassium-sodium ion exchange to achieve compressive surface layers exceeding 800 MPa. This material serves primarily as mechanically robust, optically transparent substrates for electronic displays, photonic devices, and emerging flexible electronics requiring bend radii under 5 mm. Cover glass for consumer electronics retains the largest value pool, though flexible substrates for foldable and rollable devices represent the fastest-expanding application segment with the steepest margin accretion. Protective screens for wearable gadgets constitute a mature, volume-driven category where price competition intensifies and differentiation shifts to anti-reflective and anti-microbial surface treatments.
The US FDA regulates glass components in medical imaging and diagnostic photonics devices, while REACH and RoHS frameworks in Europe restrict heavy metal content in display glass coatings and etching chemistries. China's GB standards and MIIT directives mandate localized testing for display substrates used in government procurement programs, creating non-tariff barriers for imported ultra-thin glass. Stakeholders must monitor evolving dual carbon goals across Asian manufacturing hubs and assess whether captive ion-exchange facilities or outsourced chemical strengthening delivers superior unit economics under tightening environmental compliance.
Market Dynamics
Sub-100-micron thickness grades are compressing manufacturing yields while foldable display manufacturers scramble for supply security, creating a structural shortage premium that favors fusion-draw specialists over float-process competitors.
Growth Catalysts
- Foldable Smartphone Penetration:Device manufacturers in South Korea and China are expanding substrate orders for bendable OLED stacks, pulling chemically strengthened cover glass into multi-layer laminates.
- EU F-Gas Regulation:Tightened fluorinated gas emission limits are accelerating process chemistry transitions toward aqueous etching and potassium-sodium ion exchange strengthening.
- Semiconductor Packaging Migration:Fan-out wafer-level packaging lines in Taiwan and Germany are adopting borosilicate glass interposers for thermal expansion matching with silicon dies.
Market Restraints
- Raw Material Concentration:High-purity silica sand supply from specific Appalachian and Ukrainian deposits faces logistics bottlenecks that transmit volatility into melting furnace feedstock costs.
- Fusion-Draw Equipment Scarcity:Only three equipment builders globally supply isopipe systems capable of sub-50-micron thickness control, creating 18-24 month order backlogs.
- Substitution by Polyimide Films:Samsung Display and BOE Technology Group are qualifying colorless polyimide substrates for inner fold layers, threatening glass share in radius-critical applications.
Strategic Opportunities
- India Display Manufacturing:Vedanta-Foxconn's planned fab in Gujarat creates first-mover advantage for glass suppliers establishing captive ion-exchange facilities under PLI scheme incentives.
- Automotive Transparent Antenna Integration:5G mmWave and V2X communication modules are embedding ultra-thin glass substrates within windshield laminates for signal transparency.
- Japan METI Green Innovation Fund:Subsidies for low-carbon glass melting technologies are enabling electric furnace retrofits that cut Scope 1 emissions by 40% versus conventional natural gas firing.
Industry Challenges
- Specialized Metrology Talent:Atomic force microscopy and white-light interferometry operators capable of sub-nanometer surface roughness validation command 3x standard technician salaries.
- Multi-Site Certification Burden:Medical imaging glass suppliers must maintain simultaneous FDA 21 CFR Part 820, ISO 13485, and Japan PMDA QMS compliance across geographically dispersed finishing facilities.
- Legacy Float Line Retrofit Costs:Converting soda-lime float assets to borosilicate or aluminosilicate chemistries requires $80-120 million per line for refractory and tin bath modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ultra-Thin Glass Market |
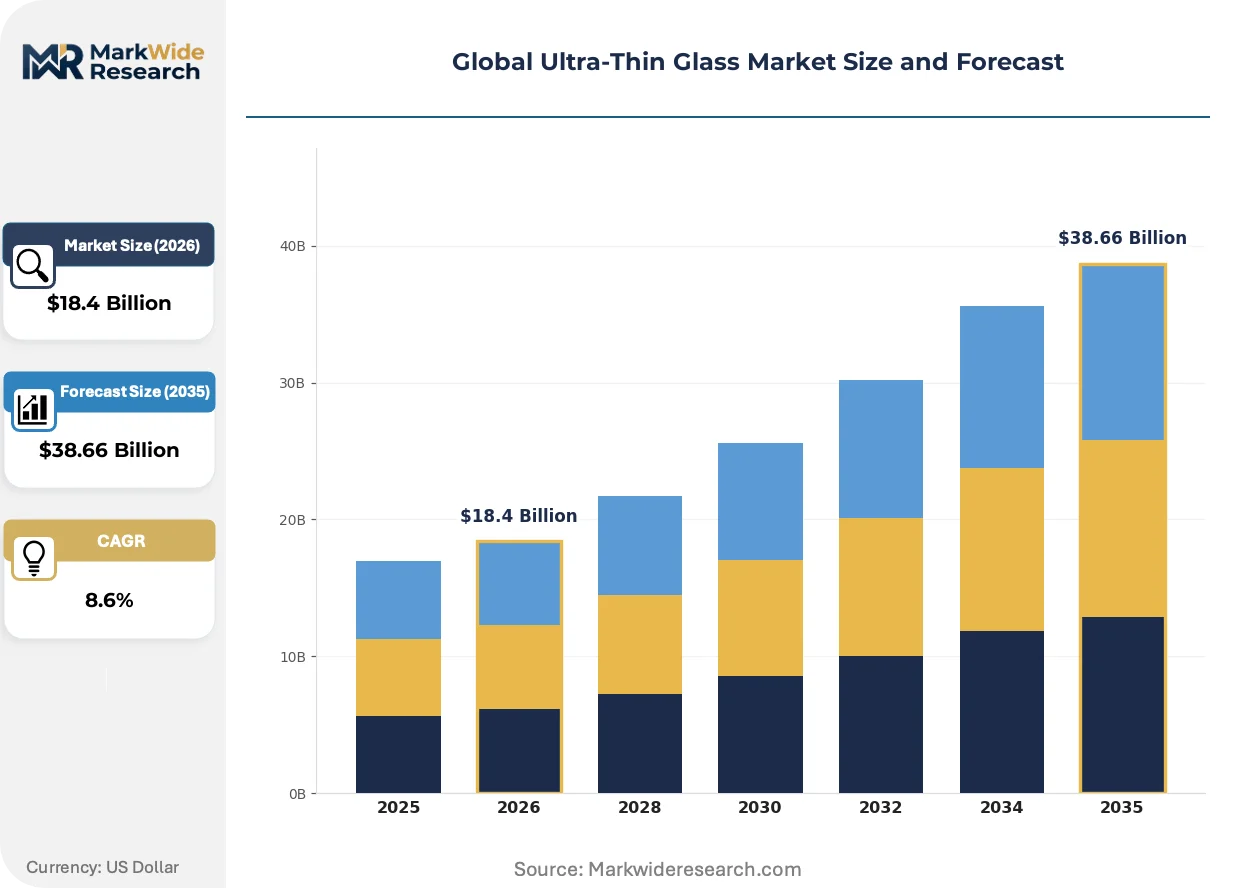
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $38.66 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Display Panels, Flexible Substrates, Protective Screens, Optical Lenses, Cover Glass Technology: Chemical Strengthening, Heat Treatment, Ion Exchange, Laser Annealing, Physical Vapor Deposition Application: Consumer Electronics, Solar Cells, Wearable Gadgets, Transparent Sensors, Photonics End User: Smartphone Manufacturers, Renewable Energy Firms, Fitness Device Makers, Sensor Developers, Photonics Companies |
| Companies Covered | Saint-Gobain, Schott AG, AGC Inc., China Glass Holdings, PPG Industries, Corning Incorporated, Guardian Industries, Asahi Glass Co., NSG Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ultra-Thin Glass Market Shifts & Advancements
Manufacturing process architectures are fragmenting into thickness-specific camps, with fusion-draw purity competing against float-process scale economics as display makers split procurement between premium and volume tiers.
Laser-based glass separation is bifurcating the cutting equipment market. Stealth dicing systems using Bessel beam optics eliminate mechanical edge grinding for sub-200-micron substrates. Samsung Display and LG Display are installing these lines at Gumi and Paju facilities. The technology is compressing traditional abrasive wheel suppliers into commodity peripheral markets while concentrating margin in laser source and beam-shaping subsystem vendors.
REACH Annex XVII restrictions on cadmium and lead compounds are forcing reformulation of anti-reflective thin-film stacks. Sol-gel silica-titania coatings are displacing vacuum-deposited metal oxides across European display glass finishing operations. Smartphone cover glass suppliers serving EU markets are qualifying aqueous dip-coating lines that eliminate sputtering targets containing restricted elements.
Device OEMs are consolidating supplier bases from six-plus glass vendors to two or three qualified partners per thickness grade. Apple and Huawei have reduced cover glass supplier rosters by 40% since 2022, prioritizing vendors with captive chemical strengthening and in-house optical coating capabilities. This concentration is most visible in Shenzhen and Chengdu procurement offices, where supplier scorecards now weight vertical integration above unit price.
Global Ultra-Thin Glass Market Segmentation
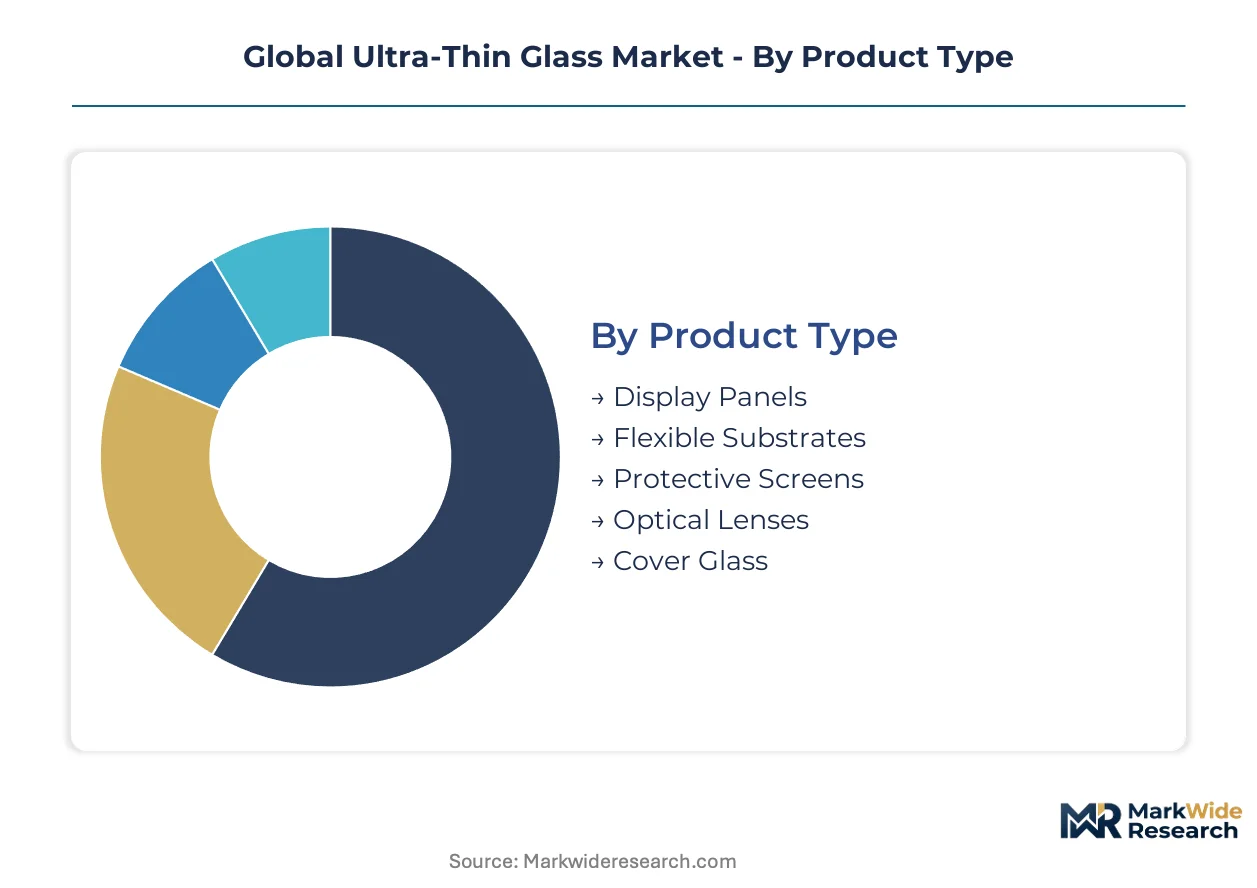
Ultra-thin glass procurement patterns diverge sharply across thickness grades and surface treatment requirements. Display makers prioritize optical clarity and bend radius performance, while semiconductor packagers emphasize thermal expansion coefficients and surface flatness tolerances.
Product Type:
Substitution pressure from polyimide films and sapphire alternatives varies dramatically by thickness regime, with sub-100-micron grades facing the most aggressive competitive threats.
- Display Panels:TFT-LCD and OLED backplane substrates requiring alkali-free borosilicate compositions with thermal expansion below 3.8 ppm/K. Demand concentrates in South Korea's Gumi cluster where Samsung Display and LG Display operate multi-billion-dollar fabs, constrained by fusion-draw furnace capacity backlogs extending 18-24 months.
- Flexible Substrates:Chemically strengthened aluminosilicate sheets below 50-micron thickness enabling sub-5mm bend radii for foldable devices. Procurement is accelerating fastest among Chinese device OEMs in Shenzhen and Dongguan, though colorless polyimide from Kolon Industries threatens glass share in radius-critical inner fold layers.
- Protective Screens:Cover glass derivatives with anti-fingerprint oleophobic coatings for mid-tier smartphones and tablets.
- Optical Lenses:Precision-molded wafer-level camera module substrates requiring sub-nanometer surface roughness.
- Cover Glass:Ion-exchange strengthened sheets for premium device tiers, dominated by Corning's fusion-draw supply to Apple and Samsung flagship lines.
Display Panels anchors the volume base while Flexible Substrates gains share at the steepest rate.
Technology:
Process selection directly determines which regulatory frameworks apply, with aqueous chemistry routes facing EU REACH scrutiny while vacuum deposition triggers RoHS compliance burdens.
- Chemical Strengthening:Potassium-sodium ion exchange generating compressive surface layers exceeding 800 MPa through immersion in molten salt baths at 400-450°C. South Korean and Japanese suppliers maintain captive facilities near Seoul and Osaka, advantaged by proximity to display manufacturing clusters and lower logistics costs for hazardous salt waste disposal.
- Ion Exchange:Variants using mixed alkali chemistries for ultra-thin substrates where conventional strengthening would induce warpage. Adoption is climbing fastest among suppliers serving foldable display laminates, constrained by EU F-Gas Regulation limits on fluorinated etching precursors used in pre-treatment.
- Heat Treatment:Thermal tempering for thicker soda-lime protective screens in cost-sensitive applications.
- Laser Annealing:Selective crystallization for transparent oxide semiconductor backplanes in high-resolution OLED panels.
- Physical Vapor Deposition:Sputtered anti-reflective and conductive coatings, facing REACH Annex XVII reformulation mandates for cadmium-free targets.
Chemical Strengthening commands the installed equipment base as Ion Exchange climbs the capability ladder for next-generation flexible devices.
Application:
End-use maturity curves separate volume-driven commodity segments from emerging applications where technical specifications command premium positioning.
- Consumer Electronics:Smartphones, tablets, and laptops consuming chemically strengthened cover glass and display substrates in billion-unit annual volumes. Procurement concentrates among five device OEMs headquartered in Cupertino, Seoul, Shenzhen, and Taipei, with supplier consolidation reducing qualified vendor rosters by 40% since 2022.
- Wearable Gadgets:Smartwatch and fitness tracker cover glass requiring extreme impact resistance at sub-1mm thicknesses. Apple's procurement from Corning and AGC for Apple Watch lines in Vietnam and China sets the specification benchmark, though price compression intensifies as Android Wear OEMs shift to chemically strengthened soda-lime alternatives.
- Solar Cells:Thin-film photovoltaic encapsulation and concentrator optics.
- Transparent Sensors:Touch-sensitive automotive and appliance interfaces.
- Photonics:Medical imaging and telecom wavelength-selective components regulated by FDA 21 CFR Part 820 and ISO 13485.
Consumer Electronics absorbs the majority of current output as Photonics delivers the highest margin per square meter.
End User:
Customer concentration and vertical integration strategies fragment procurement power across radically different commercial structures.
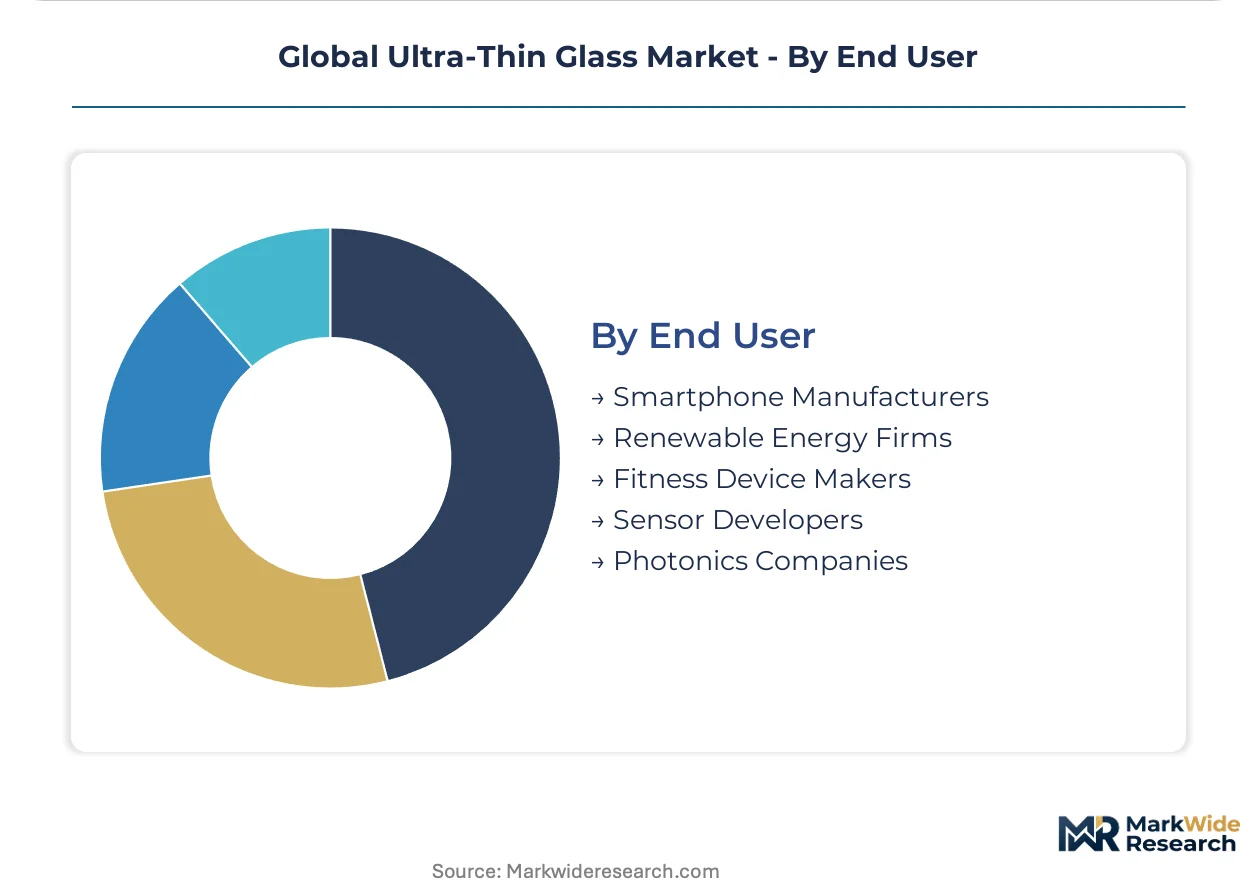
- Smartphone Manufacturers:Apple, Samsung, Xiaomi, OPPO, and vivo collectively specifying cover glass thickness, edge profile, and surface chemistry. These OEMs enforce dual-sourcing mandates that prevent single-supplier dependency, though captive ion-exchange capabilities increasingly weight supplier scorecards above unit pricing in Seoul and Shenzhen procurement offices.
- Sensor Developers:Automotive Tier 1s and IoT module integrators embedding ultra-thin glass in 5G mmWave and LiDAR packages. Continental and Bosch qualification programs in Germany and Japan are driving demand for borosilicate interposers with matched thermal expansion to silicon dies, constrained by metrology bottlenecks for sub-nanometer surface validation.
- Renewable Energy Firms:First Solar and Hanwha Q Cells for cadmium telluride and perovskite encapsulation.
- Fitness Device Makers:Garmin, Fitbit, and Chinese white-label suppliers for sports watch cover glass.
- Photonics Companies:Coherent, Lumentum, and Hamamatsu Photonics for laser and imaging substrates.
Smartphone Manufacturers dictate volume scale while Sensor Developers expand the addressable market into automotive and industrial applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fusion-draw furnace capacity clusters most densely in South Korea, Japan, and Germany, where display manufacturing ecosystems and precision glass heritage create reinforcing supply-demand loops. Regulatory fragmentation across REACH, GB standards, and FDA frameworks forces suppliers to maintain parallel certification tracks for multi-market access.
South Korea
Samsung Display and LG Display drive substrate demand for foldable OLED stacks, pulling chemically strengthened cover glass into multi-layer laminates. The Ministry of Trade, Industry and Energy enforces localized testing under KS standards for government procurement programs. Gumi and Paju host concentrated fab operations where stealth dicing laser systems are displacing mechanical edge grinding for sub-200-micron substrates.
China
BOE Technology Group and Visionox expand orders for flexible display substrates while qualifying colorless polyimide alternatives for inner fold layers. MIIT directives mandate GB standard compliance for display glass in state procurement, creating non-tariff barriers for imports. Shenzhen and Dongguan procurement offices consolidate supplier rosters, weighting captive ion-exchange capabilities above unit pricing in vendor scorecards.
Japan
Corning's alliance partners and AGC Inc. anchor supply for premium device tiers requiring sub-50-micron thickness control. METI's Green Innovation Fund subsidizes electric furnace retrofits cutting Scope 1 emissions by 40 percent versus natural gas firing. Osaka and Nagoya maintain captive chemical strengthening facilities advantaged by proximity to display clusters and lower hazardous salt waste logistics costs.
Germany
Continental and Bosch drive demand for borosilicate interposers in automotive 5G mmWave and LiDAR packages requiring thermal expansion matching with silicon dies. EU F-Gas Regulation tightens fluorinated gas emission limits, accelerating aqueous etching chemistry transitions. Bavaria and Baden-Württemberg host precision-drawn substrate operations serving semiconductor packaging lines with sub-nanometer surface flatness tolerances.
United States
Apple's procurement specifications for premium cover glass set thickness and edge profile benchmarks adopted across the device ecosystem. FDA 21 CFR Part 820 regulates glass components in medical imaging and diagnostic photonics, requiring ISO 13485 alignment. Cupertino and Austin procurement offices enforce dual-sourcing mandates while reducing qualified vendor counts by 40 percent since 2022.
Global Ultra-Thin Glass Market Competitive Landscape
Concentration sits with fusion-draw specialists possessing captive chemical strengthening infrastructure, while float-process competitors occupy volume-driven protective screen segments. Three archetypes dominate: heritage glass conglomerates with display substrate heritage, precision materials specialists serving semiconductor packaging, and Asian challengers scaling float-process capacity for OLED encapsulation. Competitive moves center on M&A for ion-exchange facility access and strategic partnerships with foldable display manufacturers for supply security.
Within the heritage conglomerate tier, Corning Incorporated and Schott AG exemplify divergent geographic anchoring strategies, with the former leveraging US-based fusion expertise and the latter anchoring European supply through precision-drawn operations. AGC Inc. occupies a position among Asian-scale specialists competing aggressively in display substrate markets. These three entities represent the capability spectrum from sub-50-micron thickness control to borosilicate thermal expansion matching, illustrating how process architecture selection locks in adjacent regulatory and customer access pathways.
| Leading Market Players |
|---|
| Saint-Gobain |
| Schott AG |
| AGC Inc. |
| China Glass Holdings |
| PPG Industries |
| Corning Incorporated |
| Guardian Industries |
| Asahi Glass Co. |
| NSG Group |
| Others |
Supply & Pricing Matrix
Eighteen-to-twenty-four-month lead times for fusion-draw isopipe systems concentrate pricing power among the three equipment builders capable of sub-50-micron thickness control, compressing buyer leverage as display manufacturers compete for scarce furnace capacity. This supply bottleneck amplifies cost pass-through for chemically strengthened substrates while float-process competitors absorb margin erosion in volume-driven protective screen tiers.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure by forcing aqueous chemistry transitions that raise processing costs for European-serving suppliers. Pricing stratifies across premium, standard, and economy tiers based on thickness grade and captive ion-exchange capability, with foldable display laminates commanding the widest spreads. Cost compression in mid-tier protective screens intensifies as soda-lime alternatives displace aluminosilicate in wearable applications. Smartphone OEMs in Shenzhen and Seoul exhibit the sharpest price sensitivity, while photonics device makers accept premiums for sub-nanometer surface validation.
Supply Chain Analysis
Raw material inventory cycles stretching 90-120 days for high-purity silica sand from Appalachian and Ukrainian deposits tether pricing volatility to logistics bottlenecks in melting furnace feedstock. Manufacturing concentrates in South Korea, Japan, and Germany where fusion-draw heritage and display manufacturing clusters reinforce supply-demand loops. The supply chain draws from specialized isopipe systems, molten salt bath chemistries, and precision metrology equipment. Single-source vulnerability sits with the three global builders of sub-50-micron thickness control systems. Distribution runs through qualified vendor rosters directly to display fab procurement offices in Gumi, Paju, and Shenzhen.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward device OEMs as Apple, Samsung, and Chinese manufacturers consolidate supplier bases from six-plus vendors to two or three qualified partners per thickness grade since 2022.
For Market Incumbents: Fortify captive ion-exchange capabilities and sub-50-micron thickness control as defensive moats against colorless polyimide substitution threatening inner fold layers. Prioritize backward integration into high-purity silica sand sourcing to mitigate Appalachian and Ukrainian logistics bottlenecks. Expand metrology talent pipelines for atomic force microscopy operators commanding premium compensation. For New Entrants and Emerging Players: Differentiate on aqueous etching chemistry compliance under EU F-Gas Regulation as established suppliers face stranded equipment risks. Target India's Gujarat display manufacturing cluster where Vedanta-Foxconn's planned fab creates first-mover advantage for localized ion-exchange facilities under PLI scheme incentives. Pursue automotive transparent antenna integration for 5G mmWave modules as a qualification-light entry path. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across sub-100-micron flexible substrate manufacturing as fusion-draw equipment backlogs extend and metrology requirements tighten. Long-term viability favors vertically integrated specialists with captive chemical strengthening rather than commodity float-process operators. Watch stealth dicing laser adoption rates at Samsung Display and LG Display facilities as the signal for mechanical cutting equipment obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Ion-Exchange Facility Buildout | Secures supply chain control for foldable display laminates serving Samsung and BOE qualification programs. |
| Stealth Dicing Laser System Deployment | Eliminates mechanical edge grinding for sub-200-micron substrates at Gumi and Paju manufacturing clusters. |
| Aqueous Etching Chemistry Transition | Aligns with EU F-Gas Regulation limits on fluorinated precursors in pre-treatment processes. |
| Electric Furnace Retrofit Program | Cuts Scope 1 emissions by 40 percent under Japan METI Green Innovation Fund subsidies. |
| India PLI Scheme Localization | Captures first-mover positioning for display glass supply to Vedanta-Foxconn Gujarat fab operations. |
Research Methodology
A standing panel of display manufacturing procurement directors, fusion-draw furnace operators, chemical strengthening process engineers, and semiconductor packaging substrate specialists provided ongoing calibration across the analysis window. Primary interviews with these stakeholders combined with secondary validation from SEC 10-K filings, Korean KS standards documentation, EU REACH Annex XVII regulatory texts, and Japan METI subsidy program disclosures. Bottom-up capacity modeling and top-down demand triangulation from device OEM bill-of-materials data ensured cross-verified outputs.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including thickness grade tier, surface treatment requirement, end-use application maturity, and regional regulatory cluster. CAGRs were derived from iterative reconciliation of supply-side capacity expansion schedules and demand-side device shipment trajectories. Key inputs included foldable smartphone penetration curves, fusion-draw furnace order backlogs, and polyimide substitution threat assessments.
Forecasts assume regulatory continuity in EU F-Gas Regulation, REACH, and China MIIT GB standards; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Asia-Pacific Silica Sand Market
Glass
Global Energy Efficient Glass Market
Glass
Global Laminated Glass Market
Glass
Screen-Printing Glass Market
Glass
Glass Forming Machine Market
Glass
Ultra Violet Glass Bottles Market
Glass
Glass Mason Jars Market
Glass
Cellular Glass Market
Glass
GCC Flat Glass Market
Glass
Middle-East and Africa Flat Glass Market
Glass
Silica Sol Market
Glass
Glass Tableware Market
Glass
Europe Sapphire Glass Market
Glass
Double Glazing Glass Market
Glass
Glass Mat Market
Glass
Glass Balustrade Lamination Market