
 Global Thermochromic Paint Market | 2026-2036
Global Thermochromic Paint Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thermochromic Paint Market Foresight
Performance-grade durability specifications is unwinding the commodity positioning that long dominated thermochromic coatings. BASF SE leverages its pigment chemistry heritage to supply leuco dye concentrates with calibrated transition temperatures. Chromatic Technologies Inc. anchors North American demand through specialized formulations for temperature-sensitive logistics. LCR Hallcrest LLC dominates the liquid crystal segment with medical and industrial sensor applications.
Thermochromic paint incorporates reversible chromic compounds—primarily leuco dyes, liquid crystals, or metal complexes—dispersed within resin binders to produce color change at defined thermal thresholds, typically engineered between minus thirty and one hundred twenty degrees Celsius for industrial readability. Liquid paint formulations sustain the largest volume share due to compatibility with conventional spray and dip coating equipment across automotive and building envelope applications. Powder coating variants are gaining traction in appliance manufacturing where zero-VOC compliance and thick-film durability outweigh higher curing energy requirements. Leuco dye technology leads unit economics through lower raw material cost and broader color palette availability compared to liquid crystal alternatives.
REACH registration requirements through ECHA govern leuco dye import and formulation within the European Union, while EPA TSCA oversight in the United States mandates pre-manufacture notification for novel chromic compounds. China's GB standards through SAMR establish migration limits for thermochromic pigments in consumer goods and textiles. Manufacturers must monitor regulatory divergence between these jurisdictions to avoid reformulation costs that erode margin pools across export portfolios.
Market Dynamics
Automotive electrification is forcing coating suppliers to engineer thermal-indicator formulations capable of operating within battery pack thermal envelopes where precision exceeds legacy HVAC applications.
Growth Catalysts
- REACH registration thresholds:ECHA's tightened leuco dye purity requirements are filtering out commodity suppliers and rewarding compliant formulators with qualified supplier status across EU automotive OEMs.
- Battery thermal management:EV manufacturers in China are specifying thermochromic coatings for cell-level temperature monitoring, creating specification pull-through from cell producers to pack integrators.
- Leuco dye production scaling:Domestic Chinese pigment houses are expanding crystallization capacity, reducing import dependency for European and North American coating compounders.
Market Restraints
- Specialty resin input volatility:Fluoropolymer binders essential for outdoor durability face price pressure from semiconductor-grade fluorochemical demand diversion.
- Leuco dye supply concentration:Crystallization expertise clusters in Zhejiang and Jiangsu provinces, creating geographic chokepoints for global formulation supply.
- Substitution by infrared thermography:Non-contact temperature sensing in industrial maintenance is displacing visual-indicator coatings in predictive maintenance budgets.
Strategic Opportunities
- India industrial safety mandate:Draft factory safety regulations under the Ministry of Labour and Employment are considering mandatory temperature-indicating coatings for pressurized equipment.
- Smart packaging convergence:Integration of thermochromic indicators with printed electronics and NFC tags is opening pharmaceutical cold-chain authentication applications.
- EU F-Gas Regulation phase-down:Refrigeration equipment manufacturers are adopting thermochromic leak-detection coatings as alternatives to electronic sensors in systems transitioning to low-GWP refrigerants.
Industry Challenges
- Color chemist talent scarcity:Formulation expertise combining leuco dye microencapsulation with UV-stable resin systems is concentrated among retiring specialists in Germany and Japan.
- Dual certification timelines:Simultaneous EPA TSCA pre-manufacture notification and ECHA REACH dossier preparation extends product launch cycles for novel chromic compounds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thermochromic Paint Market |
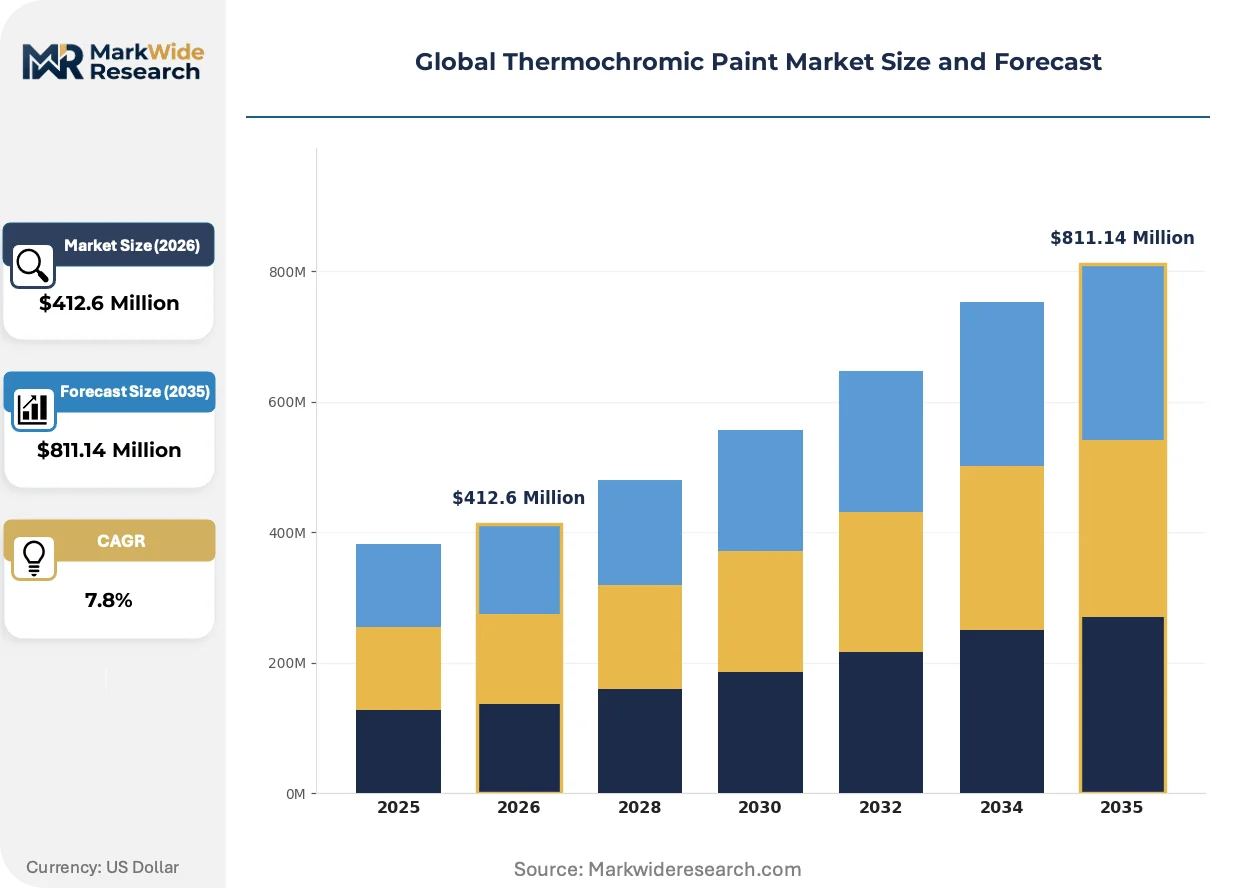
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $811.14 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Paint, Powder Coating, Spray Paint, Epoxy Coating, Acrylic Paint Technology: Leuco Dye, Liquid Crystals, Metal Complex, Phase Change, Photochromic Integration Application: Building Envelope, Temperature Sensors, Automotive Components, Consumer Electronics, Textiles End User: Construction Firms, Vehicle Manufacturers, Electronics Producers, Textile Designers, Industrial Equipment Makers |
| Companies Covered | BASF SE, Kolortek Co. Ltd., Chromatic Technologies Inc., Olikrom SAS, Smarol Industry Co. Ltd., LCR Hallcrest LLC, QCR Solutions Corp, Axalta Coating Systems Ltd., Matsui International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thermochromic Paint Market Shifts & Advancements
Reversible chromic technology is fragmenting into performance tiers as end-users differentiate between commodity color-change novelty and calibrated industrial sensing applications.
Encapsulated leuco dye systems are bifurcating the formulation landscape. Microencapsulation technology protects dye molecules from environmental degradation while enabling aqueous dispersion. Automotive battery manufacturers are specifying encapsulated grades for thermal runaway indication. This technology is bifurcating supplier tiers between toll-encapsulation houses and integrated formulators.
EPA TSCA Section 5 pre-manufacture notification requirements are tightening oversight of novel spirolactone dye structures. The industrial consequence is extended development timelines for next-generation chromic compounds with improved lightfastness. Specialty coating formulators serving aerospace and medical device segments are most affected, with several delaying 2025 product launches to complete toxicity dossiers.
Specification authority is migrating from procurement departments to engineering functions as thermal-indicator coatings become safety-critical subcomponents. Direct technical engagement between coating suppliers and OEM thermal engineers is replacing distributor-mediated transactions. This shift is most visible in German automotive supply chains, where battery pack designers now mandate direct supplier qualification audits.
Global Thermochromic Paint Market Segmentation
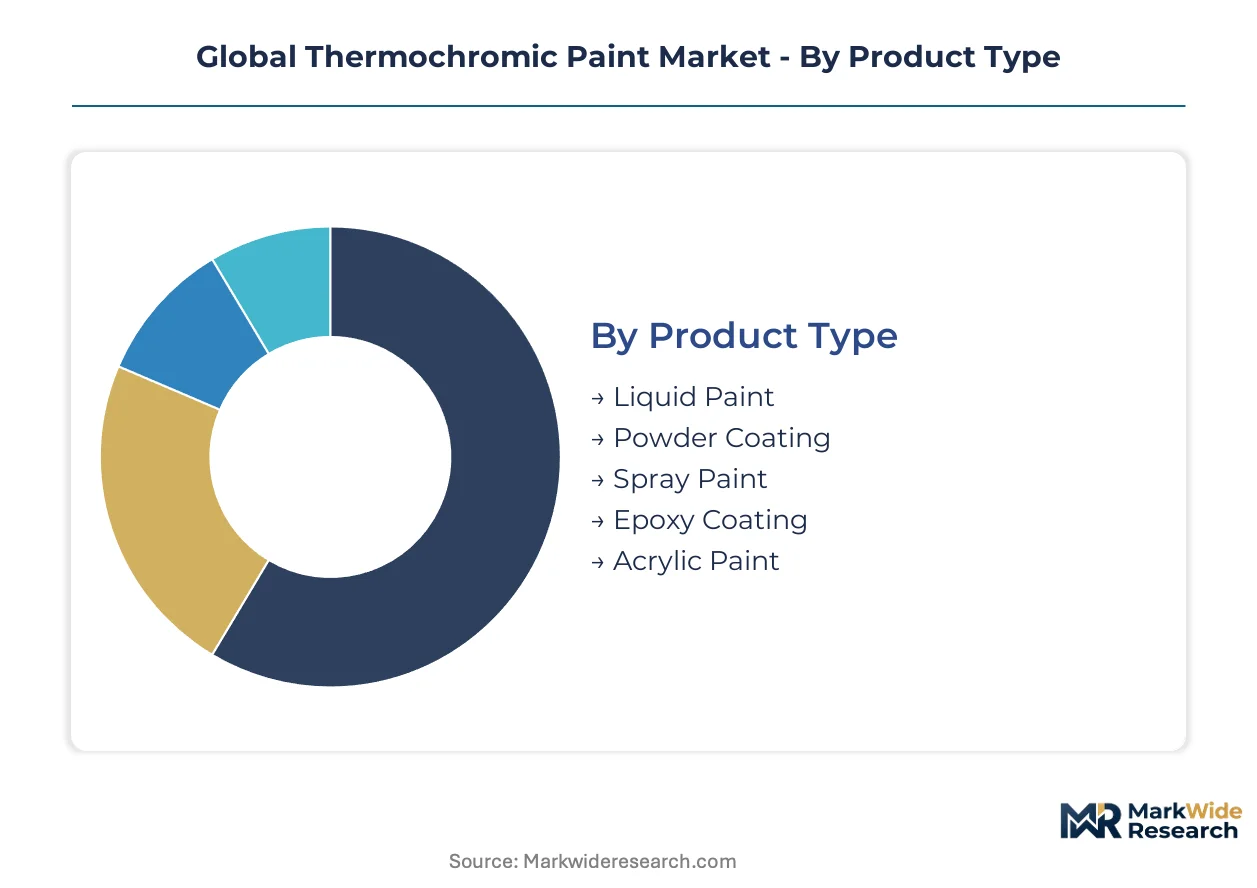
Thermochromic paint formulations fragment across multiple technical and commercial dimensions, with each axis carrying distinct regulatory footprints and supply chain configurations. Segmentation clarity enables buyers to match thermal-indicator specifications against end-use durability requirements and jurisdiction-specific compliance obligations.
Product Type:
REACH registration thresholds and EPA TSCA notification requirements diverge sharply across physical form factors, with liquid systems facing stricter VOC scrutiny while powder variants navigate fluoropolymer feedstock constraints.
- Liquid Paint:Waterborne and solvent-borne resin systems disperse leuco dyes or liquid crystals for spray, dip, or brush application. Demand concentrates in automotive battery pack manufacturing across China and Germany, where cell-level thermal monitoring requires calibrated color transition at specific thresholds. ECHA's tightened purity specifications for imported concentrates are filtering supplier pools.
- Powder Coating:Thermoset formulations encapsulate chromic pigments within zero-VOC powder particles for electrostatic deposition. Appliance manufacturers in Italy and Turkey specify these grades for oven door thermal indicators, accepting higher curing energy costs in exchange for thick-film durability and elimination of solvent handling permits.
- Spray Paint:Aerosol-dispensed systems target aftermarket maintenance and field repair applications. Industrial equipment makers in Brazil use portable thermal-indicator sprays for pressurized vessel inspection.
- Epoxy Coating:Two-part systems bond chromic compounds within high-crosslink density matrices. Offshore platform operators in Norway specify marine-grade epoxies for subsea pipeline temperature monitoring.
- Acrylic Paint:Thermoplastic resin bases enable reversible color change in architectural and decorative applications. Building envelope contractors in Australia apply acrylic thermochromics to exterior cladding for passive thermal visualization.
Established volume favors Liquid Paint; emerging adoption favors Powder Coating.
Technology:
Raw material cost tiers and intellectual property concentration separate commodity dye systems from precision liquid crystal formulations serving medical and aerospace sensing.
- Leuco Dye:Spirolactone-based molecules undergo reversible ring-opening upon thermal stimulus, microencapsulated for environmental protection. Chinese crystallization houses in Zhejiang province supply global formulators, though EPA TSCA Section 5 notification delays novel dye launches. Automotive OEMs specify encapsulated grades for battery thermal runaway indication.
- Liquid Crystals:Cholesteric mesophases exhibit selective light reflection across narrow temperature bands. Medical device manufacturers in Switzerland and Japan source calibrated liquid crystal coatings for non-invasive skin temperature mapping, paying premium prices for precision unavailable from dye alternatives.
- Metal Complex:Coordination compounds of cobalt, nickel, or copper enable irreversible thermal indicators for fire safety documentation. French construction firms apply metal-complex paints to structural steel for post-fire thermal exposure assessment.
- Phase Change:Paraffin-encapsulated systems combine thermal mass storage with visual indication. Building envelope designers in Sweden integrate phase-change thermochromics for passive temperature regulation visualization.
- Photochromic Integration:Dual-responsive systems combine thermal and UV-triggered color change. Consumer electronics producers in South Korea specify these for device casings with multi-stimulus aesthetic response.
Cost-sensitive volume concentrates in Leuco Dye; precision applications drive Liquid Crystals expansion.
Application:
End-use thermal envelope specifications and safety-criticality ratings determine formulation grade selection, with automotive and medical segments demanding calibrated performance unavailable from novelty-grade alternatives.
- Automotive Components:Battery cell, module, and pack-level thermal indicators monitor thermal runaway precursors. Chinese EV manufacturers specify transition temperatures calibrated to specific cell chemistries, creating specification pull-through from CATL and BYD to pack integrators.
- Temperature Sensors:Industrial process equipment and HVAC systems deploy visual-indicator coatings where electronic sensing is impractical. German chemical plant operators specify calibrated liquid crystal strips for reactor vessel monitoring.
- Building Envelope:Architectural coatings provide passive thermal visualization for energy audit and occupant awareness. Dutch housing associations apply thermochromic facades to social housing stock for heating behavior feedback.
- Consumer Electronics:Device casings and accessories incorporate color-change aesthetics. Japanese smartphone accessory producers source leuco dye formulations for limited-edition thermal-responsive finishes.
- Textiles:Fabric coatings and printed patterns respond to body heat or ambient conditions. Italian fashion houses specify thermochromic treatments for seasonal collections.
Specification authority concentrates in Automotive Components; aesthetic-driven adoption expands in Textiles.
End User:
Procurement sophistication and technical qualification requirements separate safety-critical OEM specifications from commoditized decorative purchases.
- Vehicle Manufacturers:Battery engineering teams specify direct supplier relationships for thermal-indicator coatings, bypassing distributor channels. German automotive OEMs mandate on-site encapsulation facility audits for qualified supplier status.
- Industrial Equipment Makers:Pressure vessel and rotating machinery producers specify thermochromic safety indicators for regulatory compliance. Indian draft factory safety regulations under the Ministry of Labour and Employment are considering mandatory adoption.
- Construction Firms:Commercial and residential contractors apply architectural-grade coatings for energy visualization and safety marking. French building codes reference thermochromic leak-detection for refrigeration equipment under EU F-Gas Regulation phase-down.
- Electronics Producers:Consumer device and component manufacturers specify aesthetic and functional thermal indicators. South Korean display panel makers source liquid crystal coatings for quality control thermal mapping.
- Textile Designers:Fashion and technical fabric creators specify color-change effects for seasonal and functional applications. British performance apparel brands integrate thermochromic treatments for outdoor gear thermal status indication.
Direct technical engagement dominates Vehicle Manufacturers; distributor-mediated procurement persists in Construction Firms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Crystallization expertise for leuco dye production clusters in Zhejiang and Jiangsu provinces, creating geographic chokepoints that shape global formulation supply. This concentration forces coating compounders in Europe and North America to navigate import dependencies while domestic Chinese producers scale for export markets.
China
EV manufacturers specify thermochromic coatings for cell-level temperature monitoring, creating specification pull-through from CATL and BYD to pack integrators. SAMR's GB standards establish migration limits for thermochromic pigments in consumer goods and textiles. Zhejiang province hosts expanding crystallization capacity among domestic pigment houses, reducing import dependency for European and North American coating compounders.
Germany
Automotive OEMs mandate direct supplier qualification audits for thermal-indicator coatings, bypassing distributor channels. ECHA's REACH registration requirements govern leuco dye import and formulation within the European Union. Bavaria anchors German automotive supply chains where battery pack designers now specify direct technical engagement with coating suppliers.
United States
EPA TSCA oversight mandates pre-manufacture notification for novel chromic compounds, extending development timelines for next-generation formulations. Industrial equipment makers specify thermochromic safety indicators for pressurized vessel inspection. The Southeast manufacturing corridor hosts appliance producers adopting powder coating variants for zero-VOC compliance.
India
Draft factory safety regulations under the Ministry of Labour and Employment are considering mandatory temperature-indicating coatings for pressurized equipment. BIS standards govern industrial safety equipment specifications. Maharashtra's chemical manufacturing belt positions domestic formulators to supply industrial safety applications if mandates materialize.
Japan
Medical device manufacturers source calibrated liquid crystal coatings for non-invasive skin temperature mapping, paying premium prices for precision. METI oversees chemical substance management under CSCL frameworks. Kansai region hosts specialized formulators serving medical and industrial sensor applications with liquid crystal technology.
Global Thermochromic Paint Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes within the thermochromic paint market. Integrated pigment-chemistry specialists compete against toll-encapsulation houses and regional formulators. The structure fragments across three strategic archetypes: crystallization-scale suppliers, microencapsulation specialists, and application-specific formulators. Dominant competitive moves include backward integration into leuco dye production and geographic expansion through qualified supplier status with automotive OEMs.
Among Germany-based chemical conglomerates, BASF SE exemplifies the integrated pigment-chemistry archetype. LCR Hallcrest LLC occupies a position within the liquid crystal specialization tier. Chromatic Technologies Inc. represents the North American application-specific formulator model. These three anchors illustrate how competitive positioning separates commodity-scale suppliers from precision-calibration specialists serving medical and aerospace sensing applications.
| Leading Market Players |
|---|
| BASF SE |
| Kolortek Co. Ltd. |
| Chromatic Technologies Inc. |
| Olikrom SAS |
| Smarol Industry Co. Ltd. |
| LCR Hallcrest LLC |
| QCR Solutions Corp |
| Axalta Coating Systems Ltd. |
| Matsui International Inc. |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between Chinese crystallization houses and European coating compounders lock in leuco dye supply access while capping price volatility for REACH-compliant grades. These contracts bundle volume commitments with purity certification, creating tiered pricing visibility that spot purchasers cannot replicate.
Pricing Analysis
REACH registration thresholds dictate the pricing tier structure across the European Union, separating qualified suppliers from commodity traders. Three-tier pricing structure across premium, standard, and economy levels reflects encapsulation quality, transition temperature calibration precision, and automotive OEM qualification status. Cost compression in standard grades is intensifying because Zhejiang crystallization capacity expansion feeds oversupply into undifferentiated dye markets. Industrial equipment makers exhibit highest price sensitivity, while medical device manufacturers pay premiums for liquid crystal precision unavailable elsewhere.
Supply Chain Analysis
Zhejiang and Jiangsu province crystallization clusters create a geographic chokepoint that constrains global leuco dye availability for European and North American formulators. Production draws from fluoropolymer binders sourced from Japan and semiconductor-grade fluorochemical feedstocks from the United States, creating cross-industry competition for critical inputs. Single-source vulnerability runs through microencapsulation toll houses in Germany and Japan where color chemist expertise concentrates. Distribution runs through direct technical engagement channels for automotive OEMs, with distributor-mediated flows serving construction and textile segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
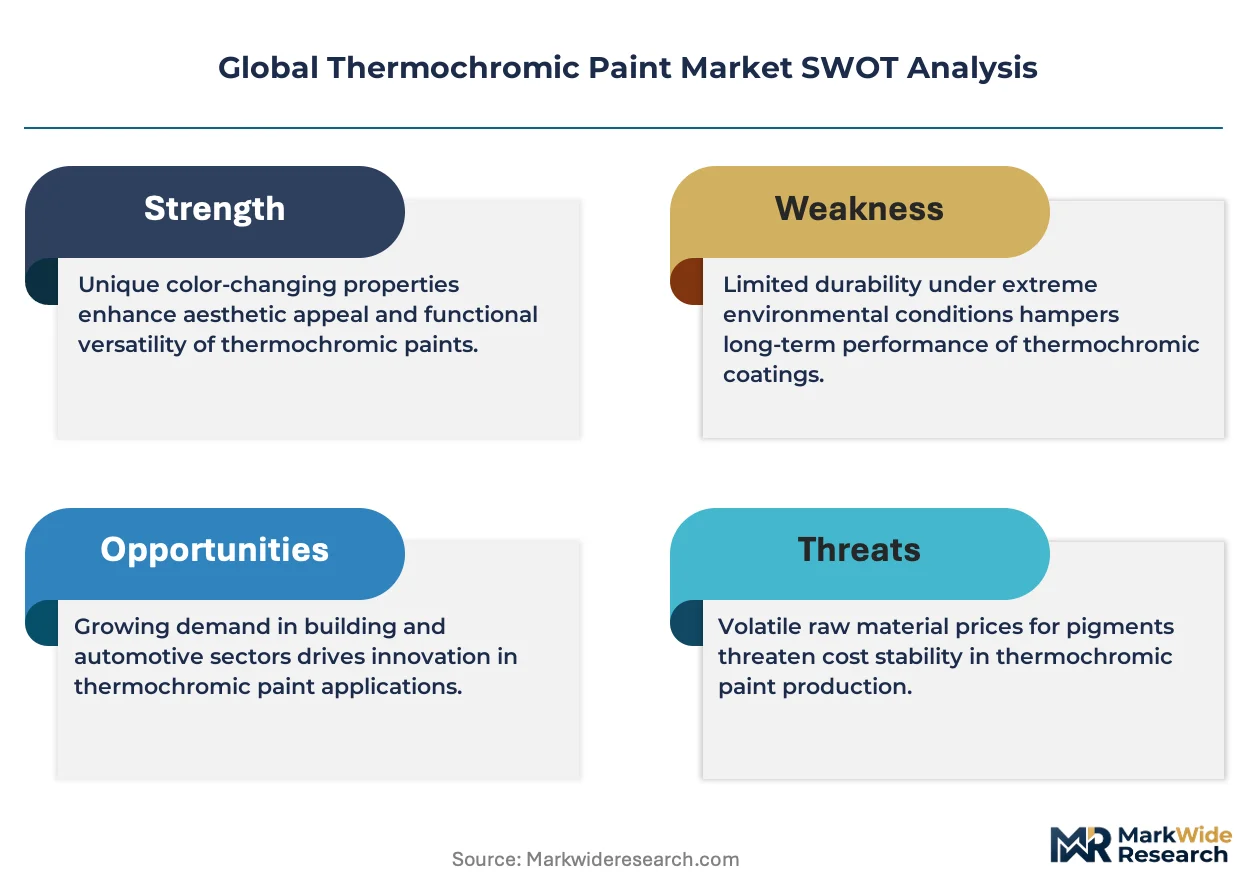
This market builds defensive moats through regulatory entrenchment—REACH dossier preparation and EPA TSCA notification timelines create switching costs that lock qualified suppliers into long-term OEM relationships.
For Market Incumbents: Secure backward integration into leuco dye crystallization capacity in Zhejiang province to capture margin pools currently flowing to Chinese pigment houses. Deepen direct technical engagement with German automotive OEM battery engineering teams before distributor relationships fully dissolve. Infrared thermography substitution in industrial maintenance budgets threatens visual-indicator coating volumes, requiring incumbents to pivot toward safety-critical automotive and medical applications where electronic sensing cannot compete. For New Entrants and Emerging Players: Aftermarket spray paint services for field repair applications represent an underserved layer where incumbents under-serve through distributor-heavy models. Brazil's industrial equipment maintenance sector and India's prospective factory safety mandates offer penetrable geographies with lower qualification barriers than EU automotive supply chains. A technical service-led go-to-market approach—deploying application engineers for on-site calibration support—differentiates against commodity traders lacking formulation expertise. For Investors and Strategic Acquirers: Microencapsulation specialists with captive relationships to Japanese medical device manufacturers present acquisition targets with durable premium pricing power. Long-term viability hinges on regulatory entrenchment deepening as ECHA and EPA tighten novel compound notification requirements, extending development timelines that favor incumbents with existing dossiers. Watch for EPA TSCA Section 5 notification backlogs as an inflection indicator—delays beyond typical cycles signal regulatory capacity constraints that advantage established players with prior approval pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Leuco Dye Crystallization | Captures margin pools concentrated in Zhejiang province pigment houses supplying global formulators. |
| Direct OEM Technical Engagement Programs | Bypasses distributor channels as German automotive battery engineers mandate supplier qualification audits. |
| Microencapsulation Capacity Expansion | Serves automotive battery thermal runaway indication specifications requiring encapsulated environmental protection. |
| Dual Jurisdiction Regulatory Dossier Preparation | Simultaneous EPA TSCA and ECHA REACH submissions accelerate product launch cycles for novel chromic compounds. |
| Medical Device Calibration Partnerships | Locks in premium pricing with Swiss and Japanese manufacturers sourcing precision liquid crystal coatings. |
Research Methodology
Operator-level perspectives from coating formulation chemists, automotive battery thermal engineers, industrial safety equipment procurement managers, and leuco dye crystallization plant managers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against ECHA REACH registration databases, EPA TSCA pre-manufacture notification filings, SAMR GB standards documentation, and customs trade flows for thermochromic pigment categories. Bottom-up segment sizing triangulated against top-down market envelope estimates derived from automotive production volumes and coating content per vehicle assumptions.
Sensitivity analysis tested forecast robustness across alternative scenarios for regulatory timeline acceleration, crystallization capacity expansion rates, and substitution elasticity from infrared thermography. Segmentation dimensions modeled include product type, technology platform, application end-use, and geographic regulatory cluster. CAGRs were derived from fitted growth curves anchored to disclosed automotive electrification roadmaps and appliance manufacturing output projections. Industry-specific inputs incorporated battery pack thermal management specification evolution and F-Gas Regulation phase-down implementation pacing.
Forecasts assume regulatory continuity in REACH, EPA TSCA, and SAMR GB regimes; material policy shifts would require re-modeling. Specific risk factors include novel spirolactone dye toxicity reclassification, fluoropolymer feedstock diversion to semiconductor demand, and crystallization cluster disruption from environmental enforcement actions. Practitioners should keep alternative scenarios live as battery thermal management specification migration and medical device precision requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Global White Inorganic Pigments Market
Dyes and Pigments
Iridescent Pigments Market
Dyes and Pigments
Resin Pigments Market
Dyes and Pigments
Pharmaceutical Dyes Market
Dyes and Pigments
Acid Stable Blue Market
Dyes and Pigments
White Pigment Market
Dyes and Pigments
Global Cosmetic Pigments Market
Dyes and Pigments
Color Concentrates Market
Dyes and Pigments
Asia-Pacific Feed Pigments Market
Dyes and Pigments
Bismuth Vanadate Pigment Market
Dyes and Pigments
Organic Pigment Dispersions Market
Dyes and Pigments
Titanium Dioxide Pigment Market
Dyes and Pigments
Pigment Dispersion Resin Market
Dyes and Pigments
Metallic Pigments Market
Dyes and Pigments
Global Aluminum Anodizing Dyes Market
Dyes and Pigments
Carmine Market