
 France Silica Sand Market | 2026-2036
France Silica Sand Market Size, Share, and Industry Trends Forecast 2026-2036
France Silica Sand Market Intelligence
Long-term supply contracts with embedded technical service layers is restructuring how silica sand gets monetized in France. Sibelco leverages its vertically integrated quarry-to-port logistics to dominate coastal deliveries. Imerys S A sustains its position through specialized high-purity chemical grade production at dedicated sites. SAMIN anchors foundry supply chains with consistent grain-size engineering for precision casting.
Silica sand consists predominantly of silicon dioxide with particle sizes typically ranging from 0.063 mm to 2 mm, mined from sedimentary deposits or processed from quartz rock for industrial purity standards. Its primary commercial purpose centers on providing the fundamental silica feedstock for glass melting, metal casting molds, construction concrete additives, and chemical synthesis substrates. Glass grade material commands the deepest margin pools due to stringent iron oxide limits below 0.02 percent, while foundry grade competes on thermal stability and roundness coefficients. Construction grade occupies volume leadership in direct sales channels tied to infrastructure batching plants.
ANSM workplace exposure directives and REACH registration requirements shape product certification burdens for domestic producers and importers alike. France's national environmental regulator enforces quarry rehabilitation bonds that concentrate operating permits among capitalized incumbents. Stakeholders must monitor how EU carbon border adjustments on imported silica-bearing materials reshape sourcing economics for coastal consumers.
Market Dynamics
France's silica sand sector is restructuring around REACH compliance and ANSM workplace exposure limits, which are compressing permissible impurity thresholds and forcing capital upgrades across extraction and processing sites.
Growth Catalysts
- Glass manufacturing expansion:Northern France's float glass corridors near Lille and Valenciennes are drawing increased silica feedstock volumes as flat glass capacity expands for automotive and construction glazing.
- Foundry precision demands:SAMIN and specialized processors are engineering tighter grain-size distributions for investment casting of aerospace turbine components, pulling higher-grade material through the supply chain.
- EU Green Deal alignment:Quarry rehabilitation bonds and circular economy mandates are favoring capitalized incumbents with integrated logistics, consolidating permit access among established operators.
Market Restraints
- Energy cost volatility:Wet processing and drying operations at quarry sites face margin compression from natural gas and electricity price swings, particularly affecting mid-scale processors without captive renewable supply.
- Import substitution limits:Coastal consumers remain tethered to domestic Hauts-de-France supply due to EU carbon border adjustment exposure on silica-bearing bulk shipments from North African or Turkish sources.
- Substitution pressure from cullet:Container glass manufacturers are elevating recycled glass percentages in furnace batches, directly displacing virgin silica sand volumes in certain melting applications.
Strategic Opportunities
- High-purity chemical grade expansion:Imerys S A and specialized producers can extend capacity at dedicated sites for semiconductor and solar polysilicon precursor markets, commanding premium spreads over construction grades.
- Port-integrated logistics:Sibelco's quarry-to-port infrastructure provides template for coastal delivery optimization to Normandy and Brittany industrial consumers currently served by higher-cost inland trucking.
- ANSM compliance services:Technical service layers embedded in long-term supply contracts create recurring revenue streams through exposure monitoring, dust suppression engineering, and worker safety certification.
Industry Challenges
- Geological assay standardization:Variability in iron oxide and heavy mineral content across Hauts-de-France deposits requires continuous beneficiation adjustment, complicating furnace batch consistency for glass customers.
- Permit renewal timelines:France's national environmental regulator extends quarry extension approvals across multi-year review cycles, freezing capacity expansion plans and requiring advanced reserve development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Silica Sand Market |
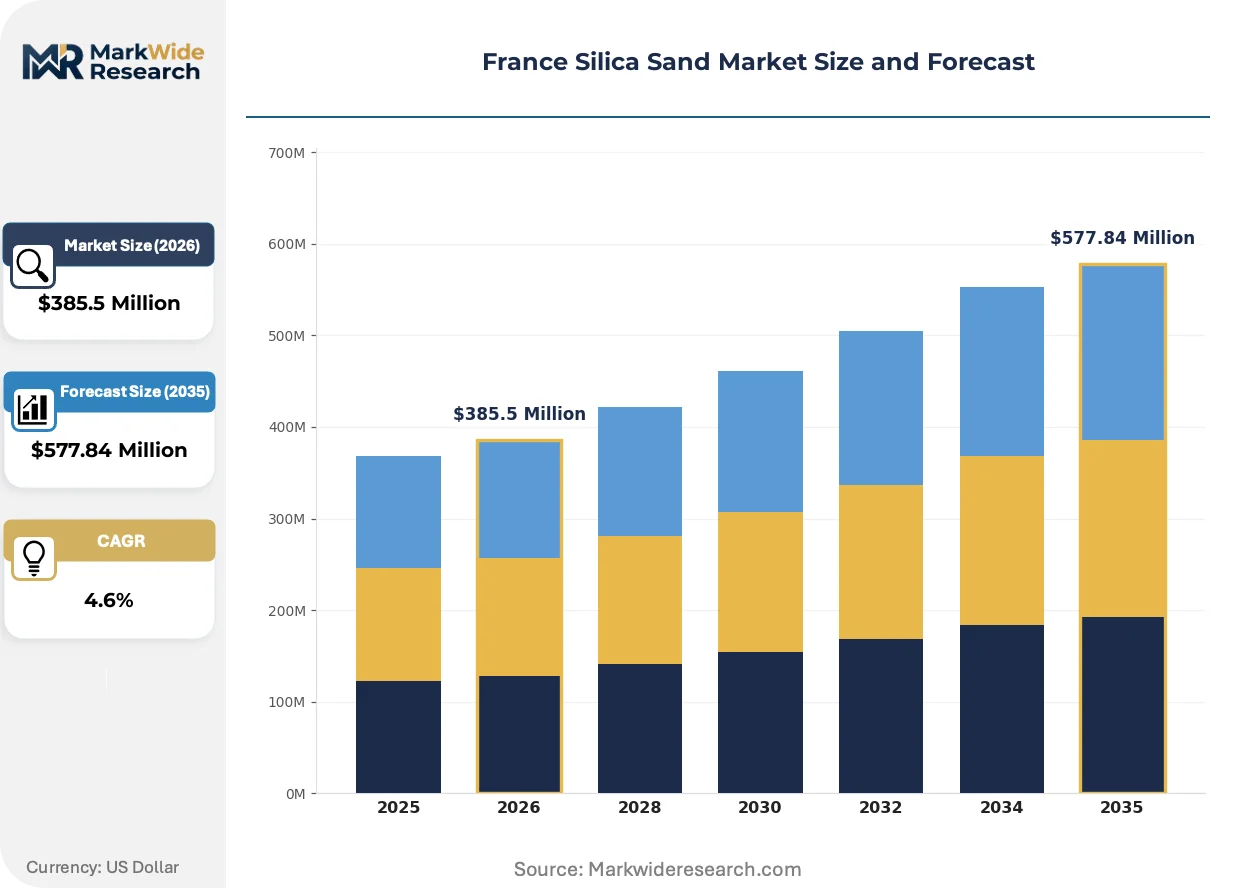
| Market Size in 2026 | $385.5 Million |
| Market Size in 2035 | $577.84 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Grade, Foundry Grade, Construction Grade, Chemical Grade End User: Construction, Chemical Manufacturing, Glass Manufacturing, Foundries Application: Construction Materials, Coatings, Electronics, Water Filtration Distribution Channel: Direct Sales, Online Sales, Retail, Wholesale |
| Companies Covered | Solvay S A, Argeco Développement, Sibelco, Quartzwerke GmbH, Sablieres Palvadeau Les Douemes, Imerys S A, Fulchiron Industrielle, Equoquarz GmbH, SAMIN (Saint-Gobain), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Silica Sand Market Strategic Shifts & Innovations
Digital assay integration and automated beneficiation are compressing quality variance in France's silica sand output, while regulatory telemetry requirements are embedding sensor networks throughout extraction and processing operations.
Optical sorting technology is absorbing silica sand beneficiation workflows across northern France's processing corridors. Glass manufacturers in the Lille-Valenciennes axis are adopting sensor-based particle separation to hit sub-0.02 percent iron oxide thresholds without secondary chemical washing. This compression of purification steps is absorbing capital that previously flowed into flotation circuit expansion, redirecting investment toward AI-driven classification infrastructure.
ANSM workplace exposure directives are mandating real-time respirable silica monitoring across French quarrying operations. The regulator's tightening permissible exposure limits are forcing dust suppression retrofit investments and continuous air quality telemetry deployment. Foundry supply chains are most affected, with precision casting facilities demanding certified low-dust material grades accompanied by exposure documentation from extraction through final delivery.
Long-term technical service contracts are displacing spot purchasing across France's glass and foundry sectors. Buyers are unbundling silica supply from embedded engineering support, creating multi-year agreements where processors guarantee grain-size consistency, chemical certification, and regulatory compliance documentation. This behavior shift is most visible in the Hauts-de-France corridor, where integrated logistics providers are capturing volume through service-augmented supply rather than commodity pricing alone.
France Silica Sand Market Segmentation
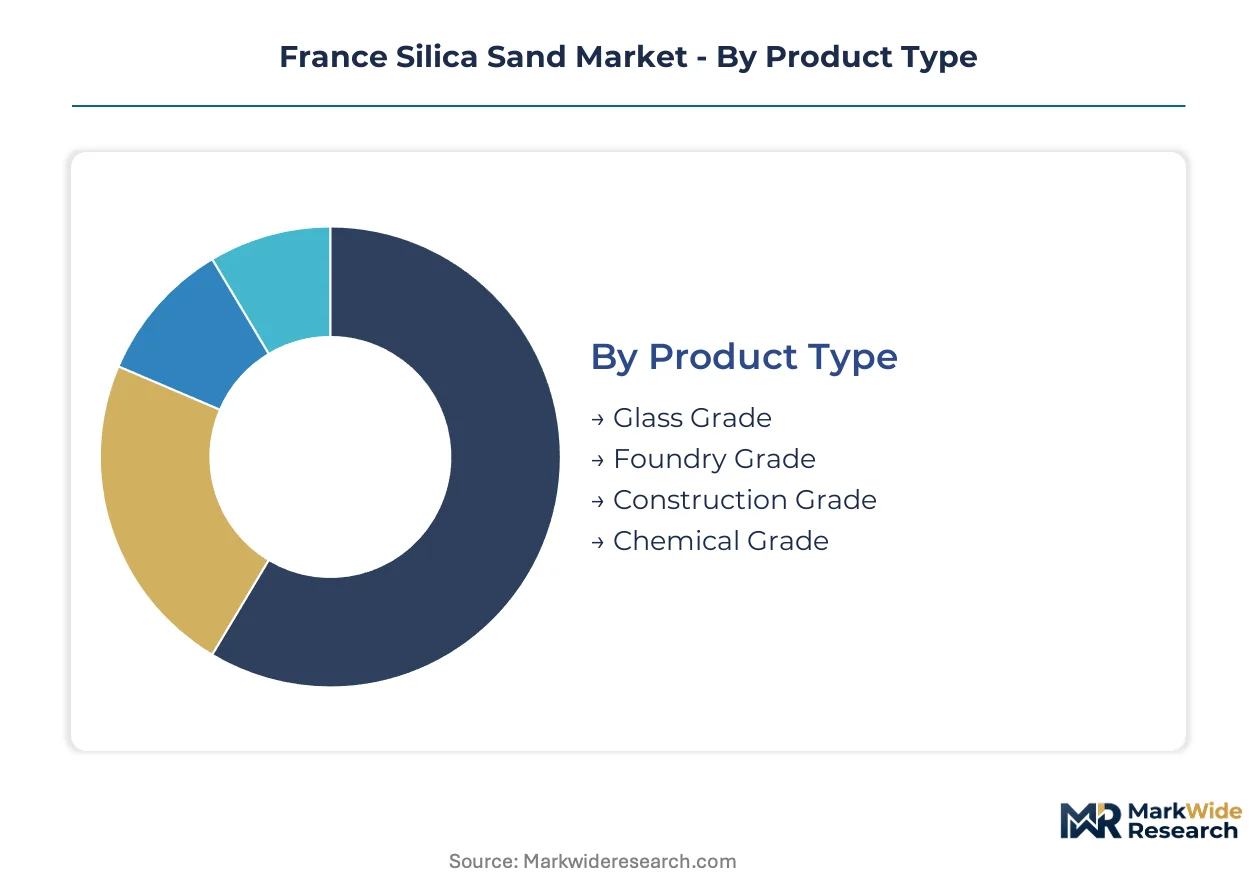
Segmentation in France's silica sand market reveals how technical specifications and regulatory compliance reshape procurement economics. Glass manufacturers impose iron oxide ceilings below 0.02 percent, while foundries prioritize thermal stability and grain roundness. Understanding these divides exposes where margin pools concentrate versus where volume flows commoditize.
Product Type:
Volume leadership sits with construction grade, yet premium capture concentrates in chemical and glass specifications that command specialized beneficiation investments.
- Glass Grade:Stringent iron oxide limits below 0.02 percent define this specification, requiring optical sorting or chemical washing to achieve furnace-ready purity. Northern France's float glass corridors near Lille and Valenciennes absorb the majority of domestic output, with ANSM exposure documentation now mandatory for bulk deliveries. REACH registration burdens concentrate procurement among capitalized incumbents with certified beneficiation infrastructure.
- Foundry Grade:Thermal stability and roundness coefficients determine casting performance, particularly for investment molds in aerospace turbine production. SAMIN and specialized processors engineer tighter grain-size distributions to meet precision demands, pulling material through Hauts-de-France supply chains with embedded technical service layers. Dust suppression certification accompanies shipments under tightening workplace exposure directives.
- Construction Grade:Concrete additive and mortar applications dominate volume flows, with direct sales channels tied to infrastructure batching plants across northern quarrying zones.
- Chemical Grade:High-purity silicon dioxide for semiconductor and solar polysilicon precursors commands the steepest premium spreads, produced at dedicated Imerys S A sites with specialized assay protocols.
Mature deployment sits with construction grade. Newer deployment is concentrated in chemical grade expansion for solar and electronics feedstocks.
End User:
Customer procurement patterns split between long-term technical service contracts in glass and foundry sectors versus spot purchasing dominance in construction applications.
- Glass Manufacturing:Flat glass capacity expansion for automotive and construction glazing drives silica feedstock absorption in the Lille-Valenciennes axis. Container glass producers are elevating recycled cullet percentages, directly displacing virgin sand volumes in certain melting applications and forcing suppliers to certify batch consistency guarantees.
- Foundries:Precision casting facilities demand certified low-dust material grades with exposure documentation from extraction through final delivery, restructuring supply agreements around ANSM compliance services.
- Construction:Infrastructure batching plants and concrete additive formulators purchase primarily through direct sales channels, with price sensitivity limiting service embedding.
- Chemical Manufacturing:Semiconductor and solar precursor producers source through dedicated high-purity supply chains with multi-year assay consistency requirements.
Procurement sophistication is climbing fastest in foundries. Volume concentration remains anchored in construction.
Application:
Technical performance requirements stratify silica sand deployment across industrial processes, with electronics and coatings demanding precision that construction materials tolerate less.
- Construction Materials:Concrete additives, mortar formulations, and specialty cement blends absorb the largest tonnage flows through direct sales to batching plants.
- Coatings:Industrial paints and surface treatments require controlled particle size distributions for texture and durability performance.
- Electronics:Semiconductor substrate and solar cell manufacturing pull high-purity chemical grade material through dedicated supply chains with continuous assay verification.
- Water Filtration:Grain-size engineering for porosity and contaminant capture specifications serves municipal and industrial treatment facilities.
Specification intensity peaks in electronics. Volume scale dominates construction materials.
Distribution Channel:
Logistics integration determines competitive positioning, with coastal quarry-to-port infrastructure compressing delivery costs against inland trucking alternatives.
- Direct Sales:Glass manufacturers and foundries negotiate multi-year agreements embedding technical service layers, grain-size consistency guarantees, and regulatory compliance documentation.
- Wholesale:Construction grade volume flows through regional distributors serving infrastructure batching plants across Hauts-de-France and beyond.
- Retail:Bagged specialty grades for smaller foundries and coating formulators move through construction supply outlets.
- Online Sales:Digital procurement platforms are emerging for standardized construction grade specifications with transparent assay documentation.
Relationship intensity clusters in direct sales. Channel experimentation is advancing in online platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's silica sand production concentrates in the Hauts-de-France corridor, while consumption spreads across northern industrial zones and Atlantic coastal manufacturing. This geographic split shapes logistics economics and regulatory enforcement patterns.
Hauts-de-France
Float glass furnaces near Lille and Valenciennes absorb the majority of domestic glass-grade output. ANSM workplace exposure directives mandate real-time respirable silica monitoring across quarrying operations here. Sibelco's quarry-to-port infrastructure at coastal terminals enables efficient bulk delivery to Normandy and Brittany consumers.
Île-de-France
Construction-grade silica flows into concrete batching plants serving Greater Paris infrastructure projects. The national environmental regulator enforces quarry rehabilitation bonds that concentrate operating permits among capitalized incumbents. Foundry supply chains here demand certified low-dust material grades with exposure documentation from extraction through delivery.
Provence-Alpes-Côte d'Azur
Specialized chemical-grade production for semiconductor precursors operates at dedicated sites with specialized assay protocols. REACH registration requirements shape product certification burdens for producers serving electronics manufacturers. Solar polysilicon feedstock demand is pulling high-purity material through dedicated supply chains with continuous verification.
Auvergne-Rhône-Alpes
Precision casting facilities for aerospace turbine components source engineered grain-size distributions from northern suppliers. EU Green Deal alignment favors capitalized incumbents with integrated logistics, consolidating permit access. Container glass manufacturers in this zone are elevating recycled cullet percentages, displacing virgin sand volumes in certain melting applications.
Nouvelle-Aquitaine
Coastal consumers here remain tethered to domestic Hauts-de-France supply due to EU carbon border adjustment exposure on imported silica-bearing bulk shipments. Wet processing and drying operations face margin compression from energy price volatility. Digital procurement platforms are emerging for standardized construction-grade specifications with transparent assay documentation.
France Silica Sand Market Key Industry Players
Top-tier vendors anchor integrated quarry-to-port logistics, while mid-scale processors compete on regional delivery relationships. The market structure favors capitalized incumbents with certified beneficiation infrastructure and multi-year technical service contracts. Three archetypes dominate: vertically integrated multinationals with coastal terminals, specialized high-purity chemical-grade producers, and regional foundry-grade specialists with precision engineering capabilities. Competitive moves concentrate on port-integrated logistics optimization and embedded compliance service layers.
Within the integrated logistics tier, Sibelco and Imerys S A exemplify capitalized incumbents leveraging quarry-to-port infrastructure. SAMIN occupies a position as the foundry-grade specialist with consistent grain-size engineering capabilities. These three anchors demonstrate how technical service embedding and regulatory compliance documentation are restructuring procurement economics away from commodity pricing alone.
| Leading Market Players |
|---|
| Solvay S A |
| Argeco Développement |
| Sibelco |
| Quartzwerke GmbH |
| Sablieres Palvadeau Les Douemes |
| Imerys S A |
| Fulchiron Industrielle |
| Equoquarz GmbH |
| SAMIN (Saint-Gobain) |
| Others |
Cost & Logistics Intelligence
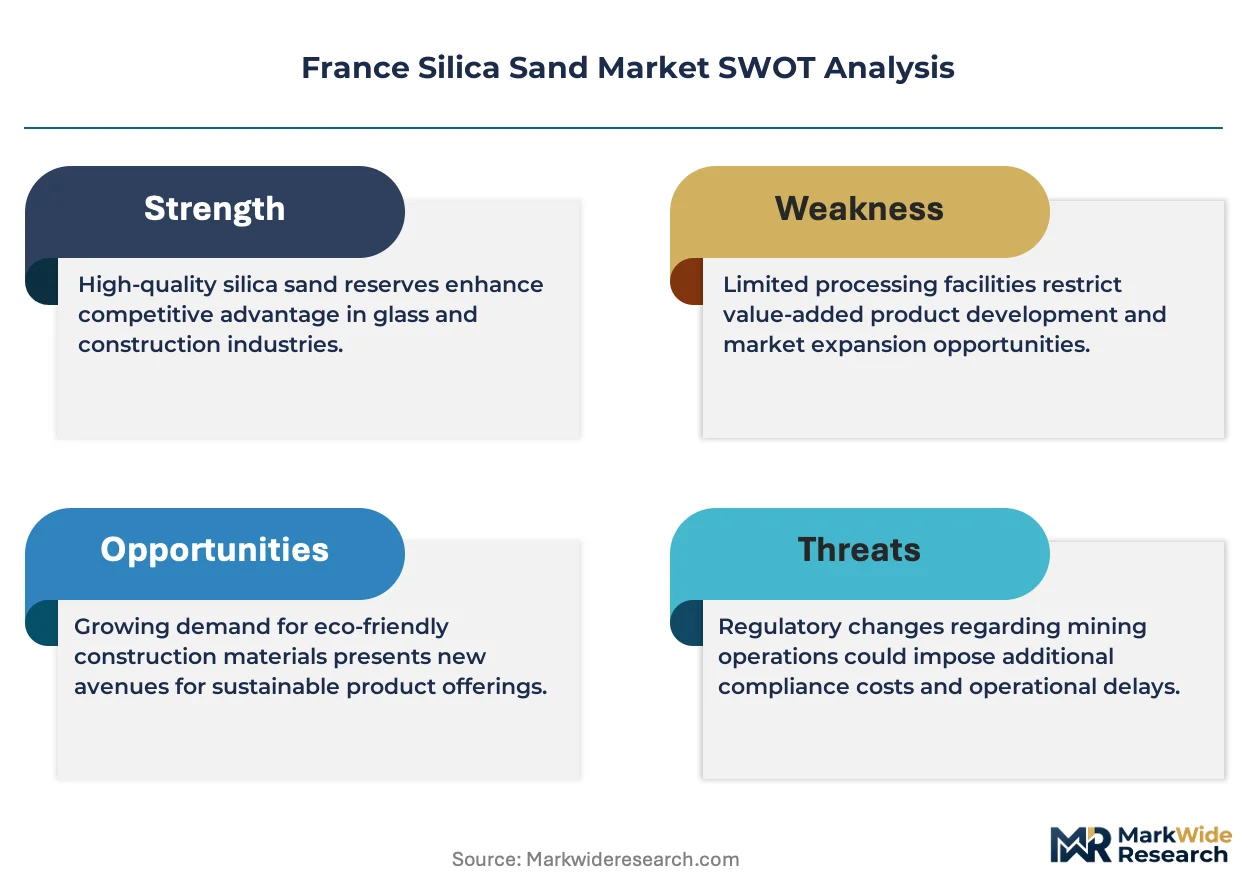
EU Green Deal quarry rehabilitation bonds gate both qualified supply and premium-tier pricing access in France's silica sand market, concentrating operating permits among capitalized incumbents with certified beneficiation infrastructure while compressing margin pools for mid-scale processors lacking bonded reserves.
Pricing Analysis
Margin tightening in chemical grade reflects Imerys S A's dedicated site premiums and semiconductor precursor demand pull. Three-tier pricing structure across premium, standard, and economy levels separates high-purity chemical grade from foundry grade with dust certification from construction grade spot purchases. Pricing pressure intensifies in glass grade as optical sorting capital costs compress purification spreads. Construction buyers exhibit highest price sensitivity through direct batching plant channels, while semiconductor manufacturers accept premium spreads for assay consistency guarantees.
Supply Chain Analysis
Quarry rehabilitation spoil and processed water recycling flows are embedding circular economy costs into Hauts-de-France extraction economics. Supply concentrates in France's northern quarrying corridor near Lille and Valenciennes, with secondary sourcing from Belgian cross-border deposits. Wet processing draws from natural gas and electricity inputs, with drying operations resting on energy price volatility exposure. Single-source vulnerability concentrates in coastal port infrastructure for Normandy and Brittany deliveries. Distribution runs through Sibelco's quarry-to-port terminals for bulk glass grade, regional wholesale for construction volume, and direct technical service contracts for foundry precision grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's silica sand market reads as supply-constrained, with ANSM workplace exposure permit renewal timelines freezing capacity expansion and propping pricing for qualified incumbents.
For Market Incumbents: Hedge against cullet substitution in container glass by embedding technical service layers into long-term supply agreements with exposure documentation and dust suppression engineering. Backward integration into captive renewable energy for wet processing and drying operations defends margin position against natural gas price volatility. Prioritize reserve development ahead of multi-year quarry extension review cycles to secure permit continuity. For New Entrants and Emerging Players: Launch via digital procurement platforms targeting standardized construction grade specifications with transparent assay documentation for Nouvelle-Aquitaine coastal consumers currently tethered to higher-cost inland trucking. White-space sits in ANSM compliance services bundled with shipments to precision foundries lacking in-house exposure monitoring. The most penetrable entry point is online sales channels for bagged specialty grades serving smaller coating formulators and regional distributors outside Sibelco's port-integrated logistics footprint. For Investors and Strategic Acquirers: Imerys S A's chemical grade capacity expansion announcements are the leading indicator that semiconductor and solar polysilicon precursor demand is structurally tightening high-purity supply. Long-term viability favors vertically integrated quarry-to-port operators with bonded reserves and certified beneficiation infrastructure over mid-scale processors facing energy cost volatility. Monitor ANSM permit renewal timelines for Hauts-de-France assets as early signals of capacity constraint inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Glass manufacturers in the Lille-Valenciennes corridor lock in grain-size consistency guarantees and regulatory compliance documentation. |
| Backward Integration | Captive renewable energy for wet processing and drying defends margins against natural gas price swings at quarry sites. |
| Green Manufacturing Transition | Quarry rehabilitation bonds and circular water recycling align with EU Green Deal mandates for permit renewal eligibility. |
| Capacity Expansion | Dedicated high-purity chemical grade sites serve semiconductor and solar polysilicon precursor markets commanding premium spreads. |
| Joint Venture | Port-integrated logistics partnerships optimize coastal delivery to Normandy and Brittany consumers beyond Hauts-de-France supply zones. |
Research Approach
Multi-period observation of ANSM workplace exposure directive implementation, REACH registration compliance trajectories, and optical sorting technology adoption anchored the trend analysis, supplemented by interviews with quarry operations managers, glass manufacturer procurement leads, foundry technical directors, and construction batching plant buyers. Secondary validation drew from ECHA registration databases, French national environmental regulator permit filings, EU carbon border adjustment mechanism disclosures, and Hauts-de-France regional industrial production statistics. Bottom-up volume modeling across grade tiers triangulated with top-down market sizing from customs trade flows and industry association aggregates.
Segment-weighting applied differential growth assumptions across glass grade, foundry grade, construction grade, and chemical grade specifications, with additional dimensional modeling by end-use industry and distribution channel complexity. CAGRs were derived from regression analysis of historical production volumes against float glass capacity expansion, foundry precision casting demand, and solar polysilicon feedstock pull across the projection horizon. Forecast inputs incorporated energy price scenario modeling for wet processing economics and quarry rehabilitation bond cost structures.
Permit renewal timeline delays, cullet substitution acceleration in container glass, and EU carbon border adjustment enforcement on North African imports are the dominant revision risks to supply and demand balances. Practitioners should monitor ANSM exposure limit tightening announcements, optical sorting capital deployment rates, and coastal port infrastructure investment commitments for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Asia Pacific Flexible Glass Market
Glass
Glass Block Market
Glass
Patterned Glass Market
Glass
Silica Sol Market
Glass
Recycled Glass Aggregates Market
Glass
Fiberglass Window Market
Glass
Global Glassware Market
Glass
Borosilicate Glass Market
Glass
Glass Reactors Market
Glass
Birefringent Crystals Market
Glass
Glazing Gel Market
Glass
Mexico Flat Glass Market
Glass
Global Vacuum Insulated Glass Market
Glass
East Africa Flat Glass Market
Glass
Europe Glassware Market
Glass
Silica Sand Market