
 Solar Control Glass Market | 2026-2036
Solar Control Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Control Glass Market Intelligence
The European Union's Green Deal and its focus on building energy efficiency is rebalancing demand toward higher-performance glazing products. Saint-Gobain leverages its extensive distribution network and R&D in high-performance coatings to capture this shift. AGC Inc. competes through its specialization in advanced architectural glass and automotive solutions. Guardian Industries sustains a strong market position with large-scale float glass manufacturing capabilities.
Solar control glass is a type of architectural or automotive glazing designed to reduce the amount of solar heat transmitted through it. This is achieved through specific material properties, such as metallic coatings applied via sputtering processes, which selectively reflect or absorb infrared radiation. Low-E coating technology dominates new installations, especially in commercial buildings, due to its superior thermal performance. Reflective coatings maintain a significant share in regions with intense sun exposure, while demand for electrochromic glass represents a high-margin, emerging segment.
Building energy codes, influenced by frameworks like the US Inflation Reduction Act (IRA) and the EU's Corporate Sustainability Reporting Directive (CSRD), are primary market accelerators. Compliance with ISO standards for glass in buildings ensures product quality and facilitates international trade. Key decisions for manufacturers will revolve around scaling production of next-generation dynamic glass technologies versus optimizing existing coated glass lines.
Market Dynamics
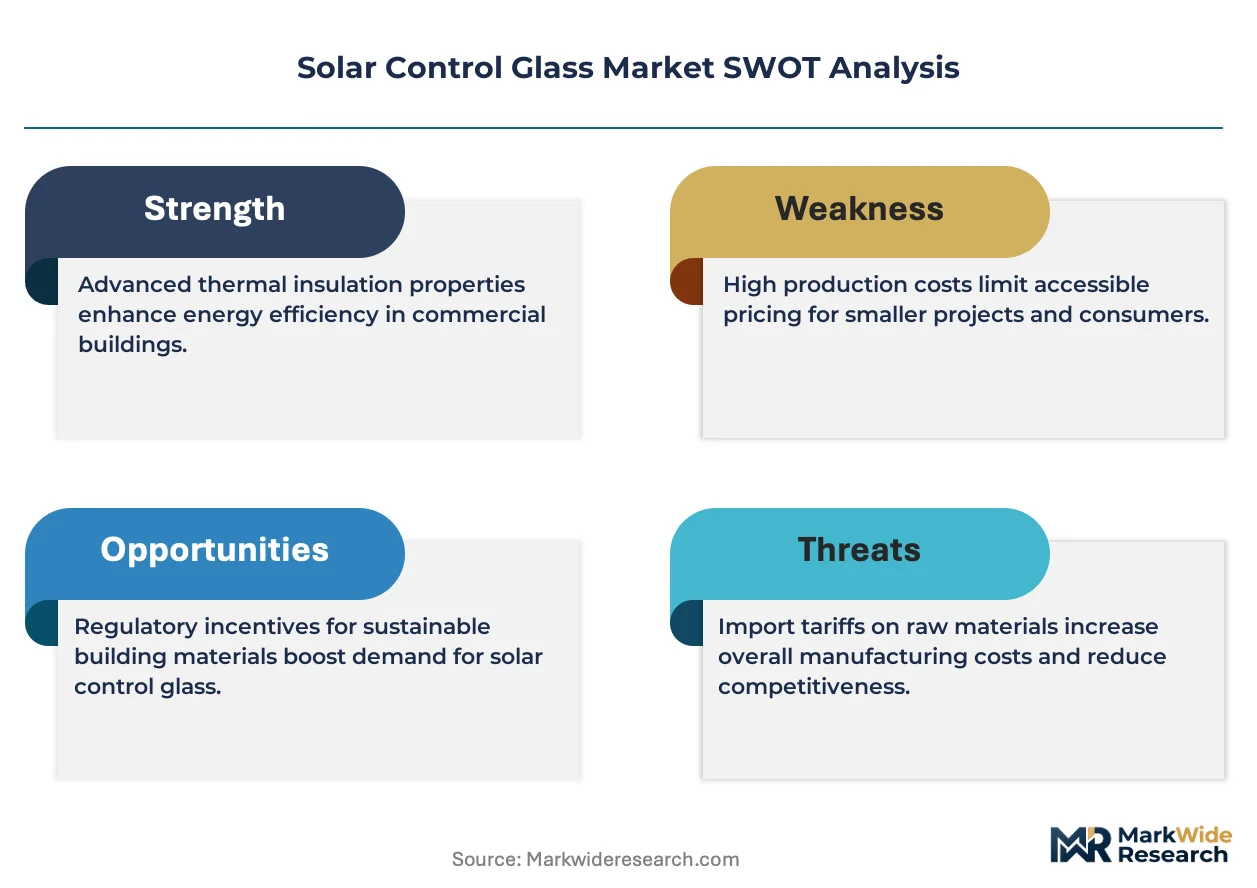
The market's primary structural force is the tension between stringent energy performance mandates for buildings and the high capital expenditure required to upgrade float glass production lines for advanced, multi-layer coatings. This dynamic dictates investment priorities and competitive intensity among manufacturers.
Growth Catalysts
- Building Energy Codes:The EU Green Deal's building renovation wave and China's dual carbon goals mandate higher energy efficiency, directly compelling the use of high-performance solar control glass in new construction and retrofitting projects.
- Advanced Coating Technology:The superior thermal performance of Low-E coating technology, applied via sputtering processes, makes it the dominant specification for commercial buildings seeking to minimize heat gain and reduce HVAC loads.
- Urban Development:Concentrated demand in rapidly urbanizing regions, particularly across China and Southeast Asia, provides a large-scale end market for architectural glass in new skyscrapers and public infrastructure.
Market Restraints
- High Initial Cost:The upfront cost of high-performance solar control glazing, especially dynamic electrochromic glass, remains a significant barrier for cost-sensitive residential and smaller commercial construction projects.
- Input Material Volatility:Production relies on sputtering processes using precious and industrial metals like silver and indium, whose price volatility can directly impact manufacturing costs and final product pricing.
- Retrofit Challenges:While a large opportunity, retrofitting existing buildings involves significant logistical complexity, higher labor costs, and potential tenant disruption, slowing the replacement cycle for older, less efficient glazing.
Strategic Opportunities
- Dynamic Glass Technologies:Emerging electrochromic and thermochromic glass segments represent a high-margin opportunity, targeting premium architectural projects where user control and maximum energy savings are prioritized.
- Automotive Sector Integration:The expansion of panoramic sunroofs in vehicles and the thermal management needs of electric vehicle batteries create new application avenues for specialized solar control glass and films.
- Emerging Market Adoption:As countries in Latin America and the Middle East begin to implement stricter building energy standards, there is a significant opportunity to introduce coated glass products into these underpenetrated markets.
Industry Challenges
- Manufacturing Complexity:Operating and maintaining large-scale float glass lines and multi-chamber vacuum sputtering coaters requires significant capital investment and a highly skilled technical workforce, which is in short supply.
- Performance Verification:Ensuring long-term durability and consistent performance of complex coatings in diverse climates is a persistent technical challenge that requires extensive testing and quality control.
- Integration with Building Systems:For dynamic glass, achieving seamless integration with building automation systems (BAS) and HVAC controls presents a software and hardware interoperability challenge for glass manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Control Glass Market |
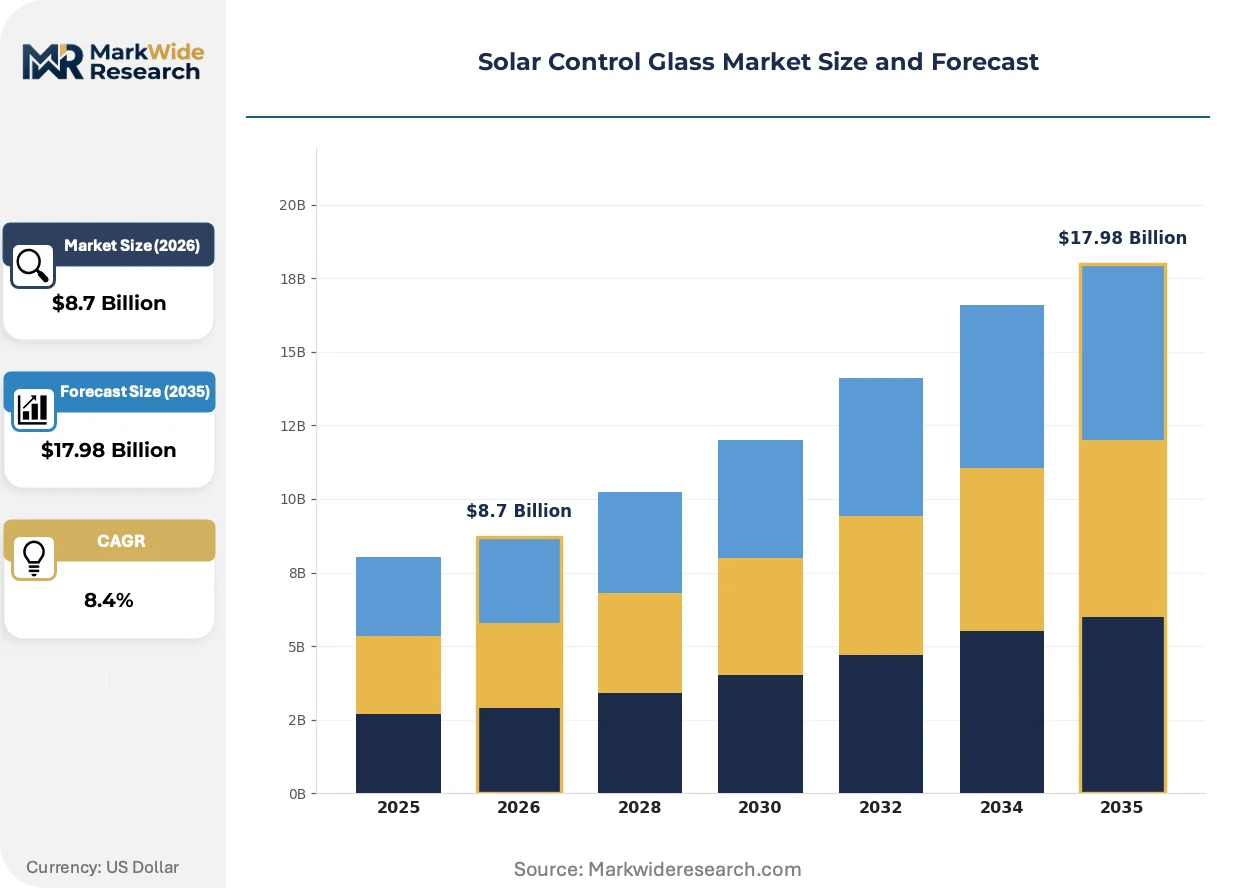
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tempered Glass, Laminated Glass, Double Glazing, Insulated Glass, Coated Glass Technology: Low-E Coating, Reflective Coating, Tinted Glass, Electrochromic Glass, Photochromic Glass Application: Commercial Buildings, Residential Construction, Automotive Windshields, Public Transport Vehicles, Greenhouses End User: Architects, Construction Firms, Vehicle Manufacturers, Agricultural Producers, Interior Designers |
| Companies Covered | CSG Holding, Nippon Sheet Glass, AGC Inc., Fuyao Glass Industry Group, Euroglas, Saint-Gobain, Central Glass Co., Ltd., Schott AG, Guardian Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Control Glass Market Strategic Shifts & Innovations
Material science advancements and the integration of smart building technologies are transforming glazing from a passive building envelope component into an active, responsive system. This evolution is redefining performance expectations and creating new value propositions for building owners and occupants.
Electrochromic glass provides on-demand, electronic control of solar heat gain and glare. Premium commercial office and high-end residential sectors are the primary adopters, despite higher initial costs. This active glazing technology is converging with building management systems, turning windows into responsive elements of a building's integrated HVAC and lighting strategy.
The European Union's Corporate Sustainability Reporting Directive (CSRD) creates a direct incentive for building owners to invest in energy efficiency upgrades. This directive forces large companies to disclose the energy performance of their real estate assets. The commercial real estate sector in Europe is accelerating retrofits with high-performance glass to comply and maintain portfolio value.
A shift in architectural specifications from static metrics to whole-building lifecycle energy modeling is gaining traction. This change disrupts the traditional method of selecting glass based on a single performance data point, favoring earlier collaboration between architects and engineers. The trend is most visible in large commercial projects in North America seeking green building certifications like LEED.
Solar Control Glass Market Segmentation
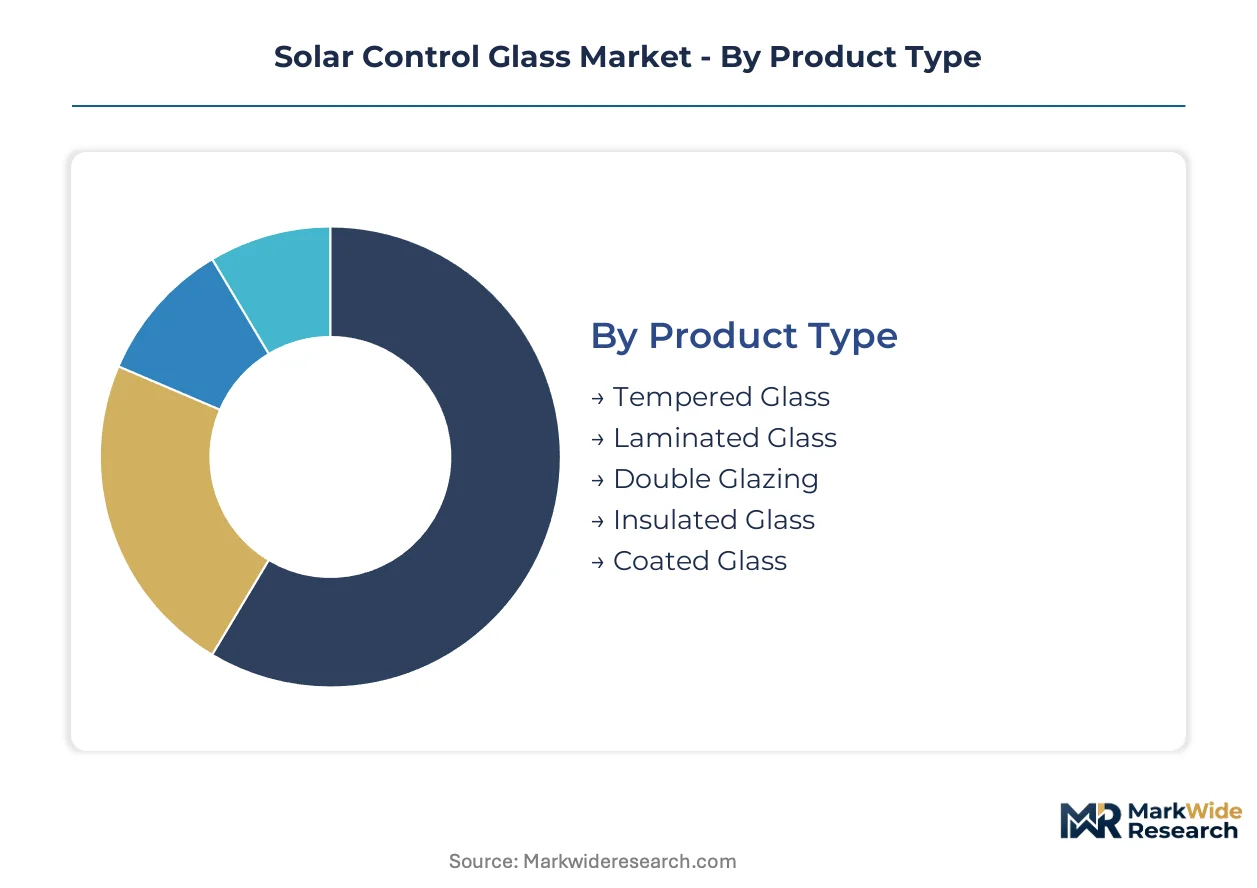
The solar control glass market structures its offerings to address diverse performance needs and architectural demands across various end-use sectors. Understanding these distinct segments allows manufacturers to align product development with specific market requirements and regulatory pressures. This granular view reveals where innovation drives value.
Product Type:
Product types span from foundational glass forms to those incorporating advanced treatments, reflecting varying levels of integration into building envelopes or vehicle structures.
- Double Glazing:Two glass panes separated by a vacuum or gas-filled space significantly enhance thermal insulation. Commercial buildings in colder climates adopt double glazing for energy performance.
- Coated Glass:Thin metallic layers applied via sputtering processes selectively reflect or absorb infrared radiation. New commercial installations specify coated glass for superior thermal performance.
- Tempered Glass:Heat-treated for strength and safety, it shatters into small, blunt pieces. Automotive side windows use this product.
- Laminated Glass:Multiple glass layers bonded by an interlayer maintain integrity upon breakage. Automotive windshields use laminated glass.
- Insulated Glass:Two or more glass panes separated by a sealed space provide thermal insulation. Building envelopes widely utilize insulated glass.
Volume placements concentrate in Double Glazing; the faster expansion belongs to Coated Glass.
Technology:
The technologies applied to solar control glass range from basic tinting to advanced dynamic systems, reflecting a spectrum of cost tiers and performance capabilities.
- Low-E Coating:Microscopically thin metallic layers minimize infrared and ultraviolet light. Commercial buildings consistently specify Low-E coating for reduced HVAC loads.
- Electrochromic Glass:This dynamic glazing allows electronic control of light and heat transmission. Premium architectural projects prioritize electrochromic glass for maximum energy savings.
- Reflective Coating:Metallic particles reflect solar radiation, reducing heat gain. Regions with intense sun exposure maintain strong demand.
- Tinted Glass:Colorants absorb solar energy, reducing heat and glare. This offers a cost-effective solution for residential applications.
- Photochromic Glass:This glass automatically darkens when exposed to ultraviolet light. Niche architectural applications utilize photochromic glass.
High-margin opportunities typically reside with Electrochromic Glass; value-focused solutions characterize Tinted Glass.
Application:
Solar control glass finds utility across various sectors, with demand volumes varying significantly between large-scale construction projects and specialized vehicle manufacturing.
- Commercial Buildings:Office towers and public institutions integrate solar control glass to manage temperatures and reduce HVAC energy consumption. The EU Green Deal compels adoption for energy efficiency.
- Automotive Windshields:Vehicles utilize solar control glass in windshields to reduce cabin heat and enhance passenger comfort. Panoramic sunroof expansion drives demand for specialized solutions.
- Residential Construction:Homes and multi-unit dwellings use solar control glass to improve comfort and lower energy bills.
- Public Transport Vehicles:Buses, trains, and trams use solar control glass for comfortable interior temperatures. Durability and safety standards are critical.
- Greenhouses:Specialized solar control glass optimizes light transmission while minimizing excessive heat gain for ideal growing conditions.
New construction projects drive significant demand for Commercial Buildings; retrofitting initiatives expand Residential Construction.
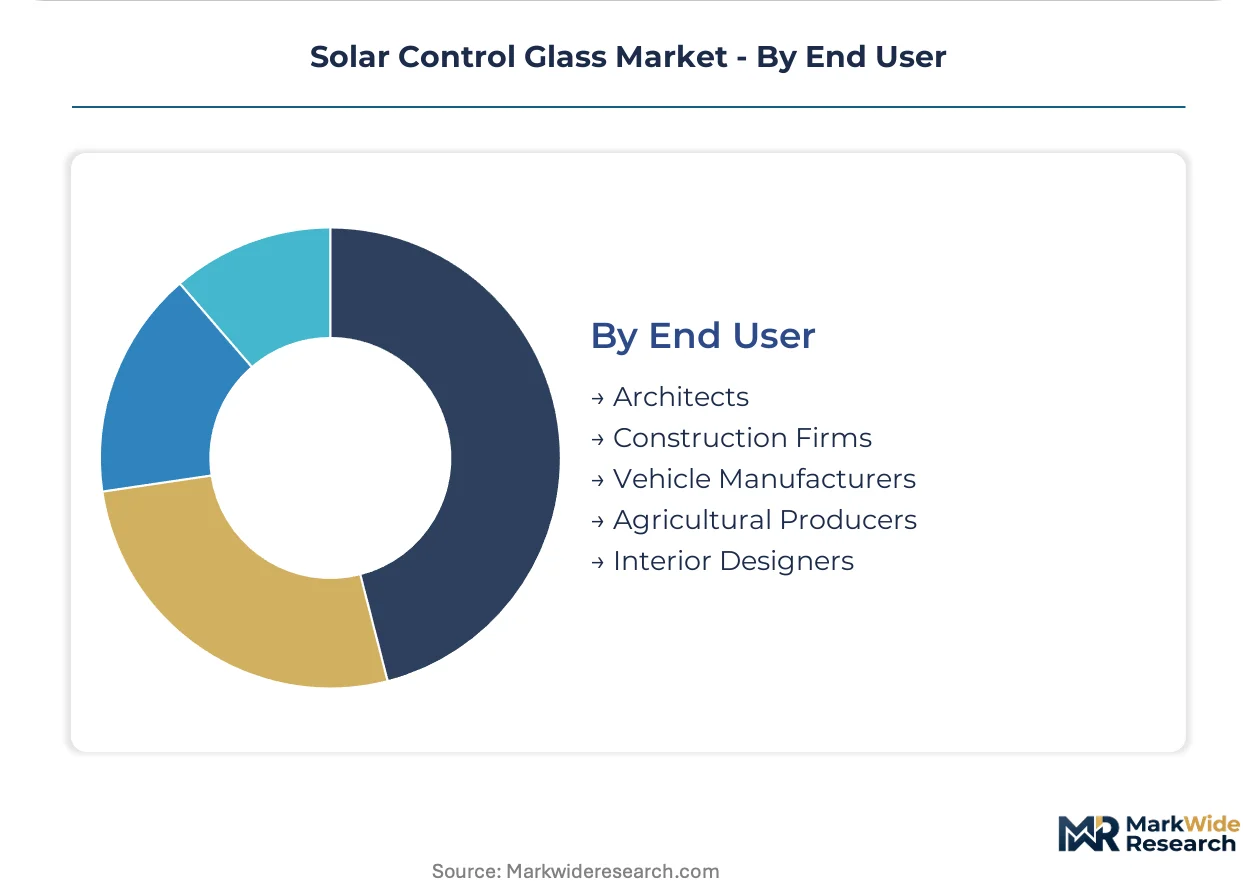
End User:
End users of solar control glass represent distinct customer types, each with unique procurement processes and influence over product specifications.
- Construction Firms:These firms procure and install solar control glass for building projects, prioritizing cost-effectiveness and code compliance. Decisions are influenced by project timelines and budgets.
- Vehicle Manufacturers:Automotive manufacturers integrate specialized solar control glass into car designs, focusing on performance, aesthetics, and safety standards. Procurement involves long-term contracts.
- Architects:Architects specify solar control glass based on aesthetic, performance, and sustainability goals. Their influence is critical for green building certifications.
- Agricultural Producers:Agricultural producers purchase specialized solar control glass for greenhouse structures, optimizing light and temperature. Maximizing yield is a primary concern.
- Interior Designers:Interior designers select solar control glass for aesthetic integration, glare reduction, and occupant comfort. Their choices balance visual appeal with function.
Direct purchasing power rests with Construction Firms; specification influence defines Architects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global solar control glass market exhibits a clear divide between major production hubs and significant consumption centers. Demand for high-performance glazing is accelerating due to stringent energy efficiency standards. Urbanization and sustainable building practices drive regional growth patterns.
China
Demand for solar control glass in China is propelled by extensive urban development and large-scale infrastructure projects. The national dual carbon goals mandate higher energy efficiency in new buildings, directly impacting glass specifications. Major cities like Shanghai and Beijing are seeing significant adoption in commercial high-rises and public facilities.
Germany
Germany's market for solar control glass benefits from the EU Green Deal's building renovation wave, driving significant retrofitting activity. Strict energy performance standards compel advanced glazing solutions across the country's construction sector. The Rhine-Ruhr region, with its strong industrial and architectural base, focuses on manufacturing and deployment of high-performance glass.
United States
The United States experiences a growing demand for solar control glass in both commercial and high-end residential sectors. The US Inflation Reduction Act (IRA) provides significant incentives for energy-efficient building materials and renovations. Green building certifications, particularly in metropolitan areas like New York and California, prioritize advanced glazing solutions.
India
India's rapid urbanization and robust construction boom fuel demand for solar control glass in its expanding urban centers. National building codes are gradually incorporating stricter energy efficiency requirements for new projects and renovations. Major cities like Mumbai and Delhi are witnessing increased use in modern commercial and residential complexes to manage heat gain.
France
France's solar control glass market is influenced by ambitious national energy efficiency targets and the EU Green Deal. The country's building renovation strategy emphasizes improved thermal performance for existing structures. Large urban centers like Paris and Lyon are driving demand for advanced glazing in both new construction and heritage building upgrades.
Solar Control Glass Market Key Industry Players
The competitive structure tilts toward large, integrated manufacturers with extensive global reach and significant capital investment capabilities. The market features a blend of established float glass producers, specialized coating technology providers, and regional players serving specific end-use segments. Strategic archetypes include diversified materials conglomerates leveraging broad product portfolios and pure-play architectural glass specialists focusing on high-performance solutions. Manufacturers increasingly prioritize capacity expansion for advanced coating technologies and strategic partnerships for R&D and market access.
Among global glass manufacturers, Saint-Gobain exemplifies a diversified materials conglomerate, leveraging its extensive distribution network and R&D in high-performance coatings. AGC Inc. represents a major player specializing in advanced architectural and automotive glass solutions, with a significant presence across multiple continents. Guardian Industries occupies a strong market position through its large-scale float glass manufacturing capabilities, serving various construction and automotive applications worldwide. These firms consistently invest in optimizing existing coated glass lines and exploring next-generation dynamic glass technologies to address evolving market demands.
| Leading Market Players |
|---|
| CSG Holding |
| Nippon Sheet Glass |
| AGC Inc. |
| Fuyao Glass Industry Group |
| Euroglas |
| Saint-Gobain |
| Central Glass Co., Ltd. |
| Schott AG |
| Guardian Industries |
| Others |
Cost & Logistics Intelligence
Silver commodity prices directly influence the cost structure of solar control glass, particularly for high-performance coated products. This volatility cascades into tiered pricing models across various end-use applications.
Pricing Analysis
Energy savings potential anchors value-based pricing for high-performance solar control glass, especially for commercial applications. Price differentiation stems from coating technology, with electrochromic glass commanding a premium over standard Low-E solutions, and customization for project-specific requirements. Pricing softness reflects intense competition in standard coated glass segments, particularly for high-volume double glazing. Premium architectural projects exhibit lower price sensitivity, while residential and smaller commercial construction prioritize cost-effectiveness.
Supply Chain Analysis
China's dual carbon goals and the US Inflation Reduction Act (IRA) increasingly shape domestic content requirements, influencing sourcing strategies for solar control glass manufacturers. Global supply concentrates in China, Germany, and the United States, which also represent significant consumption centers. The industry relies on float glass, silver, and indium for its advanced coatings. Commodity price volatility for these industrial metals presents a structural risk to manufacturing costs. Distribution runs through direct sales channels to large construction firms and specialized distributors for smaller projects, with long-term OEM contracts for automotive applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solar control glass market is supply-constrained, with limited global capacity for advanced multi-layer vacuum sputtering coaters propping pricing for high-performance products. This bottleneck restricts rapid expansion, favoring established players.
For Market Incumbents: Anticipate increasing demand for dynamic glass technologies by investing in new electrochromic production lines. Deepen R&D in coating durability and integration with building automation systems to maintain performance leadership. This defends against the emergence of low-cost regional players specializing in standard coated glass. Further vertical integration into critical metallic coating materials like silver or indium offers supply chain stability and cost control.
For New Entrants and Emerging Players: Electrochromic film technology represents a strong technology-first wedge into premium architectural projects seeking advanced energy management. Target underpenetrated emerging markets in Latin America with cost-effective coated glass solutions. Focus on specialized automotive applications, such as panoramic sunroofs for electric vehicles, and offer integrated solutions for thermal management. A go-to-market strategy emphasizing seamless integration with building automation systems will attract high-value commercial clients.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-sized float glass manufacturers with proprietary coating technologies in Europe, driven by building renovation waves. The market offers strong long-term viability, supported by global energy efficiency mandates for buildings and vehicles. Target acquisition candidates include specialized coating technology providers or regional leaders with strong distribution networks. The signal to watch is increasing consolidation activity among smaller, less diversified glass producers as capital expenditure requirements rise.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Advanced Coatings | Scaling production of Low-E and electrochromic glass addresses growing demand from commercial buildings. |
| R&D Investment in Dynamic Glass | Accelerating development of electrochromic and thermochromic solutions unlocks high-margin premium segments. |
| Strategic Partnerships for Market Access | Collaborating with construction firms and automotive OEMs ensures product adoption in key end-use sectors. |
| Vertical Integration into Raw Materials | Securing supply of critical metals like silver and indium mitigates input material volatility risks. |
| Green Building Certification Investments | Aligning products with LEED and BREEAM standards enhances marketability in sustainability-driven projects. |
Research Approach
Multi-period observation of building energy consumption data and regulatory compliance rates anchored the trend analysis, supplemented by interviews with industry stakeholders. Primary research involved discussions with architects, construction firm procurement managers, automotive engineers, and glass manufacturers' R&D heads. Secondary validation drew from EU Green Deal reports, US IRA guidelines, national building codes, and company financial filings. This approach ensured robust bottom-up and top-down triangulation for market sizing and forecasting.
Segment-weighting across product type, technology, application, end-user, and regional energy efficiency mandates formed the core analytical framework across the analysis window. Quantitative models employed regression analysis and expert consensus to derive Compound Annual Growth Rates. Key industry-specific forecast inputs included projected urbanization rates in China and India, alongside anticipated building renovation activity in Europe. This comprehensive approach ensured granular and reliable market projections.
Several conditions sit outside the modeled scope, including unforeseen geopolitical events and rapid shifts in raw material supply chains. Forecasts reflect assumptions regarding stable regulatory environments and sustained economic growth. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Asia-Pacific Fiberglass Window Market
Glass
Mirrored Glass Market
Glass
Patterned Glass Market
Glass
Soda Feldspar Market
Glass
Glass Substrate Market
Glass
Global Flat Glass Market
Glass
Glass Forming Machine Market
Glass
Europe Sapphire Glass Market
Glass
Glass Block Market
Glass
Glass Prepreg Market
Glass
Low Iron Glass Market
Glass
Flexible Glass Market
Glass
Glass Alternative Materials Market
Glass
Glass Like Carbon Market
Glass
Float Glass Market
Glass
Europe Glassware Market