
 3D Glass Substrate Market | 2026-2036
3D Glass Substrate Market Size, Share, and Industry Trends Forecast 2026-2036
3D Glass Substrate Market Insights
Buyer concentration across the display supply chain is broadening as smartphone OEMs diversify sourcing while automotive panel integrators enter as new volume purchasers. Corning Incorporated leverages its fusion-draw manufacturing scale to dominate high-performance substrate supply. AGC Inc. anchors Asian architectural and automotive display demand through specialized float-glass derivatives. SCHOTT AG differentiates via borosilicate expertise in medical and precision optical segments.
3D glass substrate denotes thermally or chemically formed glass sheets with non-planar curvature, typically 0.3 mm to 1.1 mm in thickness, engineered for optical clarity and mechanical resilience in curved display assemblies. The primary commercial purpose centers on enabling seamless touch interfaces and immersive visual surfaces across consumer and industrial devices. Tempered glass commands the largest volume share due to its shatter-resistant properties in mobile applications, while hybrid bonding technology captures expanding margin pools as semiconductor-style precision migrates into display lamination. Optical bonding leads among established processes for automotive display stacks where readability under direct sunlight remains critical.
EPA regulations govern volatile organic compound emissions from coating and etching operations in United States-based fabrication facilities, while REACH restricts hazardous substances in European-sourced chemical treatments for surface modification. China's SAMR enforces GB standards for glass product safety and dimensional consistency in domestically manufactured substrates. Stakeholders must monitor divergence between regional chemical compliance regimes as substrate fabrication increasingly fragments across multi-country supply networks.
Market Dynamics
Curved display adoption in automotive instrument clusters and premium smartphones is compressing substrate qualification timelines while forcing simultaneous investment in thermal forming and precision grinding capacity.
Growth Catalysts
- Automotive cockpit digitization:Tier-1 panel integrators are expanding procurement of thermally formed substrates for curved center-stack displays, with South Korean and Chinese vehicle platforms leading volume deployment.
- REACH chemical compliance evolution:ECHA's expanding restricted substance list is accelerating substitution of traditional hydrofluoric acid etching with plasma-based surface modification, favoring capital-rich suppliers with in-house process engineering.
- Hybrid bonding process maturation:Semiconductor-derived direct bonding techniques are displacing optical adhesive lamination in foldable device stacks, reducing optical distortion while improving mechanical fatigue resistance.
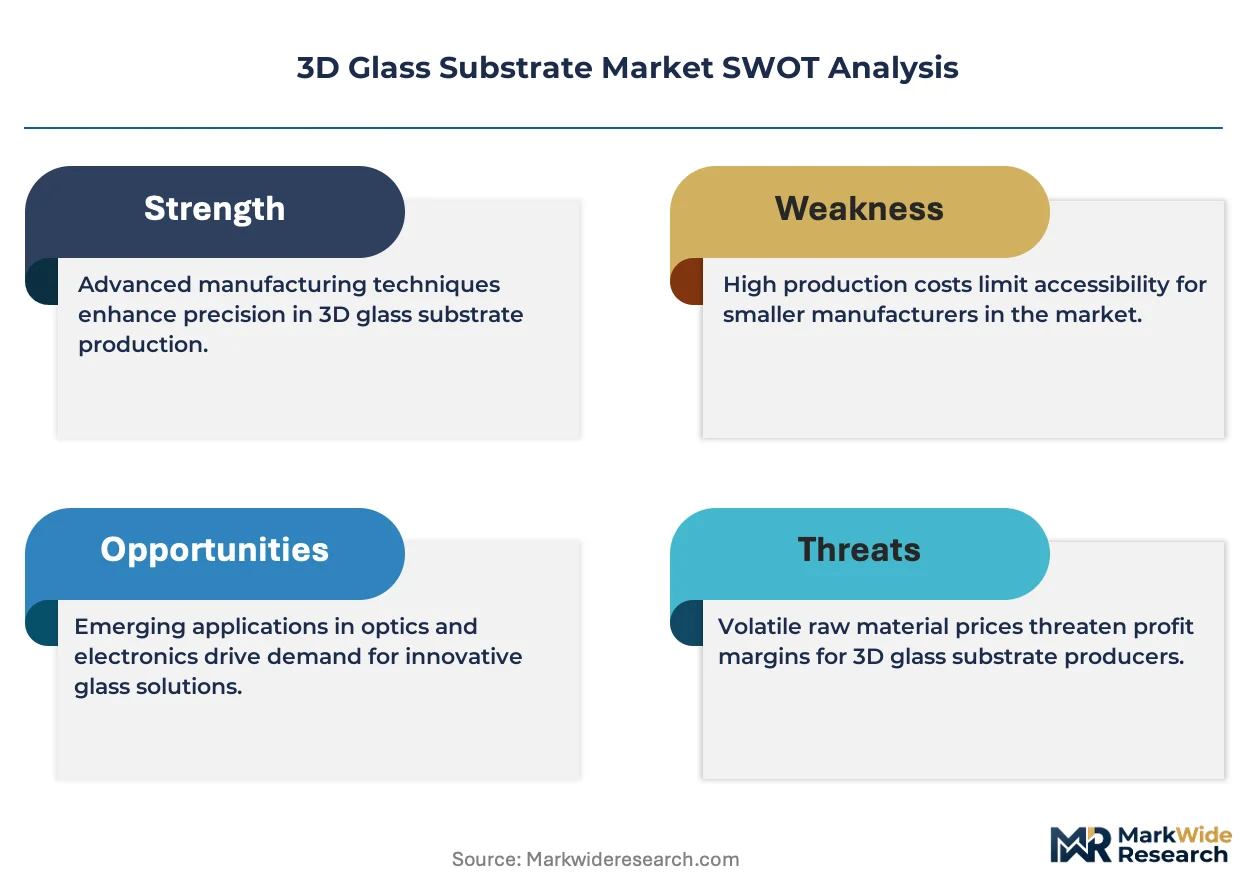
Market Restraints
- High-purity alumina supply concentration:Synthetic sapphire alternative substrates depend on Ukrainian and Russian feedstock for crucible-grade material, exposing cost structures to geopolitical supply disruption.
- Substrate thickness tolerance limitations:Chemical strengthening uniformity degrades below 0.4 mm thickness, constraining ultra-slim foldable designs and forcing compromise between mechanical resilience and device weight targets.
- EPA VOC emission thresholds:Coating solvent recovery requirements in United States fabrication facilities add 12-18% to operating expenditure versus Asian competitors with less stringent air quality enforcement.
Strategic Opportunities
- India display manufacturing incentives:PLI scheme subsidies for semiconductor and display fabrication are attracting substrate qualification programs from smartphone OEMs seeking supply chain diversification beyond East Asian concentration.
- Medical imaging interface convergence:Sterilizable borosilicate 3D substrates for surgical navigation displays represent an underdeveloped vertical with pricing power insulated from consumer electronics margin compression.
- Direct-to-OEM substrate supply contracts:Panel integrators are negotiating long-term offtake agreements that bypass traditional glass merchant intermediaries, capturing margin and securing dedicated capacity allocation.
Industry Challenges
- Multi-physics simulation talent scarcity:Thermal forming process optimization requires combined expertise in computational fluid dynamics and glass viscoelastic modeling, with fewer than two hundred qualified engineers globally.
- Automotive qualification timeline compression:OEMs demand 18-month PPAP cycles versus 36-month historical norms, straining validation infrastructure and forcing parallel rather than sequential testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Glass Substrate Market |
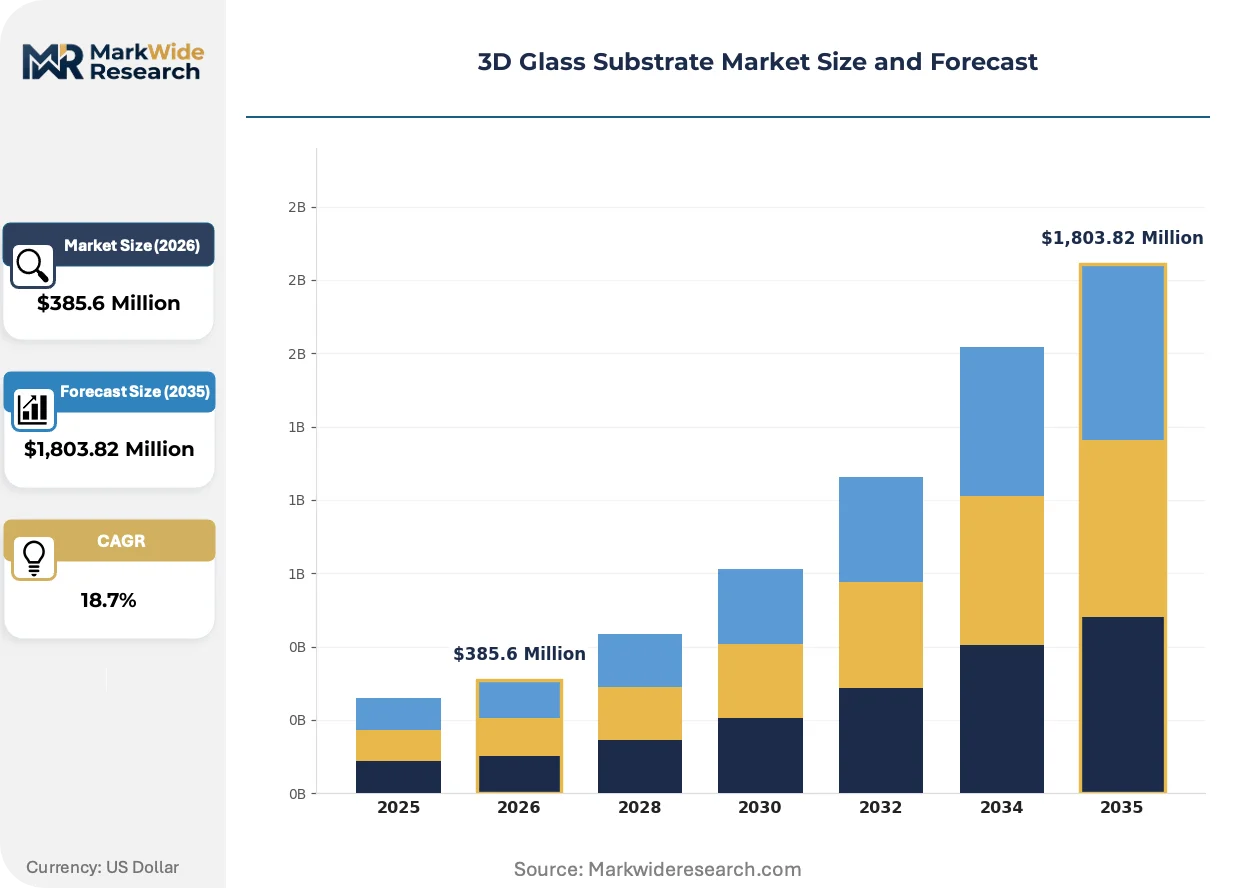
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,803.82 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tempered Glass, Laminated Glass, Coated Glass, Non-Floating Glass Technology: Optical Bonding, Hybrid Bonding, Thin Film Deposition, Glass Blowing Application: Consumer Electronics, Automotive Displays, Architectural Uses, Medical Devices End User: OEMs, Tier-1 Suppliers, Distributors, Aftermarket Providers |
| Companies Covered | Corning Incorporated, AGC Inc., SCHOTT AG, HOYA Corporation, Nippon Electric Glass Co., Ltd., Nippon Sheet Glass Co., Ltd., AvanStrate Inc., LG Chem, IRICO Group New Energy Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Glass Substrate Market Trends and Innovations
Process convergence between semiconductor wafer handling and display substrate fabrication is dissolving traditional equipment boundaries while reshaping supplier capability requirements and capital deployment patterns.
Precision glass molding using diamond-turned tungsten carbide dies is unifying optical surface quality with mechanical forming efficiency. Automotive HUD combiner manufacturers are adopting this approach for freeform mirror substrates. The technology is compressing the traditional separation between refractive optics manufacturing and protective cover glass production.
China's GB standards for foldable display mechanical durability are mandating specific radius-of-curvature testing protocols that exceed IEC baseline requirements. Domestic certification bodies are enforcing these specifications for products sold within mainland markets. Foldable smartphone OEMs are redesigning hinge-adjacent substrate geometries to satisfy these localized mechanical stress criteria.
Subscription-based substrate qualification services are displacing traditional per-project engineering consultation fees. Korean and Chinese panel makers are purchasing annual access to supplier process development libraries rather than commissioning bespoke development programs. This model concentrates technical knowledge with incumbent suppliers while raising barriers for new market entrants lacking comparable portfolio depth.
3D Glass Substrate Market Segmentation
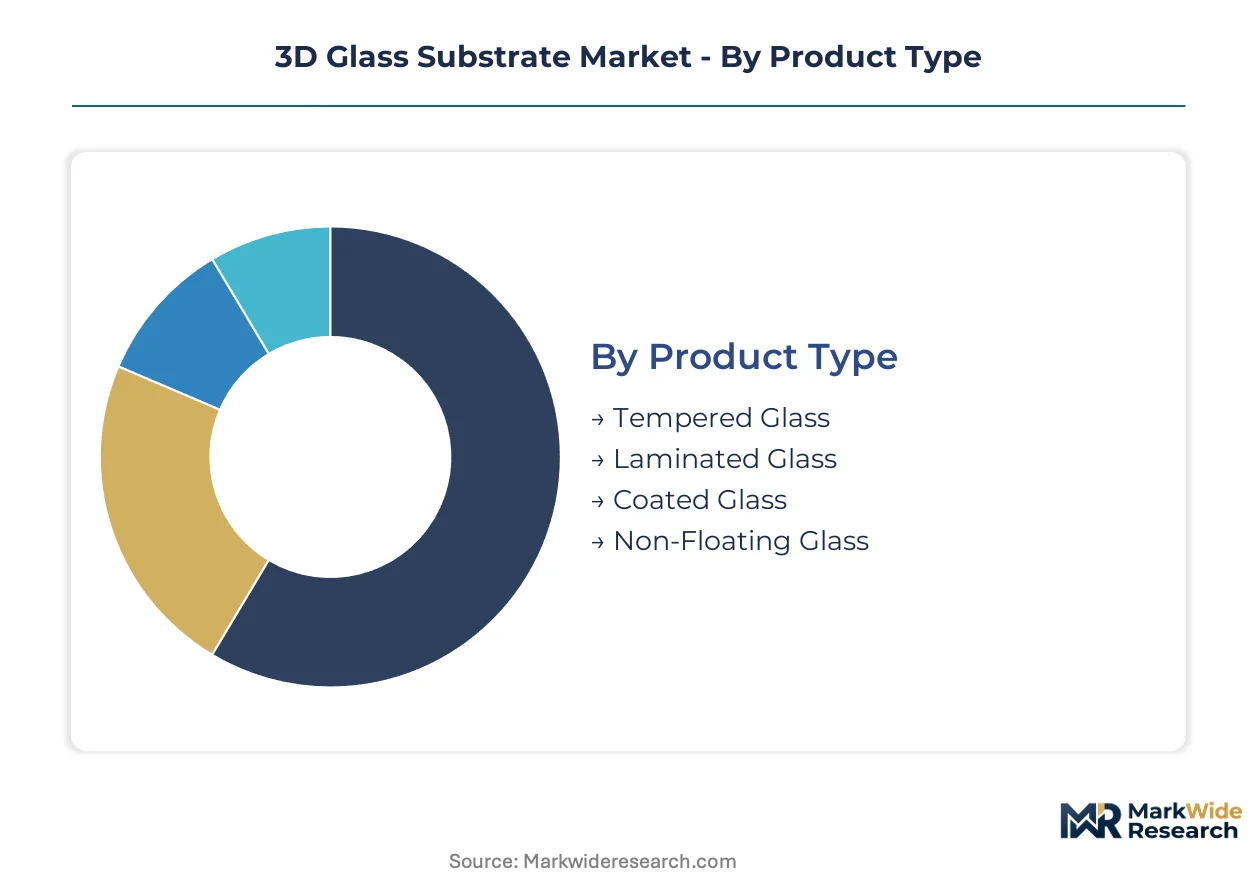
Substrate procurement patterns diverge sharply between high-volume consumer electronics and precision-demanding automotive applications. Technology selection and glass formulation choices cascade through qualification timelines, capital intensity, and margin capture potential across the value chain.
Product Type:
Tempered glass dominates volume shipments for mobile cover applications, while laminated and coated variants command premium positioning in specialized end-uses.
- Tempered Glass:Chemically strengthened through ion exchange processes, this formulation achieves compressive surface layers exceeding 800 MPa. Smartphone OEMs in South Korea and China specify tempered substrates for curved edge displays, prioritizing drop-test performance over absolute thinness. Mature deployment sits with tempered formulations. Newer deployment is concentrated in coated glass derivatives.
- Laminated Glass:Multi-layer constructions incorporating polymer interlayers absorb impact energy through controlled delamination. Automotive HUD combiner manufacturers specify laminated stacks for windshield-integrated projection surfaces where optical clarity must survive stone-chip impacts.
- Coated Glass:Anti-reflective and oleophobic surface treatments from vacuum deposition or sol-gel processes enhance readability under direct illumination. Medical imaging device producers specify coated borosilicate for surgical navigation displays requiring sterilization compatibility.
- Non-Floating Glass:Fusion-drawn or slot-drawn substrates bypass float-glass tin bath contamination, achieving superior surface flatness for semiconductor-style lithography compatibility. Precision optical manufacturers source non-floating formats for waveguide substrates in AR headsets.
Cost-sensitive mobile applications favor tempered glass scale economies. Premium optical and medical segments drive coated and non-floating adoption.
Technology:
Process selection determines bond line integrity, optical transmission losses, and thermal cycling resilience in finished display assemblies.
- Optical Bonding:Liquid optically clear adhesive lamination remains the baseline for automotive display stacks where readability under direct sunlight requires index-matched interfaces. Tier-1 panel integrators specify optical bonding for instrument cluster programs with 10-year durability requirements.
- Hybrid Bonding:Semiconductor-derived direct wafer bonding eliminates adhesive layers through atomic-scale surface activation. Foldable device manufacturers are qualifying hybrid bonding for hinge-adjacent substrate stacks where mechanical fatigue resistance determines product lifetime.
- Thin Film Deposition:Sputtered or CVD-applied functional layers create conductive, anti-reflective, or barrier properties without substrate bulk modification. Touch sensor manufacturers integrate thin film deposition with cover glass fabrication for streamlined supply chains.
- Glass Blowing:Traditional thermal forming for hollow or complex-curvature substrates persists in specialty lighting and artistic architectural applications where precision tolerances are relaxed.
Established automotive programs anchor optical bonding demand. Hybrid bonding is climbing the fastest as foldable form factors proliferate.
Application:
End-use specifications fragment substrate requirements across optical, mechanical, and environmental performance dimensions.
- Consumer Electronics:Smartphone, tablet, and wearable manufacturers drive the largest absolute substrate volumes, with curved edge and foldable form factors demanding radius-of-curvature capabilities below 2 mm. Chinese GB standards for mechanical durability exceed IEC baselines, forcing geometry redesigns for mainland market access.
- Automotive Displays:Center-stack, instrument cluster, and HUD applications require substrates surviving thermal cycling from -40°C to 85°C with optical clarity maintained. South Korean and Chinese vehicle platforms are deploying curved center-stack displays at accelerating rates.
- Architectural Uses:Structural glass walls and decorative facades employ thermally formed substrates for aesthetic curvature, with AGC Inc. anchoring supply through specialized float-glass derivatives.
- Medical Devices:Sterilizable borosilicate 3D substrates for surgical navigation and diagnostic imaging interfaces represent a developing vertical with pricing power insulated from consumer electronics margin compression.
Consumer electronics commands volume concentration. Medical devices represent the steepest expansion trajectory for specialized substrate qualifications.
End User:
Procurement authority is shifting from merchant glass intermediaries toward direct OEM and Tier-1 relationships.
- OEMs:Smartphone and automotive manufacturers are negotiating long-term offtake agreements that bypass traditional glass merchants, capturing margin and securing dedicated capacity allocation from substrate fabricators.
- Tier-1 Suppliers:Panel integrators like Samsung Display and BOE Technology Group consolidate substrate procurement for multiple OEM customers, leveraging volume concentration for price and priority access.
- Distributors:Regional inventory holders serve aftermarket replacement display markets and smaller device manufacturers lacking direct supplier relationships.
- Aftermarket Providers:Independent repair networks and refurbishment operators source substrates for screen replacement services, typically specifying tempered glass formats with relaxed tolerance bands versus OEM-grade material.
Direct OEM contracting is displacing distributor intermediation in high-volume segments. Aftermarket channels retain relevance in repair and refurbishment ecosystems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian manufacturing clusters dominate substrate procurement, with South Korean and Chinese display fabs consuming over two-thirds of qualified supply. Smartphone OEMs and automotive Tier-1s are diversifying sourcing footprints beyond this concentration.
China
Domestic foldable smartphone OEMs are driving substrate volume through curved-edge display programs. SAMR enforces GB standards for mechanical durability that exceed IEC baselines, forcing geometry redesigns for mainland market access. The Yangtze River Delta hosts the densest concentration of thermal forming and precision grinding capacity serving BOE Technology Group and TCL CSOT.
South Korea
Samsung Display anchors global demand for hybrid-bonded substrates in foldable device stacks. MFDS regulates medical device substrate sterilization protocols, creating qualification pathways for borosilicate derivatives. The Seoul Capital Area concentrates fusion-draw manufacturing and direct-to-OEM contracting infrastructure.
Japan
Precision optical manufacturers source non-floating substrates for AR waveguide applications. METI subsidizes next-generation display material development through NEDO programs targeting automotive HUD integration. The Kansai region maintains specialized float-glass derivatives capacity for architectural and automotive display demand.
United States
EPA VOC emission thresholds constrain coating and etching operations in domestic fabrication facilities. NHTSA safety standards for automotive HUD combiners drive substrate qualification for windshield-integrated projection. The Pacific Northwest hosts precision glass molding operations serving HUD and freeform mirror applications.
Germany
Automotive OEMs specify thermally formed substrates for curved center-stack displays in premium vehicle platforms. ECHA REACH restrictions on hydrofluoric acid etching accelerate plasma-based surface modification adoption. Bavaria concentrates medical imaging substrate development for surgical navigation displays requiring sterilization compatibility.
3D Glass Substrate Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue semiconductor-style precision and medical-specialized formulations. The vendor base stratifies across three capability tiers: fusion-draw scale leaders, float-glass derivative specialists, and borosilicate precision optical fabricators. Dominant competitive moves include direct-to-OEM offtake contracting that bypasses merchant intermediaries, and in-house process engineering investment to satisfy REACH chemical compliance evolution.
Among Japanese fabricators, HOYA Corporation and Nippon Electric Glass Co., Ltd. exemplify the precision optical tier, occupying positions in medical imaging and AR waveguide substrate supply. Corning Incorporated anchors the scale-driven segment through fusion-draw manufacturing dominance. These three represent divergent strategic archetypes: precision specialization, regional merchant supply, and global volume leadership.
| Leading Market Players |
|---|
| Corning Incorporated |
| AGC Inc. |
| SCHOTT AG |
| HOYA Corporation |
| Nippon Electric Glass Co., Ltd. |
| Nippon Sheet Glass Co., Ltd. |
| AvanStrate Inc. |
| LG Chem |
| IRICO Group New Energy Company Limited |
| Others |
Pricing and Supply Chain Analysis
Hybrid bonding process maturation simultaneously compresses cost economics for foldable device stacks and concentrates supply power with capital-rich incumbents possessing semiconductor-style precision equipment. This technology transition rewards fabricators with in-house ion exchange and direct wafer bonding capabilities, while marginalizing merchant glass intermediaries lacking comparable process depth.
Pricing Analysis
Volume shipments of tempered glass for mobile cover applications capture thin margins through scale economies, while hybrid-bonded substrates for foldable devices and borosilicate medical grades command substantial premiums. Price differentiation rests on certification grade—REACH-compliant plasma surface modification versus traditional hydrofluoric acid etching—and volume scale for direct-to-OEM offtake agreements. Cost compression in standard tempered formulations is intensifying as Chinese manufacturers expand thermal forming capacity. Smartphone OEMs exhibit acute price sensitivity in high-volume curved-edge programs, whereas automotive Tier-1s and medical device producers prioritize qualification reliability over unit cost.
Supply Chain Analysis
Regional distribution centers in South Korea, Japan, and China manage hub-and-spoke patterns for just-in-time delivery to Yangtze River Delta and Seoul Capital Area display fabs. Geographic supply concentrates in East Asian manufacturing clusters, with fusion-draw capacity anchored in the United States and Japan, and float-glass derivatives centered in China and Europe. Raw material dependencies include high-purity alumina for synthetic sapphire alternatives—sourced from Ukrainian and Russian feedstock—and specialty chemical treatments for surface modification. Single-source vulnerability in crucible-grade alumina exposes cost structures to geopolitical disruption. Distribution runs through direct-to-OEM contracting channels that bypass traditional merchant intermediaries, with long-term offtake agreements securing dedicated capacity allocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over ion exchange and plasma surface modification capabilities determines margin capture. Players are pursuing backward integration into chemical treatment processes to satisfy REACH compliance evolution and compress qualification timelines.
For Market Incumbents: Extend fusion-draw manufacturing scale into direct-to-OEM substrate qualification services, displacing per-project engineering consultation with annual subscription access to process development libraries. Add thermal forming capacity in the Yangtze River Delta to capture Chinese foldable smartphone volume. Defend against emerging precision optical fabricators by accelerating borosilicate medical substrate certifications under MFDS and ECHA frameworks.
For New Entrants and Emerging Players: ECHA REACH restrictions on hydrofluoric acid etching in Europe open a window for plasma-based surface modification specialists to qualify automotive and medical substrate programs. Target sterilizable borosilicate 3D substrates for surgical navigation displays, where pricing power remains insulated from consumer electronics margin compression. Enter through equipment partnerships with Korean and Chinese panel makers seeking second-source hybrid bonding capacity for foldable device stacks.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by display panel integrators seeking captive substrate supply and by precision optical conglomerates expanding medical imaging portfolios. Long-term viability favors fabricators with demonstrated multi-physics simulation expertise spanning computational fluid dynamics and glass viscoelastic modeling. Watch for inflection where automotive OEMs compress PPAP cycles below eighteen months, forcing parallel validation infrastructure investments that strain capital-constrained competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-OEM Substrate Qualification Services | Subscription-based access to process libraries concentrates technical knowledge with incumbent suppliers while raising entry barriers. |
| Plasma-Based Surface Modification Investment | ECHA REACH compliance evolution favors capital-rich fabricators with in-house process engineering over traditional etching operations. |
| Hybrid Bonding Capacity Expansion | Semiconductor-derived direct bonding techniques displace optical adhesive lamination in foldable device stacks, improving mechanical fatigue resistance. |
| Borosilicate Medical Substrate Certification | Sterilizable 3D substrates for surgical navigation displays command pricing power insulated from consumer electronics margin compression. |
| Thermal Forming Capacity in East Asian Clusters | Proximity to BOE Technology Group and Samsung Display reduces logistics costs and accelerates qualification timeline compression. |
Research Methodology
SEC filings, ECHA regulatory submissions, and SAMR GB standards documentation formed the secondary backbone for supply chain mapping and compliance trajectory assessment. Primary interviews with display panel procurement directors, thermal forming process engineers, and automotive Tier-1 substrate qualification managers combined with secondary validation to triangulate capacity expansion plans and pricing model evolution. Bottom-up aggregation of substrate shipment volumes by product type and technology crossed with top-down display industry value chain analysis.
Bottom-up modeling of tempered glass, laminated glass, coated glass, and non-floating substrate volumes across consumer electronics, automotive displays, architectural uses, and medical devices integrated with top-down display market sizing. Segmentation dimensions included product type, bonding technology, application vertical, and end-user procurement authority. CAGRs were derived from fitted growth curves calibrated to historical qualification timeline data and announced capacity investments. Forecast inputs incorporated automotive cockpit digitization rates and foldable smartphone form factor adoption patterns.
Caveats apply where REACH chemical compliance evolution, EPA VOC emission threshold adjustments, or high-purity alumina supply disruption could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Soda Feldspar Market
Glass
United States Flat Glass Market
Glass
Coated Glass Market
Glass
Global Vitrification Market
Glass
India Flat Glass Market
Glass
Glass Product Market
Glass
Tinted Glass Market
Glass
Middle East and Africa Glassware Market
Glass
Glass Tableware Market
Glass
Metallic Glass Market
Glass
Global Vacuum Insulated Glass Market
Glass
Global Glassware Market
Glass
Silica Sand for Glass Making Market
Glass
Optical Lens Material Market
Glass
Antiglare Glass Market
Glass
UAE Silica Sand Market