
 Reflective Polarizing Films Market | 2026-2036
Reflective Polarizing Films Market Size, Share, and Industry Trends Forecast 2026-2036
Reflective Polarizing Films Market Analysis
Consumer electronics display manufacturers is collapsing as the dominant buyer archetype, displacing traditional automotive tier-one suppliers in procurement volume. 3M Company leverages its optical film patent portfolio to sustain premium positioning in high-brightness display stacks. LG Chem Ltd. anchors its supply position through captive demand from its affiliated display panel operations. Toray Industries, Inc. dominates Japan's domestic polarizing film substrate supply with proprietary polymer stretching technology.
Reflective polarizing films are multilayer optical components engineered to transmit one polarization state while reflecting the orthogonal state, typically constructed from birefringent polymer stacks with layer thickness gradients tuned to specific wavelength bands, and their primary commercial purpose is to recycle otherwise wasted light in liquid crystal and OLED display backlights for luminance enhancement. Linear polarizers occupy the mature volume base across television and monitor panels where margin compression has intensified, while specialty films including reflective polarizers with integrated quarter-wave retardation represent the fastest-growing margin pool as foldable and automotive displays demand higher optical efficiency. Circular polarizers compete for design-in wins against linear configurations in OLED architectures where ambient light reflection control determines outdoor readability.
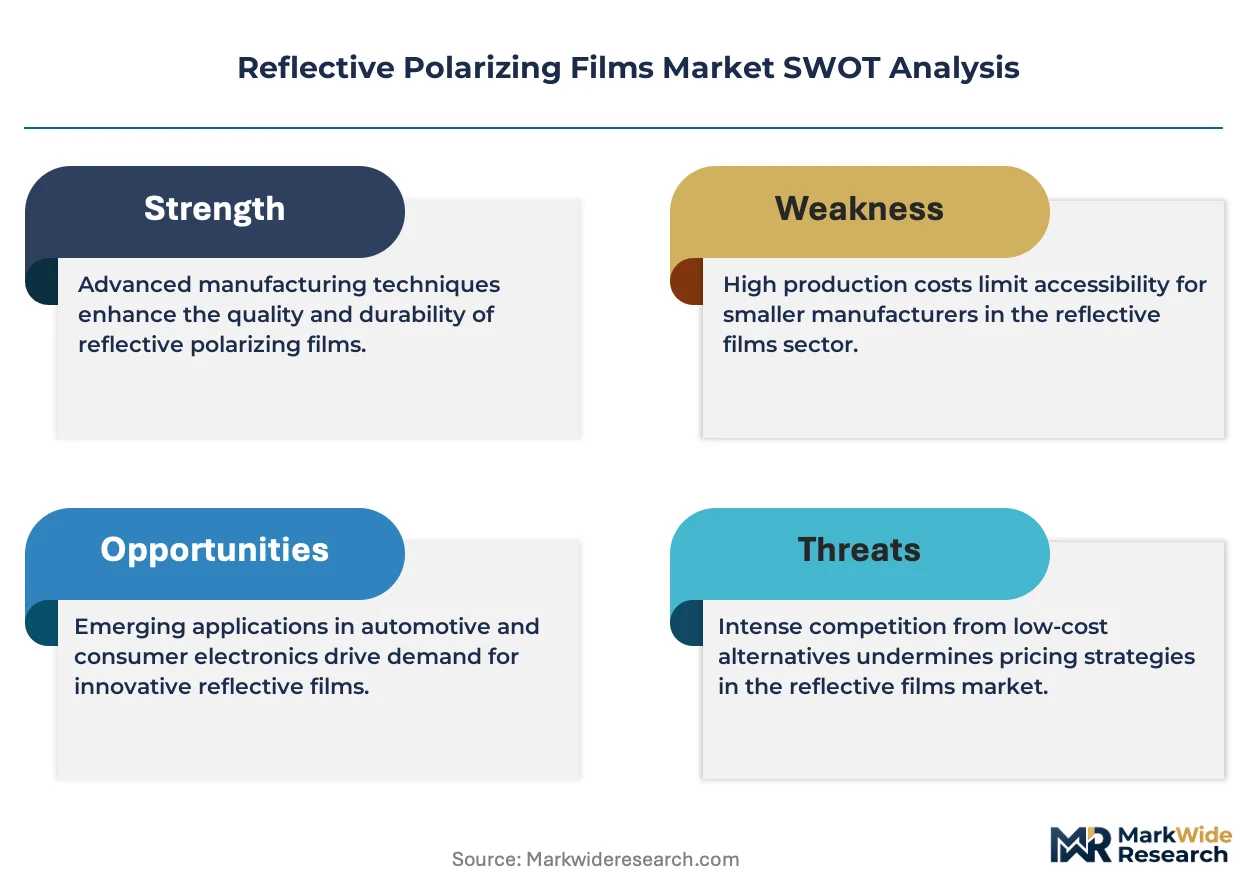
REACH restrictions on halogenated flame retardants and RoHS substance thresholds constrain adhesive and substrate chemistries in European-bound supply chains, while FDA optical device classifications and EPA manufacturing emissions standards shape product development timelines for healthcare and domestic production respectively. China's GB standards for display energy efficiency and Japan's JIS optical material specifications create divergent certification requirements that fragment regional product roadmaps. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal's embodied carbon tracking reshape polymer sourcing decisions before committing to multi-year capacity expansions.
Market Dynamics
Consumer electronics display manufacturers now command procurement volumes that automotive tier-one suppliers once dominated, forcing reflective polarizing film producers to retool specifications for foldable OLED stacks and quantum dot color conversion layers rather than windshield-integrated HUD modules.
Growth Catalysts
- OLED Display Diffusion:Foldable smartphone panels and rollable television prototypes require ultra-thin reflective polarizers with integrated quarter-wave retardation, pulling substrate innovation toward polyimide alternatives.
- REACH Chemical Restrictions:Halogenated flame retardant bans under ECHA guidance are accelerating adhesive chemistry substitution toward phosphorus-based systems in European-bound supply chains.
- East Asian Manufacturing Concentration:South Korea, Japan, and China house over eighty percent of global polarizing film demand, creating localized R&D clusters that compress development cycles for next-generation optical stacks.
Market Restraints
- PVA Substrate Supply Concentration:Polyvinyl alcohol film production clusters in Japan and select Chinese provinces, exposing downstream converters to single-source risk during polymer stretching equipment maintenance cycles.
- TAC Film Cost Volatility:Triacetyl cellulose substrate prices fluctuate with cotton linter supply and acetic anhydride feedstock costs, compressing margin predictability for optical film laminators.
- Technical Thickness Limitations:Current multilayer coextrusion processes struggle to maintain optical uniformity below 50 micrometers for foldable display applications, constraining design freedom.
Strategic Opportunities
- Automotive Interior Display Expansion:Freeform dashboard screens and pillar-to-pillar infotainment systems in electric vehicle architectures create demand for curved reflective polarizers with wide viewing angles.
- China Dual Carbon Policy Alignment:GB standards for display energy efficiency and provincial carbon intensity targets reward optical efficiency improvements that reduce backlight power consumption.
- Quantum Dot Color Conversion Convergence:Hybrid stacks combining reflective polarizers with perovskite or cadmium-free quantum dot films enable single-layer solutions for mini-LED backlights.
Industry Challenges
- Optical Metrology Talent Scarcity:Specialized expertise in Mueller matrix polarimetry and spectrally resolved birefringence mapping remains concentrated among legacy Japanese equipment suppliers, constraining quality scale-up.
- Multi-Jurisdiction Certification Burden:Simultaneous pursuit of JIS optical material specifications, GB energy efficiency labels, and FDA optical device classifications extends product qualification timelines by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reflective Polarizing Films Market |
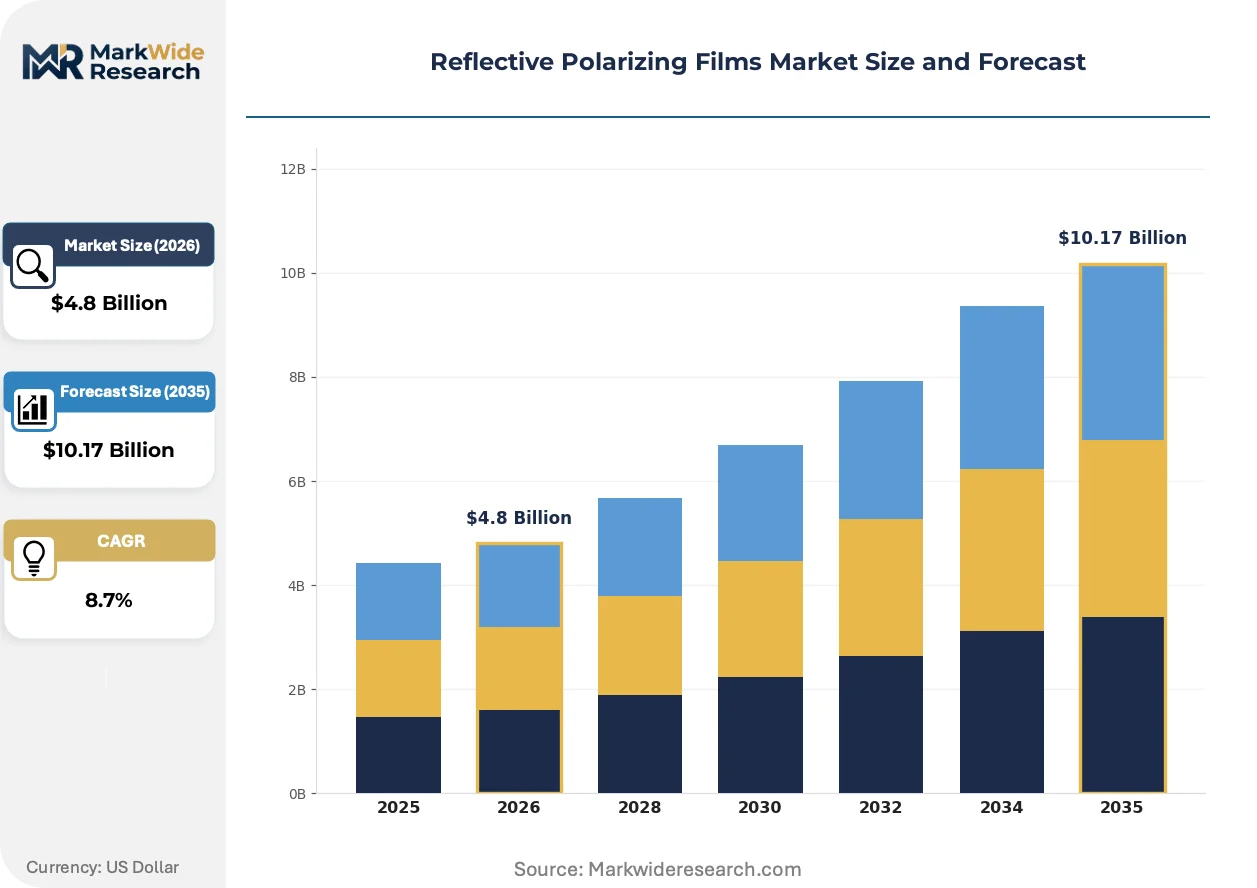
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Polarizers, Circular Polarizers, Specialty Films, Optical Filters Application: Displays, Automotive, Eyewear, Photography End User: Consumer Electronics, Automotive Industry, Healthcare, Advertising Material: Polymer, Glass, Film, Others |
| Companies Covered | 3M Company, Dai Nippon Printing Co., Ltd., LG Chem Ltd., Nitto Denko Corporation, Kolon Industries, Inc., DuPont, Fusion Optix, Inc., Gamma Optical Co., Ltd., Toray Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reflective Polarizing Films Market Emerging Trajectories
Reflective polarizing film architectures are fragmenting along application-specific performance vectors, with material scientists prioritizing mechanical flexibility for foldable displays and thermal stability for automotive-grade reliability over legacy television panel specifications.
Nanostructured dielectric reflective polarizers built through sequential layer deposition are displacing traditional birefringent polymer stacks in premium smartphone displays. Samsung Display and BOE Technology Group have qualified these films for their latest foldable panel generations. This displacement is compressing demand for conventional PVA-TAC laminates in the sub-100 micrometer thickness segment.
EU Green Deal embodied carbon tracking requirements are forcing substrate producers to document Scope 3 polymer sourcing emissions across their supply chains. German automotive OEMs now mandate cradle-to-gate carbon footprints for all optical components in their electric vehicle display modules. Japanese material suppliers are responding by certifying mass balance bio-based TAC alternatives through ISCC PLUS chain-of-custody standards.
Display panel manufacturers are consolidating supplier relationships around dual-source agreements with technology-licensing provisions rather than arm's-length component purchasing. This consolidation is displacing spot-market transactions for commodity-grade linear polarizers. The shift is most visible in South Korea, where LG Display and Samsung Display have both moved to captive-plus-partner sourcing models for reflective polarizer supply security.
Reflective Polarizing Films Market Segmentation
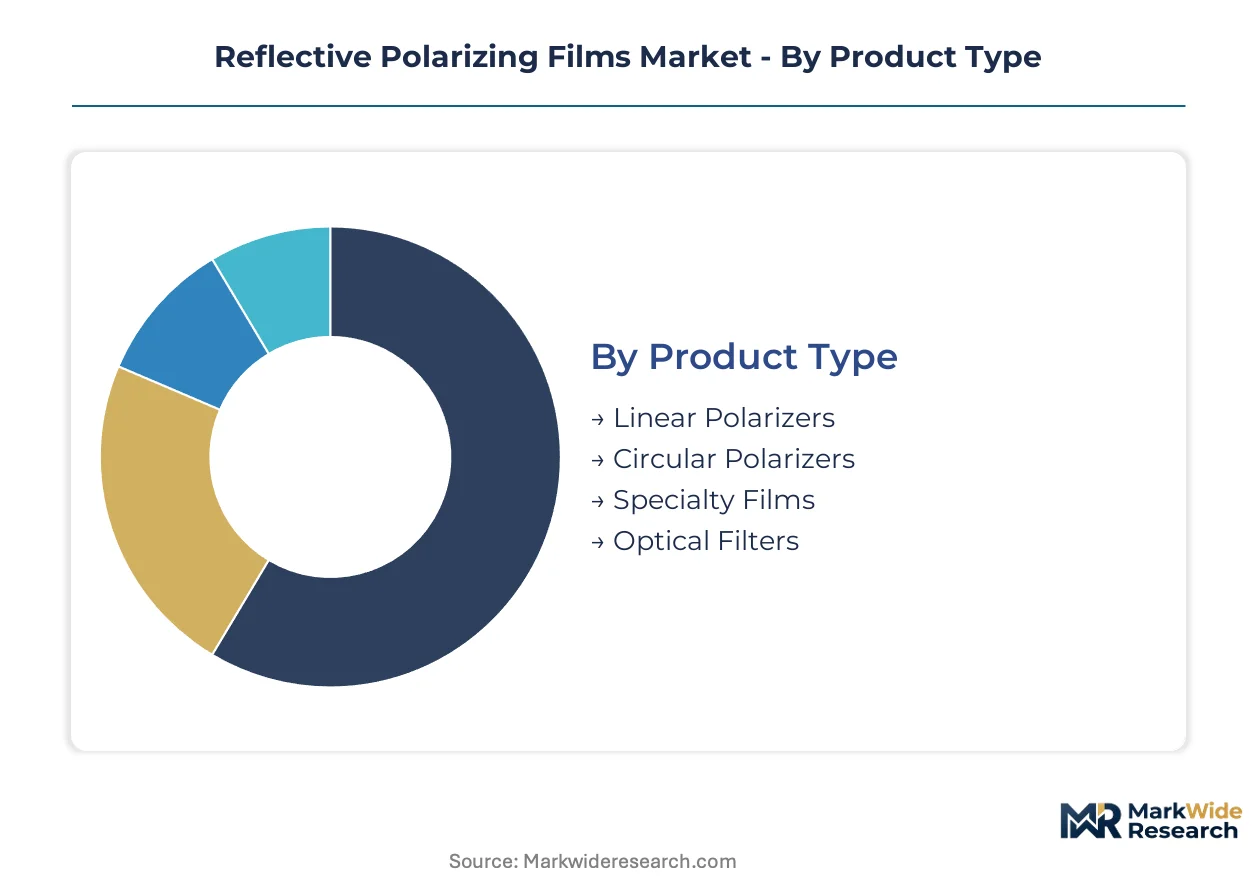
Reflective polarizing film specifications diverge sharply across downstream channels. Automotive HUD integrators demand thermal cycling resilience that consumer electronics buyers rarely specify. Material selection and optical stack architecture must align with the certification burdens and volume cadences of each procurement channel.
Product Type:
Channel flow splits between high-volume display panel laminators and specialized optical integrators. Linear polarizers move through commodity distribution to television and monitor manufacturers. Circular and specialty variants route through qualified supplier programs to smartphone and automotive OEMs.
- Linear Polarizers:Birefringent polymer laminates built from stretched polyvinyl alcohol cores with cellulose triacetate protective skins dominate television and monitor backlight recycling. Procurement concentrates with South Korean and Chinese panel makers where margin compression has intensified qualification requirements.
- Circular Polarizers:Quarter-wave retardation layers bonded to linear bases control ambient reflection in OLED architectures. Foldable smartphone manufacturers in South Korea and China specify sub-100 micrometer thicknesses that strain current coextrusion uniformity limits.
- Specialty Films:Nanostructured dielectric stacks for premium foldable displays.
- Optical Filters:Wavelength-selective components for photography and instrumentation channels.
By volume, Linear Polarizers leads. By growth pace, Circular Polarizers is climbing the fastest.
Application:
Cost tier stratification separates display mass production from low-volume precision optics. Television panels absorb commodity-grade films at wafer-thin margins. Automotive and eyewear applications sustain premium pricing through qualification depth and performance guarantees.
- Displays:Liquid crystal and OLED panels consume the majority of reflective polarizer output. Television manufacturers in China and South Korea drive specifications toward thinner substrates and higher optical efficiency to meet GB energy efficiency standards.
- Automotive:Windshield-integrated HUD modules and freeform dashboard screens demand wide-viewing-angle films with thermal stability from -40°C to 85°C. German OEMs now mandate cradle-to-gate carbon documentation under EU Green Deal supply chain requirements.
- Eyewear:Polarized sunglass lenses and prescription optics.
- Photography:Camera filter systems and studio lighting controls.
Displays commands absolute volume. Automotive applications are gaining share fastest through electric vehicle interior screen expansion.
End User:
Customer type determines contract structure and technical engagement depth. Consumer electronics buyers negotiate dual-source agreements with technology licensing clauses. Healthcare and advertising sectors purchase through specialized optical distributors with extended qualification cycles.
- Consumer Electronics:Display panel manufacturers consolidate supply relationships around captive-plus-partner models rather than spot-market purchasing. Samsung Display and LG Display have both shifted to this structure for reflective polarizer security.
- Automotive Industry:Tier-one suppliers and electric vehicle OEMs specify curved polarizers for pillar-to-pillar infotainment systems. REACH chemical restrictions on halogenated flame retardants are accelerating adhesive chemistry substitution in European-bound supply chains.
- Healthcare:FDA optical device classifications shape product development timelines for medical imaging and diagnostic displays.
- Advertising:Digital signage and outdoor display networks.
Consumer Electronics leads procurement volume. Healthcare exhibits the steepest expansion trajectory as diagnostic display requirements intensify.
Material:
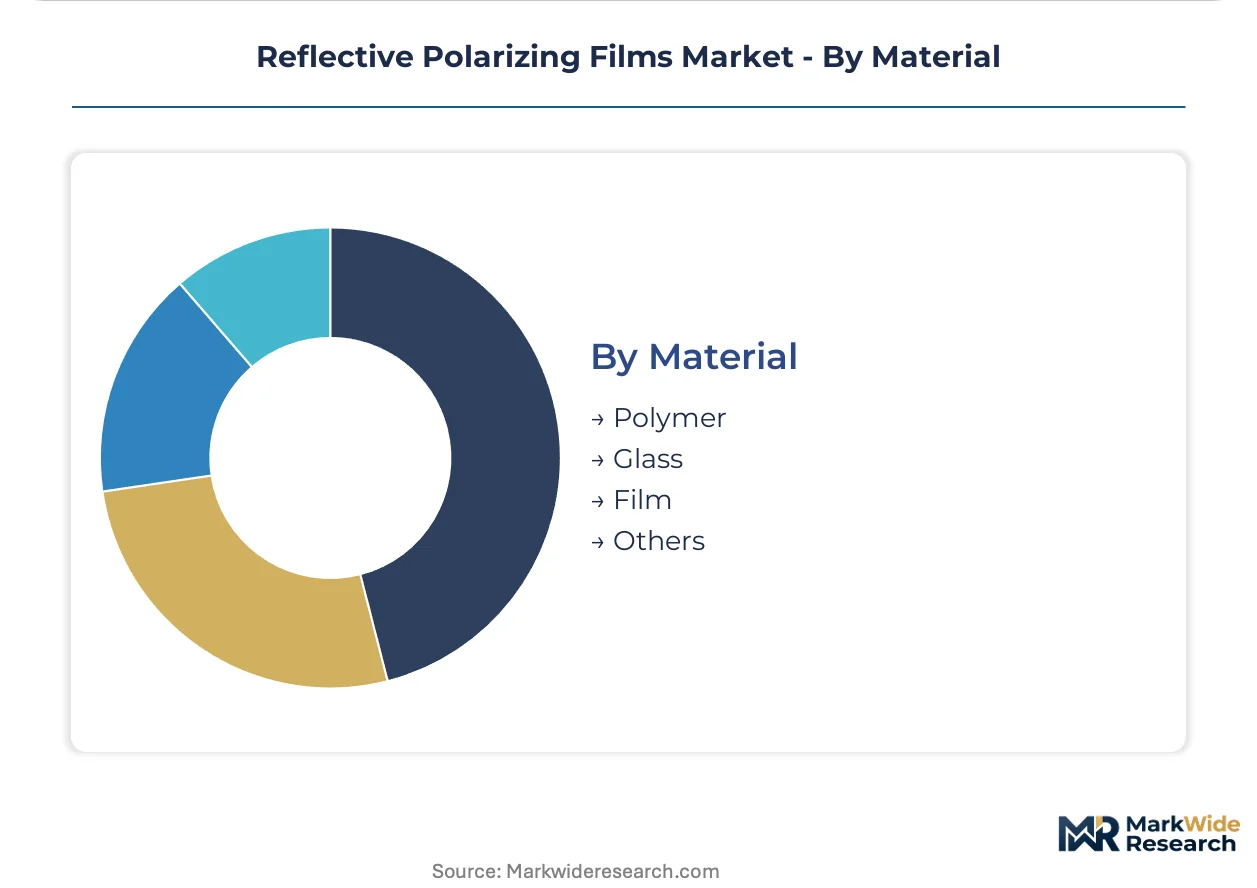
Supply concentration and margin structure vary by substrate chemistry. Polymer films dominate high-volume applications with scalable coextrusion. Glass substrates sustain niche premium positioning where optical precision outweighs weight penalties.
- Polymer:Multilayer birefringent stacks from polyimide, polyethylene naphthalate, and cyclic olefin polymers enable mechanical flexibility for foldable displays. Japanese suppliers dominate proprietary stretching equipment for these substrates.
- Glass:Borosilicate and soda-lime substrates for high-temperature automotive and industrial applications.
- Film:Composite laminates combining polymer and nanostructured dielectric layers.
- Others:Liquid crystal polymer and bio-based alternatives under ISCC PLUS certification.
Polymer leads by installed capacity. Glass maintains premium positioning despite volume constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan and South Korea export reflective polarizing films to display panel manufacturers across China and Vietnam, creating an East Asian trade corridor that concentrates procurement decisions in Seoul, Tokyo, and Shenzhen.
South Korea
Samsung Display and LG Display drive specifications for ultra-thin circular polarizers in foldable smartphones. MFDS optical material guidelines and national carbon neutrality targets by 2050 compress supplier qualification timelines. Gyeonggi Province hosts convergent R&D clusters where polymer substrate producers co-locate with panel laminators.
Japan
Toray Industries and Nitto Denko anchor proprietary PVA stretching technology for high-brightness television stacks. METI's JIS optical material specifications and 2030 decarbonization roadmap constrain adhesive chemistry selection. Kansai region manufacturing bases supply multilayer coextrusion equipment to downstream converters across East Asia.
China
BOE Technology Group and TCL CSOT consume the majority of imported reflective polarizer substrates for domestic LCD and OLED expansion. GB standards for display energy efficiency and provincial dual carbon intensity targets reward optical efficiency improvements. Yangtze River Delta cities including Suzhou and Hefei concentrate captive film laminating operations.
United States
Automotive HUD integrators and medical display manufacturers source specialty reflective polarizers for wide-temperature applications. FDA optical device classifications and EPA manufacturing emissions standards shape product development timelines for healthcare-bound supply chains. Michigan and Texas automotive clusters specify curved polarizers for electric vehicle interior screens.
Germany
BMW and Mercedes-Benz mandate cradle-to-gate carbon documentation for all optical components in electric vehicle display modules. REACH restrictions on halogenated flame retardants under ECHA guidance accelerate adhesive chemistry substitution toward phosphorus-based systems. Baden-Württemberg automotive suppliers qualify wide-viewing-angle films for pillar-to-pillar infotainment systems.
Reflective Polarizing Films Market Vendor Landscape
Listed leaders compete with private specialists across patent-protected optical film architectures, creating a tiered structure where scale advantages concentrate with diversified chemical conglomerates while niche positioning persists among substrate technology purists. Three archetypes dominate: integrated chemical-display conglomerates with captive demand, independent optical film specialists with proprietary stretching equipment, and diversified materials suppliers leveraging polymer science crossovers. Competitive intensity manifests through technology licensing provisions in dual-source agreements and backward integration into PVA substrate production.
Within the integrated chemical-display tier, LG Chem Ltd. and Kolon Industries, Inc. exemplify conglomerate positioning through affiliated panel operations that internalize procurement volume. Among independent specialists, Toray Industries, Inc. anchors Japan's domestic substrate supply position. 3M Company occupies the diversified materials archetype, leveraging optical science capabilities across multiple industrial end-uses. These three represent distinct strategic postures rather than comparable scale metrics.
| Leading Market Players |
|---|
| 3M Company |
| Dai Nippon Printing Co., Ltd. |
| LG Chem Ltd. |
| Nitto Denko Corporation |
| Kolon Industries, Inc. |
| DuPont |
| Fusion Optix, Inc. |
| Gamma Optical Co., Ltd. |
| Toray Industries, Inc. |
| Others |
Supply Flow & Price Mechanics
Phosphorus-based adhesive chemistry substitution for banned halogenated flame retardants under REACH guidance simultaneously redraws European supply geography toward certified German laminators and compresses margin structures for converters lacking chemistry-transition capabilities. Buyers now face qualification premiums for compliant stacks while spot-market PVA substrate availability tightens around Japanese stretching equipment maintenance windows.
Pricing Analysis
Foldable OLED-grade circular polarizers command substantial premiums over legacy television linear configurations, while nanostructured dielectric stacks for premium smartphone displays sit at the apex of the technology curve. Three-tier pricing structure across premium, standard, and economy levels separates automotive HUD-qualified films from commodity monitor backlight recyclers. Cost compression in television-grade linear polarizers is intensifying because Chinese panel makers consolidate procurement around dual-source captive agreements. Consumer electronics display manufacturers exhibit highest price sensitivity through volume consolidation tactics, whereas German automotive OEMs accept premium positioning for carbon-documented supply chains.
Supply Chain Analysis
Strategic stockpile preferences dominate reflective polarizing film procurement, with Samsung Display and LG Display maintaining six-month substrate buffers against PVA stretching equipment downtime in Japan. Supply concentrates in Japan, South Korea, and China, where Toray Industries and Nitto Denko anchor proprietary polymer stretching technology. Downstream converters draw from polyvinyl alcohol cores, cellulose triacetate protective skins, and quarter-wave retardation layers. Single-source vulnerability around Japanese stretching equipment exposes the supply chain to regional disruption. Distribution runs through qualified supplier programs for specialty grades and commodity channels for television linear polarizers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reflective polarizing film demand fragments across application-specific performance vectors, with foldable OLED specifications, automotive thermal resilience requirements, and quantum dot hybrid stacks creating distinct procurement niches that resist commoditization.
For Market Incumbents: Compound patent-protected optical architectures into captive demand structures through technology-licensing provisions in dual-source agreements, defending against nanostructured dielectric displacement by Samsung Display and BOE Technology Group qualification wins. Prioritize backward integration into PVA substrate production to reduce Japanese equipment dependency exposure. For New Entrants and Emerging Players: Differentiate on bio-based TAC alternatives certified through ISCC PLUS chain-of-custody standards, targeting German automotive OEM cradle-to-gate carbon documentation requirements as the most penetrable premium segment. Pursue perovskite quantum dot hybrid stack partnerships with mini-LED backlight integrators as the primary go-to-market angle. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors substrate-chemistry specialists over commodity laminators, with nanostructured dielectric displacement compressing conventional PVA-TAC valuations while foldable OLED specifications expand addressable premium volume. Target independent optical film specialists with proprietary stretching equipment and established JIS certification pathways. Watch for ECHA guidance expansion on halogenated flame retardant restrictions as the inflection signal for chemistry-transition investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PVA Substrate Production | Reduces Japanese stretching equipment dependency for Korean and Chinese laminators. |
| ISCC PLUS Bio-Based TAC Certification | Enables German automotive OEM qualification under EU Green Deal embodied carbon tracking. |
| Perovskite Quantum Dot Hybrid Stack Development | Positions suppliers for mini-LED backlight single-layer convergence with reflective polarizers. |
| Dual-Source Agreement with Technology Licensing | Mirrors Samsung Display and LG Display procurement consolidation for supply security. |
| Phosphorus-Based Adhesive Chemistry Transition | Aligns with REACH ECHA guidance for European-bound automotive and consumer electronics supply chains. |
Methodological Framework
A standing panel of display panel procurement directors, optical film R&D leads, automotive tier-one supplier quality managers, and polymer substrate plant engineers provided ongoing calibration across primary interview cycles. Secondary validation drew from SEC 10-K filings of listed chemical conglomerates, Japanese Ministry of Economy Trade and Industry optical material bulletins, China GB standard energy efficiency disclosures, and Korea Display Industry Association production statistics. Bottom-up substrate demand modeling and top-down display panel shipment analysis were triangulated against trade flow data.
Consistency checks validated volume and value outputs against external benchmarks including customs export records from Japan and South Korea, regional display panel capacity announcements, and automotive OEM interior screen procurement disclosures. Segmentation dimensions spanned product type, application, end user, and material chemistry across the projection horizon. CAGRs were derived from elasticity-adjusted adoption curves for foldable OLED penetration and quantum dot color conversion convergence. Industry-specific inputs included PVA stretching equipment utilization rates and ECHA regulatory guidance timelines.
The analysis sits within stated boundaries; outcomes outside sustained foldable OLED volume expansion or accelerated REACH chemical restriction enforcement would require recalibration. Forecasts reflect assumptions around East Asian manufacturing concentration persistence and polymer substrate technology transition rates. Revision becomes warranted when nanostructured dielectric reflective polarizer qualification crosses threshold penetration in premium smartphone display stacks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Gutta-Percha Market
Specialty Materials
Electrode Paste Market
Specialty Materials
Mesoporous Silica Market
Specialty Materials
Conductive Plastics Market
Specialty Materials
Talc Alternatives Market
Specialty Materials
Africa Collagen Market
Specialty Materials
Barium Borate Market
Specialty Materials
Asia-Pacific Green Sic Market
Specialty Materials
Hydrolysis Stable Polyester Films Market
Specialty Materials
Spermaceti Wax Market
Specialty Materials
North America Microspheres Market
Specialty Materials
Global Cellulose Esters Market
Specialty Materials
Methyl Silicone Market
Specialty Materials
Specialty Coating Market
Specialty Materials
Vulcanized Fiber Market
Specialty Materials
Specialty Silicone Market