
 Flexible Glass Market | 2026-2036
Flexible Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Glass Market Intelligence
ISO 9001 quality management certification is reorganizing supplier qualification protocols for flexible glass substrate vendors serving tier-one display manufacturers. Corning Incorporated leverages its fusion draw process to sustain ultra-thin sheet consistency at commercial scale. AGC Inc. anchors Japanese supply chains through proprietary float-glass thinning technologies. SCHOTT AG differentiates via deep specialization in borosilicate compositions for high-thermal-stability applications.
Flexible glass denotes alkali-free borosilicate or aluminosilicate sheets manufactured below 0.2 millimeters thickness, engineered to bend to radii under 5 millimeters without fracture through ion-exchange chemical strengthening. The material functions primarily as a mechanically stable, optically transparent barrier layer for organic electronics and photovoltaic architectures. OLED Displays command the dominant value share among product types, driven by foldable smartphone panel ramps and automotive curved cockpit integrations. Consumer Electronics applications absorb the largest volume flows, though Automotive Displays represent the fastest-expanding margin pool as dashboard digitization accelerates. Roll-to-Roll Processing technology leads throughput scalability, while Thin Film Deposition retains premium positioning for precision coating requirements.
EPA hazardous waste regulations constrain solvent recovery systems in U.S.-based chemical vapor deposition facilities, elevating capital requirements for domestic producers. REACH substance restrictions within the European Union limit certain heavy-metal dopants in glass formulations, redirecting R&D toward compliant alternative compositions. China's GB standards for display-grade glass impose additional testing protocols on imported substrates. Stakeholders must monitor evolving automotive safety glass homologation timelines and display maker qualification cycles to align capacity commitments with validated demand windows.
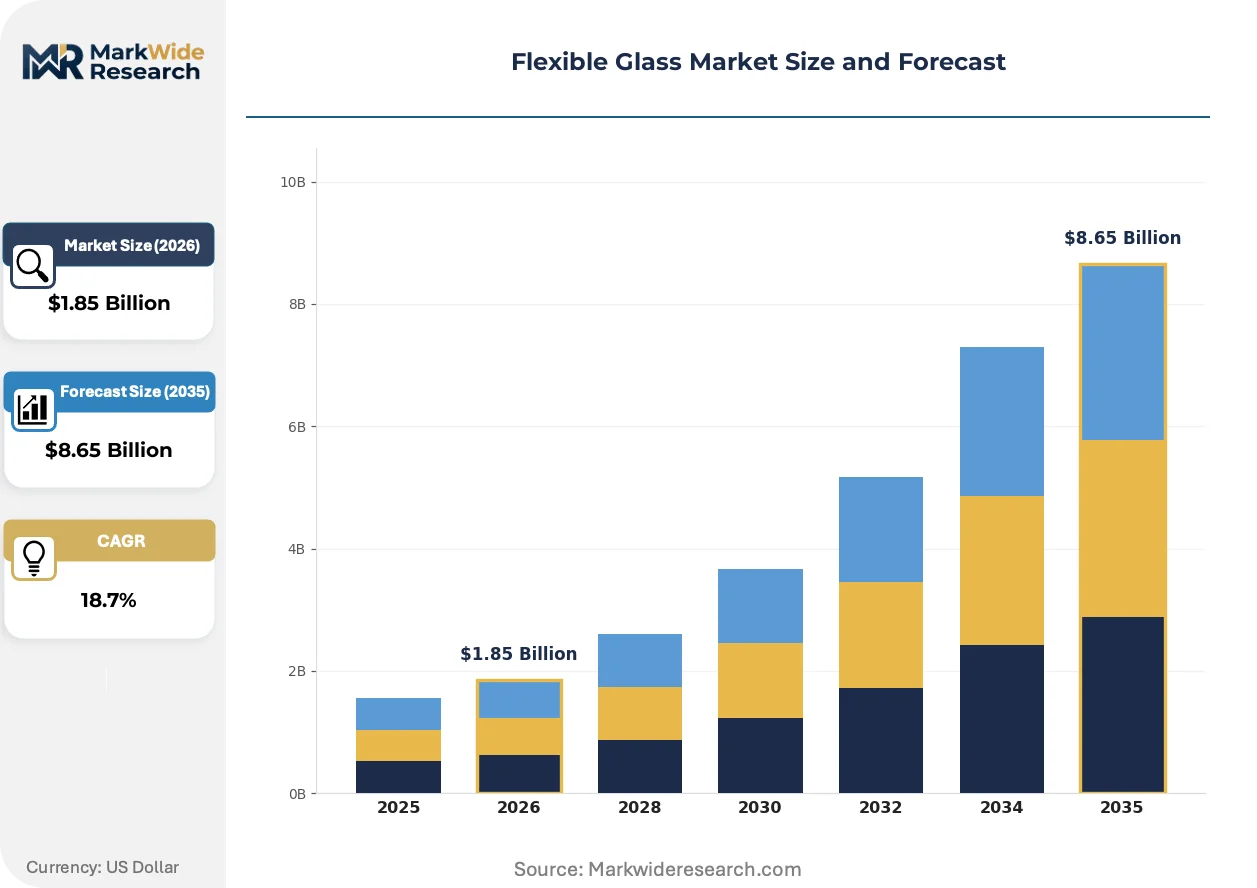
Market Dynamics
Foldable OLED panel qualification cycles are compressing supplier lead times while ion-exchange chemical strengthening throughput constraints create order backlogs at substrate conversion facilities.
Growth Catalysts
- Automotive cockpit digitization:Curved instrument clusters and freeform center displays in premium vehicle segments are qualifying flexible glass for dashboard integration. Tier-one automotive suppliers are expanding substrate sampling programs.
- REACH substance restriction compliance:European heavy-metal dopant limitations are accelerating R&D into alternative glass compositions. Compliant formulations are unlocking qualification pathways with EU-based display manufacturers.
- Roll-to-roll processing scale-up:Continuous sheet manufacturing is reducing unit costs for ultra-thin substrates below 0.1 millimeters. Korean equipment vendors are deploying next-generation coating lines.
Market Restraints
- High-purity silica sand concentration:Strategic reserves in select geographies create input cost volatility for borosilicate formulations. Supply security concerns are elevating working capital requirements.
- Fusion draw furnace capex intensity:Single production lines demand nine-figure capital commitments with five-year depreciation schedules. New market entrants face prohibitive scale thresholds.
- Polycarbonate and cyclic olefin polymer substitution:Lower-cost transparent polymers are capturing price-sensitive applications in secondary display layers. Material substitution is compressing addressable volume in mid-tier electronics.
Strategic Opportunities
- Building-integrated photovoltaics:Flexible glass encapsulation for organic solar cells is penetrating commercial facade installations. Japanese construction consortiums are piloting curved photovoltaic glazing systems.
- India PLI scheme for display manufacturing:Domestic panel production incentives are creating substrate qualification opportunities with emerging Indian display fabs. Local content requirements favor regional glass conversion partnerships.
- Wearable device form-factor convergence:Smartwatch and AR headset manufacturers are specifying sub-0.05 millimeter substrates for skin-contact applications. Biocompatibility certifications are opening medical wearable segments.
Industry Challenges
- Ion-exchange engineering talent scarcity:Chemical strengthening process optimization requires specialized materials science expertise. Korean and Japanese facilities are competing for finite technical personnel pools.
- Automotive safety glass homologation timelines:ECE R43 and FMVSS 205 validation cycles extend eighteen to thirty-six months. Misaligned capacity commitments risk stranding inventory before qualification completion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Glass Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $8.65 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: OLED Displays, Solar Panels, Smart Windows, Flexible Screens Application: Consumer Electronics, Automotive Displays, Architectural Glass, Wearable Devices End User: Manufacturers, Retailers, Construction Firms, Electronics Companies Technology: Thin Film Deposition, Chemical Vapor Deposition, Roll-to-Roll Processing, Laser Cutting |
| Companies Covered | Corning Incorporated, AGC Inc., Saint-Gobain, Nippon Electric Glass Co., Ltd., SCHOTT AG, Compagnie de Saint-Gobain S.A., NSG Group, PPG Industries, Inc., Xinyi Glass Holdings Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Glass Market Strategic Shifts & Innovations
Substrate manufacturing is bifurcating between precision deposition for premium display tiers and high-speed roll processing for cost-optimized volume segments.
Laser-induced glass thinning is fragmenting conventional mechanical grinding workflows. Korean display makers are adopting femtosecond laser ablation for sub-50 micrometer thickness targets. The technology is compressing capital requirements for mid-scale substrate converters while enabling tighter bend radius specifications.
EPA hazardous waste regulations are constraining solvent recovery in chemical vapor deposition facilities. Domestic US producers face elevated environmental compliance costs compared to Asian manufacturing bases. Display-grade substrate imports are capturing share in North American panel assembly operations.
Direct mill-to-fab substrate supply contracts are displacing multi-tier distribution for qualified display manufacturers. Korean and Chinese panel makers are consolidating procurement through single-source agreements with fused silica suppliers. Contract structures are most visible in South Korea's Gyeonggi-do cluster.
Flexible Glass Market Segmentation
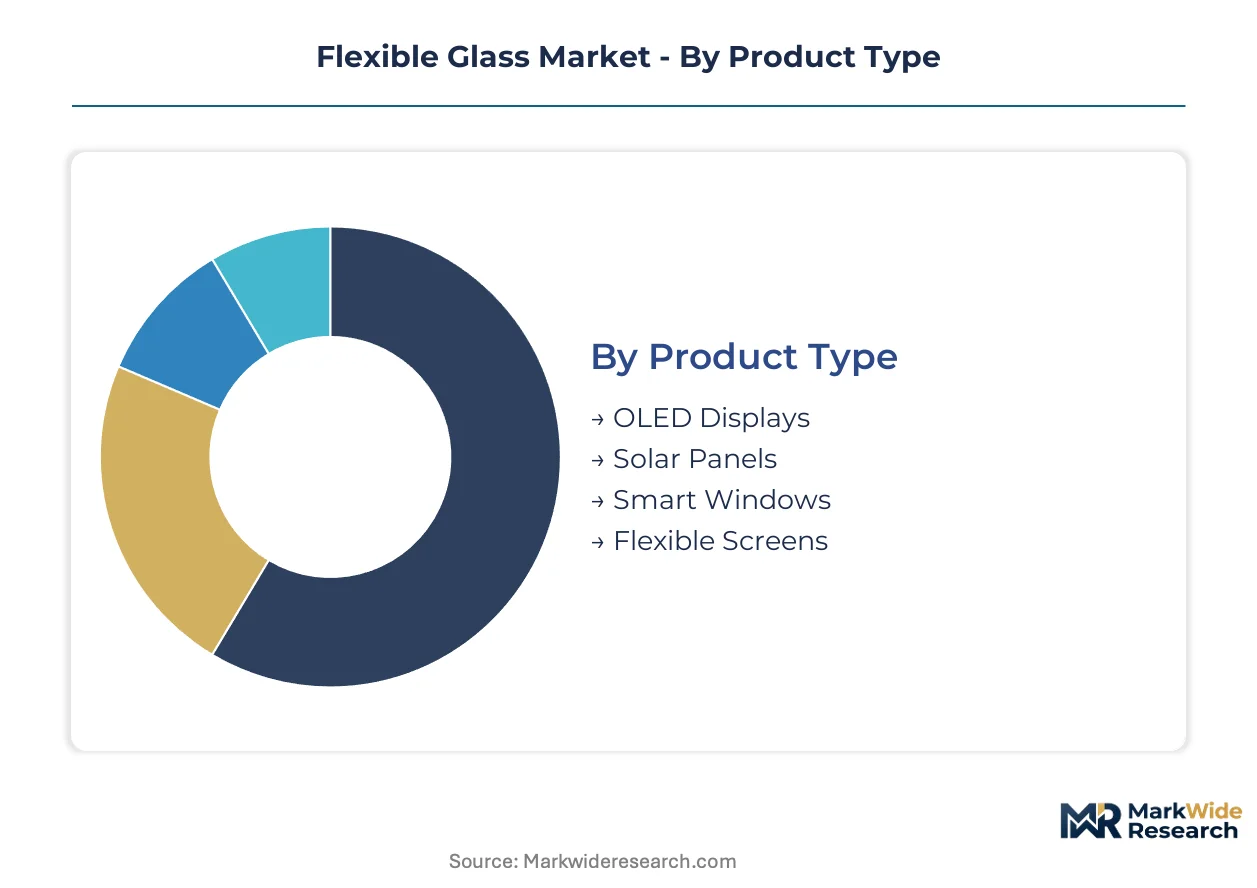
Flexible glass procurement patterns diverge sharply across end-use applications, with display manufacturers prioritizing optical precision while construction and energy sectors emphasize durability and scale economics. Understanding segment-level margin distribution enables substrate suppliers to align furnace capacity with the highest-value qualification pipelines.
Product Type:
Premium margin pools concentrate in display-grade substrates where ion-exchange strengthening and surface roughness specifications command technical premiums over commodity solar encapsulation.
- OLED Displays:Alkali-free borosilicate sheets below 0.1 millimeters thickness undergo chemical strengthening for sub-5 millimeter bend radii. Foldable smartphone panel ramps in South Korea and curved automotive cockpit programs in Germany are absorbing qualified substrate volumes fastest.
- Flexible Screens:Sub-0.05 millimeter substrates for rollable tablets and scrollable monitors require fusion-draw manufacturing for thickness uniformity. Japanese equipment vendors are deploying next-generation coating lines to serve emerging form-factor specifications.
- Solar Panels:Flexible glass encapsulation for organic photovoltaics prioritizes moisture barrier performance over optical clarity.
- Smart Windows:Electrochromic and thermochromic glazing applications demand larger sheet formats with integrated conductive coatings.
The dominant share belongs to OLED Displays, while Flexible Screens is closing the gap fastest.
Application:
Volume throughput concentrates in consumer electronics, though automotive qualification timelines are reshaping capacity allocation toward longer-contract, higher-margin supply agreements.
- Automotive Displays:Freeform center consoles and curved instrument clusters require ECE R43 and FMVSS 205 homologation. Tier-one German and Japanese suppliers are expanding substrate sampling programs for dashboard digitization roadmaps.
- Wearable Devices:Skin-contact smartwatch and AR headset specifications demand sub-0.05 millimeter thickness with biocompatibility certifications. Korean and Chinese device makers are driving medical wearable segment penetration.
- Consumer Electronics:Foldable smartphones and rollable tablets absorb the largest substrate volumes through established supply chains.
- Architectural Glass:Building-integrated photovoltaic facades and electrochromic windows prioritize cost-optimized roll-to-roll processing.
Consumer Electronics holds the largest volume position, though Automotive Displays shows the steepest expansion trajectory.
End User:
Procurement authority is consolidating among integrated display manufacturers with in-house panel assembly, fragmenting distributor influence.
- Electronics Companies:Samsung Display and LG Display anchor direct mill-to-fab contracts with fused silica suppliers. Single-source agreements are displacing multi-tier distribution for qualified substrate volumes.
- Manufacturers:Substrate conversion facilities and chemical strengthening operations serve as supply chain intermediaries for non-integrated panel makers.
- Construction Firms:Japanese building consortiums pilot curved photovoltaic glazing systems with specialized encapsulation requirements.
- Retailers:Aftermarket screen protection and device accessory channels absorb lower-specification flexible glass volumes.
Electronics Companies command procurement concentration, while Construction Firms are gaining contract visibility fastest.
Technology:
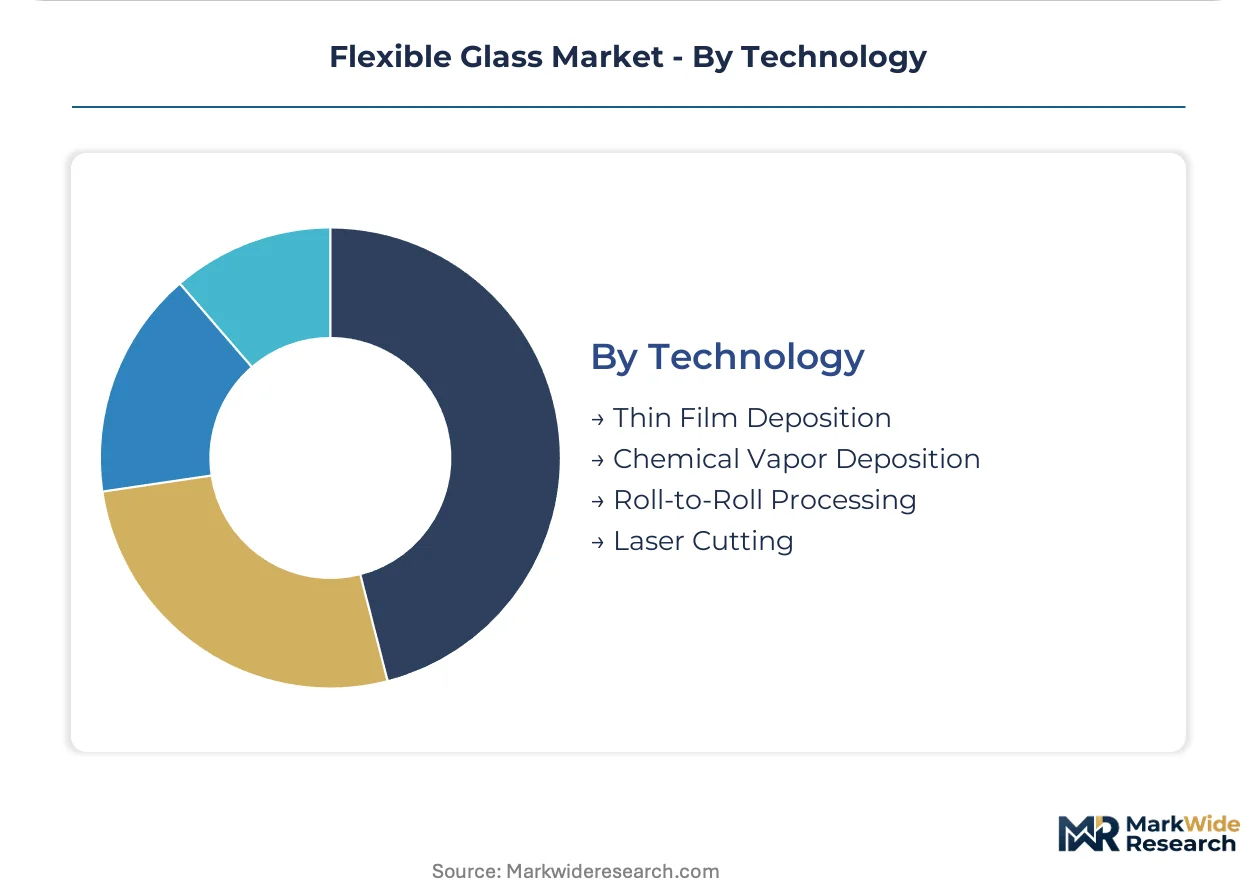
Capital intensity bifurcates between precision deposition for premium tiers and high-speed roll processing for cost-optimized volume segments.
- Roll-to-Roll Processing:Continuous sheet manufacturing reduces unit costs for ultra-thin substrates below 0.1 millimeters. Korean equipment vendors are scaling next-generation coating lines for commercial deployment.
- Thin Film Deposition:Sputtering and evaporation techniques retain premium positioning for display-grade barrier coatings with angstrom-level thickness control.
- Chemical Vapor Deposition:EPA hazardous waste regulations constrain solvent recovery systems in U.S.-based facilities, elevating compliance costs versus Asian manufacturing bases.
- Laser Cutting:Femtosecond laser ablation is fragmenting mechanical grinding workflows for sub-50 micrometer thickness targets.
Roll-to-Roll Processing leads throughput scale, while Thin Film Deposition maintains the highest margin capture rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Display manufacturing incentives in South Korea and China's dual carbon goals are redirecting flexible glass capacity toward Asia-Pacific production clusters. EPA constraints in the United States and REACH compliance costs in Europe are elevating substrate import dependence in Western markets.
South Korea
Samsung Display and LG Display anchor substrate qualification programs for foldable smartphone panels. The Ministry of Trade, Industry and Energy (METI) coordinates domestic supply chain development under national advanced materials initiatives. The Gyeonggi-do cluster concentrates mill-to-fab direct contracts between fused silica suppliers and integrated panel manufacturers.
China
GB standards for display-grade glass impose additional testing protocols on imported substrates while domestic panel makers scale OLED capacity. MIIT industrial policy prioritizes self-sufficiency in advanced display materials under dual carbon reduction targets. The Yangtze River Delta hosts expanding chemical strengthening facilities serving domestic electronics manufacturers.
United States
Automotive curved cockpit programs in Michigan and California are qualifying flexible glass for dashboard digitization roadmaps. EPA hazardous waste regulations constrain solvent recovery systems in chemical vapor deposition facilities, elevating capital requirements. Display-grade substrate imports are capturing share in North American panel assembly operations.
Germany
Tier-one automotive suppliers in Bavaria and Baden-Württemberg are expanding substrate sampling programs for freeform center console integration. ECE R43 homologation timelines extend eighteen to thirty-six months, aligning capacity commitments with validation cycles. The Stuttgart industrial corridor concentrates precision coating requirements for premium vehicle segments.
Japan
Building-integrated photovoltaic consortiums are piloting curved glazing systems with specialized encapsulation requirements. METI coordinates construction sector adoption under national renewable energy deployment targets. The Nagoya-Tokyo corridor hosts next-generation roll-to-roll coating line deployments for sub-0.05 millimeter substrate specifications.
Flexible Glass Market Key Industry Players
Player mix skews toward integrated materials conglomerates with captive fusion draw capabilities and specialized borosilicate formulators. Three to four entities control premium substrate throughput through multi-decade furnace asset bases. Strategic archetypes separate fusion-draw specialists, float-glass thinners, and regional conversion facilities. Dominant competitive moves include direct mill-to-fab contract consolidation and ion-exchange process technology licensing.
Within the integrated conglomerate tier, Corning Incorporated and AGC Inc. occupy positions representing scale-driven substrate consistency, while SCHOTT AG exemplifies high-thermal-stability specialization through borosilicate composition expertise. These three entities anchor distinct competitive vectors: fusion-draw ultra-thin uniformity, float-glass thinning scale, and premium thermal performance respectively.
| Leading Market Players |
|---|
| Corning Incorporated |
| AGC Inc. |
| Saint-Gobain |
| Nippon Electric Glass Co., Ltd. |
| SCHOTT AG |
| Compagnie de Saint-Gobain S.A. |
| NSG Group |
| PPG Industries, Inc. |
| Xinyi Glass Holdings Limited |
| Others |
Cost & Logistics Intelligence
Polycarbonate and cyclic olefin polymer substitution in secondary display layers is compressing mid-tier electronics pricing while simultaneously diverting substrate demand toward South Korean and Chinese conversion facilities with scale-advantaged cost structures. This material displacement dynamic concentrates procurement power among integrated panel manufacturers capable of qualifying premium borosilicate grades.
Pricing Analysis
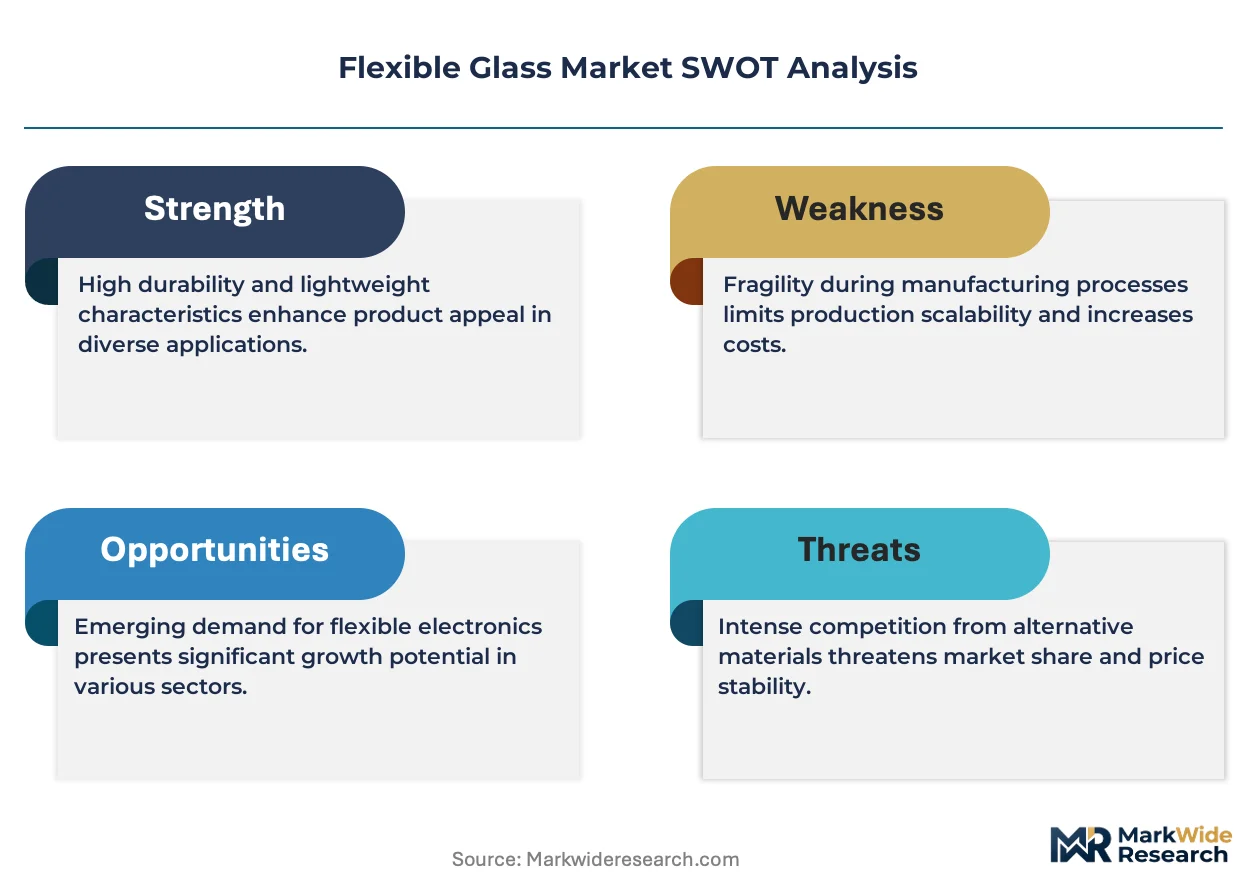
Certification level creates the primary spread, with ISO 9001-qualified substrates commanding substantial premiums over non-certified volumes in direct mill-to-fab contracts. Three-tier pricing structure separates display-grade ion-exchange strengthened sheets from automotive homologation-tier products and commodity solar encapsulation grades. Pricing pressure stems from polycarbonate substitution in price-sensitive wearable applications. Automotive tier-one suppliers exhibit lowest price sensitivity due to eighteen-to-thirty-six month qualification lock-ins, while aftermarket retailers face acute margin compression.
Supply Chain Analysis
Strategic stockpiling of high-purity silica sand reserves distinguishes integrated conglomerates from conversion-dependent competitors facing input volatility. Primary supply concentration rests in the United States, Germany, and Japan for fused silica feedstock, with South Korea and China dominating downstream chemical strengthening. Raw material dependencies draw from boron compounds, high-purity silica sand, and potassium nitrate for ion-exchange baths. Single-source vulnerability concentrates in fusion draw furnace assets with nine-figure replacement costs. Distribution runs through direct mill-to-fab contracts displacing multi-tier channels for qualified display manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flexible glass penetration sits at early-cycle expansion, with foldable smartphone panel ramps and automotive cockpit digitization creating validated demand windows ahead of supply capacity alignment.
For Market Incumbents: Fortify fusion draw asset utilization through long-term offtake agreements with Korean and Chinese panel makers before alternative substrate technologies mature. Lock in high-purity silica sand reserves through backward integration or captive supply contracts to neutralize input cost volatility. Prioritize ion-exchange process licensing revenue streams as technical talent scarcity constrains competitor scale-up.
For New Entrants and Emerging Players: Lead with laser-induced thinning equipment sales to mid-scale converters seeking sub-50 micrometer capability without fusion draw capital intensity. Target India's PLI-supported display fabs with regional conversion partnerships satisfying local content requirements. Pursue building-integrated photovoltaic encapsulation as the most penetrable segment outside display dominance.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty glass converters possessing qualified automotive homologation pipelines but constrained by furnace capacity bottlenecks. Five-to-ten year viability hinges on sustained foldable device form-factor proliferation and curved automotive display adoption. Watch ECE R43 and FMVSS 205 validation completion rates as inflection indicators for automotive tier qualification velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct Mill-to-Fab Contract Consolidation | Korean Gyeonggi-do cluster panel makers are displacing multi-tier distribution through single-source fused silica agreements. |
| Ion-Exchange Process Technology Licensing | Technical talent scarcity in Korean and Japanese facilities creates recurring revenue streams for proprietary strengthening protocols. |
| High-Purity Silica Sand Reserve Acquisition | Strategic input control neutralizes borosilicate formulation cost volatility from geographically concentrated deposits. |
| Automotive Homologation Pipeline Investment | Eighteen-to-thirty-six month ECE R43 and FMVSS 205 cycles lock in premium pricing before volume commoditization. |
| Roll-to-Roll Coating Line Scale-Up | Japanese Nagoya-Tokyo corridor equipment vendors enable sub-0.05 millimeter substrate cost parity for wearable applications. |
Research Approach
Operator-level perspectives from display panel procurement directors, ion-exchange process engineers, automotive tier-one supplier technical leads, and construction consortium glazing specifiers anchored the qualitative base. These primary insights combined with secondary validation from SEC 10-K filings of integrated glass manufacturers, Korean Ministry of Trade customs data, EPA hazardous waste enforcement records, and ECHA REACH substance restriction updates. Bottom-up substrate volume modeling triangulated against top-down display panel production forecasts.
Sensitivity analysis tested forecast robustness across alternative foldable smartphone adoption curves and automotive cockpit digitization timelines throughout the projection horizon. Segmentation dimensions modeled include product thickness tier, end-use application, strengthening technology, and regional manufacturing cluster. CAGRs derived from installed capacity utilization trajectories and qualification pipeline visibility. Industry-specific inputs incorporated ion-exchange bath throughput constraints and fusion draw furnace depreciation schedules.
Forecasts assume regulatory continuity in EPA hazardous waste enforcement and ECHA REACH substance restrictions; material policy shifts would require re-modeling. Revision becomes warranted when polycarbonate substitution rates in secondary display layers or laser thinning equipment deployment velocities cross thresholds altering substrate demand elasticity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Silica Sol Market
Glass
Technical Glass Market
Glass
Low Temperature Laminated Glass Market
Glass
Glass Product Market
Glass
Shatterproof Glass Market
Glass
Silica Sand for Glass Making Market
Glass
Optical Lens Material Market
Glass
Global Ultra-Thin Glass Market
Glass
Tinted Glass Market
Glass
Asia-Pacific Flat Glass Market
Glass
Anti-Smudge and Anti-Streak Additives for Glass Cleaners Market
Glass
Europe Sapphire Glass Market
Glass
Spherical Silica Market
Glass
Glass Tableware Market
Glass
UAE Silica Sand Market
Glass
Glass Alternative Materials Market