
 Glass Grade Dolomite Market | 2026-2036
Glass Grade Dolomite Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Grade Dolomite Market Insights
Container glass manufacturing is pivoting toward lightweighting and higher recycled cullet ratios, tightening specifications for dolomite flux agents. Sibelco leverages its integrated quarry-to-port network across Belgium and Norway to sustain supply security for premium glassmakers. Carmeuse anchors its position through deep vertical integration into lime and dolomite calcination, controlling thermal processing costs. Imerys S.A. differentiates via specialized ultra-low-iron dolomite grades targeting optical and solar glass segments.
Glass grade dolomite is a calcium magnesium carbonate mineral (CaMg(CO₃)₂) processed to strict chemical purity thresholds, typically requiring less than 0.1% Fe₂O₃ and controlled silica content below 2%, then calcined or supplied raw as a fluxing agent to reduce melting temperatures and improve chemical durability in soda-lime-silica glass. Its primary purpose is to supply magnesium oxide and calcium oxide during batch melting, preventing devitrification while enhancing thermal shock resistance in finished glassware. Calcined dolomite commands the dominant value share due to its predictable reactivity and lower volatile content, while dolomite powder is gaining traction in specialty glass and thin-film coating applications where precise dosing matters. Uncalcined raw dolomite retains cost advantages in container glass but faces margin compression as energy-intensive kilns shift toward pre-calcined inputs to cut furnace fuel consumption.
The EU REACH framework and CE marking requirements for construction materials directly shape glass grade dolomite market access, mandating full supply chain chemical disclosure and traceability. EPA air quality standards in the United States and India's BIS certification for industrial minerals impose parallel constraints on mining permits and beneficiation plant emissions. Stakeholders must monitor tightening iron-content thresholds from automotive and display glass buyers, as these specifications will determine which dolomite deposits retain commercial viability without costly beneficiation upgrades.
Market Dynamics
Container glass manufacturers are tightening dolomite purity specifications as recycled cullet ratios climb past 50%, forcing flux suppliers to certify sub-0.08% Fe₂O₃ thresholds or forfeit volume to integrated quarry operators.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbons in glass melting furnaces accelerates demand for pre-calcined dolomite that cuts fuel intensity and lowers Scope 1 emissions.
- Float glass capacity expansion:India's domestic flat glass sector is accelerating local dolomite offtake as new melting lines commission near Gujarat and Tamil Nadu mineral belts.
- Optical glass specification creep:Ultra-low-iron dolomite grades are penetrating solar panel cover glass and display substrate batches as magnesium oxide purity thresholds tighten.
Market Restraints
- Natural gas price volatility:Calcination energy costs swing with European TTF and Henry Hub benchmarks, compressing margins for merchant dolomite processors without captive kiln capacity.
- Deposit concentration:Premium glass-grade reserves cluster in Belgium's Lhoist belt and Norway's coastal quarries, creating single-source vulnerability for Asian float glassmakers.
- Limestone-magnesite substitution:Synthetic periclase and high-purity limestone blends threaten dolomite in cost-sensitive container glass segments where iron tolerance exceeds 0.15%.
Strategic Opportunities
- Specialty thin-film coatings:Dolomite nanopowder is expanding into anti-reflective and conductive oxide layers for photovoltaic and electrochromic glass stacks.
- EU Green Deal carbon border adjustments:CBAM phase-in from 2026 creates preference for EU-sourced, low-carbon-intensity dolomite in premium automotive glass supply chains.
- Digital batch optimization:AI-driven furnace control systems enable precise dolomite dosing variability, opening specification flexibility for mid-tier deposits previously excluded.
Industry Challenges
- Beneficiation capex intensity:Magnetic separation and flotation upgrades to achieve sub-0.1% iron grades require 15-20 million dollar plant investments with 7-year payback cycles.
- REACH dossier maintenance:Full supply chain chemical disclosure and SVHC monitoring impose recurring compliance costs that squeeze small-scale quarry operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Grade Dolomite Market |
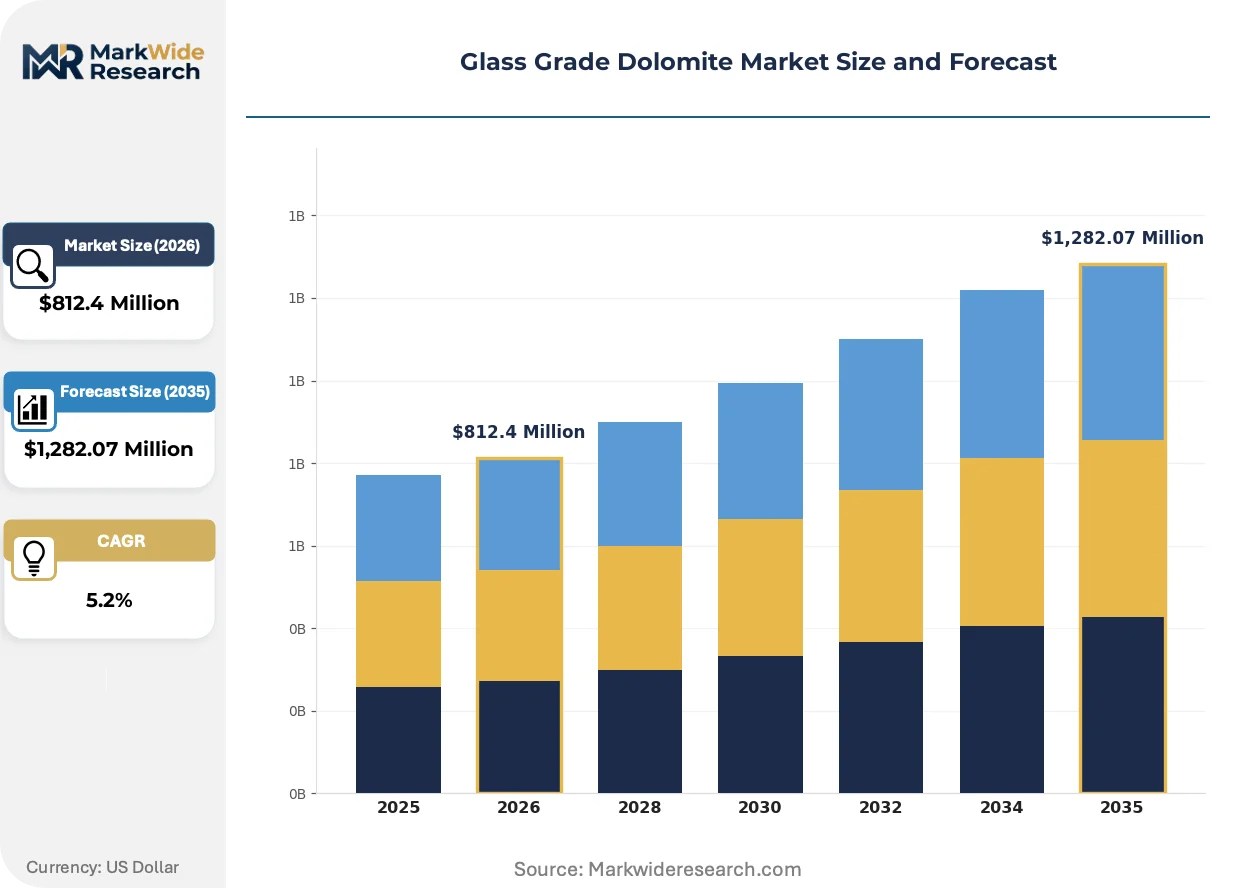
| Market Size in 2026 | $812.4 Million |
| Market Size in 2035 | $1,282.07 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcined Dolomite, Uncalcined Dolomite, Dolomitic Lime, Dolomite Powder Application: Glass Manufacturing, Ceramics, Refractories, Construction End User: Glass Industry, Construction Sector, Chemical Sector, Automotive Industry Packaging Type: Bulk Bags, 50 kg Bags, 25 kg Bags, Pallets |
| Companies Covered | Sibelco, Carmeuse, Imerys S.A., JFE Mineral & Alloy Company, Nordkalk Corporation, Lhoist Group, RHI Magnesita, Arihant MinChem, Omya AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Grade Dolomite Market Trends and Innovations
Digital traceability and low-carbon processing are reconfiguring how glass-grade dolomite moves from quarry to furnace, with certification now as critical as chemistry.
Pre-calcined dolomite with controlled reactivity indices is expanding into container glass lines seeking to cut melting energy by 8-12%. Major beverage glassmakers in Germany and Italy are retrofitting batch houses to handle calcined inputs. This shift is compressing demand for raw dolomite in premium segments while opening volume for mid-iron deposits in cost-optimized furnace operations.
REACH SVHC candidate list expansion is forcing full chemical disclosure through tier-three suppliers. ECHA's 2024-2025 update cycle adds barium and strontium trace elements to monitoring protocols. Specialty optical glassmakers in the Netherlands and solar substrate producers in Spain are accelerating supply chain audits to preempt certification gaps.
Long-term offtake contracting is displacing spot purchasing for premium grades. Float glass producers in India and container specialists in France are locking three-to-five-year supply agreements with fixed iron-content bands. This concentration is visible most acutely in automotive glass supply chains where OEMs mandate certified raw material provenance back to quarry level.
Glass Grade Dolomite Market Segmentation
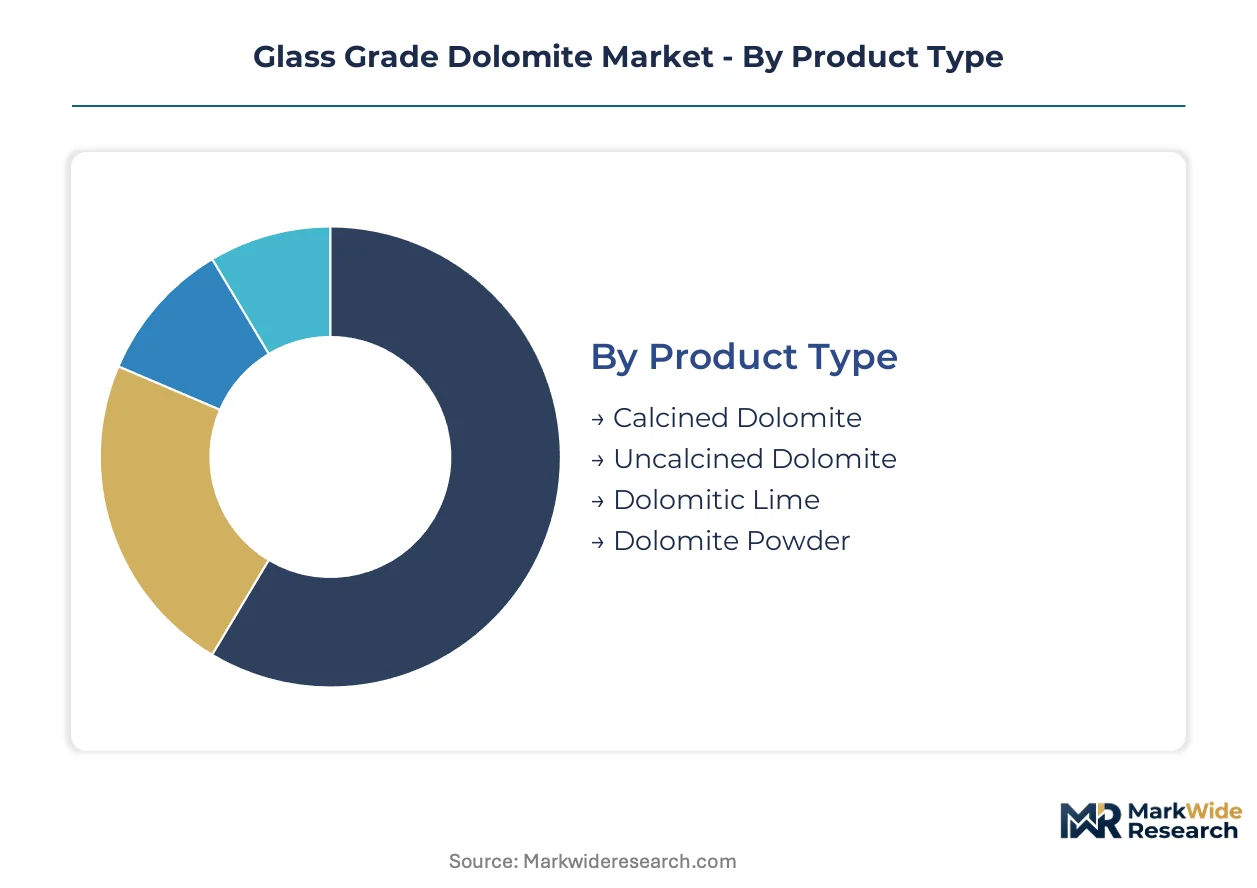
Glass grade dolomite specifications diverge sharply across furnace types and end-use purity thresholds. Product form, application intensity, and packaging logistics each reshape procurement economics and supplier selection criteria for buyers.
Product Type:
Thermal processing intensity distinguishes competitive positioning across product tiers.
- Calcined Dolomite:Pre-fired at 900-1200°C to drive off carbon dioxide, yielding MgO-CaO with predictable reactivity indices below 2% loss on ignition. Container glassmakers in Germany and Italy retrofit batch houses to handle calcined inputs that cut furnace fuel consumption by 8-12%.
- Uncalcined Dolomite:Raw calcium magnesium carbonate supplied directly to melting lines, retaining cost advantages where iron tolerance exceeds 0.15% and energy-intensive kilns remain uneconomical. Faces margin compression as pre-calcined alternatives displace volume in premium segments.
- Dolomitic Lime:Higher-calcination derivative with elevated CaO content, serving specialized refractory and chemical applications requiring aggressive fluxing action.
- Dolomite Powder:Finely milled sub-45 micron grades enabling precise dosing in thin-film coatings and specialty optical glass batches.
Calcined dolomite leads on scale; dolomite powder leads on momentum.
Application:
End-use chemistry requirements stratify supply chains from commodity flux to certified optical grades.
- Glass Manufacturing:Dominant consumption channel spanning container, float, and specialty glass. Soda-lime-silica batches incorporate dolomite at 10-15% by weight to supply magnesium oxide that prevents devitrification and enhances thermal shock resistance.
- Ceramics:Whiteware and sanitaryware applications demand controlled iron content below 0.1% Fe₂O₃ to preserve surface brightness.
- Refractories:High-temperature lining applications in steel and cement kilns utilize dead-burned dolomite with density above 3.0 g/cm³.
- Construction:Aggregate and dimension stone applications tolerate higher impurity levels, sourcing from lower-grade deposits excluded from glass certification.
Glass manufacturing commands volume concentration; ceramics and refractories split specialized grade demand.
End User:
Customer scale and certification requirements fragment procurement patterns across industrial verticals.
- Glass Industry:Float glass producers in India and container specialists in France lock three-to-five-year offtake agreements with fixed iron-content bands. OEM mandates in automotive glass supply chains require certified provenance back to quarry level.
- Construction Sector:Volume buyers accepting broader chemical tolerances, sourcing through spot markets and regional distributors rather than integrated quarry networks.
- Chemical Sector:Magnesium compound extraction and water treatment applications drive demand for high-reactivity calcined grades.
- Automotive Industry:Direct procurement of ultra-low-iron dolomite for laminated and tempered glass specifications, with iron thresholds tightening below 0.08% Fe₂O₃.
Glass industry buyers concentrate contract volume; automotive direct procurement expands specification pressure.
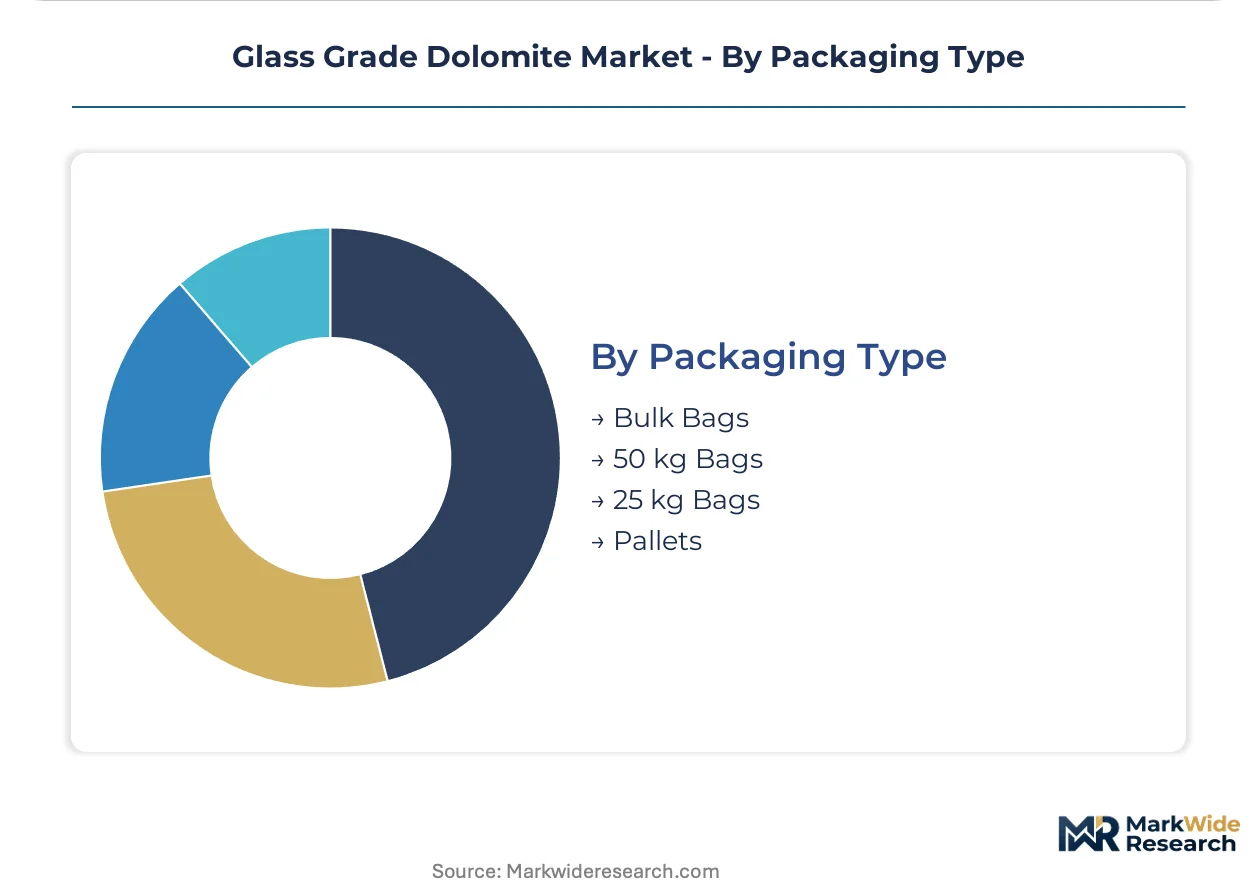
Packaging Type:
Logistics configuration aligns with customer scale, material flow requirements, and contamination risk thresholds.
- Bulk Bags:One-tonne flexible intermediate bulk containers dominate float glass and large container plant intake, minimizing handling stages and dust exposure.
- 50 kg Bags:Standard unit for mid-scale ceramic and specialty glass batch houses requiring controlled addition rates.
- 25 kg Bags:Laboratory and pilot-scale glass melting operations, plus export shipments to markets with limited unloading infrastructure.
- Pallets:Unitized loads for automated batch house systems in premium beverage glass facilities.
Bulk bags lead on tonnage throughput; 50 kg bags retain flexibility across fragmented customer bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as calcination energy costs and compliance burdens diverge across jurisdictions. Producers migrate toward mineral belts with captive quarry-to-furnace integration and favorable emissions frameworks.
Belgium
Float glass supply chains for premium automotive and display applications anchor demand in the Lhoist belt near Namur. REACH dossier maintenance and CE marking requirements impose recurring compliance costs that favor integrated quarry operators with in-house analytical laboratories. The Port of Antwerp cluster handles bulk calcined dolomite exports to Asian float glassmakers seeking EU-certified low-carbon inputs.
India
Domestic float glass capacity expansion near Gujarat and Tamil Nadu mineral belts accelerates local dolomite offtake. BIS certification for industrial minerals tightens beneficiation plant emissions standards, forcing upgrades to magnetic separation infrastructure. The Mundra-Sikka corridor hosts new melting lines commissioning with three-to-five-year supply agreements locked with fixed iron-content bands.
Germany
Container glass lightweighting and recycled cullet ratios above 50% tighten dolomite purity specifications in Bavarian and North Rhine-Westphalia glassworks. The EU F-Gas Regulation phases down hydrofluorocarbons in melting furnaces, accelerating retrofit demand for pre-calcined inputs. The Cologne-Düsseldorf industrial corridor sees beverage glassmakers retrofitting batch houses to handle calcined dolomite with controlled reactivity indices.
Norway
Coastal quarry operations leverage hydropower integration for low-carbon calcination serving premium solar and optical glass segments. ECHA monitoring protocols for barium and strontium trace elements force tier-three supply chain audits. The Nordkalk coastal network sustains supply security for German and Dutch glassmakers through integrated port loading infrastructure.
United States
EPA air quality standards constrain mining permits in Appalachian and Great Lakes mineral districts, compressing merchant processor margins without captive kiln capacity. Henry Hub natural gas price volatility drives fuel cost uncertainty for calcination operations. The Ohio River Valley cluster hosts container glass specialists balancing raw versus pre-calcined input economics amid furnace efficiency mandates.
Glass Grade Dolomite Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated quarry-to-port networks commanding premium glass supply chains while regional processors serve cost-optimized container operations. The vendor base concentrates around three strategic archetypes: integrated multinational mineral houses with captive calcination capacity, mid-tier regional quarry operators with beneficiation upgrades, and specialty chemical processors serving thin-film coating niches. Dominant competitive moves include backward integration into kiln assets to control thermal processing costs, and long-term offtake contracting to lock iron-content bands and preempt certification gaps.
Among European integrated mineral houses, Sibelco and Lhoist Group occupy positions anchored by coastal quarry networks and port logistics infrastructure. Carmeuse exemplifies the vertical integration archetype through captive lime and dolomite calcination assets. Specialty positioning sits with Imerys S.A., representing the ultra-low-iron grade tier targeting optical and solar glass segments where magnesium oxide purity thresholds tighten most aggressively. These three collectively illustrate how chemistry control, energy integration, and certification depth separate premium-tier suppliers from commodity flux providers.
| Leading Market Players |
|---|
| Sibelco |
| Carmeuse |
| Imerys S.A. |
| JFE Mineral & Alloy Company |
| Nordkalk Corporation |
| Lhoist Group |
| RHI Magnesita |
| Arihant MinChem |
| Omya AG |
| Others |
Pricing and Supply Chain Analysis
Family-owned quarry operators across Belgium's Lhoist belt and Norway's coastal districts anchor supply discipline through generational asset stewardship, limiting distressed volume releases that would otherwise erode contract pricing for calcined grades. Their patient capital structure buffers margin pressure from natural gas volatility, sustaining premium positioning against merchant processors.
Pricing Analysis
Direct-to-OEM channels handle hyperscale float glass demand with volume-discounted long-term offtake agreements, while distributor markups of 8-12% persist for mid-tier container plants lacking quarry integration. Three-tier pricing structure across premium, standard, and economy levels separates ultra-low-iron optical grades from automotive-certified batches and cost-optimized construction flux. Cost compression in calcined dolomite is intensifying because European TTF benchmarks swing unpredictably, squeezing merchant kiln operators without captive gas hedging. Container glassmakers in cost-optimized furnace operations exhibit highest price sensitivity; automotive OEM direct procurement shows lowest sensitivity due to certification lock-in.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand through integrated quarry-to-port networks in Belgium, Norway, and India, bypassing distributor layers for premium grade security. Raw material dependencies center on high-purity dolomite reserves, natural gas for calcination energy, and magnetic separation reagents for iron reduction below 0.1% thresholds. Single-source vulnerability concentrates in Belgium's Namur district and Norway's Nordkalk coastal operations, where premium glass-grade deposits face limited geological alternatives. Distribution runs through bulk bag logistics for float glass intake, with 50 kg unit packaging serving fragmented ceramic batch houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
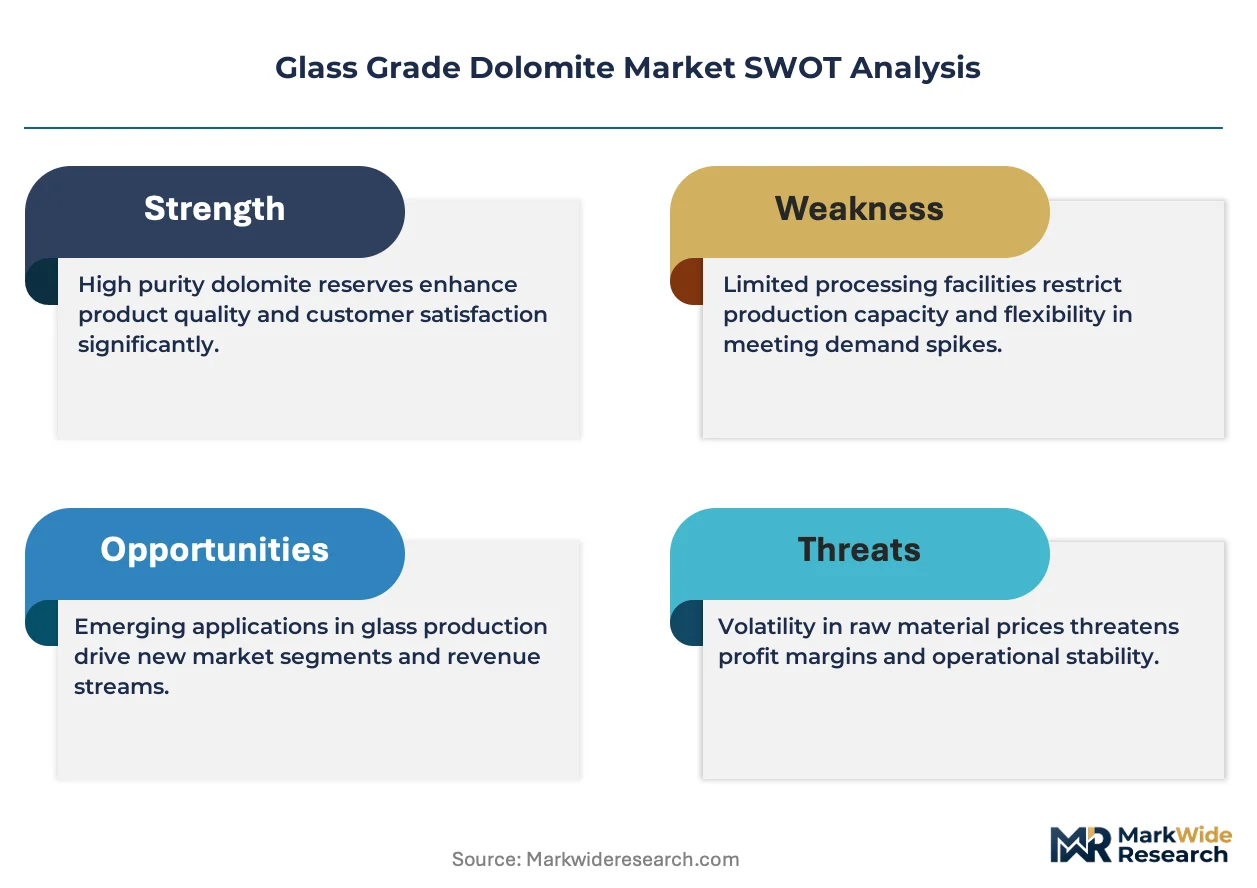
Glass grade dolomite functions as a stable compounder anchored by irreversible specification tightening in automotive and solar glass supply chains. Incumbents and entrants alike must calibrate capital deployment around beneficiation intensity and certification depth.
For Market Incumbents: Acquire magnetic separation and flotation assets to control iron reduction below 0.08% thresholds without third-party tolling exposure. Backward integration into captive kiln capacity defends margin position against Henry Hub and TTF volatility that compresses merchant processor economics. Lock three-to-five-year offtake agreements with fixed chemistry bands to preempt certification gaps from REACH SVHC expansions.
For New Entrants and Emerging Players: Mid-tier container glassmakers in India and Southeast Asia represent the most penetrable buyer archetype, as these operators tolerate 0.12-0.15% iron grades that premium suppliers disdain. Specialty thin-film coating applications for photovoltaic anti-reflective layers offer white-space expansion with nanopowder grades commanding formulation partnerships rather than commodity supply. Pursue toll-processing arrangements with established quarry operators to bypass upfront beneficiation capex while proving grade consistency.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap regional quarry operators with proven reserves but incomplete calcination infrastructure, offering bolt-on kiln investment upside. Long-term viability frames around 5-10 year window of float glass capacity expansion in India and EU carbon border adjustment preference for low-carbon intensity supply chains. Monitor ECHA REACH dossier maintenance costs as inflection indicator for small-scale operator distress that consolidates toward integrated mineral houses.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Calcination | Controls thermal processing costs against natural gas volatility at TTF and Henry Hub benchmarks. |
| Long-term Supply Agreement with Fixed Iron Bands | Locks volume commitment from Indian float glass lines commissioning near Gujarat mineral belts. |
| Beneficiation Plant Upgrade to Sub-0.08% Fe₂O₃ | Qualifies supply for automotive laminated glass specifications requiring ultra-low-iron certification. |
| EU Green Deal Carbon Border Adjustment Positioning | Secures preference for EU-sourced dolomite in premium automotive glass supply chains. |
| Specialty Nanopowder Capacity for Thin-film Coatings | Opens photovoltaic anti-reflective layer applications beyond commodity flux markets. |
Research Methodology
Coverage spans Belgium, Norway, India, Germany, and the United States, with primary inputs from each region's glass manufacturing clusters and mineral processing corridors. The analysis combines primary interviews with plant managers at float and container glassworks, procurement leads at automotive OEM glass divisions, quarry operations directors, and technical R&D directors at mineral beneficiation facilities, validated against secondary sources including customs and trade flow databases, SEC filings from integrated mineral houses, ECHA REACH registration dossiers, and BIS industrial mineral certification records. Bottom-up reserve estimates and top-down consumption modeling triangulate volume figures.
Rate-of-change decomposition separates volume growth from price evolution across product form tiers, application intensity segments, and end-user procurement patterns. The analytical framework models calcined versus uncalcined splits, glass manufacturing versus ceramics versus refractories end-use allocation, and packaging format logistics economics across the projection horizon. CAGRs derive from regression against float glass capacity commissioning schedules, container glass recycled cullet ratio trajectories, and REACH regulatory compliance cost curves.
Underlying measurement precision varies by segment; calcined dolomite volume flows carry tighter precision than emerging nanopowder specialty grades where application development remains fluid. Forecasts reflect assumptions around natural gas price normalization, REACH SVHC list expansion timing, and Indian BIS enforcement intensity that could materially revise projections. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
GCC Flat Glass Market
Glass
Ultra Violet Glass Bottles Market
Glass
Coated Glass Market
Glass
Asia-Pacific Silica Sand Market
Glass
North America Flat Glass Market
Glass
Middle-East and Africa Flat Glass Market
Glass
Tinted Glass Market
Glass
Fiberglass Window Market
Glass
Advanced Glass Market
Glass
Middle East and Africa Glassware Market
Glass
Antiglare Glass Market
Glass
3D Glass Market
Glass
North America Architectural Flat Glass Market
Glass
Cellular Glass Market
Glass
Glass Like Carbon Market
Glass
Foam Glass Granulate Market