
 3D Glass Market | 2026-2036
3D Glass Market Size, Share, and Industry Trends Forecast 2026-2036
3D Glass Market Intelligence
Aftermarket service revenue for cracked 3D glass replacement is reshaping margin distribution across the value chain, pulling profitability downstream from original equipment supply. Corning Incorporated leverages its fusion draw process and Gorilla Glass brand to anchor premium smartphone cover glass supply. AGC Inc. competes through float glass refinement and chemical strengthening scale in Asian display corridors. LENS Technology sustains cost leadership via vertical control over cutting, polishing, and tempering operations in Chinese manufacturing zones.
3D glass denotes thermally or chemically strengthened silicate substrates with non-planar geometries, typically achieving compressive surface layers exceeding 800 MPa through ion-exchange processes to resist impact and flexural stress in consumer electronics housings. Curved 3D glass and edge-to-edge 3D glass dominate current smartphone application volumes where aesthetic differentiation and bezel reduction command OEM priority. Foldable 3D glass represents the fastest-growing product category as ultra-thin glass substrates below 100 micrometers enable repeated bending cycles in next-generation handsets.
FDA guidelines for medical device displays, FCC emissions standards for touchscreen-integrated electronics, and IEC durability testing protocols collectively shape product qualification timelines and barrier-to-entry height for new 3D glass suppliers. China's SAMR enforces GB standards for consumer electronics safety that directly specify glass fracture resistance and shard containment in domestic-market devices. Stakeholders must monitor evolving foldable glass reliability benchmarks and regional certification reciprocity agreements to anticipate which manufacturing bases will capture next-generation display cover orders.
Market Dynamics
Foldable handset proliferation is compressing development cycles for ultra-thin chemically strengthened substrates, forcing glass processors to reconfigure ion-exchange protocols and thermal management systems for substrates below 100 micrometers.
Growth Catalysts
- GB Standards Enforcement:China's SAMR mandates for consumer electronics safety specify glass fracture resistance and shard containment, accelerating domestic qualification of chemically strengthened cover glass for smartphones and wearables.
- Automotive Display Integration:Curved instrument cluster and center console panels in electric vehicles require thermally formed silicate substrates with optical clarity under thermal cycling stress.
- Foldable Form Factor Diffusion:Smartphone OEMs in South Korea and Japan are expanding purchase orders for edge-to-edge cover glass as bending-radius specifications tighten below 3 millimeters.
Market Restraints
- Alumina-Silicate Raw Material Concentration:High-purity glass batch supply clusters in specific Chinese provinces create input cost volatility and single-source vulnerability for finishing operations elsewhere.
- Ion-Exchange Bath Chemistry Limits:Potassium nitrate bath maintenance and potassium ion depletion rates impose throughput ceilings on chemical strengthening lines, constraining unit economics at scale.
- Polycarbonate and Composite Substitution:Molded polymer alternatives with hardcoat surface treatments compete for mid-tier smartphone back panels and wearable housings where impact resistance tolerances permit.
Strategic Opportunities
- Medical Device Display Certification:FDA guidelines for diagnostic touchscreen interfaces create a qualified supplier gap for chemically strengthened glass meeting biocompatibility and sterilization cycle requirements.
- India Manufacturing Incentives:PLI scheme allocations for electronics component production attract glass finishing investments to serve domestic smartphone assembly and export corridors.
- AR/VR Headset Optics Convergence:Waveguide integration with curved protective cover layers demands new substrate geometries combining optical precision with impact resistance in nascent wearable computing platforms.
Industry Challenges
- Thin-Glass Handling Automation:Substrates below 100 micrometers require robotic pick-and-place systems with vacuum gripper arrays that most finishing facilities lack, creating capex barriers for foldable glass qualification.
- IEC 60068-2-32 Drop Test Recertification:Evolving durability protocols for foldable devices extend product validation timelines by 6-12 months, compressing revenue recognition windows against OEM launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Glass Market |
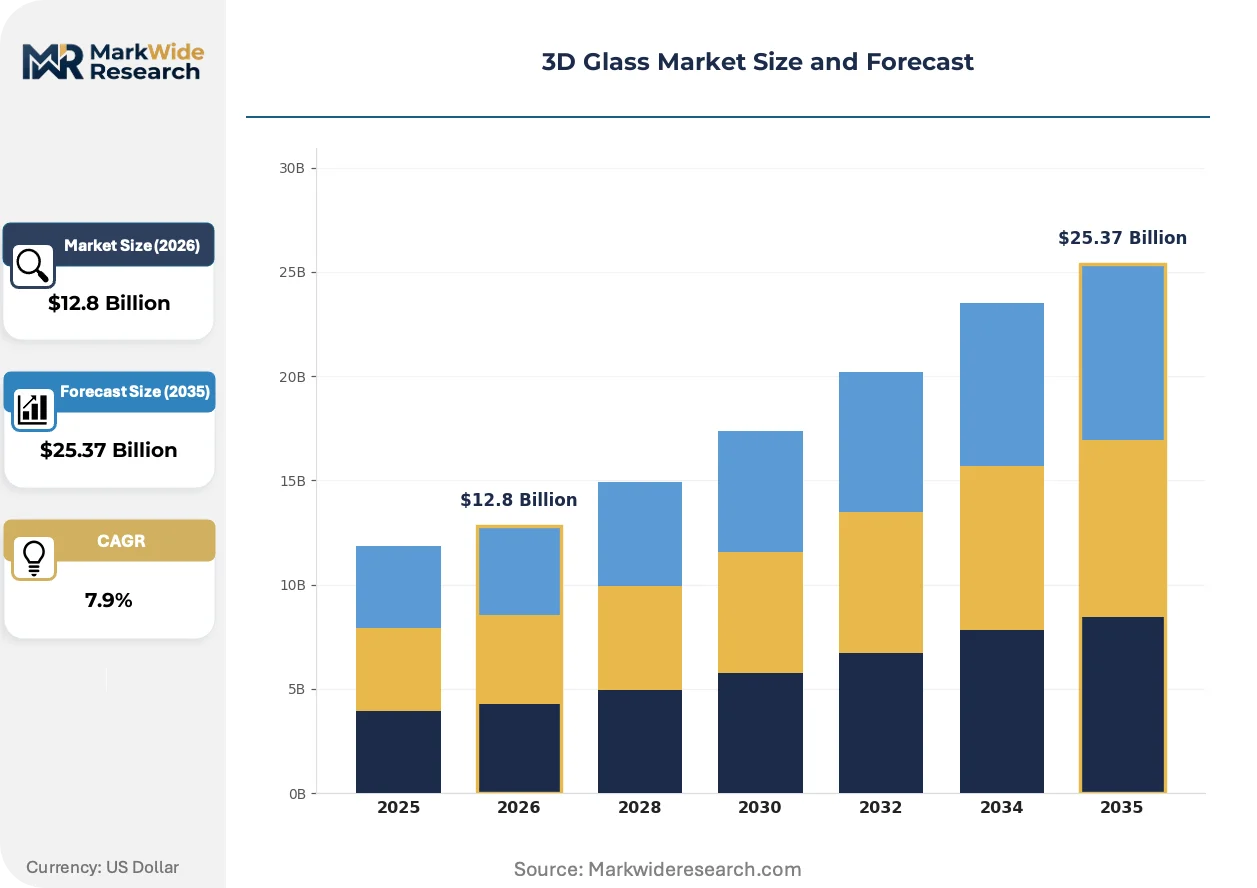
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $25.37 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Curved 3D Glass, Flat 3D Glass, Foldable 3D Glass, Edge-to-Edge 3D Glass, Tempered 3D Glass Technology: Lamination, Nanoimprinting, Chemical Strengthening, Tempering, Optical Coating Application: Smartphones, Wearables, Televisions, Monitor Displays, Gaming Devices, Digital Cameras End User: Electronics Manufacturers, Consumer Electronics OEMs, Display Panel Makers, Assembly Service Providers |
| Companies Covered | Corning Incorporated, AGC Inc., Samsung Corning Advanced Glass, Saint-Gobain S.A., NSG Group, HOYA Corporation, Schott AG, LENS Technology, BYD Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Glass Market Strategic Shifts & Innovations
Manufacturing process convergence and substrate geometry diversification are redefining competitive capabilities in cover glass supply, with chemical strengthening protocols and thermal forming techniques advancing in parallel rather than sequentially.
Ultra-thin flexible glass is hybridizing established float and fusion draw methods with precision grinding and laser cutting to achieve sub-100 micrometer thicknesses capable of 200,000 bending cycles. Samsung Display and domestic Chinese panel houses are qualifying these substrates for inward-folding handset designs launching in 2025-2026 product cycles. This hybridizing of rigid glass heritage with flexible mechanics is compressing the addressable market for polymer-based foldable cover films.
EU F-Gas Regulation phase-down schedules for fluorinated greenhouse gases are pressuring etching and cleaning processes in display glass finishing, where hydrofluorocarbon-based chemistries dominate surface preparation. German and Dutch processing facilities are retrofitting plasma-based dry etching systems to maintain throughput under tightening emission quotas. Mid-tier Asian suppliers without capital reserves for equipment conversion face exclusion from EU-bound automotive display supply chains.
Aftermarket service unbundling is fragmenting historical OEM-captive replacement glass channels as independent repair networks gain access to chemically strengthened cover glass through secondary distributors. North American and European consumer electronics repair shops now source curved smartphone glass directly from Chinese finishing houses, bypassing brand-authorized service programs. This channel disintermediation concentrates margin capture in glass processors with direct-to-repair logistics capabilities rather than handset OEMs.
3D Glass Market Segmentation
3D glass demand fragments across substrate geometry, processing technology, and end-use application, with each dimension commanding distinct qualification protocols and margin structures. Smartphone OEMs drive volume concentration in curved and edge-to-edge formats, while foldable substrates command premium positioning through ultra-thin ion-exchange specialization.
Product Type:
Smartphone housings and automotive displays impose divergent mechanical and optical specifications on thermally formed substrates, creating distinct manufacturing investment profiles.
- Curved 3D Glass:Thermally bent silicate substrates achieving radii of curvature between 2-8 millimeters enable bezel reduction in premium handsets. Samsung and Chinese panel houses in Dongguan and Suzhou concentrate procurement for flagship device launches where aesthetic differentiation commands OEM priority.
- Foldable 3D Glass:Sub-100 micrometer chemically strengthened substrates withstand repeated bending cycles below 3 millimeter radius. South Korean display foundries and domestic Chinese finishing clusters are qualifying these formats for inward-folding handset designs where polymer alternatives face displacement pressure.
- Flat 3D Glass:Planar substrates with edge beveling serve mid-tier smartphone back panels and wearable housings.
- Edge-to-Edge 3D Glass:Continuous curved surfaces eliminating display borders dominate flagship smartphone cover glass specifications.
- Tempered 3D Glass:Thermal shock-treated substrates serve protective applications where chemical strengthening infrastructure is unavailable.
Established volume favors curved formats; emerging adoption favors foldable geometries.
Technology:
Processing method determines compressive layer depth, optical transmission, and throughput economics for display cover qualification.
- Chemical Strengthening:Ion-exchange protocols in molten potassium nitrate baths generate surface compression exceeding 800 MPa through sodium-potassium ion substitution. AGC and Corning operate bath arrays at scale in Asian manufacturing corridors where IEC drop-test mandates tighten baseline performance requirements.
- Optical Coating:Vacuum-deposited anti-reflective and anti-fingerprint layers enhance display readability under ambient lighting. German and Dutch processing facilities are retrofitting plasma-based systems to maintain throughput under EU F-Gas Regulation emission quotas.
- Lamination:Interlayer bonding of glass plies creates composite structures for automotive and architectural applications.
- Nanoimprinting:Roll-to-roll patterning of micro-optical structures enables anti-glare surface textures.
- Tempering:Thermal gradient quenching generates surface compression without ion-exchange chemistry for cost-sensitive applications.
High-volume production concentrates on chemical strengthening; optical coating commands the steepest expansion trajectory in automotive display integration.
Application:
End-use device categories impose distinct impact resistance, optical clarity, and form factor constraints on substrate selection.
- Smartphones:Handset OEMs specify edge-to-edge and foldable cover glass for flagship portfolios where display area maximization drives consumer preference. China's SAMR enforces GB standards for fracture resistance and shard containment in domestic-market devices.
- Wearables:Smartwatch and fitness tracker housings demand sub-1 millimeter thickness with 3D curvature for wrist conformity. LENS Technology maintains cost leadership through vertical control over cutting, polishing, and tempering operations in Chinese manufacturing zones.
- Televisions:Large-format curved panels serve premium home entertainment segments.
- Monitor Displays:Desktop and commercial signage applications utilize flat or gently curved substrates.
- Gaming Devices:Handheld console housings prioritize impact resistance over optical refinement.
- Digital Cameras:Protective cover glass for viewfinder and rear displays requires scratch resistance and minimal optical distortion.
Smartphone procurement anchors current volume; wearable integration is climbing the fastest as health-monitoring device shipments accelerate.
End User:
Supply chain position determines specification authority, qualification timeline, and logistics requirements for glass finishing operations.
- Consumer Electronics OEMs:Apple, Samsung, and Chinese handset brands directly specify cover glass geometry and performance tiers, compressing processor margins through consolidated procurement leverage. Aftermarket service unbundling is fragmenting historical captive replacement channels as independent repair networks gain direct sourcing access.
- Display Panel Makers:Samsung Display, BOE, and domestic Chinese panel houses integrate cover glass with OLED and LCD modules, controlling optical stack specification. These integrators are driving qualification timelines for foldable substrates below 100 micrometers.
- Electronics Manufacturers:Contract assemblers source standardized glass formats for mid-tier device production.
- Assembly Service Providers:Third-party repair networks procure replacement glass through secondary distribution channels.
Procurement authority concentrates with panel makers; margin capture is shifting toward direct-to-repair logistics capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys 3D glass predominantly for smartphone cover integration, while Japan and South Korea concentrate on ultra-thin foldable substrates for next-generation display exports. Germany and the United States diverge toward automotive instrument cluster and medical device display applications respectively.
China
Domestic smartphone OEMs in Dongguan and Suzhou drive procurement for curved edge-to-edge cover glass where SAMR enforces GB standards for fracture resistance and shard containment. The Yangtze River Delta hosts vertically integrated finishing clusters combining fusion draw supply with captive chemical strengthening operations for flagship handset launches.
South Korea
Samsung Display and domestic panel foundries qualify sub-100 micrometer foldable substrates for inward-folding handset designs launching through 2025-2026 product cycles. Seoul Capital Area concentration of ion-exchange processing infrastructure supports ultra-thin glass development under tightening IEC durability protocols for repeated bending cycles.
Japan
Precision optical glass heritage from AGC and HOYA operations in Kansai and Chubu regions translates into medical device display cover qualification under PMDA biocompatibility requirements. METI industrial policy directs substrate innovation toward AR/VR waveguide integration where curved protective layers demand new geometric tolerances.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify curved instrument cluster panels for electric vehicle platforms requiring thermal cycling resistance under EU F-Gas Regulation emission constraints. Dutch and German processing facilities retrofit plasma-based dry etching systems to maintain throughput as fluorinated greenhouse gas phase-down schedules tighten.
United States
FDA guidelines for diagnostic touchscreen interfaces create qualified supplier gaps for chemically strengthened glass meeting sterilization cycle requirements in medical device manufacturing. Corning's fusion draw operations in New York State anchor premium smartphone cover supply while aftermarket repair networks in North America fragment historical OEM-captive replacement channels.
3D Glass Market Key Industry Players
Capability concentration sits with fusion draw specialists commanding premium optical clarity; scale advantage sits with Asian finishing houses integrating chemical strengthening at volume. The market structures around three tiers: heritage glass manufacturers with proprietary draw processes, vertically integrated Chinese processors controlling cutting-to-tempering workflows, and specialized ion-exchange operators serving medical and automotive qualification niches. Dominant competitive moves include backward integration into alumina-silicate batch supply and strategic partnerships with display panel makers for foldable substrate co-development.
Among heritage manufacturers, Corning Incorporated and AGC Inc. exemplify the capability-driven tier through established brand positioning in consumer electronics cover glass. LENS Technology occupies a position within the scale-optimized Chinese processor segment, representing vertical control over finishing operations in Dongguan and Suzhou manufacturing zones. Samsung Corning Advanced Glass anchors the joint-venture archetype, sitting at the intersection of Korean display integration demand and heritage glass process technology.
| Leading Market Players |
|---|
| Corning Incorporated |
| AGC Inc. |
| Samsung Corning Advanced Glass |
| Saint-Gobain S.A. |
| NSG Group |
| HOYA Corporation |
| Schott AG |
| LENS Technology |
| BYD Electronics |
| Others |
Cost & Logistics Intelligence
Yangtze River Delta container freight corridors connecting Dongguan and Suzhou finishing clusters to Shenzhen port terminals transmit alumina-silicate batch cost volatility directly into smartphone cover glass quotations, compressing margins for processors lacking captive raw material supply while amplifying price differentiation between chemically strengthened and thermally tempered tiers.
Pricing Analysis
Long-term offtake contracts between Samsung Display and heritage glass manufacturers anchor premium foldable substrate pricing, while spot-market transactions dominate mid-tier curved glass procurement from Chinese finishing houses. Price differentiation separates IEC-certified chemically strengthened grades from standard tempered alternatives, with certification tier and volume scale as primary drivers. Pricing pressure stems from polycarbonate substitution in wearable back panels, eroding entry-level glass margins. Mid-tier smartphone OEMs exhibit highest price sensitivity; medical device manufacturers show lowest due to FDA qualification barriers.
Supply Chain Analysis
LENS Technology and BYD Electronics concentrate contract-manufacturing capacity across Dongguan, Suzhou, and Shenzhen zones, feeding finished cover glass directly into Samsung Display and BOE module integration lines. High-purity alumina-silicate batch supply clusters in Hunan and Hubei provinces, with potassium nitrate ion-exchange chemistry drawn from domestic chemical processors. Single-source vulnerability in sub-100 micrometer foldable glass substrate supply creates structural risk as South Korean and Chinese panel houses compete for limited qualified finishing capacity. Distribution runs through brand-authorized service networks and secondary direct-to-repair channels serving independent electronics repair shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foldable handset form factor proliferation represents a high-growth disruption reshaping competitive positioning, with IEC 60068-2-32 durability protocol evolution as the regulatory inflection compressing qualification timelines and capital deployment windows.
For Market Incumbents: Entrench proprietary ion-exchange process advantages through backward integration into alumina-silicate batch supply in Hunan corridor processing zones, while accelerating automation capex for sub-100 micrometer handling systems to defend against polymer film substitution in foldable cover applications.
For New Entrants and Emerging Players: Establish a beachhead in medical device display cover qualification where FDA biocompatibility requirements create qualified supplier gaps, targeting diagnostic touchscreen interfaces with sterilization cycle-resistant chemically strengthened substrates as the most penetrable segment.
For Investors and Strategic Acquirers: Specialized ion-exchange operators with medical and automotive certification infrastructure offer prime acquisition targets given long-term viability in premium qualification niches across the analysis window. Monitor foldable glass reliability benchmark revisions as the signal to watch for manufacturing base reallocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina-Silicate Supply | Captive raw material access in Hunan and Hubei provinces insulates processors from batch cost volatility transmitted through Yangtze River Delta logistics. |
| Ion-Exchange Process Automation Scale-Up | Robotic handling systems for sub-100 micrometer substrates unlock foldable glass qualification at South Korean and Chinese panel houses. |
| Medical Device Display Certification Investment | FDA biocompatibility pathway for diagnostic touchscreen interfaces captures premium pricing unavailable in commoditized smartphone tiers. |
| Direct-to-Repair Logistics Capability Buildout | Secondary distribution channel access concentrates margin capture as aftermarket service unbundling fragments OEM-captive replacement glass networks. |
| Plasma-Based Dry Etching System Retrofit | EU F-Gas Regulation compliance maintains German and Dutch facility throughput for automotive display supply chains. |
Research Approach
The analysis maps curved cover glass, foldable ultra-thin substrates, and medical display qualification tiers, each validated through chemical strengthening process engineers, display panel procurement leads, smartphone OEM supply chain managers, and aftermarket repair network operators. Primary interview findings triangulate against customs trade data, SAMR GB standard filings, IEC protocol documentation, and SEC 10-K supply chain disclosures. Bottom-up finishing capacity assessments and top-down OEM procurement volume estimates converge through iterative stakeholder cross-checking.
Assumption sets held foldable handset adoption curves and IEC durability protocol evolution as variable inputs, while fixing alumina-silicate raw material cost baselines and regional regulatory reciprocity frameworks across the projection horizon. Segmentation modeling spans substrate geometry, processing technology, end-use application, and supply chain position dimensions. CAGRs derive from installed base growth rates and replacement cycle compression in smartphone and wearable categories, with ion-exchange bath throughput constraints and thin-glass handling automation penetration as industry-specific forecast inputs.
Sensitivities concentrate around foldable device reliability benchmark revisions, potassium nitrate supply cost movements, and EU F-Gas Regulation enforcement intensity on Asian exporter qualification. Forecasts reflect documented assumptions on OEM procurement consolidation patterns and aftermarket channel fragmentation trajectories. Quarterly review of IEC protocol amendment schedules, SAMR enforcement actions, and panel house capex disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Cellular Glass Market
Glass
Tempered Glass Market
Glass
Silica Sol Market
Glass
Europe Flat Glass Market
Glass
Global Vitrification Market
Glass
Flexible Glass Market
Glass
Low Temperature Laminated Glass Market
Glass
Glass Product Market
Glass
Glass Lined Equipment Market
Glass
China Flat Glass Market
Glass
Global Vacuum Insulated Glass Market
Glass
Optical Glass Market
Glass
North America and Australia Silica Market
Glass
Latin America Flat Glass Market
Glass
Insulating Glass Market
Glass
Double Glazing Glass Market