
 Double Glazing Glass Market | 2026-2036
Double Glazing Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Double Glazing Glass Market Analysis
Window and facade distribution is tilting toward contractor-direct and builder-merchant channels as project-scale procurement consolidates. Saint-Gobain leverages its integrated float-glass-to-fabrication network to control regional supply chains. Guardian Industries anchors North American production capacity with dedicated low-E coating lines. PPG Industries competes through specialized coating chemistry that differentiates thermal performance tiers.
Double glazing glass consists of two parallel glass panes separated by a dehydrated air or inert gas-filled cavity, typically bonded with warm-edge spacers and primary-secondary sealant systems to achieve U-values below 1.0 W/m²K. Low-E glass commands the highest value pool as building codes tighten thermal transmittance limits across temperate climates. Acoustic glass is expanding fastest in urban residential towers where traffic noise regulations intensify. Standard double glazing remains volume-dominant in cost-sensitive retrofit segments where homeowners prioritize payback periods over peak performance.
The EU Green Deal and REACH chemical compliance frameworks mandate phased reductions in embodied carbon and restricted substances across glazing supply chains. The US EPA Energy Star certification and IRA residential efficiency tax credits shape product positioning and market access for imported and domestic units. Stakeholders must monitor evolving national building renovation roadmaps and carbon-border adjustment mechanisms to align capacity investments with regulatory trajectories.
Market Dynamics
The EU Green Deal's building renovation mandates are compressing thermal performance thresholds across residential and commercial retrofit pipelines, forcing fabricators to recalibrate coating chemistry and spacer configurations faster than equipment replacement cycles allow.
Growth Catalysts
- EU Green Deal renovation targets:The framework mandates near-zero energy building stock by 2050, accelerating glazing replacement cycles in Germany, France, and Poland.
- Low-E coating chemistry advances:Sputtered silver-based stacks now achieve U-values below 0.8 W/m²K, opening premium positioning in Nordic residential markets.
- Urban acoustic regulations:Traffic noise limits in London, Milan, and Barcelona are specifying laminated acoustic interlayers as mandatory in new tower construction.
Market Restraints
- Float glass supply concentration:European flat glass production clusters in Belgium, Germany, and Italy, exposing distributors to energy cost pass-through volatility.
- Argon gas price instability:Inert gas filling operations face input cost swings tied to industrial gas supply rationing during winter demand peaks.
- Warm-edge spacer patent thickets:Proprietary thermal break designs from Swiss and German component suppliers create licensing friction for mid-tier fabricators.
Strategic Opportunities
- US IRA residential efficiency tax credits:The Inflation Reduction Act's window replacement incentives create pull-through demand for imported high-performance units in Northeast and Midwest climate zones.
- Vacuum-insulated glass convergence:Hybrid products combining double-glazing fabrication methods with evacuated cavity technology are targeting heritage building retrofits where thickness constraints apply.
- Contractor-direct channel expansion:Large-scale multifamily developers in the Netherlands and Denmark are bypassing merchant intermediaries to secure volume pricing and specification control.
Industry Challenges
- Coating technician scarcity:Magnetron sputtering operation and quality control require specialized training that regional vocational programs have not scaled to match retrofit demand surges.
- REACH substance compliance timelines:ECHA evaluations of sealant chemistry components are forcing reformulation cycles that compress product certification windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Double Glazing Glass Market |
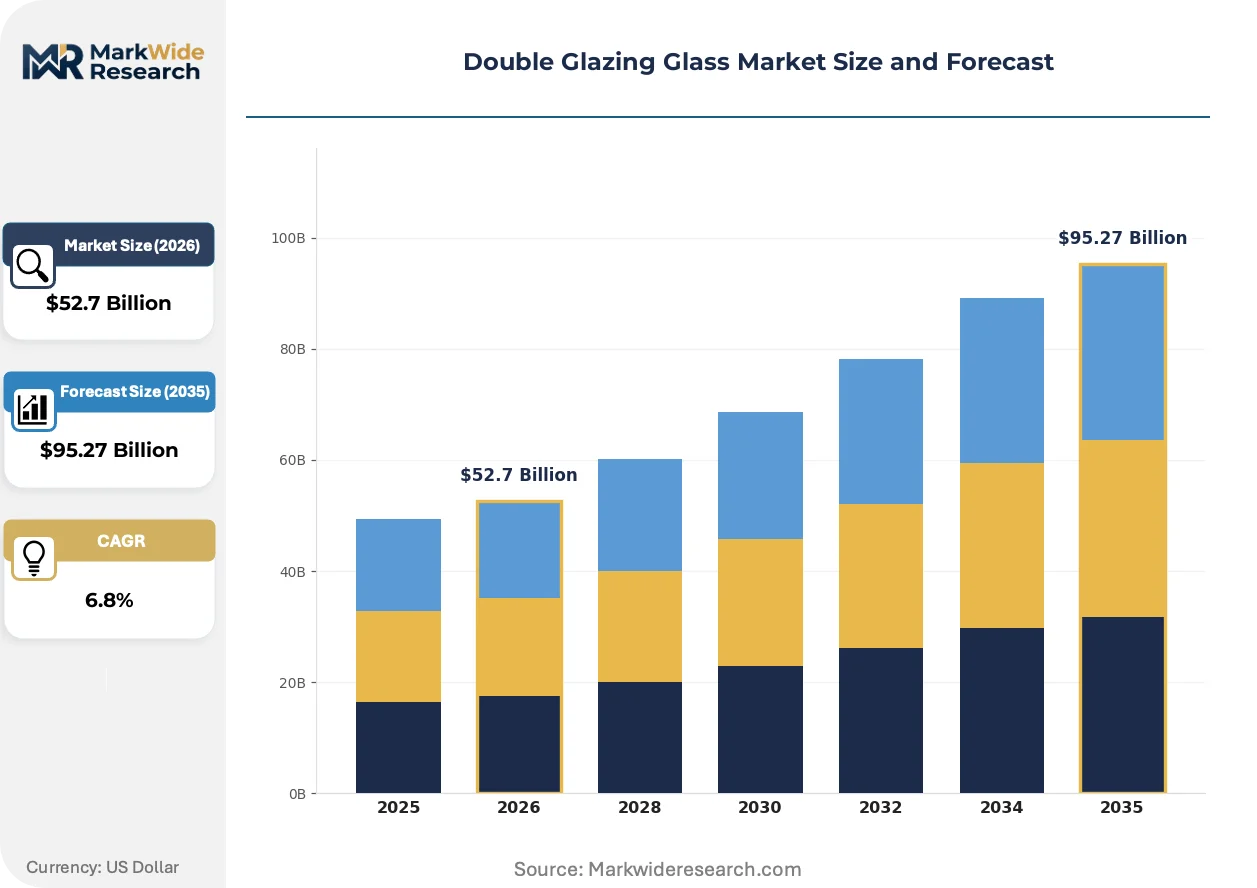
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Double Glazing, Low-E Glass, Acoustic Glass, Obscure Glass Application: Residential Windows, Commercial Facades, Skylights, Conservatories End User: Homeowners, Builders, Architects, Contractors Thickness: 4 mm, 6 mm, 12 mm, 20 mm |
| Companies Covered | PPG Industries, Schott AG, Saint-Gobain, Viracon, Cardinal Glass Industries, AGC Inc., Guardian Industries, Clayton Glass Ltd, NSG Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Double Glazing Glass Market Emerging Trajectories
Coating technology and cavity fill protocols are diverging across climate zones, with fabricators developing region-specific stacks rather than universal product lines. This specialization is fragmenting equipment vendor relationships and recalibrating R&D allocation.
Triple-silver low-E coatings are migrating from commercial curtain wall specifications into high-end residential retrofits. German and Austrian window manufacturers are specifying these stacks for passive house certification compliance. The technology is migrating from premium new construction into volume replacement markets as coating line throughput economics improve.
REACH chemical compliance frameworks are tightening scrutiny of primary sealant polymers and desiccant formulations. ECHA substance evaluations are forcing reformulation of butyl-based sealant systems ahead of sunset dates. Fabricators in France and Italy are accelerating alternative chemistry validation to avoid supply discontinuity.
Builder-merchant procurement consolidation is compressing distributor margins and shifting specification influence toward national retail chains. Large home improvement retailers in the UK and Germany are developing private-label glazing lines with dedicated coating runs. This channel capture is most visible in standard double-glazing segments where brand differentiation is weakest.
Double Glazing Glass Market Segmentation
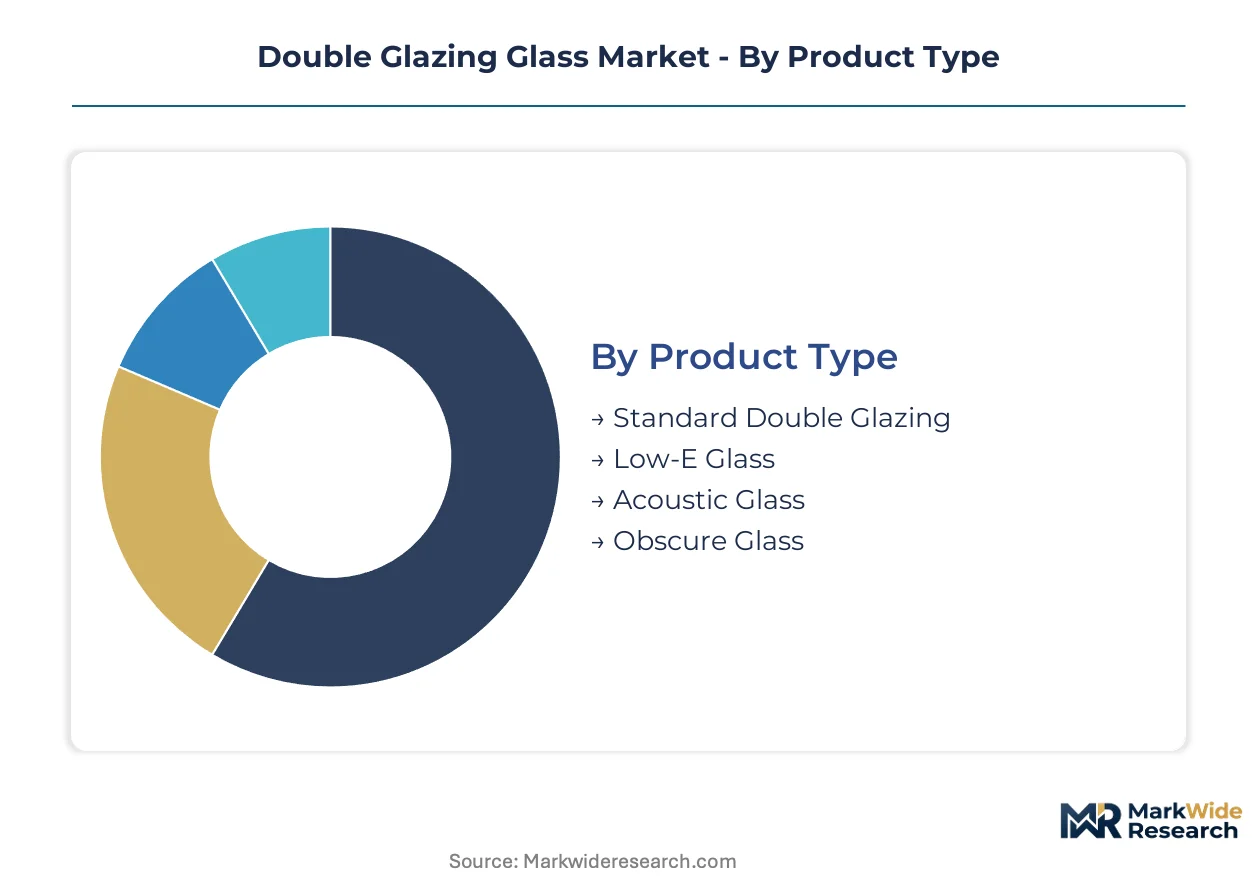
Segmentation in the double glazing glass market reflects divergent thermal performance mandates, acoustic regulations, and installation channel economics. Fabricators calibrate coating chemistry, cavity configurations, and spacer systems to match distinct end-use specifications and renovation timelines.
Product Type:
Mature low-E formulations anchor premium positioning while emerging acoustic and specialty variants capture regulatory-driven niches.
- Low-E Glass:Sputtered silver-based coating stacks achieve U-values below 0.8 W/m²K through multi-layer infrared reflection. German and Austrian passive house certification programs specify these stacks for near-zero energy retrofits, tightening coating uniformity tolerances.
- Acoustic Glass:Laminated interlayers with polyvinyl butyral dampen sound transmission across traffic-heavy frequencies. London, Milan, and Barcelona tower specifications now mandate these configurations for residential units above 60 decibel exposure thresholds.
- Standard Double Glazing:Dehydrated air-filled cavities with aluminum spacers dominate cost-sensitive replacement cycles where homeowner payback periods compress specification flexibility.
- Obscure Glass:Acid-etched or patterned surfaces deliver privacy ratings for bathroom and ground-floor installations without secondary screening.
Standard double glazing retains volume leadership; acoustic glass holds the steepest expansion curve.
Application:
Residential replacement cycles run shorter than commercial facade procurement, creating divergent specification stability and margin profiles.
- Residential Windows:Retrofit demand concentrates in Germany, France, and Poland under EU Green Deal renovation mandates. Homeowners prioritize U-value improvements that qualify for national subsidy programs.
- Commercial Facades:Curtain wall specifications demand triple-silver coatings and structural silicone glazing for thermal bridging control. Nordic markets specify these for BREEAM and LEED certification compliance.
- Skylights:Laminated safety glass with warm-edge spacers addresses condensation risk in pitched roof installations.
- Conservatories:Solar control coatings manage overheating in glazed extensions where seasonal temperature swings stress cavity seal integrity.
Residential windows command the highest unit volume; commercial facades generate the strongest value concentration per square meter.
End User:
Specification authority fragments across decision nodes, with architects controlling early design phases and contractors capturing retrofit procurement.
- Contractors:Direct procurement from fabricators consolidates in Dutch and Danish multifamily development pipelines, bypassing merchant markups for volume pricing leverage.
- Architects:Passive house and nearly-zero energy building specifications in Austria and Germany drive coating stack selection before tender release.
- Homeowners:Cost-sensitive replacement decisions prioritize visible payback periods over peak thermal performance, channeling demand toward standard configurations.
- Builders:Merchant channel relationships determine specification access for small-scale developments where project financing limits inventory holding.
Contractors are gaining procurement share fastest; homeowners remain the volume foundation across replacement markets.
Thickness:
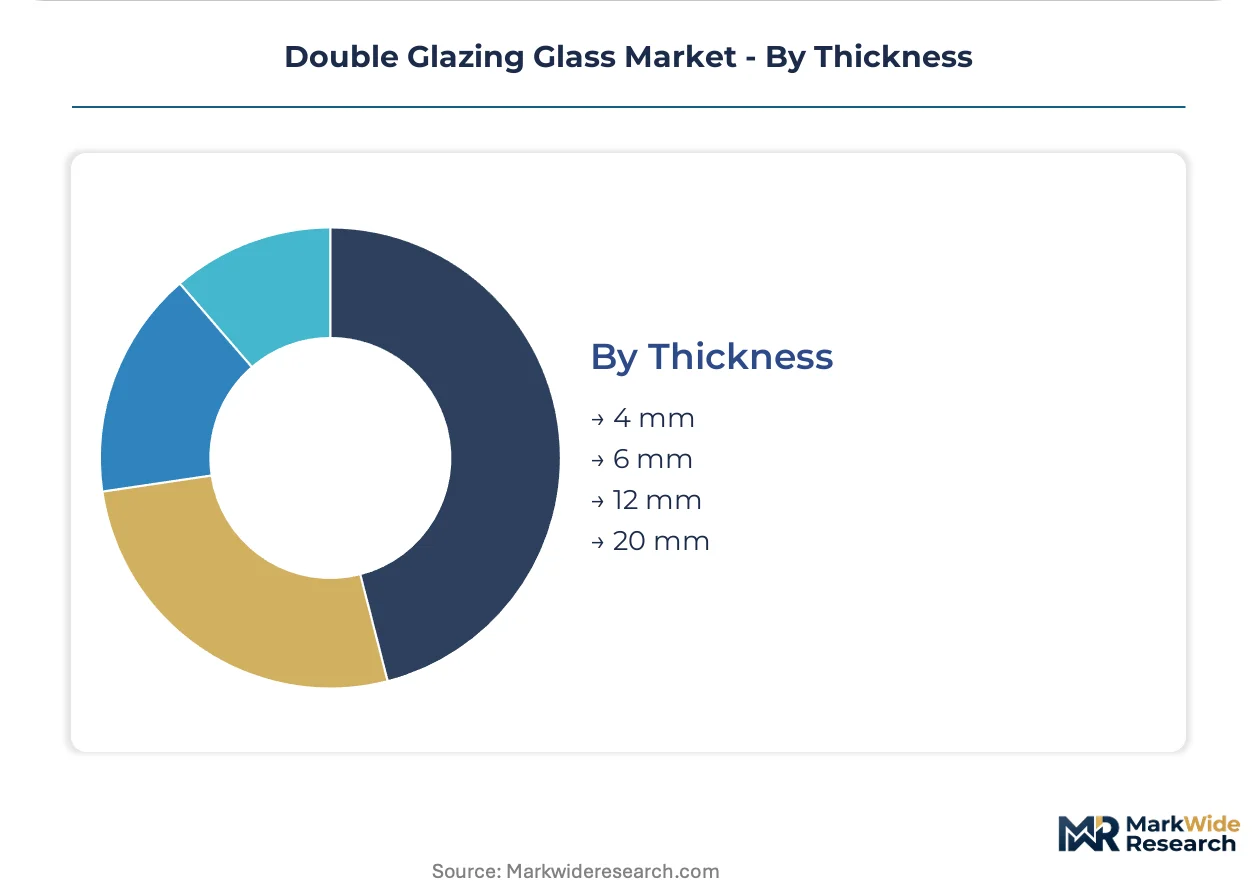
Cavity depth directly correlates with thermal resistance and structural load requirements, fragmenting fabrication line configurations.
- 20 mm:Heritage building retrofits in UK conservation areas specify these slimline cavities where external frame depth restrictions apply, driving vacuum-insulated glass hybrid development.
- 12 mm:Standard residential frames accommodate these cavities with argon fill protocols that achieve U-values near 1.0 W/m²K without triple-glazing cost premiums.
- 6 mm:Secondary glazing applications and slim aluminum profiles use these reduced cavities where structural weight limits constrain frame design.
- 4 mm:Interior partition and non-structural applications specify these minimal configurations where thermal performance is secondary to acoustic separation.
12 mm configurations dominate unit volume; 20 mm specifications are climbing fastest on heritage retrofit demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium pricing power through passive house certification requirements, while Poland absorbs volume demand on thinner margins under EU Green Deal retrofit mandates. This asymmetry shapes cross-border procurement patterns and capacity allocation across Central European fabrication networks.
Germany
Passive house retrofits in Bavaria and Baden-Württemberg specify triple-silver low-E stacks below 0.8 W/m²K. The Federal Ministry for Economic Affairs and Climate Action ties KfW subsidy rates to verified U-value performance. Stuttgart and Munich fabrication clusters run dedicated coating lines for Austrian and Swiss export markets.
France
MaPrimeRénov' grants accelerate window replacement in Île-de-France and Auvergne-Rhône-Alpes. ANAH social housing programs mandate warm-edge spacer configurations in public stock renovations. Lille and Lyon merchant networks consolidate procurement for multifamily developers seeking volume pricing leverage.
United Kingdom
Heritage conservation restrictions in London and Edinburgh drive vacuum-insulated glass hybrid development for 20 mm cavity specifications. The Future Homes Standard tightens thermal transmittance limits for new builds from 2025. Birmingham and Manchester fabricators serve contractor-direct channels bypassing national retailers.
Poland
EU cohesion fund building renovations concentrate demand in Warsaw and Kraków metropolitan areas. Polish Centre for Accreditation certification requirements align with EN 1279 cavity durability standards. Silesian glass processing clusters supply cost-sensitive retrofit segments across Baltic states.
Netherlands
Stimulering Duurzame Energieproductie subsidies drive high-performance glazing in Randstad urban cores. Dutch building decree BENG mandates nearly-zero energy performance for new residential stock. Eindhoven region fabricators serve direct procurement contracts with Danish and Belgian multifamily developers.
Double Glazing Glass Market Vendor Landscape
Integrated float-glass producers and independent coating specialists split the market along capital intensity lines. Three to five multinational chemical-glass conglomerates control upstream raw material supply and magnetron sputtering technology. Regional fabrication specialists dominate downstream customization and logistics-intensive retrofit segments. Capacity expansion and strategic partnerships constitute the dominant competitive moves as fabricators secure argon gas supply contracts and warm-edge spacer licensing agreements.
Among North American coating specialists, PPG Industries and Guardian Industries exemplify the integrated-chemistry archetype through captive low-E stack development. Saint-Gobain occupies a position bridging European float-glass production and facade system integration. These three anchor the premium tier where thermal performance certification and project-scale specification authority concentrate procurement influence.
| Leading Market Players |
|---|
| PPG Industries |
| Schott AG |
| Saint-Gobain |
| Viracon |
| Cardinal Glass Industries |
| AGC Inc. |
| Guardian Industries |
| Clayton Glass Ltd |
| NSG Group |
| Others |
Supply Flow & Price Mechanics
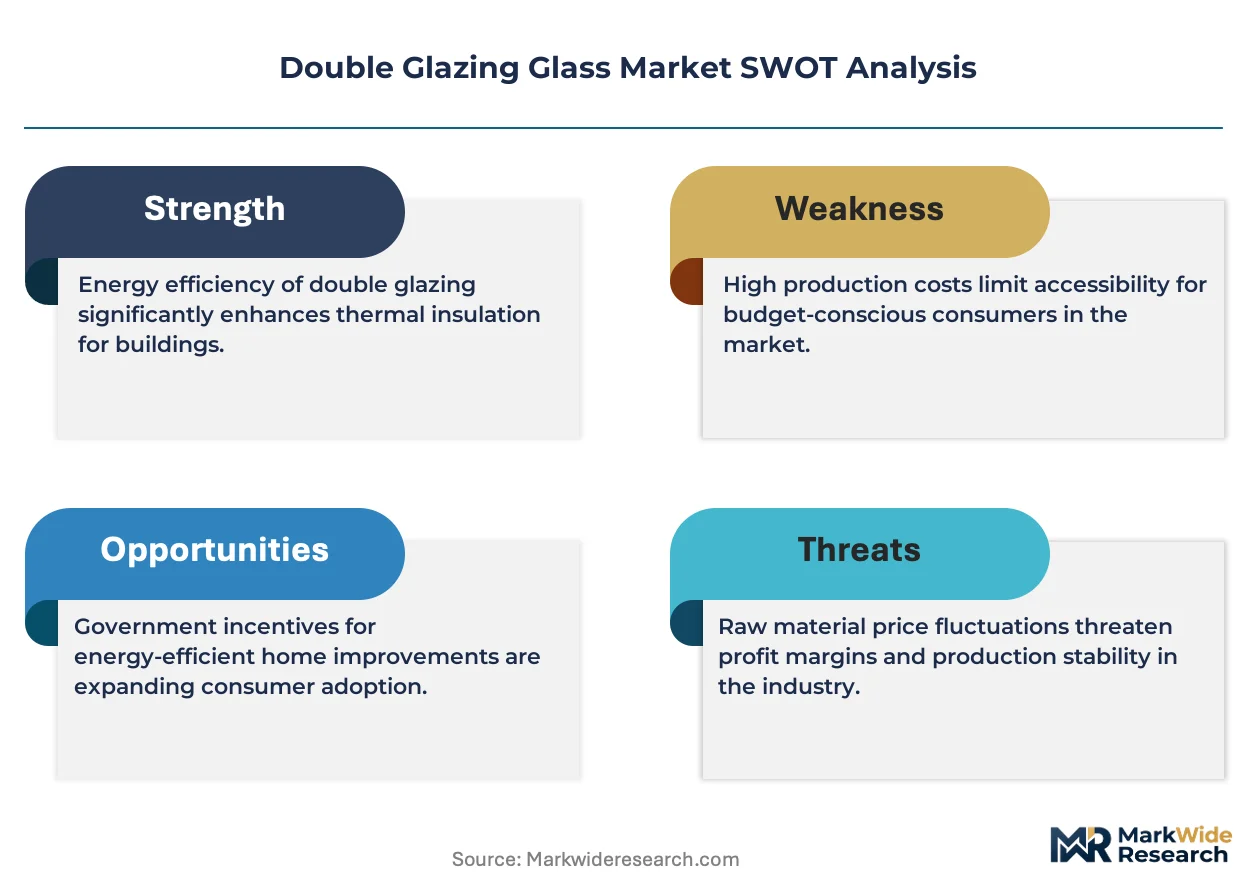
Argon gas price instability determines both pricing tier spreads and supply chain shape in double glazing glass, compressing margins for air-filled standard units while insulating premium inert-gas configurations from cost pass-through volatility. Fabricators calibrate cavity fill protocols and spacer sourcing strategies around industrial gas supply rationing risks during European winter demand peaks.
Pricing Analysis
Configured-to-order pricing for triple-silver low-E stacks with warm-edge spacers commands spreads over standard air-filled double glazing. Three-tier pricing structure across premium, standard, and economy levels segments by U-value performance and certification grade. Cost compression in economy tiers is intensifying because merchant channel consolidation concentrates procurement leverage among national retail chains. Homeowners in cost-sensitive replacement cycles exhibit highest price sensitivity; passive house-certified developers in Germany and Austria show least sensitivity.
Supply Chain Analysis
Float glass contract manufacturing concentrates in Belgium, Germany, and Italy among Saint-Gobain, Guardian Industries, and AGC Inc. capacity networks. Magnetron sputtering equipment and warm-edge spacer components draw from Swiss and German precision engineering clusters. Single-source vulnerability sits with argon and krypton gas suppliers exposed to industrial gas rationing protocols. Distribution runs through contractor-direct channels for multifamily developers and builder-merchant networks for residential retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Double glazing glass sits in early-cycle expansion as EU Green Deal renovation mandates accelerate replacement timelines across residential building stock. Passive house certification penetration in German-speaking markets signals durable premium-tier demand growth.
For Market Incumbents: Pre-empt coating technician scarcity by anchoring regional vocational partnerships in Stuttgart and Eindhoven fabrication clusters. Secure long-term argon supply contracts before winter rationing intensifies. Backward integration into magnetron sputtering equipment maintenance capabilities defends against specialized labor bottlenecks.
For New Entrants and Emerging Players: Pursue vacuum-insulated glass hybrid development for UK heritage retrofit segments where 20 mm cavity constraints block standard double glazing. Target contractor-direct procurement relationships with Dutch and Danish multifamily developers bypassing merchant markups. Lead with acoustic glass specifications for London and Barcelona tower projects facing mandatory traffic noise compliance.
For Investors and Strategic Acquirers: EU Green Deal 2050 near-zero energy building targets reshape the acquisition landscape toward coating specialists with REACH-compliant sealant chemistry pipelines. Five-to-ten-year viability favors regional fabricators with KfW subsidy verification capabilities and warm-edge spacer licensing agreements. Monitor ECHA substance evaluation timelines for butyl-based sealant sunset dates as inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Dedicated low-E coating lines in Poland and Netherlands capture EU cohesion fund retrofit demand. |
| Backward Integration | In-house argon gas storage and filling operations buffer against industrial gas supply rationing volatility. |
| Green Manufacturing Transition | Electrified float glass furnaces align with EU carbon-border adjustment mechanism compliance trajectories. |
| Long-term Supply Agreement | Warm-edge spacer licensing contracts with Swiss component suppliers secure patent-thicket access. |
| Joint Venture | Regional fabrication partnerships with German window manufacturers lock in passive house specification pipelines. |
Methodological Framework
Operator-level perspectives from coating line technicians, window fabricator procurement managers, merchant channel buyers, and KfW subsidy program administrators anchored the qualitative base. Primary fieldwork combined with secondary validation from EN 1279 cavity durability certification records, EU Green Deal building renovation roadmap documents, and ECHA REACH substance evaluation databases. Customs data on flat glass imports and SEC filings from listed glass producers supported volume triangulation through bottom-up and top-down approaches.
Scenario-bracketing framed the analytical approach across the projection horizon, modeling low-E coating chemistry advances against argon gas supply disruption risks. Segmentation dimensions included product type, application, end user, and cavity thickness configuration. CAGRs derived from installed base replacement cycle analysis and national subsidy program uptake curves. Forecast inputs incorporated EN 1279 durability testing protocols and passive house certification penetration rates.
Macroeconomic conditions sit as an overlay; deviation in construction activity indices and industrial gas pricing would shift the trajectory. Forecasts reflect documented assumptions on EU Green Deal implementation pace and REACH compliance timelines. Quarterly review of ECHA substance evaluation progress and national renovation grant disbursement rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Antibacterial Glass Market
Glass
Recycled Glass Market
Glass
Silica Sand for Glass Making Market
Glass
Glass Mason Jars Market
Glass
Global Glassware Market
Glass
North America Glass Insulators Market
Glass
Impact Resistant Glass Market
Glass
Global Glass Flake Coatings Market
Glass
Recycled Glass Aggregates Market
Glass
India Flat Glass Market
Glass
Optical Glass Market
Glass
Insulating Glass Market
Glass
Solar PV Glass Market
Glass
Porous Glass Market
Glass
3D Glass Substrate Market
Glass
Silica Market