
 Tempered Glass Market | 2026-2036
Tempered Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Tempered Glass Market Analysis
Chinese float glass capacity is restructuring toward value-added tempering as energy costs and environmental inspections thin marginal producers. Saint-Gobain leverages integrated float-temper operations across Europe and North America to sustain premium positioning in architectural safety glass. AGC Inc. anchors automotive supply contracts through dedicated tempering lines co-located with OEM assembly plants. Xinyi Glass Holdings competes on furnace scale, operating some of the largest continuous tempering installations serving export markets.
Tempered glass undergoes controlled thermal or chemical treatment to achieve compressive surface stresses typically exceeding 69 MPa, producing fragments with blunt edges upon fracture for occupant protection. Its primary commercial purpose spans architectural glazing, automotive side and rear windows, and consumer electronics displays where mechanical strength and thermal shock resistance prove critical. Flat glass retains the dominant volume share as the feedstock substrate for downstream tempering, though laminated glass commands superior margins in ballistic and hurricane-impact applications. The electronics segment is accelerating fastest as foldable device architectures and cover lens specifications drive ultra-thin chemically strengthened variants.
FDA regulates tempered glass in food-contact applications and medical device viewing ports, while ECE R43 and FMVSS 205 govern automotive glazing performance across European and US markets respectively. China's GB 15763.2 standard mandates tempered glass use in specific building locations, directly shaping domestic demand patterns. Stakeholders must monitor evolving energy efficiency codes and circular economy mandates that could alter furnace economics and recycling infrastructure requirements.
Market Dynamics
Automotive OEMs are expanding tempered glass content per vehicle amid stricter safety mandates like ECE R43 and FMVSS 205, while Chinese float-to-temper conversion lines restructure global supply geography.
Growth Catalysts
- ECE R43 and FMVSS 205 mandates:European and US automotive safety regulations now require enhanced glazing performance, forcing OEMs to specify tempered glass for side and rear windows.
- Foldable electronics architectures:Ultra-thin chemically strengthened variants are capturing display cover lens specifications as device manufacturers pursue mechanical durability at reduced thickness.
- China:Jiangsu and Guangdong provinces host major float-to-temper conversion investments that expand value-added capacity while environmental inspections thin marginal flat glass producers.
Market Restraints
- Natural gas and electricity cost volatility:Tempering furnaces consume substantial thermal energy, and input cost spikes compress margins for non-integrated processors.
- Float glass supply concentration:Chinese producers control upstream substrate capacity, creating dependency risk for tempering operations in Southeast Asia and Eastern Europe.
- Polycarbonate glazing substitution:Weight-sensitive automotive segments are specifying transparent polymers for non-vision areas, displacing some tempered glass volume.
Strategic Opportunities
- India building codes:BIS standards adoption and urban infrastructure investment are expanding safety glass requirements in commercial and residential construction.
- Photovoltaic module integration:Tempered solar glass is capturing bifacial panel specifications as PV manufacturers optimize mechanical load tolerance and thermal cycling resistance.
- Circular economy mandates:EU Green Deal recycling infrastructure requirements are creating first-mover advantage for tempering operations with captive cullet processing capabilities.
Industry Challenges
- Thermal process engineering expertise:Furnace optimization for ultra-thin electronics substrates requires specialized skill sets that outpace current vocational training pipelines.
- Multi-standard certification timelines:Simultaneous compliance with ECE R43, FMVSS 205, and GB 15763.2 extends product qualification cycles for automotive export programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tempered Glass Market |
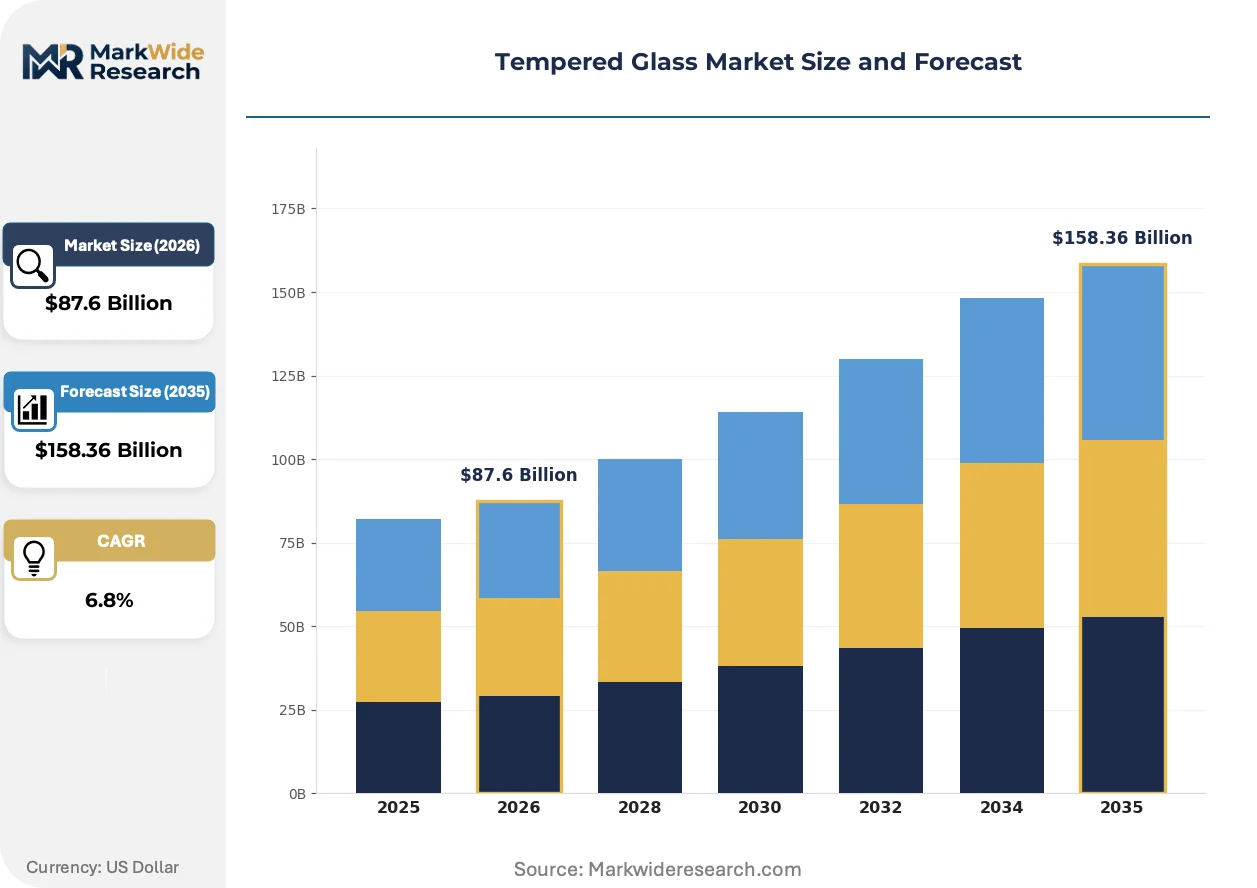
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Glass, Laminated Glass, Bulletproof Glass, Coated Glass Application: Automotive, Construction, Furniture, Electronics End User: Residential, Commercial, Industrial, Retail Distribution Channel: Direct Sales, Online Retail, Wholesale, Distributors |
| Companies Covered | Saint-Gobain, AGC Inc., Guardian Industries, Nippon Sheet Glass, Asahi Glass, Corning Incorporated, Xinyi Glass Holdings, Fuyao Glass Industry Group, Taiwan Glass Industry Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tempered Glass Market Emerging Trajectories
Chemical strengthening processes are overtaking thermal tempering in premium electronics applications, while regulatory stringency tightens across automotive and architectural end-uses.
Ultra-thin ion-exchange strengthening is overtaking conventional thermal tempering for foldable smartphone cover lenses. Device manufacturers specify chemically strengthened variants below 0.5mm thickness to enable bending radii under 5mm. This technology is overtaking legacy thermal processes in the premium display segment, compressing equipment investment cycles for dedicated electronics tempering lines.
EU Green Deal circular economy mandates are reshaping furnace economics across European tempering operations. The framework requires documented cullet recycling rates and embodied carbon disclosures for construction products. Architectural glass processors in Germany and France are responding by retrofitting batch plants with oxy-fuel combustion and electric boosting to meet CSRD reporting thresholds.
Automotive OEMs are consolidating glazing procurement through platform-level supply agreements rather than discrete component sourcing. Tier-1 suppliers are absorbing tempering capacity into module assembly operations co-located with vehicle plants. This pattern is most visible in China, where BYD and Tesla Shanghai specify direct-to-line tempered glass delivery to minimize logistics handling and quality variance.
Tempered Glass Market Segmentation
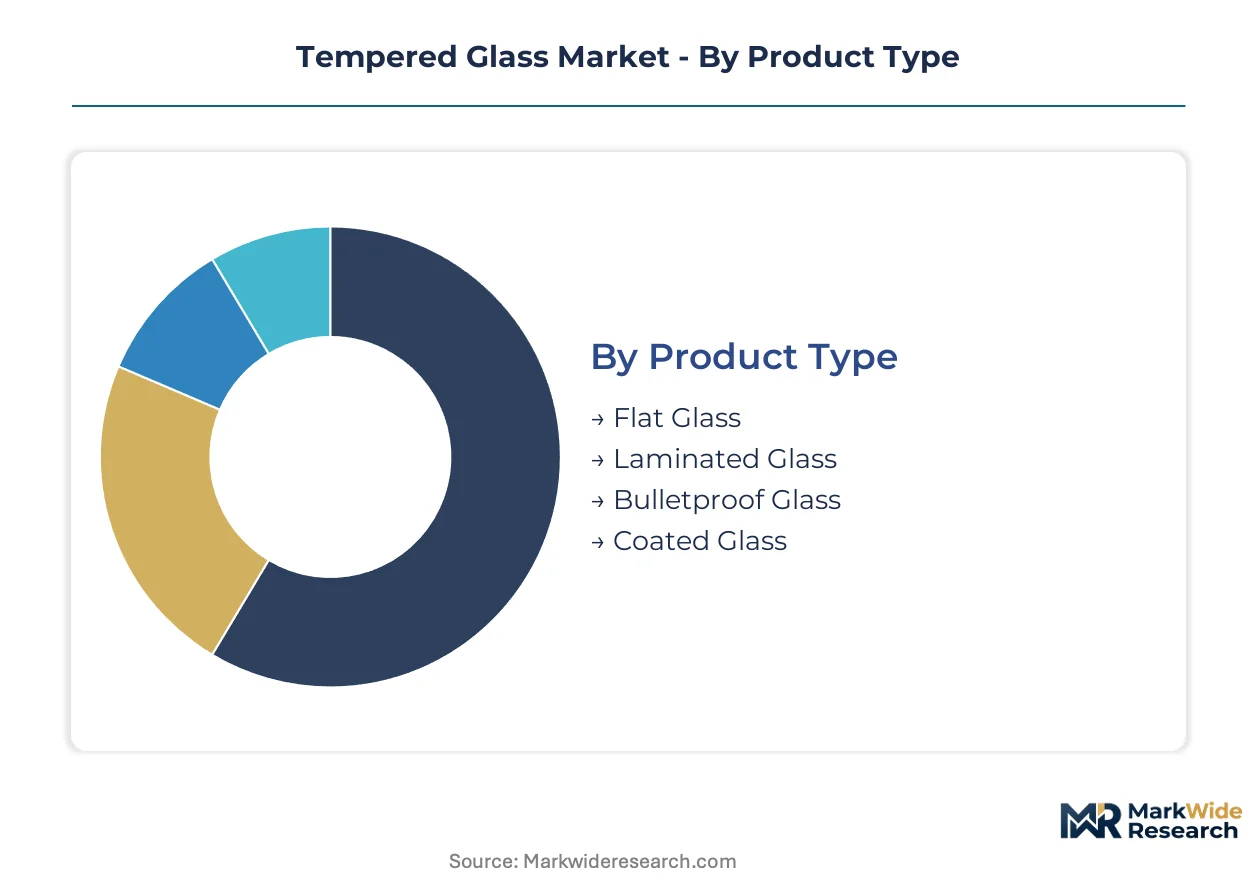
Tempered glass serves both standalone structural applications and embedded component systems, with segmentation revealing where value concentrates versus where volume flows. Understanding these splits exposes margin architecture and capital allocation priorities across the value chain.
Product Type:
Integration depth varies sharply: flat and laminated glass operate as standalone building envelope or vehicle glazing systems, while bulletproof and coated variants embed into larger security or energy-management assemblies.
- Flat Glass:Serves as the foundational substrate for downstream thermal tempering, with compressive surface stresses exceeding 69 MPa achieved through controlled heating and rapid air quenching. Construction activity in Jiangsu and Guangdong provinces drives concentrated demand as Chinese building codes mandate tempered flat glass for high-traffic architectural locations. Energy cost volatility and environmental inspections are thinning marginal float-to-temper conversion lines.
- Laminated Glass:Combines tempered glass layers with polyvinyl butyral interlayers to deliver post-breakage retention and acoustic dampening. Automotive OEMs specify laminated configurations for windshields under ECE R43 and FMVSS 205, while hurricane-impact building codes in Florida and Gulf Coast states expand architectural specifications. Premium pricing over monolithic tempered alternatives reflects ballistic certification requirements and specialized autoclave processing.
- Bulletproof Glass:Multi-layer laminated assemblies with polycarbonate or glass-clad polycarbonate cores meeting NIJ and EN 1063 ballistic standards. Banks, embassies, and VIP vehicle programs constitute primary demand.
- Coated Glass:Low-emissivity and solar-control coatings applied post-tempering to manage thermal radiation in building envelopes. LEED certification pursuit and EU Green Deal embodied carbon thresholds accelerate specification.
Flat glass leads volumes today; coated glass is gaining share fastest as energy codes tighten across major construction markets.
Application:
Cost tier segmentation separates capital-intensive automotive and electronics specifications from price-sensitive furniture and commodity construction procurement.
- Automotive:Side and rear window tempering dominates OEM glazing spend, with ECE R43 and FMVSS 205 mandating fragment characteristics upon fracture for occupant protection. BYD and Tesla Shanghai specify direct-to-line tempered glass delivery to minimize handling variance. Platform-level supply agreements are consolidating procurement through Tier-1 module assemblers co-located with vehicle plants.
- Construction:Architectural safety glazing spans curtain walls, skylights, and interior partitions under GB 15763.2, IBC, and regional energy codes. Commercial high-rise and institutional projects specify tempered glass for mechanical strength and thermal shock resistance in climate-variable envelopes.
- Furniture:Tabletops, shelving, and display cases utilize thinner tempered variants where edge quality and moderate impact resistance suffice. Retail fixture manufacturers prioritize cost over certification depth.
- Electronics:Ultra-thin chemically strengthened variants below 0.5mm enable foldable smartphone bending radii under 5mm, displacing legacy thermal tempering in premium display cover lenses. Ion-exchange processing requires specialized furnace engineering expertise that outpaces vocational training pipelines.
Construction leads volumes today; electronics is climbing the fastest as foldable device architectures multiply cover lens specifications.
End User:
Customer type segmentation distinguishes project-driven commercial and industrial procurement from fragmented residential and retail demand patterns.
- Residential:Single-family and multi-family construction specify tempered glass for shower enclosures, balcony railings, and code-mandated safety locations. Home improvement retailers and contractor networks handle distribution.
- Commercial:Office towers, hospitality, and healthcare facilities drive large-format tempered glass demand through specification-grade procurement. Facilities managers prioritize lifecycle durability and warranty coverage over first cost.
- Industrial:Manufacturing facilities, cleanrooms, and process equipment viewing ports require tempered glass for thermal shock resistance and chemical compatibility. FDA regulates food-contact and medical device applications.
- Retail:Storefront systems, display cases, and fixture programs utilize tempered glass where breakage containment and visual clarity intersect. Rollout schedules and national account pricing dominate procurement logic.
Commercial leads volumes today; industrial is expanding most quickly as manufacturing reshoring and cleanroom investment accelerate.
Distribution Channel:
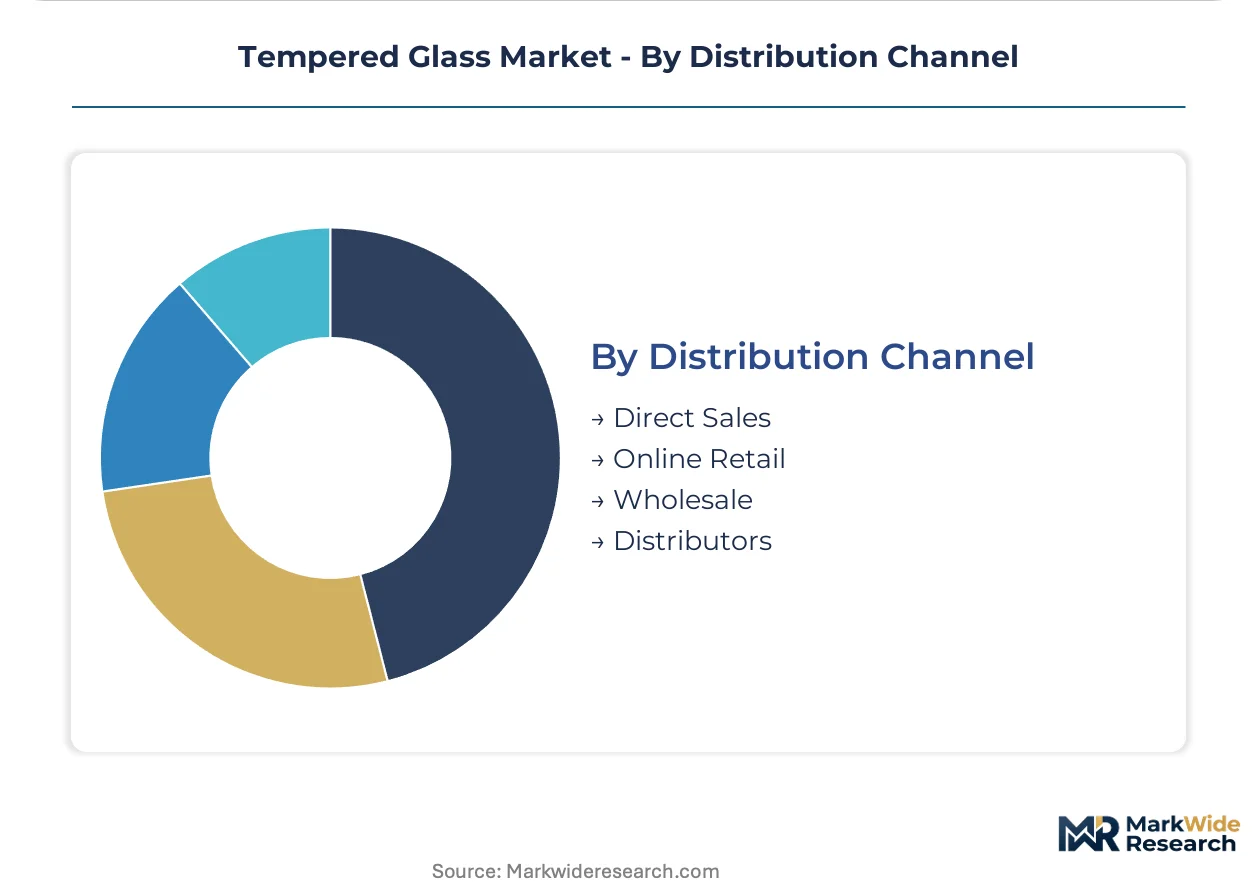
Supply concentration shapes channel economics: direct sales capture automotive and large commercial projects, while wholesale and distributors fragment construction and retail supply.
- Direct Sales:OEM automotive programs and major commercial projects negotiate directly with integrated float-temper operations. Saint-Gobain and AGC Inc. maintain dedicated account teams for platform-level supply agreements.
- Online Retail:Standardized dimensions and consumer-grade specifications migrate to digital procurement for residential replacement and small contractor orders. Logistics constraints limit large-format tempered glass e-commerce penetration.
- Wholesale:Regional glass distributors stock common thicknesses and sizes for construction trade customers. Inventory carrying costs and breakage risk compress margins for non-integrated wholesalers.
- Distributors:Specialized architectural and automotive glazing distributors provide fabrication, certification documentation, and just-in-time delivery. Technical support capabilities differentiate premium distributors.
Direct sales leads volumes today; online retail is gaining share fastest among standardized residential and small commercial specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward jurisdictions where energy costs and environmental compliance burdens create arbitrage opportunities for tempering operations. Chinese provinces with subsidized natural gas and streamlined permitting attract float-to-temper conversion investments. European and North American facilities absorb higher compliance costs through premium positioning and captive OEM relationships.
China
Jiangsu and Guangdong provinces concentrate new float-to-temper capacity as provincial governments offer energy subsidies for value-added glass processing. GB 15763.2 mandates tempered glass in specific building locations, directly stimulating domestic demand. Suzhou and Foshan industrial clusters host the largest continuous tempering installations serving export markets.
United States
Automotive OEMs in Michigan and Tennessee specify tempered glass under FMVSS 205 for side and rear window applications. NHTSA enforces fragment characteristics upon fracture for occupant protection. Southeast manufacturing corridors attract tempering operations co-located with vehicle assembly plants to minimize logistics handling.
Germany
EU Green Deal circular economy mandates reshape furnace economics across Bavaria and North Rhine-Westphalia. CSRD reporting thresholds require documented cullet recycling rates and embodied carbon disclosures. Stuttgart and Munich industrial zones retrofit batch plants with oxy-fuel combustion to meet energy efficiency codes.
India
BIS standards adoption and urban infrastructure investment expand safety glass requirements in Maharashtra and Gujarat. The national building code mandates tempered glass for high-traffic commercial locations. Mumbai and Ahmedabad construction markets drive specification-grade procurement for curtain wall and skylight applications.
Japan
METI promotes advanced materials processing in Kansai and Chubu regions through technology licensing programs. JIS standards govern mechanical strength and thermal shock resistance specifications. Osaka and Nagoya industrial clusters specialize in ultra-thin chemically strengthened variants for electronics cover lens applications.
Tempered Glass Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty electronics and photovoltaic glass segments. Market structure consolidates around integrated float-temper operations with captive substrate supply, while independent processors compete on furnace scale and regional logistics. Three archetypes dominate: multinational integrated glass groups, Asian scale-driven specialists, and electronics-focused chemical strengthening pioneers. Capacity expansion and backward integration into float glass supply represent the dominant competitive moves.
Among multinational integrated groups, Saint-Gobain and AGC Inc. exemplify the premium-tier positioning through co-located tempering and OEM supply agreements. Xinyi Glass Holdings anchors the scale-driven archetype with furnace installations serving export markets. These three entities represent distinct strategic postures: European-North American integrated operations, Japanese automotive supply specialization, and Chinese volume-focused capacity leadership.
| Leading Market Players |
|---|
| Saint-Gobain |
| AGC Inc. |
| Guardian Industries |
| Nippon Sheet Glass |
| Asahi Glass |
| Corning Incorporated |
| Xinyi Glass Holdings |
| Fuyao Glass Industry Group |
| Taiwan Glass Industry Corporation |
| Others |
Supply Flow & Price Mechanics
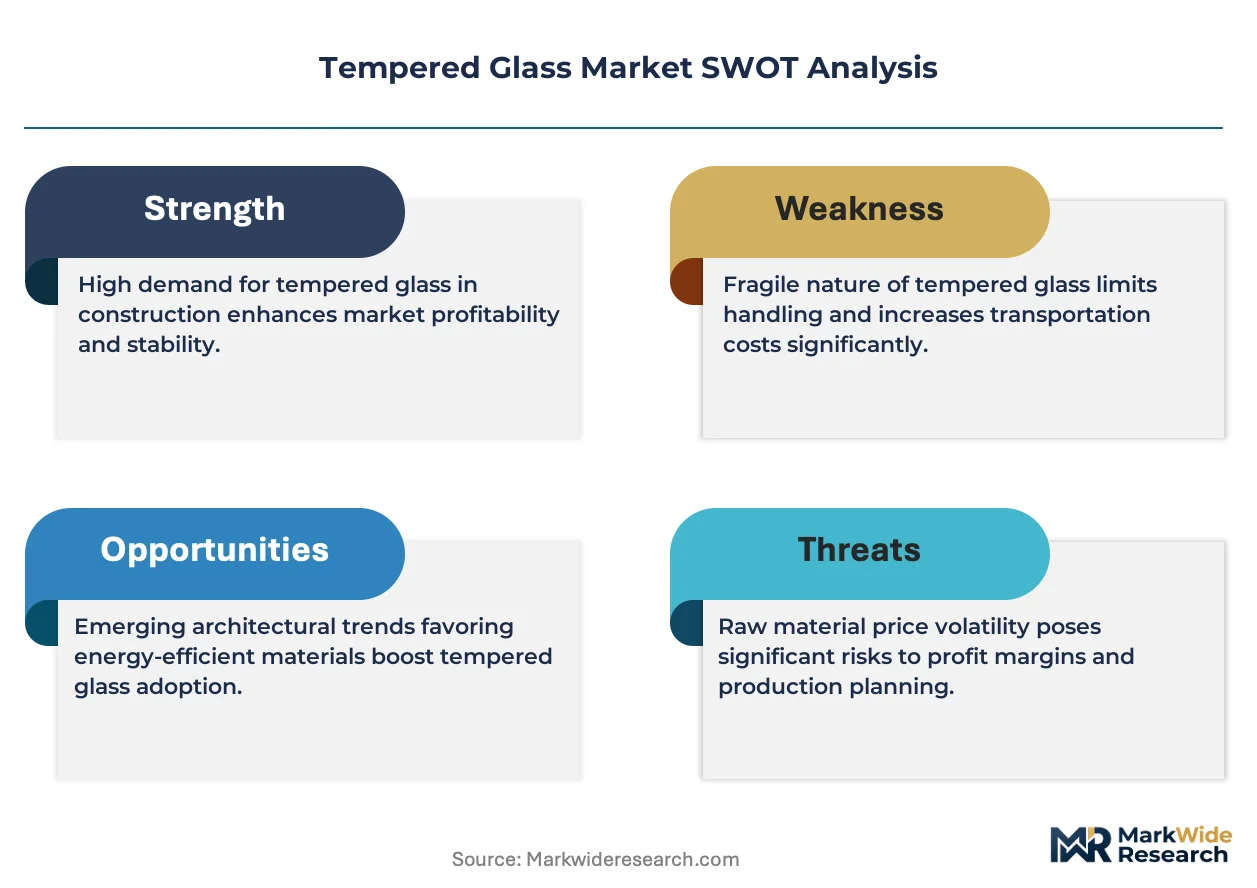
Thermal process engineering expertise concentrated in Kansai and Chubu regions feeds labor-cost differentials that widen pricing-tier spreads between premium electronics-grade and commodity architectural tempering.
Pricing Analysis
Distributor margin compression in wholesale channels contrasts with direct-to-OEM contract structures that embed volume rebates and technical service bundling. Three-tier pricing structure across premium, standard, and economy levels separates ion-exchange strengthened electronics substrates from thermal-tempered automotive glazing and commodity construction flat glass. Price differentiation hinges on certification depth—ECE R43 and FMVSS 205 automotive tiers command premiums over GB 15763.2 architectural compliance alone. Cost compression in standard-grade construction tempering is intensifying because Chinese float-to-temper conversion lines expand capacity. Residential replacement buyers exhibit highest price sensitivity; automotive OEM platform agreements show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Chinese float glass substrate supply that feeds downstream tempering operations across Southeast Asia and Eastern Europe. Geographic supply concentration centers on China, Germany, and the United States for integrated float-temper operations. Raw material dependencies rest on soda ash, natural gas for furnace combustion, and specialized ceramic rollers for continuous tempering lines. Tariff exposure on Chinese float glass imports threatens margin structures for non-integrated processors in North America and Europe. Distribution runs through direct sales for automotive OEM programs, specialized architectural distributors for commercial construction, and wholesale networks for residential trade customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where energy cost differentials between EU Green Deal compliance zones and Chinese provincial subsidy jurisdictions create furnace economics spreads of 15-25%.
For Market Incumbents: Cement captive cullet processing capabilities to capture EU circular economy mandate advantages before CSRD reporting thresholds harden. Absorb tempering capacity into module assembly operations co-located with OEM vehicle plants to defend against polycarbonate glazing substitution in weight-sensitive automotive segments. Prioritize oxy-fuel combustion retrofits in European facilities to offset natural gas cost volatility. For New Entrants and Emerging Players: E-commerce procurement platforms for standardized residential replacement glass offer lowest barrier-to-entry routes into fragmented construction supply. Target India's Maharashtra and Gujarat building code expansion zones where BIS standards adoption outpaces local tempering capacity. Pursue photovoltaic module glass specifications as bifacial panel architectures multiply tempered solar glass demand. For Investors and Strategic Acquirers: Integrated automotive Tier-1 suppliers are the most active acquirer in this space, seeking captive tempering capacity for platform-level supply agreements. Five-to-ten year viability favors processors with backward integration into float glass supply or forward integration into OEM co-location. Watch foldable electronics cover lens specification volumes as inflection indicator for ion-exchange strengthening equipment investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Float Glass Supply | Captive substrate access insulates margin compression from Chinese supply concentration risks. |
| Oxy-Fuel Combustion Retrofit | CSRD reporting thresholds in Germany and France favor low-carbon furnace technology adoption. |
| OEM Co-Location Partnership | Tesla Shanghai and BYD specifications reward direct-to-line tempered glass delivery models. |
| Ion-Exchange Equipment Investment | Foldable smartphone architectures below 0.5mm thickness displace thermal tempering in premium displays. |
| Cullet Processing Capability Buildout | EU Green Deal recycling mandates create first-mover advantage for documented circular economy compliance. |
Methodological Framework
Multiple input streams — technical interviews with furnace engineering specialists, procurement discussions with automotive Tier-1 supply managers, and regulatory tracking across ECE, FMVSS, and GB standard bodies — were reconciled against customs trade data, SEC filings from integrated glass groups, and national building code adoption records. Primary fieldwork engaged plant managers at float-to-temper conversion facilities, architectural specification consultants, and electronics display cover lens procurement leads. Secondary validation drew from energy consumption disclosures, environmental inspection reports, and OEM platform engineering documentation. Bottom-up capacity modeling and top-down demand segmentation were triangulated to constrain estimate variance.
Data-stream reconciliation across product type, application, end user, and distribution channel dimensions shaped the analytical framework over the projection horizon. Segmentation modeling captured flat versus laminated versus chemically strengthened variants, automotive OEM versus construction project versus electronics display demand patterns, and direct sales versus wholesale channel economics. CAGRs were derived from installed capacity expansion schedules, building code mandate timelines, and vehicle content-per-unit trajectories. Forecast inputs incorporated natural gas price scenario bands, environmental compliance cost curves, and foldable device penetration assumptions for ultra-thin glass specifications.
The model assumes a particular technology adoption path; alternative pathways for chemical strengthening displacing thermal tempering in mid-tier electronics would alter the outlook. Forecasts reflect assumptions about ECE R43 and FMVSS 205 enforcement consistency, Chinese environmental inspection stringency, and polycarbonate glazing substitution ceilings. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Dynamic Glazing Market
Glass
Glass Block Market
Glass
United States Flat Glass Market
Glass
Coated Solar Control Glass Market
Glass
Asia-Pacific Silica Sand Market
Glass
Middle-East and Africa Flat Glass Market
Glass
Asia-Pacific Glassware Market
Glass
Solar PV Glass Market
Glass
Glass Lens Market
Glass
Recycled Glass Market
Glass
North America and Australia Silica Market
Glass
Global Glassware Market
Glass
Insulated Glass Market
Glass
Europe Glass Insulators Market
Glass
3D Glass Market
Glass
Birefringent Crystals Market