
 Cellular Glass Market | 2026-2036
Cellular Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Cellular Glass Market Intelligence
Mineral wool is restructuring competitive economics in rigid insulation as thermal performance standards tighten across commercial construction. Owens Corning leverages its fiberglass heritage to anchor North American distribution channels for high-performance cellular glass systems. Glapor Werk Mitterteich GmbH dominates European manufacturing scale through captive supply of recycled glass feedstock. Zhejiang Zhenshen Insulation Technology Corp. Ltd. competes on cost-engineered blocks tailored to Chinese infrastructure specifications.
Cellular glass comprises a rigid foam material manufactured from crushed glass, carbon, and foaming agents, yielding a non-combustible structure with closed-cell porosity below 0.05 W/m·K thermal conductivity, primarily deployed for cryogenic and high-temperature industrial insulation. Closed-cell products sustain premium positioning in hydrocarbon processing and LNG infrastructure where moisture resistance commands price premiums. Thermal insulation applications lead volume consumption across the analysis window, while acoustic insulation segments in rail and aerospace exhibit faster expansion from stricter transit noise mandates. Blocks occupy the dominant form factor in heavy industrial settings, whereas panels penetrate commercial building retrofits where installation speed determines contractor selection.
REACH compliance in Europe and EPA industrial emissions frameworks in the United States constrain formaldehyde-containing alternatives, redirecting specification toward inorganic cellular glass systems. China's GB standards for building energy efficiency and the EU Green Deal renovation wave mandate thermal performance upgrades that expand addressable demand for non-combustible insulation materials. Stakeholders must monitor regulatory divergence between carbon-border adjustment mechanisms and domestic content incentives to calibrate regional manufacturing footprints and certification investments.
Market Dynamics
Closed-cell cellular glass formulations with sub-0.05 W/m·K thermal conductivity are displacing mineral wool in cryogenic LNG infrastructure as moisture resistance commands specification premiums in hydrocarbon processing.
Growth Catalysts
- EU Green Deal renovation wave:Mandatory thermal performance upgrades across Germany, France, and Italy expand addressable demand for non-combustible insulation in commercial building retrofits.
- GB standards tightening:China's building energy efficiency mandates accelerate specification of cellular glass blocks in district heating networks and cold-chain logistics facilities.
- LNG infrastructure buildout:Cryogenic storage terminals in the United States and Qatar specify cellular glass systems for boil-off gas containment and pipeline insulation.
Market Restraints
- Recycled glass feedstock concentration:European manufacturing depends on captive supply from Glapor Werk Mitterteich GmbH's integrated recycling operations, creating geographic supply risk.
- Formaldehyde-free alternatives cost premium:REACH-compliant cellular glass commands 15-25% price elevation versus phenolic foam in budget-constrained municipal infrastructure projects.
- Aerogel substitution threat:Silica aerogel blankets penetrate aerospace and rail acoustic insulation where weight minimization overrides fire-performance specifications.
Strategic Opportunities
- India cold-chain expansion:Food processing and pharmaceutical storage infrastructure underpenetrated by rigid foam insulation creates white space for cellular glass panel systems.
- Carbon-border adjustment alignment:EU CBAM compliance incentivizes domestic cellular glass production using recycled cullet versus imported mineral wool with embodied carbon penalties.
- Digital specification platforms:Building information modeling integration enables contractor-direct procurement of pre-cut cellular glass panels, bypassing traditional distribution.
Industry Challenges
- Cryogenic installation certification:LNG terminal contractors face extended qualification timelines for cellular glass application crews, compressing project execution windows.
- Legacy specification inertia:MEP engineers in commercial construction retain mineral wool defaults in absence of cellular glass thermal bridging calculators in standard design software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cellular Glass Market |
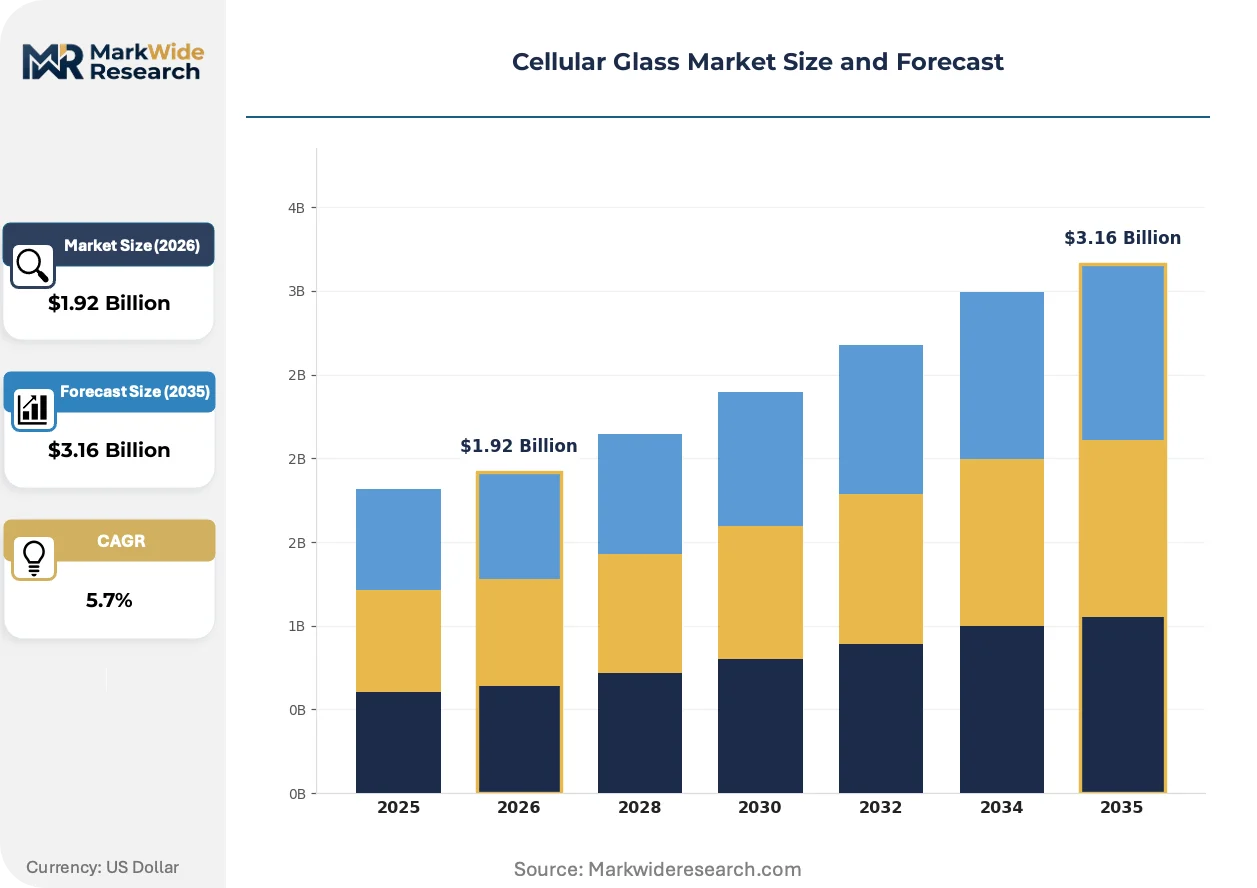
| Market Size in 2026 | $1.92 Billion |
| Market Size in 2035 | $3.16 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed Cell, Open Cell, Foam Board, Insulating Pipe End Use Industry: Construction, Automotive, Aerospace, Industrial Equipment Application: Thermal Insulation, Acoustic Insulation, Fire Protection, Lightweight Structures Form Factor: Blocks, Sheets, Panels, Granules |
| Companies Covered | Owens Corning, Misapor AG, POLYDROS, S.A., REFAGLASS, Zhejiang Zhenshen Insulation Technology Corp. Ltd., Cellglas Group AB, PINOSKLO, Glapor Werk Mitterteich GmbH, Wedge India, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cellular Glass Market Strategic Shifts & Innovations
Electrification of industrial process heat and hydrogen economy infrastructure is redirecting insulation specification toward materials surviving thermal cycling from -200°C cryogenic to 450°C steam conditions without degradation.
Advanced foaming agent chemistry is electrifying cellular glass manufacturing by enabling continuous panel production with closed-cell uniformity previously achievable only in batch-processed blocks. Hydrogen liquefaction plant EPCs in Germany and Japan specify these panels for rapid-installation tank insulation. The technology compresses installation labor hours by 40% versus traditional block-laying in large-diameter storage applications.
REACH Annex XVII restrictions on formaldehyde emissions redirect German and French commercial construction specifications toward inorganic cellular glass systems. The regulation eliminates phenolic foam from school and hospital projects where indoor air quality standards tightened. Nordic markets accelerate adoption fastest due to pre-existing building certification schemes prioritizing emission-free materials.
Contractor procurement through digital platforms fragments traditional distribution by enabling direct specification of pre-engineered cellular glass dimensions. Commercial retrofit specialists in the United States and Netherlands bypass regional distributors for project-optimized panel orders. The channel shift concentrates volume with manufacturers offering CNC cutting services and BIM-compatible submittal packages.
Cellular Glass Market Segmentation
Cellular glass manufacturers calibrate product portfolios across four distinct dimensions. Specification engineers select formulations based on thermal cycling demands, installation constraints, and regulatory fire ratings rather than commodity pricing.
Product Type:
Buyers differentiate cellular glass systems primarily by moisture resistance thresholds and thermal conductivity specifications.
- Closed Cell:Non-combustible foam structure with sub-0.05 W/m·K thermal conductivity and zero moisture absorption. LNG terminal contractors in Qatar and the United States specify these formulations for cryogenic pipeline insulation where boil-off gas containment failures carry catastrophic cost exposure.
- Open Cell:Interconnected porosity enables acoustic dampening in rail and aerospace transit applications. German and French rail operators under EU noise mandate compliance specify open-cell panels for tunnel lining retrofits where weight reduction competes with fire-performance requirements.
- Foam Board:Rigid sheet format optimized for commercial building envelope applications. Standardized dimensions reduce field cutting labor in German and Chinese district heating network installations.
- Insulating Pipe:Pre-formed cylindrical sections for industrial process piping. Prefabrication accelerates turnaround schedules in refinery maintenance windows.
Volume sits with Closed Cell; growth tilts toward Foam Board.
End Use Industry:
Margin profiles diverge sharply between project-driven industrial procurement and recurring commercial construction specification.
- Construction:Building energy code enforcement in Germany, the United States, and China drives specification for non-combustible envelope insulation. EU Green Deal renovation mandates accelerate retrofit demand across commercial building stock.
- Automotive:Electric vehicle battery pack thermal management and fire containment applications. OEMs specify cellular glass for cell-to-pack barrier materials where thermal runaway propagation must be contained.
- Aerospace:Weight-minimized acoustic insulation for cabin and cargo bay applications. Silica aerogel blankets compete aggressively on mass reduction metrics.
- Industrial Equipment:Cryogenic storage, process heat containment, and hydrogen liquefaction infrastructure. EPC contractors in Germany and Japan prioritize rapid-installation panel systems over traditional block-laying.
Construction commands current volume; Industrial Equipment climbs the fastest.
Application:
Performance certification requirements separate premium specification from commodity substitution.
- Thermal Insulation:Dominant consumption across district heating networks, cold-chain logistics, and hydrocarbon processing. GB standards tightening in China accelerates specification for cellular glass blocks in municipal infrastructure.
- Acoustic Insulation:Transit noise mandates in the European Union and Japan drive rail and aerospace adoption. REACH Annex XVII formaldehyde restrictions redirect specification from phenolic foam toward inorganic cellular glass in school and hospital projects.
- Fire Protection:Non-combustible rating enables penetration sealing and compartmentation in high-rise construction. Building codes in the United States and Germany mandate cellular glass for passive fire protection in commercial towers.
- Lightweight Structures:Granular and panel formats reduce dead load in modular construction and prefabricated building systems. Dutch and United States commercial retrofit specialists specify pre-engineered dimensions for installation speed.
Thermal Insulation anchors revenue; Acoustic Insulation gains share fastest.
Form Factor:
Installation labor economics and field adaptability determine contractor preference.
- Blocks:Batch-processed rigid units for heavy industrial settings. Cryogenic storage terminal contractors specify blocks for large-diameter tank bases where thermal bridging must be eliminated.
- Sheets:Continuous-rolled format for commercial building envelope applications. Standardized widths reduce material waste in facade retrofit projects.
- Panels:CNC-cut dimensions with BIM-compatible submittal packages. Digital procurement platforms enable contractor-direct ordering, bypassing traditional distribution channels in the Netherlands and United States.
- Granules:Loose-fill applications for irregular cavity insulation and lightweight concrete additive. Specialized niche with limited volume concentration.
Blocks dominate tonnage; Panels expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for cellular glass insulation clusters in industrial corridors with concentrated LNG infrastructure, district heating networks, and cryogenic storage buildouts. Germany, the United States, China, Qatar, and Japan absorb the dominant share of specification volume.
Germany
District heating retrofits in the Ruhr and Bavaria drive block consumption for pipeline networks. The EU Green Deal renovation mandates accelerate commercial building envelope upgrades. Munich-based Glapor Werk Mitterteich GmbH anchors European manufacturing through captive recycled glass supply.
United States
LNG export terminals on the Gulf Coast specify closed-cell systems for cryogenic containment. EPA industrial emissions frameworks constrain formaldehyde-containing alternatives. Houston and Corpus Christi contractors face extended crew certification timelines for cryogenic installation.
China
GB standards tightening accelerates cellular glass specification in municipal district heating and cold-chain logistics. Building energy efficiency mandates in Beijing and Shanghai redirect procurement toward non-combustible insulation. Zhejiang province fabricators supply cost-engineered blocks for infrastructure scale.
Qatar
North Field LNG expansion projects specify cellular glass for boil-off gas containment in storage tanks. The country's national hydrocarbon regulator enforces fire-safety standards for hydrocarbon processing insulation. Ras Laffan Industrial City concentrates EPC contractor activity for rapid-installation panel systems.
Japan
Hydrogen liquefaction plant construction in Kansai and Chubu regions drives demand for thermal cycling-resistant panels. METI decarbonization roadmaps prioritize cryogenic infrastructure for hydrogen economy buildout. Osaka-based engineering firms specify pre-cut dimensions to compress installation labor hours.
Cellular Glass Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with closed-cell formulations commanding premium positioning in cryogenic applications while foam board variants compete on installation speed in commercial retrofits. The vendor base organizes around three archetypes: integrated glass recyclers with captive feedstock, regional fabricators serving infrastructure specifications, and diversified insulation conglomerates leveraging distribution scale. Competitive moves concentrate on backward integration into recycled cullet supply and BIM-compatible pre-engineering services that bypass traditional distribution channels.
Among Germany-based fabricators, Glapor Werk Mitterteich GmbH occupies a position exemplifying the integrated recycler archetype through its captive glass supply chain. Owens Corning represents the diversified conglomerate model, anchoring North American distribution reach. Zhejiang Zhenshen Insulation Technology Corp. Ltd. sits within the cost-engineered regional specialist tier, serving Chinese infrastructure scale with block formulations tailored to domestic specifications.
| Leading Market Players |
|---|
| Owens Corning |
| Misapor AG |
| POLYDROS, S.A. |
| REFAGLASS |
| Zhejiang Zhenshen Insulation Technology Corp. Ltd. |
| Cellglas Group AB |
| PINOSKLO |
| Glapor Werk Mitterteich GmbH |
| Wedge India |
| Others |
Cost & Logistics Intelligence
Specialized cryogenic installation crews in the United States Gulf Coast and Qatar concentrate wage premiums that compress margins for LNG terminal contractors, widening spreads between premium closed-cell systems and economy-grade foam board alternatives in municipal district heating tenders.
Pricing Analysis
Volume concentrates in standardized foam board for commercial building retrofits while margins concentrate in certified closed-cell blocks for cryogenic infrastructure. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant formulations from phenolic foam substitutes and uncertified imports. Pricing pressure stems from silica aerogel substitution in aerospace acoustic applications where weight reduction overrides fire-performance premiums. Municipal infrastructure buyers in China exhibit highest price sensitivity; LNG EPC contractors in Qatar and Japan show lowest sensitivity due to catastrophic failure cost exposure.
Supply Chain Analysis
Single-source vulnerability sits with Glapor Werk Mitterteich GmbH's captive recycled glass feedstock anchoring European manufacturing scale. Production draws from Germany, China, and the United States with raw material dependencies on post-consumer cullet, carbon foaming agents, and borosilicate glass additives. Tariff exposure on Chinese block imports into the EU threatens cost-engineered supply lines. Distribution runs through regional insulation distributors with BIM-integrated direct procurement fragmenting traditional channels in the Netherlands and United States commercial retrofit segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH Annex XVII formaldehyde restrictions and EU Green Deal renovation mandates erect barrier-to-entry moats favoring incumbents with certified inorganic production lines.
For Market Incumbents: Hedge against aerogel substitution in aerospace and rail acoustic segments by accelerating panel-format R&D for rapid-installation LNG applications. Backward integration into captive recycled cullet supply secures margin defense against Chinese cost-engineered block imports. Prioritize cryogenic installation crew certification programs to compress project execution windows and lock out unqualified competitors.
For New Entrants and Emerging Players: Cold-chain logistics contractors in India represent an underserved buyer archetype with minimal rigid foam penetration and growing pharmaceutical storage infrastructure. White space concentrates in pre-engineered panel systems for hydrogen liquefaction plants where Japanese and German EPCs prioritize installation speed. A go-to-market angle through digital specification platforms with CNC cutting services bypasses entrenched distribution relationships.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated glass recyclers possessing captive feedstock and REACH certification assets given EU carbon-border adjustment mechanism alignment. Long-term viability over a multi-year horizon favors manufacturers with backward integration into post-consumer cullet supply and BIM-compatible pre-engineering capabilities. Watch hydrogen liquefaction plant announcement velocity in Germany and Japan as inflection indicator for panel-format demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Cullet Supply | Captive glass feedstock insulates Glapor Werk Mitterteich GmbH from raw material price volatility. |
| BIM-Compatible Pre-Engineering Services | CNC-cut panel dimensions enable contractor-direct procurement bypassing traditional distribution channels. |
| Cryogenic Installation Certification Programs | Qualified crews compress project timelines for LNG terminal contractors in Qatar and the United States. |
| Hydrogen Liquefaction Panel Development | Thermal cycling-resistant formats address METI decarbonization roadmaps in Japanese Kansai region. |
| REACH Annex XVII Compliance Investment | Formaldehyde-free positioning captures EU school and hospital renovation mandates in Germany and France. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with EPC contract managers, cryogenic installation supervisors, commercial building retrofit specialists, and insulation procurement directors at LNG terminal operators combined with secondary validation from ECHA REACH registrations, EPA industrial emissions disclosures, and China GB standards documentation. Bottom-up volume modeling across product types and end-use industries triangulated against top-down macroeconomic indicators.
Data-stream reconciliation across shipment volumes, import-export flows, and project announcement databases informed the analytical framework over the projection horizon. Segmentation dimensions spanned closed-cell versus open-cell formulations, construction versus industrial equipment end-use, thermal versus acoustic versus fire protection applications, and blocks versus panels versus sheets format factors. CAGRs derived from regression analysis against building energy code enforcement timelines and LNG infrastructure capital expenditure patterns with hydrogen economy buildout trajectories serving as industry-specific demand drivers.
Revisions become necessary when EU carbon-border adjustment mechanism implementation timelines accelerate, Chinese GB standards enforcement intensifies beyond modeled scenarios, or silica aerogel cost curves compress faster than anticipated in aerospace and rail segments. Deviation in hydrogen liquefaction plant construction velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
UAE Silica Sand Market
Glass
Low-E Glass Market
Glass
3D Glass Market
Glass
Heat Resistant Glass Market
Glass
Anti-Smudge and Anti-Streak Additives for Glass Cleaners Market
Glass
Birefringent Crystals Market
Glass
Foam Glass Granulate Market
Glass
Mirrored Glass Market
Glass
Silica Sol Market
Glass
Global Scratch Resistant Glass Market
Glass
Global Flat Glass Market
Glass
Global Energy Efficient Glass Market
Glass
Global Vacuum Insulated Glass Market
Glass
Solar Control Glass Market
Glass
Asia Pacific Flexible Glass Market
Glass
Europe Glass Insulators Market