
 Dynamic Glazing Market | 2026-2036
Dynamic Glazing Market Size, Share, and Industry Trends Forecast 2026-2036
Dynamic Glazing Market Analysis
High-performance electrochromic specifications is rotating toward the center of project bids across North America and Europe. View Inc. leverages vertically integrated manufacturing to control installation quality from fabrication through commissioning. Saint-Gobain S.A. anchors European supply through its specialized flat glass division with dedicated electrochromic capacity. PPG Industries, Inc. competes on coating chemistry depth, sustaining R&D pipelines that extend its architectural glass portfolio.
Dynamic glazing comprises facade-integrated systems that modulate visible light transmission and solar heat gain through applied voltage, thermal response, or suspended particle alignment, typically achieving 10-60% visible light transmittance adjustment. These systems reduce HVAC loads in commercial envelopes by blocking infrared spectrum entry during peak solar periods. Electrochromic glass leads product type revenue due to its precise voltage control and long cycle durability, while suspended particle devices occupy faster-growth niches in automotive sunroofs where switching speed matters. Commercial buildings dominate application demand as owners prioritize operational energy reductions, with aerospace representing a concentrated margin pool despite smaller volume.
The EU Green Deal and Energy Performance of Buildings Directive shape European demand by mandating near-zero energy standards for new construction. In the United States, the IRA tax incentives for energy-efficient commercial buildings lower payback periods for electrochromic retrofits. Building owners and glazing contractors must monitor evolving code adoption timelines across jurisdictions to align specification cycles with compliance deadlines.
Market Dynamics
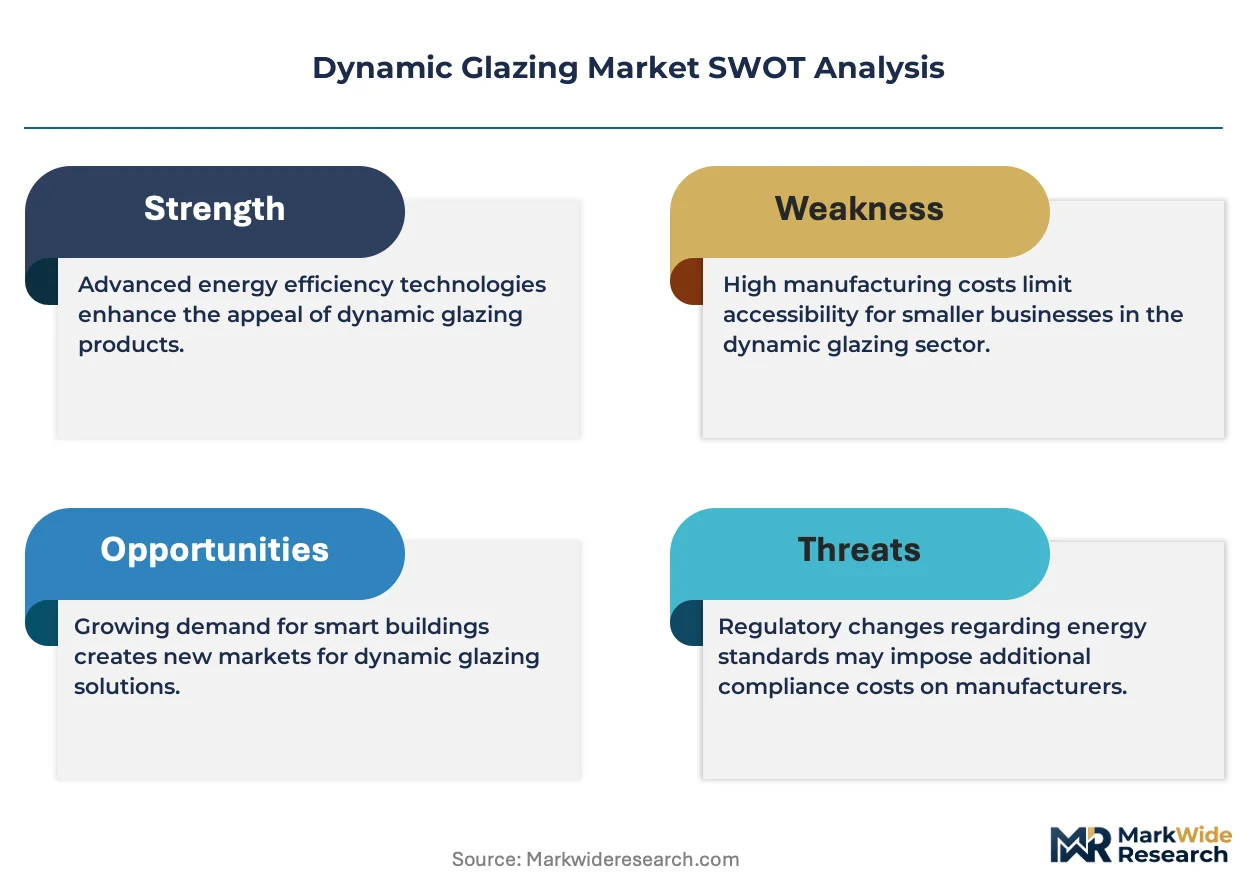
Electrochromic manufacturing scale-up is compressing unit economics while EU building envelope mandates force specification upgrades across commercial construction pipelines. The tension between coating chemistry IP concentration and distributed facade integration demand is restructuring competitive boundaries.
Growth Catalysts
- IRA Tax Incentives:United States commercial building owners capture accelerated depreciation for electrochromic retrofits, shortening payback calculations in Class A office and healthcare facility procurement.
- Suspended Particle Speed Advantages:Automotive OEMs specify faster-switching SPD technology for premium sunroof applications where electrochromic response lag creates user experience friction.
- German Retrofit Mandates:Berlin and Munich municipal codes require smart glazing integration in facade renovations exceeding 1,000 square meters, creating concentrated specification pull.
Market Restraints
- Tungsten Oxide Supply Concentration:Electrochromic active layer production depends on refined tungsten oxide feedstock concentrated in Chinese processing facilities, exposing coating manufacturers to input volatility.
- Installation Skill Scarcity:Electrical commissioning of facade-integrated systems requires glazing contractors with low-voltage certification crossover, a qualification pool thinner than conventional curtain wall trades.
- Static Low-E Substitution:Passive low-emissivity glass achieves 60-70% of solar heat gain reduction at 40% lower installed cost, capturing budget-constrained commercial segments.
Strategic Opportunities
- Residential Penetration Gap:Single-family and multifamily housing in France and Spain remain below 5% smart glazing attachment, presenting first-mover positioning for integrated window-wall systems.
- Photovoltaic Glazing Convergence:Building-integrated photovoltaics with electrochromic interlayers enable simultaneous energy generation and load reduction, opening utility-scale demonstration projects.
- CSRD Disclosure Requirements:Corporate Sustainability Reporting Directive mandates granular building energy intensity disclosures, making operational envelope performance a board-level procurement criterion.
Industry Challenges
- Commissioning Complexity:Facade-integrated control systems require coordination between glazing contractors, building automation integrators, and commissioning agents, extending project handover timelines.
- Cycle Durability Validation:Electrochromic devices must demonstrate 50,000+ switching cycles to meet warranty terms, testing protocols that lag product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dynamic Glazing Market |
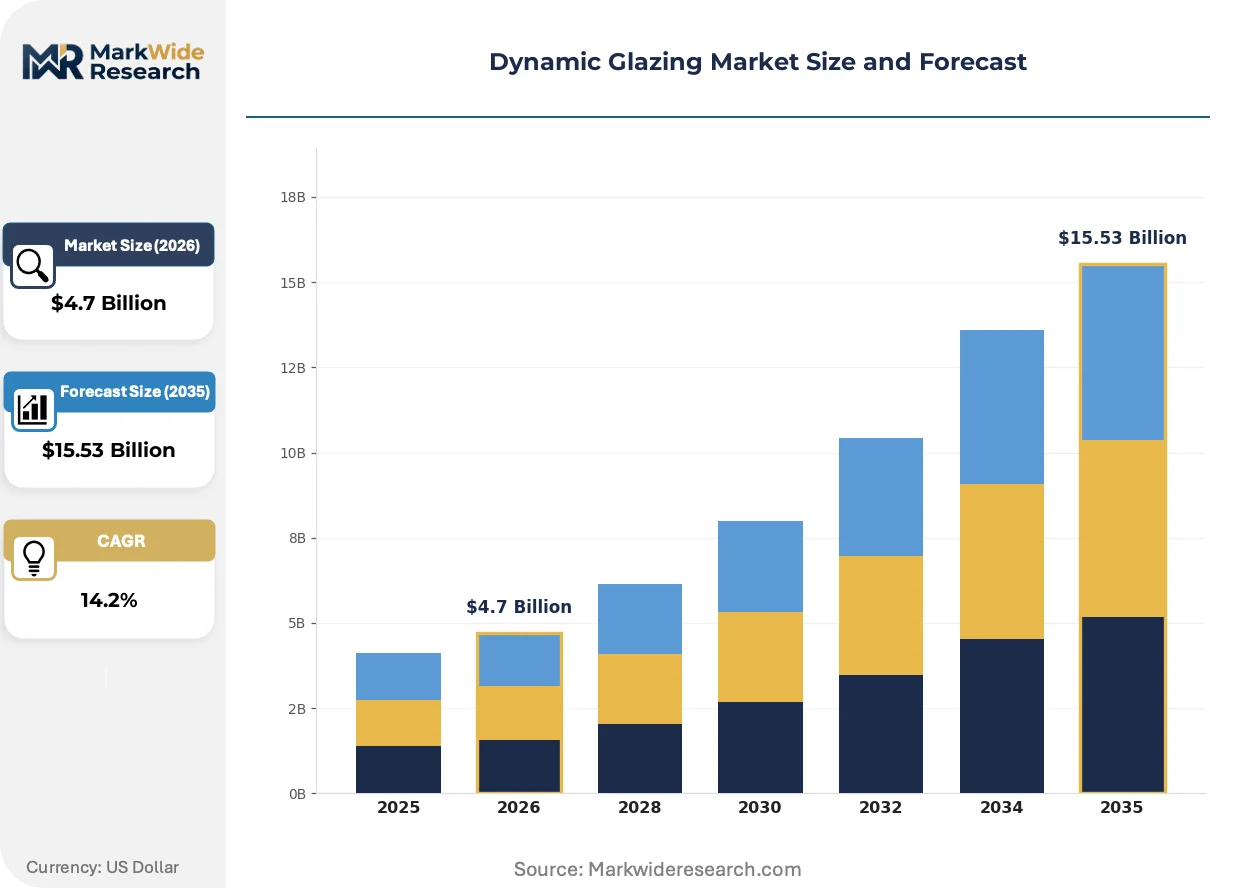
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $15.53 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrochromic Glass, Thermochromic Glass, Photochromic Glass, Suspended Particle Devices Application: Commercial Buildings, Residential Buildings, Automotive, Aerospace Technology: Smart Window Technology, Energy-efficient Coatings, Light Management Systems, Control Systems End User: Architects, Builders, OEMs, Government Agencies |
| Companies Covered | PPG Industries, Inc., Research Frontiers, Inc., Guardian Industries, Nippon Sheet Glass Co., Ltd., Pleotint LLC, Corning Inc., View Inc., Kinestral Technologies, Inc., Saint-Gobain S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dynamic Glazing Market Emerging Trajectories
Product architecture is fragmenting across performance tiers as coating chemistry advances enable thinner active layers without sacrificing optical density. The competitive frontier is shifting from raw switching speed to predictive control algorithms that anticipate solar load.
Electrochromic tungsten oxide thin-film deposition is bifurcating between sputtered architectures optimized for architectural scale and solution-processed coatings targeting automotive volume. Sputtered systems dominate German and US commercial facade specifications where optical clarity standards exceed 90% baseline transmittance. Solution processing is capturing Korean and Japanese automotive programs seeking curved surface compatibility.
EU Energy Performance of Buildings Directive recasts nearly-zero-energy building definitions to include dynamic envelope performance, compelling member states to revise national calculation methodologies. The directive forces recognition of operational savings from switchable glazing in compliance modeling, elevating electrochromic specifications from optional to preferred in public procurement. Netherlands and Denmark building codes are adopting the revised annex first, creating template adoption patterns for southern European markets.
Building owners are consolidating glazing specifications under performance-based service agreements that transfer commissioning risk to facade system providers. Contractors in the United Kingdom and Ireland now bundle electrochromic installation with ten-year energy performance guarantees, displacing traditional material-plus-labor contracts. This restructuring concentrates accountability with vertically integrated manufacturers capable of warranting both hardware and control logic.
Dynamic Glazing Market Segmentation
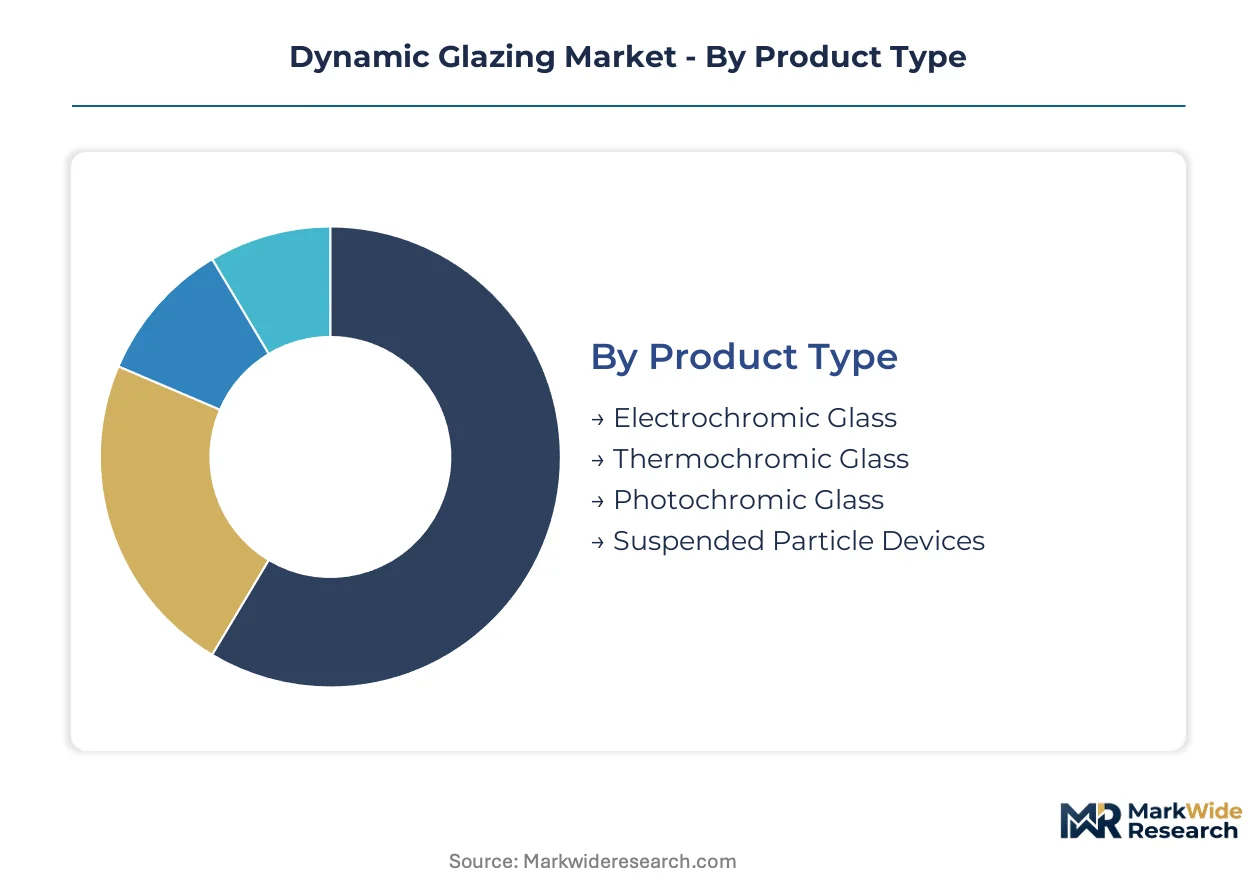
Dynamic glazing segmentation reveals how coating chemistry, application context, and control architecture determine specification pathways. Manufacturers align product development with distinct procurement hierarchies across building envelope and transportation sectors.
Product Type:
Electrochromic glass faces the most acute substitution pressure from static low-E alternatives, while photochromic and thermochromic variants compete against simpler solar control films.
- Electrochromic Glass:Tungsten oxide active layers enable precise voltage-driven optical switching with 10-60% transmittance modulation. Demand concentrates in United States Class A office retrofits where IRA tax incentives compress payback periods for facade replacements.
- Suspended Particle Devices:Polymer-dispersed liquid crystal matrices deliver sub-second switching speeds unmatched by electrochromic alternatives. Automotive OEMs in Germany and Japan specify SPD for premium sunroof programs where driver experience tolerates no perceptible lag.
- Thermochromic Glass:Vanadium dioxide coatings passively respond to surface temperature thresholds without electrical infrastructure. Building owners in Spain and Italy deploy thermochromic solutions in budget-constrained residential renovations.
- Photochromic Glass:Silver halide microcrystals darken under ultraviolet exposure, finding niche adoption in skylight applications where wiring complexity proves prohibitive.
Electrochromic glass anchors the volume base while suspended particle devices gain share at the steepest rate.
Application:
Cost tier differentiation separates premium envelope retrofits from new construction specifications across building categories.
- Commercial Buildings:Curtain wall and storefront systems dominate procurement value, with electrochromic specifications spreading from headquarters campuses to healthcare facilities. Germany's municipal retrofit mandates exceeding 1,000 square meters create concentrated demand in Berlin and Munich.
- Residential Buildings:Single-family and multifamily housing in France and Spain remain below 5% smart glazing attachment, presenting first-mover positioning for integrated window-wall systems targeting near-zero-energy building compliance.
- Automotive:Sunroof and side-window programs in Korean and Japanese OEM lineups favor SPD technology for curved surface compatibility and switching speed.
- Aerospace:Cabin window systems for commercial aviation represent a concentrated margin pool despite smaller absolute volume, with electrochromic specifications standard in premium cabin classes.
Commercial buildings command the revenue base while residential applications climb the fastest.
Technology:
Supply concentration in coating deposition equipment shapes competitive boundaries across technology tiers.
- Smart Window Technology:Integrated electrochromic and SPD systems with embedded control logic. United States and German facade specifications require 90%+ baseline optical clarity achievable only through sputtered thin-film architectures.
- Energy-efficient Coatings:Static low-E and solar control layers that complement dynamic systems. These coatings represent the primary substitute threat, capturing budget-constrained segments at 40% lower installed cost.
- Light Management Systems:Daylight harvesting controls that coordinate glazing tint with artificial lighting reduction.
- Control Systems:Building automation integration and predictive algorithms that anticipate solar load rather than react to it.
Smart window technology anchors specification value while control systems expand most quickly.
End User:
Customer type determines whether procurement emphasizes first-cost minimization or lifecycle performance optimization.
- Architects:Specification gatekeepers who balance aesthetic performance with energy modeling compliance. Netherlands and Denmark building codes elevate dynamic envelope performance in nearly-zero-energy calculations, compelling architect attention.
- Builders:Installation contractors facing scarcity of low-voltage certification crossover required for electrical commissioning of facade-integrated systems.
- OEMs:Automotive and aerospace manufacturers with volume programs that justify solution-processed coating investments for curved surface compatibility.
- Government Agencies:Public procurement bodies bound by EU Energy Performance of Buildings Directive revisions that recast dynamic envelope performance as preferred rather than optional.
Architects control specification flow while government agencies accelerate fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refined tungsten oxide processing concentrates in Chinese facilities, exposing coating manufacturers to input volatility while electrochromic fabrication clusters in Germany and the United States dominate architectural specification. Municipal retrofit mandates and federal tax incentives are reshaping procurement geography.
United States
Class A office developers in New York and Chicago are expanding electrochromic facade procurement for energy retrofits. IRA tax incentives compress payback periods for commercial building owners seeking accelerated depreciation on efficiency upgrades. Silicon Valley and Boston clusters concentrate control system integration expertise for smart window commissioning.
Germany
Berlin and Munich municipal codes mandate smart glazing integration in facade renovations exceeding 1,000 square meters. The EU Energy Performance of Buildings Directive recasts nearly-zero-energy calculations to include dynamic envelope performance, compelling specification upgrades. Bavaria and North Rhine-Westphalia host specialized flat glass fabrication with dedicated electrochromic capacity.
China
Domestic tungsten oxide refining supplies feedstock for regional coating manufacturers serving building and automotive programs. National dual carbon goals accelerate envelope efficiency standards in commercial construction codes. Yangtze River Delta clusters concentrate thin-film deposition equipment manufacturing for architectural scale production.
Japan
Automotive OEMs in Nagoya and Tokyo specify suspended particle devices for premium sunroof applications where switching speed determines user experience. METI efficiency standards for commercial buildings elevate dynamic glazing in new construction specifications. Kansai region fabricators develop solution-processed coatings for curved surface compatibility.
France
Single-family and multifamily housing in Île-de-France and Provence-Alpes-Côte d'Azur remains below 5% smart glazing attachment, presenting first-mover positioning for integrated window-wall systems. CSRD disclosure requirements make operational envelope performance a board-level procurement criterion. National building codes are adopting EU directive annex revisions for near-zero-energy compliance modeling.
Dynamic Glazing Market Vendor Landscape
Concentration sits with vertically integrated glass manufacturers and specialized coating chemistry developers. Three to five dominant players control sputtered thin-film deposition capacity for architectural specifications, while a fragmented tier of automotive-focused specialists competes on solution-processed coating speed. Strategic moves center on backward integration into tungsten oxide supply and captive control system development to warranty bundled energy performance.
Among North American fabricators, View Inc. and PPG Industries, Inc. occupy positions spanning coating chemistry through facade integration. Saint-Gobain S.A. anchors European supply architecture through specialized flat glass operations with dedicated electrochromic capacity. Research Frontiers, Inc. exemplifies the intellectual property licensing archetype, occupying a distinct tier from capital-intensive manufacturing players.
| Leading Market Players |
|---|
| PPG Industries, Inc. |
| Research Frontiers, Inc. |
| Guardian Industries |
| Nippon Sheet Glass Co., Ltd. |
| Pleotint LLC |
| Corning Inc. |
| View Inc. |
| Kinestral Technologies, Inc. |
| Saint-Gobain S.A. |
| Others |
Supply Flow & Price Mechanics
Static low-emissivity glass substitution is compressing electrochromic pricing premiums while simultaneously shifting procurement geography toward German and US fabrication clusters where optical clarity standards justify residual value capture. This dual pressure reshapes supplier economics as coating manufacturers absorb margin erosion in budget segments while defending premium positioning in municipal-mandated retrofits.
Pricing Analysis
The EU Energy Performance of Buildings Directive dictates the pricing tier structure across European specifications, compelling three-tier pricing stratification across premium electrochromic, standard thermochromic, and economy static low-E levels. Price differentiation centers on CE marking tier and volume scale, with certified facade systems commanding substantial premiums over uncertified alternatives. Cost compression in standard tiers is intensifying because static low-E achieves comparable solar heat gain reduction at lower installed cost. Residential builders in France and Spain exhibit highest price sensitivity, while German municipal retrofit mandates render commercial developers least sensitive.
Supply Chain Analysis
Strategic stockpiling of refined tungsten oxide feedstock dominates inventory strategy among coating manufacturers seeking insulation from Chinese processing volatility. Supply concentrates in Chinese tungsten oxide refining, German electrochromic fabrication, and US control system integration. Raw material dependencies include tungsten oxide active layers, indium tin oxide transparent conductors, and low-iron soda-lime glass substrates. Single-source vulnerability in Chinese feedstock processing exposes coating manufacturers to input disruption. Distribution runs through vertically integrated facade system providers bundling hardware, control logic, and commissioning services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of low-voltage certification crossover among glazing contractors concentrates project execution risk with a narrow qualified pool, elevating the strategic value of captive installation capabilities for manufacturers seeking to warranty bundled energy performance.
For Market Incumbents: Compound defensive positioning through backward integration into tungsten oxide supply and captive control system development to offset static low-E substitution threat in budget-constrained segments. Add dedicated electrochromic capacity in Bavaria and North Rhine-Westphalia to secure German municipal retrofit pipeline access. Prioritize CE marking investment to maintain specification eligibility under revised EU Energy Performance of Buildings Directive annexes. For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships in Netherlands and Denmark creates specification entry points before southern European code adoption accelerates. Target residential housing in France and Spain where smart glazing attachment remains below penetration thresholds. Pursue integrated window-wall system positioning for near-zero-energy building compliance rather than component supply. For Investors and Strategic Acquirers: The market sits at a standardization phase that favors vertically integrated manufacturers with captive coating chemistry and control system capabilities. Long-term viability hinges on consolidation of fragmented automotive SPD specialists and architectural electrochromic fabricators into unified envelope-performance platforms. Watch German municipal code adoption velocity as inflection indicator for European demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tungsten Oxide Supply | Captive feedstock secures coating manufacturers against Chinese processing volatility and input cost spikes. |
| Control System Development | In-house predictive algorithms differentiate facade providers from hardware-only competitors in EU public procurement. |
| CE Marking Pathway Investment | Notified body certification unlocks specification access under revised Energy Performance of Buildings Directive annexes. |
| Residential Window-Wall System Launch | Integrated offerings capture first-mover positioning in French and Spanish housing below current smart glazing penetration. |
| Photovoltaic Glazing Joint Venture | Building-integrated PV with electrochromic interlayers opens utility-scale demonstration projects and CSRD-aligned procurement. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with glazing contractors, building automation integrators, facade system procurement managers, and municipal code enforcement officials. Secondary validation drew from EU Energy Performance of Buildings Directive implementation tracking, national building code revision databases, IRA tax incentive utilization filings, and customs records for tungsten oxide trade flows. Bottom-up project pipeline analysis triangulated against top-down envelope efficiency spending estimates.
Across the analysis window, forecasts applied multi-dimensional segmentation by product type, application category, control architecture, and national regulatory cluster. CAGRs derived from installed base growth modeling and replacement cycle assumptions specific to commercial envelope retrofits. Key inputs included municipal mandate adoption timelines, IRA incentive phase-out schedules, and electrochromic cycle durability validation progress against warranty thresholds.
Underlying assumptions cover continued EU directive enforcement, IRA incentive continuity, and tungsten oxide supply stability, with deviation risk concentrated in trade policy shifts affecting Chinese feedstock access and code adoption delays in southern European markets. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Decorative Glass Market
Glass
Pharma Glass Tubing Market
Glass
Middle-East and Africa Flat Glass Market
Glass
Glass Prepreg Market
Glass
Shatterproof Glass Market
Glass
Europe Glass Insulators Market
Glass
Birefringent Crystals Market
Glass
Antiglare Glass Market
Glass
Anti-Smudge and Anti-Streak Additives for Glass Cleaners Market
Glass
Mirrored Glass Market
Glass
Silica Sand for Glass Making Market
Glass
Glass Insulator Market
Glass
3D Glass Substrate Market
Glass
East Africa Flat Glass Market
Glass
North America Flat Glass Market
Glass
Global Glassware Market