
 Global Energy Efficient Glass Market | 2026-2036
Global Energy Efficient Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Global Energy Efficient Glass Market Intelligence
Market Context
Triple-silver low-emissivity coatings are hardening as the default specification against double-silver alternatives in premium commercial projects. Saint-Gobain leverages captive sputtering capacity across four continents to secure raw material throughput. AGC Inc. anchors its position through integrated float glass and coating operations in Southeast Asia. Guardian Glass differentiates via proprietary vacuum deposition chambers that reduce noble gas consumption per pane.
Technical Definition and Segment Structure
Energy efficient glass denotes glazing systems engineered to minimize thermal transmittance while optimizing visible light transmission, typically achieving U-values below 1.0 W/m²K through multi-layer silver stacks, inert gas fills, or evacuated cavities. Its primary purpose is reducing HVAC energy loads in enclosed structures while maintaining daylighting performance. Low-E glass dominates value capture due to established coating infrastructure and architect familiarity, though vacuum insulation represents the fastest-growing technology segment as manufacturers resolve edge-seal longevity. Residential buildings constitute the largest application volume, but commercial buildings command superior per-square-meter pricing through performance-guaranteed specifications.
Regulatory Environment and Outlook
The EU Green Deal and REACH frameworks mandate progressive reductions in building operational carbon, directly tightening allowable U-values for fenestration in member states. China's GB standards and dual carbon goals enforce comparable thermal performance thresholds for new urban construction. The US EPA and state-level stretch codes such as California's Title 24 extend these requirements across North American jurisdictions. Stakeholders must monitor divergence between regional test protocols and certification reciprocity agreements.
Market Dynamics
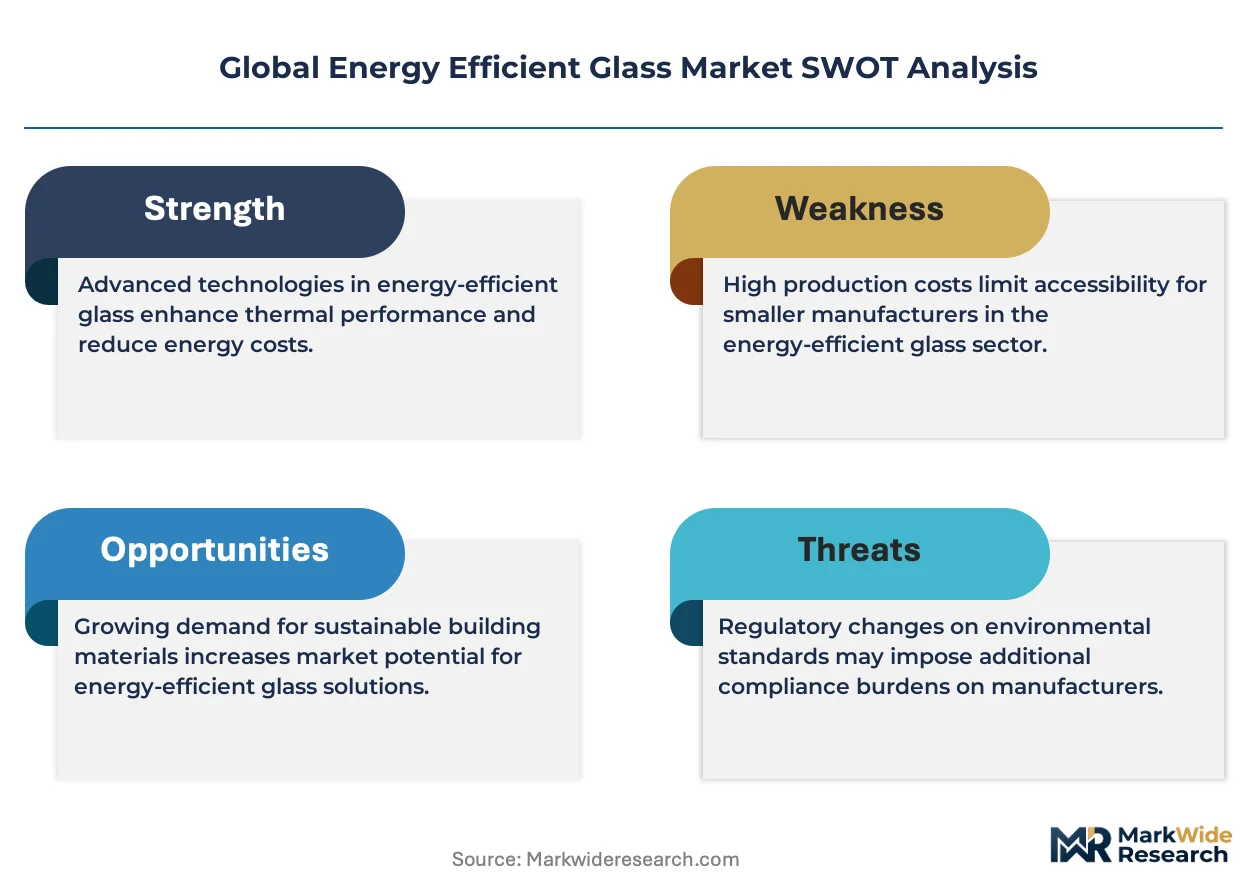
Building performance mandates across Germany, France, and China are compressing allowable U-values faster than coating technology can commoditize, forcing specification upgrades ahead of cost curves.
Growth Catalysts
- EU Green Deal building codes:Tightened operational carbon thresholds in Germany and France mandate triple-pane glazing in commercial retrofits, accelerating replacement cycles.
- China's dual carbon goals:Municipal green building codes in Shanghai and Jiangsu province now enforce high-performance glazing for all new urban construction above 10,000 square meters.
- Low-E sputtering advances:Multi-layer silver stack deposition now achieves sub-1.0 W/m²K thermal transmittance at commercial scale, expanding addressable building stock.
Market Restraints
- Argon and krypton supply concentration:Noble gas extraction concentrates in Ukraine and Russia, exposing coating operations to input volatility and forced substitution with air fills.
- Vacuum insulation edge-seal longevity:Current ceramic-metal transition joints fail at 25-year building lifecycle requirements, limiting VIG adoption to demonstration projects.
- California Title 24 compliance costs:Performance documentation and third-party certification add 12-18% to installed costs for out-of-state manufacturers.
Strategic Opportunities
- India's commercial real estate pipeline:LEED and IGBC certification momentum in Bangalore and Mumbai creates specification pull for low-E glazing in premium office stock.
- Smart glass convergence:Electrochromic and thermochromic layers integrated with low-E substrates enable dynamic solar control in healthcare and aviation sectors.
- US Inflation Reduction Act rebates:Section 179D deductions for energy-efficient commercial buildings expand addressable retrofit volume across aging office inventory.
Industry Challenges
- Magnetron sputtering technician scarcity:Vacuum deposition expertise concentrates at legacy float-coating facilities, constraining new plant commissioning in Southeast Asia.
- Multi-jurisdictional certification lag:Divergent NFRC, CE marking, and GB standard test protocols force redundant testing cycles for global product families.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Energy Efficient Glass Market |
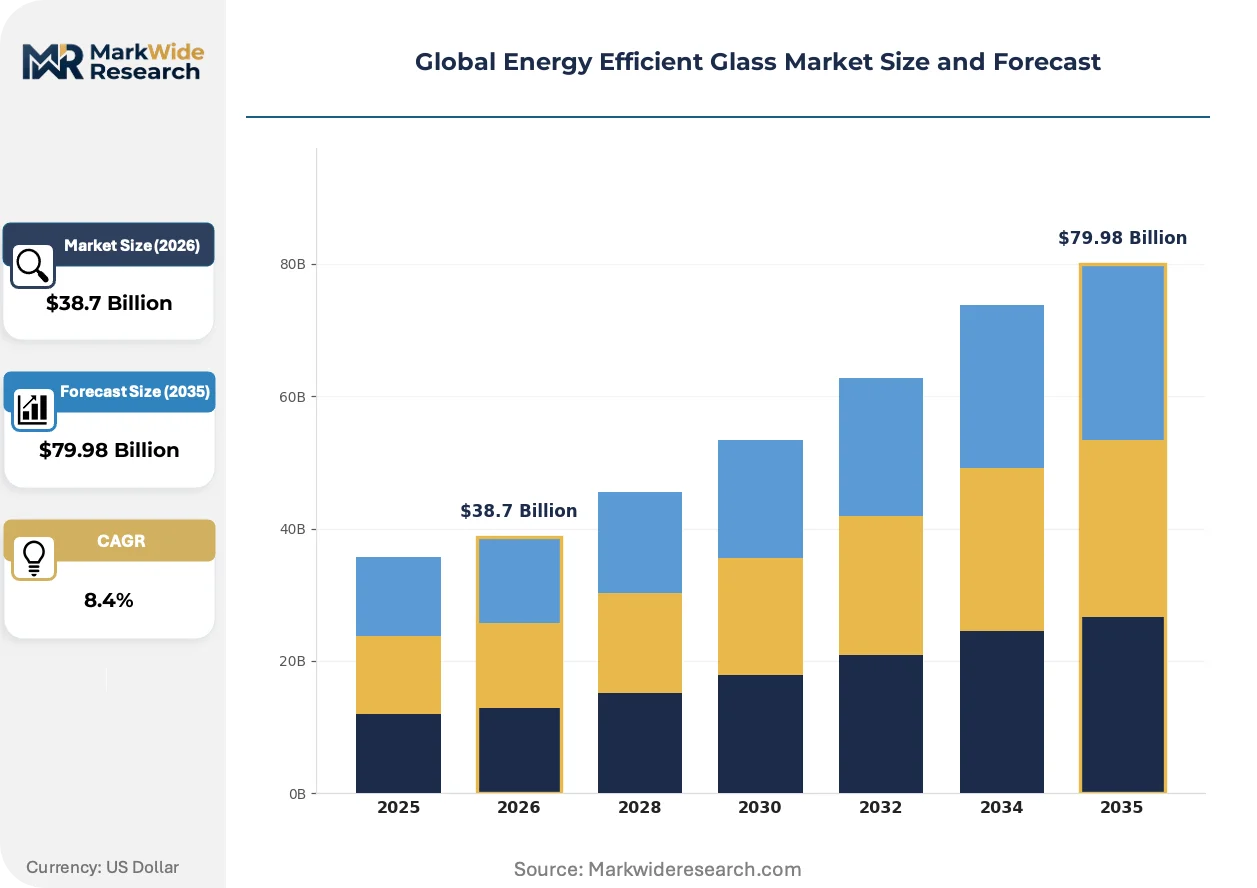
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-E Glass, Insulated Glass, Solar Control Glass, Laminated Glass Application: Residential Buildings, Commercial Buildings, Automotive, Industrial Facilities Technology: Coating Technology, Vacuum Insulation, Gas-Filled Technology, Phased-Change Technology End User: Contractors, Architects, Builders, Property Developers |
| Companies Covered | Saint-Gobain, AGC Inc., Guardian Glass, Nippon Sheet Glass Co., Ltd., Corning Incorporated, Vitro Architectural Glass, Xinyi Glass Holdings Ltd., Pilkington, Cardinal Glass Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Energy Efficient Glass Market Strategic Shifts & Innovations
Coating architecture, regulatory stringency, and procurement logic are simultaneously evolving, compressing the gap between laboratory performance and field-installed outcomes across temperate and tropical climate zones.
Dynamic glazing is converging with building management systems to enable real-time thermal response. Large-format electrochromic panels now integrate with BACnet protocols in Class A office towers. This convergence is compressing the performance gap between passive low-E and active solar control, forcing coating manufacturers to develop hybrid substrate architectures.
REACH F-Gas Regulation phase-down is accelerating hydrocarbon and CO2 blowing agent adoption in insulating glass unit spacer systems. European manufacturers reformulate warm-edge spacer chemistry to maintain thermal break performance without HFC-365mfc. Residential retrofits in Northern Europe face the steepest compliance timeline, driving specification toward thermoplastic spacer designs.
Developer procurement now bundles glazing performance guarantees with HVAC system warranties, transferring operational risk to envelope contractors. General contractors in China's eastern coastal provinces absorb energy modeling liability through design-build contracts. This risk transfer is most pronounced in Singapore and Hong Kong, where green building certification tiers determine lease premiums and asset valuation.
Global Energy Efficient Glass Market Segmentation
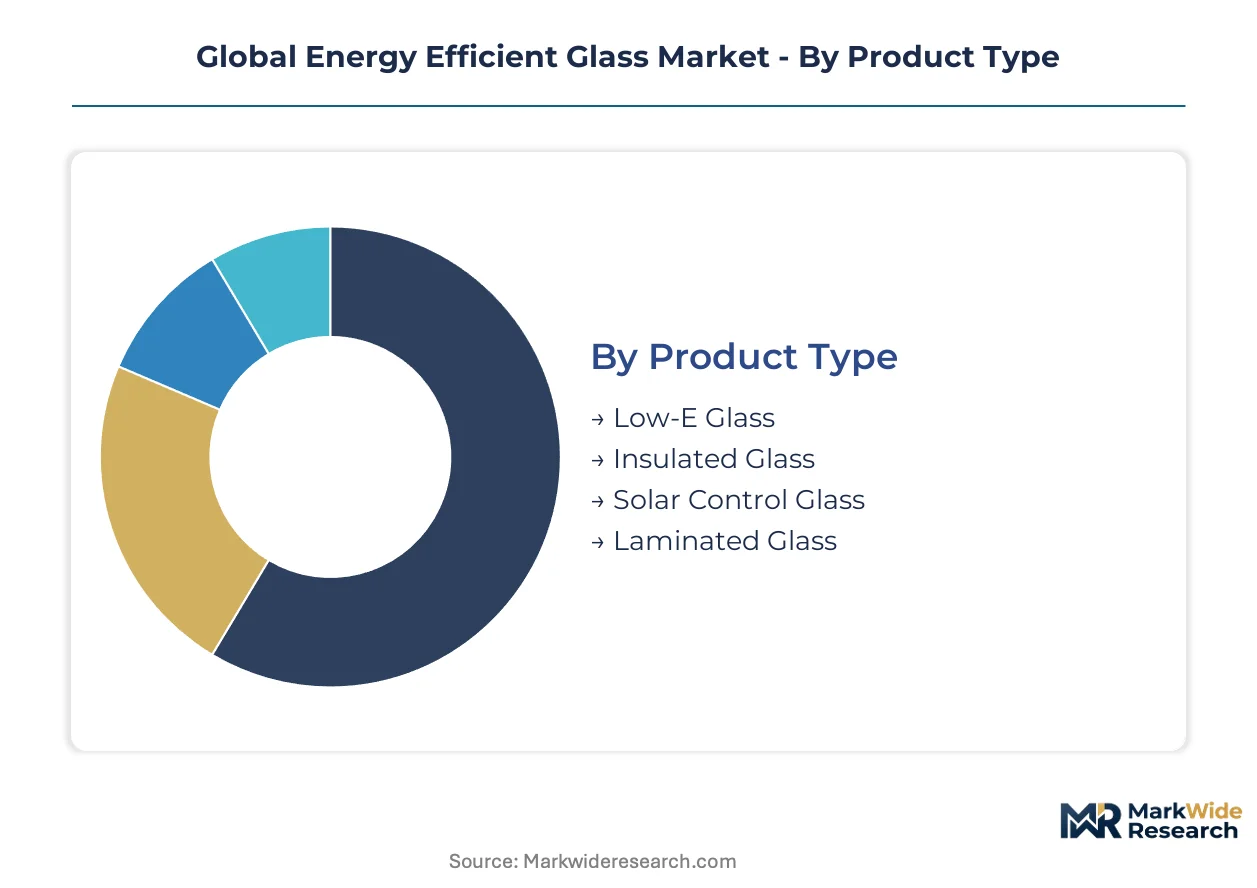
Segmentation reveals where capital intensity concentrates and which specification tiers command pricing power. Each dimension exposes distinct procurement logics, from coating technology investments to end-user risk-transfer structures.
Product Type:
Low-E glass and vacuum insulation demand the heaviest upfront sputtering chamber and edge-seal equipment outlays, while laminated and solar control variants leverage existing float line infrastructure.
- Low-E Glass:Multi-layer silver stack deposition achieves sub-1.0 W/m²K thermal transmittance through magnetron sputtering. Demand clusters in Germany and France where EU Green Deal retrofits mandate triple-pane commercial specifications.
- Insulated Glass:Dual-pane argon or krypton-filled cavities with warm-edge spacers dominate residential volume. China's eastern coastal provinces enforce municipal codes requiring high-performance glazing for new urban construction above 10,000 square meters.
- Solar Control Glass:Spectrally selective coatings reduce cooling loads in tropical climates.
- Laminated Glass:Interlayer technology combines safety with modest thermal gains in heritage building retrofits.
Low-E glass absorbs the bulk of installed capacity; vacuum insulation is expanding most quickly as manufacturers resolve ceramic-metal transition joint longevity.
Application:
Commercial buildings generate the steepest per-square-meter pricing through performance-guaranteed specifications, while residential volume spreads across fragmented retrofit and new construction channels.
- Residential Buildings:Single-family and multi-family housing stock drives unit volume across temperate climate zones. Northern Europe faces compressed compliance timelines under REACH F-Gas Regulation phase-downs, accelerating thermoplastic spacer adoption.
- Commercial Buildings:Class A office towers and healthcare facilities bundle glazing warranties with HVAC system guarantees. Singapore and Hong Kong green building certification tiers directly determine lease premiums and asset valuation.
- Automotive:OEM thermal comfort specifications push laminated low-E adoption in electric vehicle panoramic roofs.
- Industrial Facilities:Process cooling and controlled atmosphere requirements create niche demand for gas-filled systems.
Residential applications capture the greatest unit volume; commercial buildings yield the highest margin per installation.
Technology:
Coating and vacuum insulation technologies concentrate R&D expenditure, while gas-filled and phased-change approaches leverage mature manufacturing platforms with lower barrier to entry.
- Coating Technology:Triple-silver low-emissivity stacks now harden as default specification against double-silver alternatives in premium commercial projects. Sputtering expertise concentrates at legacy float-coating facilities, constraining new plant commissioning in Southeast Asia.
- Vacuum Insulation:Evacuated cavities with edge-seal ceramics achieve superior thermal performance but fail at 25-year lifecycle requirements. Current adoption limits to demonstration projects pending longevity validation.
- Gas-Filled Technology:Argon and krypton fills face supply concentration risks from Ukraine and Russia extraction.
- Phased-Change Technology:Dynamic thermal response materials remain in pilot deployment for healthcare and aviation sectors.
Coating technology anchors current production; vacuum insulation climbs the fastest as edge-seal reliability improves.
End User:
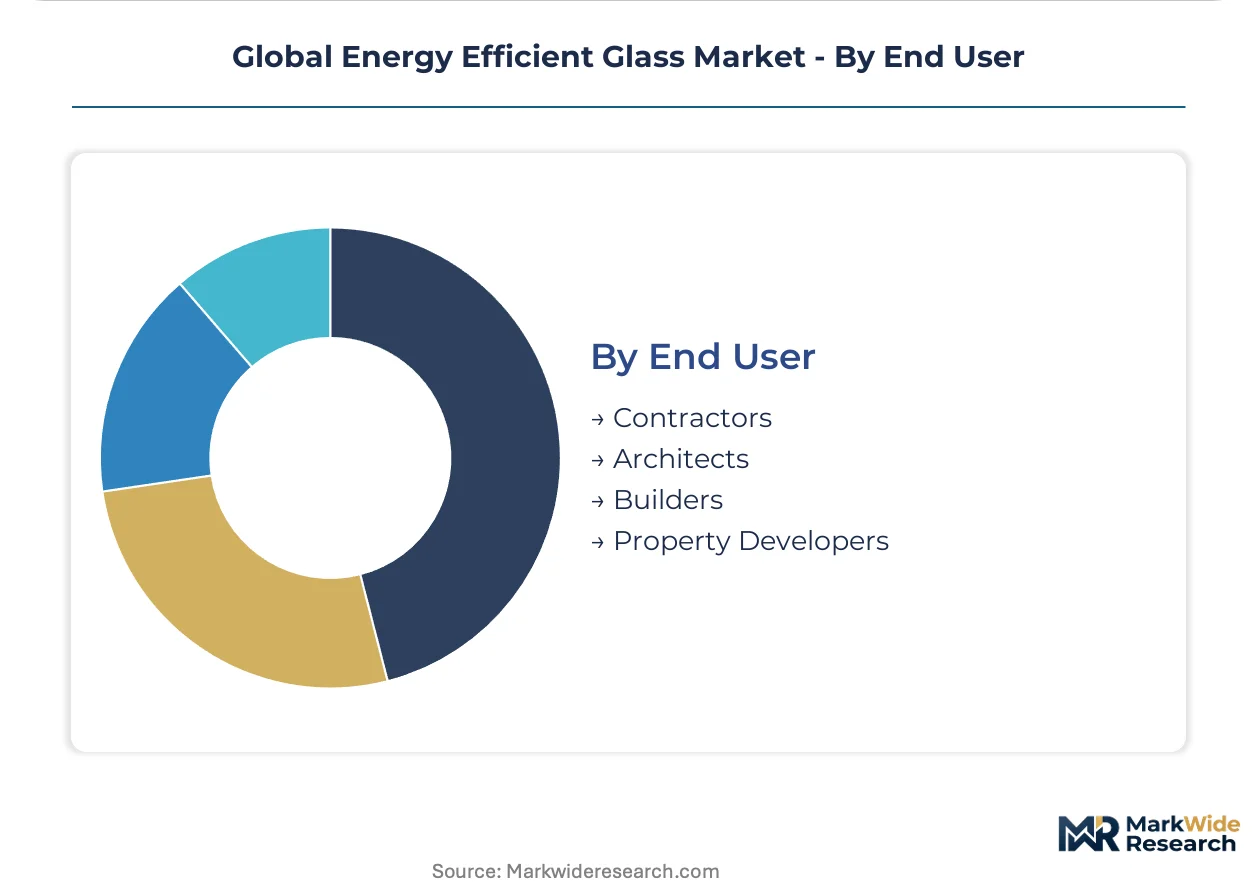
Property developers and general contractors now absorb energy modeling liability through design-build contracts, shifting specification authority away from traditional architect-led procurement.
- Contractors:Design-build firms in China's eastern coastal provinces assume envelope performance risk through integrated procurement. California Title 24 compliance costs add 12-18% to installed costs for out-of-state manufacturers.
- Architects:Specification authority concentrates in LEED and IGBC certification-driven projects across Bangalore and Mumbai commercial pipelines.
- Builders:Production homebuilders prioritize cost-standardized low-E packages across volume housing.
- Property Developers:Asset valuation models in Singapore and Hong Kong directly link green building tier to lease premiums, forcing high-performance glazing into base specifications.
Contractors control the largest share of specification decisions; property developers are gaining share fastest through integrated development platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the largest share of new construction demand, while Germany and France drive retrofit specification upgrades through tightened building codes. Municipal mandates in Shanghai and Jiangsu province now enforce high-performance glazing thresholds for commercial projects above 10,000 square meters.
China
Eastern coastal provinces anchor domestic demand as Shanghai and Jiangsu municipal codes mandate triple-pane specifications for new urban construction. The country's dual carbon goals enforce GB standard thermal performance thresholds across all major metros. Yangtze River Delta manufacturing clusters supply sputtering equipment to domestic float-coating facilities.
Germany
Commercial building retrofits in Berlin and Munich accelerate specification upgrades ahead of 2030 operational carbon targets. The EU Green Deal mandates progressive U-value reductions for fenestration in member states. North Rhine-Westphalia hosts captive sputtering capacity serving Central European project pipelines.
United States
California Title 24 stretch codes extend high-performance glazing requirements across Western states. The Inflation Reduction Act's Section 179D deductions expand addressable retrofit volume for aging office inventory. Pacific Northwest construction markets absorb premium low-E specifications for net-zero building certifications.
France
Île-de-France commercial towers drive specification pull for triple-silver low-emissivity coatings in premium office stock. REACH F-Gas Regulation phase-downs accelerate hydrocarbon blowing agent adoption in insulating glass unit spacer systems. Auvergne-Rhône-Alpes industrial corridors supply warm-edge spacer components to Northern European retrofit markets.
India
LEED and IGBC certification momentum in Bangalore and Mumbai creates specification pull for low-E glazing in premium commercial real estate. The Bureau of Indian Standards enforces progressive thermal performance codes for green building tiers. Maharashtra and Gujarat manufacturing bases import magnetron sputtering expertise from legacy float-coating facilities.
Global Energy Efficient Glass Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated float-coating operations commanding premium pricing in commercial specification channels. The vendor base organizes around three strategic archetypes: captive sputtering specialists with continental manufacturing footprints, regional fabricators serving retrofit replacement markets, and technology licensors supplying deposition equipment to third-party coaters. Dominant competitive moves include backward integration into noble gas supply chains and strategic partnerships with envelope contractors absorbing energy modeling liability.
Among integrated multinational specialists, Saint-Gobain and AGC Inc. occupy positions exemplifying captive sputtering scale across multiple continents. Guardian Glass represents the technology-differentiation archetype through proprietary vacuum deposition approaches. These three entities anchor the premium specification tier where performance guarantees bundle with HVAC system warranties.
| Leading Market Players |
|---|
| Saint-Gobain |
| AGC Inc. |
| Guardian Glass |
| Nippon Sheet Glass Co., Ltd. |
| Corning Incorporated |
| Vitro Architectural Glass |
| Xinyi Glass Holdings Ltd. |
| Pilkington |
| Cardinal Glass Industries, Inc. |
| Others |
Cost & Logistics Intelligence
General contractors in China's eastern coastal provinces anchor procurement volume through design-build contracts that bundle glazing performance with HVAC warranties, compressing margin structures for out-of-state manufacturers facing California Title 24 compliance documentation burdens. This buyer concentration forces pricing stratification across certification tiers rather than pure product grades.
Pricing Analysis
Volume concentrates in residential insulated glass with argon fills while margins concentrate in commercial triple-silver low-E specifications. Price differentiation rests on CE marking and NFRC certification reciprocity gaps, with premium tiers commanding 15-20 point spreads over economy double-silver alternatives. Pricing pressure intensifies as REACH F-Gas Regulation phase-downs force hydrocarbon spacer reformulation costs onto European fabricators. Residential retrofits in Northern Europe exhibit highest price sensitivity; Singapore and Hong Kong Class A towers show lowest.
Supply Chain Analysis
CE marking and GB standard test protocol divergence gates market access before production economics, forcing redundant certification cycles for global product families. Magnetron sputtering equipment concentrates in Germany, Japan, and China; noble gas extraction draws from Ukraine and Russia exposure. Single-source vulnerability in krypton supply chains threatens coating operations with forced air-fill substitution. Distribution runs through envelope contractors absorbing energy modeling liability in integrated procurement structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around coating technology scale as REACH F-Gas and China's dual carbon goals force sub-scale float-coating facilities into exit or acquisition.
For Market Incumbents: Lock in captive noble gas supply chains through long-term offtake agreements with extraction facilities outside Eastern Europe, insulating coating operations from substitution risk. Deepen backward integration into warm-edge spacer manufacturing to capture REACH-driven hydrocarbon reformulation premiums. Acquire magnetron sputtering technician training programs in Southeast Asia to preempt commissioning bottlenecks at greenfield plants. For New Entrants and Emerging Players: The premium-to-economy price gap in India's LEED and IGBC-certified commercial pipeline offers white-space entry below Saint-Gobain and AGC Inc. pricing floors. Target vacuum insulation edge-seal longevity validation as a technical wedge; demonstration project credentials unlock specification authority before manufacturing scale. Partner with envelope contractors in Bangalore and Mumbai to absorb energy modeling liability through design-build structures. For Investors and Strategic Acquirers: The window for entry favors mid-cap float-coating operations with idle sputtering capacity and existing CE marking infrastructure. Long-term viability hinges on regulatory reciprocity arbitrage across EU Green Deal, GB standards, and California Title 24 frameworks. Watch for ceramic-metal transition joint reliability breakthroughs as inflection signal for vacuum insulation commercialization timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Noble Gas Supply | Captive krypton and argon sourcing insulates coating margins from Eastern Europe supply shocks. |
| Warm-Edge Spacer Chemistry Reformulation | Hydrocarbon blowing agent adoption aligns with REACH F-Gas phase-downs in Northern European retrofits. |
| Magnetron Sputtering Technician Training | Vacuum deposition expertise expansion unlocks greenfield commissioning in Southeast Asian manufacturing clusters. |
| Vacuum Insulation Edge-Seal Validation | Ceramic-metal transition joint reliability demonstration opens commercial specification beyond pilot projects. |
| Design-Build Contractor Partnerships | Energy modeling liability absorption through envelope procurement bundles glazing with HVAC performance guarantees. |
Research Approach
Independent corroboration across plant managers at float-coating facilities, procurement leads at commercial envelope contractors, and regulatory affairs specialists at certification bodies underwrites the qualitative findings. Primary interviews with magnetron sputtering technicians, glazing specification architects, and GPO contracts managers at healthcare facility developers combined with secondary validation from EU Green Deal implementation reports, ECHA REACH substance databases, and China GB standards disclosure filings. Bottom-up capacity assessments triangulate against top-down construction spend forecasts.
Rate-of-change decomposition across coating technology generations, regulatory stringency phases, and procurement model shifts structures the analytical framework. Segmentation models incorporate product type, application, technology, and end-user decision authority across the projection horizon. CAGRs derive from installed base replacement cycles, new construction permitting data, and specification upgrade elasticities to building code tightening. Forecast inputs include noble gas spot price volatility bands and certification reciprocity agreement timelines.
Inputs from ECHA substance registration databases and China Ministry of Housing construction permitting records were available through the study window; gaps in real-time vacuum insulation field performance data introduce uncertainty bands around edge-seal longevity assumptions. Forecasts reflect documented assumptions regarding ceramic-metal transition joint reliability improvement trajectories. A model refresh is warranted upon material change in EU Green Deal building performance standard implementation timelines or GB standards thermal transmittance threshold adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Optical Materials Market
Glass
Glass Vials Market
Glass
Tinted Glass Market
Glass
Solar Control Glass Market
Glass
Asia-Pacific Flat Glass Market
Glass
North America Architectural Flat Glass Market
Glass
Low Iron Glass Market
Glass
Technical Glass Market
Glass
Global Silicone Structural Glazing Market
Glass
Birefringent Crystals Market
Glass
Glass Mat Thermoplastic Market
Glass
Tempered Glass Market
Glass
Europe Silica Sand for Glass Making Market
Glass
Silica Sand Market
Glass
France Silica Sand Market
Glass
Glass Like Carbon Market