
 Technical Glass Market | 2026-2036
Technical Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Technical Glass Market Analysis
Direct technical glass procurement from original equipment manufacturers is reconfiguring traditional distributor roles across the electronics and automotive supply chains. Corning Inc. leverages captive fusion-draw technology to dominate display substrate supply for mobile and IT panels. Schott AG anchors European pharmaceutical packaging and optical glass demand through precision borosilicate capabilities. AGC Inc. competes aggressively in automotive laminated safety glass across Japanese and Southeast Asian assembly networks.
Technical glass comprises engineered silica-based materials formulated with precise thermal expansion coefficients, chemical durability thresholds, and optical transmission properties, produced through melting, forming, and post-processing steps such as ion exchange or chemical vapor deposition. Its primary commercial purpose spans hermetic sealing, thermal management, structural transparency, and dielectric insulation across demanding industrial environments. Specialty glass commands the deepest margin pools due to pharmaceutical vial and semiconductor wafer requirements, while glass fiber sustains volume leadership through wind turbine blade and construction reinforcement applications. Flat glass occupies a mature position in architectural glazing, though coating technology upgrades are reviving value capture in smart facade systems.
EPA emissions guidelines and OSHA silica exposure limits in the United States shape furnace design and worker protection investments across domestic manufacturing facilities. REACH substance restrictions in Europe constrain cadmium and lead content in optical coatings, redirecting formulation R&D toward rare-earth and titanium dioxide alternatives. Stakeholders must monitor evolving building energy codes and semiconductor subsidy programs to anticipate which glass compositions and processing technologies will secure preferential procurement status.
Market Dynamics
Semiconductor packaging substrates and advanced display substrates are pulling specialty glass demand upward, while REACH compliance in Europe and tightening energy-efficiency codes in North America force reformulation of architectural and automotive glass compositions.
Growth Catalysts
- Semiconductor packaging substrates:Advanced chiplet architectures require ultra-low thermal expansion glass interposers. Foundries in South Korea and Taiwan are expanding specialty glass procurement for 2.5D/3D integration.
- EU Green Deal building codes:Mandatory near-zero energy building standards across Germany, France, and the Netherlands are accelerating vacuum-insulated glass and electrochromic glazing retrofits in commercial facades.
- Fusion-draw thin glass:Mobile device manufacturers demand sub-0.1mm chemically strengthened cover glass. This process enables foldable display durability without sacrificing optical clarity.
Market Restraints
- High-purity silica supply concentration:Over 70% of semiconductor-grade quartz sand originates from Spruce Pine, North Carolina and limited deposits in China, creating single-point-of-failure risk for high-CTE control substrates.
- Energy cost volatility:Float glass furnaces consume natural gas equivalent to 5-7 GJ per ton of product. European manufacturers face feedstock cost swings exceeding 40% year-on-year.
- Polymer substitution in automotive:Polycarbonate glazing achieves 50% weight reduction versus laminated safety glass. German OEMs are qualifying polymer solutions for non-vision zone applications.
Strategic Opportunities
- India pharmaceutical packaging:CDSCO's tightening injectable drug standards and domestic production incentives under PLI schemes create demand for Type I borosilicate vials currently met by imports.
- Solid-state battery electrolyte substrates:Lithium-sulfur and sodium-ion cell architectures require chemically inert glass-ceramic separators. Japanese materials firms are piloting roll-to-roll processing.
- Direct OEM procurement platforms:Electronics manufacturers are bypassing distributors for ion-exchange strengthened glass. Corning's direct supply agreements with South Korean panel makers demonstrate channel compression potential.
Industry Challenges
- Fusion-draw furnace engineering talent:The specialized thermodynamics expertise required for overflow downdraw systems is concentrated among retiring cohorts at Corning and AGC, constraining capacity expansion.
- REACH substance authorization timelines:Cadmium and lead oxide replacements in optical glass require 18-24 month ECHA notification cycles, delaying new product qualification for European medical device OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Technical Glass Market |
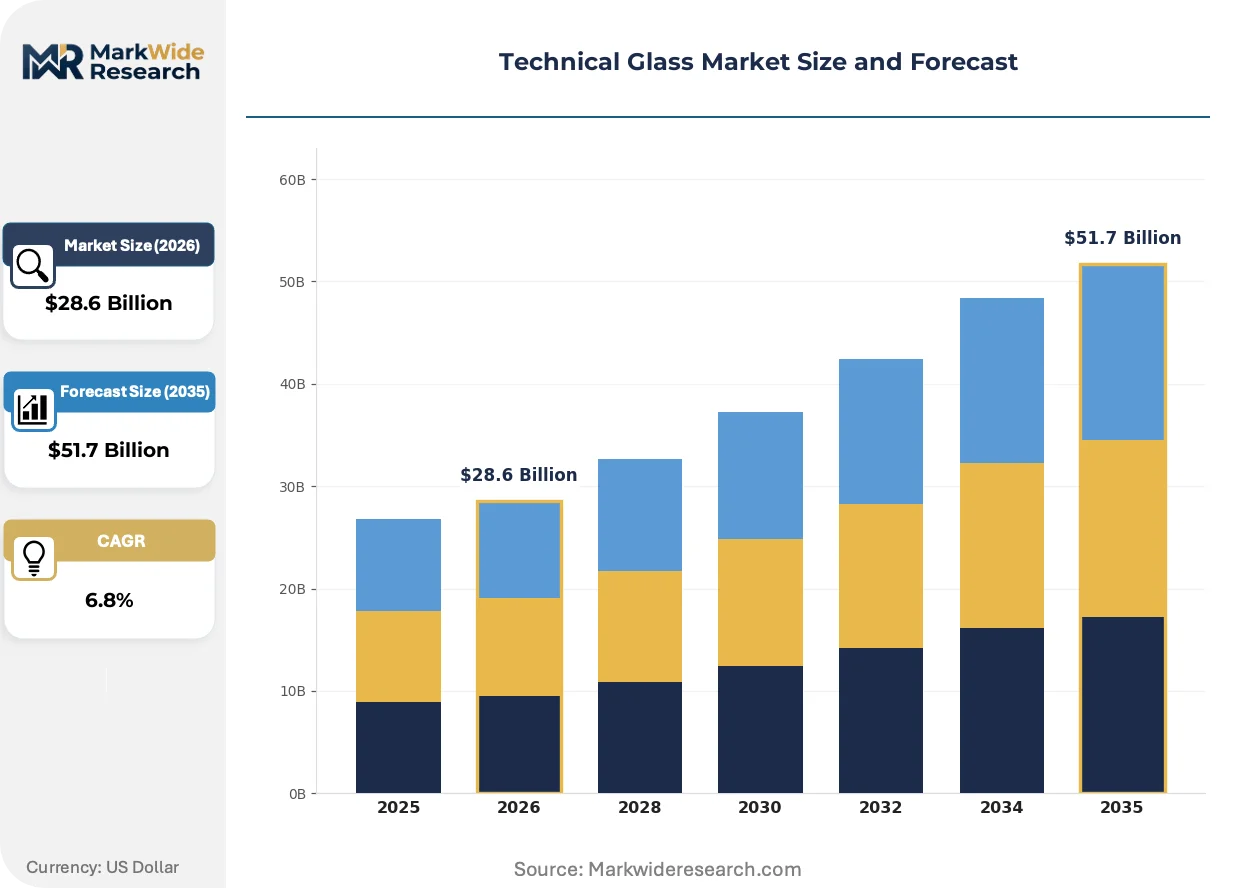
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Glass, Glass Fiber, Specialty Glass, Container Glass End User: Automotive, Electronics, Aerospace, Architectural Application: Interior Design, Optical Devices, Thermal Insulation, Construction Technology: Tempering, Laminating, Coating, Printing |
| Companies Covered | PPG Industries Inc., Guardian Glass, Saint-Gobain, Xinyi Glass Holdings Limited, Fuyao Glass Industry Group Co., Ltd., Corning Inc., AGC Inc., Technical Glass Products Inc., Schott AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Technical Glass Market Emerging Trajectories
Process instrumentation and quality control systems are digitizing technical glass manufacturing, while regulatory pressure on embodied carbon and chemical content accelerates formulation innovation.
Machine vision and spectral inline monitoring is digitizing defect detection in float and fusion-draw lines. Display glass manufacturers in South Korea and Japan deploy real-time thickness mapping to reduce edge trimming waste. This compression of quality assurance cycles enables single-pass processing for sub-0.05mm substrates.
REACH substance restrictions constrain cadmium and lead content in optical coatings across European pharmaceutical and aerospace supply chains. ECHA's 2023 sunset dates for certain chromophore compounds redirect R&D toward rare-earth and titanium dioxide alternatives. German optical glass specialists are reformulating high-index flint glasses to maintain Abbe number performance without restricted elements.
Automotive OEMs now specify full lifecycle carbon footprints for glazing systems, not just operational energy performance. Tier-1 suppliers to German and Japanese assembly plants must document Scope 3 emissions from soda ash mining through furnace combustion. This certification-driven preference shift favors manufacturers with renewable energy contracts and recycled cullet integration above 30% by weight.
Technical Glass Market Segmentation
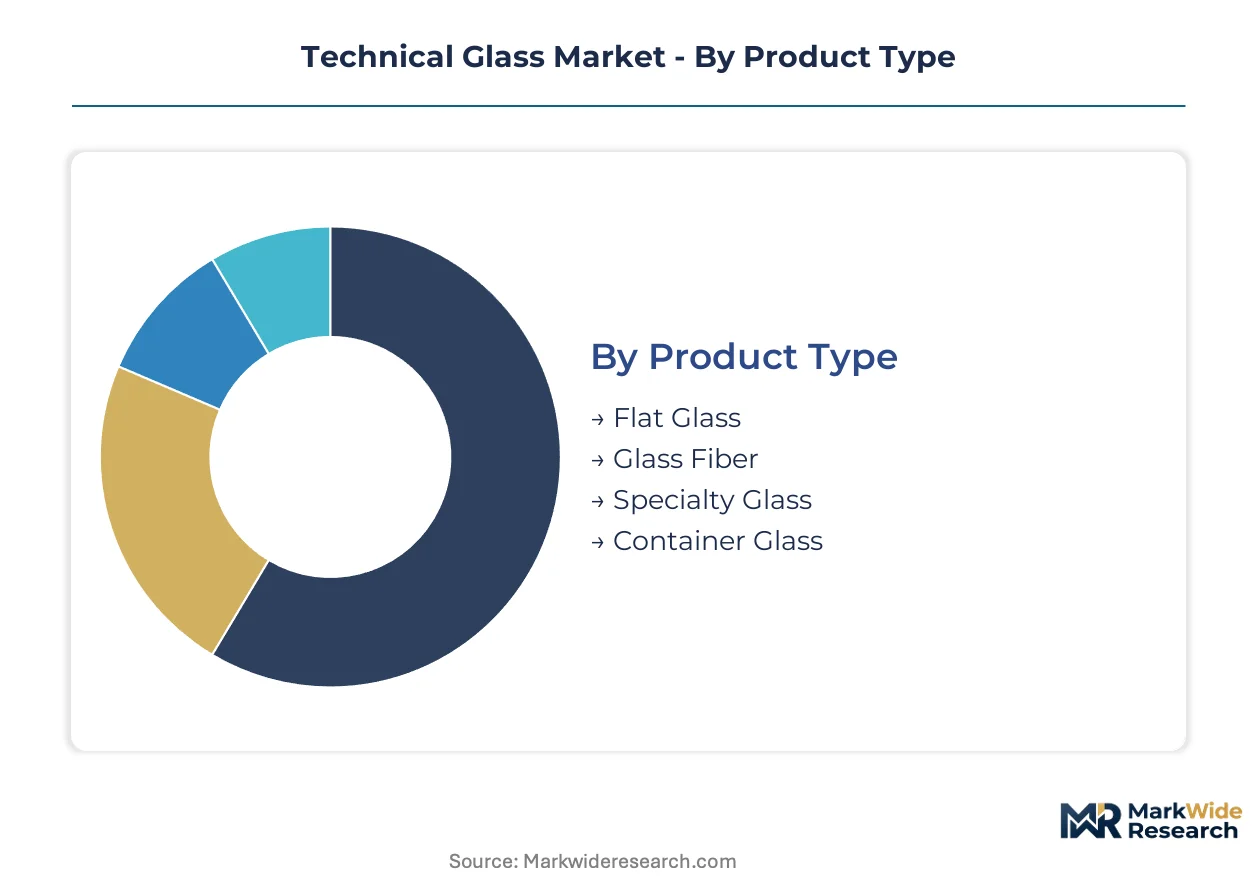
Technical glass segmentation reveals divergent margin structures across product architectures. Product type and end-user concentration determine capital intensity and regulatory exposure for manufacturers.
Product Type:
Mature volume segments coexist with emerging specialty formulations commanding premium positioning.
- Flat Glass:Soda-lime silica compositions dominate architectural and automotive glazing through float process manufacturing. Construction retrofits in Germany and France absorb tempered and laminated variants as EU Green Deal codes tighten thermal performance thresholds.
- Specialty Glass:Engineered borosilicate and aluminosilicate formulations deliver precise thermal expansion coefficients for semiconductor packaging and pharmaceutical containment. South Korean foundries and German medical device OEMs drive procurement for ion-exchange strengthened substrates.
- Glass Fiber:Continuous filament and chopped strand configurations reinforce wind turbine blades and polymer composites. E-glass formulations sustain volume leadership through energy infrastructure buildouts.
- Container Glass:Amber and flint soda-lime compositions package food and beverage products. Type I borosilicate variants serve pharmaceutical injectables under tightening CDSCO and FDA purity standards.
Flat glass retains volume leadership; specialty glass holds the steepest expansion curve.
End User:
Customer concentration patterns split between consolidated OEM procurement and fragmented specification-driven demand.
- Electronics:Display substrate and semiconductor interposer requirements specify ultra-thin fusion-drawn glass with sub-5 ppm thermal expansion. Japanese and South Korean panel manufacturers consolidate supply agreements directly with specialty glass producers.
- Automotive:Laminated safety glass for windshields and tempered sidelites must satisfy ECE R43 and FMVSS 205 impact standards. German OEMs qualify polymer alternatives for non-vision zones to reduce curb weight.
- Architectural:Commercial facade systems integrate low-emissivity coatings and vacuum-insulated glazing. Dutch and French building codes mandate near-zero energy performance for new construction.
- Aerospace:Chemically strengthened transparent armor and optical windows require MIL-PRF-25690 compliance. Cockpit display cover glass demands abrasion resistance under FAA certification protocols.
Electronics commands the tightest supplier consolidation; automotive presents the most substitution vulnerability.
Application:
Functional requirements determine processing complexity and certification burden across use cases.
- Construction:Structural glazing and curtainwall systems specify heat-soaked tempered glass for spontaneous breakage mitigation. German facade engineers prioritize embodied carbon documentation under new tender protocols.
- Thermal Insulation:Vacuum-insulated glass units achieve center-of-glass U-values below 0.4 W/m²K. Dutch commercial retrofits accelerate deployment as energy renovation subsidies expand.
- Optical Devices:Precision lenses and prisms demand high-homogeneity melts with striae-free transmission. ECHA REACH restrictions on lead and cadmium chromophores force rare-earth reformulation cycles.
- Interior Design:Decorative glass panels and partitions utilize digital printing and acid-etching surface treatments. Hospitality and corporate fit-out specifications drive short-run customization.
Construction anchors absolute volume; thermal insulation gains share fastest on regulatory tailwinds.
Technology:
Process selection locks in capital expenditure profiles and defect tolerance thresholds.
- Coating:Magnetron sputtered low-emissivity and anti-reflective layers modify optical and thermal performance. Online pyrolytic coating integrates with float lines; offline sputtering enables multi-layer stacks.
- Tempering:Thermal or chemical strengthening induces compressive surface layers for mechanical durability. Automotive and architectural safety glazing mandates specify minimum surface compression depths.
- Laminating:Polyvinyl butyral and ionomer interlayers bond glass plies for post-breakage retention. Windshield specifications require optical clarity and penetration resistance under ECE and DOT protocols.
- Printing:Ceramic frit and digital inkjet deposition enable aesthetic and functional surface patterns. Spandrel and signage applications specify UV-stable pigmentation.
Coating captures the deepest value-add per square meter; laminating sustains the broadest regulatory mandate coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers command pricing leverage through fused silica scale, while German and South Korean suppliers extract premiums via precision interposer substrates. This asymmetry shapes procurement patterns across semiconductor and display supply chains. Regional specialization deepens as furnace technology and regulatory compliance fragment production economics.
China
Display substrate foundries in Suzhou and Hefei drive specialty glass consumption for OLED and micro-LED panel manufacturing. The Ministry of Industry and Information Technology's dual carbon goals tighten energy intensity standards for float glass furnaces above 500 tons daily capacity. Yangtze River Delta clusters concentrate ion-exchange strengthening capacity for foldable device cover glass.
Germany
Automotive glazing OEMs in Stuttgart and Munich qualify vacuum-insulated glass for electric vehicle thermal management. The KBA enforces updated ECE R43 homologation protocols for laminated windshields with embedded antenna systems. Bavarian optical glass workshops near Jena reformulate lead-free flint compositions under REACH chromophore sunset deadlines.
South Korea
Semiconductor packaging foundries in Pyeongtaek and Yongin expand procurement of ultra-low CTE glass interposers for 2.5D chiplet integration. The MFDS regulates Type I borosilicate vial imports for biologics manufacturing under tightened purity standards. Seoul Capital Area display makers negotiate direct supply agreements bypassing traditional distributor networks.
United States
Pharmaceutical packaging demand in New Jersey and North Carolina sustains borosilicate vial production for injectable drug containment. The EPA's updated emissions guidelines for glass manufacturing reshape furnace investment timelines in Ohio and Pennsylvania. Spruce Pine, North Carolina anchors high-purity quartz sand supply for semiconductor-grade substrates.
India
Domestic injectable drug manufacturers in Maharashtra and Gujarat drive Type I borosilicate vial demand under CDSCO tightening standards. The PLI scheme for pharmaceuticals incentivizes local glass packaging capacity to replace imports from Europe and China. Hyderabad and Mumbai clusters attract technical glass distributors establishing regional fulfillment centers.
Technical Glass Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with formulation and process IP. The market structures around three tiers: multinational material science conglomerates with captive fusion-draw technology, mid-scale regional fabricators serving automotive and architectural specifications, and niche specialists in pharmaceutical and optical grades. Strategic moves concentrate on backward integration into high-purity silica mining and forward integration into direct OEM supply agreements that compress distributor margins.
Among diversified material science conglomerates, Corning Inc., Schott AG, and AGC Inc. occupy positions defined by proprietary furnace architectures and end-market anchoring. Corning exemplifies the platform-integrator archetype through captive fusion-draw scale. Schott AG represents European precision borosilicate specialization. AGC Inc. anchors Japanese and Southeast Asian automotive glazing networks. These three entities illustrate how technology lock-in and geographic clustering create defensible positioning against mid-tier competitors.
| Leading Market Players |
|---|
| PPG Industries Inc. |
| Guardian Glass |
| Saint-Gobain |
| Xinyi Glass Holdings Limited |
| Fuyao Glass Industry Group Co., Ltd. |
| Corning Inc. |
| AGC Inc. |
| Technical Glass Products Inc. |
| Schott AG |
| Others |
Supply Flow & Price Mechanics
Float glass furnace undercapacity in Germany is forcing spot-market premiums for architectural grades while compressing contract-renewal margins for automotive laminates. This utilization asymmetry rewards manufacturers with captive silica reserves and renewable energy contracts while punishing merchant producers exposed to natural gas volatility.
Pricing Analysis
The customization-premium spread between configured-to-order specialty glass and standard float products now exceeds three-to-one on a per-square-meter basis. Contract-based long-term offtake dominates semiconductor substrate procurement, while spot purchasing persists in construction tempered glass. Price differentiation hinges on ion-exchange certification tiers and volume scale, with German automotive OEMs least sensitive due to safety-critical mandates and Indian pharmaceutical packagers most sensitive given PLI scheme cost caps. Cost compression in container glass is intensifying because Chinese soda-ash exports are flooding Southeast Asian markets.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for display substrate procurement. High-purity quartz sand concentrates in Spruce Pine, North Carolina and limited Chinese deposits, while fusion-draw furnace engineering talent clusters in South Korea and Japan. The supply chain rests on semiconductor-grade silica, boron compounds for borosilicate formulations, and rare-earth oxides for lead-free optical coatings. Single-source vulnerability pervades ion-exchange salt chemistry. Distribution runs through direct OEM agreements for electronics substrates and regional fabricator networks for architectural glazing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fusion-draw thermodynamics expertise now concentrates among retiring cohorts at two dominant manufacturers, constraining capacity expansion and inflating acquisition premiums for specialized engineering teams.
For Market Incumbents: Insulate proprietary furnace architectures through selective patent enforcement and targeted hiring from university glass-science programs. Secure captive high-purity silica offtake from Spruce Pine deposits before competitor lock-in accelerates. Expand ion-exchange strengthening capacity in the Yangtze River Delta to capture foldable device demand. For New Entrants and Emerging Players: India's pharmaceutical packaging corridor offers the most penetrable white space, with CDSCO tightening standards and PLI incentives creating import-substitution demand for Type I borosilicate vials. Solid-state battery electrolyte substrates represent a second entry vector, with Japanese materials firms piloting roll-to-roll glass-ceramic processing. Target contract manufacturing partnerships with domestic injectable drug producers as the primary go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty glass producers with direct semiconductor foundry agreements spanning multiple chiplet generations. Long-term viability favors manufacturers with backward integration into high-purity silica mining and forward integration into direct OEM supply platforms. Watch for ECHA REACH authorization delays on cadmium replacements as the inflection signal for European medical device supply requalification cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Purity Silica Mining | Captive Spruce Pine quartz sand reserves secure semiconductor substrate supply against geographic concentration risk. |
| Fusion-Draw Capacity Expansion | Sub-0.1mm chemically strengthened glass output captures foldable display procurement from South Korean panel makers. |
| Direct OEM Supply Agreement | Bypassing distributor networks compresses channel margins and locks in multi-year semiconductor interposer offtake. |
| REACH-Compliant Optical Glass Reformulation | Rare-earth and titanium dioxide alternatives to lead-cadmium chromophores maintain European medical device market access. |
| Vacuum-Insulated Glass Retrofit Partnership | EU Green Deal building codes in Germany and France mandate near-zero energy performance for commercial facades. |
Methodological Framework
A standing panel of fusion-draw furnace engineers, pharmaceutical packaging procurement managers, semiconductor foundry supply chain directors, and architectural glazing specification consultants provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from SEC filings of listed glass manufacturers, ECHA REACH substance authorization databases, customs trade data for soda ash and silica imports, and CDSCO pharmaceutical packaging regulatory circulars. Bottom-up demand modeling for end-use applications triangulated against top-down capacity estimates from furnace engineering disclosures.
Scenario-bracketing framed projections across the analysis window, with base, upside, and downside cases reflecting semiconductor capital expenditure cycles, EU building code enforcement timing, and energy cost volatility. Segmentation dimensions modeled include product type, end-user concentration, application functional requirements, and processing technology. CAGRs derived from historical volume trajectories adjusted for structural shifts in direct OEM procurement and regulatory-driven formulation changes. Forecast inputs incorporated ion-exchange strengthening capacity buildouts and solid-state battery electrolyte substrate pilot production timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese display substrate producers or accelerated polymer substitution by German automotive OEMs would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Flexible Glass Market
Glass
Global Anti-Reflective Glass Market
Glass
Glass Vials Market
Glass
North America Architectural Flat Glass Market
Glass
Pharmaceutical Glass Tubing Market
Glass
Foam Glass Granulate Market
Glass
Foam Glass Market
Glass
Glass Grade Dolomite Market
Glass
Coated Glass Market
Glass
Glass Reactors Market
Glass
Glass Tableware Market
Glass
Advanced Glass Market
Glass
United States Flat Glass Market
Glass
East Africa Flat Glass Market
Glass
Glass Alternative Materials Market
Glass
Europe Glassware Market