
 Solar Reflective Film Market | 2026-2036
Solar Reflective Film Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Reflective Film Market Insights
Asian petrochemical producers is hardening supply availability for polyester and polyethylene terephthalate substrates used in solar reflective films. 3M leverages its multi-layer coating patents to sustain premium positioning in architectural glazing channels. Saint-Gobain anchors European demand through building insulation partnerships with major construction firms. Eastman Chemical Company specializes in advanced acrylic formulations that compete on optical clarity and durability metrics.
Solar reflective film comprises a thin polymer substrate, typically polyester or polyethylene terephthalate ranging from 25 to 175 microns, coated with metalized aluminum or ceramic oxide layers that reflect infrared solar radiation while transmitting visible light for glare reduction and thermal management in enclosed spaces. Metalized technology dominates volume shipments due to mature sputtering equipment and lower unit costs, while ceramic and nanotechnology segments capture margin pools from automotive OEMs and high-performance building projects seeking electromagnetic interference transparency. Application demand skews heavily toward building insulation as energy retrofit codes tighten across developed economies, with automotive glazing representing the fastest-growing structural segment as electric vehicle manufacturers prioritize thermal load reduction to extend battery range.
The EU Green Deal and REACH frameworks mandate chemical transparency and embodied carbon disclosure for construction materials sold across member states, directly shaping product formulation decisions by film manufacturers. The US EPA Energy Star program and state-level stretch codes in California and New York create fragmented but demanding compliance terrain that favors suppliers with certified testing laboratories. China's GB standards and dual carbon goals impose parallel efficiency benchmarks that filter market access for imported films. Stakeholders must monitor divergence between regional testing protocols for solar heat gain coefficient and visible light transmission, as misalignment threatens to fragment product portfolios and inflate certification costs without commensurate pricing power.
Market Dynamics
Building energy retrofit mandates across the United States, Germany, and China are compressing specification cycles for solar reflective films, forcing manufacturers to align product portfolios with divergent testing protocols for solar heat gain coefficient and visible light transmission.
Growth Catalysts
- EU Green Deal efficiency mandates:The framework's embodied carbon disclosure requirements for construction materials accelerate replacement of conventional glazing in commercial buildings across member states.
- Electric vehicle thermal management:Automotive OEMs specify ceramic-coated films to reduce cabin thermal load and extend battery range in premium electric vehicle platforms.
- China's dual carbon goals:National efficiency benchmarks under GB standards filter market access and drive domestic production scale for retrofit applications.
Market Restraints
- Polyester substrate cost volatility:Asian petrochemical supply tightness for polyethylene terephthalate creates input price pressure without commensurate pricing power transfer.
- Metalized film technical ceiling:Electromagnetic interference opacity limits adoption in connected vehicle and smart building applications requiring signal transparency.
- REACH chemical transparency:ECHA disclosure requirements inflate formulation costs and certification timelines for imported films entering European markets.
Strategic Opportunities
- Underpenetrated Indian commercial construction:Bureau of Indian Standards energy code adoption creates first-mover positioning for certified suppliers in high-rise glazing retrofits.
- Nanotechnology-ceramic convergence:Hybrid coating architectures enable premium positioning in electromagnetic interference-transparent segments previously closed to metalized alternatives.
- US state-level stretch codes:California and New York building efficiency mandates exceed federal baselines, creating certified-product premiums in fragmented compliance terrain.
Industry Challenges
- Multi-protocol certification complexity:Divergent SHGC and VLT testing standards across EPA Energy Star, EU Green Deal, and China's GB standards fragment product portfolios and inflate laboratory validation costs.
- Sputtering equipment capex intensity:Metalized layer deposition requires vacuum chamber investments that constrain mid-scale entrants from achieving cost parity with established multi-layer coating specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Reflective Film Market |
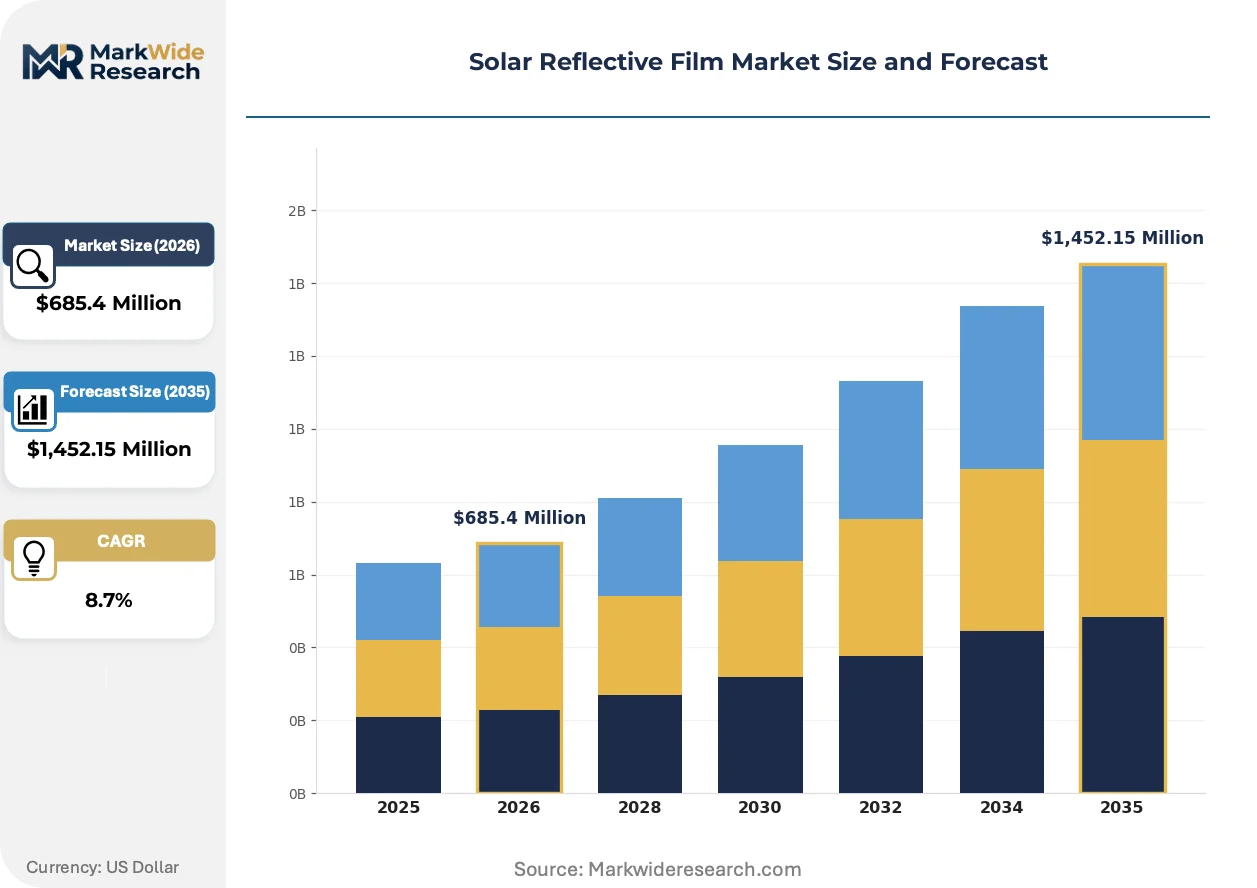
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Polycarbonate, Acrylic, Vinyl, Polyethylene Terephthalate, Polypropylene Technology: Metalized, Multi-layer Coating, Ceramic, Micro-etched, Nanotechnology Application: Building Insulation, Automotive Glazing, Agriculture, Electronics, Signage End User: Construction Companies, Transportation Providers, Farming Operations, Electronics Manufacturers, Advertising Agencies |
| Companies Covered | 3M, Saint-Gobain, Eastman Chemical Company, Avery Dennison Corporation, Madico Inc, Garware Hi-Tech Films, Lintec Corporation, Solar Gard, Hanita Coatings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Reflective Film Market Trends and Innovations
Ceramic oxide and nanotechnology coating architectures are displacing legacy metalized formulations in premium segments, while regulatory fragmentation forces parallel product development tracks and testing laboratory investments.
Multi-layer sputtered ceramic coatings is integrating infrared-reflective functionality with electromagnetic interference transparency, a combination previously unattainable with aluminum metalization. Electric vehicle manufacturers in Germany and South Korea specify these films for panoramic roof applications where connectivity and thermal performance must coexist. The technology is integrating optical clarity benchmarks that compress margin pools for conventional metalized suppliers locked into sputtering equipment with lower performance ceilings.
REACH chemical transparency and embodied carbon disclosure requirements are reshaping formulation decisions for construction-grade films sold across EU member states. ECHA mandates force substrate and adhesive suppliers to document supply chain emissions, favoring vertically integrated manufacturers with captive polymer production. High-performance building projects seeking BREEAM and LEED certification drive specification of films with verified lifecycle data, compressing market access for uncertified imports.
Specification authority is migrating from general contractors to glazing subcontractors and energy consultants who control technical compliance documentation. This channel shift compresses brand loyalty and elevates certified testing laboratory relationships as the primary competitive moat. The United States exhibits the most pronounced consultant-driven procurement, particularly in California and New York where local stretch codes exceed federal Energy Star baselines and require jurisdiction-specific compliance verification.
Solar Reflective Film Market Segmentation
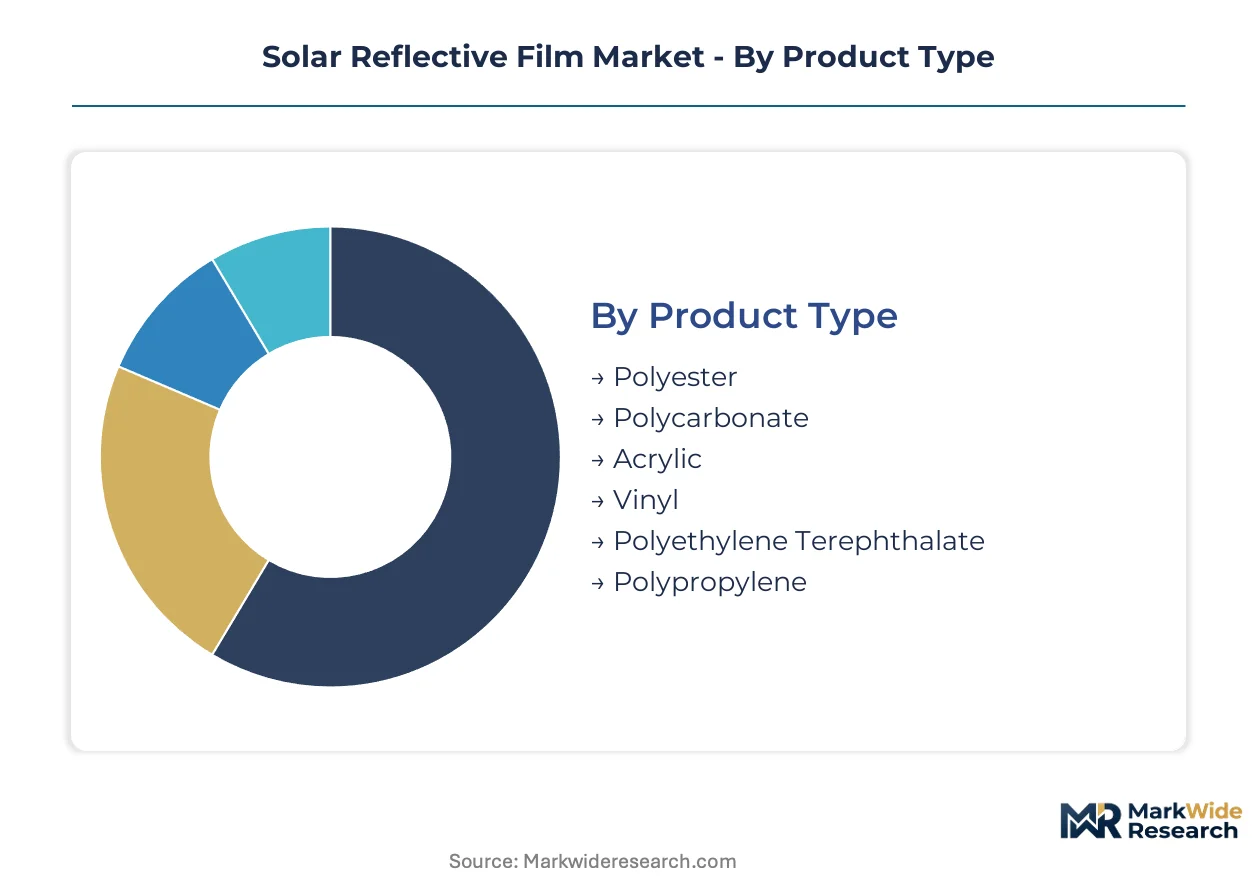
Segmentation in solar reflective films determines which certification pathways manufacturers must navigate. Product type dictates REACH chemical disclosure burdens, while technology choice governs electromagnetic interference transparency requirements for automotive and smart building applications.
Product Type:
Polyester and polyethylene terephthalate substrates face the heaviest EU Green Deal embodied carbon disclosure requirements, while acrylic formulations compete on optical clarity benchmarks under EPA Energy Star testing protocols.
- Polyester:The dominant substrate ranging from 25 to 175 microns, polyester films require sputtering-compatible surface properties for metalized layer adhesion. Construction companies in Germany and China specify polyester-based films for high-rise retrofit projects where GB standards and EU Green Deal mandates overlap, though Asian petrochemical supply tightness inflates input costs without guaranteed pricing power recovery.
- Polyethylene Terephthalate:Crystalline clarity and dimensional stability make PET the preferred substrate for automotive OEMs requiring visible light transmission above 70%. Electric vehicle manufacturers in South Korea prioritize PET-based ceramic coatings for panoramic roof applications where thermal load reduction extends battery range.
- Polycarbonate:Impact-resistant substrate serving signage and agricultural greenhouse applications where mechanical durability outweighs optical precision requirements.
- Acrylic:Eastman Chemical Company specializes in advanced acrylic formulations competing on optical clarity and durability metrics under EPA Energy Star certification.
- Vinyl:Cost-effective substrate for temporary signage and budget-tier building insulation where certification requirements remain minimal.
- Polypropylene:Emerging substrate for agriculture films where chemical resistance to pesticides and fertilizers takes priority over thermal performance.
Leading the category by volume: Polyester. Growing fastest: Polyethylene Terephthalate.
Technology:
Cost tiers separate mature sputtering equipment investments from emerging nanotechnology capex requirements, with ceramic coatings commanding premium positioning in electromagnetic interference-transparent segments.
- Metalized:Aluminum sputtering dominates volume shipments through mature vacuum chamber equipment and lower unit costs. 3M leverages multi-layer coating patents to sustain premium positioning in architectural glazing channels, though electromagnetic interference opacity limits adoption in connected vehicles and smart buildings.
- Ceramic:Oxide coatings enable infrared reflection with signal transparency, a combination unattainable with aluminum metalization. Automotive OEMs in Germany specify ceramic films for premium electric vehicle platforms where connectivity and thermal performance must coexist.
- Nanotechnology:Hybrid coating architectures capture margin pools from high-performance building projects seeking BREEAM and LEED certification with verified lifecycle data.
- Multi-layer Coating:Proprietary stack configurations differentiate established suppliers from mid-scale entrants constrained by sputtering equipment capex intensity.
- Micro-etched:Surface patterning technology serving niche signage applications where light diffusion properties take priority over thermal management.
Volume concentration: Metalized. Steepest expansion trajectory: Ceramic.
Application:
Customer procurement patterns diverge sharply between consultant-driven building retrofits and OEM-integrated automotive specifications.
- Building Insulation:Energy retrofit codes across the United States, Germany, and China compress specification cycles for commercial and residential glazing. Saint-Gobain anchors European demand through building insulation partnerships with major construction firms.
- Automotive Glazing:Electric vehicle manufacturers prioritize thermal load reduction to extend battery range. Ceramic-coated films gain specification in panoramic roof applications where electromagnetic interference transparency supports connectivity systems.
- Agriculture:Greenhouse operators deploy reflective films to optimize light distribution and reduce cooling loads, with demand concentrated in Mediterranean climate zones and protected cultivation clusters.
- Electronics:Display and device manufacturers specify ultra-thin films for thermal management in compact form factors.
- Signage:Advertising agencies and outdoor media companies utilize reflective films for visibility enhancement and weather resistance.
Revenue concentration: Building Insulation. Gaining share fastest: Automotive Glazing.
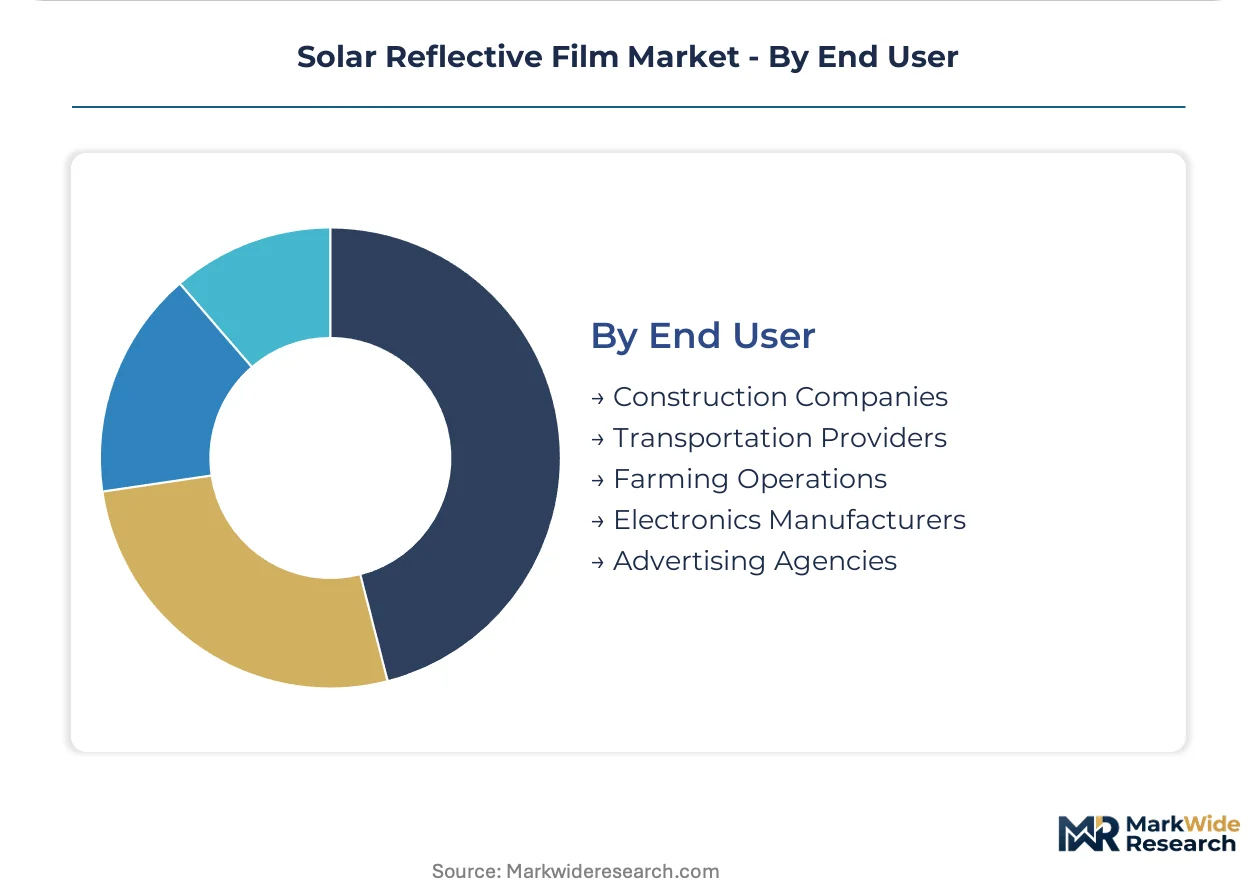
End User:
Procurement authority migration from general contractors to glazing subcontractors and energy consultants reshapes channel dynamics across end user categories.
- Construction Companies:Commercial and residential builders scale adoption to meet stricter building energy codes. The United States exhibits the most pronounced consultant-driven procurement, particularly in California and New York where local stretch codes exceed federal baselines.
- Transportation Providers:Automotive OEMs and fleet operators specify ceramic-coated films for thermal management in electric vehicle platforms.
- Farming Operations:Protected cultivation specialists in greenhouse-intensive regions deploy reflective films for climate control.
- Electronics Manufacturers:Device producers integrate films for thermal management in compact consumer electronics.
- Advertising Agencies:Outdoor media buyers prioritize durability and visibility performance in signage applications.
Dominant procurement volume: Construction Companies. Expanding most quickly: Transportation Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asian petrochemical clusters supply the polyester and polyethylene terephthalate substrates that anchor solar reflective film manufacturing across construction and automotive end markets.
United States
California and New York stretch codes exceed federal Energy Star baselines, compressing specification cycles for commercial glazing retrofits. EPA certification requirements fragment compliance terrain. Consultant-driven procurement in Los Angeles and New York City elevates certified testing laboratory relationships above brand loyalty.
China
Dual carbon goals under GB standards filter market access for imported films while scaling domestic production. MIIT efficiency benchmarks accelerate replacement cycles in high-rise commercial construction. Yangtze River Delta manufacturing clusters concentrate sputtering equipment investments serving both local retrofit demand and export markets.
Germany
EU Green Deal embodied carbon disclosure requirements reshape formulation decisions for construction-grade films. ECHA REACH mandates inflate certification timelines for non-EU suppliers. Bavaria and Baden-Württemberg automotive OEMs specify ceramic-coated films for premium electric vehicle panoramic roof applications.
India
Bureau of Indian Standards energy code adoption creates first-mover positioning for certified suppliers in high-rise glazing retrofits. CEA efficiency benchmarks filter specification authority toward glazing subcontractors. Mumbai and Delhi-NCR commercial construction clusters drive initial demand concentration as green building certification programs expand.
South Korea
Electric vehicle manufacturers prioritize thermal load reduction to extend battery range, specifying PET-based ceramic coatings. MFDS-aligned quality frameworks shape automotive glazing procurement. Seoul Capital Area and Busan-Ulsan industrial corridors concentrate film specification for domestic OEM platforms and export-oriented production.
Solar Reflective Film Market Competitive Landscape
Global majors compete with regional champions across certification capacity and substrate supply integration. Market structure tilts toward established multi-layer coating specialists with captive testing laboratory networks and backward-integrated polymer sourcing. Three archetypes dominate: vertically integrated chemical conglomerates with substrate production, specialized film coaters with proprietary sputtering configurations, and regional fabricators serving price-sensitive construction tiers. Competitive intensity concentrates on M&A for testing laboratory assets and geographic expansion into underpenetrated retrofit markets.
Within the chemical conglomerate tier, Eastman Chemical Company and Saint-Gobain exemplify substrate-to-film integration strategies that satisfy ECHA disclosure requirements. 3M occupies a position among multi-layer coating specialists, leveraging patent-protected sputtering architectures to sustain premium positioning in consultant-driven procurement channels. These three anchors represent divergent responses to regulatory fragmentation: captive polymer production, European regulatory compliance depth, and intellectual property-driven product differentiation respectively.
| Leading Market Players |
|---|
| 3M |
| Saint-Gobain |
| Eastman Chemical Company |
| Avery Dennison Corporation |
| Madico Inc |
| Garware Hi-Tech Films |
| Lintec Corporation |
| Solar Gard |
| Hanita Coatings |
| Others |
Pricing and Supply Chain Analysis
Multi-layer sputtered ceramic coatings are displacing legacy aluminum metalization across premium automotive and architectural segments, simultaneously compressing margin pools for conventional suppliers locked into depreciated vacuum chamber equipment while concentrating pricing power with patent-protected coating specialists. This technology transition reshapes cost economics by elevating capital intensity barriers for mid-scale entrants and tethering premium pricing to electromagnetic interference transparency certifications.
Pricing Analysis
Warranty-backed performance guarantees and certified testing laboratory relationships anchor premium pricing tiers, while unbundled commodity films compete on transactional spot pricing. Three-tier pricing structure across premium, standard, and economy levels separates ceramic-coated architectural films with BREEAM documentation from metalized retrofit grades and uncertified budget imports. Price differentiation hinges on REACH-compliant formulation transparency and jurisdiction-specific SHGC validation. Cost compression in standard metalized tiers is intensifying because Asian petrochemical supply tightness for polyester substrates transmits input pressure without full pricing power recovery. Construction companies in California and New York exhibit lowest price sensitivity due to stretch code compliance premiums, while Indian commercial retrofit buyers remain most price-sensitive pending Bureau of Indian Standards enforcement maturity.
Supply Chain Analysis
Polyester and polyethylene terephthalate substrate supply rests on Yangtze River Delta petrochemical clusters in China, South Korean specialty film producers, and German chemical conglomerates with captive polymer production. Sputtering equipment for metalized layer deposition draws from Japanese vacuum technology specialists and German precision engineering suppliers. Ceramic oxide precursors rely on Australian mineral sands and Chinese rare earth processing capacity. Single-source vulnerability concentrates in advanced sputtering chamber components where two Japanese equipment makers dominate global installations. Distribution runs through glazing subcontractors and energy consultants who control specification authority in consultant-driven procurement markets, particularly in the United States and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solar reflective film supply is structurally constrained by sputtering equipment lead times and certified testing laboratory capacity, propping pricing power for established multi-layer coating specialists with backward-integrated substrate production.
For Market Incumbents: Deploy multi-protocol certification capacity as the primary defensive lever. Expand captive testing laboratory networks in California and New York to capture stretch code compliance premiums before regional challengers achieve EPA Energy Star accreditation. Deepen backward integration into polyester substrate production to offset Asian petrochemical supply tightness and satisfy EU Green Deal embodied carbon disclosure requirements. Ceramic coating patent portfolios must be reinforced against nanotechnology convergence threats from South Korean automotive suppliers. For New Entrants and Emerging Players: Glazing subcontractors in Indian commercial construction represent the most penetrable channel partner type for first-mover positioning. Target Mumbai and Delhi-NCR high-rise retrofit clusters where Bureau of Indian Standards energy code adoption is compressing specification cycles without established incumbent relationships. Ceramic-coated films for electric vehicle panoramic roof applications offer white-space expansion as German and South Korean OEMs prioritize thermal load reduction. A certified testing laboratory partnership strategy accelerates market access faster than proprietary sputtering equipment investments. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by vertically integrated chemical conglomerates seeking REACH-compliant formulation capabilities and captive substrate supply. Long-term viability across the analysis window favors specialists with electromagnetic interference-transparent ceramic architectures and verified lifecycle data for BREEAM and LEED certification. Testing laboratory assets in consultant-driven procurement markets command scarcity premiums. The signal to watch is divergence between EPA Energy Star, EU Green Deal, and China's GB standards testing protocols, which could fragment product portfolios and inflate validation costs without commensurate pricing power recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Protocol Certification Investment | Parallel EPA Energy Star and EU Green Deal laboratory accreditation captures consultant-driven specification authority in California and Germany. |
| Backward Integration into Substrate Production | Captive polyester supply satisfies ECHA embodied carbon disclosure and insulates margin pressure from Asian petrochemical volatility. |
| Ceramic-Nanotechnology Coating Convergence | Hybrid architectures penetrate electromagnetic interference-transparent segments previously closed to aluminum metalization in connected vehicles. |
| Testing Laboratory Asset Acquisition | Certified validation capacity becomes primary competitive moat as specification authority migrates from general contractors to glazing subcontractors. |
| Indian Market Channel Partnership | Bureau of Indian Standards enforcement creates first-mover positioning in high-rise commercial retrofits before incumbent certification networks establish presence. |
Research Methodology
Trade data from customs authorities, SEC 10-K filings from listed chemical conglomerates, and EU ECHA REACH registration databases formed the secondary backbone of this analysis. Primary interviews with plant managers at polyester substrate producers, procurement leads at glazing subcontractors, technical R&D directors at coating specialists, and energy consultants in California and New York provided forward-looking specification trend validation. Bottom-up demand modeling across construction retrofit cycles and electric vehicle production platforms was triangulated against top-down petrochemical feedstock supply analysis.
Historical trendline analysis of metalized and ceramic coating technology adoption informed projection framework construction across the modeling period. Segmentation dimensions modeled include substrate type, coating technology architecture, application end-use, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles, new build penetration rates, and technology substitution elasticities. Forecast inputs incorporated MIIT efficiency benchmark enforcement timelines in China and stretch code adoption trajectories in New York and California.
Caveats apply where divergence between SHGC and VLT testing protocols across EPA Energy Star, EU Green Deal, and China's GB standards could materially shift the outlook through portfolio fragmentation and certification cost inflation. Forecasts reflect assumptions regarding petrochemical supply normalization, electric vehicle thermal management specification trajectories, and REACH chemical transparency enforcement intensity. A small set of named triggers warrants ongoing watch: Asian polyester substrate supply disruptions, ceramic coating patent litigation outcomes, and Indian Bureau of Indian Standards code enforcement acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Middle-East and Africa Thermal Spray Market
Coatings
Coating Binders Market
Coatings
Global Flat Glass Coatings Market
Coatings
North America Concrete Floor Coatings Market
Coatings
Corrosion Protection Polymer Coating Market
Coatings
Morocco Automotive OEM Coatings Market
Coatings
Asia-Pacific Anti-Friction Coatings Market
Coatings
Anti-Graffiti Coatings Market
Coatings
Acrylic Coating Market
Coatings
CVD Coating Technology Market
Coatings
South Korea Protective Coatings Market
Coatings
Plastic-Coated Wires Market
Coatings
Global Surface Protection Films Market
Coatings
Japan Protective Coatings Market
Coatings
Polymer Modified Cementitious Coatings Market
Coatings
Asia-Pacific Epoxy Powder Coatings Market