
 Heat Resistant Glass Market | 2026-2036
Heat Resistant Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Heat Resistant Glass Market Foresight
Asset-light leasing models for specialty glass production equipment are reconfiguring competitive entry barriers, allowing mid-scale fabricators to access tempering and coating lines without full capital commitment. SCHOTT AG leverages its captive melting capacity for borosilicate to sustain premium positioning in laboratory and industrial segments. AGC Inc. anchors Asia-Pacific supply through integrated float-to-temper operations. Saint-Gobain competes across architectural and automotive channels with controlled distribution networks spanning multiple continents.
Heat resistant glass withstands thermal shock through controlled thermal expansion coefficients, typically manufactured via tempering, lamination with intumescent interlayers, or borosilicate melting to achieve softening points above 820°C for industrial and safety applications. Tempered glass dominates volume in architectural fire-rating applications where building codes mandate specific resistance durations. Coated glass captures margin pools in high-performance facades where low-emissivity and heat-reflective layers add energy-efficiency value. Laminated glass extends into transportation and security segments where structural integrity under thermal stress determines specification.
FDA standards govern heat resistant glass in food-contact and appliance applications, while OSHA mandates thermal protection in industrial viewing ports and furnace enclosures. The EU Green Deal and F-Gas Regulation tighten embodied-carbon thresholds for construction materials, redirecting specification toward recyclable and low-carbon-intensity heat resistant formulations. Stakeholders must monitor evolving national building codes and carbon-border adjustments that will determine which manufacturing locations and product certifications secure market access.
Market Dynamics
EU Green Deal embodied-carbon thresholds and F-Gas Regulation thermal-performance mandates are compressing specification windows for heat resistant glass in commercial construction, forcing fabricators to requalify product lines for building-code compliance.
Growth Catalysts
- Passive house construction mandates:Germany's federal building efficiency standards require borosilicate and tempered grades in fire-rated partitions, expanding procurement volumes for facade fabricators serving commercial developments.
- REACH-compliant low-carbon formulations:ECHA restrictions on high-global-warming-potential blowing agents redirect specification toward recyclable heat resistant glass with verified lifecycle carbon footprints.
- Industrial furnace rebuild cycles:Steel and ceramics manufacturers in the Ruhr region are replacing legacy viewing ports with OSHA-compliant tempered assemblies, sustaining replacement demand for high-softening-point grades.
Market Restraints
- Borosilicate raw material concentration:Specialty silica and boron oxide supply concentrates among a limited set of chemical suppliers, creating input cost volatility for melt-based production.
- CE marking complexity:MDR and construction-product-regulation harmonized standards impose extended testing timelines for fire-rated glass assemblies, delaying market entry for new formulations.
- Polycarbonate thermal barrier substitution:Advanced engineering plastics with intumescent coatings capture share in transportation interior applications where weight reduction outweighs optical clarity requirements.
Strategic Opportunities
- CSRD-driven building retrofit mandates:Corporate sustainability reporting requirements accelerate facade replacement cycles in France and the Netherlands, opening specification windows for high-performance coated glass.
- Digital twin integration:Convergence of Building Information Modeling with thermal-performance simulation allows fabricators to pre-qualify custom heat resistant assemblies for specific project envelopes.
- Equipment leasing penetration:Asset-light tempering-line access enables mid-scale German and Polish fabricators to serve premium architectural segments without full capital commitment.
Industry Challenges
- Fire-test engineer scarcity:Qualified personnel for EN 1363 and EN 1364 furnace testing are concentrated among a limited set of notified bodies, creating certification bottlenecks for new product introductions.
- Float-to-temper coordination:Synchronizing raw glass supply with tempering furnace schedules requires precision logistics that smaller fabricators struggle to maintain during demand spikes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat Resistant Glass Market |
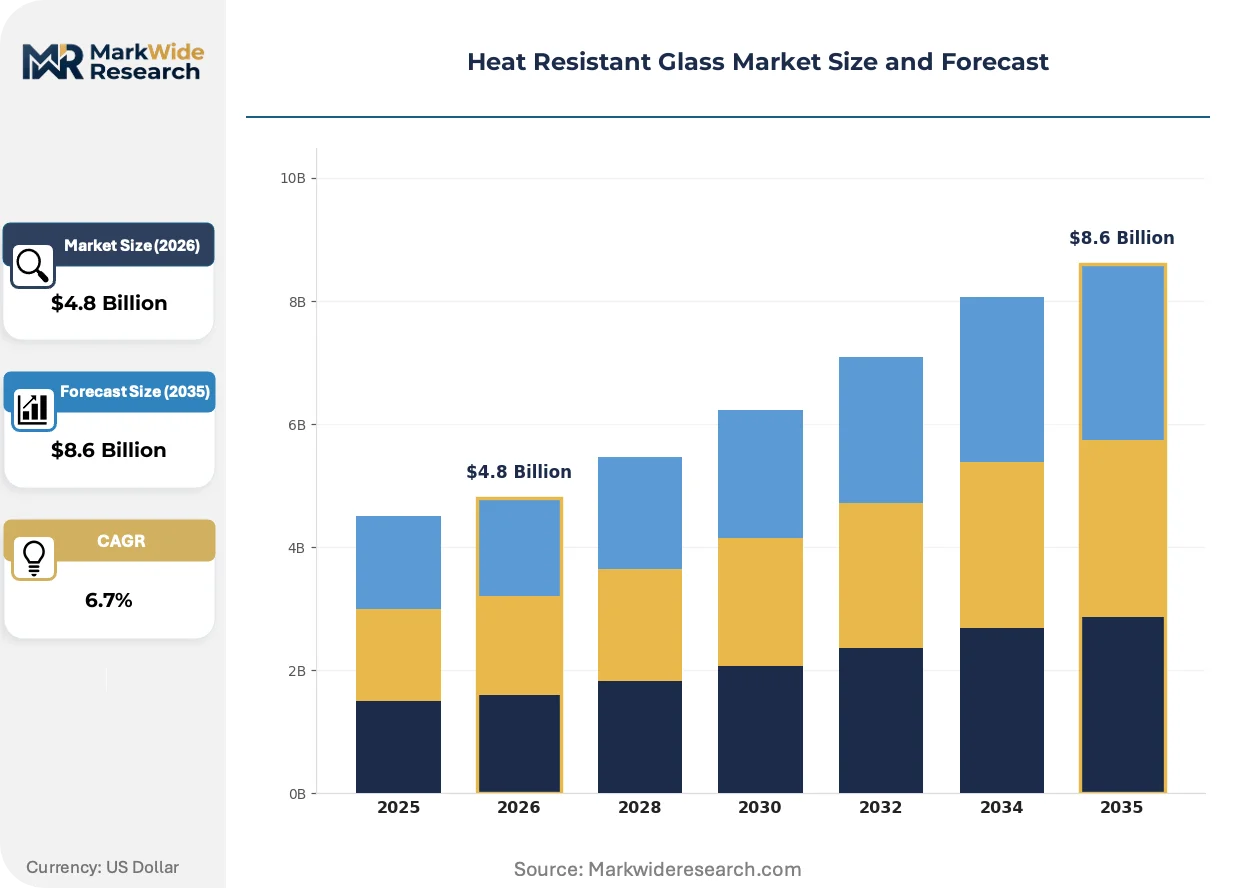
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tempered Glass, Laminated Glass, Insulated Glass, Coated Glass Application: Architectural, Automotive, Industrial, Kitchen End User: Construction, Automotive Manufacturers, Appliance Producers, Aerospace Distribution Channel: Direct Sales, Retail, Online, Wholesale |
| Companies Covered | Saint-Gobain, AGC Inc., SCHOTT AG, Nippon Sheet Glass Co. Ltd, Pyroguard, Technical Glass Products, Glas Trösch, Asahi India Glass Limited, POLFLAM Sp. z o.o., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat Resistant Glass Market Shifts & Advancements
Computational design and predictive thermal modeling are compressing product development cycles while regulatory pressure on embodied carbon forces material-science innovation in glass formulations.
Thin-film low-emissivity coatings with nanostructured metal-oxide layers are virtualizing traditional multi-pane insulating glass units. German facade engineers specify these monolithic alternatives for heritage building retrofits where weight constraints prohibit double-glazing. The technology is virtualizing the supply chain for high-performance architectural glass by collapsing fabrication steps and reducing transport costs.
F-Gas Regulation phase-down schedules for hydrofluorocarbons are tightening thermal-insulation requirements in commercial building envelopes. ECHA implementation timelines force glass processors to requalify intumescent interlayer chemistries before 2027 compliance deadlines. German and Dutch specification communities respond by front-loading procurement of certified fire-rated assemblies to lock in approved formulations.
Buyers are consolidating vendor relationships around full-service facade system integrators capable of warranting thermal performance across the complete assembly. This pattern displaces component-only procurement through independent glass distributors in commercial construction channels. The shift is most visible in Scandinavian markets where single-source accountability reduces liability exposure for developer-consortium project financing.
Heat Resistant Glass Market Segmentation
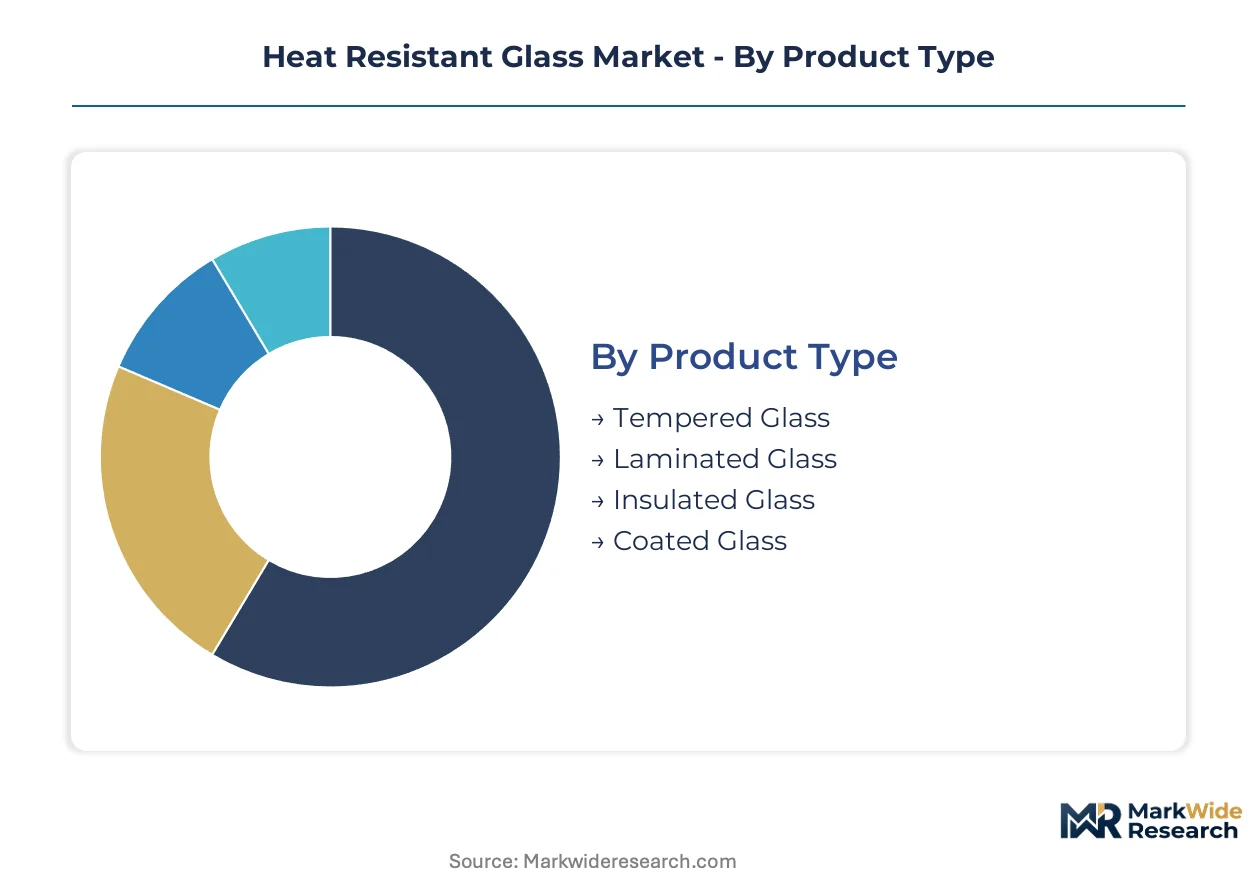
Segmentation in heat resistant glass determines specification pathways, certification requirements, and margin capture. Product chemistry, application thermal loads, and channel service intensity create distinct commercial territories with diverging competitive dynamics.
Product Type:
After-sales service intensity varies sharply across product categories, with coated and laminated grades demanding ongoing performance validation and warranty administration that reshapes distributor economics.
- Tempered Glass:Rapid thermal shock resistance derives from surface compression layers created through controlled quenching, yielding softening points above 600°C. German passive house builders and Ruhr industrial furnace operators specify tempered grades for fire-rated partitions and OSHA-compliant viewing assemblies, driven by federal building efficiency mandates and replacement cycles in steel manufacturing.
- Coated Glass:Nanostructured metal-oxide low-emissivity layers deliver thermal performance in monolithic configurations, collapsing traditional multi-pane fabrication steps. Dutch and French facade retrofit projects under CSRD reporting requirements are concentrating procurement of these high-margin formulations, where digital twin integration allows pre-qualification for specific envelope thermal profiles.
- Laminated Glass:Intumescent interlayers maintain structural integrity under thermal stress for transportation and security applications.
- Insulated Glass:Multi-pane assemblies with specialized spacer systems address heritage building constraints where weight limits prohibit conventional approaches.
Tempered glass holds the largest share; momentum sits with coated glass.
Application:
Cost tier stratification separates specification communities, with industrial and architectural buyers paying performance premiums while kitchen applications compete on landed cost.
- Architectural:Fire-rated facade assemblies and partition systems dominate volume, with EN 1363 and EN 1364 certification requirements creating qualification bottlenecks. German commercial developers front-load procurement of F-Gas Regulation-compliant assemblies to lock in approved formulations before ECHA deadlines.
- Industrial:High-softening-point borosilicate and tempered viewing ports serve steel, ceramics, and chemical processing equipment. Ruhr region furnace rebuild cycles sustain replacement demand, with OSHA thermal protection mandates specifying tempered assembly construction for operator safety.
- Automotive:Engine compartment glazing and thermal barrier applications specify heat resistant grades for under-hood visibility and fire containment.
- Kitchen:Appliance door panels and cookware applications fall under FDA food-contact standards, with price-sensitive specification patterns.
Architectural applications command the dominant revenue position; industrial retrofit cycles are climbing the fastest.
End User:
Customer type determines procurement modality, with construction buyers consolidating around full-service integrators while appliance producers maintain component-direct relationships.
- Construction:Developer-consortium project financing in Scandinavian markets drives single-source accountability, displacing independent glass distributors. Facade system integrators now warrant complete assembly thermal performance, compressing vendor relationships toward full-service partners capable of lifecycle liability coverage.
- Automotive Manufacturers:Weight reduction priorities and thermal management requirements specify heat resistant grades for electric vehicle battery enclosures and powertrain shielding.
- Appliance Producers:FDA-compliant formulations for oven doors and cooktop surfaces compete on volume scale and manufacturing consistency.
- Aerospace:Specialized thermal protection systems for engine nacelles and fire containment demand certified traceability and extreme temperature performance.
Construction end users represent the primary volume concentration; aerospace specifications carry the steepest expansion trajectory.
Distribution Channel:
Channel configuration reflects product complexity, with direct sales capturing premium architectural and industrial segments while wholesale handles standardized tempered volumes.
- Direct Sales:Large-format facade projects and industrial furnace contracts require application engineering support, thermal modeling validation, and warranty structuring that only manufacturer-direct relationships can deliver. German and Polish mid-scale fabricators leverage this channel for premium segment access.
- Wholesale:Standardized tempered and laminated grades for regional construction markets move through distributor networks with inventory risk transfer.
- Retail:Replacement kitchen appliance panels and small-format industrial viewing ports serve maintenance and repair demand.
- Online:Specification-grade procurement remains limited, with digital channels capturing only commodity replacement volumes.
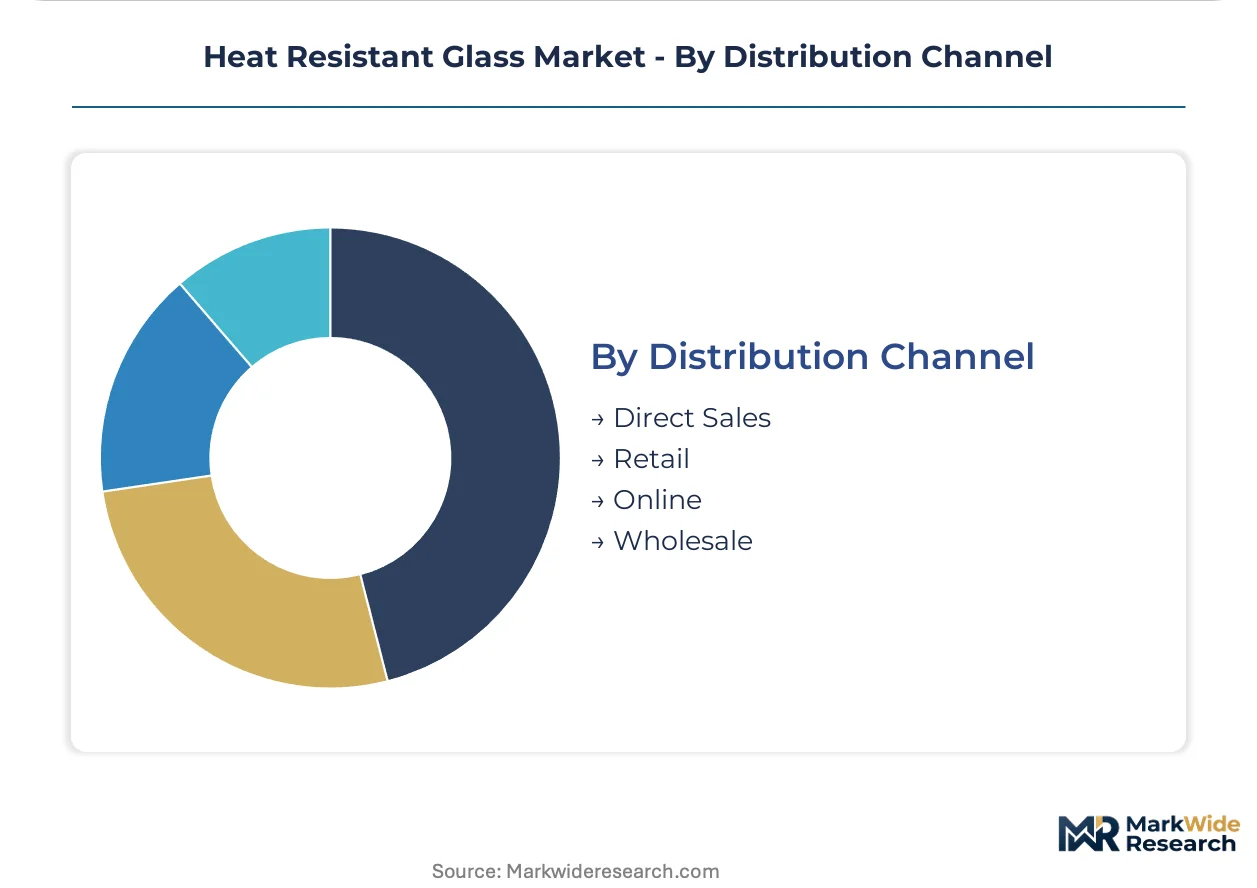
Direct sales channels dominate value capture; wholesale infrastructure handles the greatest unit velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German specification markets while Chinese supply zones compete on volume scale. EU regulatory stringency creates a two-tier geography where compliance-capable fabricators capture margin premiums. Regional demand patterns diverge sharply between passive house construction zones and industrial furnace replacement corridors.
Germany
Ruhr region steel manufacturers and Bavarian passive house developers drive dual demand streams for borosilicate viewing ports and fire-rated facade assemblies. The federal building efficiency standards and F-Gas Regulation implementation force rapid requalification of tempered and coated grades. Stuttgart and Munich architectural clusters front-load procurement to lock in certified formulations before ECHA deadlines.
France
CSRD reporting mandates accelerate facade retrofit cycles across Paris and Lyon commercial districts. The EU Green Deal embodied-carbon thresholds redirect specification toward low-carbon-intensity glass formulations. Île-de-France developer consortiums consolidate vendor relationships around full-service integrators capable of warranting complete assembly performance.
Netherlands
Randstad region heritage building retrofits specify nanostructured low-emissivity coatings where weight constraints prohibit double-glazing. Dutch building codes under EU Green Deal harmonization tighten thermal performance requirements for commercial envelopes. Eindhoven fabrication clusters leverage digital twin integration to pre-qualify custom assemblies for specific project thermal profiles.
China
Yangtze River Delta construction volume and Pearl River Delta industrial furnace rebuilds sustain tempered glass demand at scale. GB standards for fire-rated building materials and dual carbon goals redirect capacity toward energy-efficient formulations. Shanghai and Shenzhen fabrication zones coordinate float-to-temper logistics to serve domestic architectural and automotive channels.
United States
OSHA thermal protection mandates and passive house construction in Pacific Northwest and Northeast corridors drive specification of high-softening-point grades. FDA food-contact standards govern appliance and kitchen applications competing on landed cost. Texas and California industrial clusters sustain replacement demand for furnace viewing assemblies in petrochemical and steel processing.
Heat Resistant Glass Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in chemistry and melting. The vendor base organizes around three structural tiers: captive melters with borosilicate capacity, integrated float-to-temper operators, and mid-scale fabricators accessing equipment through lease arrangements. Two strategic archetypes dominate: full-service facade system integrators warranting assembly performance, and specialty glass producers with controlled distribution networks. Competitive moves concentrate on backward integration into raw material supply and geographic expansion through notified body certification stacking.
Within the captive melting tier, SCHOTT AG exemplifies premium positioning through in-house borosilicate capacity. AGC Inc. anchors Asia-Pacific supply through integrated operations spanning raw glass to finished tempering. Saint-Gobain occupies a position across architectural and automotive channels with multi-continent distribution infrastructure. These three represent the dominant competitive anchors against which mid-scale fabricators define lease-based entry strategies.
| Leading Market Players |
|---|
| Saint-Gobain |
| AGC Inc. |
| SCHOTT AG |
| Nippon Sheet Glass Co. Ltd |
| Pyroguard |
| Technical Glass Products |
| Glas Trösch |
| Asahi India Glass Limited |
| POLFLAM Sp. z o.o. |
| Others |
Supply & Pricing Matrix
Specialty silica and boron oxide supply concentrates among German and Chinese chemical suppliers, anchoring margin capture in downstream tempered and borosilicate grades where fabricators pass through input volatility via project-based pricing.
Pricing Analysis
Configured-to-order pricing for fire-rated facade assemblies commands substantial premiums over standard tempered volumes moving through wholesale channels. Price differentiation rests on EN 1363/EN 1364 certification tier and after-sales warranty bundling. Pricing pressure stems from polycarbonate thermal barrier substitution in transportation interiors where weight reduction trumps optical clarity. Kitchen appliance buyers exhibit highest price sensitivity, while German passive house developers absorb premiums for verified lifecycle carbon footprints.
Supply Chain Analysis
Contract manufacturing capacity concentrates with Saint-Gobain, AGC Inc., and SCHOTT AG across Germany, China, and Japan. Raw material supply draws from specialty silica deposits, boron oxide chemical processors, and float glass production lines. Single-source vulnerability concentrates in certified intumescent interlayer chemistry following ECHA restriction timelines. Distribution runs through direct sales for large-format architectural projects and wholesale networks for standardized tempered grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polycarbonate substitution with intumescent coatings threatens optical-clarity-dependent segments, forcing incumbents to articulate performance differentiation around thermal shock resistance and regulatory compliance durability.
For Market Incumbents: Harden certification stacking across multiple notified bodies to compress competitor entry timelines. Deepen backward integration into borosilicate melting capacity to defend margin pools against lease-enabled mid-scale fabricators. Prioritize digital twin integration investments that pre-qualify custom assemblies for specific envelope thermal profiles, locking out specification-stage competition.
For New Entrants and Emerging Players: Pursue equipment leasing arrangements for tempering lines serving Polish and Czech mid-scale fabricators lacking capital for full ownership. White-space concentrates in CSRD-driven facade retrofit cycles across Dutch and French commercial districts where heritage weight constraints favor nanostructured low-emissivity coatings. Go-to-market through Building Information Modeling partnerships that embed thermal-performance simulation into architect workflows.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European facade system integrators consolidating vendor relationships around single-source accountability. Long-term viability hinges on regulatory compliance durability across tightening EU Green Deal embodied-carbon thresholds and F-Gas Regulation phase-down schedules. Acquisition targets should demonstrate stacked notified body certifications and captive borosilicate or coating technology positions. Monitor ECHA implementation timelines for intumescent interlayer restrictions as inflection signals for formulation obsolescence risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Borosilicate Melting | SCHOTT AG's captive capacity anchors premium positioning against lease-dependent competitors. |
| Digital Twin Integration for Pre-Qualification | Eindhoven fabrication clusters embed thermal modeling into architect specification workflows. |
| Equipment Leasing Penetration | Mid-scale German and Polish fabricators access tempering lines without full capital commitment. |
| Certification Stacking Across Notified Bodies | Fire-test engineer scarcity creates bottlenecks that multi-certified suppliers exploit for margin defense. |
| CSRD-Driven Retrofit Channel Development | Paris and Lyon developer consortiums consolidate around integrators warranting complete assembly performance. |
Research Methodology
Operator-level perspectives from facade system integrators, tempering line operators, passive house developers, and ECHA regulatory affairs specialists anchored the qualitative base. Primary fieldwork combined with secondary validation from EU construction-product-regulation harmonized standards documentation, SEC filings of listed glass manufacturers, German federal building efficiency standard releases, and customs data tracking specialty silica and boron oxide trade flows. Bottom-up project pipeline analysis triangulated against top-down macro construction spend models.
Scenario-bracketing framed volume and value outputs across the analysis window, with segmentation modeling across product chemistry, application thermal load, end-user procurement modality, and channel service intensity. CAGRs derived from fitted growth curves applied to disclosed capacity expansions and replacement cycle timing. Industry-specific forecast inputs included EN 1363/EN 1364 certification backlog durations and ECHA restriction implementation timelines.
Macroeconomic conditions sit as an overlay; deviation in commercial construction lending rates or EU carbon-border adjustment stringency would shift the trajectory. Quarterly review of notified body certification queue lengths and intumescent interlayer formulation approval statuses is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Antibacterial Glass Market
Glass
Laboratory Glass Container Market
Glass
Glass Mason Jars Market
Glass
Solar PV Glass Market
Glass
3D Glass Substrate Market
Glass
Europe Glass Insulators Market
Glass
Glass Mat Market
Glass
Coated Solar Control Glass Market
Glass
Optical Lens Material Market
Glass
Birefringent Crystals Market
Glass
Global Laminated Glass Market
Glass
Global Glass Flake Coatings Market
Glass
Coated Glass Market
Glass
Glass Polishing Powder Market
Glass
Paper Glass Maker Market
Glass
Glass Tableware Market