
 Sapphire Glass Market | 2026-2036
Sapphire Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Sapphire Glass Market Intelligence
A shift from single-source boule procurement to multi-vendor sourcing for finished components is recalibrating supply chain strategies. Saint-Gobain leverages its diversified materials science portfolio to serve aerospace and industrial sectors. Monocrystal specializes in large-diameter sapphire growth for LED and electronics substrates. Kyocera Corporation competes with its deep expertise in ceramic and electronic component manufacturing, offering integrated solutions for various end-use applications.
Sapphire glass is a synthetically produced crystal, second only to diamond in hardness, composed of pure aluminum oxide (Al2O3). It is grown at high temperatures using methods like the Kyropoulos process and valued for its extreme scratch resistance and transparency. Consumer electronics applications represent the largest source of demand, primarily for camera lens covers and smartwatch faces. Sapphire substrates for micro-LED and semiconductor fabrication constitute a critical, high-purity segment.
Material standards for aerospace applications are governed by bodies like the FAA in the United States and the European Union Aviation Safety Agency (EASA). Medical device components must comply with regulations from authorities such as the US FDA and China's NMPA, ensuring biocompatibility. Stakeholder success will hinge on navigating cost-performance trade-offs against competing hardened glass technologies for mass-market adoption.
Market Dynamics
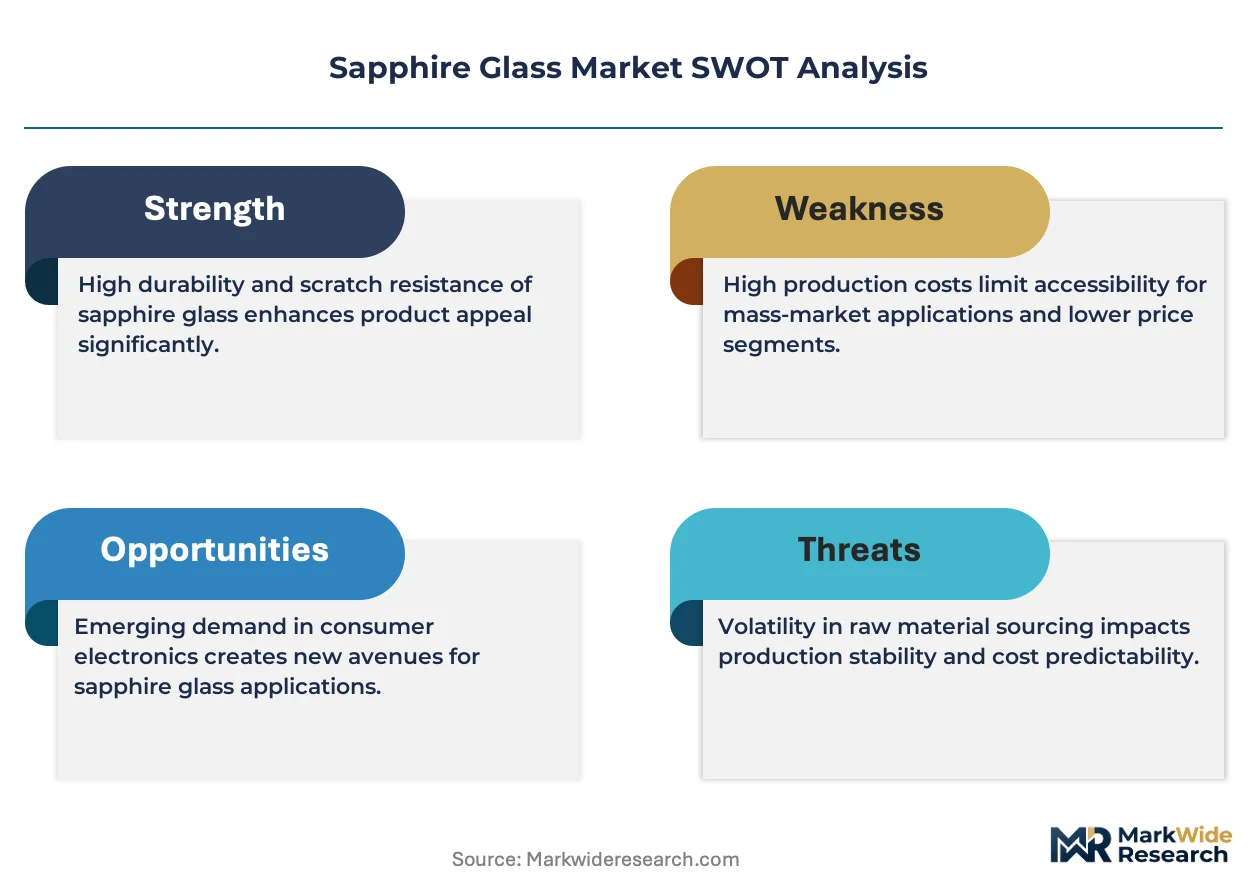
The fundamental market dynamic is the tension between the material's superior hardness and transparency, which commands premium pricing, and the intense cost-down pressure from high-volume consumer electronics supply chains seeking viable, lower-cost alternatives like chemically hardened glass.
Growth Catalysts
- Micro-LED Substrates:The development of micro-LED display technology creates a significant pull for high-purity, large-diameter sapphire substrates, which are essential for the gallium nitride (GaN) epitaxial growth process.
- Luxury Wearables:Expansion in the luxury smartwatch and high-end consumer electronics segments sustains demand for sapphire glass as a premium, scratch-resistant material for watch faces and camera lens covers.
- Aerospace Modernization:Stringent material performance standards from bodies like the FAA and EASA for sensor windows and cockpit displays in next-generation aircraft favor sapphire's durability and optical clarity in harsh environments.
Market Restraints
- High Production Cost:The energy-intensive nature of crystal growth methods, such as the Kyropoulos process, combined with long production cycles, results in a high unit cost compared to competing materials.
- Substitution from Hardened Glass:Advanced aluminosilicate and lithium aluminosilicate (LAS) glasses present a significant substitution threat, offering improved drop resistance and a more favorable cost structure for smartphone screens.
- Processing Complexity:The extreme hardness of sapphire makes cutting, grinding, and polishing it into finished components a difficult and costly process, requiring specialized diamond tooling and increasing manufacturing waste.
Strategic Opportunities
- Medical Device Components:There is an opportunity in manufacturing biocompatible windows for medical endoscopes, surgical tools, and implantable electronic devices, which must meet strict regulatory standards from the US FDA and China's NMPA.
- Durable Optical Sensors:Integrating sapphire into optical sensors for industrial automation, autonomous vehicles, and public infrastructure provides a durable, transparent protective layer that extends operational life in abrasive conditions.
- Defense and Security Applications:Underpenetrated defense markets seek sapphire for applications in transparent armor, missile domes, and multispectral imaging systems that require superior ballistic performance and optical transmission across a wide wavelength range.
Industry Challenges
- Yield Improvement for Large Diameters:Consistently achieving low-defect, high-yield production runs for sapphire boules greater than eight inches in diameter remains a primary technical and capital-intensive challenge for crystal growers.
- Lack of Grading Standardization:The absence of globally recognized, uniform standards for sapphire's mechanical and non-optical properties creates inconsistencies and complicates procurement for buyers outside the established LED substrate market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sapphire Glass Market |
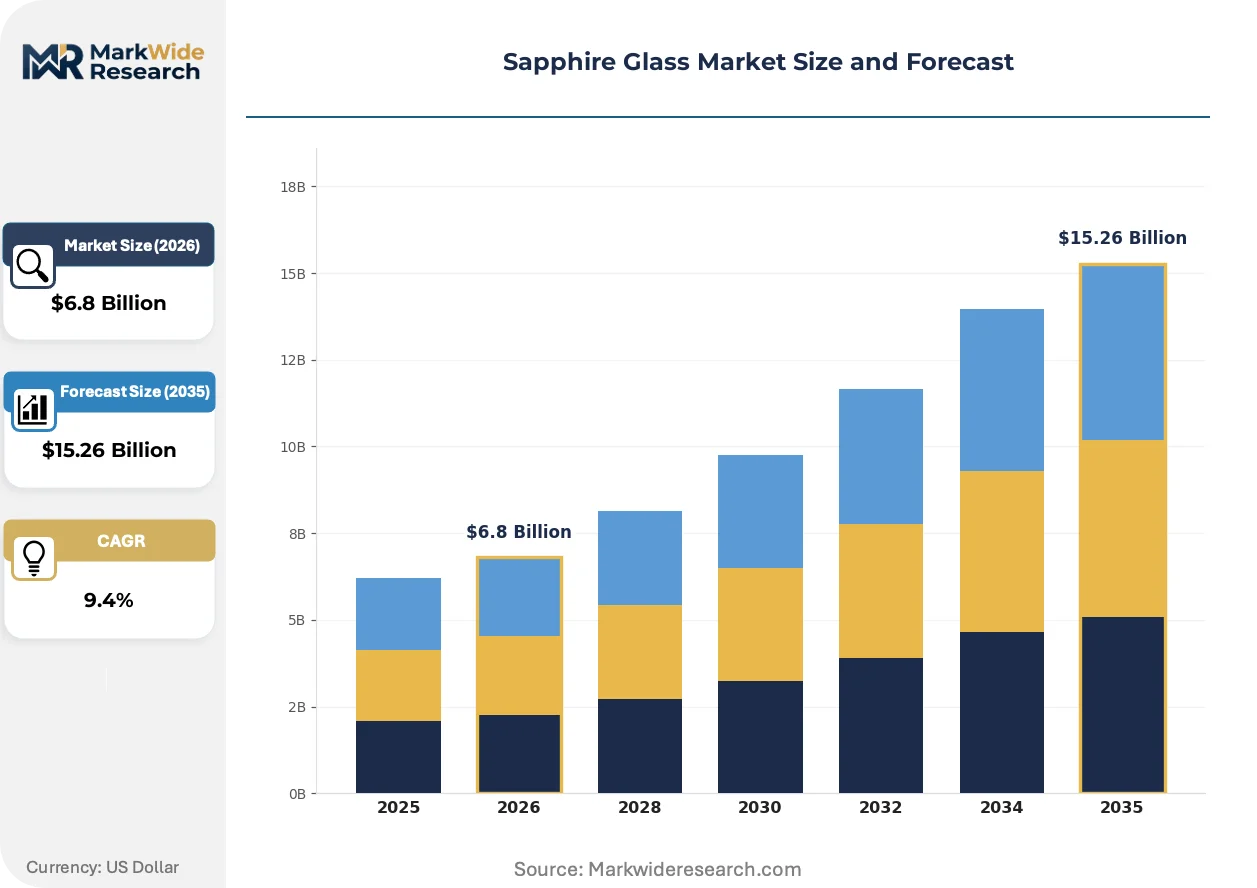
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Substrates, Windows, Lenses, Covers Application: Consumer Electronics, Aerospace, Medical Devices, Automotive End User: Manufacturers, Research Institutions, OEMs, Consumer Distribution Channel: Online Retail, Distributors, Direct Sales, Specialty Stores |
| Companies Covered | Morgan Advanced Materials, Rubicon Technology, Precision Sapphire Technologies, Monocrystal, Saint-Gobain, II-VI Optical Systems, Coorstek Corporation, Schott AG, Kyocera Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sapphire Glass Market Strategic Shifts & Innovations
The market's trajectory is defined by a push toward higher material purity and larger, more complex component geometries. This evolution is a direct response to the performance requirements of next-generation applications in micro-LED displays and advanced optical systems.
Large-diameter sapphire substrates provide a chemically and thermally stable foundation for the epitaxial growth of light-emitting diodes. Display manufacturers and semiconductor foundries are steadily adopting these larger formats to improve production throughput and reduce per-device costs. The availability of uniform, six-inch and eight-inch sapphire wafers is electrifying the micro-LED ecosystem, enabling the potential for mass-market commercialization of this new display technology.
Heightened regulatory scrutiny over material safety and traceability, particularly under the EU's Medical Device Regulation (MDR), is influencing material selection. This framework mandates comprehensive documentation of a material's lifecycle and biocompatibility for any component used in medical devices. Consequently, suppliers of sapphire for surgical instruments and diagnostic equipment must now provide extensive validation data, favoring producers with robust quality management systems like ISO 13485.
A notable behavioral change involves a move away from purchasing raw sapphire boules toward sourcing finished, application-specific components from a network of specialized fabricators. This unbundling of the supply chain allows consumer electronics OEMs in South Korea and Taiwan to reduce in-house capital expenditure and increase supplier flexibility. The shift is most pronounced in the fast-paced smartphone camera lens cover and smartwatch crystal segments, where rapid design changes benefit from an agile, multi-vendor sourcing strategy.
Sapphire Glass Market Segmentation
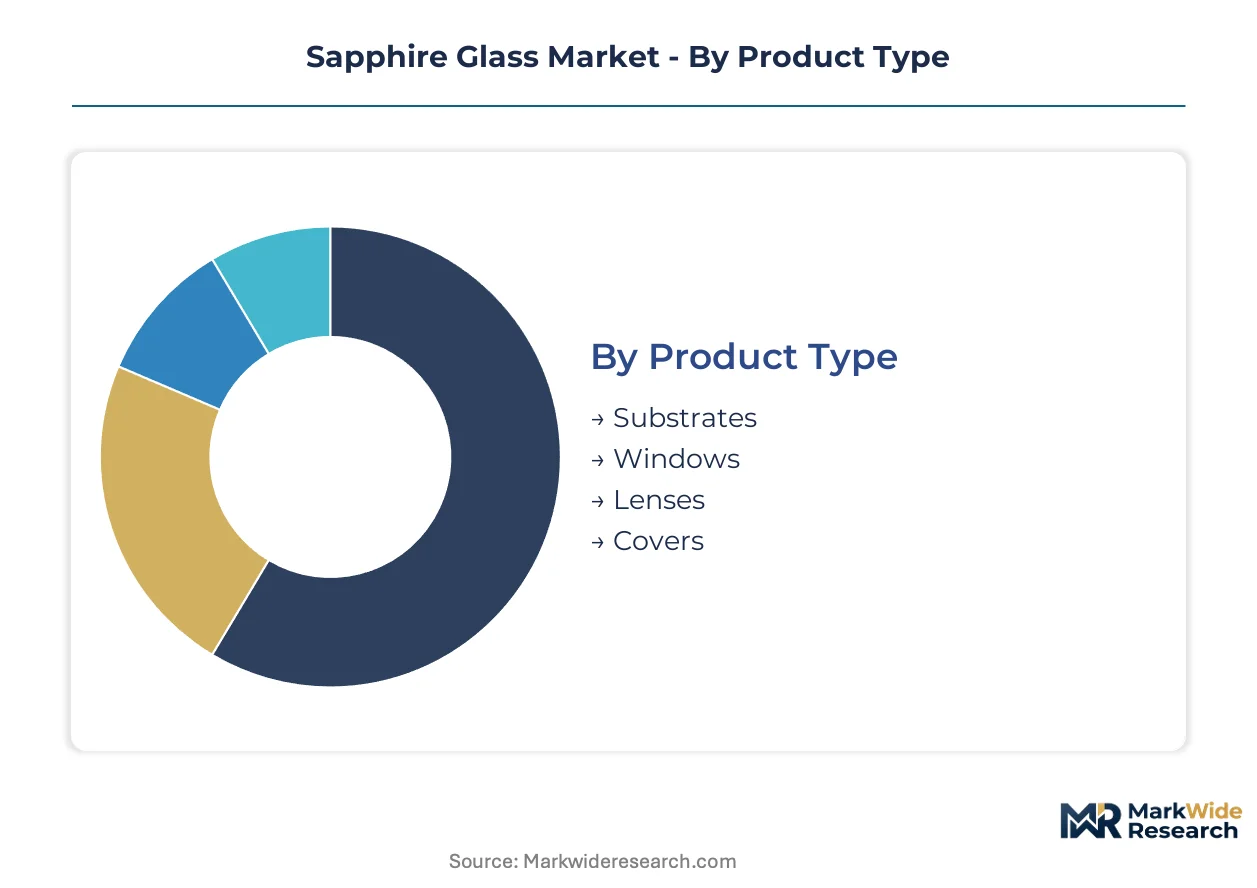
The sapphire glass market is segmented to provide a granular understanding of its diverse applications and procurement dynamics. This segmentation clarifies how different product forms, end-use applications, and distribution channels influence material specifications and market value across the industry.
Product Type:
Different product types of sapphire glass face varying regulatory hurdles, with some requiring stringent approvals from bodies like the US FDA or EASA.
- Substrates:These are high-purity, single-crystal aluminum oxide wafers used as foundational layers for advanced electronic components. Demand concentrates in South Korea and Taiwan for micro-LED and semiconductor fabrication, driven by the need for chemically and thermally stable platforms.
- Windows:Optically transparent, highly durable sapphire panels serve as protective covers or sensor interfaces in demanding environments. Aerospace modernization in Europe and North America drives demand for FAA and EASA certified sensor windows due to superior optical clarity and scratch resistance.
- Lenses:Precision-ground sapphire components are utilized in optical systems requiring extreme hardness and transparency for imaging or sensing.
- Covers:Thin, scratch-resistant sapphire sheets primarily protect displays and camera modules in high-end consumer electronics.
Leading the category by volume: Covers. Growing fastest: Substrates.
Application:
The application segments for sapphire glass exhibit distinct cost-performance trade-offs, influencing material selection and market adoption.
- Consumer Electronics:Sapphire glass protects smartwatch faces and smartphone camera lenses, valued for its extreme scratch resistance in high-volume mass-market devices. Demand concentrates in China and Taiwan, driven by design aesthetics and durability requirements.
- Medical Devices:Biocompatible sapphire components are crucial for endoscopes, surgical tools, and implantable sensors, requiring rigorous NMPA and US FDA compliance. High-purity sapphire ensures chemical inertness and optical clarity in critical diagnostic and therapeutic instruments.
- Aerospace:Durable sapphire windows and domes are essential for aircraft sensors and cockpit displays, meeting FAA and EASA performance standards in harsh operational conditions.
- Automotive:Sapphire is considered for advanced driver-assistance systems (ADAS) sensor covers and interior displays, providing extreme scratch resistance against environmental wear.
Consumer Electronics drives the largest volume, while Medical Devices commands premium margins due to stringent regulatory requirements.
End User:
The end-user landscape for sapphire glass reflects distinct patterns of supply chain engagement, from direct procurement to specialized fabrication.
- OEMs:Original equipment manufacturers integrate finished sapphire components into their products, leveraging multi-vendor sourcing for supply chain agility. South Korean and Taiwanese electronics OEMs drive significant sapphire component demand for their consumer devices.
- Manufacturers:These entities process raw sapphire boules into specific forms like wafers or finished parts for diverse industries, managing complex fabrication processes. Crystal growers and fabricators in China and Japan supply these specialized components.
- Research Institutions:Academic and corporate laboratories utilize high-purity sapphire for advanced material science experiments and optical system development.
- Consumer:End-users indirectly purchase sapphire glass within finished products like smartwatches and high-end smartphones, valuing the material's inherent durability.
OEMs represent the largest customer segment, while Research Institutions drive innovation in niche applications.
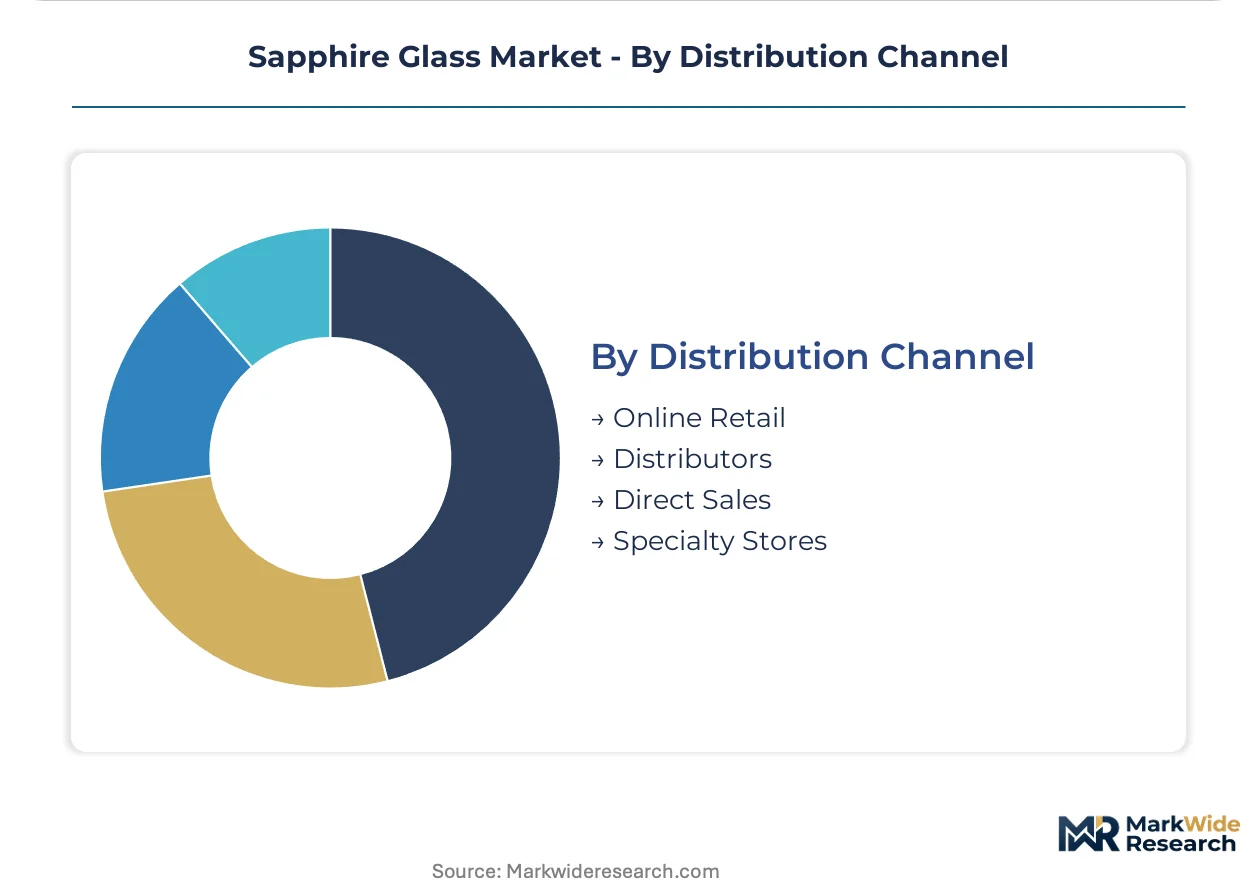
Distribution Channel:
Distribution channels for sapphire glass vary in maturity and efficiency, reflecting the specialized nature of the material and its end-use markets.
- Direct Sales:Major sapphire producers engage directly with large-volume OEMs and aerospace contractors, offering customized solutions and technical support. This channel is prevalent for high-value substrates and specialized optical windows.
- Distributors:These intermediaries provide regional access and inventory management for a broader customer base, including smaller manufacturers and research laboratories. Distributors often handle standard sapphire components across Europe and North America.
- Online Retail:E-commerce platforms facilitate procurement of standard sapphire components and small-volume orders, particularly for prototyping and niche applications.
- Specialty Stores:These outlets cater to specific markets like luxury watch repair or custom optical fabrication, offering specialized sapphire parts and services.
Direct Sales offers high efficiency for large-scale industrial buyers, while Distributors provide broader market reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global sapphire glass market's geographic footprint is anchored by regions with advanced electronics manufacturing and high-tech industries. These areas drive demand for scratch-resistant components and high-purity substrates. Significant production and consumption centers exist across Asia and North America.
China
Demand for sapphire glass in China is propelled by its vast consumer electronics manufacturing base and micro-LED development. The country's dual carbon goals also encourage energy-efficient production methods for material science. Manufacturing hubs like Shenzhen and the Yangtze River Delta concentrate significant production of camera lens covers and display substrates.
South Korea
South Korea's robust semiconductor and display industries create substantial pull for large-diameter sapphire substrates. The MFDS regulations ensure material quality for medical device components, a growing application area. Seoul and Gyeonggi Province house major OEMs and fabricators that integrate sapphire into premium consumer devices.
United States
Aerospace modernization and defense applications drive significant sapphire glass demand in the United States. FAA regulations mandate stringent performance standards for sensor windows and cockpit displays. Silicon Valley and the aerospace clusters in Seattle and Wichita foster innovation in optical systems and advanced material integration.
Japan
Precision engineering and advanced optical systems in Japan sustain demand for sapphire lenses and substrates. METI initiatives support high-purity material research and development for next-generation displays. Osaka and Tokyo host specialized fabricators and research institutions focused on complex sapphire component geometries.
Germany
Europe's industrial heartland, Germany, utilizes sapphire glass for high-durability industrial sensors and medical devices. CE marking and the EU MDR dictate strict compliance for biocompatible sapphire components. Bavaria and Baden-Württemberg are centers for automotive and industrial automation, integrating sapphire into durable optical systems.
Sapphire Glass Market Key Industry Players
Portfolio diversification dominates the current landscape as companies seek to mitigate reliance on single-market segments. The market exhibits a tiered structure, with a few large, integrated materials science companies alongside numerous specialized fabricators. Strategic archetypes include raw material growers, precision component manufacturers, and integrated solutions providers. Strategic partnerships and technology licensing are prevalent competitive moves, accelerating innovation in sapphire crystal growth.
Specialists in large-diameter sapphire growth, such as Monocrystal, exemplify the focus on high-purity substrates for advanced electronics. Saint-Gobain, with its diversified materials science portfolio, occupies a position serving both aerospace and industrial sectors. Kyocera Corporation represents the archetype of a vertically integrated manufacturer, leveraging deep expertise in ceramic and electronic components to offer integrated sapphire solutions. These entities collectively shape the supply dynamics for various end-use applications.
| Leading Market Players |
|---|
| Morgan Advanced Materials |
| Rubicon Technology |
| Precision Sapphire Technologies |
| Monocrystal |
| Saint-Gobain |
| II-VI Optical Systems |
| Coorstek Corporation |
| Schott AG |
| Kyocera Corporation |
| Others |
Cost & Logistics Intelligence
South Korean and Taiwanese consumer electronics OEMs, seeking supply flexibility, influence a transactional, per-unit pricing model for finished sapphire components. This model balances material cost with processing complexity.
Pricing Analysis
Warranty and after-sales service are often unbundled from the core sapphire component price, allowing for customized support agreements. The dominant pricing model is per-unit transactional, varying significantly by component complexity and purity. Price differentiation stems from the sapphire's quality grade, specific regulatory certifications like FAA or US FDA compliance, and volume scale. High-volume consumer electronics segments exert downward pricing pressure. Medical device and aerospace applications demonstrate lower price sensitivity due to stringent performance requirements.
Supply Chain Analysis
Reverse logistics for sapphire components are minimal, given the material's extreme hardness and processing costs, making refurbishment uneconomical. Supply concentration centers on China, South Korea, and Japan for boule growth and fabrication. The supply chain depends on consistent access to high-purity aluminum oxide and specialized diamond tooling. A structural risk involves single-source vulnerability for large-diameter boules. Direct sales dominate for large-volume OEMs, while distributors serve smaller manufacturers and research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sapphire glass market is supply-constrained, with consistently achieving low-defect, high-yield production for large-diameter boules acting as a significant capacity bottleneck. This technical challenge props up premium pricing for high-purity substrates.
For Market Incumbents: Deploy advanced crystal growth R&D to continuously improve yields for large-diameter sapphire boules, mitigating the threat of substitution from advanced hardened glass. Incumbents should also invest in expanding specialized fabrication capacity in key regions like South Korea and Japan to meet evolving OEM demands. Pursuing additional regulatory certifications, such as for medical devices or aerospace, strengthens market position against emerging players.
For New Entrants and Emerging Players: Specialized fabricators and engineering firms represent a key channel to penetrate niche applications where incumbents lack agility. New entrants should target underpenetrated segments like medical device components or durable optical sensors for industrial automation. The medical device market, with its high-margin and stringent US FDA and NMPA compliance, is particularly penetrable. A go-to-market angle focusing on rapid prototyping and application-specific component design can differentiate offerings.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers seeking to consolidate specialized fabrication capabilities for sapphire. Long-term viability remains strong for high-purity substrates and application-specific components over the next 5-10 years. Vertically integrated mid-cap specialists in crystal growth or precision fabrication represent attractive acquisition targets. Investors should monitor commercialization milestones for micro-LED displays as a key inflection indicator for substrate demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Large-Diameter Boule Production | Addresses foundational supply constraints for micro-LED and advanced electronics substrates. |
| Acquire Precision Fabrication Specialists | Enhances capabilities for complex component geometries and reduces reliance on external processing. |
| Invest in Medical Device Certifications | Unlocks access to high-margin medical markets requiring US FDA and EU MDR compliance. |
| Develop Advanced Diamond Tooling | Improves processing efficiency and reduces waste associated with sapphire's extreme hardness. |
| Form Partnerships for Micro-LED Integration | Secures long-term demand by embedding sapphire into next-generation display technologies. |
Research Approach
Multi-period observation of production yields and material purity specifications anchored the trend analysis, supplemented by interviews with key industry stakeholders. Primary research involved discussions with crystal growers, component fabricators, OEM procurement leads, and R&D scientists. Secondary validation drew from company financial filings, trade association reports, and regulatory body publications like FAA and US FDA. This approach enabled bottom-up and top-down triangulation of market data.
Segment weighting by product type, application, end-user, and distribution channel formed the basis of the quantitative forecast model. This analytical framework projects market evolution across the analysis window, incorporating material purity grade. Compound Annual Growth Rates were derived from historical growth trends and projected technology adoption curves. Micro-LED display roadmaps and aerospace modernization budgets informed forecast inputs.
Caveats apply where energy price volatility or new hardened glass breakthroughs could materially shift the outlook. Forecasts reflect assumptions regarding technological advancements and stable geopolitical trade policies. Practitioners should monitor micro-LED commercialization progress for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
North America and Australia Silica Market
Glass
Glazing Gel Market
Glass
Glass Lined Equipment Market
Glass
Screen-Printing Glass Market
Glass
Glass Forming Machine Market
Glass
Silica Sand Market
Glass
Heat Resistant Glass Market
Glass
Ultra Violet Glass Bottles Market
Glass
Coated Solar Control Glass Market
Glass
Impact Resistant Glass Market
Glass
Advanced Glass Market
Glass
Asia-Pacific Glassware Market
Glass
Foam Glass Granulate Market
Glass
Technical Glass Market
Glass
Asia Pacific Flexible Glass Market
Glass
Middle East and Africa Glassware Market