
 Solar PV Junction Box Market | 2026-2036
Solar PV Junction Box Market Size, Share, and Industry Trends Forecast 2026-2036
Solar PV Junction Box Market Intelligence
Modular unbundling of power electronics from the junction box enclosure is decoupling procurement decisions for Indian EPC contractors. QC Solar leverages backward integration into diode and connector production to control cost structures. SolarEdge Technologies differentiates through embedded power optimizer architectures that bypass traditional junction box functions. Amphenol Industrial Products Group anchors its position via sealed connector expertise suited to coastal and desert installations.
A solar PV junction box is an electrical enclosure mounted on the rear side of photovoltaic modules, housing bypass diodes, terminal blocks, and cable connectors to protect against hot-spot failures and enable series string connectivity. The assembly typically employs polyamide housings with silicone gasket sealing to achieve IP67 ingress protection against dust and moisture in outdoor environments. Waterproof junction boxes capture premium positioning as floating PV systems and monsoon-exposed installations expand across India's eastern and western coasts. Combiner boxes represent the fastest-growing product configuration as utility-scale developers consolidate string outputs before inverter coupling. Polymeric sealing technologies dominate manufacturing throughput due to lower cycle times versus gasket-intensive alternatives.
BIS mandates IEC 62790 certification for junction boxes deployed in Indian solar projects, compelling manufacturers to submit thermal cycling and damp-heat test documentation before commercial supply. The Central Electricity Authority's technical standards for grid-connected solar plants specify flame-retardant housing materials and overvoltage protection thresholds that shape product design priorities. CEA notification requirements on module-level monitoring are pushing integration of smart sensing capabilities into junction box architectures. Stakeholders must weigh the capital cost of dual-certification against the revenue access that BIS plus IEC compliance unlocks across domestic and export markets.
Market Dynamics
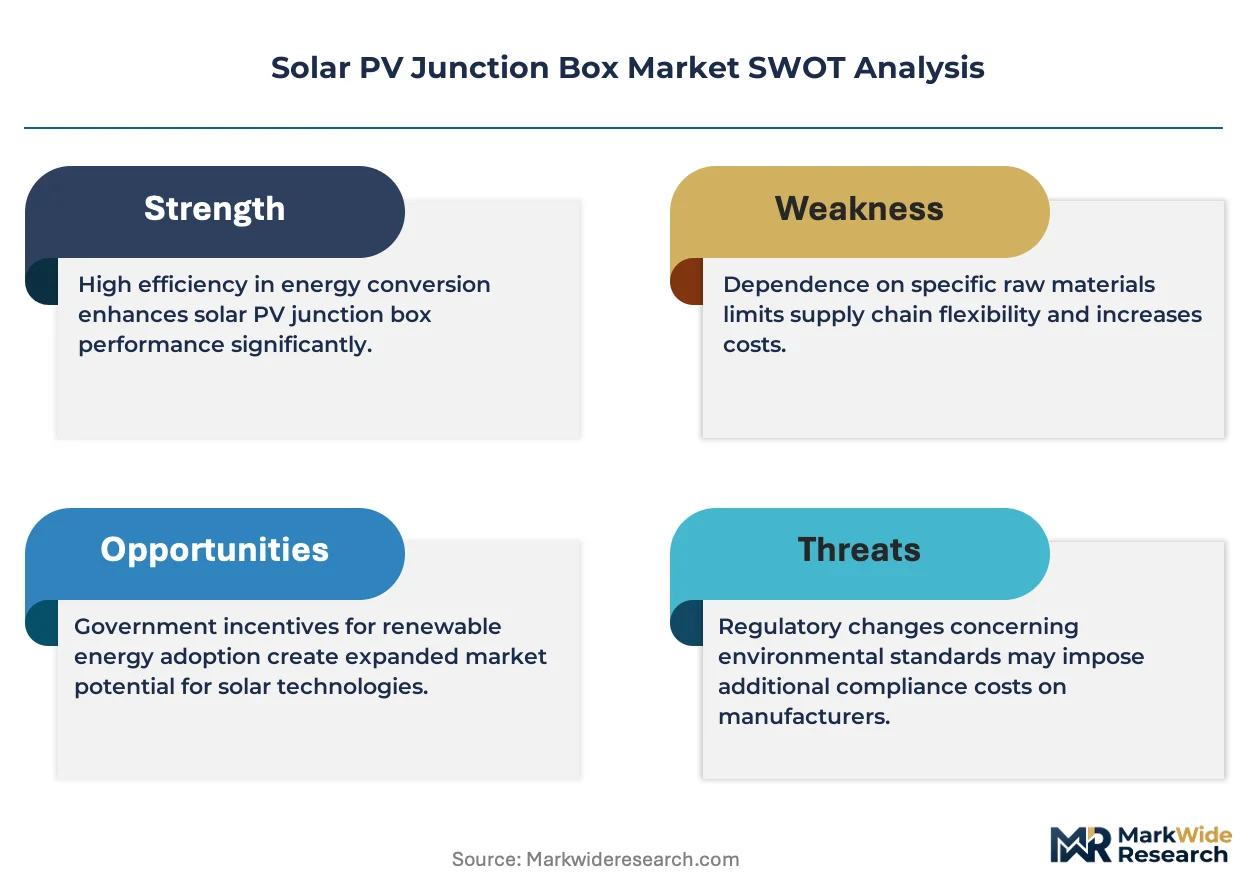
Modular decoupling of power electronics from junction box housings is fragmenting procurement decisions among Indian EPC contractors, forcing suppliers to compete on component specialization rather than bundled enclosure sales.
Growth Catalysts
- CEA notification requirements:Module-level monitoring mandates from India's Central Electricity Authority are embedding smart sensing architectures into junction box designs, creating pull-through demand for intelligent enclosures.
- Gujarat-Rajasthan-Karnataka corridor:Gigawatt-scale solar park pipelines in these three states concentrate demand for IP65-rated and IP67-rated junction boxes at volumes that justify dedicated manufacturing capacity.
- Floating PV expansion:Waterproof junction box specifications are tightening as monsoon-exposed and floating installations proliferate across India's eastern and western coastlines, elevating sealing performance requirements.
Market Restraints
- Polyamide resin cost volatility:Housing material input prices fluctuate with crude oil derivatives, compressing margin buffers for manufacturers locked into fixed-price utility contracts.
- Connector supply concentration:Sealed connector expertise clusters among a narrow supplier base, creating single-source vulnerability for junction box assemblers dependent on specialized maritime-grade components.
- BIS-IEC dual certification burden:Manufacturers must submit thermal cycling and damp-heat documentation to both BIS and IEC regimes, extending commercialization timelines and raising compliance overhead.
Strategic Opportunities
- Combiner box configuration growth:Utility-scale developers are consolidating string outputs before inverter coupling, expanding the addressable market for higher-capacity enclosure architectures.
- Backward integration into diodes:Captive production of bypass diodes and terminal blocks allows cost structure control unavailable to pure assembly competitors.
- PLI scheme alignment:India's production-linked incentive schemes for solar component manufacturing reward domestic value addition, favoring local assembly over imported finished goods.
Industry Challenges
- Polymeric sealing cycle time gaps:Lower-throughput gasket-intensive alternatives compete with dominant polymeric sealing technologies, forcing manufacturers to balance speed against performance differentiation.
- Smart sensing integration complexity:Embedding monitoring electronics into traditional junction box form factors requires thermal management and electromagnetic compatibility engineering that strains legacy design teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar PV Junction Box Market |
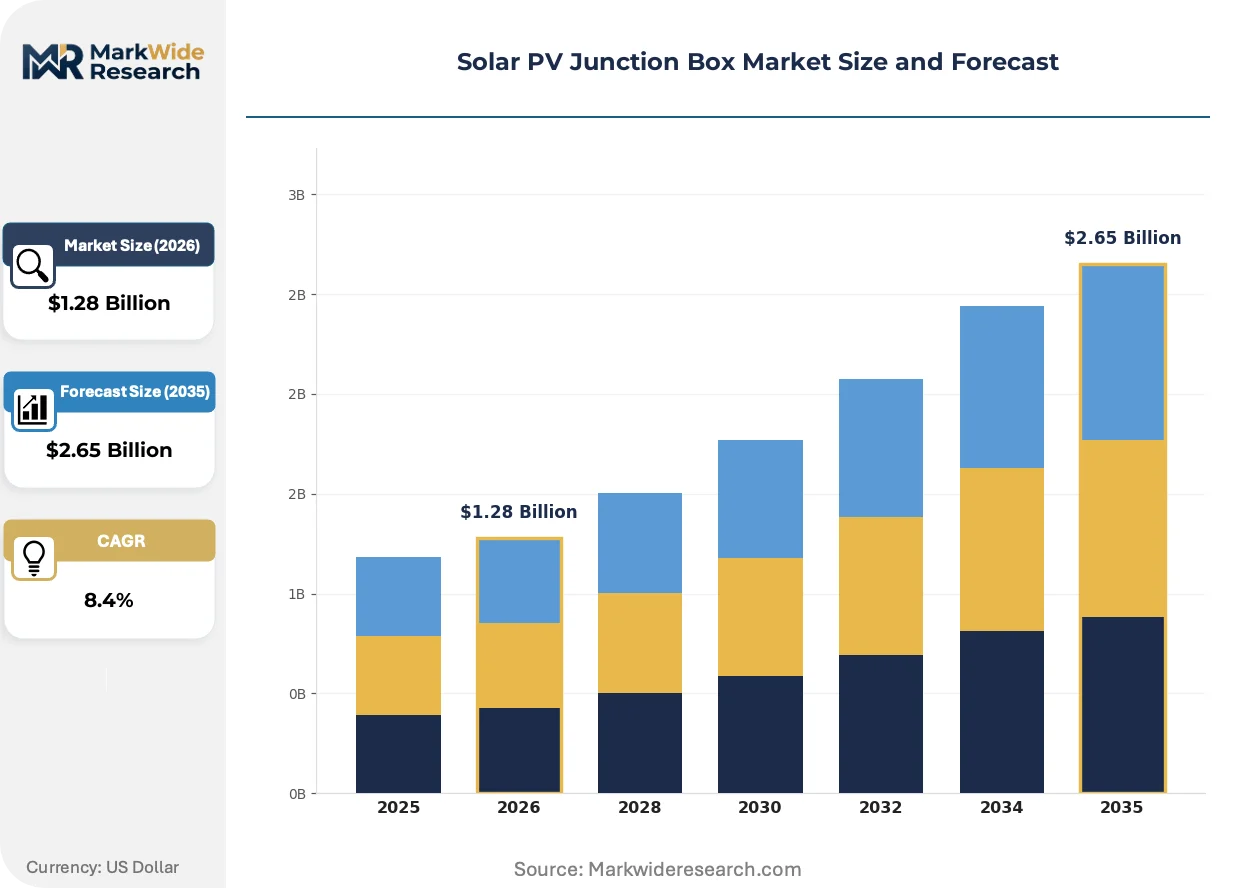
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Junction Boxes, Waterproof Junction Boxes, MC4 Connector Boxes, Combiner Boxes, IP65 Junction Boxes Technology: Polymeric Sealing, Silicone Gaskets, UV Resistant Materials, Flame Retardant Components, Thermal Protection, Overvoltage Protection Application: Residential Solar Systems, Commercial Solar Installations, Utility-Scale Solar Plants, Off-Grid Solar Solutions, Floating PV Systems End User: Residential Consumers, Commercial Enterprises, Power Generation Companies, Off-Grid Developers, Solar EPC Contractors |
| Companies Covered | QC Solar, SolarEdge Technologies, Amphenol Industrial Products Group, Staubli, DuPont, Tigo Energy, DhaSh PV Technologies, Ningbo Jinghua New Energy Technical, AXIOM Solar Private Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar PV Junction Box Market Strategic Shifts & Innovations
Active reshaping of the Solar PV Junction Box Market stems from three converging vectors: embedded intelligence architectures, tightening enclosure performance standards, and procurement unbundling that separates power electronics from mechanical housing decisions.
Power optimizer technology is integrating directly into module-level architectures, bypassing traditional junction box current-handling functions while retaining enclosure duties for environmental sealing and connectivity. Utility-scale developers in Rajasthan and Gujarat are specifying these integrated configurations to reduce balance-of-system component counts. The structural consequence is compressing standalone junction box value capture as power electronics vendors capture margin upstream.
BIS mandates IEC 62790 certification for all junction boxes deployed in Indian solar installations, compelling manufacturers to document thermal cycling and damp-heat test performance before commercial supply. This regulatory friction elevates technical barriers for new market entrants while rewarding incumbent suppliers with established testing relationships. Domestic manufacturers with existing BIS laboratory partnerships are accelerating certification timelines relative to import-dependent competitors.
Contracting patterns among Indian EPC firms are unbundling power electronics procurement from mechanical enclosure sourcing, enabling specialized vendors to compete on diode performance, connector sealing, or housing materials separately. Large solar park developers in Karnataka are issuing split purchase orders for junction box subassemblies rather than finished units. This behavioral shift is most visible in multi-hundred-megawatt projects where procurement teams optimize component-level total cost of ownership rather than bundled pricing.
Solar PV Junction Box Market Segmentation
Junction box procurement in the solar PV sector fragments across technical specifications, installation environments, and buyer sophistication. Understanding these divides reveals where margin concentrates and which configurations justify dedicated manufacturing investment.
Product Type:
Technical specification tiers separate commodity enclosures from performance-differentiated variants engineered for extreme environments.
- Standard Junction Boxes:Polyamide housings with basic IP65 sealing dominate residential and small commercial rooftop deployment. Cost-sensitive procurement from solar EPC contractors in Gujarat and Rajasthan favors these units for gigawatt-scale volume contracts where specification compliance trumps premium features.
- Waterproof Junction Boxes:Silicone gasket sealing and marine-grade connectors achieve IP67 ingress protection for monsoon-exposed installations. Demand clusters along India's eastern and western coastlines where floating PV systems and coastal solar parks require submersion-resistant architectures.
- MC4 Connector Boxes:Pre-terminated cable assemblies reduce field wiring labor for residential installers.
- Combiner Boxes:Higher-current busbar configurations consolidate multiple string outputs before inverter coupling.
- IP65 Junction Boxes:Dust-tight enclosures with pressure-compensating membranes address desert solar park conditions.
Mature deployment sits with Standard Junction Boxes. Newer deployment is concentrated in Waterproof Junction Boxes.
Technology:
Sealing methodology and protective architectures determine manufacturing cycle economics and field reliability profiles.
- Polymeric Sealing:Injection-molded housing-to-lid bonds achieve faster throughput than gasket-intensive alternatives. Indian manufacturers leverage this technology to meet PLI scheme domestic value-addition thresholds while serving utility-scale developers in Karnataka with volume-capable supply.
- Silicone Gaskets:Compression-molded elastomer seals deliver superior thermal cycling durability for extreme climate exposure. BIS certification mandates for damp-heat testing favor suppliers with established gasket validation protocols, extending commercialization timelines for new entrants.
- UV Resistant Materials:Stabilized polyamide compounds prevent brittleness in high-irradiance desert installations.
- Flame Retardant Components:Halogen-free housing materials satisfy CEA technical standards for grid-connected solar plants.
- Thermal Protection:Integrated heat sinks and bypass diode thermal management extend module lifespan.
- Overvoltage Protection:Surge suppression circuits embedded at string consolidation points.
Volume manufacturing gravitates toward Polymeric Sealing. Performance differentiation concentrates in Silicone Gaskets.
Application:
Installation scale and environmental exposure create divergent requirements for enclosure durability and connectivity density.
- Utility-Scale Solar Plants:Centralized procurement from power generation companies specifies combiner box architectures with string-level monitoring compatibility. Rajasthan and Gujarat solar parks drive demand for IP65-rated units at volumes justifying dedicated production lines.
- Floating PV Systems:Waterproof junction box specifications tighten as reservoir and coastal installations expand across India. Monsoon exposure and wave action elevate sealing performance requirements beyond standard rooftop configurations.
- Residential Solar Systems:Rooftop installers prioritize compact footprints and plug-and-play connectivity.
- Commercial Solar Installations:Mid-scale projects balance cost control with monitoring integration requirements.
- Off-Grid Solar Solutions:Battery-coupled architectures demand enhanced overvoltage protection.
Procurement scale peaks with Utility-Scale Solar Plants. Technical complexity is climbing fastest in Floating PV Systems.
End User:
Buyer sophistication and procurement authority shape specification stringency and contract structure preferences.
- Solar EPC Contractors:Unbundled procurement of junction box subassemblies—separating power electronics from mechanical enclosures—enables component-level total cost of ownership optimization. Large solar park developers in Karnataka issue split purchase orders that fragment traditional bundled supplier relationships.
- Power Generation Companies:Centralized technical specifications mandate BIS-certified units with IEC 62790 documentation for thermal cycling and damp-heat performance. These buyers anchor demand for premium-tier configurations with embedded smart sensing architectures.
- Residential Consumers:Price-sensitive procurement through installer channels favors standard configurations.
- Commercial Enterprises:Corporate renewable energy buyers balance visibility requirements with capital constraints.
- Off-Grid Developers:Remote installation logistics prioritize field-serviceable designs.
Contract sophistication concentrates with Solar EPC Contractors. Certification rigor is tightest with Power Generation Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity concentrates in China while procurement gravity shifts toward India, where gigawatt-scale solar deployment is reshaping regional trade flows. Domestic content requirements and certification regimes are fragmenting supply chains across Asia-Pacific.
India
Gujarat, Rajasthan, and Karnataka anchor domestic demand through gigawatt-scale solar park pipelines. BIS mandates IEC 62790 certification for all junction box deployments, compelling thermal cycling documentation before commercial supply. The PLI scheme rewards local value addition, incentivizing domestic assembly over imported finished goods.
China
Zhejiang and Jiangsu provinces house concentrated manufacturing clusters serving export markets with polymeric sealing technologies. MIIT industrial policy prioritizes solar component exports while domestic dual carbon goals accelerate module deployment. Ningbo-based fabricators supply waterproof enclosures for floating PV systems across Southeast Asia.
United States
Utility-scale developers in Texas and California drive demand for combiner box configurations with embedded monitoring capabilities. IRA domestic content bonuses are restructuring procurement toward North American assembly, though connector supply remains import-dependent. Arizona solar parks specify IP67-rated enclosures for desert thermal cycling exposure.
Germany
Baden-Württemberg engineering firms specialize in high-reliability gasket sealing systems for European utility projects. REACH compliance restricts halogen-free housing material formulations, elevating technical barriers for non-EU suppliers. Bavarian solar parks require CEA-equivalent overvoltage protection thresholds under grid connection codes.
Japan
Kanto region commercial installers prioritize compact footprints for rooftop density constraints. METI feed-in tariff revisions are compressing project margins, forcing cost optimization at the component level. Osaka-based EPC contractors unbundle power electronics from mechanical enclosure procurement.
Solar PV Junction Box Market Key Industry Players
The competitive structure tilts toward component specialists over integrated system vendors. Market concentration remains moderate, with tier-one suppliers capturing utility-scale contracts while regional assemblers serve distributed installation channels. Three archetypes dominate: diode-integrated manufacturers, sealed connector specialists, and power optimizer vendors bypassing traditional junction box functions. Capacity expansion and backward integration into core components represent the primary competitive vectors.
Among Asia-Pacific-based fabricators, QC Solar and Ningbo Jinghua New Energy Technical occupy positions within the integrated manufacturing tier, exemplifying captive production strategies for cost structure control. SolarEdge Technologies represents the power electronics convergence archetype, embedding optimizer architectures that compress standalone enclosure value capture. These three anchors illustrate the procurement unbundling reshaping supplier relationships across Indian and Chinese solar markets.
| Leading Market Players |
|---|
| QC Solar |
| SolarEdge Technologies |
| Amphenol Industrial Products Group |
| Staubli |
| DuPont |
| Tigo Energy |
| DhaSh PV Technologies |
| Ningbo Jinghua New Energy Technical |
| AXIOM Solar Private Limited |
| Others |
Cost & Logistics Intelligence
Certification-grade bifurcation between BIS-IEC dual-certified premium enclosures and single-standard commodity units manifests in both margin capture and sourcing strategies across Indian solar deployment. Polyamide resin cost volatility compresses buffers for manufacturers locked into fixed-price utility contracts while connector supply concentration elevates procurement risk for assemblers dependent on maritime-grade components.
Pricing Analysis
Margin tightening in standard IP65-rated enclosures traces to polyamide resin price volatility linked to crude oil derivatives, forcing manufacturers to absorb input swings or renegotiate utility-scale contracts. Three-tier pricing structure across premium waterproof, standard dust-tight, and economy residential configurations differentiates on certification depth and sealing performance rather than brand alone. Cost-down pressure on combiner box architectures accelerates as EPC contractors unbundle power electronics from mechanical housing procurement. Residential rooftop installers exhibit highest price sensitivity, while power generation companies anchored in Rajasthan and Gujarat solar parks prioritize thermal cycling documentation over unit economics.
Supply Chain Analysis
Field return flows for thermal-stressed bypass diodes and gasket degradation create refurbishment channels that extend component lifecycle and compress new-unit demand cycles. Manufacturing gravity centers on Zhejiang and Jiangsu provinces in China, with Ningbo fabricators supplying waterproof enclosures for floating PV systems across Southeast Asia. Polyamide resin, marine-grade connectors, and silicone gasket materials constitute critical input dependencies. Single-source vulnerability clusters around sealed connector expertise, with tariff exposure on Chinese-manufactured housings elevating landed cost uncertainty. Distribution runs through EPC contractor procurement offices in Gujarat, Rajasthan, and Karnataka, with direct OEM relationships bypassing traditional component distributors for gigawatt-scale solar park contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
BIS certification mandates for IEC 62790 compliance erect a cost-of-compliance moat that rewards incumbent suppliers with established laboratory partnerships while extending commercialization timelines for import-dependent competitors.
For Market Incumbents: Anticipate power optimizer integration compressing standalone junction box value capture as SolarEdge Technologies and Tigo Energy embed intelligence upstream. Defend position through backward integration into diode and connector production, mirroring QC Solar's captive supply strategy. Accelerate BIS certification timelines by deepening relationships with domestic testing laboratories before CEA notification requirements expand module-level monitoring mandates. For New Entrants and Emerging Players: Begin with waterproof junction box specialization targeting floating PV systems along India's eastern and western coastlines, where IP67 sealing requirements outpace established supply capacity. Karnataka's multi-hundred-megawatt solar parks with split purchase order structures offer the most penetrable entry point. Pursue unbundled subassembly contracts that separate mechanical enclosure sourcing from power electronics procurement. For Investors and Strategic Acquirers: Re-rating potential sits with diode-integrated manufacturers given PLI scheme alignment rewarding domestic value addition over imported finished goods. Long-term viability favors suppliers with captive bypass diode production and established BIS-IEC dual certification pathways. Monitor CEA notification expansion on module-level monitoring as the inflection signal for smart sensing architecture demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Diode Production | Captive bypass diode manufacturing mirrors QC Solar's cost structure control strategy. |
| BIS-IEC Dual Certification Investment | Accelerated commercialization timelines unlock Rajasthan and Gujarat utility-scale contracts. |
| Waterproof Enclosure Capacity Buildout | IP67-rated production lines address floating PV expansion across India's coastline. |
| Smart Sensing Architecture Development | Embedded monitoring electronics satisfy CEA notification requirements on module-level visibility. |
| PLI Scheme Alignment | Domestic assembly qualification rewards local value addition over imported finished goods. |
Research Approach
Document review covered BIS certification registries, CEA technical standards notifications, and PLI scheme implementation guidelines, complemented by interviews with solar EPC procurement directors, power generation company technical specification leads, and junction box manufacturing operations managers. Secondary validation drew from customs trade data, SEC filings of listed solar component suppliers, and project development databases tracking gigawatt-scale solar park pipelines. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction across the analysis window.
Segment-level outputs reflect modeling across product type, sealing technology, application scale, and end-user procurement sophistication dimensions. CAGRs derive from regression analysis of historical deployment velocity against projected solar park commissioning schedules. Key forecast inputs include polyamide resin price indices, BIS certification processing timelines, and EPC contractor unbundling behavior patterns observed in Karnataka and Gujarat contracting data.
Regulatory enforcement delays, polyamide resin supply disruptions, and faster-than-anticipated power optimizer adoption are the dominant revision risks to modeled outcomes. Practitioners should monitor CEA notification implementation pace and connector supplier capacity expansion for early signals of forecast deviation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Third Generation Solar Cell Sales Market
Solar Power Systems
Building Integrated Photovoltaics Module Market
Solar Power Systems
Tubular Solar Collector Market
Solar Power Systems
CPV Solar Sales Market
Solar Power Systems
Half-Cell Solar Module Market
Solar Power Systems
Off-Grid Solar Energy Market
Solar Power Systems
Mexico Solar Energy Market
Solar Power Systems
Argentina Solar Energy Market
Solar Power Systems
Solar Cells Market
Solar Power Systems
Bangladesh Solar Energy Market
Solar Power Systems
Canada Distributed Solar Power Generation Market
Solar Power Systems
Global Solar Panel Tracking Mount Market
Solar Power Systems
Solar Polysilicon Ingot Wafer Cell Module Market
Solar Power Systems
Egypt Solar Energy Market
Solar Power Systems
Solar Powered Elevator Market
Solar Power Systems
Kuwait Solar Energy Market