
 Solar Powered Elevator Market | 2026-2036
Solar Powered Elevator Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Powered Elevator Market Analytics
Project finance tied to green building certifications is reconfiguring competitive entry barriers for solar elevator suppliers. KONE Corporation leverages its service network density to bundle photovoltaic retrofits with maintenance contracts. Otis Elevator anchors North American demand through direct-drive technology partnerships with municipal housing authorities. Schindler differentiates in Europe by controlling battery-to-grid integration software for commercial high-rises.
A solar powered elevator integrates photovoltaic panels, battery storage, and regenerative drive systems to offset grid electricity consumption, typically achieving 60-90% energy autonomy depending on building height and solar irradiance. The system serves commercial and residential structures seeking net-zero operational carbon footprints. Photovoltaic cell technology leads installed base volumes while battery storage represents the fastest-expanding margin pool as lithium-ion costs decline. Commercial buildings dominate application demand, though hospitals command premium pricing for uninterrupted power specifications.
FAA guidelines govern solar panel installations near airport flight paths, while OSHA standards mandate fall protection during rooftop photovoltaic mounting for elevator retrofits. India's CEA grid-interconnection rules and BIS electrical safety codes shape product certification requirements for domestic suppliers. Stakeholders must monitor evolving municipal solar mandate expansions and battery recycling liability frameworks as procurement criteria shift from first-cost to lifecycle carbon accounting.
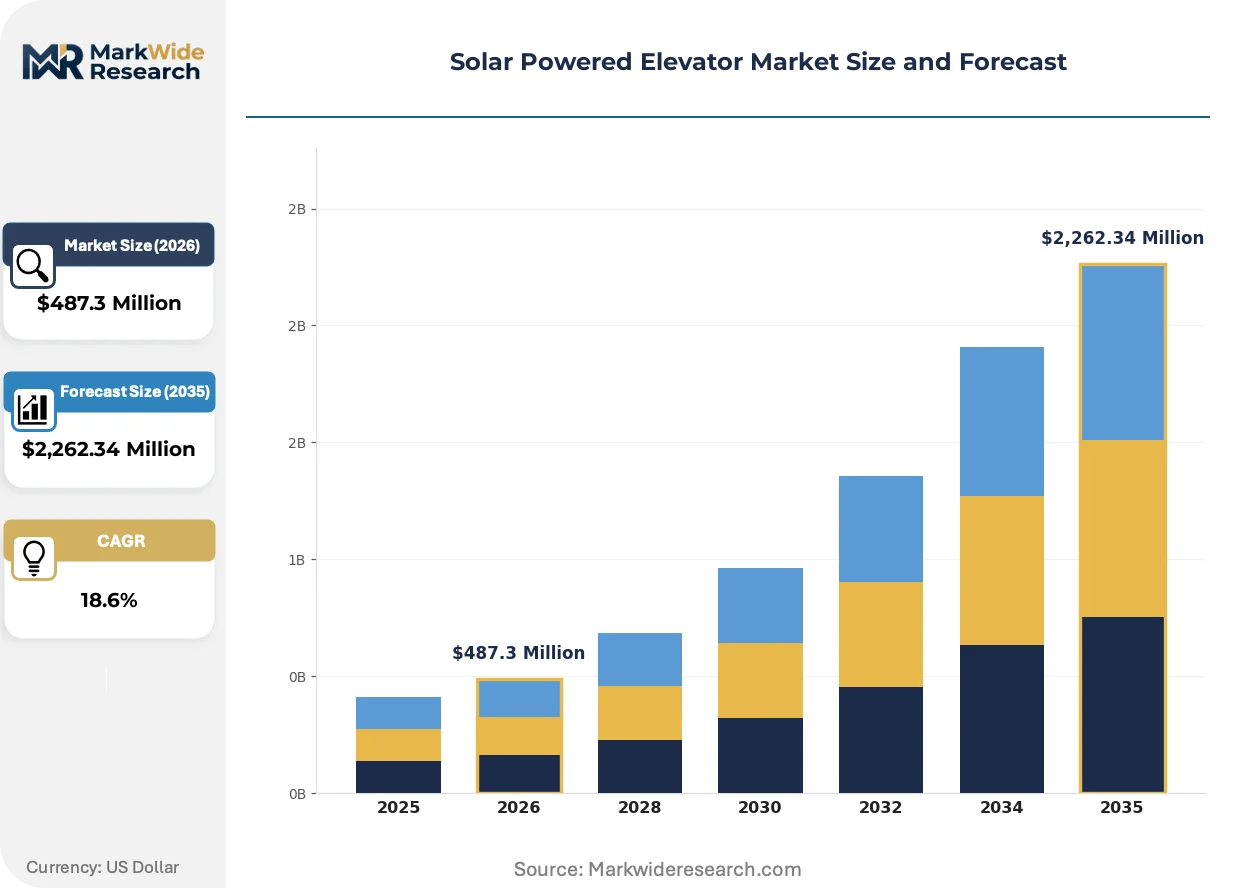
Market Dynamics
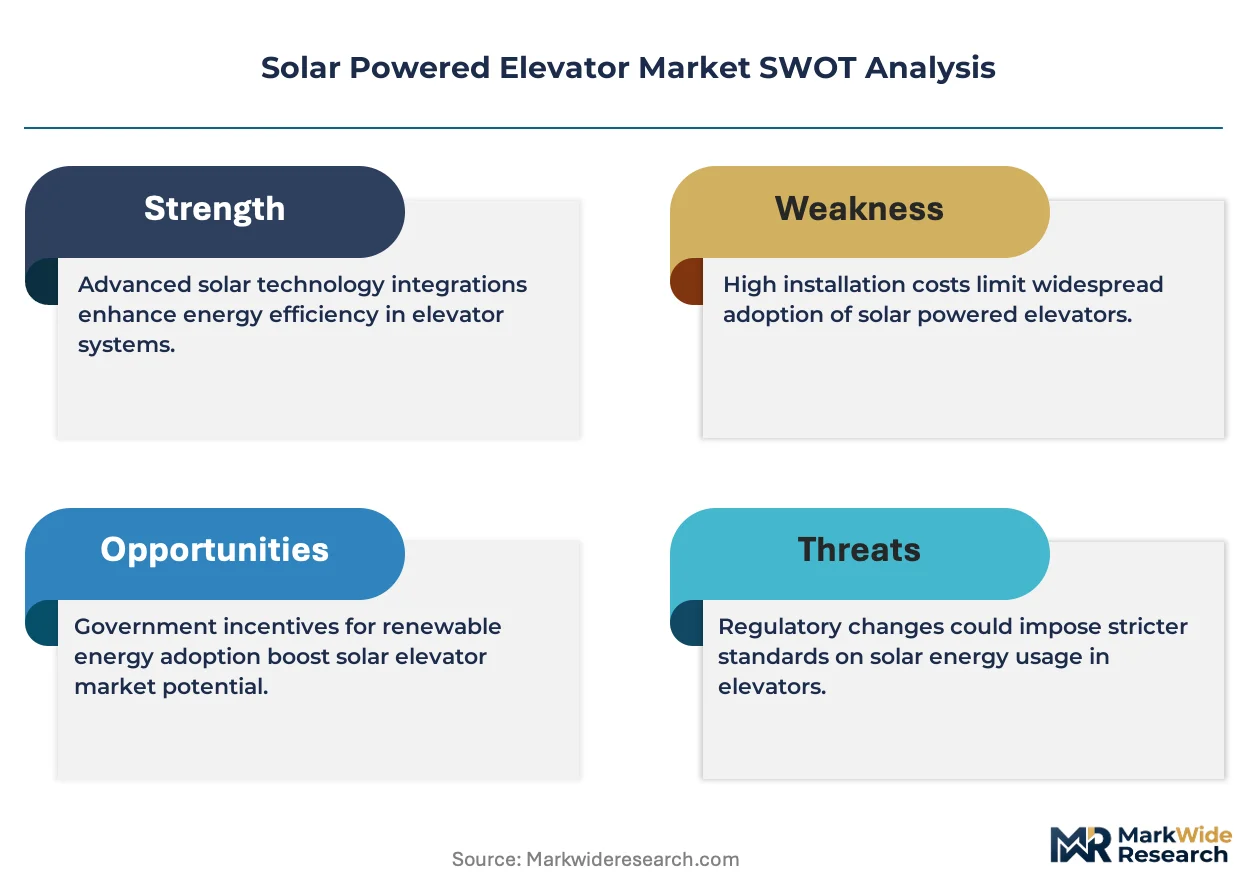
Building decarbonization mandates are compressing payback thresholds for photovoltaic-hybrid lift retrofits, forcing suppliers to restructure financing around energy-as-a-service models rather than equipment sales.
Growth Catalysts
- India's PLI scheme for solar manufacturing:Domestic cell and module production incentives are collapsing import dependency for elevator integrators, accelerating certification timelines under BIS electrical safety codes.
- Regenerative drive technology maturation:Bi-directional power flow from elevator motors is now standard in mid-rise commercial specifications, reducing battery sizing requirements by capturing descent-phase energy.
- Mumbai-Pune corridor green building retrofits:Maharashtra's municipal solar mandates for existing commercial stock are creating concentrated demand clusters for photovoltaic-hybrid lift installations.
Market Restraints
- Lithium-ion battery cost volatility:Raw material price swings for cathode metals are compressing margin pools in storage-integrated system bids, particularly for hospital uninterrupted power specifications.
- Rooftop structural load limitations:Older commercial buildings in dense urban cores lack the structural capacity for photovoltaic panel arrays sufficient to power high-speed traction elevators.
- FAA flight path restrictions:Solar installations near airport approach corridors face height and reflectivity constraints that disqualify entire building categories from autonomous elevator power systems.
Strategic Opportunities
- Battery-to-grid integration software:Commercial high-rises in Germany and France can monetize elevator storage assets through frequency regulation markets under evolving EU grid codes.
- Direct-drive technology partnerships:Municipal housing authorities in the United States are piloting gearless motor retrofits that eliminate mechanical efficiency losses and reduce photovoltaic array sizing.
- CEA grid-interconnection rule harmonization:India's streamlining of net-metering procedures for building-integrated solar is opening standardized procurement pathways for multi-elevator commercial portfolios.
Industry Challenges
- Photovoltaic-electrical-mechanical cross-training gaps:Installation crews with combined competencies in rooftop solar mounting, battery commissioning, and elevator safety systems remain scarce, elongating project timelines.
- OSHA fall protection compliance:Rooftop photovoltaic work for elevator retrofits triggers stringent harness and anchor point requirements that add labor cost and scheduling complexity.
- Legacy building automation integration:Proprietary elevator control protocols from the 1990s lack the communication interfaces required for battery management system coordination and solar forecasting algorithms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Powered Elevator Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $2,262.34 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Commercial Buildings, Residential Towers, Hospitals, Industrial Facilities Power Rating: 5 kW, 10 kW, 15 kW, 20 kW Technology: Photovoltaic Cells, Battery Storage, Hydraulic Systems, Direct Drive Installation Type: Retrofit, New Construction, Modular, Custom Designed |
| Companies Covered | ThyssenKrupp, Pneumatic Vacuum Elevators, KONE Corporation, Cube Elevators, Asian Elevators Control & Automation, Otis Elevator, Mezolift, Gravo Elevators, Schindler, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Powered Elevator Market Evolving Landscape
Digital twin technology is digitizing predictive maintenance workflows across the installed base, compressing service response times and enabling remote diagnostics that reduce truck rolls for solar elevator systems.
Machine learning algorithms applied to elevator usage patterns are digitizing energy dispatch optimization, allowing commercial building operators to shave peak demand charges by predicting passenger load and pre-charging batteries accordingly. Large property management firms in Singapore and Australia are deploying these systems at scale. The structural consequence is a shift from hardware-centric bids to software-augmented service contracts.
The EU F-Gas Regulation is accelerating refrigerant-based cooling system phaseouts in elevator machine rooms, driving adoption of liquid-cooled permanent magnet motors that pair efficiently with rooftop photovoltaic arrays. German and Dutch building codes now reference this compatibility in technical specifications. Commercial high-rise developers are responding by specifying integrated solar-motor packages rather than discrete component procurement.
Building owners are unbundling elevator maintenance from original equipment contracts, creating independent service provider channels that specialize in photovoltaic-hybrid system upkeep. This fragmentation is most visible in India's Maharashtra and Karnataka states, where domestic integrators are capturing retrofit opportunities from multinational incumbents. The shift rewards technical agility over brand recognition in vendor selection criteria.
Solar Powered Elevator Market Segmentation
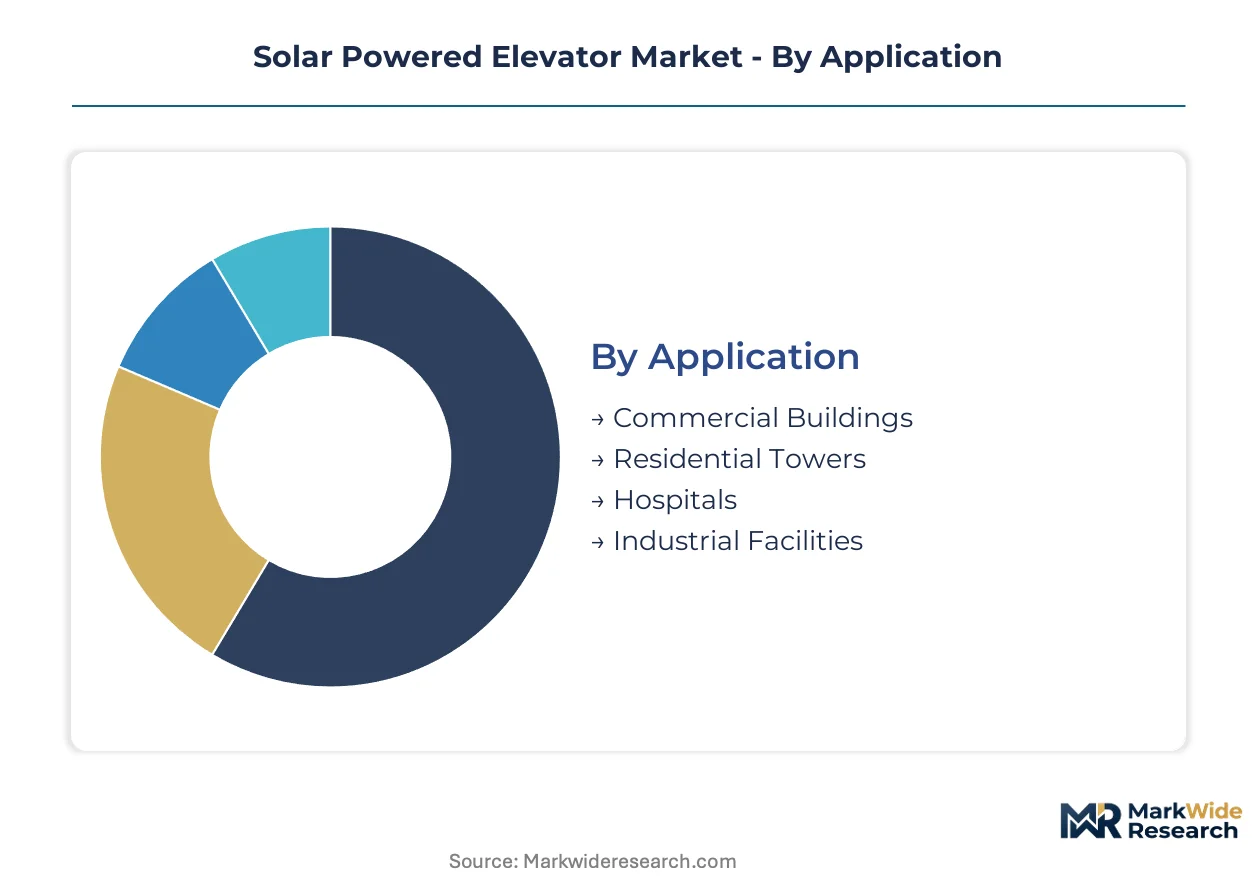
Segmentation in the solar powered elevator market reveals distinct procurement cycles and margin structures across application types and power configurations. Understanding these divisions allows suppliers to align financing models and service contracts with segment-specific energy autonomy requirements and retrofit timelines.
Application:
Replacement cycles vary dramatically across building types, with hospitals demanding uninterrupted power specifications that extend procurement lead times while commercial retrofits compress decision windows under municipal mandate deadlines.
- Commercial Buildings:Mid-rise offices and retail complexes constitute the dominant installation base, with Maharashtra's Mumbai-Pune corridor driving concentrated procurement under state-level solar mandates for existing building stock. Building operators prioritize 60-80% energy autonomy targets to meet green certification thresholds and secure project finance tied to net-zero operational benchmarks.
- Residential Towers:Multi-family housing developments in dense urban cores face structural load constraints that limit rooftop photovoltaic array sizing, forcing integrators toward smaller battery configurations and regenerative drive optimization. Municipal housing authorities in the United States are piloting direct-drive retrofits that reduce mechanical losses and compensate for reduced solar capture surface.
- Hospitals:Healthcare facilities command premium pricing for lithium-ion storage systems sized to guarantee uninterrupted power through grid outages, though raw material cost volatility compresses margins on these specifications.
- Industrial Facilities:Manufacturing plants with heavy freight elevators require 15-20 kW power ratings that strain rooftop structural capacity in older facilities.
Commercial Buildings anchors the volume base while Residential Towers gains share at the steepest rate as municipal housing authorities accelerate gearless motor retrofits.
Power Rating:
Cost tiers stratify sharply across kilowatt bands, with smaller systems achieving faster payback in low-rise applications while high-capacity configurations require complex structural reinforcement.
- 5 kW:Entry-level systems serve low-rise residential and small commercial installations where elevator duty cycles remain moderate and rooftop space constraints limit photovoltaic array expansion.
- 10 kW:Mid-capacity configurations dominate the retrofit market, balancing battery storage costs against regenerative drive energy capture in buildings with 6-12 story heights.
- 15 kW:High-traffic commercial towers and hospital specifications demand this tier, where lithium-ion battery sizing must accommodate peak morning and evening passenger loads independent of solar generation timing.
- 20 kW:Maximum-capacity systems target industrial freight elevators and supertall commercial structures, though structural load limitations in dense urban cores restrict addressable building stock.
10 kW systems capture the highest retrofit volume while 15 kW configurations climb the fastest as hospital uninterrupted power specifications proliferate.
Technology:
Maturity curves diverge across component categories, with photovoltaic cells achieving commodity pricing while battery-to-grid software remains a differentiated margin pool.
- Photovoltaic Cells:Silicon-based panels constitute the installed base majority, with India's PLI scheme for domestic manufacturing collapsing import dependency and accelerating BIS certification timelines for elevator integrators sourcing locally produced modules.
- Battery Storage:Lithium-ion systems represent the fastest-expanding margin pool as cell costs decline, though cathode metal price volatility creates bidding uncertainty for hospital uninterrupted power specifications. German and French commercial high-rises are monetizing these assets through frequency regulation markets under evolving EU grid codes.
- Hydraulic Systems:Legacy installations in older industrial facilities face phaseout pressure under building decarbonization mandates, limiting growth trajectory despite lower upfront capital requirements.
- Direct Drive:Gearless permanent magnet motors eliminate mechanical efficiency losses and pair efficiently with liquid-cooled configurations specified under EU F-Gas Regulation compliance pathways.
Photovoltaic Cells underpins current revenue while Battery Storage expands most quickly as building operators unbundle hardware procurement from energy-as-a-service contracts.
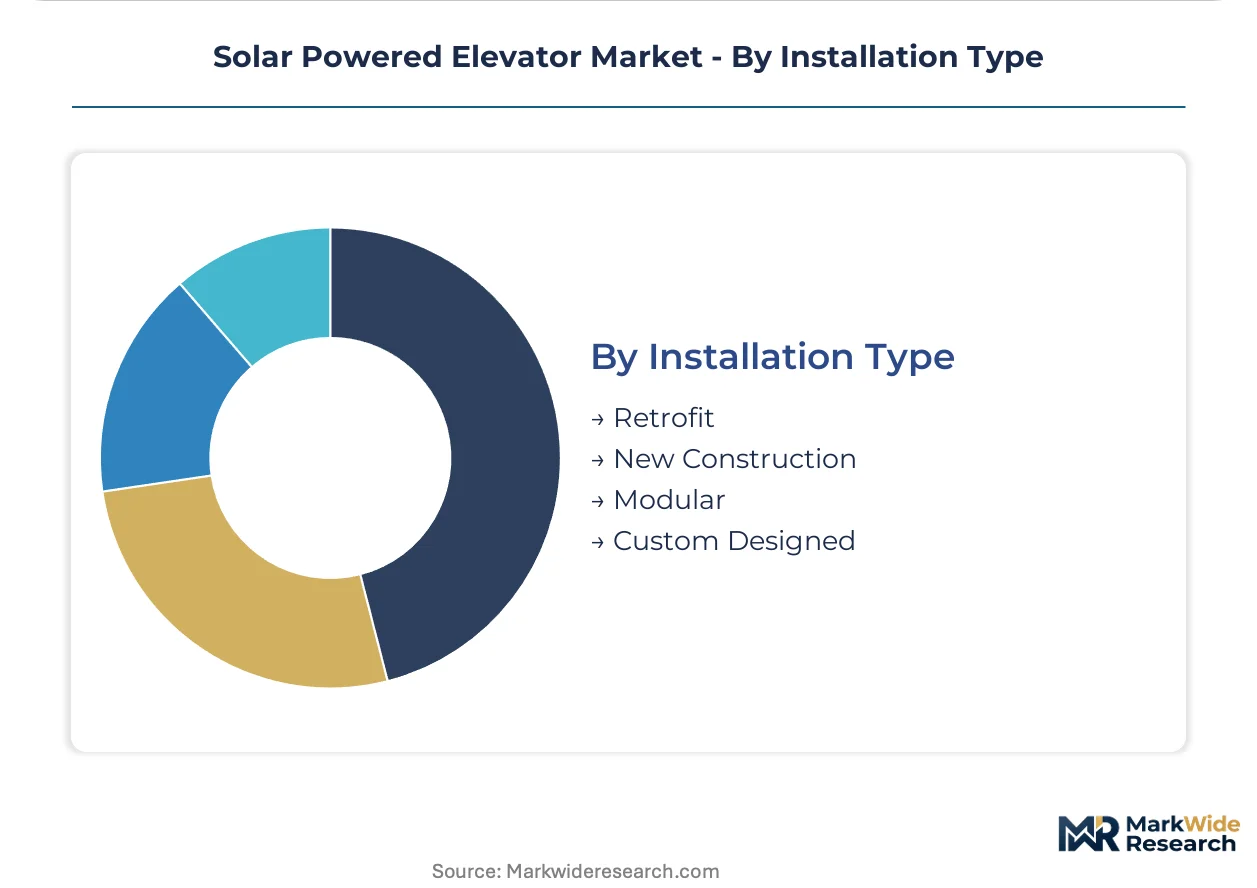
Installation Type:
Customer type and project ownership structure determine whether integrators capture one-time equipment margins or recurring service revenue streams.
- Retrofit:Existing building modifications dominate current demand, particularly in Maharashtra and Karnataka states where domestic integrators are capturing opportunities from multinational incumbents by specializing in photovoltaic-hybrid system upkeep independent of original equipment contracts.
- New Construction:Greenfield developments allow integrated solar-motor package specification from foundation phase, with German and Dutch building codes now referencing liquid-cooled permanent magnet compatibility in technical standards.
- Modular:Prefabricated elevator-solar-battery skids reduce on-site commissioning time for standardized commercial building formats, though proprietary control protocol mismatches from 1990s legacy systems complicate building automation integration.
- Custom Designed:Bespoke configurations serve supertall structures and specialized industrial applications where standard power ratings and structural constraints require engineering exceptions.
Retrofit commands current volume concentration while New Construction accelerates fastest as EU F-Gas Regulation drives liquid-cooled motor adoption in greenfield commercial high-rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in photovoltaic-hybrid lift systems tilt toward import-dependent markets lacking domestic cell manufacturing, while exporter economies leverage integrated solar supply chains to capture retrofit demand in dense urban corridors.
India
Maharashtra's Mumbai-Pune corridor concentrates green building retrofit activity as commercial developers procure photovoltaic-hybrid lifts to comply with state-level solar mandates for existing building stock. The national PLI scheme for solar manufacturing collapses import dependency for elevator integrators sourcing domestically produced modules. BIS electrical safety codes and CEA grid-interconnection rules accelerate certification timelines for multi-elevator commercial portfolios in Karnataka and Tamil Nadu.
Germany
Commercial high-rises in Frankfurt and Hamburg monetize elevator battery assets through frequency regulation markets under evolving EU grid codes. The F-Gas Regulation accelerates refrigerant-based cooling system phaseouts, driving specification of liquid-cooled permanent magnet motors that pair efficiently with rooftop photovoltaic arrays. North Rhine-Westphalia and Bavaria anchor demand for integrated solar-motor packages in greenfield developments.
United States
Municipal housing authorities in New York and Chicago pilot gearless motor retrofits that eliminate mechanical efficiency losses and reduce photovoltaic array sizing requirements. FAA guidelines govern solar panel installations near airport approach corridors in Atlanta and Los Angeles, restricting autonomous elevator power systems in entire building categories. OSHA fall protection standards add labor cost and scheduling complexity to rooftop photovoltaic work for elevator retrofits.
France
Paris commercial towers deploy battery-to-grid integration software to capture frequency regulation revenue under EU grid code harmonization. The F-Gas Regulation drives liquid-cooled permanent magnet motor adoption in Île-de-France new construction. Auvergne-Rhône-Alpes and Provence-Alpes-Côte d'Azur concentrate demand for hospital uninterrupted power specifications with premium lithium-ion storage systems.
Singapore
Large property management firms deploy machine learning algorithms for elevator energy dispatch optimization, shaving peak demand charges by predicting passenger load and pre-charging batteries accordingly. The city-state's building decarbonization mandates compress payback thresholds for photovoltaic-hybrid lift retrofits in the central business district. Domestic integrators capture opportunities from multinational incumbents by specializing in photovoltaic-hybrid system upkeep.
Solar Powered Elevator Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: multinational elevator OEMs bundling photovoltaic retrofits with service contracts, domestic integrators specializing in independent maintenance of hybrid systems, and component suppliers controlling battery-to-grid software or direct-drive motor technology. Competitive moves center on energy-as-a-service financing restructuring and geographic expansion through municipal housing authority partnerships.
Among multinational OEMs, KONE Corporation, Otis Elevator, and Schindler occupy positions defined by service network density and technology partnerships rather than pure equipment sales. KONE exemplifies the retrofit-bundling archetype through maintenance contract integration. Otis anchors North American positioning via municipal authority relationships. Schindler sits within the European premium tier through battery-to-grid software control. Domestic specialists including Asian Elevators Control & Automation and Gravo Elevators represent the technical agility tier capturing India's Maharashtra and Karnataka retrofit markets from established incumbents.
| Leading Market Players |
|---|
| ThyssenKrupp |
| Pneumatic Vacuum Elevators |
| KONE Corporation |
| Cube Elevators |
| Asian Elevators Control & Automation |
| Otis Elevator |
| Mezolift |
| Gravo Elevators |
| Schindler |
| Others |
Value Network & Pricing Analysis
China's concentration in lithium-ion cathode processing anchors margin capture for battery storage tiers, while downstream integrators in India and Germany compete on energy-as-a-service contract structures rather than equipment markups. Photovoltaic cell commoditization has collapsed module pricing, forcing elevator OEMs to extract value from battery management software and predictive maintenance bundling.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing stratification across premium uninterrupted power specifications, standard commercial retrofits, and economy residential configurations. Price differentiation hinges on lithium-ion storage capacity and BIS electrical safety certification tier. Pricing pressure stems from cathode metal cost volatility compressing margins on hospital specifications. Municipal housing authorities exhibit highest price sensitivity, while commercial high-rises in green certification programs demonstrate lowest.
Supply Chain Analysis
Contract manufacturing for photovoltaic modules concentrates in China, Vietnam, and India under the PLI scheme's production-linked incentives. Battery cell supply draws from South Korea and Japan for premium lithium-ion configurations. Single-source vulnerability in refined cobalt and nickel processing creates procurement risk. Distribution runs through elevator OEM service networks and independent domestic integrators in retrofit-heavy corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against grid-tied regenerative drive systems that achieve comparable efficiency without rooftop photovoltaic infrastructure. Incumbents must restructure value capture around software and service contracts.
For Market Incumbents: Pre-empt domestic integrator fragmentation by unbundling maintenance contracts from original equipment sales. Capture battery-to-grid software control as the primary margin lever against Schindler's European positioning. Vertical integration into local photovoltaic module sourcing under India's PLI scheme collapses certification timelines.
For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, with less stringent structural load requirements and nascent green building enforcement. Municipal housing authority partnerships in secondary US cities offer direct-drive retrofit opportunities without competing against established service network density. Lead with energy-as-a-service financing rather than capital equipment sales.
For Investors and Strategic Acquirers: Capital is best deployed toward battery-to-grid software specialists and regional integrators with CEA grid-interconnection compliance capabilities. Long-term viability rests on control of dispatch optimization algorithms and frequency regulation market access. Monitor EU F-Gas Regulation enforcement timelines as inflection signal for liquid-cooled motor adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery-to-Grid Software Acquisition | Captures frequency regulation revenue streams under evolving EU grid codes in German and French commercial towers. |
| CEA Grid-Interconnection Certification | Accelerates multi-elevator commercial portfolio approvals in India's Karnataka and Tamil Nadu corridors. |
| Direct-Drive Motor Partnership | Eliminates mechanical efficiency losses for municipal housing authorities in New York and Chicago retrofits. |
| Liquid-Cooled Permanent Magnet Integration | Pairs with rooftop photovoltaic arrays under EU F-Gas Regulation compliance pathways in Dutch greenfield developments. |
| Predictive Maintenance Platform Launch | Compresses service response times through digital twin deployment across Singapore property management portfolios. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with elevator OEM procurement directors, CEA grid-interconnection compliance officers, municipal housing authority facilities managers, and independent domestic integrators; and secondary validation through BIS certification databases, CEA net-metering filings, EU F-Gas Regulation implementation trackers, and customs trade data for photovoltaic module flows. Bottom-up installation counts across Maharashtra, Karnataka, Frankfurt, and New York were triangulated against top-down market sizing from equipment manufacturer disclosures.
Forecast inputs span power rating tiers, application segments, installation types, and technology configurations across the projection horizon. CAGRs were derived from regression analysis of historical procurement cycles and mandate-driven retrofit timelines. Industry-specific inputs include lithium-ion cost decline curves, structural load assessment data for older commercial stock, and municipal solar mandate expansion schedules.
Practitioners should monitor cathode metal price volatility, FAA flight path restriction amendments, and OSHA fall protection enforcement intensity for early signals of forecast revision. Quarterly review of CEA grid-interconnection queue lengths and BIS certification backlogs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Portugal Solar Energy Market
Solar Power Systems
Middle East and Africa Solar PV Inverters Market
Solar Power Systems
Solar Power Tracker Market
Solar Power Systems
Solar Cells Market
Solar Power Systems
PV Solar Data Logger Market
Solar Power Systems
Greece Renewable Energy Market
Solar Power Systems
Smart Solar Tracker Market
Solar Power Systems
Industrial Solar Water Heaters Market
Solar Power Systems
Asia-Pacific Solar Blanket Market
Solar Power Systems
Biohybrid Solar Cell Market
Solar Power Systems
India Solar Photovoltaic (PV) Market
Solar Power Systems
Solar PV Carport Market
Solar Power Systems
Solar Power Manager Market
Solar Power Systems
Mexico Solar Photovoltaic (PV) Market
Solar Power Systems
Bulgaria Solar Energy Market
Solar Power Systems
Australia Solar Market