
 Half-Cell Solar Module Market | 2026-2036
Half-Cell Solar Module Market Size, Share, and Industry Trends Forecast 2026-2036
Half-Cell Solar Module Market Insights
Utility-scale independent power producers is collapsing their procurement toward half-cell architectures as these modules cut resistive losses and improve shade tolerance. LONGi Green Energy leverages its integrated ingot-to-module chain to dominate premium monocrystalline half-cell supply. JinkoSolar Holding Co., Ltd. anchors its competitive position through Tiger Neo N-type half-cell platforms with industry-leading temperature coefficients. Trina Solar Co., Ltd. specializes in Vertex series ultra-high-power half-cell modules designed explicitly for utility-scale deployment.
Half-cell solar modules split standard cells into two equal sections, halving current flow to reduce resistive losses and enabling tighter packing densities with power outputs frequently exceeding standard equivalents. Monocrystalline half-cell variants command the dominant share of new capacity additions due to superior conversion efficiency and declining wafer cost premiums. Utility end users represent the fastest-expanding demand pool as developers seek higher module wattage to compress balance-of-system costs across large-scale solar farms. Bifacial technology integration with half-cell architecture creates distinct margin pools, since dual-sided energy capture justifies pricing premiums in high-albedo installations.
China's MIIT enforces module efficiency thresholds through national standard GB/T 9535, while the EU Green Deal and CE marking requirements under the F-Gas Regulation shape import eligibility and carbon footprint disclosure obligations for modules entering European markets. India's BIS certification mandates and PLI scheme eligibility criteria directly influence which half-cell module technologies qualify for domestic manufacturing incentives. Stakeholders must monitor evolving efficiency mandates and carbon-border adjustment mechanisms to align product roadmaps with jurisdiction-specific compliance thresholds.
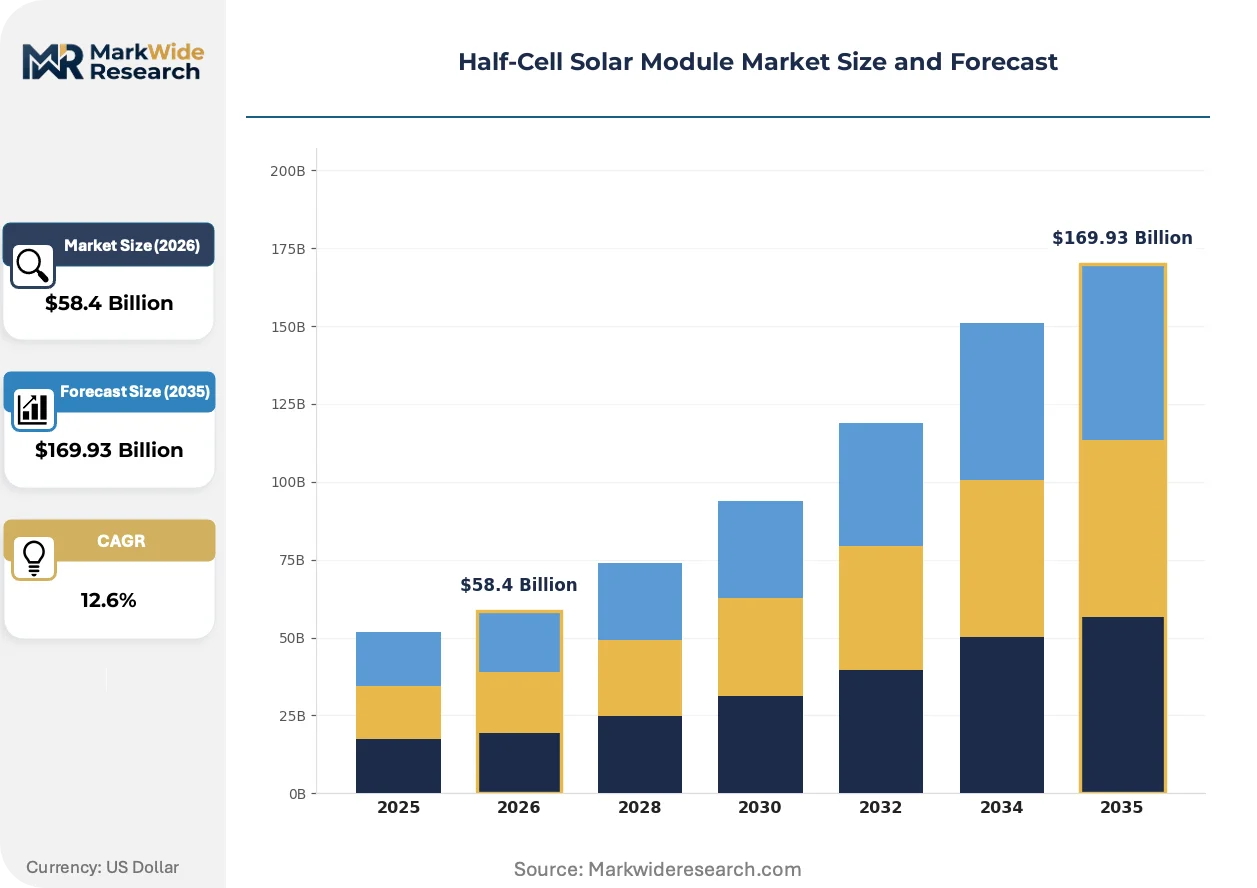
Market Dynamics
Utility-scale developers are compressing procurement cycles toward higher-wattage half-cell modules as balance-of-system cost reduction becomes the decisive competitive lever in utility PPA bidding.
Growth Catalysts
- EU Green Deal efficiency mandates:The EU Green Deal and national renewable portfolio standards in Germany, Spain, and Italy are accelerating module efficiency thresholds, forcing technology upgrades across European solar fleets.
- Shade-tolerant architecture:Half-cell designs improve shade tolerance and cut resistive losses, making them essential for distributed commercial rooftops with complex shading profiles.
- Jiangsu-Anhui supply clusters:China's integrated cell-to-module capacity concentration in Jiangsu and Anhui provinces is driving cost-down trajectories through captive wafer supply and automated stringing.
Market Restraints
- Silver paste cost volatility:Cell metallization depends on silver paste, whose price swings directly compress module margins during commodity spikes.
- Polysilicon supply concentration:Xinjiang-based polysilicon suppliers dominate feedstock supply, creating geographic concentration risk for non-Chinese module assemblers.
- GB/T 9535 efficiency thresholds:China's MIIT-enforced national standard creates compliance friction for legacy module lines unable to hit updated conversion efficiency floors.
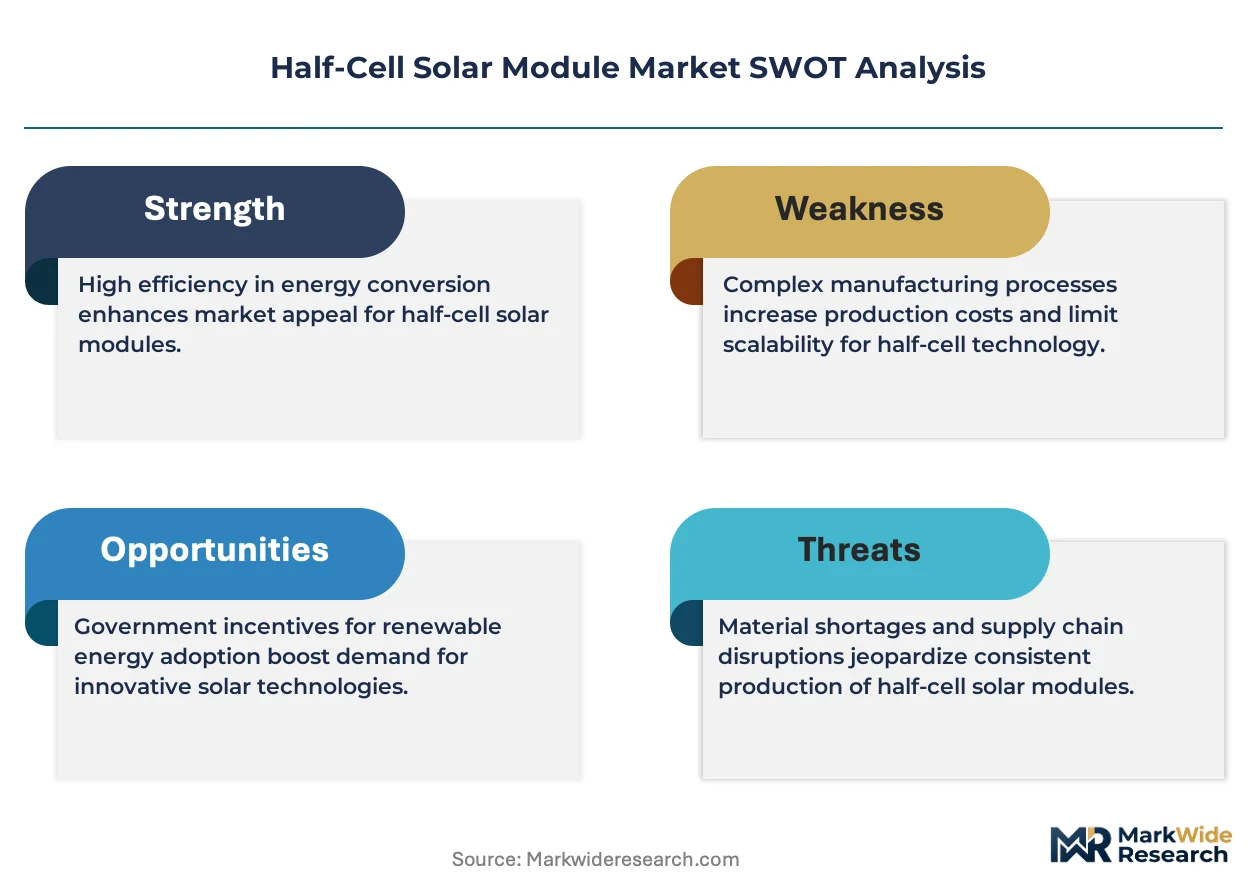
Strategic Opportunities
- Agrivoltaics integration:Bifacial half-cell modules paired with elevated mounting structures unlock dual-use land revenue streams for agricultural regions.
- India PLI scheme eligibility:India's production-linked incentive scheme creates a regulatory tailwind for domestic half-cell module manufacturing capacity.
- N-type TOPCon convergence:Tunnel oxide passivated contact cell technology converging with half-cell architecture enables higher open-circuit voltages and degradation resistance.
Industry Challenges
- Cell-to-module yield engineering:Half-cell stringing and bussing require precision automation expertise that remains scarce outside tier-one Chinese manufacturers.
- CE marking carbon footprint disclosure:The EU F-Gas Regulation and emerging carbon-border adjustment mechanisms impose documentation burdens that extend certification timelines for import-bound modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Half-Cell Solar Module Market |
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $169.93 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polycrystalline, Monocrystalline, Bifacial, Thin Film End User: Residential, Commercial, Industrial, Utility Installation Type: Rooftop, Ground-mounted, Building-integrated, Floating Technology: Standard, PERC, Heterojunction, Bifacial Technology |
| Companies Covered | LONGi Green Energy, JinkoSolar Holding Co., Ltd., JA Solar Technology Co., Ltd., Trina Solar Co., Ltd., Tongwei Solar, Hanwha Q CELLS, First Solar, Inc., Canadian Solar Inc., Astronergy (CHINT SOLAR), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Half-Cell Solar Module Market Trends and Innovations
Module architecture is bifurcating between ultra-high-power utility formats and distributed-optimized designs as end-use requirements diverge sharply across installation scales.
TOPCon cell technology is fragmenting the passivated emitter and rear contact mainstream by delivering higher conversion efficiency and superior temperature coefficients. Utility-scale independent power producers are adopting n-type platforms at accelerating pace for large solar farms. This technology shift is fragmenting procurement specifications as developers rewrite module datasheets around n-type performance guarantees.
The EU Green Deal's carbon footprint disclosure requirements under the F-Gas Regulation are reshaping import eligibility for modules entering European markets. Manufacturers must now document embodied carbon across wafer, cell, and module production stages. European utility-scale developers are responding by tightening supplier qualification criteria to exclude high-carbon-intensity supply chains.
Developer procurement teams are consolidating vendor lists around integrated manufacturers capable of ingot-to-module traceability. Long-term supply agreements are displacing spot-market purchasing for utility-scale projects. This consolidation is most visible in Germany and Spain, where PPA offtakers demand bankability proofs that favor vertically integrated suppliers with captive polysilicon and wafer capacity.
Half-Cell Solar Module Market Segmentation
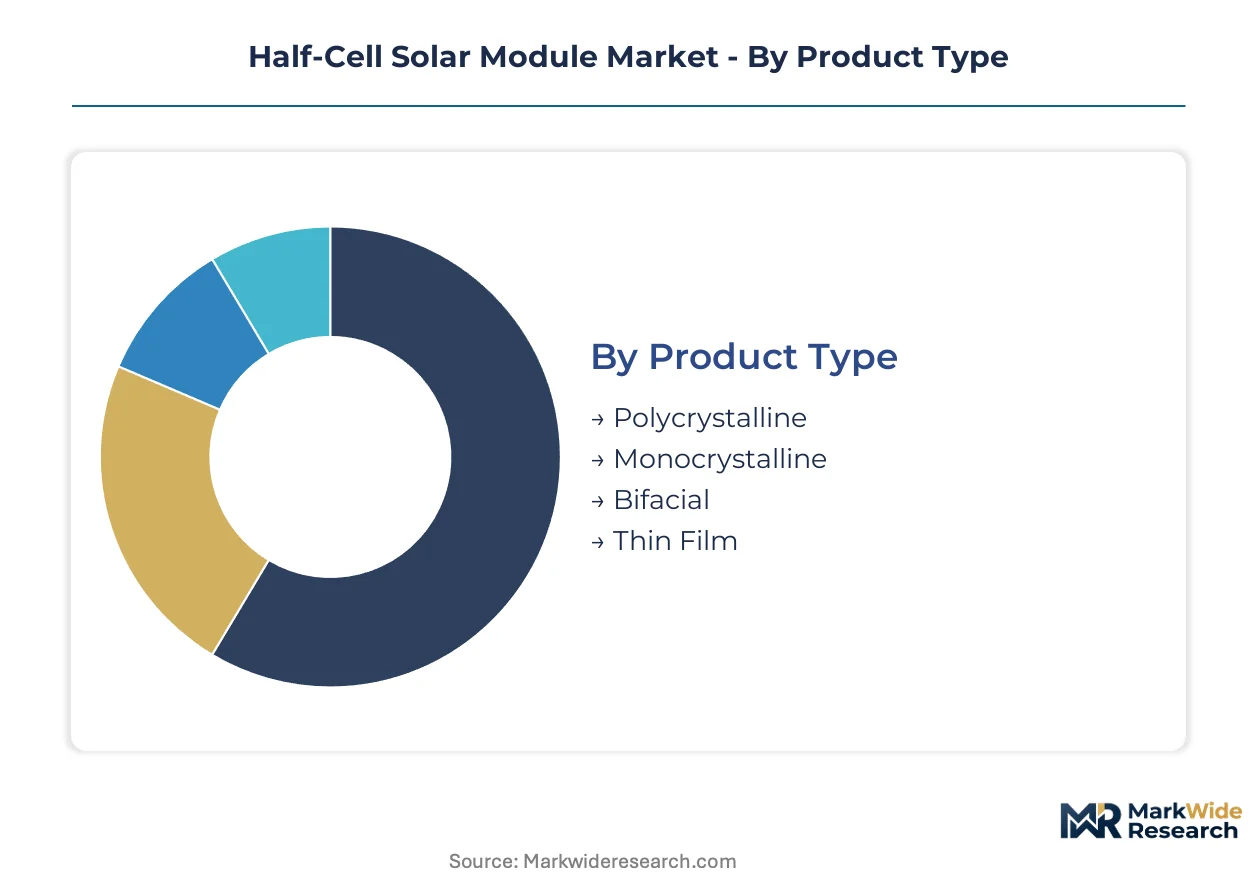
Half-cell solar module procurement splits sharply across product architectures and installation contexts. Developers optimize module selection against balance-of-system cost structures and shading profiles that vary by deployment scale.
Product Type:
Margin pools concentrate in premium monocrystalline and bifacial variants where efficiency premiums justify pricing power.
- Monocrystalline:Silicon ingots sliced from single-crystal boules deliver higher conversion efficiency and tighter cell-to-cell uniformity. Utility-scale developers in Germany and Spain prioritize monocrystalline half-cells to maximize wattage per hectare and compress land acquisition costs.
- Bifacial:Dual-sided cell architecture captures reflected irradiance from ground surfaces, boosting effective yield in high-albedo environments. Agrivoltaic installations in Italy's Po Valley and commercial rooftops with white membrane surfaces concentrate demand for this technology.
- Polycrystalline:Multi-crystalline silicon cells trade efficiency for lower wafer costs, retaining relevance in price-sensitive distributed markets.
- Thin Film:Cadmium telluride and CIGS alternatives occupy niche applications where weight constraints or low-light performance outweigh silicon efficiency advantages.
Monocrystalline holds installed capacity. Bifacial is rotating up the share rankings.
End User:
Volume concentration shifts toward utility procurement as independent power producers rewrite module specifications around bankability requirements.
- Utility:Independent power producers and project developers deploy multi-megawatt solar farms requiring standardized, high-wattage modules with 25-year performance guarantees. China's Jiangsu province hosts the densest concentration of utility-scale half-cell procurement, where developers source directly from integrated cell-to-module manufacturers.
- Commercial:Distributed generation for office buildings, warehouses, and manufacturing facilities prioritizes shade-tolerant half-cell designs. Complex rooftop geometries in Spain's industrial corridors drive demand for modules with improved bypass diode configurations.
- Residential:Homeowner installations favor compact form factors and aesthetic integration over absolute efficiency metrics.
- Industrial:On-site power generation for energy-intensive manufacturing balances self-consumption economics against grid export tariffs.
Utility procurement dominates new capacity additions. Commercial distributed generation is gaining share fastest.
Installation Type:
Ground-mounted deployments command the steepest expansion trajectory as utility-scale project pipelines accelerate across European renewable auction mechanisms.
- Ground-mounted:Fixed-tilt and tracking structures support utility-scale arrays across agricultural and brownfield sites. Germany's renewable auction rounds and Spain's PPA market are concentrating new ground-mounted half-cell deployments in regions with high solar resource and grid access.
- Rooftop:Commercial and residential building-apex installations require lightweight framing and rapid mounting systems. Italy's Superbonus incentive scheme has historically concentrated rooftop half-cell adoption among residential aggregators.
- Building-integrated:Façade and canopy applications substitute conventional construction materials with photovoltaic surfaces.
- Floating:Reservoir and coastal installations exploit water surface cooling effects and reduced land use conflicts.
Ground-mounted arrays anchor utility-scale deployment. Rooftop commercial is climbing the fastest among distributed segments.
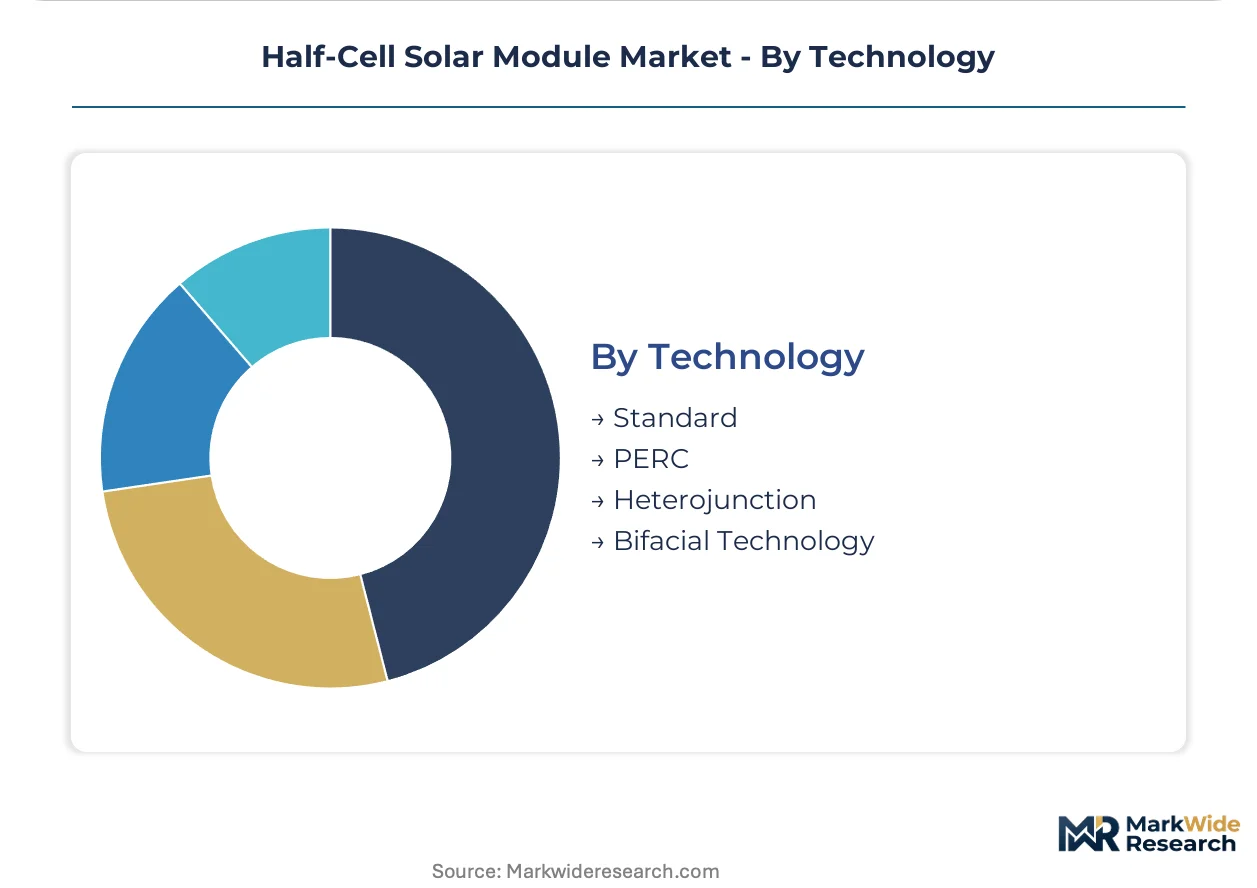
Technology:
Technology selection determines module efficiency floors and degradation curves that directly impact project finance assumptions.
- PERC:Passivated emitter and rear contact cell architecture dominates current manufacturing capacity with proven efficiency gains over standard aluminum back surface field designs. Anhui province's integrated manufacturing clusters have standardized PERC half-cell production for export to European utility markets.
- Heterojunction:Amorphous silicon-crystalline silicon junctions enable higher open-circuit voltages and superior temperature coefficients. Japanese and South Korean equipment suppliers are licensing heterojunction production lines to Chinese cell manufacturers targeting premium European residential segments.
- Standard:Conventional aluminum back surface field cells retain cost advantages in price-sensitive procurement.
- Bifacial Technology:Dedicated bifacial cell processing with transparent rear-side metallization enables dual-sided energy capture distinct from monofacial alternatives.
PERC technology holds installed capacity. Heterojunction is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated cell-to-module capacity clusters in China's Jiangsu and Anhui provinces dominate supply, while procurement demand concentrates in European markets with aggressive renewable auction mechanisms.
China
Utility-scale developers in Jiangsu province source directly from integrated manufacturers with captive wafer supply. MIIT enforces module efficiency thresholds through national standard GB/T 9535, creating compliance friction for legacy production lines. Automated stringing operations in Anhui province drive cost-down trajectories through precision half-cell assembly.
Germany
Renewable auction rounds concentrate ground-mounted half-cell deployments in regions with high solar resource and grid access. The EU Green Deal and CE marking requirements under the F-Gas Regulation shape import eligibility and carbon footprint disclosure obligations. PPA offtakers in Bavaria and North Rhine-Westphalia demand bankability proofs favoring vertically integrated suppliers.
Spain
Independent power producers rewrite module specifications around bankability requirements in the PPA market. National renewable portfolio standards accelerate module efficiency mandates across utility-scale solar fleets. Industrial corridors in Catalonia drive demand for shade-tolerant half-cell designs with improved bypass diode configurations.
India
Production-linked incentive scheme eligibility creates a regulatory tailwind for domestic half-cell module manufacturing capacity. BIS certification mandates directly influence which technologies qualify for domestic manufacturing incentives. Gujarat and Rajasthan host accelerating utility-scale project pipelines seeking higher module wattage.
Italy
Agrivoltaic installations in the Po Valley concentrate demand for bifacial half-cell modules with dual-sided energy capture. The Superbonus incentive scheme has historically concentrated rooftop adoption among residential aggregators. Commercial rooftops with white membrane surfaces prioritize bifacial technology for reflected irradiance capture.
Half-Cell Solar Module Market Competitive Landscape
Concentration sits with integrated ingot-to-module chains that control captive polysilicon and wafer capacity. Three archetypes dominate: vertically integrated Chinese manufacturers with automated stringing expertise, European and North American project developers tightening supplier qualification criteria, and equipment suppliers licensing heterojunction production lines. Competitive moves center on long-term supply agreements displacing spot-market purchasing and strategic consolidation around traceable supply chains.
Among integrated Chinese manufacturers, LONGi Green Energy, JinkoSolar Holding Co., Ltd., and Trina Solar Co., Ltd. anchor the premium monocrystalline half-cell supply tier. These entities exemplify the scale-driven archetype through ingot-to-module vertical control. Hanwha Q CELLS represents the non-Chinese integrated position, while First Solar, Inc. occupies a distinct technology specialization outside silicon-based architectures.
| Leading Market Players |
|---|
| LONGi Green Energy |
| JinkoSolar Holding Co., Ltd. |
| JA Solar Technology Co., Ltd. |
| Trina Solar Co., Ltd. |
| Tongwei Solar |
| Hanwha Q CELLS |
| First Solar, Inc. |
| Canadian Solar Inc. |
| Astronergy (CHINT SOLAR) |
| Others |
Pricing and Supply Chain Analysis
Sixty-day polysilicon inventory cycles in Xinjiang directly amplify pricing power for integrated Chinese manufacturers while compressing margins for non-captive module assemblers. This lead-time asymmetry between feedstock concentration and downstream assembly capacity concentrates margin capture upstream.
Pricing Analysis
GB/T 9535 efficiency mandates dictate the pricing tier structure across Chinese domestic procurement, separating premium n-type half-cell modules from legacy p-type lines facing compliance-driven obsolescence. Pricing stratifies across premium, standard, and economy tiers based on cell efficiency bands and carbon footprint certification status. Cost compression in standard-tier modules is intensifying because silver paste volatility and wafer thinning limits squeeze metallization economics. Utility-scale independent power producers in Germany and Spain exhibit the least price sensitivity, prioritizing bankability and 25-year performance guarantees over per-watt procurement savings.
Supply Chain Analysis
Wafer inventory cycles stretching 45-60 days from Jiangsu ingot pull to Anhui module assembly create working capital intensity that favors scale players with balance-sheet depth. Cell-to-module capacity concentrates in China, South Korea, and Vietnam, with polysilicon feedstock drawing from Xinjiang, Inner Mongolia, and Sichuan. Silver paste, aluminum frames, and ethylene-vinyl acetate encapsulant constitute critical input dependencies. Single-source vulnerability sits with Xinjiang polysilicon purification, where geographic concentration risk escalates under emerging carbon-border adjustment mechanisms. Distribution runs through long-term supply agreements displacing spot-market purchasing for utility-scale deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The half-cell solar module market sits in early-cycle expansion as EU Green Deal efficiency mandates force technology replacement across European solar fleets, accelerating penetration of n-type architectures.
For Market Incumbents: Fortify margin position through backward integration into wafer pulling and polysilicon purification, eliminating feedstock cost volatility exposure. Lock in 10-year supply agreements with utility-scale developers in Germany and Spain before heterojunction equipment licensing fragments the technology base. Priority levers include automated stringing capacity expansion in Anhui and carbon footprint certification investment for EU F-Gas Regulation compliance. For New Entrants and Emerging Players: BIS certification fast-tracks for India's PLI scheme eligibility open white-space access in Gujarat and Rajasthan utility pipelines. Target agrivoltaic bifacial deployments in Italy's Po Valley, where dual-use land revenue streams justify pricing premiums and customer education requirements create incumbent vulnerability. Go-to-market angle centers on elevated mounting structure integration with half-cell module supply. For Investors and Strategic Acquirers: Carve-out targets emerge from state-owned enterprise solar divisions seeking technology refresh capital, particularly those stranded on legacy p-type PERC lines facing GB/T 9535 compliance cliffs. Long-term viability frames around 5-10 year technology convergence toward n-type TOPCon and heterojunction platforms. Signal to watch: equipment supplier order books for heterojunction PECVD tools indicating technology transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Utility-scale developers in Germany and Spain lock in bankable module supply chains. |
| Backward Integration | Captive polysilicon and wafer capacity insulates margins from Xinjiang feedstock volatility. |
| Green Certification Program | EU F-Gas Regulation carbon footprint disclosure qualifies modules for European import eligibility. |
| Technology Licensing | Heterojunction equipment licenses from Japanese and South Korean suppliers enable n-type conversion. |
| Capacity Buildout | Automated stringing expansion in Jiangsu-Anhui clusters drives half-cell assembly cost-down trajectories. |
Research Methodology
A spread of perspectives from utility procurement officers, EPC contractors, cell manufacturing engineers, and silver paste metallization suppliers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against MIIT efficiency filings, EU F-Gas Regulation documentation, and Indian PLI scheme eligibility criteria. Bottom-up module shipment data triangulated against top-down solar capacity installation forecasts across the analysis window.
Segmentation dimensions modeled include cell technology type, module architecture, end-use application, and regional regulatory cluster throughout the forecast period. CAGRs derived from regression analysis of historical capacity additions against policy mandate trajectories and technology cost curves. Industry-specific inputs incorporated silver paste price volatility bands and polysilicon supply concentration risk factors.
Decision-makers should treat outputs as directional under base assumptions of continued EU Green Deal enforcement and China MIIT efficiency threshold maintenance; material deviation in subsidy phase-out timing or trade restriction intensity would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
US Residential Solar PV Market
Solar Power Systems
Ghana Solar Energy Market
Solar Power Systems
Solar Encapsulation Market
Solar Power Systems
Solar Power Meters Market
Solar Power Systems
Solar Panels for Home Market
Solar Power Systems
Amorphous Silicon PV Market
Solar Power Systems
Global Airport Solar Power Market
Solar Power Systems
Solar Kiosk Market
Solar Power Systems
DSC Solar Technologies Market
Solar Power Systems
Global Concentrating Solar Power Market
Solar Power Systems
Mexico Solar Photovoltaic (PV) Market
Solar Power Systems
Trinidad and Tobago Solar Energy Market
Solar Power Systems
Industrial Solar Water Heaters Market
Solar Power Systems
Frameless Solar Panel Market
Solar Power Systems
Global Solar Module for Electric Vehicle Market
Solar Power Systems
Flexible Parylene-Based Solar Cells Market