
 Kuwait Solar Energy Market | 2026-2036
Kuwait Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Kuwait Solar Energy Market Foresight
Utility buyer concentration in Kuwait is pivoting from single-entity tenders to diversified independent power producer arrangements. ACWA Power anchors large-scale project development through its operational track record in Middle Eastern solar parks. Masdar competes aggressively on photovoltaic engineering expertise and regional financing structures. Schneider Electric leverages integrated grid solutions and energy management platforms to sustain its position across utility and commercial installations.
Kuwait solar energy encompasses photovoltaic systems, concentrated solar power, and solar thermal technologies that convert electromagnetic radiation into electrical or thermal energy through semiconductor junctions, mirrored collectors, or absorber tubes operating at temperatures exceeding 300°C for industrial heat applications. Photovoltaic systems dominate current installed capacity due to modular deployment and declining module costs, while concentrated solar power retains structural relevance for utility-scale thermal storage integration. Among end user segments, government and industrial applications lead procurement volumes driven by sovereign energy diversification mandates and petrochemical sector decarbonization requirements.
Kuwait's Ministry of Electricity, Water and Renewable Energy and the Partnerships Technical Bureau govern project licensing and public-private frameworks, with compliance requirements shaping developer qualification criteria and technology selection protocols. The country's national renewable energy roadmap and grid interconnection standards from the Gulf Cooperation Council Interconnection Authority determine market access timelines and technical specifications for new capacity. Stakeholders must monitor tender schedule execution and transmission infrastructure buildout to align project pipelines with offtake availability.
Market Dynamics
The pivot from government single-tender procurement to long-term independent power producer contracts is restructuring Kuwait's solar development pipeline, concentrating project finance expertise among developers capable of 25-year operational commitments.
Growth Catalysts
- Al-Shagaya Renewable Energy Park concentration:The zone southwest of Kuwait City aggregates transmission infrastructure, land permits, and grid interconnection capacity, reducing developer soft costs and accelerating project timelines.
- National development plan renewable mandates:Sovereign energy diversification targets under Kuwait's national roadmap compel the Ministry of Electricity, Water and Renewable Energy to integrate solar into electricity procurement schedules.
- Concentrated solar power thermal storage:Molten salt systems operating above 300°C enable dispatchable renewable output, addressing grid stability concerns that limit photovoltaic-only deployments.
Market Restraints
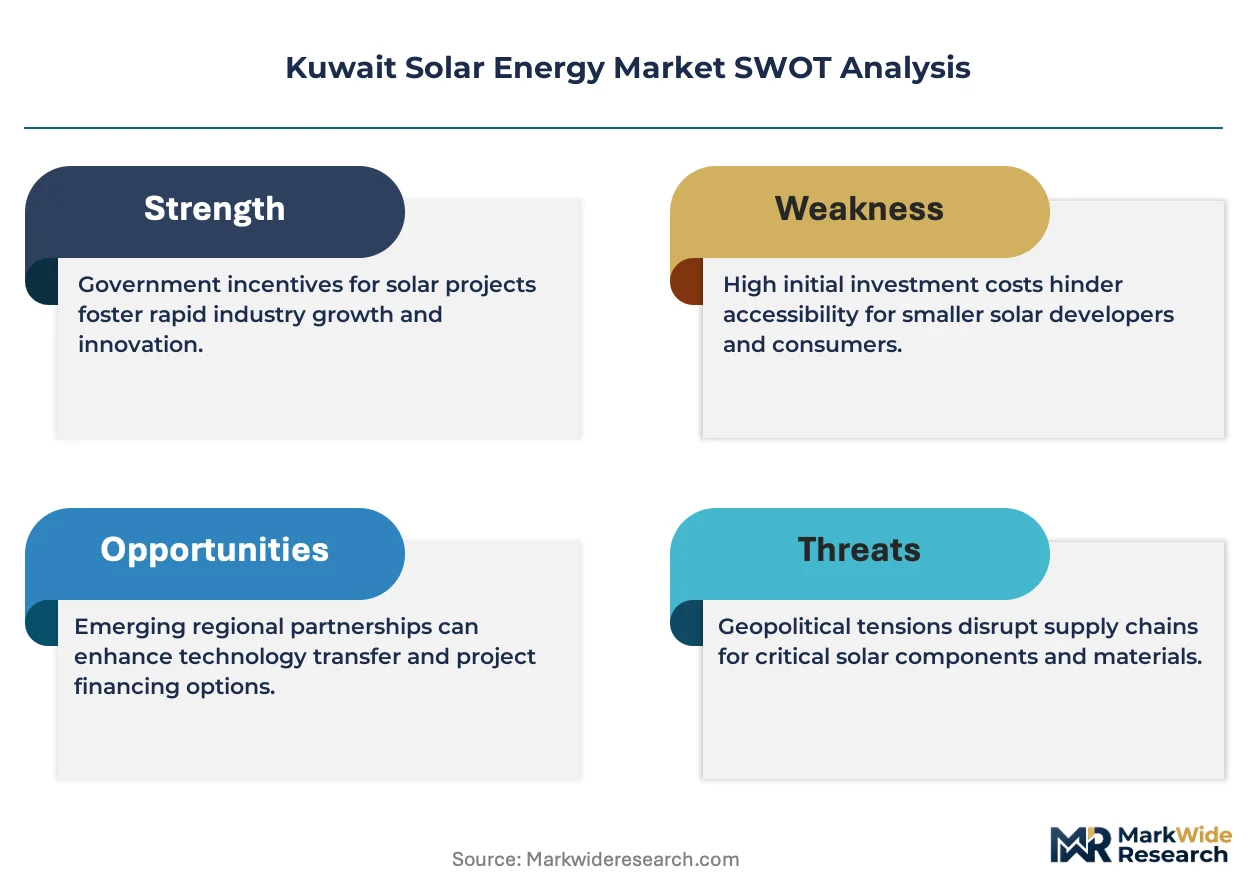
- Polysilicon supply concentration:Module manufacturing relies on upstream polysilicon production concentrated in a narrow supplier base, exposing project developers to input price volatility and forced allocation risks.
- Desert soiling degradation:Fine particulate accumulation on panel surfaces in Kuwait's arid climate reduces energy yield by 15-30% without automated cleaning systems, elevating operational expenditure assumptions.
- Gulf Cooperation Council Interconnection Authority grid standards:Technical specifications for frequency response and reactive power capability impose equipment certification requirements that extend procurement lead times.
Strategic Opportunities
- Petrochemical sector thermal integration:Industrial heat demand from Kuwait's oil refining and chemical complexes creates offtake potential for concentrated solar power steam generation displacing fossil fuel burners.
- Partnerships Technical Bureau framework evolution:Public-private partnership structures are expanding to accommodate smaller distributed commercial installations beyond utility-scale park developments.
- Photovoltaic-plus-storage hybrid configurations:Lithium-ion battery integration with solar farms is expanding into evening peak shaving applications, capturing value from Kuwait's time-of-use tariff differentials.
Industry Challenges
- Grid integration engineering capacity:Local scarcity of power systems engineers familiar with inverter synchronization and harmonic filtering delays commissioning schedules and increases reliance on foreign technical labor.
- Land use permitting coordination:Multiple government entities must approve renewable energy site leases, creating bureaucratic friction that extends pre-construction phases beyond developer financial model assumptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kuwait Solar Energy Market |
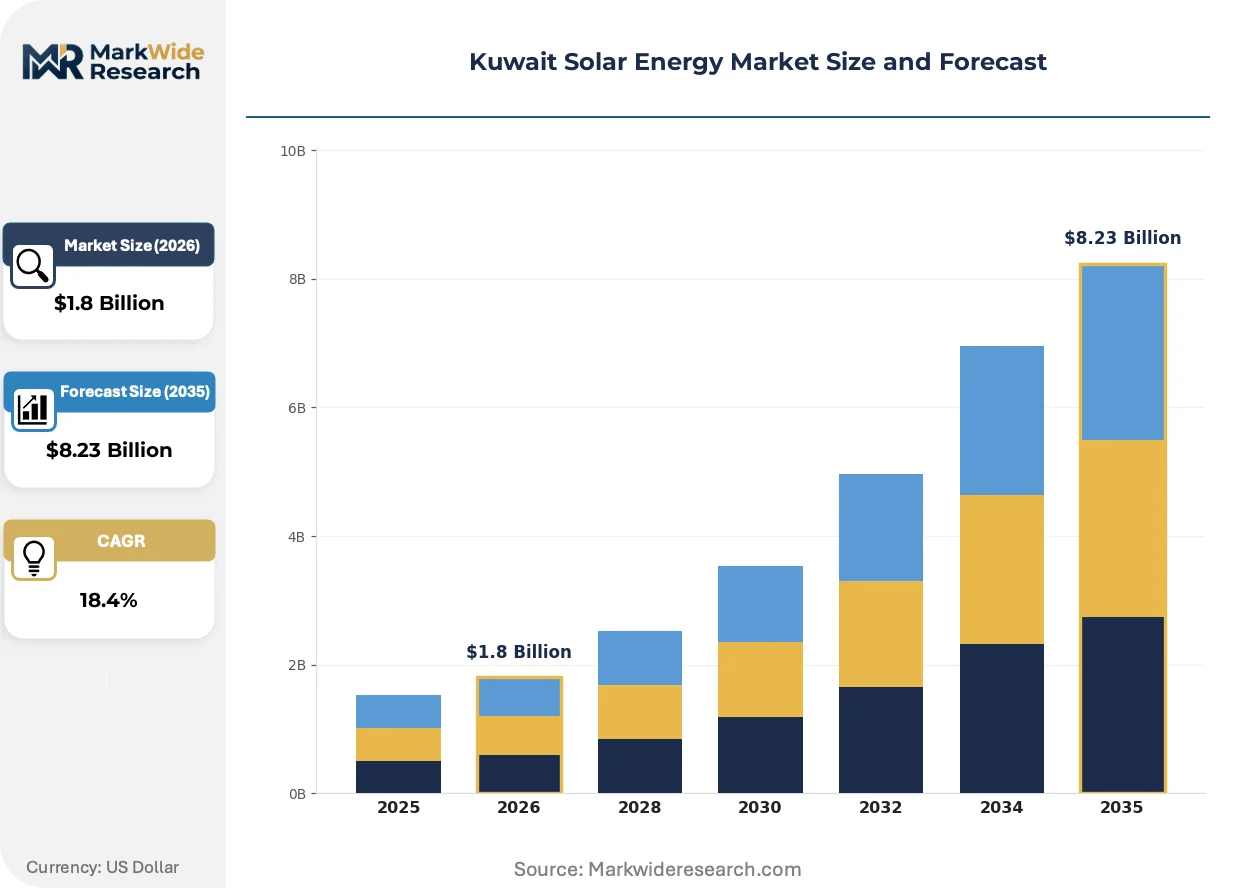
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Systems, Solar Thermal, Concentrated Solar Power, BIPV End User: Residential, Commercial, Industrial, Government Technology: C-Si, Thin Film, CPV, Hybrid Systems Application: Power Generation, Water Heating, Cooling Solutions, Backup Power |
| Companies Covered | EDF Renouvelables, Schneider Electric, ACWA Power, ABB, Huawei Technologies, Masdar, Jinko Power, ACCIONA S.A., TotalEnergies Renewables, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kuwait Solar Energy Market Shifts & Advancements
Technology convergence and procurement model innovation are compressing project development cycles while elevating performance requirements for grid-connected solar assets in Kuwait's utility sector.
Bifacial photovoltaic modules are expanding into utility-scale installations across Kuwait's desert sites, capturing reflected irradiance from high-albedo sand surfaces to boost energy yield. The Ministry of Electricity, Water and Renewable Energy is incorporating bifacial performance guarantees into tender evaluation criteria, favoring developers with advanced irradiance modeling capabilities. This technology is expanding into the Al-Shagaya zone as developers seek to maximize generation density per hectare of leased land.
Kuwait's national renewable energy roadmap is mandating domestic content thresholds for solar project participation, requiring developers to source specified shares of engineering, construction, or equipment from local vendors. The Partnerships Technical Bureau is enforcing these requirements through qualification scoring that disadvantages pure foreign consortiums. Industrial developers are responding by forming joint ventures with Kuwaiti construction firms to satisfy procurement rules while retaining technology control.
Power purchase agreement tenor extension is replacing traditional engineering-procurement-construction contracts as the dominant procurement mechanism for new capacity. Long-term offtake commitments from the Ministry of Electricity, Water and Renewable Energy are attracting institutional capital seeking yield stability, displacing short-term construction-focused developer margins with operational asset ownership returns. This structural shift is most visible in the Al-Shagaya park, where 25-year independent power producer arrangements now dominate tender awards.
Kuwait Solar Energy Market Segmentation
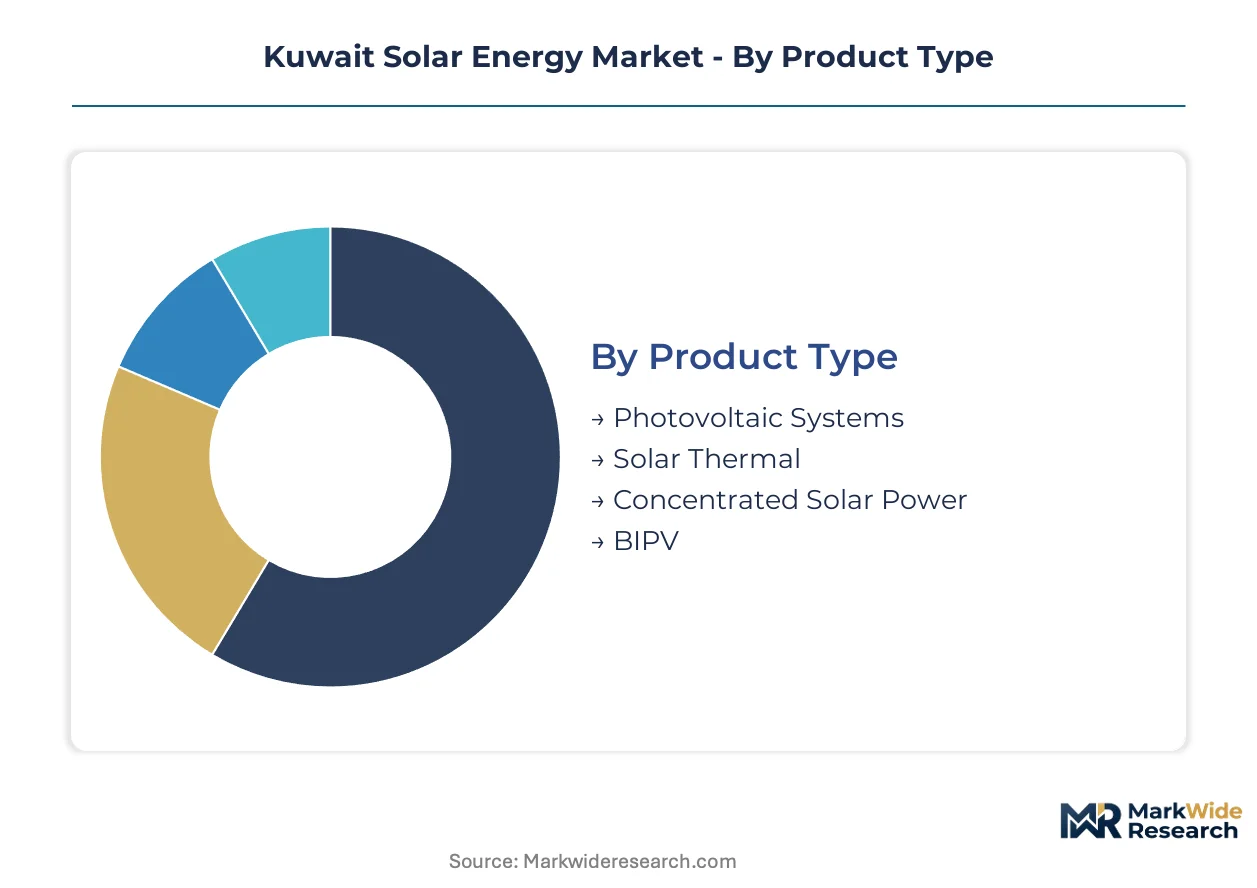
Kuwait's solar market segments reveal divergent deployment economics across technology maturity curves and customer procurement capabilities. Understanding these divides enables developers to align project pipelines with offtake structures and financing availability.
Product Type:
Standalone utility-scale installations dominate procurement volumes while building-integrated systems remain embedded within construction workflows with distinct customer touchpoints.
- Photovoltaic Systems:Crystalline silicon and thin-film modules convert electromagnetic radiation through semiconductor junctions into direct current electricity. Al-Shagaya Renewable Energy Park anchors demand concentration as the Ministry of Electricity, Water and Renewable Energy prioritizes modular deployment with rapid installation timelines and declining unit costs.
- Concentrated Solar Power:Mirrored collector arrays focus solar irradiance onto receiver tubes operating above 300°C, generating thermal energy for steam turbines or molten salt storage. Kuwait's petrochemical sector drives offtake interest for industrial heat applications where thermal storage enables dispatchable output displacing fossil fuel burners.
- Solar Thermal:Flat-plate and evacuated tube collectors harness absorber surfaces for water heating and low-temperature industrial processes.
- BIPV:Building-integrated photovoltaic systems substitute conventional construction materials with power-generating facades and roofing elements.
Photovoltaic systems lead volumes today; concentrated solar power is gaining share fastest.
End User:
Customer segmentation follows sovereign procurement authority concentration versus distributed commercial decision-making autonomy.
- Government:The Ministry of Electricity, Water and Renewable Energy and Partnerships Technical Bureau govern utility-scale tendering through 25-year independent power producer contracts. Al-Shagaya park developments concentrate procurement schedules with standardized technical specifications and transmission infrastructure access.
- Industrial:Petrochemical complexes and oil refineries procure thermal energy for process heat and electricity for operational loads. National development plan renewable mandates compel sectoral decarbonization while concentrated solar power thermal integration addresses baseload requirements.
- Commercial:Office complexes, retail centers, and hospitality operators deploy rooftop installations under evolving public-private partnership frameworks.
- Residential:Single-family and multi-unit dwellings represent emerging distributed generation with net metering policy development.
Government procurement dominates installed capacity; industrial self-generation is expanding most quickly.
Technology:
Cell architecture and manufacturing process differentiation creates performance-cost tradeoffs across Kuwait's desert deployment conditions.
- C-Si:Crystalline silicon cells fabricated from polysilicon wafers deliver proven efficiency and supply chain depth. Bifacial configurations capturing reflected irradiance from high-albedo sand surfaces are expanding into Al-Shagaya zone tenders as developers maximize generation density per hectare.
- Thin Film:Cadmium telluride and copper indium gallium selenide deposition on glass substrates offers temperature coefficient advantages and reduced soiling sensitivity. Desert climate thermal performance and automated cleaning compatibility drive evaluation in specific site conditions.
- CPV:Concentrator photovoltaic systems employ optical lenses or mirrors to focus sunlight onto high-efficiency multi-junction cells.
- Hybrid Systems:Photovoltaic-plus-storage configurations integrate lithium-ion battery dispatch for evening peak shaving applications.
C-Si technology anchors current deployments; hybrid systems with storage integration show steepest expansion trajectory.
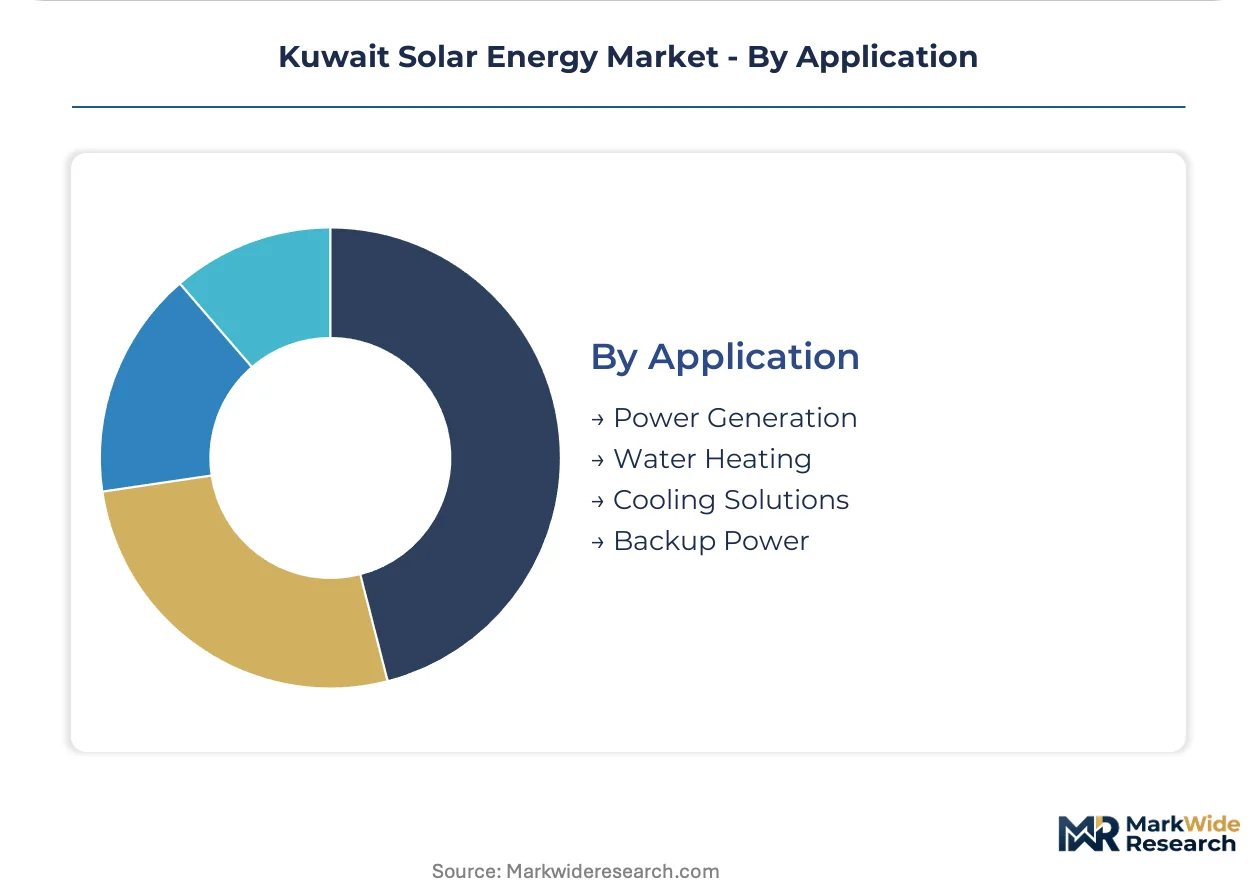
Application:
Use case segmentation separates grid-connected bulk supply from thermal end-uses and resilience-oriented backup configurations.
- Power Generation:Grid-connected solar farms feed electricity into the Kuwaiti transmission network under power purchase agreement structures. Gulf Cooperation Council Interconnection Authority standards for frequency response and reactive power capability shape equipment selection and commissioning protocols.
- Water Heating:Solar thermal collectors address domestic and commercial hot water demand with direct thermal conversion bypassing electrical intermediation.
- Cooling Solutions:Absorption chillers driven by solar thermal energy or photovoltaic-powered compression systems serve air conditioning loads.
- Backup Power:Battery-integrated solar installations provide resilience for critical facilities during grid disturbances.
Power generation commands the largest share; cooling solutions are climbing fastest amid building efficiency regulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia deploys concentrated solar power at scale while the UAE dominates photovoltaic manufacturing partnerships, yet Kuwait concentrates procurement authority within a single renewable energy park southwest of Kuwait City.
Saudi Arabia
The Kingdom's Public Investment Fund channels capital into gigawatt-scale solar developments across the Red Sea coast. The Saudi Power Procurement Company governs long-term power purchase agreements under the National Renewable Energy Program. The Sudair and Al Shuaibah clusters anchor manufacturing and deployment activity with ACWA Power-led consortia securing dominant project positions.
United Arab Emirates
Masdar and Dubai Electricity and Water Authority drive procurement volumes through the Mohammed bin Rashid Al Maktoum Solar Park. The Emirates Water and Electricity Company mandates domestic content thresholds for independent power producer qualification. Jebel Ali and the Al Dhafra region concentrate engineering expertise and module assembly capacity for regional export.
Qatar
The Qatar General Electricity and Water Corporation integrates solar into desalination complexes to reduce fossil fuel dependency for water production. Kahramaa's renewable energy strategy mandates 20% clean power by 2030. Industrial zones around Ras Laffan host pilot concentrated solar power installations serving petrochemical thermal loads.
Egypt
The New and Renewable Energy Authority governs feed-in tariff structures for private solar development across the Western Desert. The Egyptian Electricity Transmission Company mandates grid code compliance for utility-scale interconnectors. The Benban Solar Park near Aswan aggregates over 1.5 gigawatts of photovoltaic capacity from international developer consortia.
Jordan
The Ministry of Energy and Mineral Resources liberalized renewable energy procurement through direct private sales agreements. Grid integration standards from the National Electric Power Company shape inverter certification requirements. Ma'an and the southern governorates concentrate wind-solar hybrid developments exploiting high irradiance and transmission corridor access.
Kuwait Solar Energy Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Kuwait's solar development pipeline, creating a tiered structure where utility-scale experience determines tender access. The vendor base clusters around three archetypes: integrated energy majors leveraging balance sheet scale, regional developers with Middle Eastern operational track records, and technology providers supplying inverters and grid infrastructure. Strategic moves concentrate on forming joint ventures with Kuwaiti construction firms to satisfy domestic content requirements and securing 25-year power purchase agreement tenors that attract institutional capital.
Within the regional developer tier, ACWA Power and Masdar exemplify the project finance expertise and long-term operational commitment that Kuwait's Ministry of Electricity, Water and Renewable Energy prioritizes in Al-Shagaya park tenders. Among diversified technology conglomerates, Schneider Electric and Huawei Technologies occupy positions spanning grid infrastructure and digital energy management platforms. These named entities represent the competitive archetypes—regional IPP specialists and integrated equipment suppliers—that dominate qualification scoring under Partnerships Technical Bureau frameworks.
| Leading Market Players |
|---|
| EDF Renouvelables |
| Schneider Electric |
| ACWA Power |
| ABB |
| Huawei Technologies |
| Masdar |
| Jinko Power |
| ACCIONA S.A. |
| TotalEnergies Renewables |
| Others |
Supply & Pricing Matrix
Utility-scale independent power producer procurement from Kuwait's Ministry of Electricity, Water and Renewable Energy concentrates buyer power into long-term power purchase agreement structures that compress developer margins while rewarding operational asset ownership returns.
Pricing Analysis
Capacity additions in China and Southeast Asia are reshaping price floors for photovoltaic modules imported into Kuwaiti solar developments. Project economics stratify across premium bifacial configurations with performance guarantees, standard monofacial crystalline silicon arrays, and economy thin-film alternatives selected for desert thermal tolerance. Price erosion runs through the economy tier as polysilicon oversupply from Chinese manufacturers intensifies module cost competition. Industrial petrochemical offtakers demonstrate lowest price sensitivity due to thermal storage integration premiums, while commercial distributed installations face acute capital constraint pressures.
Supply Chain Analysis
Dual-sourcing qualification mandates from the Partnerships Technical Bureau require developers to demonstrate multi-supplier module and inverter procurement strategies before Al-Shagaya park tender participation. Manufacturing concentration in China, Vietnam, and Malaysia dominates crystalline silicon cell and module assembly capacity feeding Kuwaiti project pipelines. Polysilicon ingots, silver metallization pastes, and aluminum framing extrusions constitute critical input dependencies tethered to commodity price volatility. Single-source vulnerability from concentrated polysilicon purification exposes developers to forced allocation risks during supply disruptions. Distribution runs through engineering-procurement-construction contractors with established Kuwaiti joint venture structures satisfying domestic content thresholds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kuwait's solar market represents a late-cycle quality story where 25-year operational commitments and bifacial performance guarantees displace price-only competition in Al-Shagaya tender awards.
For Market Incumbents: Cement position through backward integration into module supply chains and captive development of automated desert cleaning systems addressing soiling degradation. ACWA Power and Masdar archetypes must defend against emerging regional developers acquiring local construction joint venture capabilities by deepening Partnerships Technical Bureau relationship infrastructure and pre-qualifying for expanded distributed commercial frameworks. For New Entrants and Emerging Players: Launch via concentrated solar power thermal storage specialization targeting petrochemical sector industrial heat offtake agreements outside Al-Shagaya park concentration. The most penetrable white space sits in commercial rooftop installations under evolving public-private partnership structures, with lithium-ion battery hybrid configurations offering evening peak shaving value capture from time-of-use tariff differentials. For Investors and Strategic Acquirers: Regional sovereign wealth funds and infrastructure-focused institutional capital represent the most active acquirer category in this space, attracted by yield stability from Ministry of Electricity, Water and Renewable Energy offtake commitments. Acquisition targets should demonstrate 25-year power purchase agreement execution capability and Kuwaiti joint venture operational presence. The signal to watch is Partnerships Technical Bureau framework expansion into smaller distributed commercial installations as inflection indicator for addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Execution | Long-term offtake commitments from Kuwait's Ministry of Electricity attract institutional capital seeking yield stability. |
| Backward Integration into Module Supply | Developer control over polysilicon sourcing mitigates forced allocation risks and input price volatility exposure. |
| Automated Desert Cleaning System Development | Proprietary soiling mitigation technology addresses 15-30% energy yield degradation in Kuwait's arid climate. |
| Kuwaiti Joint Venture Formation | Local construction partnerships satisfy Partnerships Technical Bureau domestic content qualification requirements. |
| Lithium-Ion Storage Integration | Battery hybrid configurations capture value from evening peak shaving under Kuwait's time-of-use tariff structures. |
Research Methodology
Bottom-up utility and industrial offtake modeling reconciled against top-down module supply and project pipeline tracking forms the analytical core of this study. Primary interviews with utility planning officers at the Ministry of Electricity, Water and Renewable Energy, independent power producer project developers, engineering-procurement-construction contractors, and Gulf Cooperation Council Interconnection Authority grid operators combined with secondary validation from IEA renewable energy reports, FERC-style regulatory filings, and regional project development databases. Triangulation across these sources ensures demand-side procurement schedules align with supply-side manufacturing capacity and transmission infrastructure buildout timelines.
Historical trendline analysis of tender award patterns and capacity installation trajectories informed the projection framework across the analysis window. Segmentation dimensions modeled include technology type, project scale tier, end-user category, and regulatory framework cluster. CAGRs were derived from fitted trend extrapolation adjusted for policy mandate acceleration effects and grid interconnection constraint bottlenecks. Forecast inputs incorporated Partnerships Technical Bureau tender schedule execution probability and Al-Shagaya park transmission infrastructure commissioning timelines.
Several conditions sit outside the modeled scope, including geopolitical disruption to polysilicon supply corridors and unanticipated shifts in Gulf Cooperation Council Interconnection Authority grid code requirements. Forecasts reflect assumptions regarding sovereign renewable mandate continuity and institutional capital appetite for emerging market infrastructure exposure. Deviation in Partnerships Technical Bureau public-private partnership framework evolution or Ministry of Electricity procurement schedule acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Canada Solar Energy Market
Solar Power Systems
Middle East and Africa Solar PV Inverters Market
Solar Power Systems
Outdoor Solar LED Market
Solar Power Systems
Solar Tracker Installation Market
Solar Power Systems
Solar PV Panels Market
Solar Power Systems
Thin Film Solar PV Market
Solar Power Systems
Amorphous Silicon PV Market
Solar Power Systems
Solar Cullet Market
Solar Power Systems
On-Site Photovoltaic Solar Power for Data Centers Market
Solar Power Systems
Solar Encapsulation Market
Solar Power Systems
Netherlands Solar Energy Market
Solar Power Systems
Thailand Solar Energy Market
Solar Power Systems
Global Micro Solar Inverter Market
Solar Power Systems
Solar Concentrator Market
Solar Power Systems
Residential Solar Panels Market
Solar Power Systems
Global EV Solar Modules Market