
 Residential Solar Inverter Market | 2026-2036
Residential Solar Inverter Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Solar Inverter Market Insights
Silicon carbide is consolidating its position in residential inverter power electronics, replacing silicon IGBTs across efficiency-critical applications. SMA leverages its German engineering heritage to sustain premium positioning in European markets. Enphase specializes in microinverter architectures that dominate the retrofit segment. SolarEdge controls the power optimizer channel through integrated module-level electronics.
A residential solar inverter converts direct current from rooftop photovoltaic arrays into alternating current synchronized with household loads or utility grids, typically operating at 95-98% conversion efficiency with maximum power point tracking across variable irradiance conditions. String inverter configurations anchor volume shipments in new-build single-family installations where module uniformity permits centralized conversion. Microinverter deployments are accelerating fastest among multi-family homes and complex roof geometries where shading mismatch degrades string performance. Hybrid inverters incorporating battery charge controllers command the deepest margin pools as homeowners prioritize backup power resilience.
Grid interconnection standards from IEEE 1547 in the United States and IEC 62109 internationally dictate anti-islanding thresholds, voltage ride-through requirements, and electromagnetic compatibility testing that shape product development roadmaps. California's Title 24 building energy code and Germany's EEG framework mandate smart inverter capabilities including reactive power support and dynamic grid stabilization functions. Stakeholders must monitor evolving utility rate structures and storage mandate expansions to align product portfolios with shifting homeowner value propositions.
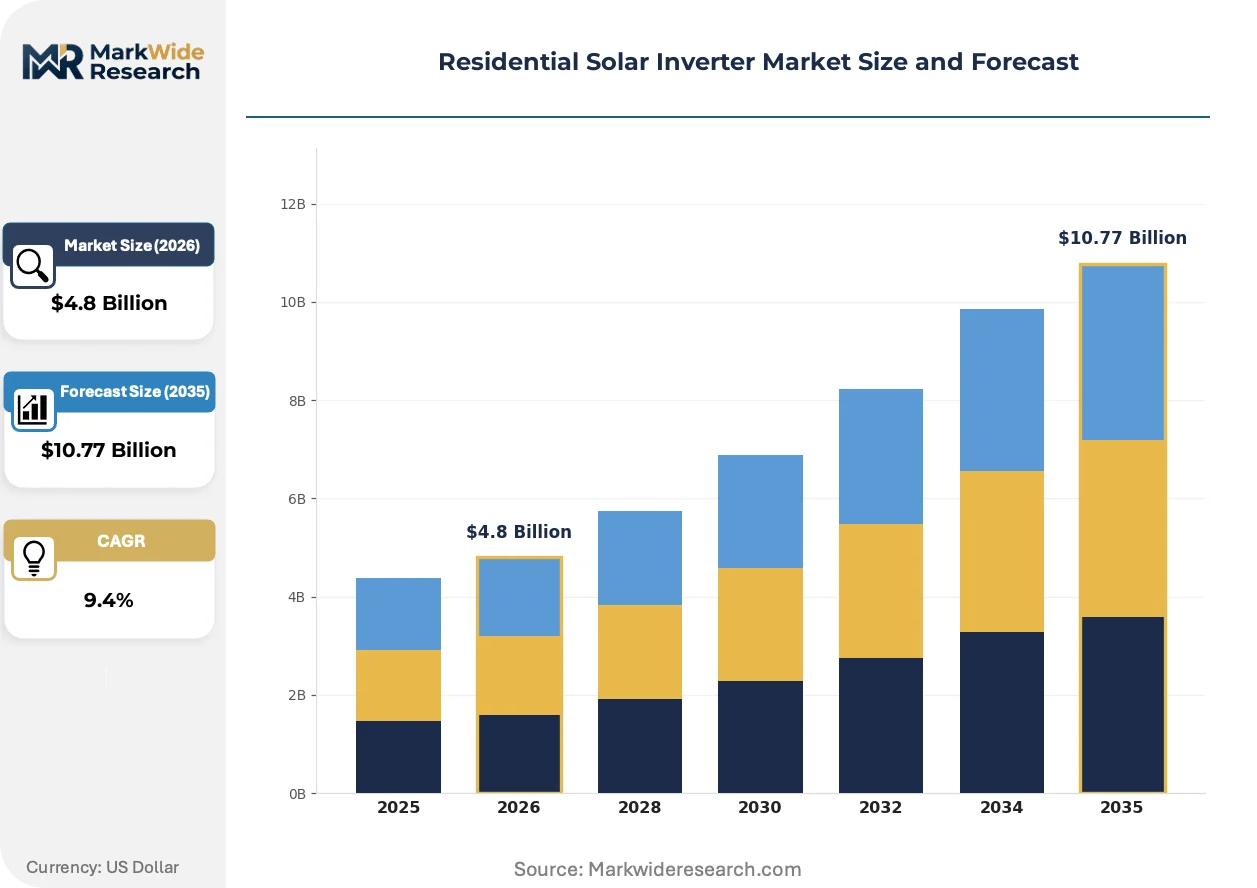
Market Dynamics
Silicon carbide semiconductor technology is absorbing capital allocation across power electronics supply chains, compressing incumbent silicon IGBT architectures while grid codes in Germany, Australia, and the United States mandate smarter inverter capabilities.
Growth Catalysts
- California's Title 24 energy code:This mandate requires solar-ready construction and smart inverter functionality in new residential builds, pulling demand toward integrated battery-compatible systems.
- Single-family rooftop solar:Homeowners in Australia and Germany are retrofitting existing arrays with hybrid inverters as feed-in tariffs decline and self-consumption economics improve.
- Silicon carbide MOSFETs:These wide-bandgap devices enable 99% peak efficiency and 50% reduction in thermal management hardware, justifying premium positioning in efficiency-critical applications.
Market Restraints
- Semiconductor supply concentration:Wolfspeed and Coherent control 70% of silicon carbide substrate supply, creating input bottleneck risk for inverter OEMs scaling production.
- IEC 62109 certification timelines:Safety testing for grid-tied inverters requires 8-14 months of third-party validation, delaying product launches and freezing design iterations.
- String inverter technical limitations:Centralized architectures suffer 15-25% output degradation from partial shading on complex roof geometries, limiting addressable market in multi-family housing.
Strategic Opportunities
- United States IRA storage incentives:The standalone 30% investment tax credit for residential batteries is pulling hybrid inverter attach rates above 40% in key states.
- Virtual power plant aggregation:Software platforms are monetizing distributed inverter fleets for frequency regulation, creating recurring revenue streams beyond hardware sales.
- India's rooftop solar program:PLI scheme subsidies and net metering expansion in Gujarat and Rajasthan are opening volume markets for cost-optimized string inverter platforms.
Industry Challenges
- Power electronics talent scarcity:Design engineers with silicon carbide gate driver expertise command 40% wage premiums, constraining R&D velocity at mid-tier manufacturers.
- Legacy grid infrastructure interoperability:Aging distribution transformers in rural Germany and Australia struggle with bidirectional power flows from battery-backed inverters, triggering costly utility-side upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Solar Inverter Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.77 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grid-Tied, Off-Grid, Hybrid, Microinverter Technology: String Inverter, Power Optimizer, Central Inverter, Battery Inverter End User: Single-Family Homes, Multi-Family Homes, Residential Complexes, Green Buildings Installation Type: Roof-Mounted, Ground-Mounted, Building-Integrated, Portable |
| Companies Covered | SMA, Hoymiles, Enphase, Generac, Sol-Ark, SolarEdge, APsystems, Qcells, Tesla, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Solar Inverter Market Trends and Innovations
Power semiconductor material transitions and software-defined grid services are compressing hardware differentiation cycles while opening new monetization vectors beyond unit sales.
Silicon carbide power modules are absorbing design wins across 3-10 kW residential segments, replacing silicon super-junction MOSFETs in boost stages and H-bridge topologies. String inverter manufacturers in Germany and the United States are adopting these devices first, prioritizing efficiency gains that justify premium pricing in high-electricity-cost markets. The technology is absorbing margin pressure from commodity silicon competitors by enabling passive cooling architectures that eliminate fan failure modes and reduce acoustic signatures.
Germany's EEG 2023 framework mandates dynamic power curtailment and reactive power provision from residential inverters above 4.6 kW, forcing firmware architecture redesigns. Manufacturers must now embed grid-forming capabilities and real-time telemetry that previously resided in utility-scale equipment. Single-phase string inverters sold into the German market face the steepest compliance burden, with certification bodies extending validation timelines by 30% to verify grid support functions.
Installer channel consolidation is compressing inverter brand diversity at the point of sale, with national roofing and electrical contractors standardizing on two-three approved vendor lists. Independent installers in Australia and the United States are losing share to vertically integrated solar retailers who captive-source inverters through exclusive OEM agreements. California and Texas exhibit the most concentrated procurement patterns, where top-five installation platforms control 60% of residential inverter placement decisions.
Residential Solar Inverter Market Segmentation
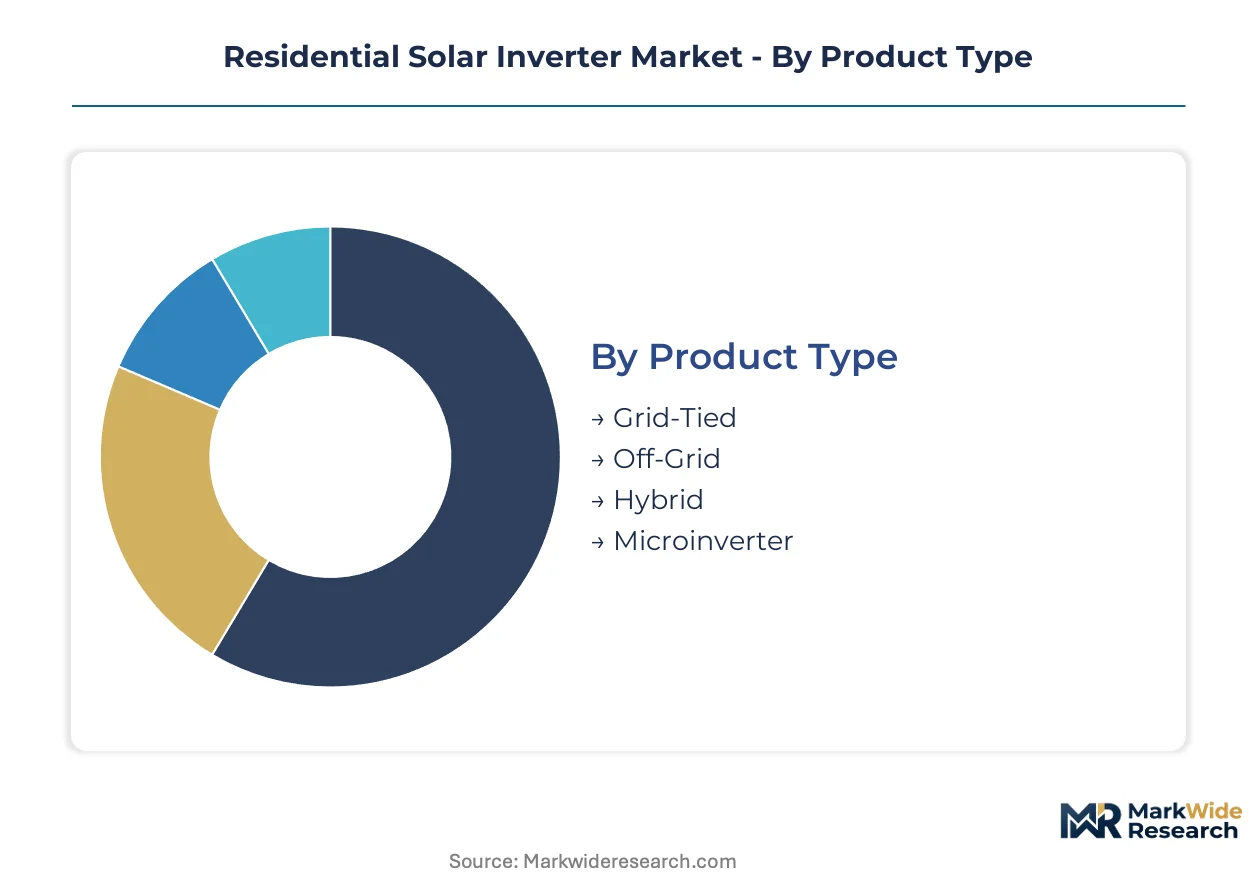
Residential solar inverter segmentation reflects divergent technical requirements across grid interconnection modes, installation topologies, and homeowner energy strategies. Product architecture choices determine whether systems operate as standalone power conversion units or as embedded components within broader energy management ecosystems.
Product Type:
Integration depth varies sharply across this category, with some segments functioning as isolated conversion devices while others embed storage control and grid services natively.
- Hybrid:Combines DC/AC conversion with integrated battery charge controllers and backup power management, enabling seamless islanding during grid outages. Demand concentrates in Germany and Australia where homeowners prioritize self-consumption optimization as feed-in tariffs decline. These systems command the deepest margin pools by capturing value from both solar generation and storage arbitrage.
- Grid-Tied:Synchronizes photovoltaic output with utility frequency without storage capability, representing the baseline architecture for net-metering markets. Single-family installations in the United States dominate placements where IEEE 1547 compliance enables straightforward interconnection approval.
- Off-Grid:Standalone power conversion for remote properties lacking utility infrastructure, incorporating battery management and load prioritization logic. Rural installations in Western Australia and mountainous regions of Germany rely on these systems where grid extension proves economically unviable.
- Microinverter:Module-level power electronics that eliminate string mismatch losses through distributed conversion at each panel. Complex roof geometries with partial shading in multi-family housing drive adoption where centralized architectures suffer 15-25% output degradation.
Volume placements concentrate in Grid-Tied configurations; the faster expansion belongs to Hybrid systems as battery attach rates climb above 40% in key incentive markets.
Technology:
Cost tier stratification separates commodity string platforms from premium power optimizer and battery inverter architectures with embedded intelligence.
- String Inverter:Centralized DC/AC conversion for uniform module arrays, delivering 95-98% efficiency at the lowest installed cost per watt. New-build single-family homes in Australia and Germany anchor volume shipments where roof geometry permits homogeneous panel orientation.
- Power Optimizer:Module-level DC/DC conditioning paired with simplified string inverters, enabling per-panel maximum power point tracking without full microinverter cost. Retrofit installations in the United States with aging arrays or shading constraints drive fastest uptake.
- Battery Inverter:Bidirectional power conversion for AC-coupled storage systems, managing charge/discharge cycles and grid export limitations. California's Title 24 storage mandates and Germany's EEG dynamic curtailment requirements accelerate specification.
- Central Inverter:High-capacity conversion platforms typically scaled above residential thresholds, appearing in small commercial or shared solar configurations attached to residential complexes. Germany's apartment building solar programs occasionally deploy downsized commercial units.
Shipments stratify across cost tiers with String Inverter commanding unit volume; Power Optimizer architectures gain share fastest in retrofit-heavy markets.
End User:
Customer type determines installation scale, regulatory pathway, and decision-making authority complexity.
- Single-Family Homes:Owner-occupied detached housing with straightforward rooftop access and unilateral procurement decisions. Australia's suburban expansion corridors and Texas metropolitan rings generate concentrated demand for 5-10 kW systems.
- Multi-Family Homes:Duplexes, townhouses, and small apartment buildings requiring shared infrastructure agreements and split incentive resolution. California's virtual net metering frameworks and Germany's tenant electricity models unlock these segments.
- Residential Complexes:Master-planned communities and homeowner association-governed developments with centralized solar and distributed billing. Arizona retirement communities and Florida condominium towers represent emerging specification channels.
- Green Buildings:Certification-driven construction meeting LEED, BREEAM, or national efficiency standards with integrated renewable mandates. Germany's KfW efficiency house programs and California's CALGreen code drive specification of smart inverter functionality.
Single-Family Homes anchor installation counts; Green Buildings exhibit the steepest expansion trajectory as building codes tighten renewable integration requirements.
Installation Type:
Mounting topology constrains inverter thermal management, accessibility for maintenance, and architectural integration depth.
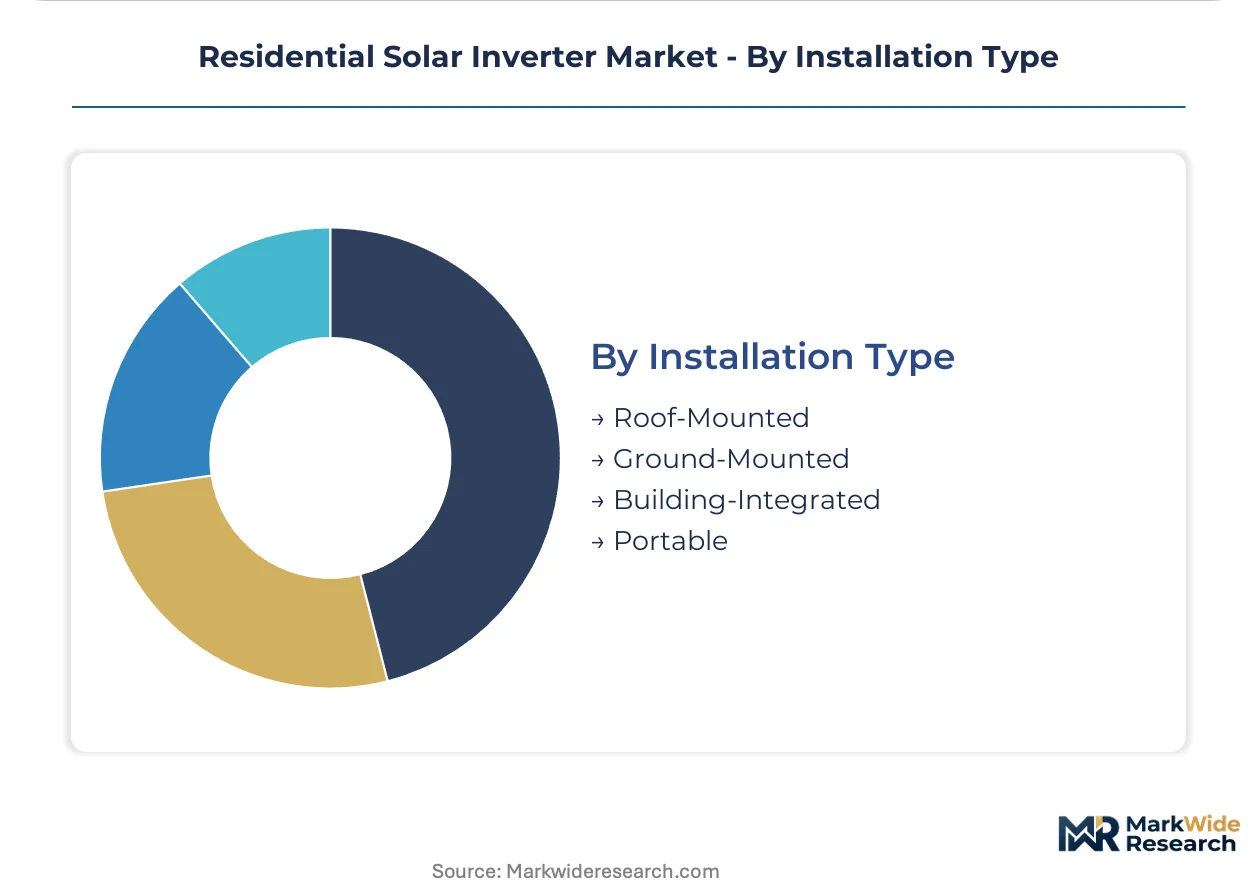
- Roof-Mounted:Panels affixed to pitched or flat residential roofing with inverters sited in garages, basements, or exterior walls. Australia's tile roof heritage and Germany's steep-pitched slate traditions shape weatherproofing and mounting hardware requirements.
- Ground-Mounted:Free-standing array structures on residential property with dedicated inverter shelters, appearing on large rural lots. Texas Hill Country and Arizona desert properties with acreage deploy these configurations.
- Building-Integrated:Photovoltaic elements replacing conventional roofing or facade materials, requiring specialized inverters matched to atypical electrical characteristics. Germany's solar tile subsidies and California's solar-ready mandate drive niche adoption.
- Portable:Temporary or mobile power systems for recreational vehicles, emergency backup, or rental properties with restrictive covenants. Australian caravan culture and United States disaster preparedness markets sustain this segment.
Roof-Mounted placements dominate absolute volumes; Building-Integrated configurations climb fastest as aesthetic constraints override pure economics in premium housing markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Homeowners in Germany, Australia, and the United States drive the deepest rooftop solar penetration, with each market evolving distinct regulatory frameworks that reshape inverter specifications and procurement patterns.
United States
California's Title 24 energy code mandates solar-ready construction and smart inverter functionality in new residential builds, pulling demand toward battery-compatible hybrid systems. The IRA's standalone 30% investment tax credit for residential batteries has pushed hybrid inverter attach rates above 40% in key states. Installer channel consolidation concentrates procurement decisions in California and Texas, where top-five installation platforms control 60% of residential inverter placement decisions.
Germany
Single-family homeowners are retrofitting existing arrays with hybrid inverters as EEG feed-in tariffs decline and self-consumption economics improve. The EEG 2023 framework mandates dynamic power curtailment and reactive power provision from residential inverters above 4.6 kW, forcing firmware architecture redesigns. Certification bodies in Berlin and Munich have extended validation timelines by 30% to verify grid support functions for single-phase string inverters.
Australia
Suburban expansion corridors in Sydney and Melbourne generate concentrated demand for 5-10 kW systems among owner-occupied detached housing. Declining feed-in tariffs in New South Wales and Victoria accelerate hybrid inverter retrofits as homeowners prioritize self-consumption optimization. Rural Western Australia relies on off-grid standalone systems where grid extension proves economically unviable.
India
PLI scheme subsidies and net metering expansion in Gujarat and Rajasthan are opening volume markets for cost-optimized string inverter platforms. The country's rooftop solar program targets residential deployment through state-level implementation agencies. Industrial clusters in Ahmedabad and Jaipur concentrate manufacturing partnerships for regionally adapted power electronics.
Residential Solar Inverter Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium engineering heritage commanding pricing power in European markets while scale-driven Asian producers capture volume in cost-sensitive regions. The vendor base organizes into three tiers: integrated energy management platforms, pure-play power electronics specialists, and contract manufacturers serving private-label channels. Consolidation pressures intensify as national roofing and electrical contractors standardize procurement around two-three approved vendor lists. Dominant competitive moves include exclusive OEM agreements with vertically integrated solar retailers and silicon carbide technology licensing partnerships that compress R&D timelines.
Within the integrated platform tier, Tesla and Generac exemplify archetypes that bundle inverter functionality with broader home energy ecosystems, occupying positions where hardware margins subsidize software and services revenue. SMA represents the engineering-heritage specialist model, leveraging German technical credibility to sustain premium positioning amid commodity pressure. Enphase and SolarEdge anchor the distributed power electronics segment, with the former exemplifying microinverter architecture specialization and the latter representing module-level power optimizer integration. These five entities collectively illustrate how competitive positioning stratifies across technology architecture, geographic focus, and vertical integration depth.
| Leading Market Players |
|---|
| SMA |
| Hoymiles |
| Enphase |
| Generac |
| Sol-Ark |
| SolarEdge |
| APsystems |
| Qcells |
| Tesla |
| Others |
Pricing and Supply Chain Analysis
California's Title 24 energy code gates both qualified supply and premium-tier pricing access, restricting installer eligibility to vendors with certified smart inverter architectures while compressing margins on commodity string platforms. German EEG compliance requirements and Australian CEC listing standards replicate this filtering mechanism across key demand centers, concentrating pricing power with engineering-heritage specialists.
Pricing Analysis
Volume placements concentrate in economy-tier string inverters while margin pools deepen in hybrid and microinverter segments. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and silicon carbide component inclusion. Pricing pressure stems from installer channel consolidation, with national contractors standardizing procurement around approved vendor lists. Multi-family housing and retrofit installers exhibit highest price sensitivity; green building and backup-power segments show lowest.
Supply Chain Analysis
India's domestic-content requirements under the PLI scheme and proposed US IRA domestic manufacturing bonuses are reshaping sourcing patterns for power electronics assembly. Silicon carbide substrate supply concentrates in the United States, Japan, and Germany; power module packaging and final inverter assembly draw heavily from China, Vietnam, and Mexico. Raw material dependencies include silicon carbide wafers, copper busbars, aluminum heat sinks, and rare-earth magnetic components. Single-source vulnerability in wide-bandgap semiconductor substrates creates supply risk. Distribution runs through vertically integrated solar retailers and national electrical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon carbide substrate capacity constraints prop pricing premiums, creating a supply-constrained market structure where qualified component access determines competitive viability.
For Market Incumbents: Anticipate silicon carbide supply rationing by securing long-term substrate agreements with Wolfspeed or Coherent before capacity allocations freeze. Defend channel position by embedding firmware-based grid services that exceed baseline IEEE 1547 compliance, creating switching costs for installer partners. Prioritize certification investment in Germany's extended EEG 2023 validation timelines to capture premium-tier placement. For New Entrants and Emerging Players: India's PLI scheme in Gujarat and Rajasthan opens a window for cost-optimized string inverter platforms with localized assembly partnerships. Target Western Australia's off-grid segment where grid extension economics favor standalone power systems over utility interconnection. Pursue white-label OEM agreements with national roofing contractors as the fastest go-to-market angle. For Investors and Strategic Acquirers: Hybrid inverter attach rates crossing 40% in key US states is the leading indicator that storage-integrated architectures will command sustained margin premiums. Five-to-ten year viability favors engineering-heritage specialists with silicon carbide gate driver expertise and firmware-defined grid service capabilities. Monitor IEC 62109 certification timeline extensions as the signal for R&D velocity constraints compressing mid-tier competitive sets.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Technology Licensing | Accelerates power electronics R&D timelines for inverter OEMs competing on efficiency benchmarks. |
| Exclusive Installer Channel Agreements | Locks procurement decisions with national contractors controlling 60% of California and Texas placements. |
| Virtual Power Plant Software Integration | Creates recurring revenue streams beyond hardware through FERC Order 2222-enabled grid services. |
| Domestic Manufacturing Footprint Expansion | Captures IRA production tax credits while reducing tariff exposure on Chinese-assembled power modules. |
| EEG 2023 Firmware Certification | Enables German market access where dynamic curtailment mandates extend validation timelines by 30%. |
Research Methodology
Regulatory filings from FERC, CEA, and Germany's Bundesnetzagentur formed the secondary backbone, supplemented by customs trade data and inverter shipment disclosures. Primary interviews with utility interconnection engineers, EPC procurement managers, and silicon carbide substrate specialists validated demand assumptions. Bottom-up modeling of installer channel placements triangulated against top-down market sizing across product type, technology, and end user dimensions.
Historical trendline analysis of rooftop solar penetration rates and inverter replacement cycles informed the projection framework. Segmentation modeling spanned product architecture, power electronics technology, installation topology, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating feed-in tariff phase-out schedules and storage incentive trajectories. Forecast inputs included silicon carbide adoption curves and grid code evolution timelines.
Caveats apply where semiconductor supply disruptions or accelerated net metering policy reversals could materially shift the outlook. Forecasts reflect documented assumptions about installer channel consolidation velocity and wide-bandgap component cost curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Off-Grid Solar Power Market
Solar Power Systems
US Solar PV Market
Solar Power Systems
Slovakia Renewable Energy Market
Solar Power Systems
Solar Polysilicon Ingot Wafer Cell Module Market
Solar Power Systems
Building Integrated Photovoltaic (BIPV) Market
Solar Power Systems
Iran Solar Energy Market
Solar Power Systems
Box Solar Cookers Market
Solar Power Systems
Egypt Solar Energy Market
Solar Power Systems
Solar Fuel Market
Solar Power Systems
Off Grid Solar Market
Solar Power Systems
Portugal Solar Energy Market
Solar Power Systems
Grid Connected PV Systems Market
Solar Power Systems
Solar Shingles Market
Solar Power Systems
US Solar Films Market
Solar Power Systems
Europe Solar Photovoltaic (PV) Market
Solar Power Systems
Residential Solar Panels Market