
 CPV Solar Sales Market | 2026-2036
CPV Solar Sales Market Size, Share, and Industry Trends Forecast 2026-2036
CPV Solar Sales Market Insights
The EU Green Deal's renewable energy targets is broadening the addressable market for high-efficiency solar technologies across member states. SunPower Corporation leverages its vertically integrated cell manufacturing to sustain technology leadership in III-V multijunction architectures. Amonix anchors its competitive position through utility-scale tracker-integrated deployments in high-DNI zones. Arzon Solar differentiates via compact refractive concentrator designs that reduce balance-of-system costs for commercial adopters.
Concentrator photovoltaic systems employ lenses or mirrors to focus sunlight onto small-area, high-efficiency multijunction solar cells, typically achieving conversion efficiencies above 40% under concentrated illumination of 500 to 1000 suns. These systems require direct normal irradiance above 1800 kWh/m² annually and active dual-axis tracking to maintain optical alignment, serving primarily utility-scale and large commercial installations where land availability and solar resource quality justify capital intensity. The technology dimension shows Fresnel lens architectures leading installed base while hybrid systems represent the fastest-expanding segment as developers combine concentrating and flat-plate elements to broaden geographic applicability. Application-side structural pools concentrate in utility-scale procurement where power purchase agreement durations and offtaker creditworthiness determine margin distribution, with commercial installations gaining traction where behind-the-meter economics align with peak demand charges.
FERC interconnection standards and state-level renewable portfolio obligations in California, Arizona, and Nevada shape deployment timelines and grid access prioritization for CPV projects. The EPA's greenhouse gas reduction frameworks and state public utility commission integrated resource planning mandates indirectly steer utility procurement toward high-efficiency, land-efficient generation technologies. Stakeholders must monitor tracker reliability degradation curves and multijunction cell supply chain concentration as these variables determine long-term levelized cost trajectories and financing terms for new project development.
Market Dynamics
The Inflation Reduction Act's production tax credit recalibration is compressing levelized cost thresholds for high-concentration photovoltaic systems, forcing developers to resequence procurement timelines and tracker integration decisions.
Growth Catalysts
- Direct normal irradiance thresholds:Southwestern United States utility-scale developers are accelerating site qualification in Arizona, California, and Nevada where annual DNI exceeds 1800 kWh/m², the minimum viability threshold for multijunction cell efficiency gains.
- EU Green Deal renewable targets:Member state renewable portfolio obligations are broadening addressable market access for high-efficiency solar technologies previously confined to premium utility applications.
- Dual-axis tracker maturation:Active optical alignment systems are achieving reliability curves that satisfy project finance tenor requirements, unlocking institutional capital deployment.
Market Restraints
- III-V multijunction cell supply concentration:Epitaxial wafer production clusters in specific manufacturing zones create single-source vulnerability for project developers with fixed completion deadlines.
- Geographic irradiance limitation:CPV systems require direct normal irradiance above 1800 kWh/m² annually, excluding high-latitude and humid subtropical markets from addressable demand.
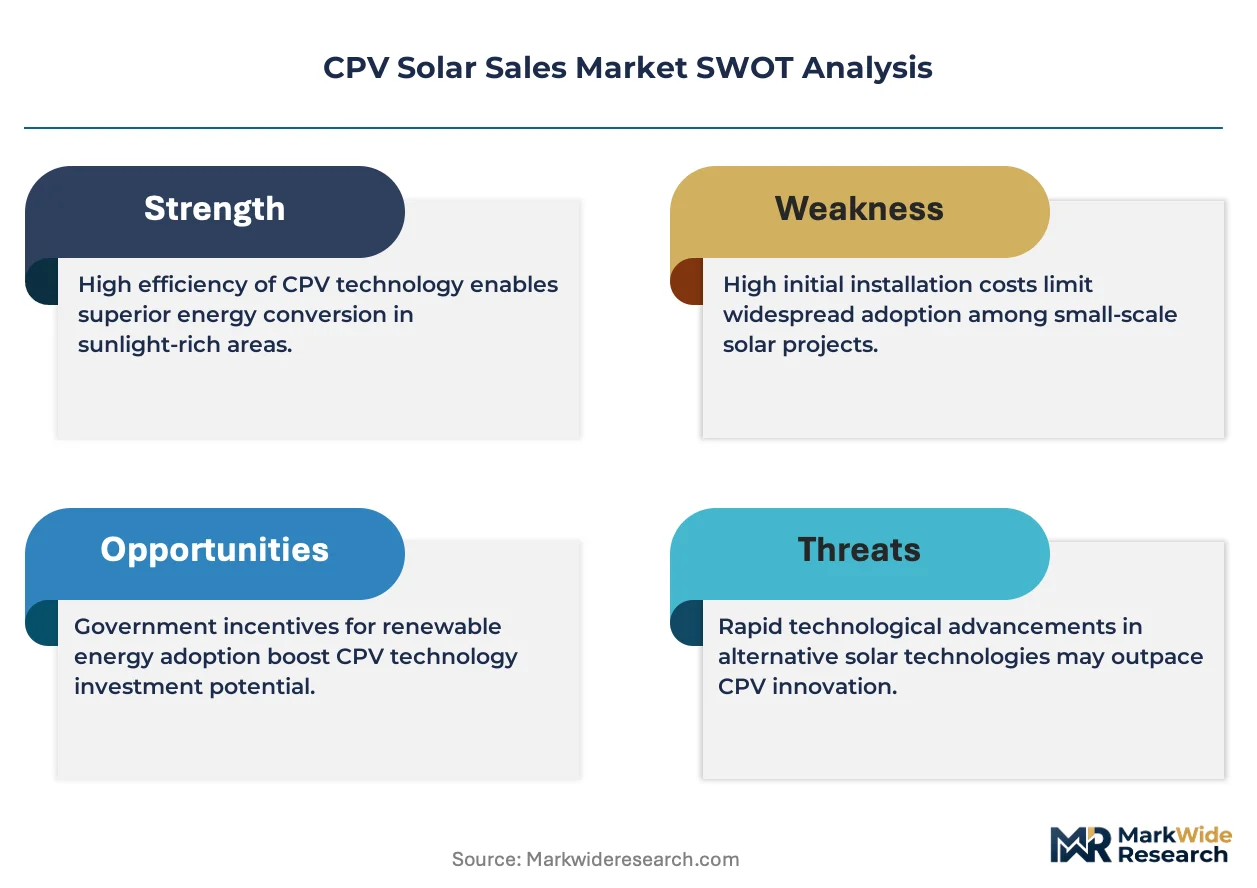
- Flat-plate photovoltaic substitution:Crystalline silicon module cost curves continue compressing, narrowing the efficiency-premium window that justifies CPV capital intensity.
Strategic Opportunities
- Hybrid system architectures:Developers are combining Fresnel lens concentrating elements with flat-plate photovoltaic backplanes to broaden geographic applicability into moderate-DNI zones.
- Behind-the-meter commercial installations:Peak demand charge structures in California and Nevada are creating favorable economics for distributed CPV deployment at industrial facilities.
- FERC interconnection standardization:Streamlined grid access protocols for high-efficiency renewable assets are reducing project development timeline uncertainty.
Industry Challenges
- Multijunction cell fabrication expertise scarcity:Epitaxial growth and III-V compound semiconductor processing skills concentrate in a limited workforce pool, constraining manufacturing scale-up velocity.
- Tracker reliability degradation uncertainty:Long-term dual-axis mechanical performance data remains sparse, complicating project finance underwriting and insurance pricing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CPV Solar Sales Market |
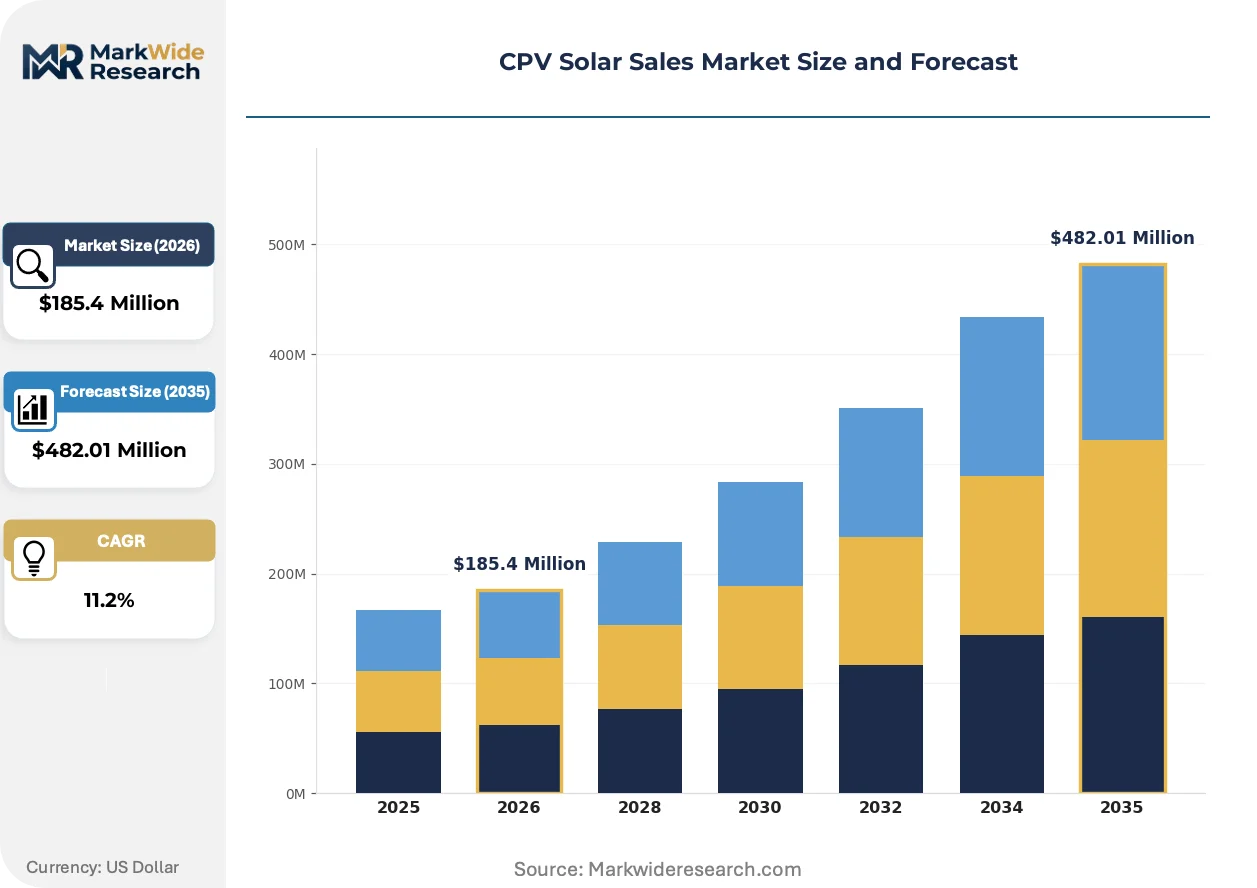
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $482.01 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fresnel Lens, Parabolic Reflector, Reflective Concentrator, Hybrid System Application: Utility Scale, Commercial, Residential, Off-grid End User: Energy Providers, Industrial Sector, Government, Private Sector Installation Type: Ground-mounted, Rooftop, Trackers, Integrated Solutions |
| Companies Covered | SunPower Corporation, Amonix, Arzon Solar, Zytech Solar, China Sunergy, Cool Earth Solar, Emcore, ISOFOTON, Morgan Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CPV Solar Sales Market Trends and Innovations
Refractive concentrator designs and hybrid photovoltaic architectures are broadening the addressable geographic footprint for concentrating solar systems beyond traditional high-DNI desert installations.
Fresnel lens concentrator systems are expanding into moderate-irradiance markets through hybrid configurations that combine concentrating elements with conventional flat-plate photovoltaic backplanes. Utility developers in Spain and Australia are piloting these systems where DNI falls below traditional CPV thresholds but land constraints favor efficiency maximization. This technology convergence is compressing the addressable market gap between premium concentrating systems and commodity flat-plate installations.
The EU Green Deal's renewable energy framework is mandating technology-neutral auction designs that reward high-efficiency generation regardless of underlying photovoltaic architecture. Member state energy regulators are incorporating land-use efficiency metrics into procurement scoring, advantaging concentrating systems in densely populated regions. German and Italian utility planners are revising site qualification protocols to accommodate tracker-integrated concentrating installations.
Power purchase agreement structures are compressing developer margin exposure through shorter tenor offerings and merchant tail risk allocation. Southwestern United States offtakers are unbundling energy and renewable energy credit streams, forcing CPV developers to optimize for merchant price capture rather than contracted revenue stability. Arizona and Nevada industrial buyers are driving this contractual evolution through direct procurement rather than utility-mediated programs.
CPV Solar Sales Market Segmentation
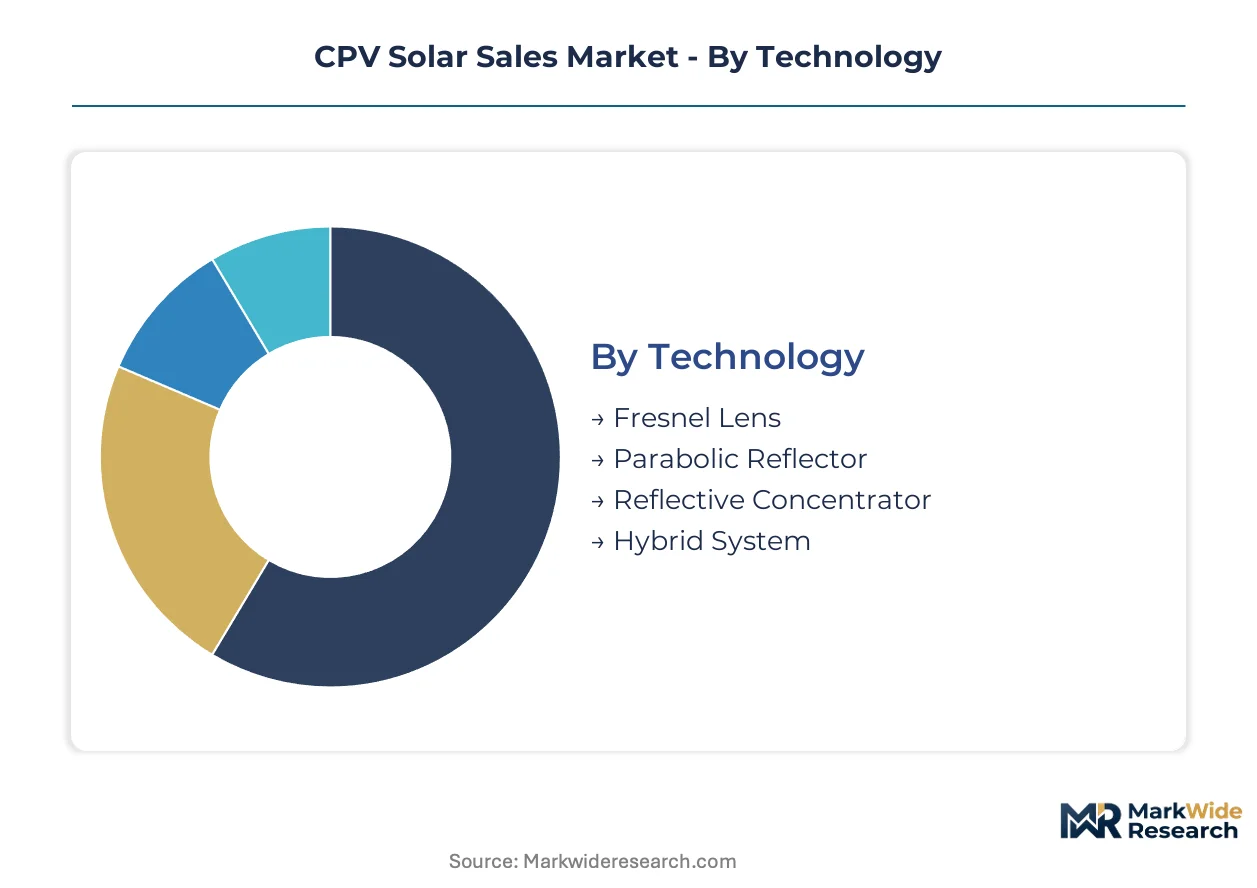
CPV solar sales segmentation reveals how technology architecture, application scale, and installation configuration determine project economics and regulatory compliance pathways. Each dimension carries distinct certification burdens and capital intensity profiles that shape vendor positioning and customer procurement criteria.
Technology:
Fresnel lens architectures require IEC 61215 certification for concentrator modules, while hybrid systems face dual compliance with both concentrating and flat-plate standards under IEC 61215 and IEC 61646.
- Fresnel Lens:Refractive optical elements focus sunlight onto multijunction cells at 500-1000x concentration ratios. Utility-scale developers in Arizona and Nevada deploy these systems where DNI exceeds 2000 kWh/m² annually, leveraging mature supply chains for acrylic lens manufacturing.
- Hybrid System:Combines Fresnel concentrating elements with silicon backplane cells to capture diffuse irradiance. Spanish and Australian developers pilot these configurations in moderate-DNI zones where pure CPV economics fail, broadening addressable geography.
- Parabolic Reflector:Curved mirror dishes achieve higher concentration ratios than refractive designs.
- Reflective Concentrator:Deploys secondary optics to homogenize flux distribution across cell surfaces.
Leading the category by volume: Fresnel Lens. Growing fastest: Hybrid System.
Application:
Utility-scale procurement dominates revenue concentration, though commercial behind-the-meter installations are gaining traction where peak demand charges justify capital intensity.
- Utility Scale:Power purchase agreements with 15-25 year tenors finance installations exceeding 10 MW capacity. Arizona Public Service and NV Energy procurement schedules drive deployment timelines, with FERC interconnection queues determining project completion sequencing.
- Commercial:Industrial facilities in California and Nevada deploy 100 kW-2 MW systems to offset peak demand charges. Manufacturing campuses with high daytime load profiles achieve favorable behind-the-meter economics.
- Residential:Minimal penetration due to capital intensity and tracking complexity.
- Off-grid:Remote mining and telecommunications applications in high-DNI desert regions.
Highest revenue concentration: Utility Scale. Steepest expansion trajectory: Commercial.
End User:
Energy providers command procurement volume through regulated asset base treatment, while industrial sector buyers drive merchant tail risk exposure.
- Energy Providers:Vertically integrated utilities and independent power producers deploy CPV within renewable portfolio obligation compliance strategies. Southwestern United States utilities leverage production tax credit recalibration under the Inflation Reduction Act.
- Industrial Sector:Data centers and semiconductor fabrication facilities procure direct to manage energy cost volatility. Arizona and Nevada manufacturing clusters prioritize land-efficient generation.
- Government:Military installations and federal land management agencies.
- Private Sector:Corporate offtakers through virtual power purchase agreements.
Dominant procurement volume: Energy Providers. Fastest-growing buyer category: Industrial Sector.
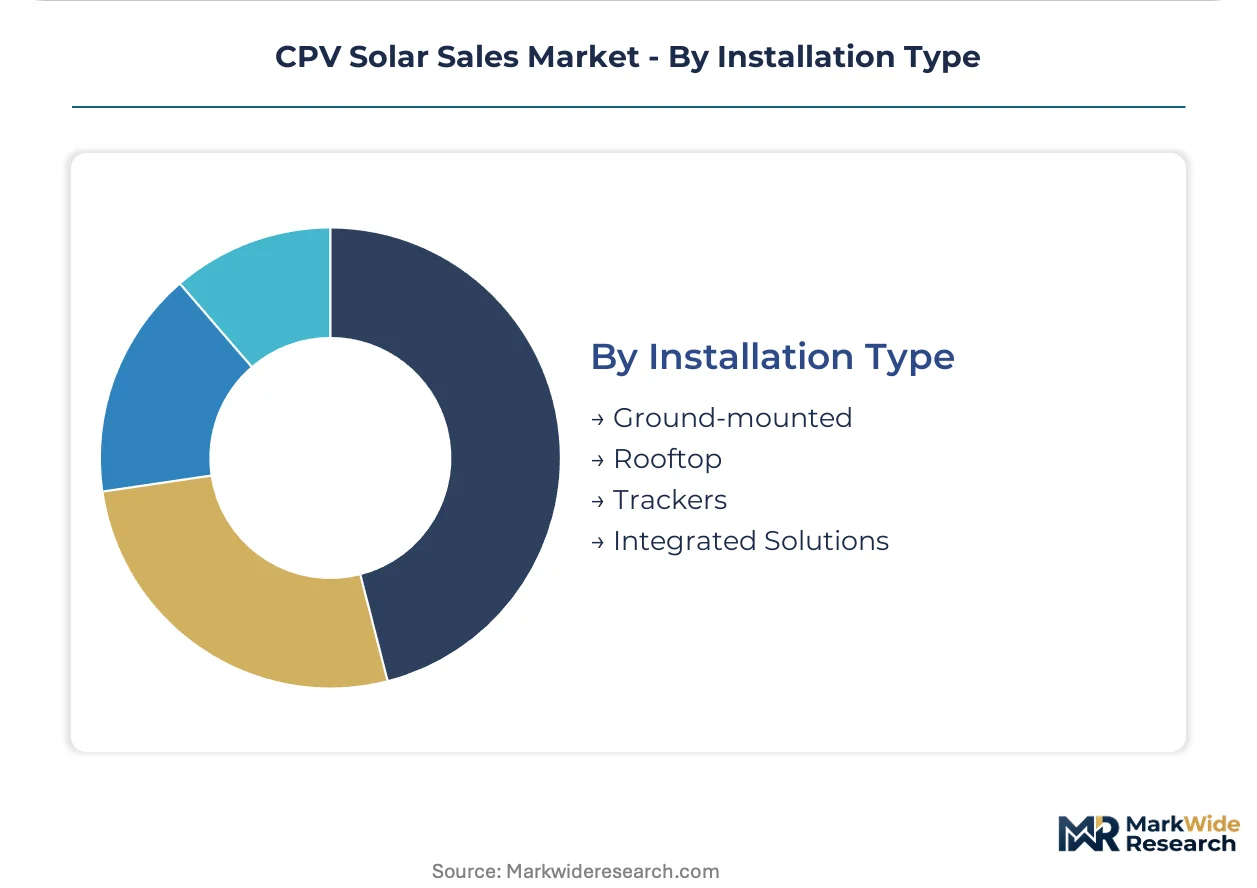
Installation Type:
Ground-mounted tracker systems achieve optimal optical alignment but impose reliability degradation risks that complicate project finance underwriting.
- Trackers:Dual-axis active alignment systems maintain perpendicular incidence throughout solar day. Nevada Solar One and comparable installations demonstrate 25-30% energy yield gains over fixed-tilt configurations, though mechanical complexity elevates O&M cost projections.
- Ground-mounted:Fixed-tilt foundations reduce capital expenditure for high-DNI sites where tracking gains are marginal. Arizona utility-scale developers deploy these in flat desert terrain with minimal soiling exposure.
- Rooftop:Structural load constraints limit concentrator deployment.
- Integrated Solutions:Building-integrated concentrating elements for commercial facades.
Primary deployment mode: Trackers. Gaining share fastest: Ground-mounted.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Phoenix-Mesa metropolitan corridor anchors CPV deployment activity through Arizona Public Service procurement schedules and high-DNI desert siting. Developers concentrate installation crews across Maricopa County where annual direct normal irradiance exceeds 2200 kWh per square meter.
United States
Southwestern utilities accelerate site qualification in Arizona, California, and Nevada where annual DNI surpasses 1800 kWh/m² viability thresholds. FERC interconnection standardization streamlines grid access protocols for high-efficiency renewable assets. The Imperial Valley and Mojave Desert host active procurement clusters where NV Energy and Arizona Public Service drive deployment timelines.
Spain
Andalusian solar parks pilot hybrid CPV-flat-plate configurations where moderate-DNI conditions previously excluded concentrating systems. The EU Green Deal mandates technology-neutral auction designs rewarding land-use efficiency in densely populated regions. Seville and Granada provinces concentrate early-adopter developers revising site qualification protocols for tracker-integrated installations.
Australia
Queensland and Western Australian mining operations deploy off-grid CPV systems for remote telecommunications and extraction site electrification. The national renewable energy target framework broadens addressable market access for high-efficiency solar technologies. The Pilbara region hosts industrial offtakers prioritizing land-efficient generation for daytime load profiles.
Germany
Bavarian and Baden-Württemberg industrial facilities experiment with behind-the-meter commercial installations to offset peak demand charges. EU Green Deal renewable portfolio obligations reshape procurement scoring to incorporate land-use efficiency metrics. Stuttgart and Munich manufacturing campuses achieve favorable economics through high daytime load alignment.
Saudi Arabia
NEOM and the Eastern Province integrate CPV within gigawatt-scale renewable city infrastructure where solar resource quality justifies capital intensity. The national renewable energy program under the Vision 2030 framework prioritizes high-efficiency generation technologies. The Tabuk and Medina regions concentrate developer activity around tracker-integrated utility-scale procurement.
CPV Solar Sales Market Competitive Landscape
The competitive structure tilts toward vertically integrated cell manufacturers with captive III-V multijunction fabrication capabilities. A limited workforce pool concentrates epitaxial growth expertise, constraining manufacturing scale-up velocity for new entrants. Two strategic archetypes dominate: utility-scale tracker-integrated system integrators and compact refractive concentrator specialists targeting commercial behind-the-meter applications. Competitive moves center on hybrid system architecture development and dual-axis tracker reliability certification for project finance underwriting.
Among US-based technology developers, SunPower Corporation and Amonix occupy positions within the utility-scale integration archetype, while Arzon Solar exemplifies the compact refractive concentrator specialization. These three entities anchor the competitive conversation around Fresnel lens deployment economics, active optical alignment system maturation, and balance-of-system cost compression for commercial adopters. Their collective positioning reflects the market's bifurcation between large-scale desert installations and distributed industrial applications.
| Leading Market Players |
|---|
| SunPower Corporation |
| Amonix |
| Arzon Solar |
| Zytech Solar |
| China Sunergy |
| Cool Earth Solar |
| Emcore |
| ISOFOTON |
| Morgan Solar |
| Others |
Pricing and Supply Chain Analysis
The EU Green Deal's land-use efficiency mandates gate qualified supply access and premium-tier pricing for concentrator photovoltaic systems, compressing procurement economics for developers unable to demonstrate compliance with technology-neutral auction scoring criteria.
Pricing Analysis
Yield-based pricing anchors CPV system valuation, with developers monetizing guaranteed energy output per installed kilowatt rather than capital expenditure alone. Three-tier pricing structure across premium, standard, and economy levels separates IEC-certified multijunction modules from uncertified alternatives and hybrid configurations. Cost compression in standard-tier Fresnel lens assemblies is intensifying because crystalline silicon module price curves narrow efficiency-premium windows. Utility-scale energy providers exhibit lowest price sensitivity due to long-tenor power purchase agreement financing, while commercial behind-the-meter buyers face acute capital constraint pressure.
Supply Chain Analysis
III-V epitaxial wafer supply rests on Japanese and German specialty semiconductor foundries, with MOCVD reactor capacity concentrated among a limited equipment vendor base. Germanium substrates, gallium arsenide wafers, and precision acrylic Fresnel lenses constitute critical input dependencies. Single-source vulnerability for MOCVD equipment creates project completion timeline risk for developers with fixed interconnection deadlines. Distribution runs through vertically integrated system integrators and regional EPC contractors serving southwestern United States utility procurement clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Inflation Reduction Act's production tax credit recalibration creates a compliance moat separating qualified domestic content from import-dependent competitors, elevating capital requirements for market participation.
For Market Incumbents: Cement technology leadership through captive III-V multijunction cell fabrication and dual-axis tracker reliability certification programs. Flat-plate photovoltaic substitution threatens efficiency-premium positioning, demanding accelerated hybrid system architecture development. Backward integration into epitaxial wafer production secures supply continuity against single-source MOCVD equipment constraints.
For New Entrants and Emerging Players: Regional EPC contractors offer the most accessible channel partnership pathway for commercial behind-the-meter penetration. White-space opportunity concentrates in moderate-DNI European markets where hybrid CPV-flat-plate configurations satisfy EU Green Deal land-use efficiency scoring. Target industrial facilities in Spain and Germany with peak demand charge structures favoring distributed generation economics.
For Investors and Strategic Acquirers: FERC interconnection queue prioritization for high-efficiency renewable assets is the leading indicator that utility-scale deployment velocity will accelerate. Long-term viability frames around manufacturing scale-up velocity for III-V cell fabrication and tracker reliability data accumulation. Acquisition target archetype: compact refractive concentrator specialists with commercial installation track records and IEC certification pathways.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid System Architecture Development | Combining Fresnel concentrating elements with flat-plate backplanes broadens geographic applicability into moderate-DNI zones. |
| Dual-Axis Tracker Reliability Certification | Mechanical performance validation satisfies project finance tenor requirements for institutional capital deployment. |
| III-V Multijunction Cell Manufacturing Scale-Up | Epitaxial wafer production expansion reduces single-source supply vulnerability for fixed-completion deadline projects. |
| EU Green Deal Compliance Positioning | Technology-neutral auction scoring advantages land-efficient concentrating systems in densely populated member states. |
| Behind-the-Meter Commercial Channel Development | Industrial facility direct procurement captures peak demand charge economics in California and Nevada markets. |
Research Methodology
Document review covered FERC interconnection filings, EIA generation capacity databases, and EU Green Deal implementation guidelines, complemented by interviews with utility planning officers, independent power producer project developers, EPC contractors, and III-V cell manufacturing technical directors. Secondary validation drew from IEA renewable energy reports, SEC filings of vertically integrated solar developers, and customs trade data for germanium substrate imports. Bottom-up project pipeline aggregation and top-down regulatory scenario modeling provided cross-referencing triangulation.
Historical deployment trajectories in Arizona, Nevada, and California were cross-referenced against panel input from procurement schedule disclosures and tracker reliability field data. Segmentation modeling spanned technology architecture, application scale, installation configuration, and regional regulatory framework clusters. CAGRs were derived from capacity-weighted average pricing trends and production tax credit recalibration scenarios. Forecast inputs incorporated DNI threshold viability mapping and multijunction cell supply chain concentration indices.
Several conditions sit outside the modeled scope, including crystalline silicon module cost curve trajectories beyond current compression trends and unilateral tariff modifications affecting germanium substrate trade flows. Forecasts reflect assumptions regarding IRA domestic content guidance stability and FERC interconnection standardization implementation timelines. A small set of named triggers warrants ongoing watch: tracker mechanical degradation data accumulation, MOCVD equipment order backlogs, and EU member state auction design finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Turkey Solar Energy Market
Solar Power Systems
Solar Vegetable Dryer Market
Solar Power Systems
Middle-East and Africa Distributed Solar Power Generation Market
Solar Power Systems
Solar Cell Busbar Market
Solar Power Systems
Solar Simulator Market
Solar Power Systems
Sweden Solar Energy Market
Solar Power Systems
Australia Solar Market
Solar Power Systems
Solar Freezer Market
Solar Power Systems
Thin-Film Photovoltaic Market
Solar Power Systems
Spain Solar Energy Market
Solar Power Systems
South America Solar Photovoltaic Market
Solar Power Systems
Solar Shed Light Market
Solar Power Systems
Middle East and Africa Solar PV Inverters Market
Solar Power Systems
Off-Grid Solar Generator Market
Solar Power Systems
Israel Solar Energy Market
Solar Power Systems
Solar Photovoltaic (PV) Market