
 Solar EPC Market | 2026-2036
Solar EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Solar EPC Market Analysis
Utility-scale developer procurement channels are rewriting competitive access rules across the Solar EPC landscape. SOLV Energy leverages its domestic U.S. project execution scale to anchor large-format photovoltaic installations. McCarthy Building competes through self-perform civil and electrical capabilities that reduce subcontractor dependency. Larsen & Toubro dominates utility-scale engineering in India through integrated module mounting and substation delivery.
Solar EPC denotes the integrated engineering, procurement, and construction services required to deliver operational photovoltaic generating assets, encompassing DC-AC power conversion design, tracker or fixed-tilt structural systems, and grid-interconnection switchyard buildout with functional parameters typically spanning 15-25 year performance warranties. The primary industrial purpose is converting capital commitments into revenue-generating clean power infrastructure under fixed-price contractual risk transfer. Utility-scale project size categories sustain the deepest margin pools due to multi-hundred-megawatt procurement leverage and repeat-developer relationships, while bifacial technology segments lead growth as these modules require specialized mounting and row-spacing engineering that commands premium EPC fees. Crystalline silicon technology occupies the mature volume base, though thin-film applications persist in utility settings where temperature coefficients and spectral response advantages offset efficiency gaps.
FERC interconnection queues and state renewable portfolio standards in the United States shape project timelines and EPC contract structuring, while India's CEA grid codes and PLI scheme domestic content requirements redirect procurement toward local module sourcing. Saudi Arabia's PIF-backed project mandates and grid operator specifications are concentrating Gulf EPC awards around integrated consortium structures. Stakeholders must monitor which regulatory bodies tighten local content thresholds versus streamlining permitting, as this balance determines where EPC margins compress or expand.
Market Dynamics
Turnkey procurement mandates from sovereign wealth funds and renewable purchase obligations in high-irradiance markets are compressing EPC contract timelines while expanding performance guarantee durations. This structural pressure rewards integrated consortiums with captive engineering and construction capabilities.
Growth Catalysts
- India's PLI scheme domestic content requirements:Local module sourcing mandates redirect capital toward EPCs with integrated manufacturing partnerships, creating captive demand pools for engineering-procurement-construction services.
- Bifacial module engineering complexity:Dual-sided photovoltaic technology requires specialized row-spacing algorithms and elevated mounting systems that command premium EPC fees.
- Saudi Arabia's PIF-backed project mandates:Sovereign capital deployment specifies integrated EPC delivery structures, concentrating awards around consortiums with substation and transmission capabilities.
Market Restraints
- Polysilicon supply concentration:Refining capacity clusters in specific manufacturing geographies expose EPC margins to raw material volatility and trade policy friction.
- FERC interconnection queue delays:Grid access timelines in the United States extend project development cycles, freezing capital commitments and compressing contractor cash conversion.
- Fixed-price contractual risk transfer:Lump-sum turnkey structures place escalation exposure on EPCs during periods of tracker component and steel tariff volatility.
Strategic Opportunities
- Floating solar construction methods:Reservoir and coastal installations in land-constrained markets create specialized engineering demand for mooring systems and marine electrical infrastructure.
- CEA grid code harmonization:India's central electricity authority standards convergence enables standardized substation designs that reduce engineering redundancy across state boundaries.
- Agrivoltaic dual-use applications:Agricultural land co-location requirements in water-stressed regions open EPC service lines combining elevated tracking structures with irrigation-compatible spacing.
Industry Challenges
- High-voltage substation commissioning expertise:Grid interconnection switchyard construction requires specialized relay protection and SCADA integration skills that outpace training pipeline output.
- Tracker mechanical warranty alignment:EPCs face liability compression when single-axis tracker suppliers limit structural guarantees below the 15-25 year performance warranties demanded by project finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar EPC Market |
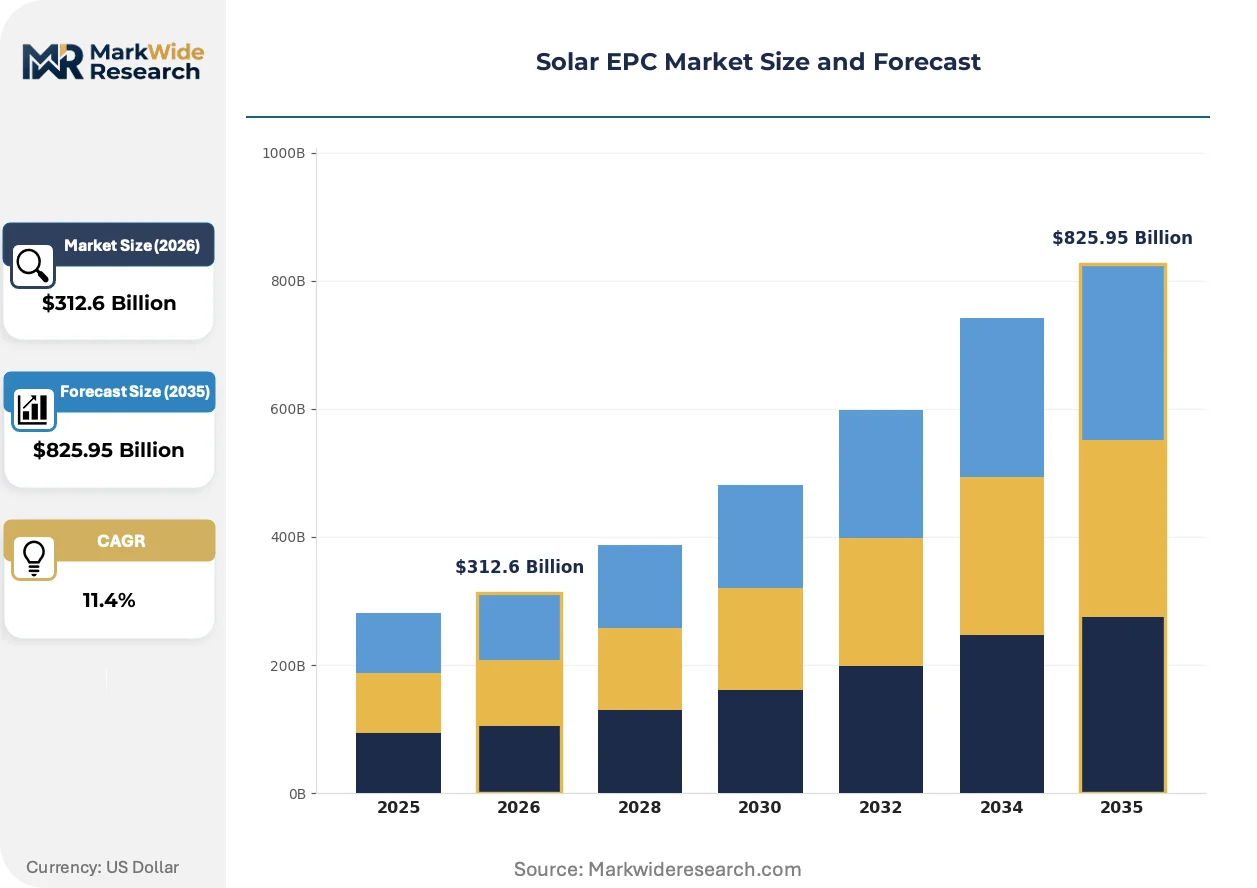
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $825.95 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Size: Utility Scale, Commercial, Residential, Microgrid Service Type: Design, Procurement, Construction, Operation Technology: Thin Film, Crystalline Silicon, Bifacial, Integrated Systems End User: Government, Industrial, Developers, Others |
| Companies Covered | SOLV Energy, McCarthy Building, Eiffage, Larsen & Toubro, Sterling and Wilson Renewable Energy Ltd., Tata Power Solar Systems Ltd., Adani Solar, Belectric, JinkoSolar Holding Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar EPC Market Emerging Trajectories
Digital twin technology and modular construction methods are compressing field assembly timelines while expanding remote commissioning capabilities. These shifts reward EPCs with in-house software development and prefabrication facilities.
Bifacial performance modeling software is virtualizing traditional DC-AC power conversion design workflows. Utility-scale developers in India and Saudi Arabia now mandate cloud-based irradiance simulation before contract award. This technology is virtualizing the engineering validation phase that previously required physical pilot arrays.
The United States IRA domestic content bonus credits are restructuring module procurement geography. EPCs must now trace crystalline silicon wafer and cell provenance to qualify projects for adder incentives. Southeast Asian assembly facilities are responding by relocating cell manufacturing to U.S.-Mexico border zones.
Developer consolidation is compressing vendor qualification cycles. Repeat-contractor relationships now bypass traditional competitive bidding for balance-of-system packages. This concentration is most visible in the U.S. Southwest and Gujarat industrial corridors, where three developers control majority procurement volume.
Solar EPC Market Segmentation
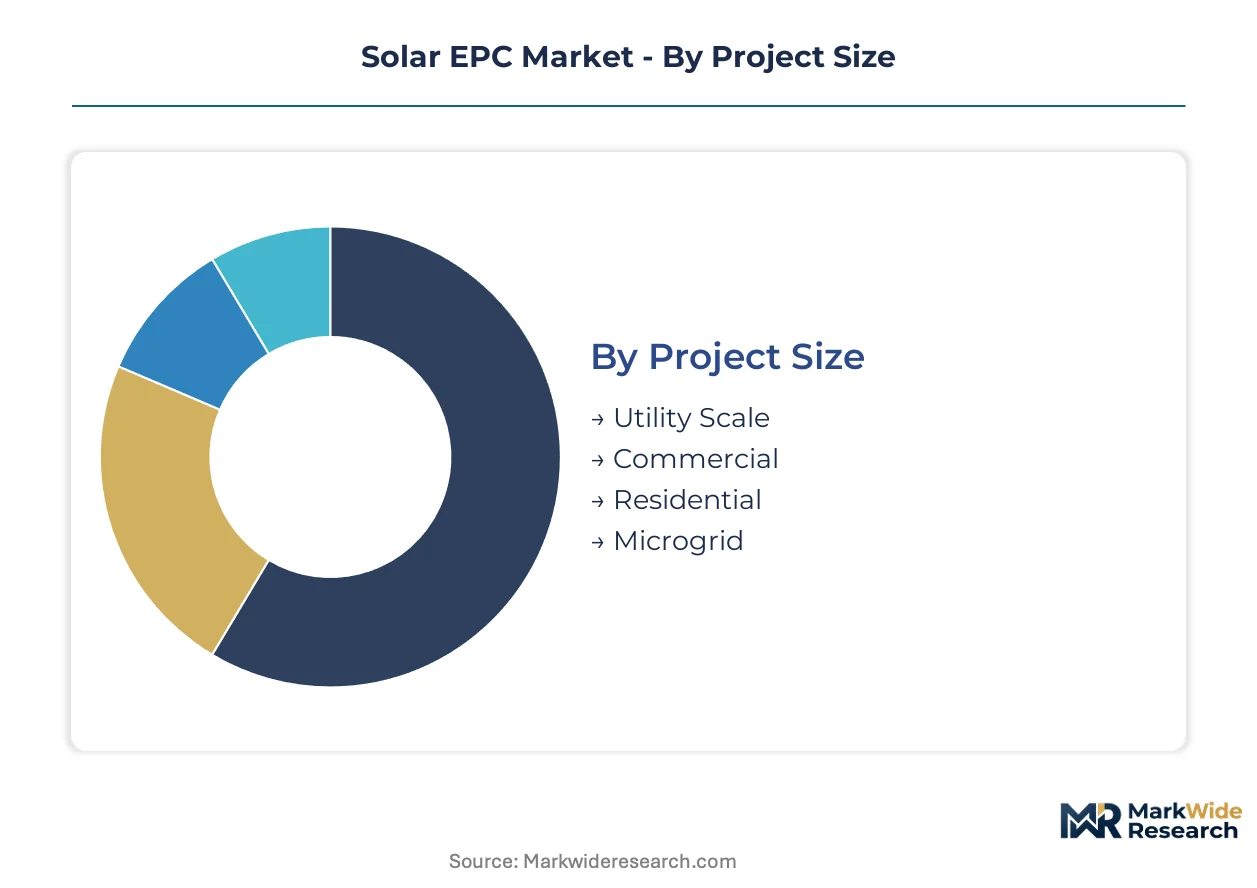
Segmentation in Solar EPC reveals how contract structures, technology choices, and client risk appetites fragment service delivery models. Project size determines procurement leverage and performance guarantee terms. Service type boundaries are blurring as turnkey mandates consolidate engineering, procurement, and construction under single-contractor liability.
Project Size:
Mature volume categories coexist with emerging formats that reshape margin structures and capability requirements.
- Utility Scale:Multi-hundred-megawatt installations command the deepest procurement leverage and repeat-developer relationships. Developers in India, the United States, and Saudi Arabia concentrate awards here under sovereign wealth fund mandates and renewable purchase obligations that compress timelines while extending warranty durations.
- Commercial:Rooftop and ground-mount systems between 100 kilowatts and 5 megawatts serve corporate off-takers with sustainability targets. C&I procurement in Gujarat industrial corridors and U.S. Southwest distribution centers is accelerating as electricity tariffs rise and net metering policies stabilize.
- Residential:Distributed rooftop installations under 20 kilowatts per site require localized permitting expertise and homeowner financing partnerships.
- Microgrid:Islanded or weak-grid configurations combining solar with storage and diesel backup serve remote industrial sites and rural electrification programs.
Utility Scale handles the majority of throughput; Microgrid is gaining share fastest as grid reliability concerns and remote industrial demand expand addressable market boundaries.
Service Type:
Cost tier differentiation separates full-risk turnkey providers from specialized component suppliers.
- Design:DC-AC power conversion engineering, tracker or fixed-tilt structural specification, and grid-interconnection switchyard layout. FERC interconnection queue delays in the United States and CEA grid code harmonization in India are reshaping design fee structures and timeline risk allocation.
- Procurement:Module, inverter, and balance-of-system sourcing with provenance tracing for domestic content incentives. IRA bonus credit requirements are forcing crystalline silicon wafer and cell sourcing shifts toward U.S.-Mexico border zones.
- Construction:Field assembly, commissioning, and performance testing under fixed-price contractual risk transfer. Self-perform civil and electrical capabilities reduce subcontractor dependency and margin compression.
- Operation:Long-term asset management, performance monitoring, and warranty enforcement spanning 15-25 year contractual horizons.
Construction captures the largest fee pool; Operation is climbing the fastest as performance guarantee durations extend and digital twin remote monitoring reduces field service intensity.
Technology:
Application-driven selection separates established volume platforms from premium-engineered alternatives.
- Crystalline Silicon:Mature monocrystalline and polycrystalline cell architectures dominate installed base volume. Temperature coefficient limitations in high-irradiance desert environments are redirecting some procurement toward alternative platforms.
- Bifacial:Dual-sided photovoltaic modules requiring specialized row-spacing algorithms and elevated mounting systems. Land-scarce markets with high albedo surfaces—coastal Saudi Arabia, reservoir-adjacent India—are concentrating demand for these premium-engineered configurations.
- Thin Film:Cadmium telluride and copper indium gallium selenide technologies persist in utility settings where spectral response advantages offset efficiency gaps.
- Integrated Systems:Pre-engineered containerized solutions combining modules, inverters, and storage for rapid deployment in frontier markets.
Crystalline Silicon maintains volume leadership; Bifacial is expanding most quickly as specialized mounting engineering commands premium EPC fees and sovereign mandates specify dual-sided performance.
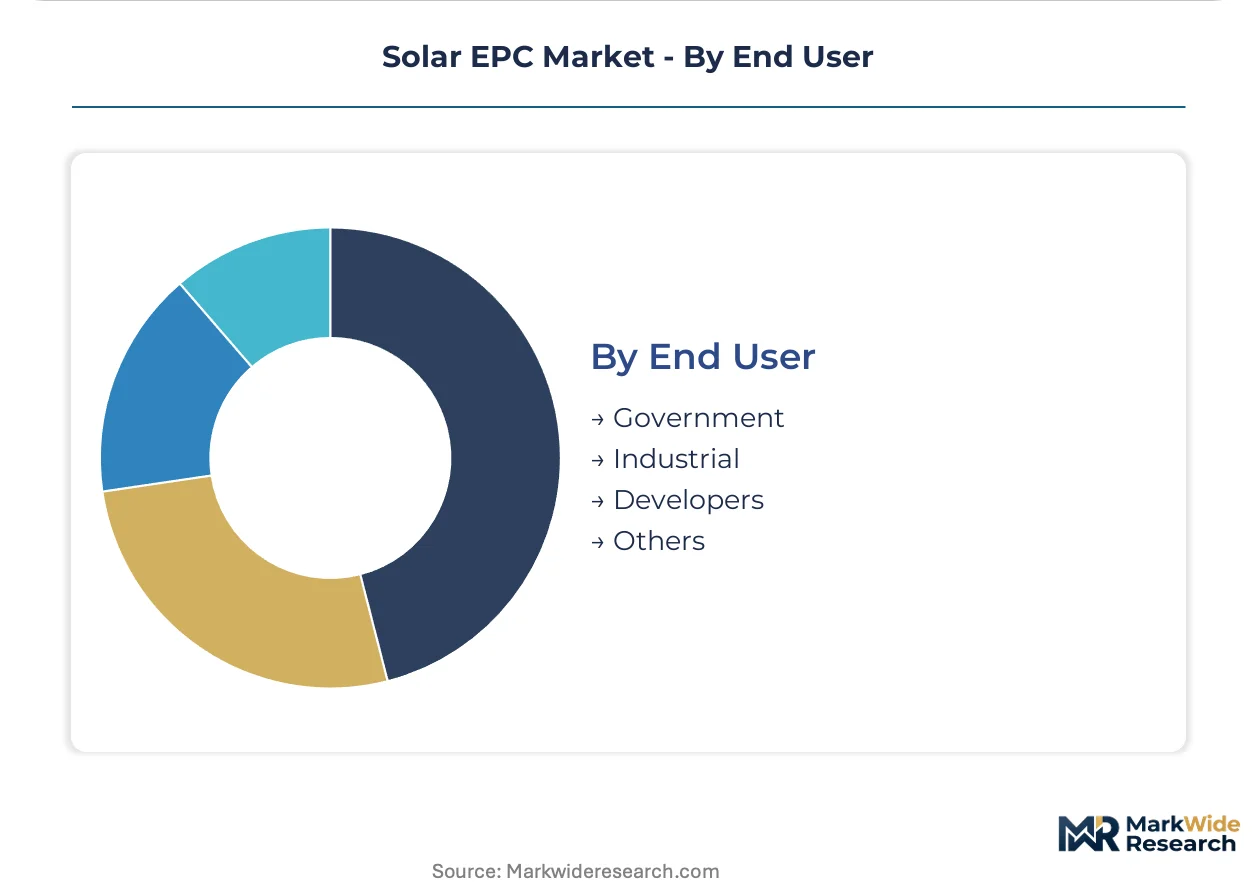
End User:
Customer type determines risk tolerance, contract complexity, and local content compliance intensity.
- Developers:Independent power producers and renewable energy corporations with repeat-contractor relationships and multi-gigawatt pipelines. Consolidation in the U.S. Southwest and Gujarat is compressing vendor qualification cycles and bypassing traditional competitive bidding.
- Government:Sovereign wealth funds, public utilities, and ministry-backed programs with domestic content mandates and grid code specifications. Saudi Arabia's PIF-backed project structures and India's PLI scheme requirements are concentrating awards around integrated consortiums with captive engineering capabilities.
- Industrial:Mining, manufacturing, and data center off-takers seeking behind-the-meter generation with reliability guarantees.
- Others:Agricultural co-operatives, educational institutions, and non-profit entities with grant-dependent financing and simplified technical requirements.
Developers transact the highest contract value; Government is the fastest mover on share as sovereign capital deployment restructures competitive access rules across high-irradiance markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Renewable purchase obligations and grid interconnection standards are redirecting capital toward high-irradiance markets with sovereign-backed procurement mandates. Utility-scale developers in India, the United States, and Saudi Arabia concentrate project awards where domestic content requirements and performance guarantee structures align with EPC delivery capabilities.
United States
FERC interconnection queues and IRA domestic content bonus credits are reshaping module procurement geography. EPCs trace crystalline silicon wafer and cell provenance to qualify projects for adder incentives. The U.S. Southwest concentrates repeat-developer relationships that bypass traditional competitive bidding for balance-of-system packages.
India
CEA grid code harmonization and PLI scheme domestic content requirements redirect capital toward EPCs with integrated manufacturing partnerships. Gujarat industrial corridors anchor multi-gigawatt procurement pipelines. Maharashtra and Karnataka clusters standardize substation designs that reduce engineering redundancy across state boundaries.
Saudi Arabia
PIF-backed project mandates specify integrated EPC delivery structures with substation and transmission capabilities. Coastal zones with high albedo surfaces concentrate bifacial module demand. NEOM Northwest and Eastern Province developments award contracts to consortiums with captive engineering and construction capabilities.
Germany
EU Green Deal implementation and REPowerEU targets accelerate utility-scale solar deployment despite land constraints. EPCs specialize in agrivoltaic dual-use applications combining elevated tracking structures with agricultural compatibility. Bavaria and North Rhine-Westphalia industrial zones host engineering centers for floating solar mooring systems.
Australia
Weak grid infrastructure and remote mining demand expand microgrid configurations combining solar with storage and diesel backup. New South Wales and Queensland utility-scale pipelines face FERC-equivalent interconnection delays that extend project development cycles. EPCs with high-voltage substation commissioning expertise capture premium fees in this supply-constrained environment.
Solar EPC Market Vendor Landscape
On the supply side, the industry is consolidating around integrated consortiums with captive engineering and construction capabilities. Self-perform civil and electrical capabilities reduce subcontractor dependency and margin compression. Three archetypes dominate: domestic-scale execution specialists, integrated industrial conglomerates with module mounting and substation delivery, and renewable-pure-play developers with repeat-contractor relationships. Competitive moves center on backward integration into module sourcing and geographic expansion into high-irradiance procurement markets.
Within the integrated conglomerate tier, Larsen & Toubro and Tata Power Solar Systems Ltd. exemplify engineering-procurement-construction providers with domestic manufacturing partnerships that satisfy PLI scheme requirements. SOLV Energy anchors the domestic-scale execution archetype in the United States, occupying a position where large-format photovoltaic installation scale anchors competitive access.
| Leading Market Players |
|---|
| SOLV Energy |
| McCarthy Building |
| Eiffage |
| Larsen & Toubro |
| Sterling and Wilson Renewable Energy Ltd. |
| Tata Power Solar Systems Ltd. |
| Adani Solar |
| Belectric |
| JinkoSolar Holding Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Polysilicon refining capacity clustering in China and Southeast Asia concentrates upstream margin capture, forcing EPCs to absorb raw material volatility through fixed-price contractual structures while downstream procurement leverage pools with repeat-developer relationships in India, the United States, and Saudi Arabia.
Pricing Analysis
Volume-discount tiering structures separate turnkey EPC providers from specialized component suppliers across the market. Project scale determines pricing bands, with utility-scale developers commanding standard-tier rates through multi-hundred-megawatt procurement leverage while microgrid and commercial segments face premium pricing due to customization requirements. Price differentiation hinges on domestic content compliance intensity and self-perform capability depth, as EPCs with integrated civil and electrical teams avoid subcontractor markups. Cost compression in crystalline silicon module sourcing is intensifying because IRA bonus credit requirements are forcing provenance tracing investments. Government-backed developers in Saudi Arabia and India exhibit lowest price sensitivity due to sovereign capital deployment mandates, whereas C&I off-takers in competitive procurement markets demonstrate highest sensitivity to per-watt pricing.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for crystalline silicon module procurement. Manufacturing concentration in China, Vietnam, and Thailand for cell and wafer production creates geographic dependency that EPCs must navigate through U.S.-Mexico border zone assembly relocation. Raw material inputs including polysilicon, tracker steel components, and high-voltage switchgear draw from concentrated supplier bases vulnerable to trade policy friction. Single-source vulnerability in single-axis tracker mechanical systems exposes EPC margins to warranty misalignment with project finance requirements. Distribution runs through integrated consortium structures in high-irradiance markets, with captive engineering capabilities reducing subcontractor dependency and compressing delivery timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Long-term operation and maintenance contracts represent a service-attach opportunity expanding faster than hardware installation revenue, as performance guarantee durations extend toward 25-year horizons and digital twin remote monitoring reduces field service intensity.
For Market Incumbents: Build captive substation commissioning expertise as a defensive moat against specialized electrical contractors encroaching on grid-interconnection work. Backward integration into module sourcing through PLI scheme partnerships in India and IRA-compliant supply chains in North America secures margin control against polysilicon price volatility. Capacity addition in Saudi Arabia's Eastern Province and Gujarat industrial corridors anchors repeat-developer relationships that bypass competitive bidding cycles. For New Entrants and Emerging Players: Establish a beachhead in floating solar construction methods where marine electrical infrastructure skills remain scarce relative to land-based EPC saturation. Agrivoltaic dual-use applications in water-stressed regions offer the most penetrable segment due to agricultural land co-location requirements and limited incumbent specialization. A go-to-market angle centered on elevated tracking structures with irrigation-compatible spacing differentiates against standardized fixed-tilt providers. For Investors and Strategic Acquirers: Capital is best deployed toward EPCs with integrated digital twin software development and prefabrication facilities that compress field assembly timelines. Long-term viability across the next decade favors providers with captive high-voltage relay protection and SCADA integration capabilities that outpace training pipeline output. The signal to watch is FERC interconnection queue clearance rates as an inflection indicator for capital deployment velocity in the U.S. Southwest.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Module Sourcing | PLI scheme compliance in India and IRA bonus credit qualification in the United States secure domestic content advantages. |
| Digital Twin Platform Development | Remote commissioning capabilities expand addressable market boundaries to weak-grid and frontier installations. |
| Floating Solar Capability Buildout | Reservoir and coastal expertise in land-constrained markets commands premium EPC fees through specialized mooring engineering. |
| High-Voltage Substation Partnership | Relay protection and SCADA integration skills capture grid-interconnection premiums in supply-constrained environments. |
| Agrivoltaic Service Line Launch | Elevated tracking structures with irrigation-compatible spacing open agricultural co-location revenue streams. |
Methodological Framework
Desk research of FERC interconnection queue filings, CEA grid code documentation, and sovereign wealth fund procurement mandates preceded structured interviews with utility-scale IPP development executives, EPC project directors, grid operator planning officers, and module supply chain specialists. Primary fieldwork across India, the United States, and Saudi Arabia captured procurement timeline compression and performance guarantee extension trends. Secondary validation drew from IEA renewable deployment databases, EIA generation capacity reports, and PLI scheme administrative records. Bottom-up project pipeline aggregation and top-down market sizing triangulated volume estimates.
Assumptions held fixed include continued enforcement of renewable purchase obligations in high-irradiance markets and sustained IRA domestic content bonus credit structures, while variables included polysilicon price trajectories and FERC queue clearance velocity. The analytical framework modeled segmentation across project scale, service type, technology platform, and end-user archetype throughout the forecast period. CAGRs derived from utility-scale procurement momentum, bifacial technology penetration curves, and sovereign capital deployment schedules. Industry-specific inputs encompassed tracker mechanical warranty alignment gaps and floating solar mooring system cost curves.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments, steel tariff regimes, or trade policy friction between major manufacturing geographies would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory continuity and technology cost reduction curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
China Wind Energy Market
Renewable Energy
Romania Solar Energy Market
Renewable Energy
West Europe Renewable Energy Market
Renewable Energy
Wind Turbine Automation Market
Renewable Energy
Europe Power to Gas Market
Renewable Energy
Philippines Power Market
Renewable Energy
Renewable Energy Monitoring and Control System Market
Renewable Energy
Hybrid Solar Wind Diesel Market
Renewable Energy
Solar Oven Market
Renewable Energy
Republic of Ireland Renewable Energy Market
Renewable Energy
Zimbabwe Renewable Energy Market
Renewable Energy
Tidal Energy Generation Systems Market
Renewable Energy
Solar Cooker Market
Renewable Energy
Global Organic Rankine Cycle Market
Renewable Energy
Renewable Energy Contractor Market
Renewable Energy
Biogas Upgrading Technology Market