
 Egypt Solar Energy Market | 2026-2036
Egypt Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Solar Energy Market Foresight
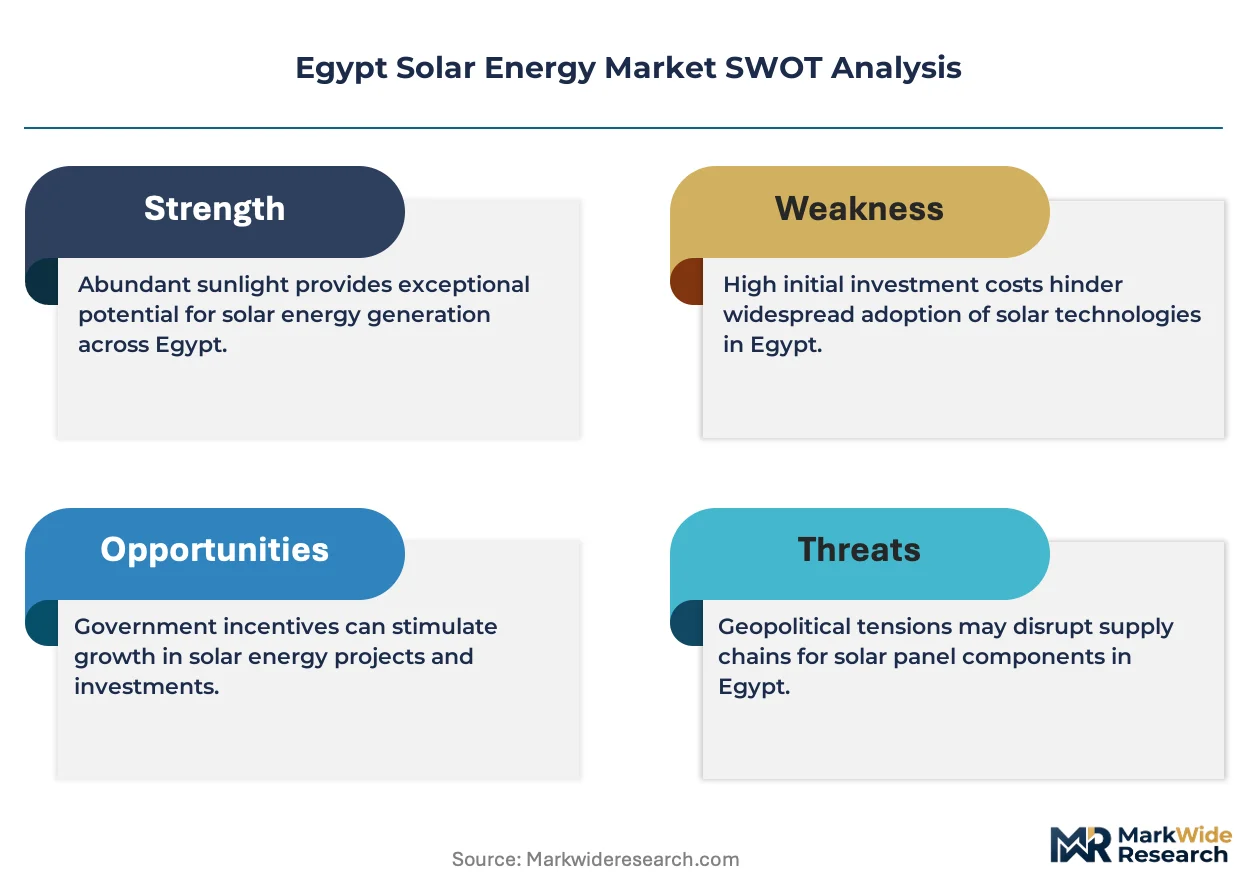
Perovskite-silicon tandem cell research is consolidating around high-efficiency architectures that threaten conventional thin-film economics in Egypt's utility-scale tenders. Elsewedy Electric leverages integrated manufacturing from polysilicon to module assembly, sustaining cost advantages against imported panels. KarmSolar specializes in decentralized commercial installations, competing aggressively with TAQA Arabia's utility-focused pipeline.
Egypt solar energy encompasses photovoltaic and concentrated solar thermal systems that convert incident radiation into electricity through semiconductor junctions or heat-transfer fluids, typically operating at 15-22% cell efficiency for commercial silicon modules. The technology serves grid-connected generation, rural electrification, and industrial process heat across Egypt's high Direct Normal Irradiance zones exceeding 2,000 kWh/m² annually. Photovoltaic modules dominate installed capacity, with crystalline silicon occupying the premium efficiency tier and thin-film systems anchoring cost-sensitive desert applications. Concentrated Solar Power retains structural importance for evening dispatch, though its project pipeline lags photovoltaic deployments in tender participation.
Egypt's New and Renewable Energy Authority administers competitive bidding rounds that shape developer participation rules and local content thresholds. The Egyptian Electricity Holding Company implements grid codes through the Egyptian Electricity Transmission Company, determining interconnection standards that constrain project locations. Stakeholders must monitor forthcoming regulatory adjustments to net metering caps and domestic manufacturing quotas that will determine which technology suppliers capture the next procurement cycle.
Market Dynamics
Feed-in tariff procurement under the New and Renewable Energy Authority is compressing project timelines and forcing crystalline silicon module suppliers to localize assembly operations within Egypt's Industrial Development Authority zones.
Growth Catalysts
- Benban Solar Park cluster expansion:Land availability and transmission infrastructure near Aswan are pulling concentrated developer investment into utility-scale installations.
- Domestic manufacturing mandates:The Industrial Development Authority's local content thresholds are compelling module assembly lines to relocate from import-dependent models.
- High Direct Normal Irradiance zones:Annual solar exposure exceeding 2,000 kWh/m² across Upper Egypt is reducing levelized cost of energy calculations for photovoltaic developers.
Market Restraints
- Polysilicon price volatility:Input cost swings for metallurgical-grade silicon are squeezing margin structures for crystalline module assemblers operating under fixed-tariff contracts.
- Grid interconnection bottlenecks:Egyptian Electricity Transmission Company queue delays are extending project commissioning timelines beyond original financial close assumptions.
- Concentrated Solar Power cost disadvantage:Thermal storage-equipped plants face displacement from photovoltaic-plus-battery configurations in tender participation.
Strategic Opportunities
- Decentralized commercial installations:Industrial zones in the Nile Delta present untapped demand for behind-the-meter solar systems bypassing utility interconnection queues.
- Perovskite-silicon tandem commercialization:Laboratory efficiency breakthroughs are converging with Egypt's utility-scale tender requirements to create first-mover advantages for technology licensors.
- Net metering cap expansion:Anticipated regulatory adjustments to distributed generation thresholds will unlock residential and small commercial segments currently excluded from feed-in tariff access.
Industry Challenges
- Skilled technician scarcity:Photovoltaic installation and maintenance expertise lags deployment velocity, constraining quality assurance for decentralized projects.
- Currency hedging complexity:Egyptian pound volatility against dollar-denominated equipment imports is complicating long-term power purchase agreement pricing structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Solar Energy Market |
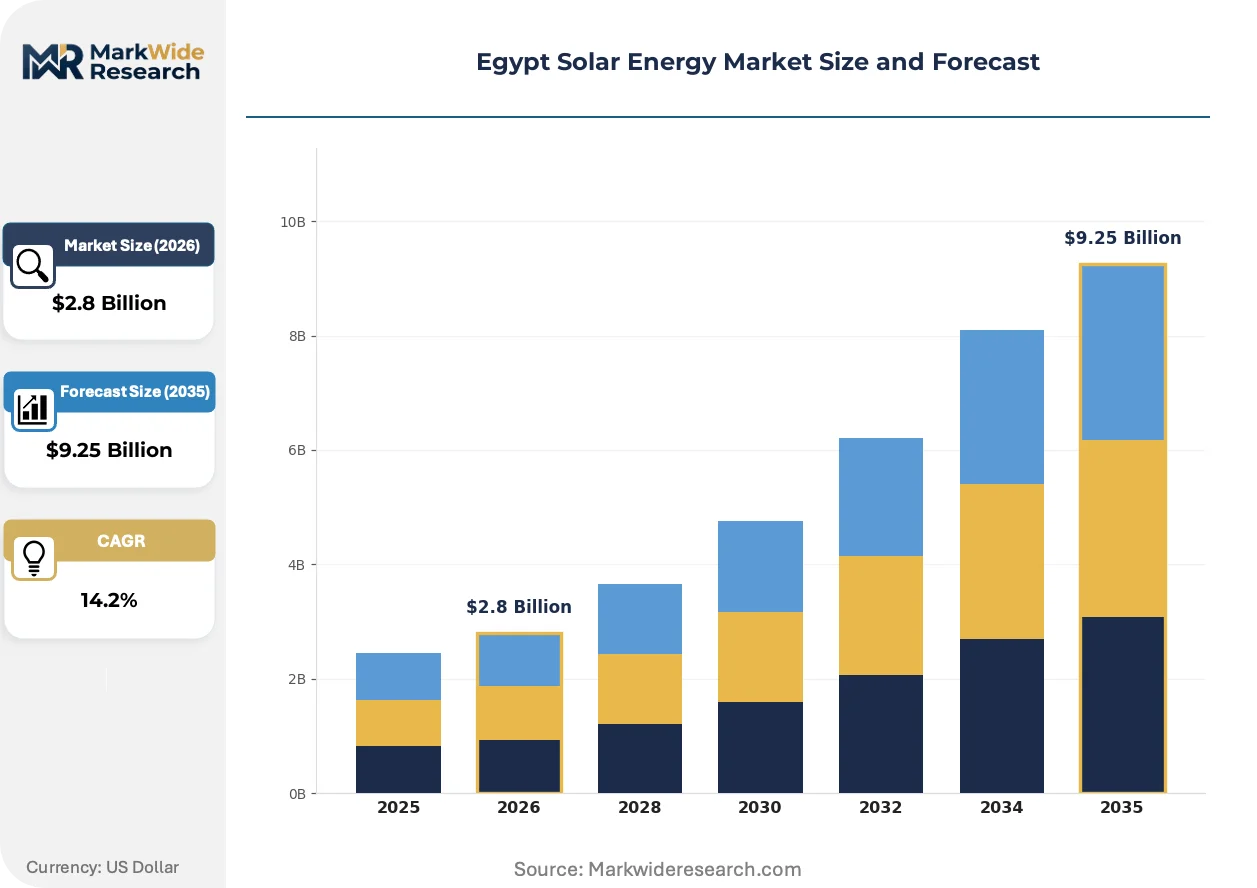
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.25 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Modules, Inverters, Batteries, Charge Controllers Application: Residential, Commercial, Industrial, Off-grid Technology: C-Si, Thin-film, BIPV, Concentrated Solar Power End User: Utilities, Government, Corporations, NGOs |
| Companies Covered | Egyptian Electricity Holding Company, Lightsource BP, TAQA Arabia, KarmSolar, Rees Tech, Infinity Power, Acropol, Elsewedy Electric, Scatec ASA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Solar Energy Market Shifts & Advancements
Module efficiency architectures and procurement mechanisms are undergoing parallel transformation, with crystalline silicon supply chains and competitive bidding frameworks both restructuring around localization imperatives.
Bifacial photovoltaic modules are capturing reflected irradiance from desert surfaces to boost effective energy yield. Utility-scale developers in the Benban cluster are specifying these configurations for new tenders. This technology is converging with tracking systems to compress levelized cost benchmarks against fixed-tilt thin-film alternatives.
The New and Renewable Energy Authority is tightening local content thresholds for competitive bidding rounds. Domestic assembly mandates are reshaping supplier qualification criteria. Crystalline silicon module producers are responding by establishing captive manufacturing within Industrial Development Authority zones rather than relying on import-dependent distribution.
Power purchase agreement structures are migrating from feed-in tariff fixation toward competitive auction mechanisms. Industrial offtakers in the Nile Delta are negotiating bilateral contracts directly with project developers. This shift is most visible among cement and steel producers seeking to bypass grid tariff volatility through captive renewable supply arrangements.
Egypt Solar Energy Market Segmentation
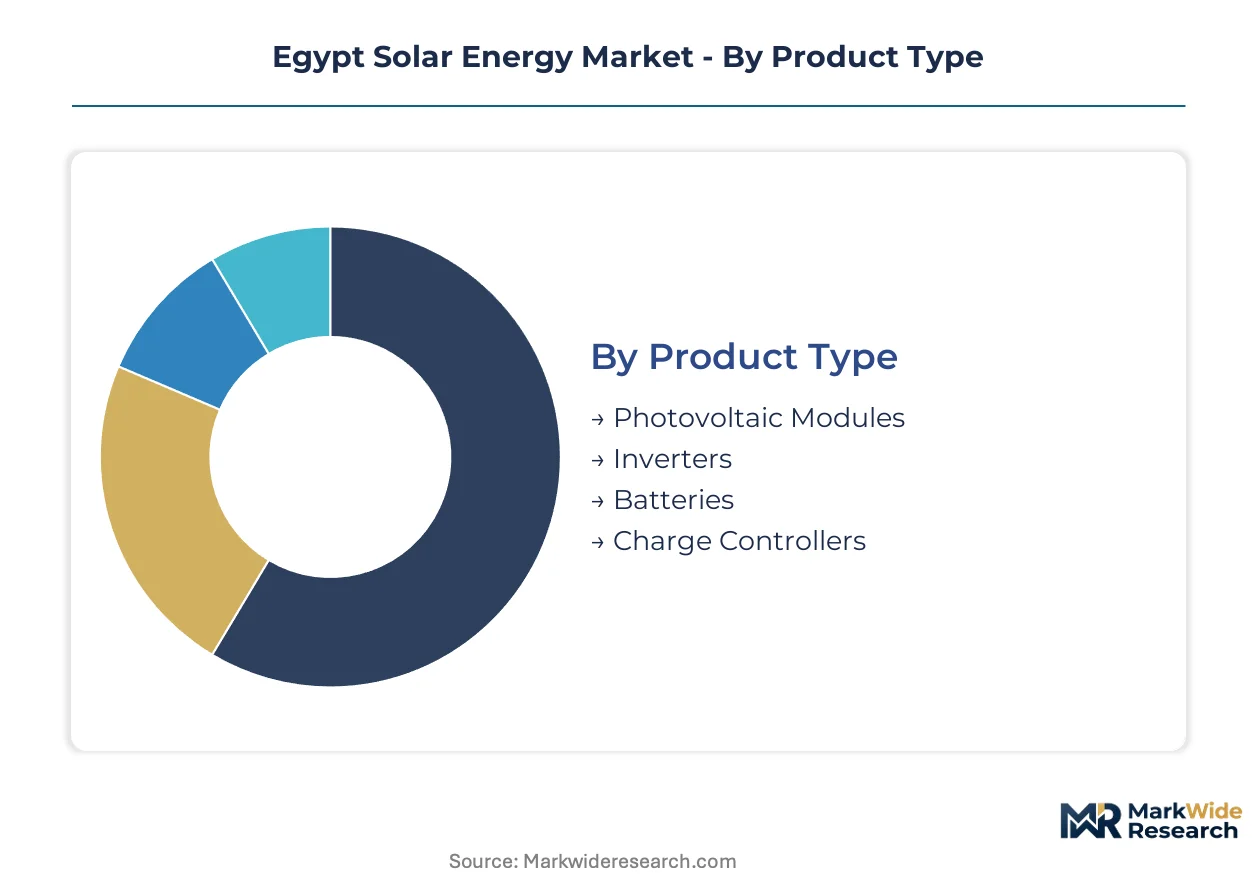
Segmentation in Egypt's solar energy market reveals how capital deployment, technology risk, and regulatory access determine project economics. Each dimension—product, application, technology, and end user—channels investment toward distinct return profiles and local content compliance thresholds.
Product Type:
Capital intensity varies sharply across the hardware stack, with upstream components demanding the heaviest balance-sheet commitment before revenue realization.
- Photovoltaic Modules:Crystalline silicon and thin-film assemblies convert incident radiation through semiconductor junctions, with efficiency ratings spanning 15-22% for commercial deployments. Demand concentrates in the Benban Solar Park cluster near Aswan, where land availability and grid infrastructure attract concentrated utility-scale procurement under the New and Renewable Energy Authority's feed-in tariff scheme.
- Inverters:Power electronics convert DC module output to grid-synchronous AC, with string and central configurations matching project scale. Procurement is accelerating from Chinese and European suppliers establishing local assembly within Industrial Development Authority zones to satisfy domestic content mandates.
- Batteries:Lithium-ion and emerging flow battery systems enable evening dispatch and grid stabilization services. Industrial offtakers in the Nile Delta are specifying storage-integrated systems to bypass interconnection queue delays.
- Charge Controllers:Regulate voltage and current flow in off-grid and hybrid configurations, protecting battery banks from overcharge cycles. Rural electrification programs and decentralized commercial installations drive procurement from specialized electronics distributors.
Most installed capacity flows through Photovoltaic Modules. Expansion is steepest in Batteries as photovoltaic-plus-storage configurations displace Concentrated Solar Power in tender participation.
Application:
Customer scale determines financing structure, with larger installations accessing project finance and smaller deployments relying on balance-sheet or consumer credit.
- Residential:Rooftop systems serving single-family and multi-unit dwellings, typically 3-10 kW capacity. Net metering caps currently constrain segment access, though anticipated regulatory adjustments will unlock demand among Egyptian Electricity Holding Company ratepayers.
- Commercial:Behind-the-meter installations for retail, hospitality, and office facilities, ranging 50 kW to 2 MW. Cement and steel producers in the Nile Delta are negotiating bilateral power purchase agreements directly with developers to bypass grid tariff volatility.
- Industrial:Captive generation for manufacturing, mining, and process heat applications, often 5-50 MW scale. High Direct Normal Irradiance zones exceeding 2,000 kWh/m² annually in Upper Egypt reduce levelized cost calculations for heavy electricity consumers.
- Off-grid:Standalone systems for remote settlements, agricultural pumping, and telecommunications infrastructure. Skilled technician scarcity constrains quality assurance as deployment velocity outpaces training pipeline capacity.
Industrial applications anchor current revenue. Commercial behind-the-meter systems are climbing the fastest as interconnection bottlenecks push developers toward distributed configurations.
Technology:
Efficiency benchmarks and manufacturing localization requirements are restructuring competitive positioning across cell architectures.
- C-Si:Crystalline silicon dominates utility-scale tenders through efficiency leadership and established supply chains. Domestic assembly mandates from the Industrial Development Authority are compelling module producers to relocate from import-dependent models.
- Thin-film:Cadmium telluride and copper indium gallium selenide systems anchor cost-sensitive desert applications where lower efficiency tolerates larger land footprints. Benban cluster developers specify these for fixed-tilt configurations on sandy substrates.
- BIPV:Building-integrated photovoltaics embed generation into facades, canopies, and roofing materials. Urban commercial projects in Cairo and Alexandria deploy these where rooftop space is constrained and aesthetic integration carries premium value.
- Concentrated Solar Power:Parabolic trough and tower systems with thermal storage retain structural importance for evening dispatch. Project pipeline participation lags photovoltaic deployments as photovoltaic-plus-battery configurations compress levelized cost benchmarks.
C-Si captures the dominant share of procurement volume. BIPV holds the steepest expansion trajectory as urban land scarcity intensifies and architectural integration standards tighten.
End User:
Contracting authority and offtake credit quality determine developer risk allocation and financing cost.
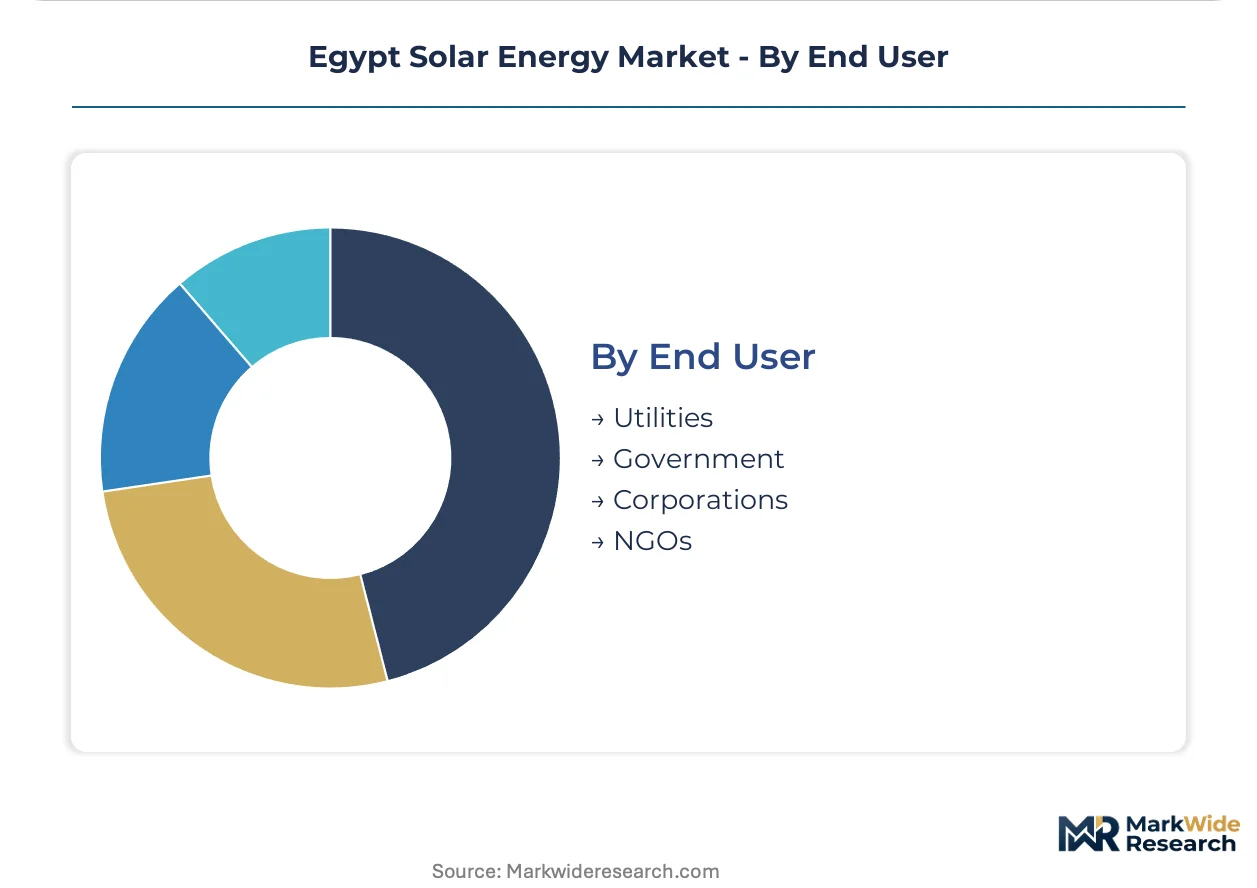
- Utilities:Egyptian Electricity Holding Company and distribution subsidiaries procure through competitive bidding rounds administered by the New and Renewable Energy Authority. Feed-in tariff fixation is migrating toward auction mechanisms that reward lowest-cost submissions.
- Government:Ministries and public agencies deploy solar for administrative facilities, military installations, and rural electrification programs. Budget execution cycles and currency hedging complexity complicate long-term power purchase agreement pricing structures.
- Corporations:Industrial offtakers in cement, steel, and chemicals negotiate captive renewable supply arrangements. Currency volatility against dollar-denominated equipment imports is squeezing margin structures under fixed-tariff contracts.
- NGOs:International development organizations and domestic nonprofits finance community-scale installations in underserved governorates. Implementation partners face skilled technician scarcity as decentralized project velocity accelerates.
Utilities channel the largest procurement volumes. Corporate offtakers are gaining share fastest as bilateral contracting bypasses utility interconnection queues and grid tariff uncertainty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Benban Solar Park anchors Egypt's solar deployment through concentrated transmission infrastructure and land availability that pulls utility-scale investment into Upper Egypt's high-irradiance zones.
Upper Egypt
Direct Normal Irradiance exceeding 2,000 kWh/m² annually drives photovoltaic economics for heavy industrial consumers. The New and Renewable Energy Authority administers competitive bidding rounds with local content thresholds that reshape supplier qualification. Aswan Governorate hosts the Benban cluster where crystalline silicon deployments dominate fixed-tilt and tracking configurations.
Nile Delta
Cement and steel producers negotiate bilateral power purchase agreements to bypass grid tariff volatility and interconnection queues. The Egyptian Electricity Transmission Company implements grid codes that constrain project locations and extend commissioning timelines. Industrial zones in Gharbia and Sharqia Governorates attract behind-the-meter commercial installations seeking captive renewable supply.
Greater Cairo
Building-integrated photovoltaics embed generation into constrained urban rooftops and facades where aesthetic integration carries premium value. The Industrial Development Authority mandates domestic assembly operations that compel module producers to relocate from import-dependent models. New Cairo and 6th of October City concentrate commercial deployments for retail and hospitality facilities.
Alexandria
Port infrastructure and Mediterranean logistics position the governorate for equipment import and coastal industrial solar applications. The Egyptian Electricity Holding Company procurement through distribution subsidiaries migrates from feed-in tariff fixation toward auction mechanisms. Borg El Arab industrial city anchors manufacturing-linked renewable installations for textile and food processing operations.
Red Sea Coast
Tourism and desalination facilities drive demand for off-grid and hybrid configurations in remote coastal settlements. Skilled technician scarcity constrains quality assurance as decentralized project velocity accelerates beyond training pipeline capacity. Hurghada and Sharm El Sheikh concentrate hospitality-sector solar procurement seeking energy cost stabilization.
Egypt Solar Energy Market Competitive Landscape
Global majors compete with regional champions across technology licensing and utility-scale development rights. The vendor base structures around three tiers: integrated industrial conglomerates with captive manufacturing, specialized renewable developers with project pipelines, and international IPP platforms with balance-sheet scale. Strategic archetypes include backward-integrated manufacturers controlling polysilicon-to-module supply chains, distributed generation specialists targeting commercial behind-the-meter segments, and utility-focused developers securing long-term power purchase agreements. Dominant competitive moves center on local assembly mandates compliance and bilateral contracting with industrial offtakers.
Within the integrated manufacturing tier, Elsewedy Electric exemplifies backward control over polysilicon through module assembly operations. Among specialized developers, KarmSolar occupies a position representing decentralized commercial installation expertise competing with utility-focused pipelines. At the international IPP vector, Scatec ASA anchors Nordic capital deployment into emerging market renewable infrastructure. These three archetypes—industrial conglomerate, distributed specialist, and international platform—capture distinct risk-return profiles across Egypt's procurement mechanisms.
| Leading Market Players |
|---|
| Egyptian Electricity Holding Company |
| Lightsource BP |
| TAQA Arabia |
| KarmSolar |
| Rees Tech |
| Infinity Power |
| Acropol |
| Elsewedy Electric |
| Scatec ASA |
| Others |
Supply & Pricing Matrix
Photovoltaic installation technician scarcity in Upper Egypt creates labor-cost differentials that widen pricing-tier spreads between premium tracking-system deployments and economy fixed-tilt configurations. Crystalline silicon module assemblers operating within Industrial Development Authority zones leverage captive manufacturing to compress margin structures against import-dependent competitors serving price-sensitive commercial segments.
Pricing Analysis
Input-cost pass-through from metallurgical-grade silicon volatility compresses margin structures for crystalline module assemblers operating under fixed-tariff contracts. Three-tier pricing structure across premium, standard, and economy levels separates bifacial tracking configurations from fixed-tilt thin-film alternatives from basic polycrystalline rooftop systems. Price differentiation hinges on efficiency certification tiers and domestic assembly compliance. Pricing pressure stems from Egyptian pound volatility against dollar-denominated equipment imports. Industrial offtakers in the Nile Delta demonstrate highest price sensitivity, while utility-scale developers at Benban prioritize performance guarantees over unit economics.
Supply Chain Analysis
Freight costs from Chinese polysilicon refineries and European inverter manufacturers constitute significant landed cost components for Egyptian project developers. Supply concentrates in China for metallurgical-grade silicon and module components, Germany for string inverter electronics, and domestic Industrial Development Authority zones for final assembly. Raw material dependencies include polysilicon feedstock, silver metallization pastes, and aluminum framing extrusions. Single-source vulnerability from concentrated Chinese polysilicon refining creates exposure to export restriction risks. Distribution runs through Egyptian Electricity Holding Company procurement channels, direct bilateral contracting with industrial offtakers, and specialized renewable EPC contractors serving decentralized commercial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's solar market offers margin expansion potential through crystalline silicon efficiency gains and localization-driven cost compression in module assembly operations.
For Market Incumbents: To counter photovoltaic-plus-battery configurations displacing Concentrated Solar Power in tender participation, crystalline silicon producers should deepen backward integration into polysilicon refining and expand captive manufacturing capacity within Industrial Development Authority zones. Securing long-term power purchase agreements with cement and steel producers in the Nile Delta anchors offtake volume against utility interconnection queue delays. For New Entrants and Emerging Players: Begin with behind-the-meter commercial installations in Gharbia and Sharqia Governorates, where grid tariff volatility drives captive renewable demand among manufacturing facilities. Perovskite-silicon tandem technology licensing offers differentiation in utility-scale bidding rounds. Direct bilateral contracting with industrial offtakers bypasses Egyptian Electricity Holding Company procurement complexity and accelerates revenue realization. For Investors and Strategic Acquirers: Industrial conglomerates with captive manufacturing footprints are the most active acquirer in this space, seeking technology licensors and distributed generation specialists to fill portfolio gaps. Acquisition targets should demonstrate compliance with New and Renewable Energy Authority local content thresholds and established project pipelines in high Direct Normal Irradiance zones. The signal to monitor is regulatory adjustment timing for net metering cap expansion, which would unlock residential and small commercial segment access.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Manufacturing Scale-Up | Industrial Development Authority zone establishment satisfies local content mandates for New and Renewable Energy Authority tenders. |
| Technology Licensing Agreement | Perovskite-silicon tandem cell IP partnerships position developers for efficiency breakthroughs in Benban cluster expansions. |
| Long-term Power Purchase Agreement | Bilateral contracting with Nile Delta cement and steel producers bypasses Egyptian Electricity Transmission Company interconnection queues. |
| Backward Integration into Polysilicon | Captive metallurgical-grade silicon supply insulates margin structures from commodity price volatility under fixed-tariff contracts. |
| Green Certification Program | Egyptian Electricity Holding Company procurement increasingly weights sustainability credentials in competitive auction mechanisms. |
Research Methodology
Coverage spans Upper Egypt, the Nile Delta, Greater Cairo, and the Red Sea Coast, with primary inputs from each region combined with secondary validation. Primary interviews engaged utility planning officers at Egyptian Electricity Holding Company, IPP project developers active in Benban cluster expansion, EPC contractors specializing in crystalline silicon deployment, and grid operators managing interconnection queue processes. Secondary sources included New and Renewable Energy Authority tender documentation, Egyptian Electricity Transmission Company grid code filings, Industrial Development Authority manufacturing zone records, and customs data tracking module import volumes. Bottom-up project pipeline aggregation triangulates against top-down procurement target analysis.
Segmentation granularity spans product type across photovoltaic modules, inverters, batteries, and charge controllers; application across residential, commercial, industrial, and off-grid configurations; technology across crystalline silicon, thin-film, building-integrated photovoltaics, and Concentrated Solar Power; and end user across utilities, government, corporations, and NGOs. CAGRs derive from project commissioning timelines, tender participation rates, and manufacturing capacity expansion schedules across the analysis window. Forecast inputs incorporate Direct Normal Irradiance zone mapping, local content threshold evolution, and currency hedging cost assumptions.
Several conditions sit outside the modeled scope, including geopolitical disruptions to polysilicon supply chains, abrupt regulatory cancellation of feed-in tariff mechanisms, and grid infrastructure investment delays beyond Egyptian Electricity Transmission Company disclosed timelines. Forecasts reflect assumptions regarding continued New and Renewable Energy Authority procurement activity and stable bilateral contracting frameworks for industrial offtakers. Stakeholders should weight assumptions against their own operating context and monitor forthcoming regulatory adjustments to net metering caps and domestic manufacturing quotas.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Ribbon Market
Solar Power Systems
Solar Charger Market
Solar Power Systems
Global Photovoltaic Glass Market
Solar Power Systems
Building Integrated Photovoltaic (BIPV) Market
Solar Power Systems
Plastic Solar Cell Market
Solar Power Systems
Asia-Pacific Solar Concentrator Market
Solar Power Systems
Solar Energy Market
Solar Power Systems
Smart Solar Tracker Market
Solar Power Systems
Slovakia Solar Energy Market
Solar Power Systems
Organic PV Solar Cells Market
Solar Power Systems
Industrial Solar Water Heaters Market
Solar Power Systems
United States Solar Microinverter Market
Solar Power Systems
CPV Solar Sales Market
Solar Power Systems
Photovoltaic Mounting System Market
Solar Power Systems
Solar Panels for Home Market
Solar Power Systems
Amorphous Silicon PV Market