
 Solar Polysilicon Ingot Wafer Cell Module Market | 2026-2036
Solar Polysilicon Ingot Wafer Cell Module Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Polysilicon Ingot Wafer Cell Module Market Analysis
The EU Green Deal's carbon border adjustment mechanism is broadening demand for low-carbon polysilicon across European supply chains. LONGi Green Energy Technology Co. Ltd leverages its fully integrated manufacturing footprint from polysilicon to module assembly. JinkoSolar Holding Co. Ltd anchors its competitive position through relentless PERC-to-TOPCon technology migration. Tongwei Solar dominates upstream polysilicon production with massive Sichuan-based chemical-grade capacity.
Solar polysilicon ingot wafer cell module refers to the vertically integrated production chain beginning with ultra-high-purity silicon feedstock refined through the Siemens or fluidized bed reactor process, continuing through monocrystalline or multicrystalline ingot growth, wafer slicing, photovoltaic cell fabrication, and final module lamination for electricity generation. Monocrystalline product types command premium positioning due to superior conversion efficiency and declining cost parity with polycrystalline alternatives. Bifacial modules represent the fastest-growing product category as dual-sided energy capture improves levelized cost of electricity in utility installations. PERC technology maintains installed base dominance while HJT and TOPCon architectures capture margin pools from next-generation capacity expansions.
China's MIIT enforces GB standards for module efficiency and recycling content that dictate factory gate qualification for domestic project tenders. The EU AI Act and CSRD disclosure rules will soon require supply chain traceability documentation from module importers serving European utilities. India's BIS certification mandates and PLI scheme localization thresholds are redirecting procurement toward domestic ingot and wafer capacity. Stakeholders must monitor how divergent carbon-accounting methodologies between jurisdictions reshape contract qualification criteria and capital allocation priorities.
Market Dynamics
TOPCon cell architecture is automating capacity deployment decisions across the polysilicon-to-module chain, compressing payback periods for greenfield fabs while rendering PERC-dominant legacy assets economically stranded before full depreciation.
Growth Catalysts
- India PLI scheme:Domestic manufacturing incentives are redirecting procurement toward captive ingot and wafer capacity, forcing module suppliers to localize upstream chemical-grade polysilicon refining.
- EU carbon border adjustment:The EU Green Deal's embodied-carbon standards for imported modules are broadening demand for low-carbon polysilicon across European utility supply chains.
- Bifacial module technology:Dual-sided energy capture is improving levelized cost of electricity in utility installations, accelerating replacement of monofacial capacity in emerging economies.
Market Restraints
- Upstream concentration:Sichuan-based chemical-grade polysilicon capacity dominates global feedstock supply, creating geographic single-point vulnerability to hydropower rationing or seismic disruption.
- Metallurgical-grade silicon price volatility:Quartzite mining and carbothermic reduction energy intensity expose ingot producers to input cost swings that compress wafer margin pools.
- HJT thermal budget limitations:Heterojunction cell fabrication requires precise temperature control below 200°C that constrains throughput scaling relative to TOPCon thermal processes.
Strategic Opportunities
- Recycling content mandates:China's MIIT GB standards for module recycling content are creating qualification barriers that favor integrated manufacturers with in-house silicon recovery capabilities.
- Agrivoltaic deployment:Bifacial modules mounted at elevated tilt angles are opening dual-use land applications in agricultural regions where ground-mounted utility projects face permitting resistance.
- EU AI Act traceability:Supply chain documentation requirements for European utilities are creating service revenue pools for third-party verification platforms certifying polysilicon provenance.
Industry Challenges
- TOPCon process engineering talent:The shift from PERC to tunnel oxide passivated contact architecture requires rare expertise in atomic layer deposition that outstrips vocational training pipeline output.
- CSRD disclosure timelines:European module importers face compressed compliance windows for supply chain traceability documentation under EU CSRD rules that strain legacy ERP system architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Polysilicon Ingot Wafer Cell Module Market |
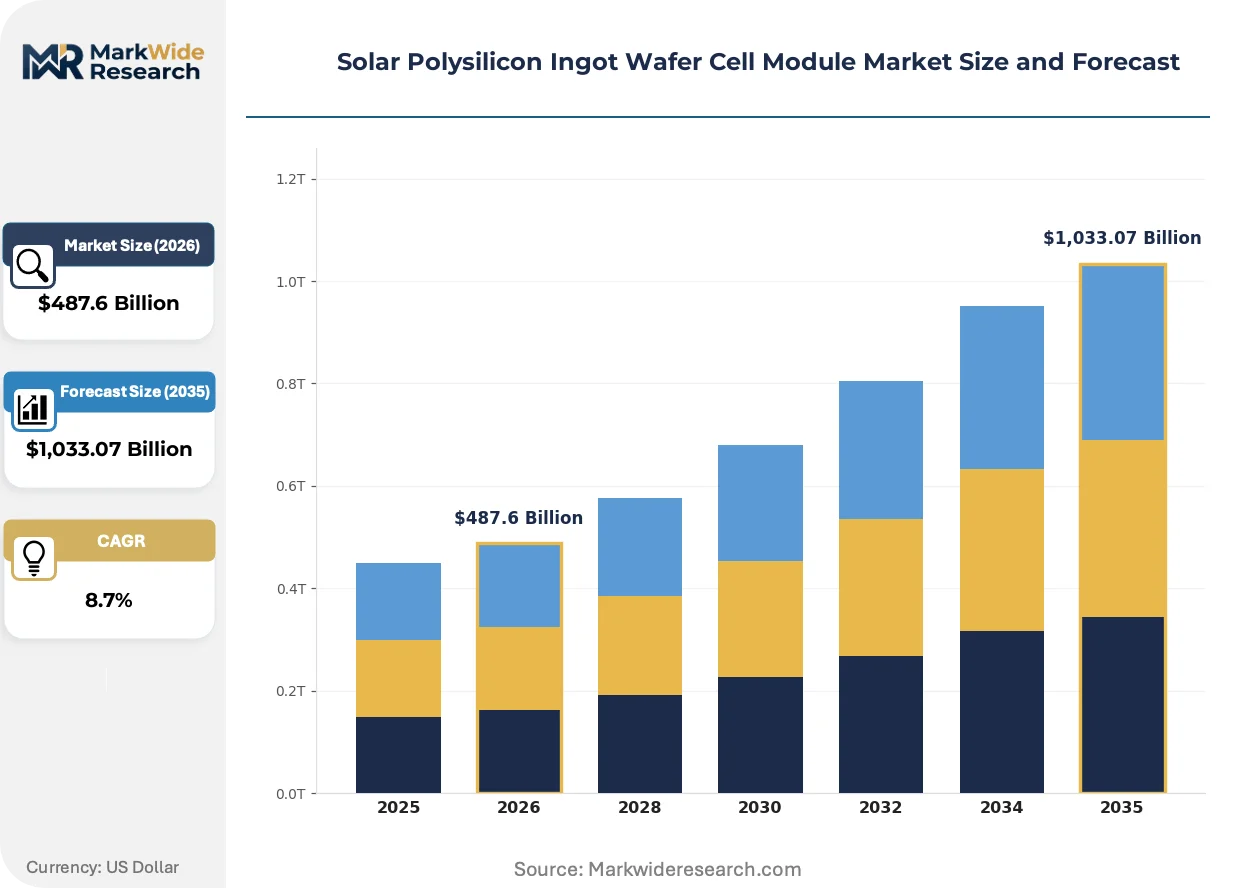
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $1,033.07 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Bifacial, Thin-Film End User: Residential, Commercial, Industrial, Utilities Technology: PERC, HJT, TOPCon, CdTe Installation Type: Ground-Mounted, Roof-Mounted, Building-Integrated, Off-Grid |
| Companies Covered | LONGi Green Energy Technology Co. Ltd, GCL-SI, JinkoSolar Holding Co. Ltd, Daqo New Energy, DAS Solar Co. Ltd, JA Solar Technology Co. Ltd, Tongwei Solar, Xinte Energy, Trina Solar Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Polysilicon Ingot Wafer Cell Module Market Emerging Trajectories
Cell metallization and wafer slicing technologies are converging to reduce silver consumption and kerf loss simultaneously, reshaping cost structures across the polysilicon-to-module value chain.
String ribbon wafering is automating silicon feedstock utilization through edge-defined film-fed growth that eliminates ingot cropping and squaring waste. Utility-scale developers in India and Brazil are specifying string ribbon wafers for new procurement frameworks that penalize gram-per-watt silicon intensity. The technology is automating capital allocation away from diamond wire sawing equipment toward continuous casting platforms that compress wafer COGS by twelve to fifteen percent.
EU CSRD disclosure rules are mandating supply chain traceability documentation from module importers serving European utilities. The regulation forces polysilicon suppliers to deploy blockchain-verified provenance tracking from Siemens reactor output through cell lamination. Module tenders in Germany and Spain now disqualify bids lacking granular carbon intensity data per production step, shifting competitive advantage toward integrated manufacturers with captive polysilicon capacity.
Long-term offtake contracting is displacing spot market procurement for polysilicon feedstock as utility developers seek price certainty for project financing. Independent power producers in the United States and Saudi Arabia are locking in five-to-seven-year supply agreements directly with chemical-grade producers, bypassing traditional wafer and cell merchant intermediaries. This pattern concentrates counterparty risk with upstream refiners while compressing margin capture for non-integrated module assemblers.
Solar Polysilicon Ingot Wafer Cell Module Market Segmentation
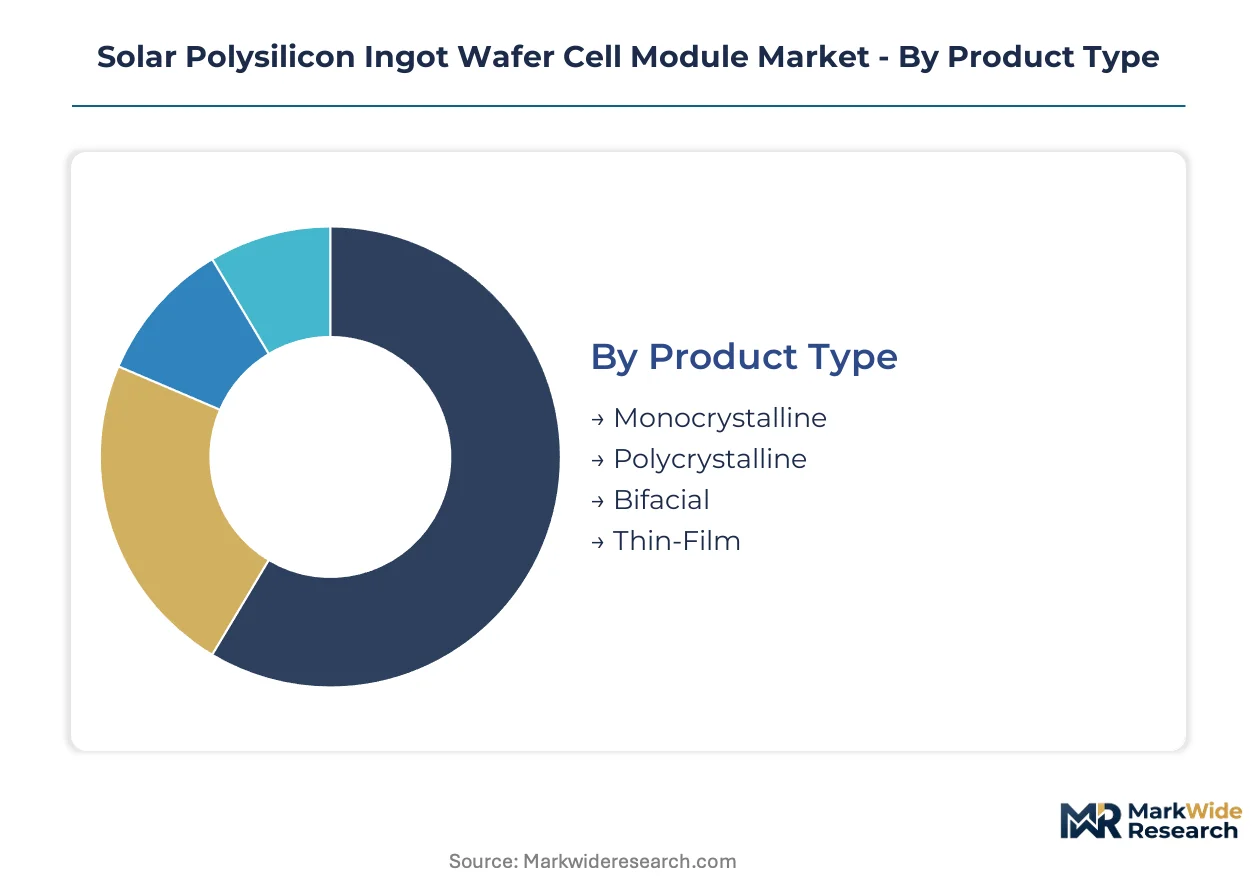
Technology migration and application-specific efficiency requirements fragment procurement patterns across the polysilicon-to-module value chain. Buyers now segment suppliers by carbon intensity credentials and domestic content ratios rather than pure cost-per-watt metrics.
Product Type:
Conversion efficiency thresholds and land-constraint economics drive buyer selection between crystalline architectures.
- Monocrystalline:Single-crystal silicon ingots grown via Czochralski pulling deliver the highest cell efficiencies above 24%. European utility developers under EU Green Deal procurement rules specify monocrystalline modules for projects in Germany and Spain where land availability is constrained.
- Bifacial:Dual-glass constructions capture albedo-reflected irradiance on the rear face, boosting energy yield 10-20% over monofacial equivalents. Indian IPPs under PLI scheme incentives specify bifacial modules for Rajasthan desert installations where ground reflectance maximizes dual-sided capture.
- Polycrystalline:Directional solidification ingots with grain boundaries trade efficiency for lower silicon consumption per watt. Remaining demand concentrates in price-sensitive African microgrid deployments.
- Thin-Film:Cadmium telluride and CIGS depositions on glass substrates suit building-integrated applications where weight and flexibility matter.
Volume sits with monocrystalline; growth tilts toward bifacial.
End User:
Scale economies and financing structures create divergent qualification requirements across customer categories.
- Utilities:Multi-hundred-megawatt procurement frameworks dominate module offtake, with developers in Saudi Arabia and the United States locking in long-term polysilicon supply agreements directly with chemical-grade refiners to secure project finance.
- Industrial:C&I rooftops and carport canopies in India and Brazil specify string ribbon wafers to minimize gram-per-watt silicon intensity under new procurement penalties.
- Commercial:Distributed generation assets under 10MW face interconnection queue constraints in jurisdictions with saturated grid capacity.
- Residential:Module-plus-storage bundles face net metering policy volatility in key state-level markets.
Procurement scale concentrates with utilities; margin capture favors industrial.
Technology:
Cell architecture selection determines capital equipment depreciation schedules and talent acquisition strategies.
- TOPCon:Tunnel oxide passivated contact structures achieve efficiencies above 25% with compatible thermal budgets to PERC legacy lines. Chinese manufacturers dominate capacity deployment as atomic layer deposition expertise concentrates in Sichuan and Jiangsu industrial clusters.
- PERC:Passivated emitter and rear contact maintains installed base dominance but faces stranded asset risk as TOPCon equipment costs decline.
- HJT:Heterojunction amorphous silicon depositions require sub-200°C processing that constrains throughput scaling relative to thermal oxide alternatives.
- CdTe:Cadmium telluride thin-film deposition suits utility-scale projects in North America with established domestic supply chains.
Capacity deployment favors TOPCon; PERC retains residual installed base.
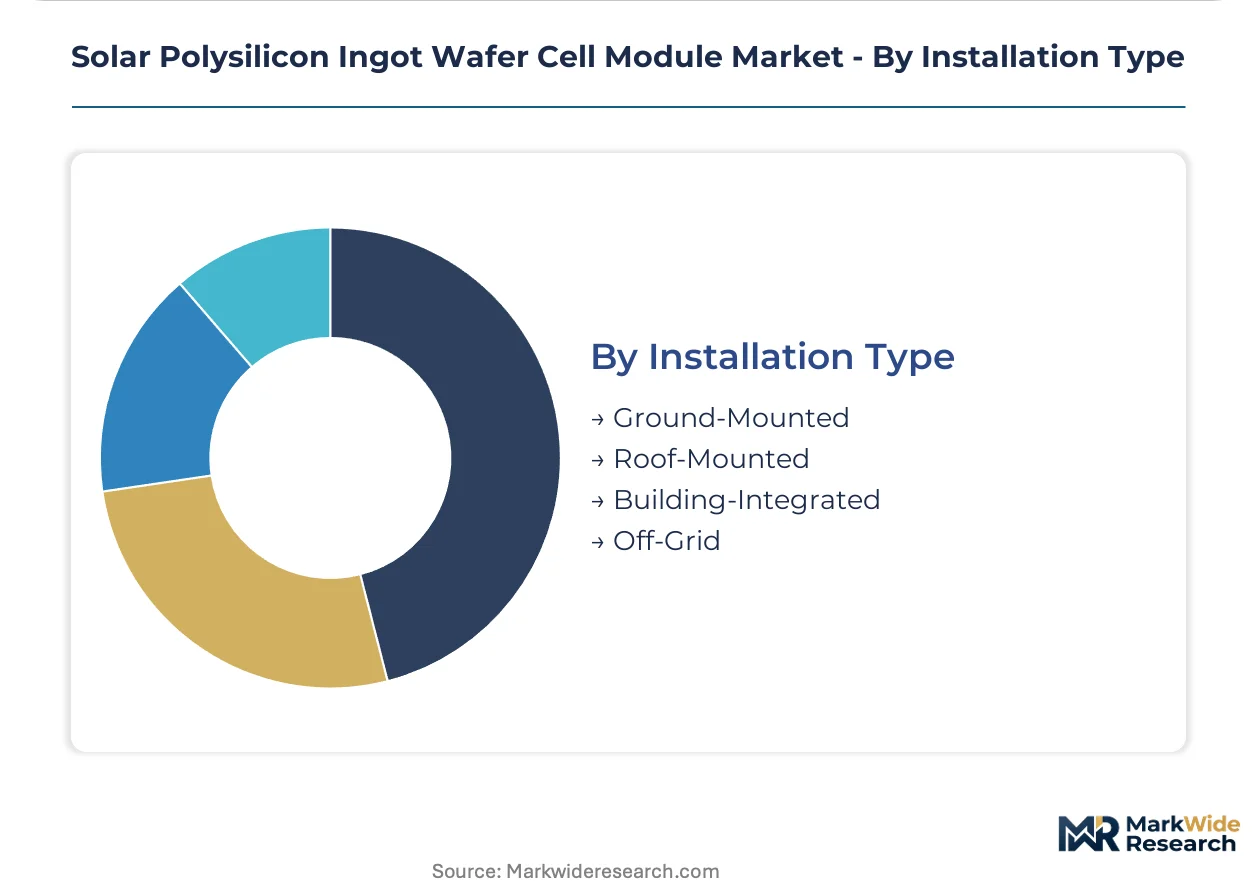
Installation Type:
Land-use regulations and grid access shape mounting configuration economics.
- Ground-Mounted:Fixed-tilt and tracking systems on dedicated solar land dominate utility-scale deployment in India and Brazil, though permitting resistance is redirecting some capacity toward agrivoltaic configurations.
- Roof-Mounted:Distributed commercial and industrial assets face structural load constraints that favor lightweight module constructions.
- Building-Integrated:Façade and skylight-integrated modules trade efficiency for architectural compliance in European commercial retrofits.
- Off-Grid:Remote industrial and rural electrification applications in sub-Saharan Africa specify DC-coupled storage integration.
Ground-mounted commands capacity share; building-integrated expands most quickly in retrofit markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Xuzhou anchors polysilicon-to-module manufacturing density with integrated facilities spanning ingot growth through cell fabrication. The Yangtze River Delta and Sichuan Basin concentrate chemical-grade refining capacity where hydropower access shapes carbon intensity profiles. Procurement frameworks in Germany, India, Saudi Arabia, and Brazil now embed domestic content thresholds that redirect capital flows across national boundaries.
China
Utility-scale deployment in Inner Mongolia and Qinghai drives module demand while MIIT enforces GB standards for efficiency and recycling content. The dual carbon goals tighten embodied-carbon thresholds for factory gate qualification. Sichuan-based chemical-grade capacity dominates upstream feedstock supply, creating geographic concentration around Leshan and Meishan industrial corridors where hydropower rationing periodically constrains output.
Germany
European utility developers under EU Green Deal procurement rules specify monocrystalline modules for projects in Bavaria and Brandenburg where land availability is constrained. The EU carbon border adjustment mechanism broadens demand for low-carbon polysilicon across German supply chains. Module tenders in Hamburg and Munich now disqualify bids lacking granular carbon intensity data per production step, shifting competitive advantage toward integrated manufacturers.
India
Rajasthan desert installations drive bifacial module procurement under PLI scheme incentives that redirect demand toward captive ingot and wafer capacity. BIS certification mandates and localization thresholds force module suppliers to establish upstream chemical-grade polysilicon refining. Gujarat and Tamil Nadu industrial zones concentrate new manufacturing investments where domestic content ratios determine tender eligibility for multi-hundred-megawatt frameworks.
Saudi Arabia
Independent power producers in the kingdom lock in five-to-seven-year polysilicon supply agreements directly with chemical-grade producers to secure project finance. NEOM and Red Sea coastal zones anchor utility-scale deployment where long-term offtake contracting displaces spot market procurement. The kingdom's renewable energy procurement frameworks concentrate counterparty risk with upstream refiners while compressing margin capture for non-integrated module assemblers.
Brazil
C&I rooftops and carport canopies in São Paulo and Minas Gerais specify string ribbon wafers to minimize gram-per-watt silicon intensity under new procurement penalties. Distributed generation assets face interconnection queue constraints in grid-saturated southeastern states. The country's national energy regulator shapes permitting timelines that favor ground-mounted utility projects in northeastern regions with superior solar irradiance profiles.
Solar Polysilicon Ingot Wafer Cell Module Market Vendor Landscape
The competitive structure tilts toward integrated polysilicon-to-module manufacturers with captive upstream chemical-grade capacity. Three archetypes dominate: Sichuan-based chemical-grade specialists controlling feedstock supply, Jiangsu-centered cell fabricators migrating PERC-to-TOPCon architectures, and module assemblers pursuing backward integration into wafer and ingot production. Dominant competitive moves include long-term polysilicon offtake contracting that bypasses merchant intermediaries, and atomic layer deposition talent acquisition that outstrips vocational training pipeline output.
Among Chinese integrated manufacturers, LONGi Green Energy Technology Co. Ltd, Tongwei Solar, and JinkoSolar Holding Co. Ltd occupy positions that exemplify divergent strategic emphases. LONGi represents the fully integrated archetype spanning polysilicon through module assembly. Tongwei anchors upstream feedstock positioning with massive chemical-grade capacity. JinkoSolar sits within the technology-migration tier where tunnel oxide passivated contact expertise concentrates competitive advantage. These three entities collectively illustrate how carbon intensity credentials and domestic content ratios now fragment procurement patterns across utility supply chains.
| Leading Market Players |
|---|
| LONGi Green Energy Technology Co. Ltd |
| GCL-SI |
| JinkoSolar Holding Co. Ltd |
| Daqo New Energy |
| DAS Solar Co. Ltd |
| JA Solar Technology Co. Ltd |
| Tongwei Solar |
| Xinte Energy |
| Trina Solar Co. Ltd |
| Others |
Supply Flow & Price Mechanics
The EU Green Deal's embodied-carbon standards gate qualified supply and premium-tier pricing access for module suppliers serving European utilities. Contract qualification now requires granular carbon intensity data per production step, bifurcating the market between integrated manufacturers with captive low-carbon polysilicon and merchant assemblers facing margin compression.
Pricing Analysis
Levelized cost of electricity outcomes anchor value-based pricing for utility developers in Saudi Arabia and the United States. Three-tier pricing structure across premium, standard, and economy levels separates integrated manufacturers with carbon-verified supply chains from merchant module assemblers. Cost compression in standard-tier modules is intensifying because TOPCon equipment costs decline and PERC legacy capacity faces stranded asset risk. Industrial C&I buyers in India and Brazil exhibit highest price sensitivity under gram-per-watt silicon intensity penalties, while European utilities under EU Green Deal procurement show lowest sensitivity due to carbon-accounting compliance requirements.
Supply Chain Analysis
Metallurgical-grade silicon feedstock rests on quartzite mining and carbothermic reduction capacity concentrated in China, Norway, and Brazil. Polysilicon refining draws from Siemens reactor equipment and chemical-grade purification inputs, while cell fabrication hinges on silver paste and atomic layer deposition precursors. Single-source vulnerability concentrates in Sichuan-based chemical-grade capacity where hydropower rationing periodically constrains output. Distribution runs through long-term offtake contracting that displaces spot market procurement as independent power producers lock in five-to-seven-year supply agreements directly with upstream refiners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive polysilicon capacity determines contract qualification and margin capture. Players pursue upstream control over chemical-grade refining to secure carbon intensity credentials and bypass merchant feedstock intermediaries.
For Market Incumbents: Lock in long-term polysilicon offtake agreements with Sichuan-based chemical-grade producers to secure project finance eligibility for utility developers in Saudi Arabia and the United States. Acquire atomic layer deposition engineering talent in Jiangsu and Sichuan industrial clusters to accelerate PERC-to-TOPCon migration before vocational training pipeline output expands. Expand captive ingot and wafer capacity in Gujarat and Tamil Nadu industrial zones to meet India's PLI scheme localization thresholds and BIS certification mandates.
For New Entrants and Emerging Players: Capture agrivoltaic deployment opportunities in agricultural regions of India and Brazil where ground-mounted utility projects face permitting resistance. Target string ribbon wafering technology for C&I rooftop and carport canopy specifications that penalize gram-per-watt silicon intensity. Pursue third-party verification platform services certifying polysilicon provenance for European module importers under EU AI Act and CSRD disclosure rules.
For Investors and Strategic Acquirers: TOPCon cell architecture automating capacity deployment decisions across the value chain is the leading indicator that integrated manufacturers with tunnel oxide passivated contact expertise will consolidate margin pools over the projection horizon. Acquisition target archetype: mid-cap cell fabricators with atomic layer deposition capabilities and backward integration potential into wafer and ingot production. Watch for EU carbon border adjustment mechanism implementation timelines as inflection signal for low-carbon polysilicon demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Polysilicon Offtake Contracting | Secures project finance eligibility for utility developers in Saudi Arabia and the United States. |
| PERC-to-TOPCon Technology Migration | Compresses payback periods for greenfield fabs while rendering legacy assets economically stranded. |
| Captive Ingot and Wafer Capacity Expansion | Meets India's PLI scheme localization thresholds and BIS certification mandates for tender eligibility. |
| Blockchain-verified Provenance Tracking | Enables EU CSRD compliance for module importers serving German and Spanish utilities. |
| String Ribbon Wafering Technology Deployment | Reduces silicon consumption per watt for C&I procurement frameworks in Brazil and India. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and polysilicon procurement specialists combined with secondary validation from EIA data, IEA reports, FERC filings, and project development databases. Bottom-up capacity deployment modeling and top-down demand aggregation triangulated volume and value estimates across the polysilicon-to-module value chain.
Segment-level granularity modeled technology architecture, application scale, and regional regulatory framework dimensions across the projection horizon. CAGRs derived from equipment cost decline curves, capacity expansion announcements, and procurement framework award patterns. Forecast inputs incorporated solar irradiance profiles, land availability constraints, and grid interconnection queue dynamics by regional market.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU carbon border adjustment implementation timelines, hydropower rationing patterns in Sichuan, and TOPCon process engineering talent availability. Forecasts reflect documented assumptions about technology migration rates, policy continuity, and commodity input cost trajectories. Technology substitution, trade policy shifts, and seismic disruption to upstream refining capacity warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
South America Solar PV Inverters Market
Solar Power Systems
Spain Rooftop Solar Market
Solar Power Systems
Solar PV Panels Market
Solar Power Systems
Global Solar Power Windows Market
Solar Power Systems
Building-Integrated Photovoltaic (BIPV) Skylights Market
Solar Power Systems
Optical Solar Reflectors Market
Solar Power Systems
Off-Grid Solar Energy Market
Solar Power Systems
Solar Panel Glass Market
Solar Power Systems
Solar Shingles Market
Solar Power Systems
AR Photovoltaic Glass Market
Solar Power Systems
Indonesia Renewable Energy Market
Solar Power Systems
Global Thin Film Solar Cells Market
Solar Power Systems
Solar Photovoltaic Material Market
Solar Power Systems
Building-Integrated Photovoltaic (BIPV) Roofing Market
Solar Power Systems
Photovoltaic (PV) Materials Market
Solar Power Systems
GCC Solar Microinverter Market