
 Canada Distributed Solar Power Generation Market | 2026-2036
Canada Distributed Solar Power Generation Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Distributed Solar Power Generation Market Outlook
Ontario's manufacturing corridor is rewriting the competitive terrain for module supply and inverter distribution across central Canada. Canadian Solar Inc. leverages its domestic cell assembly footprint to anchor procurement contracts with Ontario's commercial building sector. Silfab Solar Inc. specializes in high-efficiency monocrystalline output from its Washington-based facilities, sustaining cross-border shipments into British Columbia and Alberta. Grasshopper Solar Corporation dominates the residential lease and power-purchase agreement channel, controlling customer acquisition in Ontario's Greater Toronto Area.
Canada Distributed Solar Power Generation encompasses small-scale photovoltaic, thermal, and hybrid energy systems typically installed at or near the point of consumption, with DC-to-AC conversion efficiencies ranging from 19% to 22% for crystalline silicon modules under standard test conditions. These installations serve commercial, industrial, and agricultural load centers seeking to reduce grid dependency and manage escalating electricity tariffs. Photovoltaic systems occupy the dominant revenue share, while battery storage attachments represent the fastest-expanding margin pool as lithium-ion pack costs decline and provincial time-of-use spreads widen. Rooftop deployment leads installation-type volumes in urban Ontario and Quebec, though ground-mounted arrays gain traction among Alberta agricultural operators with surplus acreage.
Health Canada and the Canadian Standards Association govern electrical safety and grid-interconnection protocols, while provincial regulators including the Ontario Energy Board and Alberta Utilities Commission set net-metering caps and feed-in tariff structures that directly shape project economics. The federal Clean Electricity Regulations impose escalating emissions-intensity thresholds that push provincial grids toward non-emitting sources, indirectly expanding the addressable market for behind-the-meter solar. Stakeholders must monitor interprovincial transmission build-out schedules and natural gas retirement timelines to calibrate distributed asset deployment against wholesale price volatility and capacity-value compensation reforms.
Market Dynamics
The federal Clean Electricity Regulations are compressing payback periods for behind-the-meter installations by tightening grid-emissions thresholds and elevating carbon-offset valuations for commercial hosts. Provincial net-metering caps and interconnection queues now determine deployment velocity more than module pricing does.
Growth Catalysts
- Alberta's Agricultural Electrification:Prairie grain-drying and irrigation loads drive ground-mounted array adoption among farm operators with surplus acreage and rising electricity tariffs.
- Ontario's Time-of-Use Spreads:The Ontario Energy Board's rate structures create arbitrage value for battery-attached solar, accelerating commercial building investment.
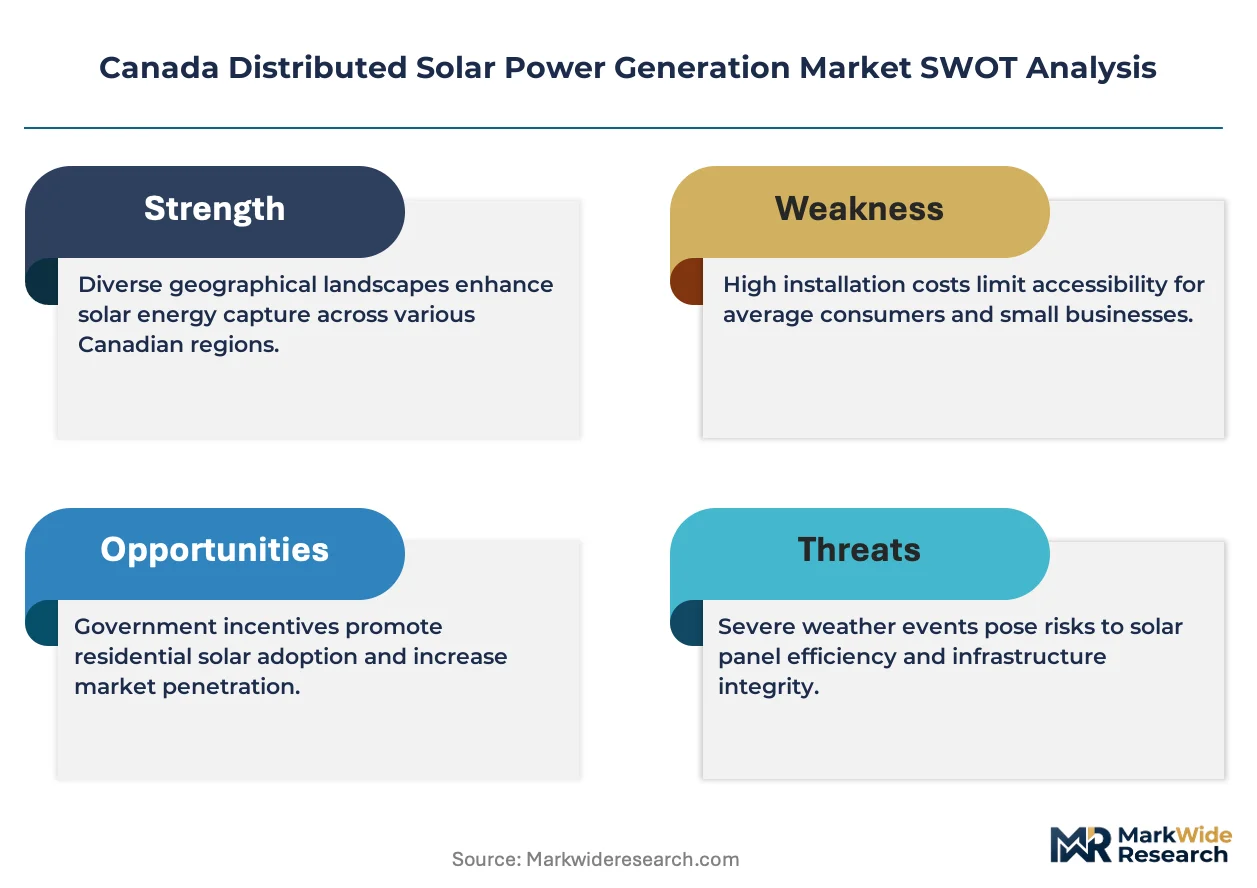
- Federal Clean Electricity Regulations:Escalating emissions-intensity thresholds push provincial grids toward non-emitting sources, expanding the addressable market for distributed photovoltaic assets.
Market Restraints
- Polysilicate Input Cost Volatility:Crystalline silicon module production remains exposed to upstream metallurgical-grade silicon price swings from Chinese smelter concentration.
- Interconnection Queue Congestion:Alberta Utilities Commission processing timelines for behind-the-meter approvals now stretch 8-14 months, freezing capital deployment.
- Natural Gas Baseload Competition:Alberta and Saskatchewan grid operators maintain gas-fired capacity as reliability backstop, capping peak-hour price premiums that solar captures.
Strategic Opportunities
- Quebec's Untapped Commercial Segment:Low historical electricity rates suppressed solar adoption, but Hydro-Québec rate hikes and carbon-accounting mandates now open mid-market building portfolios.
- Agricultural Hybrid Arrays:Agrivoltaic configurations combining ground-mounted panels with livestock grazing or pollinator habitats unlock provincial conservation incentive stacking.
- Third-Party Ownership Channels:Power-purchase agreements and equipment leases bypass upfront capital barriers for Ontario manufacturing SMEs with constrained balance sheets.
Industry Challenges
- Certified Electrician Scarcity:Canadian Standards Association licensed solar installers remain concentrated in Toronto and Calgary, constraining deployment in Atlantic Canada and rural Prairie markets.
- Legacy Grid Integration Complexity:Distribution utilities in Ontario and British Columbia require extensive protection-coordination studies for high-penetration solar feeders, extending commissioning timelines.
- Interprovincial Equipment Standards Divergence:Quebec's Régie du bâtiment du Québec maintains distinct electrical code interpretations from Ontario's Electrical Safety Authority, fragmenting installer certification requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Distributed Solar Power Generation Market |
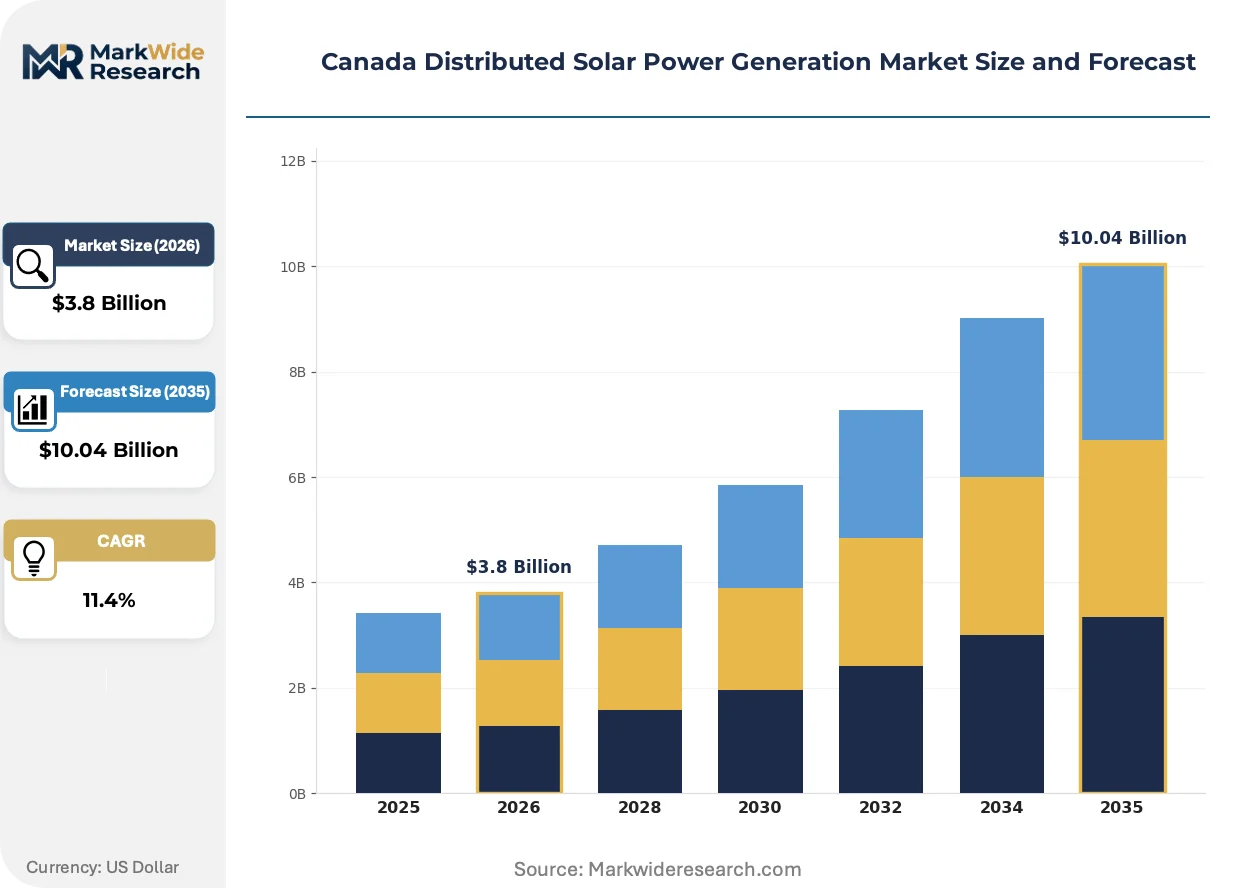
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Systems, Solar Thermal Systems, Hybrid Systems, Battery Storage Technology: Crystalline Silicon, Thin-Film, Bifacial, Concentrated Solar Power End User: Residential, Commercial, Industrial, Agricultural Installation Type: Rooftop, Ground-Mounted, Building-Integrated, Off-Grid |
| Companies Covered | LONGi Green Energy Technology Co., Ltd., Grasshopper Solar Corporation, Canadian Solar Inc., Silfab Solar Inc., Heliene Inc., EDF Renewables Canada Inc., Polaron Solartech Corp, SolarEdge Technologies Inc., Brookfield Renewable Partners L.P., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Distributed Solar Power Generation Market Strategic Shifts
Module-level power electronics and lithium-ion storage are converging to reshape system architecture and value capture for Canadian commercial hosts. Technology trajectories now favor integrated solutions over component stacking.
Bifacial photovoltaic modules with dual-glass construction are hybridizing system design by capturing reflected irradiance from snow-covered ground surfaces and rooftop membranes. Alberta agricultural operators with high-albedo soil conditions report energy yield premiums exceeding monofacial baselines during winter months. This technology is hybridizing ground-mount economics by extending productive hours and flattening seasonal generation curves.
The federal Clean Electricity Regulations impose escalating emissions-intensity thresholds that force provincial grid operators to value behind-the-meter solar for capacity deferral and locational marginal price suppression. Industrial load centers in Ontario's manufacturing corridor now face carbon-border adjustment exposure, accelerating on-site renewable procurement. Commercial building owners respond by bundling solar with battery storage to maximize carbon-offset registry eligibility and peak-demand charge avoidance.
Building operators are consolidating vendor relationships around integrated engineering-procurement-construction contractors who assume performance risk and warranty obligations. Ontario's Greater Toronto Area sees mid-market commercial buyers abandon component-by-component sourcing in favor of turnkey contracts with guaranteed production ratios. This concentration is most visible among multi-site retail and logistics portfolios seeking standardized reporting for corporate sustainability disclosures.
Canada Distributed Solar Power Generation Market Segmentation
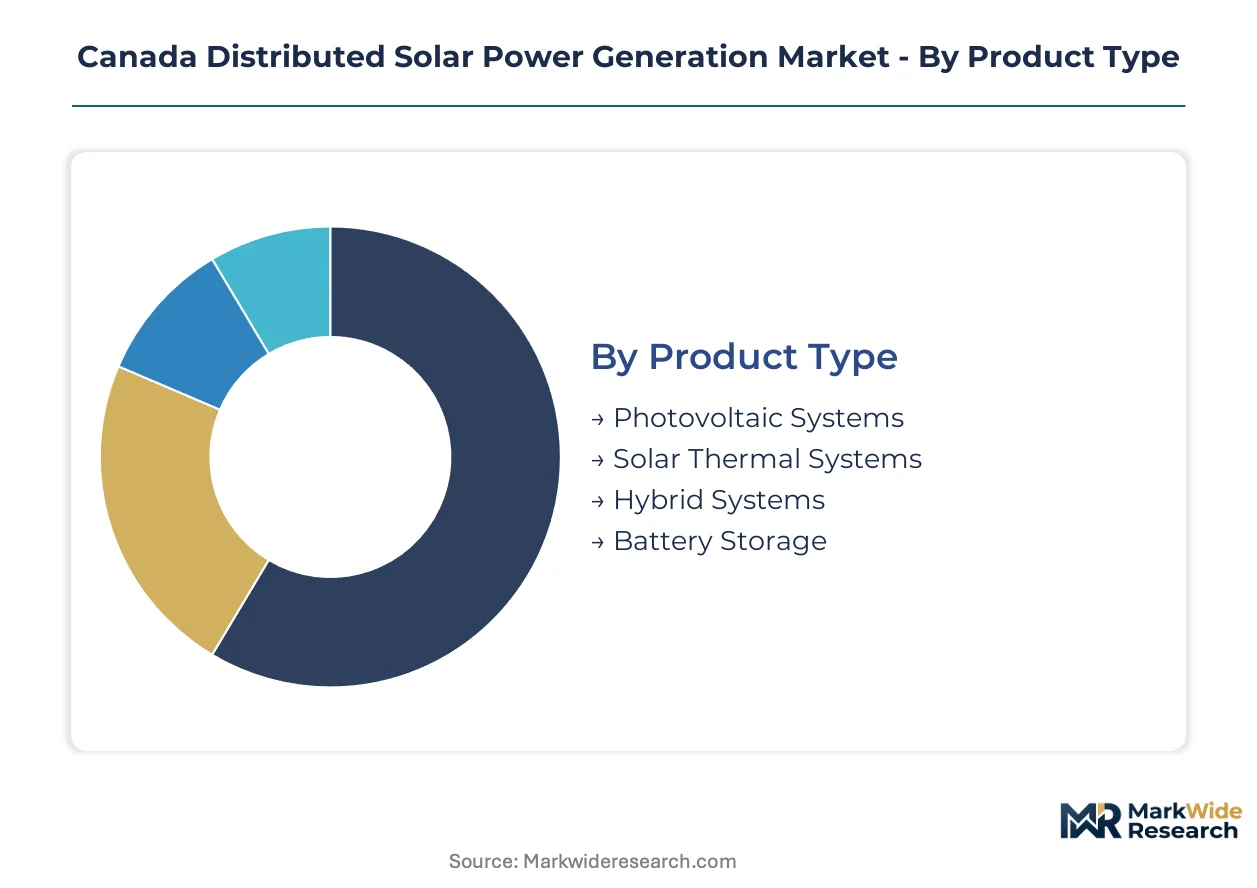
Segmentation in Canada's distributed solar market reveals how provincial regulations, load profiles, and capital constraints fragment procurement patterns across customer types and installation formats. Understanding these divides exposes where battery attachments command premium pricing and where agricultural ground-mounts bypass interconnection bottlenecks.
Product Type:
Cost tier determines attachment rates for storage and thermal components, with premium configurations concentrating where time-of-use spreads justify capital stacking.
- Photovoltaic Systems:Crystalline silicon modules dominate DC-to-AC conversion at 19-22% efficiency under standard test conditions. Ontario commercial buildings and Alberta farm operations anchor procurement volumes, driven by net-metering frameworks and carbon-offset registry eligibility.
- Battery Storage:Lithium-ion pack attachments are climbing fastest as provincial time-of-use spreads widen and peak-demand charges escalate for mid-market commercial hosts. Falling cell costs compress payback periods below five years in Ontario's manufacturing corridor.
- Solar Thermal Systems:Flat-plate and evacuated-tube collectors serve water heating loads in multi-unit residential buildings across British Columbia and Quebec.
- Hybrid Systems:Combined photovoltaic-thermal configurations capture rejected heat for process applications in Prairie agricultural facilities.
Photovoltaic systems command the established base. The steepest expansion runs through battery storage.
Technology:
Application-specific performance requirements push bifacial and high-efficiency architectures into commercial portfolios while standard monocrystalline serves cost-sensitive residential channels.
- Crystalline Silicon:Monocrystalline and polycrystalline cells anchor module supply through established domestic assembly footprints. Ontario's commercial building sector sources heavily from provincial distributors seeking supply security.
- Bifacial:Dual-glass construction captures reflected irradiance from snow-covered ground surfaces, delivering yield premiums exceeding monofacial baselines during Alberta winter months.
- Thin-Film:Cadmium-telluride and amorphous silicon configurations occupy niche building-integrated applications where weight constraints dominate.
- Concentrated Solar Power:Parabolic trough and dish-Stirling systems remain marginal in distributed applications due to tracking complexity and maintenance requirements.
Crystalline silicon retains volume leadership. Bifacial technology is gaining share fastest among agricultural ground-mount deployments.
End User:
Customer type shapes financing channel selection and ownership structure, with third-party leases penetrating residential segments while commercial buyers favor direct procurement.
- Commercial:Multi-site retail and logistics portfolios in Ontario's Greater Toronto Area drive standardized procurement through turnkey engineering-procurement-construction contracts. Corporate sustainability disclosures mandate production guarantees.
- Agricultural:Prairie grain-drying and irrigation loads justify ground-mounted arrays with surplus acreage deployment. Alberta operators leverage high-albedo soil conditions for bifacial yield optimization.
- Residential:Single-family rooftop installations concentrate in Ontario and British Columbia, constrained by certified installer scarcity in Atlantic Canada.
- Industrial:Manufacturing load centers face carbon-border adjustment exposure, accelerating on-site renewable procurement with battery attachments for peak shaving.
Commercial installations command the established base. The steepest expansion runs through agricultural electrification.
Installation Type:
Volume and interconnection complexity diverge sharply between urban rooftop saturation and rural ground-mount greenfield development.
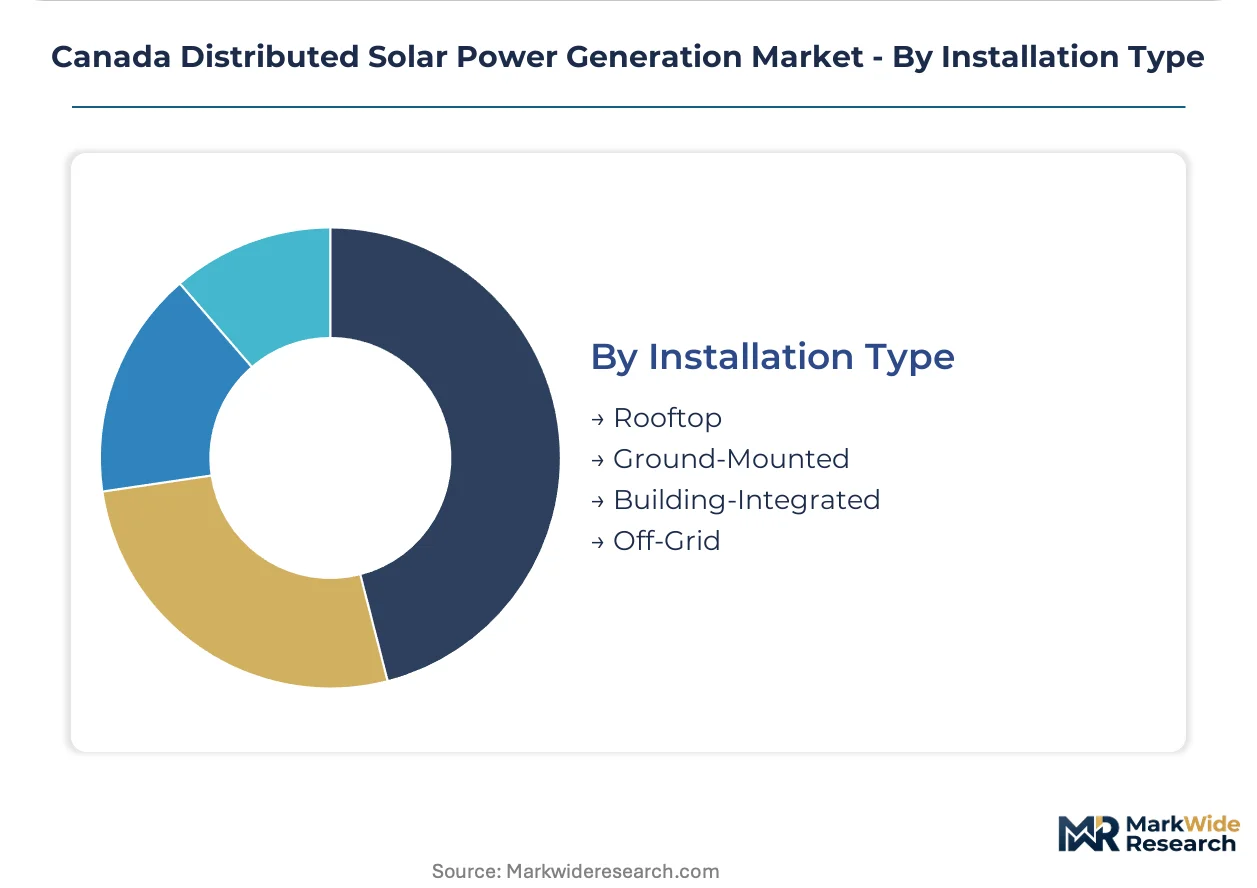
- Rooftop:Behind-the-meter deployment leads installation-type volumes in urban Ontario and Quebec, constrained by distribution utility protection-coordination studies for high-penetration feeders.
- Ground-Mounted:Agricultural surplus acreage in Alberta and Saskatchewan bypasses rooftop structural limitations and interconnection queue congestion. Agrivoltaic configurations with livestock grazing unlock conservation incentive stacking.
- Building-Integrated:Photovoltaic-embedded facades and skylights serve architectural mandates in Vancouver and Toronto commercial developments.
- Off-Grid:Remote mining camps and Indigenous communities in northern territories deploy diesel-hybrid systems with solar supplementation.
Rooftop deployment commands the established base. The steepest expansion runs through ground-mounted arrays.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Module assembly and inverter distribution concentrate in Ontario's manufacturing corridor, with cross-border supply chains feeding Prairie agricultural deployments and Pacific Coast commercial installations.
Ontario
Commercial building portfolios in the Greater Toronto Area drive standardized procurement through turnkey engineering contracts. The Ontario Energy Board's time-of-use rate structures create arbitrage value for battery-attached solar systems. Manufacturing load centers in Hamilton and Windsor face carbon-border adjustment exposure, accelerating on-site renewable procurement.
Alberta
Prairie grain-drying and irrigation loads justify ground-mounted arrays among farm operators with surplus acreage. The Alberta Utilities Commission maintains net-metering frameworks though interconnection queues now stretch 8-14 months. Calgary and Edmonton anchor commercial deployment, with rural municipalities adopting agrivoltaic configurations.
Quebec
Hydro-Québec rate hikes and carbon-accounting mandates now open mid-market building portfolios previously suppressed by low historical electricity rates. The Régie du bâtiment du Québec maintains distinct electrical code interpretations from Ontario. Montreal's commercial sector leads adoption, with multi-unit residential buildings in Quebec City adding solar thermal for water heating.
British Columbia
Distribution utilities require extensive protection-coordination studies for high-penetration solar feeders, extending commissioning timelines in Vancouver and Victoria. Cross-border shipments from Washington-based facilities sustain module supply. The province's building-integrated photovoltaic mandates drive architectural specifications in commercial developments.
Prairie Provinces
Saskatchewan agricultural operators with high-albedo soil conditions deploy bifacial modules for winter yield premiums. Manitoba's rural electrification programs supplement remote Indigenous community diesel systems with solar hybridization. Regional installer scarcity constrains deployment velocity outside Regina and Saskatoon.
Canada Distributed Solar Power Generation Market Competitive Environment
Vertically integrated manufacturers and specialized installation contractors split the market between upstream supply security and downstream customer acquisition control. Tier-one module producers anchor procurement contracts with provincial distributors, while regional installers dominate lease and power-purchase agreement channels. Strategic moves concentrate on cross-border supply chain optimization and turnkey performance guarantees for commercial portfolios.
Among domestic-anchored players, Canadian Solar Inc. and Silfab Solar Inc. represent integrated manufacturing archetypes with cell assembly footprints serving central Canada procurement. Grasshopper Solar Corporation occupies the residential lease channel position, controlling customer acquisition in Ontario's dense urban markets. These three entities exemplify the strategic divergence between upstream supply security and downstream financing innovation.
| Leading Market Players |
|---|
| LONGi Green Energy Technology Co., Ltd. |
| Grasshopper Solar Corporation |
| Canadian Solar Inc. |
| Silfab Solar Inc. |
| Heliene Inc. |
| EDF Renewables Canada Inc. |
| Polaron Solartech Corp |
| SolarEdge Technologies Inc. |
| Brookfield Renewable Partners L.P. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese polysilicon smelters compresses module input costs while simultaneously eroding pricing power for Canadian distributors serving Ontario's commercial building sector. This utilization dynamic forces domestic installers to absorb margin compression or accelerate battery attachment sales to preserve project economics.
Pricing Analysis
The federal Clean Electricity Regulations dictate the pricing tier structure across residential, commercial, and agricultural installation segments. Three-tier pricing structure across premium, standard, and economy levels separates turnkey engineering-procurement-construction bundles from component-only sales and self-managed procurement. Price differentiation hinges on certification grade—Canadian Standards Association licensed installations command premiums—and volume scale for multi-site retail portfolios. Cost compression in standard-tier crystalline silicon modules is intensifying because upstream metallurgical-grade silicon spot prices remain volatile. Agricultural operators in Alberta exhibit highest price sensitivity due to seasonal cash flow constraints, while Ontario manufacturing load centers prioritize performance guarantees over upfront cost.
Supply Chain Analysis
Extended payment terms from tier-one cell manufacturers now stretch 90-120 days for Canadian distributors, straining working capital for mid-scale installation contractors. Module assembly concentrates in China, Malaysia, and Vietnam, with cross-border shipments from Washington-based facilities sustaining British Columbia and Alberta demand. Raw material dependencies span metallurgical-grade silicon, silver paste metallization, and ethylene-vinyl acetate encapsulant films. Single-source vulnerability in Chinese polysilicon purification capacity threatens supply continuity during trade policy shifts. Distribution runs through provincial distributor networks anchored in Toronto and Calgary, with rural Prairie markets underserved by certified logistics infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's distributed solar market sits in early-cycle expansion, with the federal Clean Electricity Regulations creating structural tailwinds that accelerate behind-the-meter adoption across provincial net-metering frameworks.
For Market Incumbents: Insulate margin structures by deepening backward integration into battery storage distribution and securing exclusive procurement contracts with Ontario's manufacturing corridor. The threat of interconnection queue congestion at the Alberta Utilities Commission demands preemptive capacity reservation. Channel control through certified installer training programs defends customer acquisition costs against emerging lease-channel competitors. For New Entrants and Emerging Players: Atlantic Canada's installer scarcity and underserved rural electrification programs represent immediate white-space targets. Quebec's mid-market commercial building portfolios, recently activated by Hydro-Québec rate hikes, offer the most penetrable segment for standardized solar-thermal hybrid offerings. A power-purchase agreement go-to-market angle bypasses upfront capital barriers for agricultural operators with constrained balance sheets. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among third-party ownership providers with lease and power-purchase agreement books. Long-term viability across the analysis window favors acquisition targets with integrated engineering-procurement-construction capabilities and performance-guarantee track records. The signal to monitor is Alberta Utilities Commission processing timeline compression, which would unlock frozen capital deployment and revalue installation pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Storage | Captures margin pool from lithium-ion attachment growth in Ontario's time-of-use arbitrage segment. |
| Agrivoltaic Configuration Development | Unlocks provincial conservation incentive stacking for Alberta agricultural operators with surplus acreage. |
| Certified Installer Network Expansion | Addresses scarcity constraints in Atlantic Canada and rural Prairie markets outside Toronto and Calgary. |
| Turnkey Performance Guarantee Programs | Consolidates vendor relationships among multi-site retail portfolios seeking standardized sustainability disclosures. |
| Cross-Border Supply Chain Optimization | Reduces logistics friction for Washington-based module shipments into British Columbia and Alberta demand centers. |
Study Parameters
The analysis maps photovoltaic systems, battery storage attachments, solar thermal configurations, and hybrid energy systems, each validated through utility planning officers, engineering-procurement-construction contractors, provincial regulator staff, and agricultural load center operators. Primary fieldwork combined structured interviews with secondary validation against EIA data, IEA distributed generation reports, FERC interconnection filings, and provincial net-metering registry disclosures. Bottom-up project pipeline aggregation triangulated against top-down addressable market sizing across the analysis window.
Assumptions held fixed include current federal Clean Electricity Regulations emissions-intensity thresholds and existing provincial net-metering caps; varied assumptions included interconnection queue processing timelines and lithium-ion cell cost trajectories. The forecast framework segmented by product type, technology architecture, end-user category, and installation format, with CAGRs derived from regression against historical deployment velocity and policy implementation schedules. Key inputs incorporated time-of-use rate spread projections and carbon-offset registry eligibility rules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated Chinese module manufacturers would shift outcomes through pricing disruption. Macroeconomic deviation in interest rate environments, regulatory acceleration of natural gas retirement timelines, or technological breakthrough in perovskite cell commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
United States Distributed Solar Power Generation Market
Solar Power Systems
Box Solar Cookers Market
Solar Power Systems
PV Array Combiner Box Sales Market
Solar Power Systems
Solar Thermal Market
Solar Power Systems
Asia-Pacific Solar Concentrator Market
Solar Power Systems
Concentrated Photovoltaic System Market
Solar Power Systems
Bulgaria Solar Energy Market
Solar Power Systems
Australia Solar Power Market
Solar Power Systems
Slovakia Renewable Energy Market
Solar Power Systems
Europe Solar Microinverter Market
Solar Power Systems
Solar PV Tracker Market
Solar Power Systems
Thin Film Solar PV Market
Solar Power Systems
Building Applied Photovoltaics (BAPV) Market
Solar Power Systems
Europe Solar Blanket Market
Solar Power Systems
Solar Power Tracker Market
Solar Power Systems
Off-Grid Solar Generator Market