
 North America Electric Vehicle Battery Manufacturing Market | 2026-2036
North America Electric Vehicle Battery Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
North America Electric Vehicle Battery Manufacturing Market Insights
Solid-state and silicon-anode chemistries are rewriting cell architecture roadmaps across the region. LG Energy Solution leverages its joint venture structure with Detroit automakers to anchor large-format cylindrical cell output in Ohio. SK On competes through aggressive capacity builds in Georgia, while Panasonic Energy sustains its technology leadership through high-nickel cathode partnerships with Tesla in Nevada.
North America Electric Vehicle Battery Manufacturing encompasses the industrial production of electrochemical energy storage systems using lithium-ion, solid-state, or alternative chemistries, typically achieving energy densities above 250 Wh/kg for automotive-grade cells through electrode coating, formation cycling, and module assembly processes. These systems power traction motors in battery electric and plug-in hybrid vehicles while supplying grid stabilization services. Cell and pack segments dominate current revenue pools, with solid-state technology representing the fastest-growing category as manufacturers resolve electrolyte interface challenges. OEM Manufacturers constitute the primary end-user channel, though Utility Companies are emerging as a distinct demand vertical through stationary storage offtake agreements tied to renewable intermittency.
The Inflation Reduction Act, EPA tailpipe standards, and NHTSA fuel economy regulations collectively mandate domestic battery sourcing thresholds that reshape procurement geography and cathode precursor supply decisions. OSHA and ISO 14001 compliance requirements add incremental certification burdens for new entrants establishing US-based formation and dry room operations. Stakeholders must monitor how Treasury Department guidance on foreign entity of concern rules affects joint venture equity structures and technology licensing terms.
Market Dynamics
The Inflation Reduction Act's domestic content thresholds are forcing cathode precursor production to relocate from East Asian refineries to US-based chemical processing corridors, compressing established supply relationships while creating captive demand for North American lithium conversion capacity.
Growth Catalysts
- IRA Domestic Content Bonuses:The Inflation Reduction Act's tax credit thresholds for North American battery assembly are redirecting Korean and Japanese cell makers toward joint ventures with Detroit automakers in Ohio, Georgia, and Tennessee.
- Silicon-Anode Commercialization:Silicon nanowire anode technologies are reaching automotive qualification standards, enabling 20-40% energy density improvements that extend electric vehicle range without pack size expansion.
- Midwest Gigafactory Clustering:Michigan, Ohio, and Indiana are concentrating cathode active material plants, cell formation facilities, and module assembly within 300-mile logistics corridors that minimize inbound transport costs.
Market Restraints
- Lithium Hydroxide Supply Concentration:Chilean and Australian spodumene concentrate currently feeds 90% of North American chemical conversion, exposing cell makers to shipping bottlenecks and DDP pricing volatility at US ports.
- Dry Room Infrastructure Scarcity:Ultra-low humidity manufacturing environments require 18-24 month construction timelines and specialized HVAC contractors, delaying capacity ramps even where capital is committed.
- Nickel Sulfate Processing Gap:The absence of Class 1 nickel refining capacity in North America forces reliance on Indonesian and Russian intermediate products that face foreign entity scrutiny under Treasury Department guidance.
Strategic Opportunities
- Quebec Lithium Corridor:Canada's James Bay region hosts hard rock spodumene deposits with rail access to US Midwest processing plants, offering IRA-compliant critical mineral sourcing outside traditional South American supply chains.
- Grid-Scale Stationary Storage:Utility offtake agreements for battery energy storage systems are creating secondary demand channels for cells that fail automotive grade specifications, improving manufacturing yield economics.
- Solid-State Electrolyte Licensing:Sulfide and oxide solid-state technologies are approaching pilot production, enabling IP holders to capture value through technology licensing rather than capital-intensive manufacturing scale-up.
Industry Challenges
- Electrolyte Formulation Talent Gap:North American universities produce fewer than 200 doctoral graduates annually in electrochemical engineering, forcing cell makers to recruit from Korean and Chinese competitors at premium compensation.
- Formation Cycling Bottlenecks:Initial charge-discharge cycles require 14-21 days of controlled aging, creating work-in-process inventory piles that consume 30-40% of factory floor space and constrain throughput.
- OSHA Combustible Dust Compliance:Cathode powder handling facilities must implement NFPA 654 explosion protection systems that add 8-12 months to facility commissioning and require specialized safety engineering contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Electric Vehicle Battery Manufacturing Market |
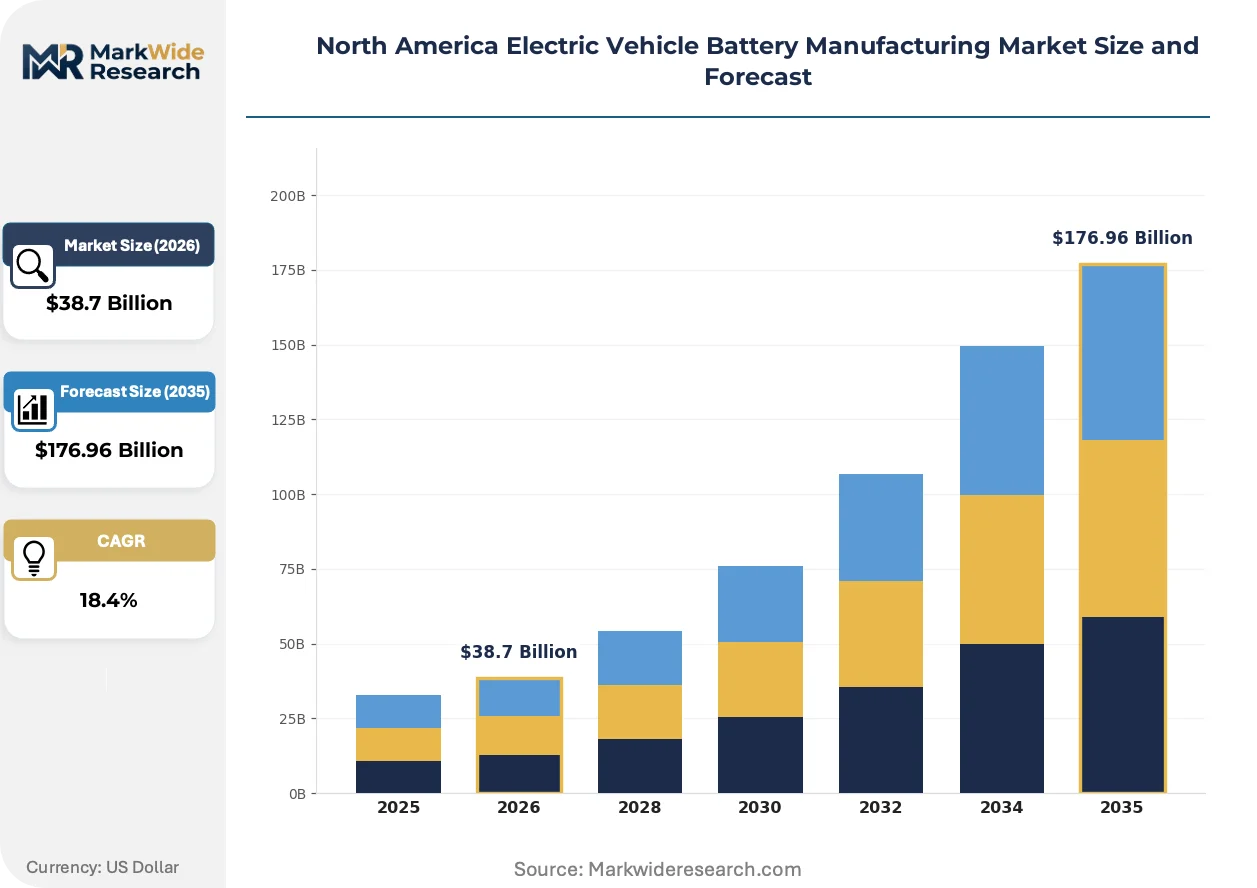
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $176.96 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Lithium-ion, Nickel-Metal Hydride, Solid-State, Lead-Acid End User: OEM Manufacturers, Aftermarket Providers, Fleet Operators, Utility Companies Product Type: Cell, Module, Pack, Battery Management System Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Energy Storage Systems |
| Companies Covered | LG Energy Solution, Panasonic Energy, SK On, Samsung SDI, Envision AESC, Ultium Cells, A123 Systems, East Penn Manufacturing, EnerSys, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Electric Vehicle Battery Manufacturing Market Trends and Innovations
Cell architecture roadmaps are diverging from cylindrical formats toward prismatic and blade-style designs that optimize pack-level volumetric efficiency while simplifying thermal management integration with vehicle platforms.
Silicon-anode chemistries are rendering obsolete graphite-dominant electrode formulations in premium electric vehicle segments. SK On and LG Energy Solution have accelerated automotive qualification timelines for silicon oxide blends to 18-month cycles. The technology is rendering obsolete range anxiety as a purchase barrier among luxury SUV buyers in California and Texas.
The EPA's tightened tailpipe standards through 2032 are mandating battery electric vehicle sales thresholds that exceed current domestic cell capacity by 40-60 gigawatt-hours annually. Automakers are responding by pre-paying for dedicated production lines at joint venture facilities. Light-duty truck platforms face the steepest compliance penalties, accelerating cell offtake negotiations for Detroit's full-size electric pickup programs.
Fleet procurement departments are consolidating battery sourcing decisions at the holding-company level rather than delegating to individual brand purchasing teams. Rental car aggregators and commercial leasing subsidiaries now negotiate directly with cell makers for multi-year supply agreements. This concentration is most visible in corporate fleet electrification programs across Texas and California, where procurement volume thresholds exceed 10,000 vehicles annually.
North America Electric Vehicle Battery Manufacturing Market Segmentation
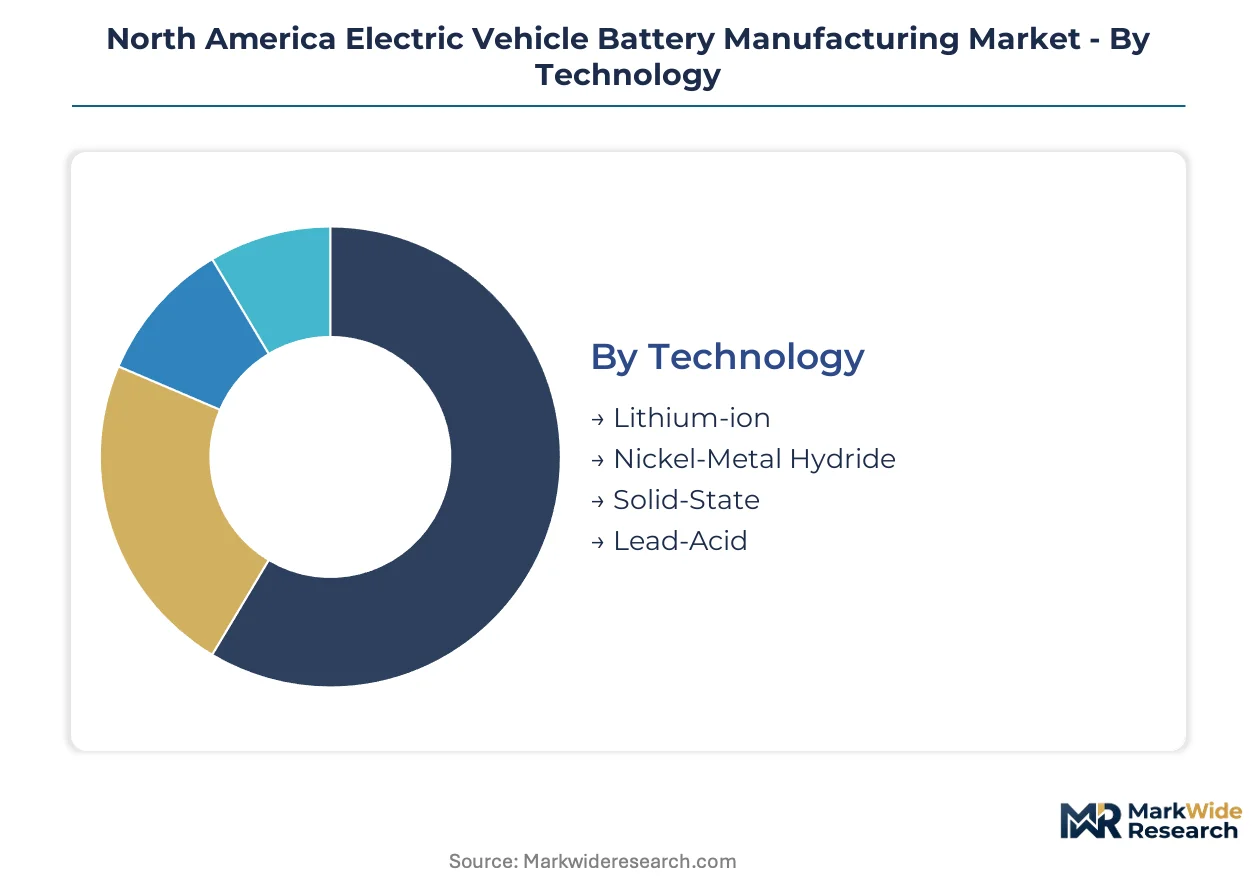
Technology roadmaps and procurement patterns diverge sharply across segment boundaries in North American battery manufacturing. Cell format decisions cascade through module design, pack integration, and end-use qualification timelines, creating distinct competitive arenas with unequal margin profiles.
Technology:
Cycle times separate these chemistries: lithium-ion cells qualify in 12-18 months while solid-state prototypes demand 36-48 months of validation before automotive release.
- Lithium-ion:NCM and LFP cathode formulations dominate current output, with high-nickel variants exceeding 300 Wh/kg for premium electric SUVs. Michigan and Ohio gigafactories concentrate cylindrical and prismatic output for Detroit automaker platforms.
- Solid-State:Sulfide electrolyte interfaces remain the critical barrier, though pilot lines in Nevada and California are resolving dendrite suppression at scale. The technology commands qualification timelines three times longer than conventional liquid electrolyte systems.
- Nickel-Metal Hydride:Toyota's hybrid programs in Kentucky sustain residual demand for this mature chemistry in mild-hybrid applications where energy density requirements remain modest.
- Lead-Acid:Starter-lighting-ignition functions in commercial truck platforms preserve this segment despite lithium substitution in traction applications.
Lithium-ion dominates installed base. Solid-state is where expansion concentrates.
End User:
Procurement scale and contract duration vary dramatically: OEM Manufacturers commit to 5-7 year offtake agreements while Fleet Operators negotiate annual volume pools with price reopener clauses.
- OEM Manufacturers:Ford, General Motors, and Tesla anchor demand through joint venture structures that embed cell makers within dedicated supply corridors. These partnerships specify cathode chemistry, cell format, and module architecture three model years ahead of production.
- Utility Companies:Grid-scale storage procurement is climbing the fastest, with ERCOT and CAISO interconnection queues driving 4-hour duration battery energy storage system deployments across Texas and California renewable zones.
- Fleet Operators:Rental car aggregators and commercial leasing subsidiaries now consolidate purchasing at holding-company level, negotiating direct supply agreements that bypass traditional OEM distribution channels.
- Aftermarket Providers:Independent repair networks and remanufacturing specialists service out-of-warranty hybrid vehicles, though lithium-ion pack replacement economics favor dealer channel capture.
OEM Manufacturers command volume concentration. Utility Companies are gaining share fastest.
Product Type:
Margin architecture inverts through the value chain: cells capture 60-70% of pack-level material cost while battery management systems extract software-recurring revenue streams.
- Cell:Electrode coating, calendering, and formation cycling constitute the most capital-intensive manufacturing stage, with dry room infrastructure consuming 40% of facility construction budgets.
- Pack:Thermal management integration and vehicle platform interface engineering determine pack-level performance, with structural battery designs eliminating module intermediaries in Tesla's 4680 architecture.
- Module:Cell-to-module assembly with voltage and temperature monitoring creates intermediate work-in-process inventory that constrains throughput in just-in-sequence automotive supply chains.
- Battery Management System:Firmware-controlled cell balancing and state-of-charge algorithms differentiate pack performance, enabling over-the-air updates that extend operational life.
Cell production anchors capacity investment. Pack integration is where value capture concentrates.
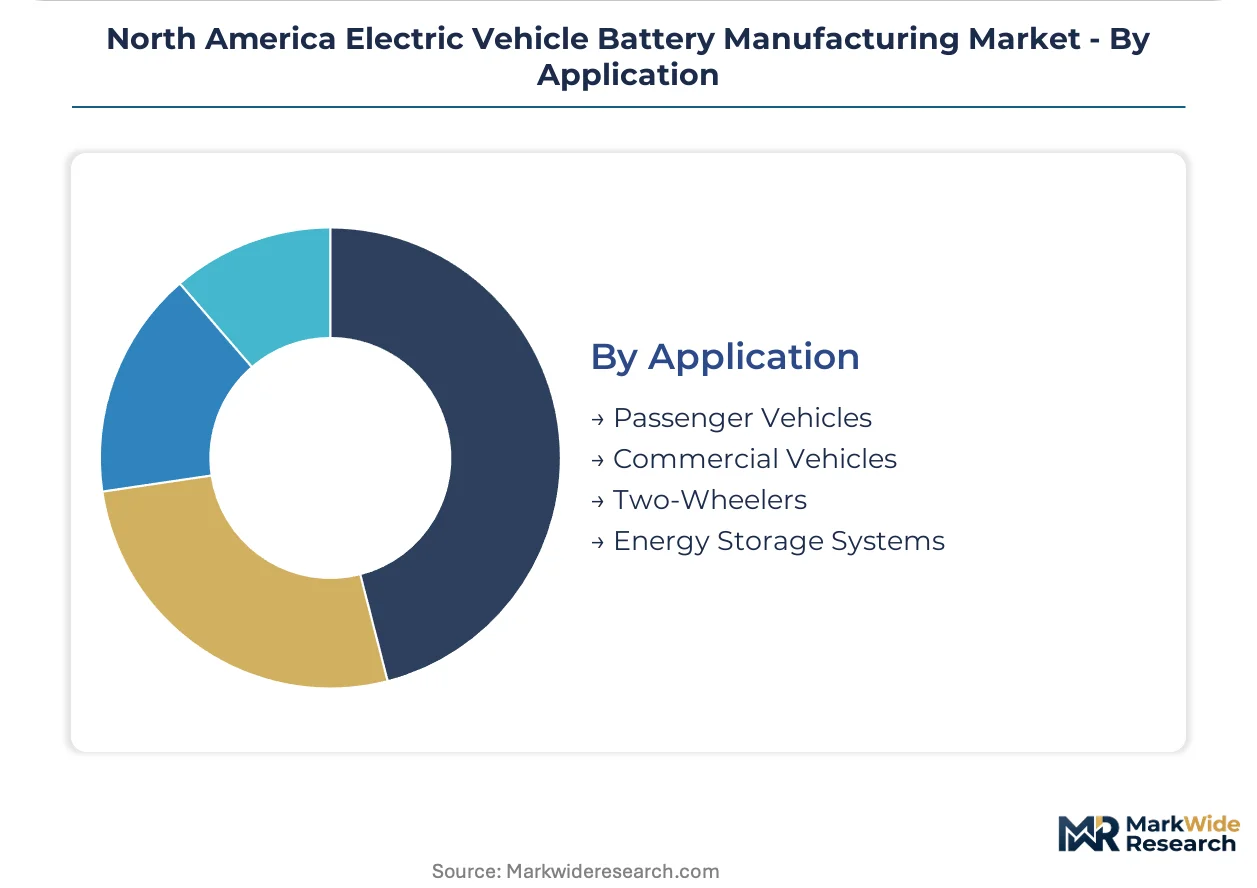
Application:
Regulatory pressure intensity varies by vehicle class: EPA tailpipe standards impose steeper compliance penalties on light-duty trucks than passenger sedans, accelerating cell offtake for electric pickup programs.
- Passenger Vehicles:Compact and mid-size electric sedans absorb the highest cell volumes, with California and Texas markets driving premium SUV demand where silicon-anode chemistries extend range.
- Commercial Vehicles:Class 8 electric trucks and delivery vans face payload constraints that favor high-energy-density cells, though charging infrastructure gaps limit depot-based fleet electrification outside urban corridors.
- Energy Storage Systems:Utility-scale deployments create secondary demand channels for cells that fail automotive grade specifications, improving manufacturing yield economics through alternative revenue streams.
- Two-Wheelers:Electric motorcycles and scooters represent a marginal addressable market in North America compared to Asia-Pacific, with niche demand concentrated in California urban mobility programs.
Passenger Vehicles dominate cell consumption. Energy Storage Systems are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and utility procurement departments drive demand concentration across North American battery manufacturing corridors. The Inflation Reduction Act's domestic content thresholds reshape investment geography toward US-based cell production. Canadian critical mineral deposits and Mexican component assembly create integrated supply networks spanning national boundaries.
United States
Michigan and Ohio host expanding gigafactory clusters serving Detroit automaker EV platforms. The Inflation Reduction Act's tax credit thresholds redirect Korean and Japanese cell makers toward joint ventures in the Midwest and Southeast. Tennessee's corridor concentrates cathode active material plants with rail links to lithium conversion facilities.
Canada
Quebec's James Bay region supplies hard rock spodumene deposits with rail access to US Midwest processing infrastructure. The country's critical mineral strategy aligns with IRA-compliant sourcing requirements for North American battery supply chains. Ontario's manufacturing base integrates module assembly with cross-border automotive just-in-sequence delivery.
Mexico
Northern border states concentrate electrode component and module assembly operations serving US gigafactory demand. The country's manufacturing incentives attract Korean suppliers establishing precursor chemical processing near Texas and Arizona corridors. Baja California hosts cathode powder handling facilities with OSHA-equivalent safety certifications for cross-border supply.
North America Electric Vehicle Battery Manufacturing Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions in North American battery manufacturing. Korean and Japanese cell makers dominate through joint venture structures with Detroit automakers, while domestic specialists capture niche module and pack integration roles. Strategic archetypes separate scale-driven cylindrical cell producers from prismatic format specialists and solid-state technology licensors. Competitive moves concentrate on capacity pre-commitments through multi-year offtake agreements and backward integration into cathode precursor production.
Among Korean-based cell manufacturers, LG Energy Solution and SK On anchor the joint venture tier through partnerships with US automakers in Ohio and Georgia. Panasonic Energy occupies a position exemplifying technology-led supply relationships with premium EV platforms in Nevada. These three companies represent distinct competitive archetypes: LG Energy Solution through multi-OEM partnership structures, SK On via aggressive capacity scaling in Southeastern corridors, and Panasonic Energy through high-nickel cathode co-development models.
| Leading Market Players |
|---|
| LG Energy Solution |
| Panasonic Energy |
| SK On |
| Samsung SDI |
| Envision AESC |
| Ultium Cells |
| A123 Systems |
| East Penn Manufacturing |
| EnerSys |
| Others |
Pricing and Supply Chain Analysis
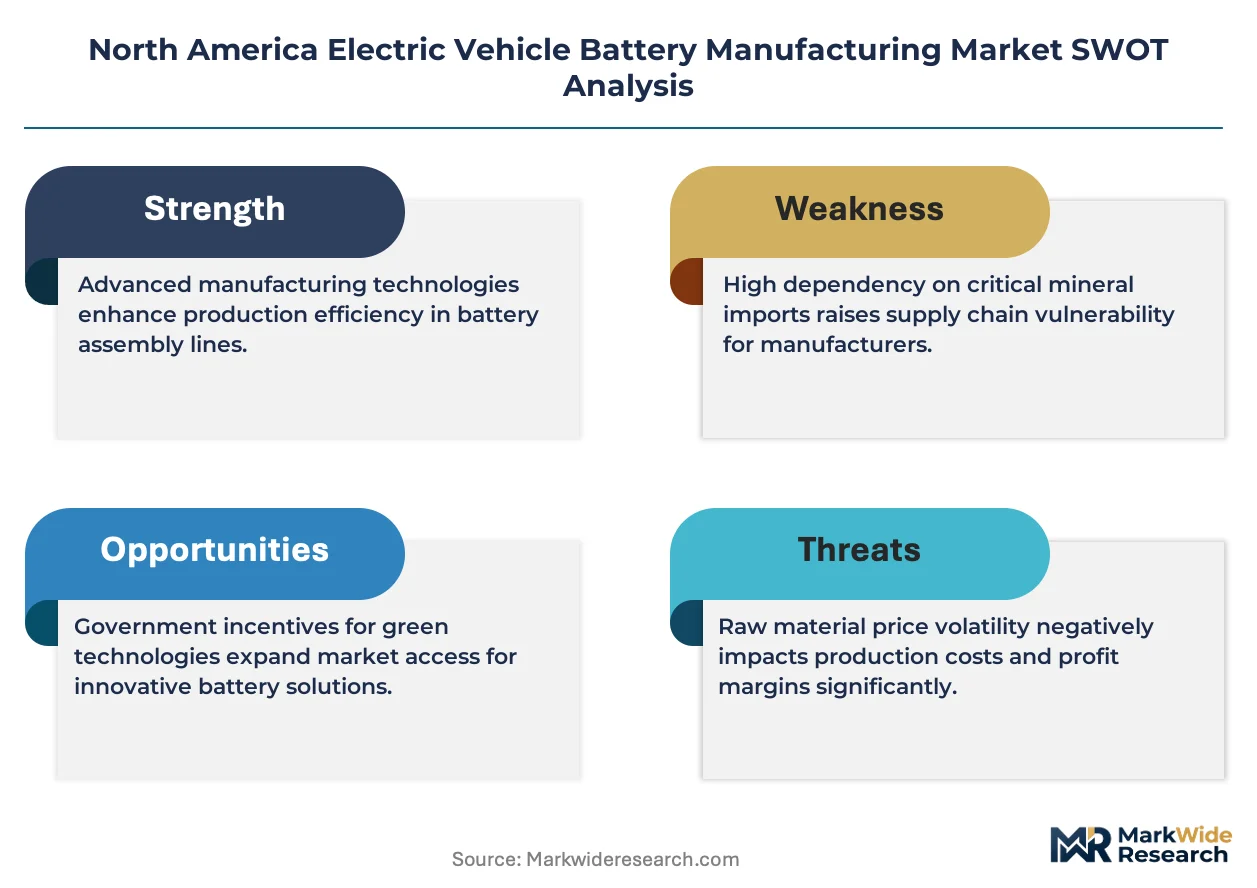
Chilean and Australian spodumene concentrate dominance feeds 90% of North American lithium hydroxide conversion, anchoring margin pools in cathode active material processing rather than raw extraction. Cell makers absorb DDP pricing volatility at US ports while joint venture structures with Detroit automakers lock in long-term offtake premiums.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate cathode precursor procurement, transferring commodity volatility to automaker balance sheets. Price differentiation rests on IRA domestic content compliance tiers and silicon-anode energy density grades. Cost compression in LFP cells is intensifying as Chinese capacity spills into non-automotive storage markets. Fleet operators exhibit the highest price sensitivity, while premium SUV platforms absorb nickel-rich cathode premiums without volume pushback.
Supply Chain Analysis
Tariff exposure between Indonesia and the United States dominates nickel sulfate procurement risk as Treasury Department foreign entity scrutiny tightens. The supply chain draws from Chile, Australia, and Canada for lithium conversion; South Korea and Japan for cell manufacturing equipment; and the US Midwest for cathode active material plants. Single-source vulnerability concentrates in Class 1 nickel refining capacity. Distribution runs through rail-linked gigafactory corridors in Michigan, Ohio, and Tennessee with just-in-sequence module delivery to assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Electric Vehicle Battery Manufacturing Market is cycling through a capital-intensive buildout phase as IRA-compliant capacity ramps absorb three years of committed investment. Automaker pre-payment structures for dedicated production lines signal trough conditions transitioning toward utilization-driven margin recovery.
For Market Incumbents: Build captive cathode precursor capacity as the defensive moat against Korean and Japanese joint venture partners' backward integration moves. Secure Quebec lithium offtake with rail-served processing infrastructure to displace Chilean concentrate exposure. Preempt SK On and LG Energy Solution's upstream chemical investments by anchoring spodumene conversion in the US Midwest. IRA Treasury guidance on foreign entity rules is the regulatory threat requiring legal structure hedging. For New Entrants and Emerging Players: Solid-state electrolyte licensing to established cell makers represents the most penetrable entry point without capital-intensive dry room construction. Grid-scale stationary storage module assembly in Texas ERCOT zones bypasses automotive qualification barriers. Target utility procurement departments directly with 4-hour duration BESS configurations. Technology licensing agreements with sulfide electrolyte IP holders offer the cleanest go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across solid-state pilot production as equipment utilization improves and formation cycling bottlenecks resolve. Long-term viability favors technology licensors and cathode chemical processors over pure-play cell manufacturers facing Korean conglomerate scale advantages. Acquisition target archetypes include electrochemical engineering talent pools and Quebec lithium development stage assets. The signal to watch is Treasury Department guidance clarity on foreign entity of concern joint venture equity limits.| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Precursor Backward Integration | Captive nickel sulfate processing in Tennessee secures IRA compliance and displaces Indonesian import exposure. |
| Solid-State Electrolyte Licensing | Sulfide technology IP holders capture value without dry room capital intensity in Nevada pilot facilities. |
| Quebec Lithium Corridor Development | James Bay spodumene deposits with rail access to Midwest processing plants diversify Chilean concentrate dependence. |
| Utility BESS Direct Procurement | ERCOT and CAISO interconnection queues create secondary revenue channels for cells failing automotive grade specifications. |
| Silicon-Anode Automotive Qualification | SK On and LG Energy Solution accelerate 18-month qualification cycles to extend premium SUV range thresholds. |
Research Methodology
Desk research of SEC 10-K filings, EIA electricity market data, and IRA Treasury Department guidance documents preceded structured interviews with cathode plant engineering directors, OEM platform procurement managers, utility storage procurement leads, and dry room construction specialists. Primary fieldwork validated capacity ramp timelines and joint venture equity structures. Secondary sources included customs trade data for lithium concentrate flows, FERC interconnection queue filings, and IHS Markit vehicle production databases. Bottom-up cell capacity builds were triangulated against top-down automaker electrification commitments.
Assumptions held fixed include IRA domestic content bonus thresholds and EPA tailpipe standard stringency through the analysis window, while silicon-anode commercialization timelines and solid-state electrolyte interface resolution were varied across scenarios. Segmentation modeling incorporated technology chemistry, cell format architecture, end-user procurement channel, and regional production cluster dimensions. CAGRs were derived from installed capacity ramps weighted by formation cycling yield curves and cathode active material cost trajectories. Forecast inputs included lithium hydroxide spot price volatility bands and utility offtake agreement execution rates.
Macroeconomic conditions sit as an overlay; deviation in federal EV tax credit continuity or Class 1 nickel supply disruption would shift the trajectory. Forecasts reflect these assumptions without claiming predictive certainty. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
South America Electric Vehicle Battery Manufacturing Market
EV Batteries
Asia-Pacific Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
EV Battery Cells Market
EV Batteries
United States Electric Vehicle Battery Manufacturing Market
EV Batteries
Europe Electric Vehicle VRLA Batteries Market
EV Batteries
Spain Rechargeable Battery Market
EV Batteries
Auto Storage Battery Market
EV Batteries
ASEAN Countries Electric Vehicle Battery Manufacturing Market
EV Batteries
Europe Electric Vehicle Battery Manufacturing Market
EV Batteries
Europe Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Electric Vehicle Battery Coolant Market
EV Batteries
Curved Lipo Battery Market
EV Batteries
Japan EV Battery Pack Market
EV Batteries
Electric Vehicle Traction Batteries Market
EV Batteries
China EV Battery Pack Market
EV Batteries
US EV Battery Pack Market