
 Chad Oil and Gas Upstream Market | 2026-2036
Chad Oil and Gas Upstream Market Size, Share, and Industry Trends Forecast 2026-2036
Chad Oil and Gas Upstream Market Outlook
Chad's southern oilfields is tilting investment toward enhanced recovery and incremental drilling programs. Exxon Mobil Corporation leverages its historical Doba Basin position and infrastructure control to sustain operational continuity. China National Petroleum Corporation anchors its presence through the Chad-Cameroon pipeline system and integrated field development. TotalEnergies competes by specializing in deepwater exploration technologies applicable to Chad's underexplored sedimentary basins.
Chad Oil and Gas Upstream encompasses crude petroleum extraction, reservoir pressure maintenance, and wellhead processing operations typically yielding API gravity ranges between 20 and 35 degrees with associated natural gas handling. The primary commercial purpose centers on feedstock supply to export pipelines and domestic thermal power stations. Production services within the Service Type dimension carry the heaviest capital burden as operators prioritize workover rigs and artificial lift systems over greenfield exploration. The End User category shows National Oil Companies consolidating operational control while Joint Ventures face heightened scrutiny over cost recovery mechanisms.
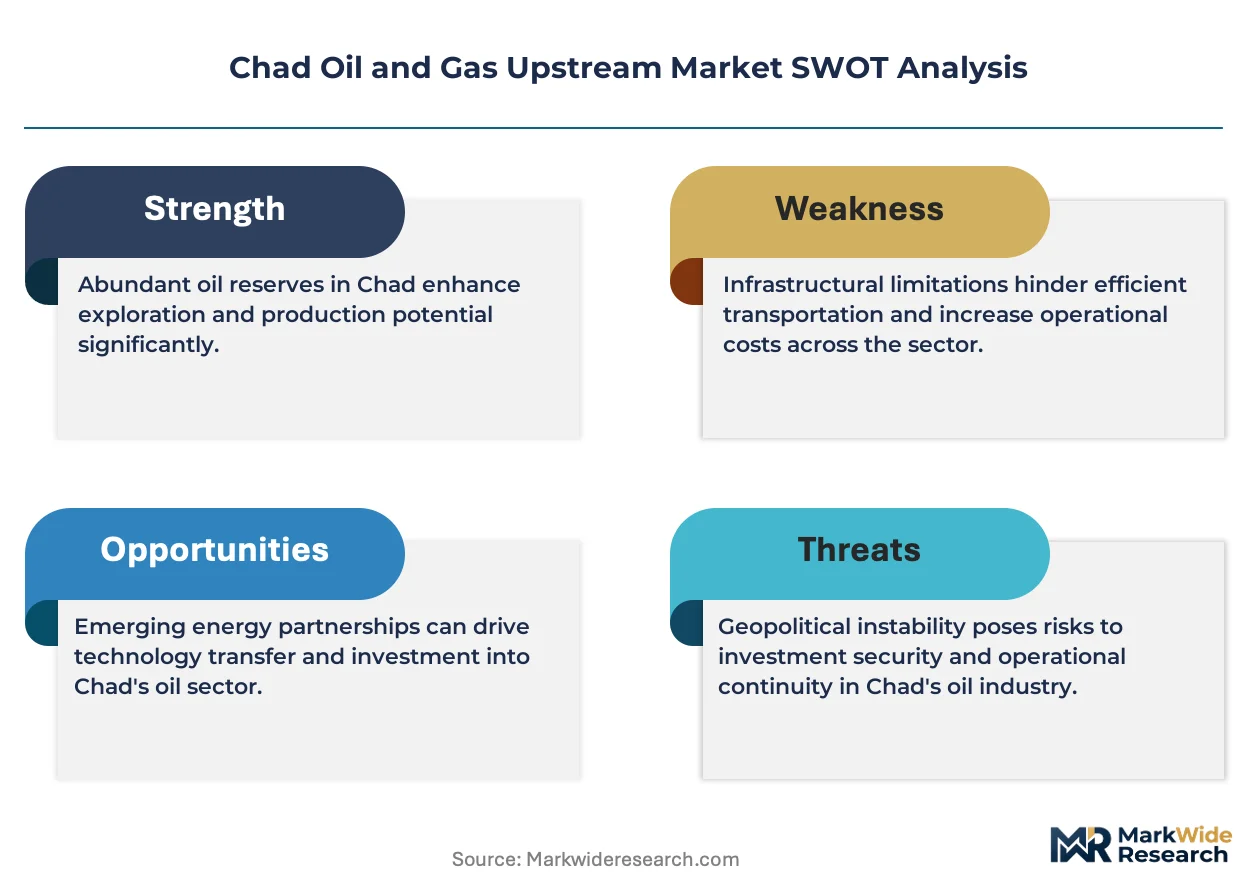
Chad's Ministry of Petroleum and Energy enforces production sharing contract terms that dictate cost recovery ceilings and state participation thresholds. The country's national petroleum regulator mandates environmental impact assessments aligned with regional basin management protocols. These frameworks shape contractor eligibility and equipment sourcing requirements. Stakeholders must monitor fiscal term renegotiations and local content enforcement intensity as determinants of project economics.
Market Dynamics
Chad's Ministry of Petroleum and Energy is tightening local content mandates that force contractors to source equipment and labor domestically, fundamentally altering procurement economics for international operators in the Doba Basin corridor.
Growth Catalysts
- Domestic electrification mandates:Chad's national power utility is expanding thermal generation capacity, creating guaranteed offtake for associated gas and heavier crude grades that previously lacked market outlets.
- Enhanced oil recovery techniques:Waterflooding and gas injection programs are unlocking stranded reserves in mature Doba Basin fields, extending productive life without new exploration capex.
- Chad-Cameroon pipeline infrastructure:The 1,070-kilometer export system operated by COTCO provides dedicated throughput capacity to Atlantic terminals, de-risking production commitments for field developers.
Market Restraints
- Capital equipment import dependence:Workover rigs and subsea processing hardware must transit through Douala or Pointe-Noire, exposing projects to port congestion and currency volatility in the Central African franc zone.
- Basin geology limitations:Chad's proven reservoirs exhibit high wax content and low permeability in certain horizons, constraining flow rates and complicating artificial lift selection.
- Fiscal term uncertainty:Production sharing contract renegotiations triggered by the 2023 Hydrocarbons Code amendments have frozen final investment decisions on marginal field developments.
Strategic Opportunities
- Underexplored northern basins:The Erdis and Bongor graben systems contain sedimentary sequences analogous to productive Sudanese structures, offering wildcat potential beyond the mature southern corridor.
- Gas-to-power integration:Chad's national petroleum regulator is fast-tracking permits for captive power plants at field sites, enabling operators to monetize flared gas through direct electricity sales to mining concessions.
- Digital twin deployment:Reservoir simulation and predictive maintenance platforms are converging with satellite connectivity improvements, allowing remote monitoring of wellhead facilities across Chad's dispersed southern fields.
Industry Challenges
- Petroleum engineering talent scarcity:Chad's technical universities produce fewer than fifty petroleum engineering graduates annually, forcing operators to rely on expatriate specialists for reservoir management and drilling supervision.
- Legacy well integrity management:Decades-old wellbores installed during initial Doba Basin development require continuous monitoring and recompletion, diverting capital from new drilling programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chad Oil and Gas Upstream Market |
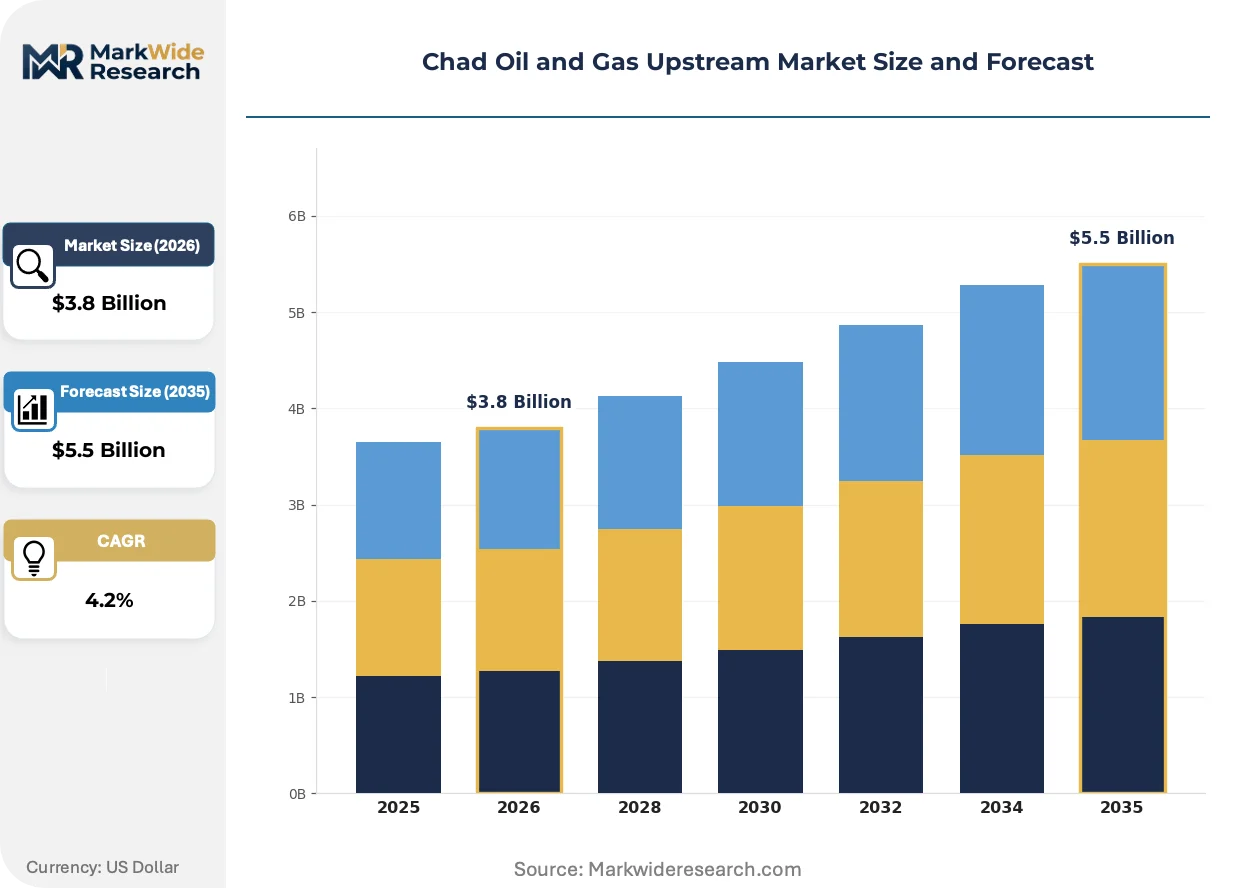
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Drilling, Exploration, Production, Reservoir Management Service Type: Exploration Services, Production Services, Maintenance Services, Consulting Services End User: National Oil Companies, Independent Operators, Service Contractors, Joint Ventures Offering: Software Solutions, Equipment Rentals, Environmental Services, Training Programs |
| Companies Covered | Glencore PLC, Delonex Energy Limited, Exxon Mobil Corporation, Société des Hydrocarbures du Tchad, China National Petroleum Corporation, TotalEnergies, PetroChad, Addax Petroleum, Perenco, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chad Oil and Gas Upstream Market Strategic Shifts
Digitalization and environmental compliance are compressing operational timelines in Chad's upstream sector, with operators adopting remote monitoring and emissions tracking systems to satisfy tightening regulatory frameworks and reduce field personnel exposure.
Electrical submersible pumps with variable frequency drives are rendering obsolete conventional beam-pump installations in Chad's marginal wells. Field operators in the Doba Basin corridor are retrofitting existing wellheads with ESP systems to handle high-viscosity crude and extend economic production limits. The shift is compressing artificial lift maintenance cycles from quarterly to annual interventions, reducing helicopter logistics costs for remote pad locations.
Chad's 2023 Hydrocarbons Code amendments impose stricter environmental impact assessment protocols aligned with regional basin management frameworks. The national petroleum regulator now requires real-time methane monitoring and flare minimization plans as conditions for production license renewal. International joint ventures are responding by deploying portable gas capture units and re-injecting associated gas into depleted reservoirs rather than venting to atmosphere.
Integrated service contracts are displacing discrete procurement of drilling, completion, and production services in Chad's upstream market. National oil companies and their joint venture partners are consolidating vendor relationships under single-point accountability structures that bundle equipment, labor, and maintenance. This consolidation is most visible in the southern Doba Basin, where COTCO pipeline commitments favor operators with guaranteed throughput backed by integrated service guarantees.
Chad Oil and Gas Upstream Market Segmentation
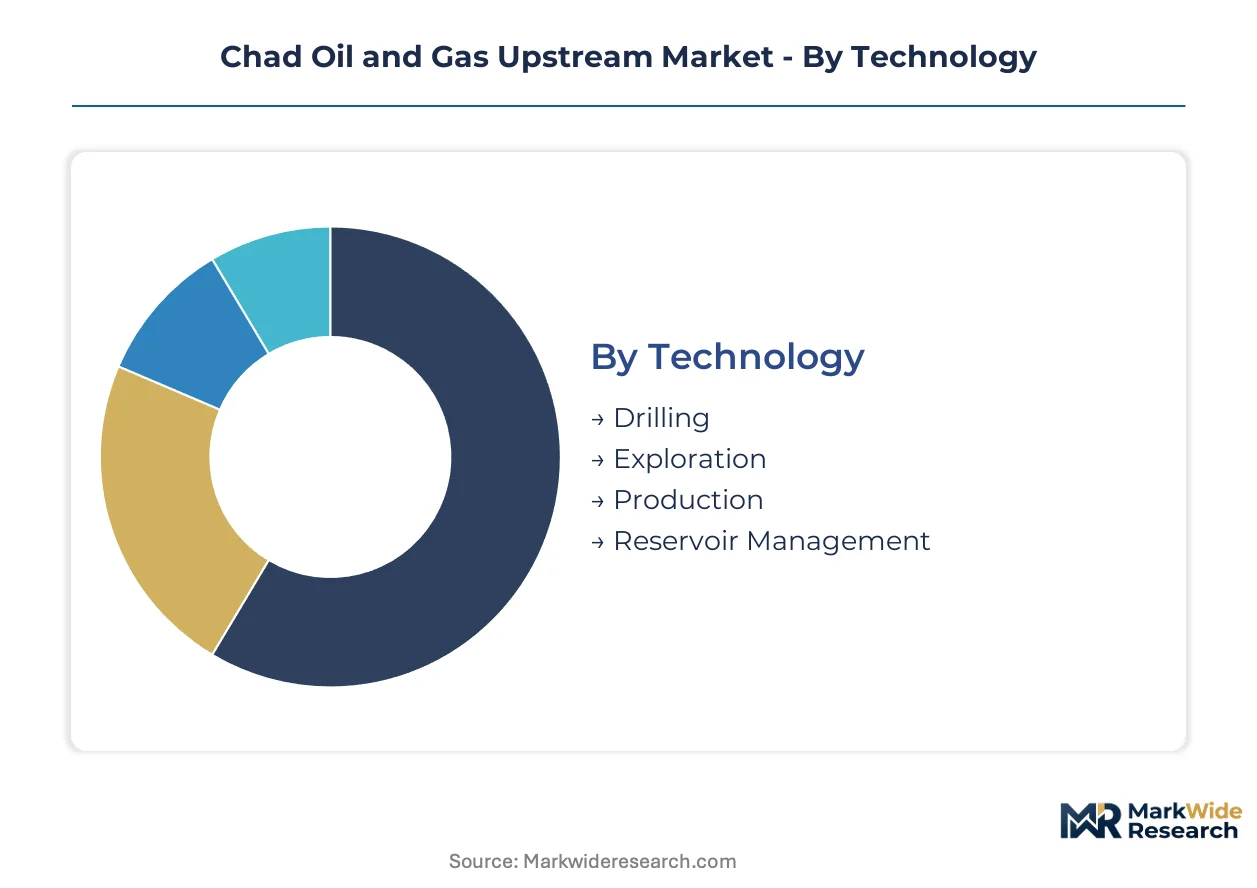
Segmentation in Chad's upstream market reveals how capital allocation priorities diverge across contractor capabilities and operator ownership structures. Each dimension exposes distinct procurement patterns shaped by the Doba Basin's mature field economics and the national petroleum regulator's local content mandates.
Technology:
Mature technologies dominate capital deployment while emerging techniques gain traction in marginal field extensions.
- Drilling:Rotary and directional drilling systems penetrate high-wax formations in southern Chad with specialized mud formulations. Demand concentrates around infill drilling programs in the Doba Basin where Exxon Mobil Corporation and China National Petroleum Corporation seek to sustain plateau production.
- Production:Artificial lift systems—primarily electrical submersible pumps and gas lift—handle viscous crude extraction from depleted reservoirs. Procurement is accelerating for ESP retrofits that extend well life without new wellbore construction.
- Exploration:Seismic acquisition and wildcat drilling target underexplored northern basins including the Erdis and Bongor graben systems. Activity remains constrained by fiscal term uncertainty following Hydrocarbons Code amendments.
- Reservoir Management:Waterflooding and gas injection programs maintain pressure in mature fields. Adoption is expanding as operators prioritize enhanced recovery over greenfield exploration capex.
Production handles the majority of throughput; Drilling is the fastest mover on share.
Service Type:
Cost tier differentiation separates capital-intensive field operations from advisory and support functions.
- Production Services:Workover rigs, artificial lift installation, and well intervention dominate service spending. Workover activity concentrates in the Doba Basin corridor where legacy well integrity demands continuous recompletion.
- Exploration Services:Seismic surveying, geological modeling, and exploratory drilling support wildcat campaigns. Procurement is tightening as integrated service contracts displace discrete vendor relationships.
- Maintenance Services:Pipeline integrity management, facility upkeep, and corrosion control sustain export infrastructure. Demand tracks COTCO pipeline throughput commitments and field aging profiles.
- Consulting Services:Reservoir engineering, regulatory compliance, and project economics advisory support operator decision-making. Local content mandates are forcing international consultants to partner with Chadian firms.
Production Services absorbs the heaviest capital burden; Consulting Services is expanding most quickly as regulatory complexity deepens.
End User:
Customer type segmentation exposes ownership structure as the primary determinant of procurement authority and risk appetite.
- National Oil Companies:Société des Hydrocarbures du Tchad and state-affiliated entities exercise operational control over production sharing contracts. Consolidation is tightening as the Ministry of Petroleum and Energy renegotiates fiscal terms.
- Joint Ventures:Partnerships between international majors and national operators share capital burden and technical expertise. Scrutiny is intensifying over cost recovery mechanisms and state participation thresholds.
- Independent Operators:Smaller exploration-focused companies target marginal fields and underexplored basins. Activity is frozen pending clarity on 2023 Hydrocarbons Code implementation.
- Service Contractors:Integrated service providers and specialized vendors execute field operations under contract. Selection criteria are shifting toward domestic equipment sourcing and labor content.
National Oil Companies command procurement authority; Joint Ventures face the steepest compliance burden expansion.
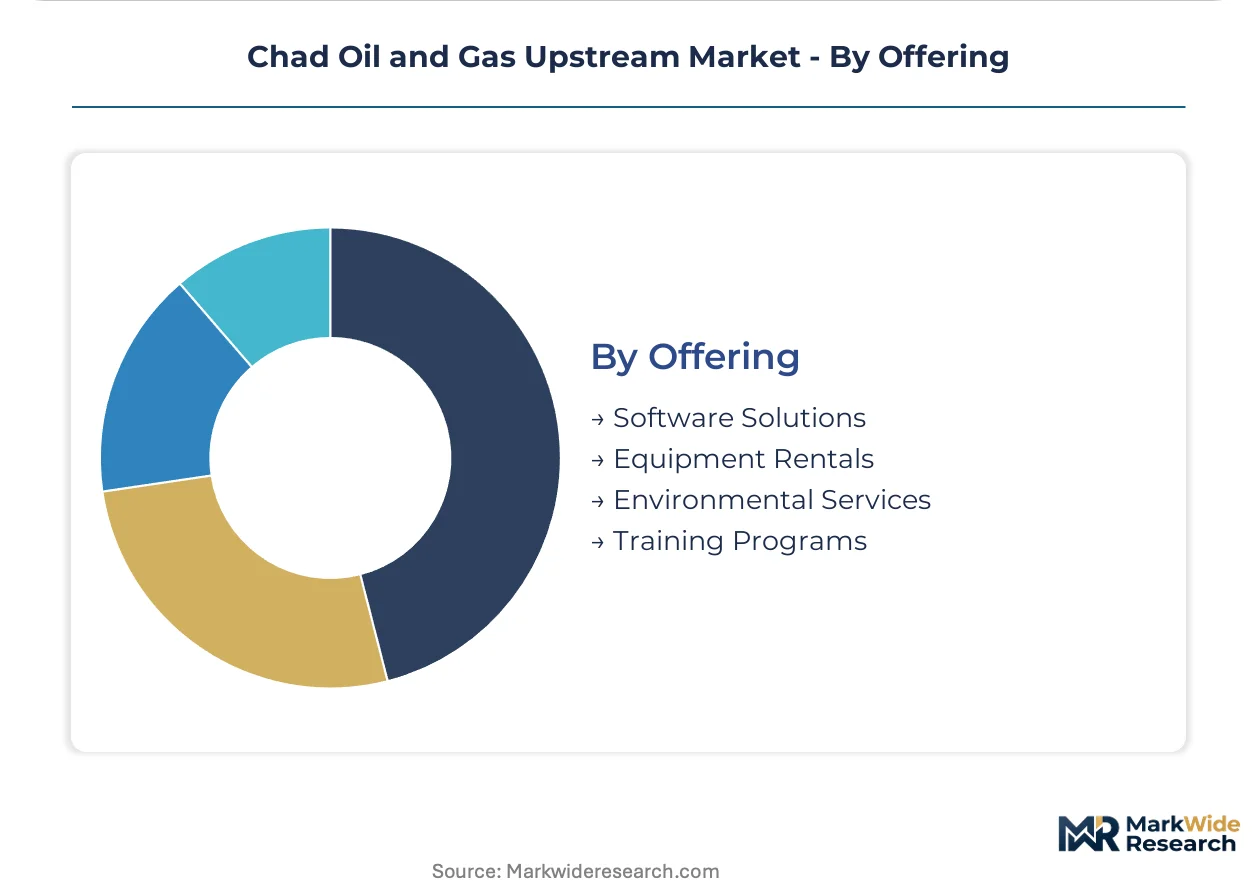
Offering:
Supply concentration distinguishes capital equipment from intangible service deliveries.
- Equipment Rentals:Drilling rigs, workover units, and production hardware leased on term contracts. Sourcing is complicated by import dependence through Douala and Pointe-Noire ports.
- Software Solutions:Reservoir simulation, digital twin platforms, and predictive maintenance systems enable remote monitoring. Satellite connectivity improvements are accelerating deployment across dispersed southern fields.
- Environmental Services:Impact assessments, methane monitoring, and flare minimization compliance support license renewal. Real-time emissions tracking is becoming mandatory under regulator protocols.
- Training Programs:Technical skills development for petroleum engineering and field operations. Domestic university output falls short of operator needs, forcing reliance on expatriate specialists.
Equipment Rentals anchors procurement volume; Software Solutions is gaining share fastest as digitalization compresses operational timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Chad-Cameroon pipeline system anchors the Doba Basin corridor as the critical export artery connecting southern fields to Atlantic terminals. This infrastructure underwrites production economics across Chad's southern sedimentary basins while northern regions remain underexplored due to logistical isolation.
Doba Basin Core
Exxon Mobil Corporation and China National Petroleum Corporation operate the mature oilfields around Kome, Miandoum, and Bolobo. Chad's Ministry of Petroleum and Energy enforces local content requirements that reshape contractor selection for workover programs. The N'Djamena-Sarh road corridor concentrates logistics capacity for rig mobilization and equipment transit.
Logone Oriental Province
Associated gas handling facilities absorb expanding crude output as electrification targets tighten around Moundou industrial zones. The national petroleum regulator mandates environmental impact assessments for flare minimization projects. Pipeline tie-in points at Komé-Badila cluster production from multiple field extensions.
Mayo-Kebbi Est
Perenco and smaller independents target marginal field opportunities near the Bongor graben system. The 2023 Hydrocarbons Code amendments have frozen final investment decisions pending fiscal term clarity. Drilling camps at Bongor city support exploration teams assessing Sudanese-analog structures.
Lake Chad Basin
Underexplored northern sedimentary sequences contain wildcat potential that remains stranded without pipeline connectivity. Chad's national petroleum regulator has issued preliminary exploration permits contingent on seismic commitment timelines. The Diffa-N'Djamena logistics corridor offers the only viable equipment transit route through insecure territory.
Guera Region
Frontier basin assessment programs target Erdis graben structures with gravity and magnetic surveys. The Ministry of Petroleum and Energy has designated the zone for future licensing rounds once infrastructure gaps close. Exploration teams operate from N'Djamena with helicopter support to remote survey grids.
Chad Oil and Gas Upstream Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with narrower scope. The Chad upstream market structures around three tiers: international majors controlling pipeline infrastructure, national oil companies exercising state participation rights, and specialized service contractors executing field operations. Strategic archetypes include integrated field developers, production service bundlers, and exploration-focused independents. Competitive moves concentrate on integrated service contract consolidation and local content partnership formation.
Among the international majors, Exxon Mobil Corporation and TotalEnergies occupy positions shaped by historical concession holdings and technology access. China National Petroleum Corporation anchors the state-backed tier through Chad-Cameroon pipeline control and integrated field development. Société des Hydrocarbures du Tchad represents the national oil company archetype with strengthening operational control over production sharing contracts.
| Leading Market Players |
|---|
| Glencore PLC |
| Delonex Energy Limited |
| Exxon Mobil Corporation |
| Société des Hydrocarbures du Tchad |
| China National Petroleum Corporation |
| TotalEnergies |
| PetroChad |
| Addax Petroleum |
| Perenco |
| Others |
Value Chain & Pricing Dynamics
Douala port congestion in Cameroon's commercial corridor compresses equipment transit timelines and amplifies pricing power for domestic logistics providers serving Chad's Doba Basin operators. The Central African franc zone's currency volatility feeds directly into capital equipment leasing rates, with workover rig contractors indexing long-term contracts to euro-pegged adjustments.
Pricing Analysis
Volume-discount tiering structures separate major integrated service contracts from discrete procurement arrangements. Three-tier pricing stratifies across premium bundled services, standard equipment rentals, and economy maintenance packages. Cost compression in the economy tier intensifies because local content mandates force international contractors to absorb domestic sourcing premiums. National Oil Companies exhibit lowest price sensitivity due to state-backed fiscal guarantees, while independent operators face acute margin pressure.
Supply Chain Analysis
Contract manufacturing concentration for subsea processing hardware and artificial lift systems rests in Houston, Singapore, and Aberdeen fabrication yards. Raw material dependencies center on high-grade steel alloys, specialized electronics for ESP variable frequency drives, and corrosion-resistant coatings. Single-source vulnerability runs through the Chad-Cameroon pipeline's exclusive throughput allocation system. Distribution runs through the N'Djamena-Sarh road corridor with helicopter logistics to remote well pads.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chad's upstream market represents a high-growth disruption anchored by the 2023 Hydrocarbons Code amendments reshaping fiscal terms and local content enforcement. Digital twin deployment and real-time methane monitoring requirements create immediate technology adoption imperatives.
For Market Incumbents: Build switching-cost moats through integrated service contract consolidation binding National Oil Companies to multi-year equipment and maintenance commitments. Anchor defensive positioning by securing Chad-Cameroon pipeline throughput guarantees before fiscal term renegotiations conclude. Deepen backward integration into domestic training programs to satisfy regulator mandates and reduce expatriate dependency. For New Entrants and Emerging Players: Build out captive power plant development at marginal field sites to monetize previously flared gas through direct electricity sales to mining concessions. Target the Erdis and Bongor graben systems where seismic commitments remain unfulfilled and competition is sparse. Lead with digital twin platform partnerships that compress operational timelines for remote field monitoring. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated service bundlers with established local content partnerships and pipeline throughput access. Long-term viability hinges on regulatory compliance infrastructure rather than pure exploration acreage. Acquisition targets should demonstrate proven Chad-Cameroon pipeline relationships. Watch local content enforcement intensity as the primary inflection signal for contractor margin expansion or compression.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Service Contract Consolidation | Bundles drilling, completion, and production under single-point accountability favored by COTCO throughput commitments. |
| Local Content Partnership Formation | Satisfies Ministry of Petroleum mandates while securing preferential contractor status for Doba Basin workover programs. |
| Digital Twin Platform Deployment | Enables remote monitoring of dispersed southern fields through improved satellite connectivity infrastructure. |
| Gas-to-Power Infrastructure Development | Captures value from associated gas through captive power plants serving mining concessions near Moundou. |
| Enhanced Recovery Technology Licensing | Extends productive life of mature Doba Basin fields without requiring new exploration capital expenditure. |
Study Parameters
Initial hypotheses were tested against primary input from petroleum engineering directors, procurement leads at National Oil Companies, drilling contractors, and Chad's Ministry of Petroleum officials and refined through secondary validation. Sources included customs records for capital equipment imports, production sharing contract disclosures, and regional energy regulator filings. Bottom-up field-level production estimates and top-down macroeconomic indicators were triangulated to anchor market sizing.
Demand-supply-balance framing structured the analytical approach across the projection horizon. Segmentation dimensions modeled include technology maturity tier, service type cost structure, end-user ownership archetype, and offering tangibility. CAGRs were derived from production volume trajectories and capital expenditure commitments across the modeling period. Industry-specific inputs incorporated pipeline throughput capacity utilization and local content compliance cost premiums.
Sensitivities concentrate around fiscal term renegotiation outcomes and local content enforcement intensity. Forecasts reflect assumptions regarding Hydrocarbons Code implementation timelines and COTCO infrastructure maintenance schedules. Quarterly review of pipeline throughput allocations and drilling permit issuance rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Asphaltene Inhibitors Market
Oil & Gas
LNG Loading Skid Market
Oil & Gas
Global LNG Liquefaction Equipment Market
Oil & Gas
Indonesia Oil and Gas Midstream Market
Oil & Gas
Subsea Well Intervention Market
Oil & Gas
Sudan Oil and Gas Market
Oil & Gas
Oil and Gas Field Services Market
Oil & Gas
Africa Drilling and Completion Fluids Market
Oil & Gas
Shale Gas Hydraulic Fracturing Market
Oil & Gas
Iron Ore Mining Market
Oil & Gas
India Oil and Gas Midstream Market
Oil & Gas
Flare Gas Recovery System Market
Oil & Gas
Drilling Fluids Market
Oil & Gas
Europe Oil and Gas Electric Submersible Pump Market
Oil & Gas
Downhole Equipment Market
Oil & Gas
Methane Hydrate Extraction Market