
 Hybrid Flow Battery Market | 2026-2036
Hybrid Flow Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Flow Battery Market Intelligence
Higher energy density chemistries are reorganizing the competitive landscape for hybrid flow batteries, enabling longer duration storage. Sumitomo Electric Industries leverages its deep expertise in vanadium-based systems for large-scale utility projects. ESS Tech, Inc. specializes in iron-flow battery technology for commercial and industrial applications, while Redflow Limited competes with its unique zinc-bromine modular designs.
A hybrid flow battery is an electrochemical storage device where energy is stored in external tanks of liquid electrolyte, allowing power and energy capacity to be scaled independently. This design makes it suitable for long-duration energy storage applications. The utilities segment represents the largest end-user group, driven by the need for grid stabilization and renewable integration. Within technology segments, zinc-bromine and vanadium chemistries show significant development for large-scale deployments.
Regulatory frameworks are critical for market development. In the United States, the Inflation Reduction Act (IRA) provides investment tax credits, while the EU Green Deal and China's dual carbon goals create policy tailwinds for energy storage. These government initiatives directly influence project economics and investment decisions. The key strategic decision for manufacturers will be aligning technology roadmaps with evolving grid interconnection standards and safety protocols.
Market Dynamics
The need to stabilize electrical grids against the intermittency of renewable energy sources, amplified by significant government policy support, is the central force shaping the market. This creates non-discretionary demand for long-duration storage solutions from the utilities sector.
Growth Catalysts
- Favorable Regulatory Policies:The US Inflation Reduction Act (IRA) provides substantial tax credits for energy storage projects, directly improving project viability and accelerating deployments by utilities and commercial entities.
- National Decarbonization Goals:China's dual carbon goals mandate extensive renewable energy integration, creating a massive, policy-driven market for utility-scale flow batteries to ensure grid stability.
- Technology Maturation:Advances in higher energy density chemistries, particularly in vanadium and zinc-based systems, are improving performance and cost-effectiveness, making them more competitive for long-duration applications.
Market Restraints
- High Initial Capital Costs:The upfront investment for hybrid flow batteries, especially the cost of vanadium electrolyte for certain chemistries, remains a significant barrier compared to other storage technologies.
- Supply Chain Vulnerabilities:The geographic concentration of raw materials processing, such as vanadium, creates potential price volatility and supply chain risks for manufacturers dependent on these inputs.
- Technical Performance Gaps:Lower round-trip efficiency and energy density compared to established lithium-ion batteries can make hybrid flow batteries less suitable for applications requiring rapid charge and discharge cycles.
Strategic Opportunities
- Emerging Geographic Markets:India's national push for grid modernization and renewable energy capacity expansion creates a significant new market for long-duration storage to support its energy transition.
- Green Hydrogen Production:Pairing flow batteries with hydrogen electrolyzers offers an opportunity to provide the stable, continuous power required for efficient green hydrogen production, a new application segment.
- Grid Services Ancillary Markets:The development of markets for ancillary grid services, such as frequency regulation and voltage support, opens new revenue streams for owners of flow battery assets.
Industry Challenges
- Standardization and Interconnection:A lack of uniform grid interconnection standards and safety protocols across different regions and utilities complicates and delays project deployment and commissioning.
- System Integration Complexity:Integrating flow battery control systems with legacy utility energy management systems and SCADA platforms requires specialized software development and engineering expertise.
- Specialized Talent Scarcity:The industry faces a shortage of chemical and systems engineers with specific expertise in flow battery electrochemistry, long-term maintenance, and operational management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Flow Battery Market |
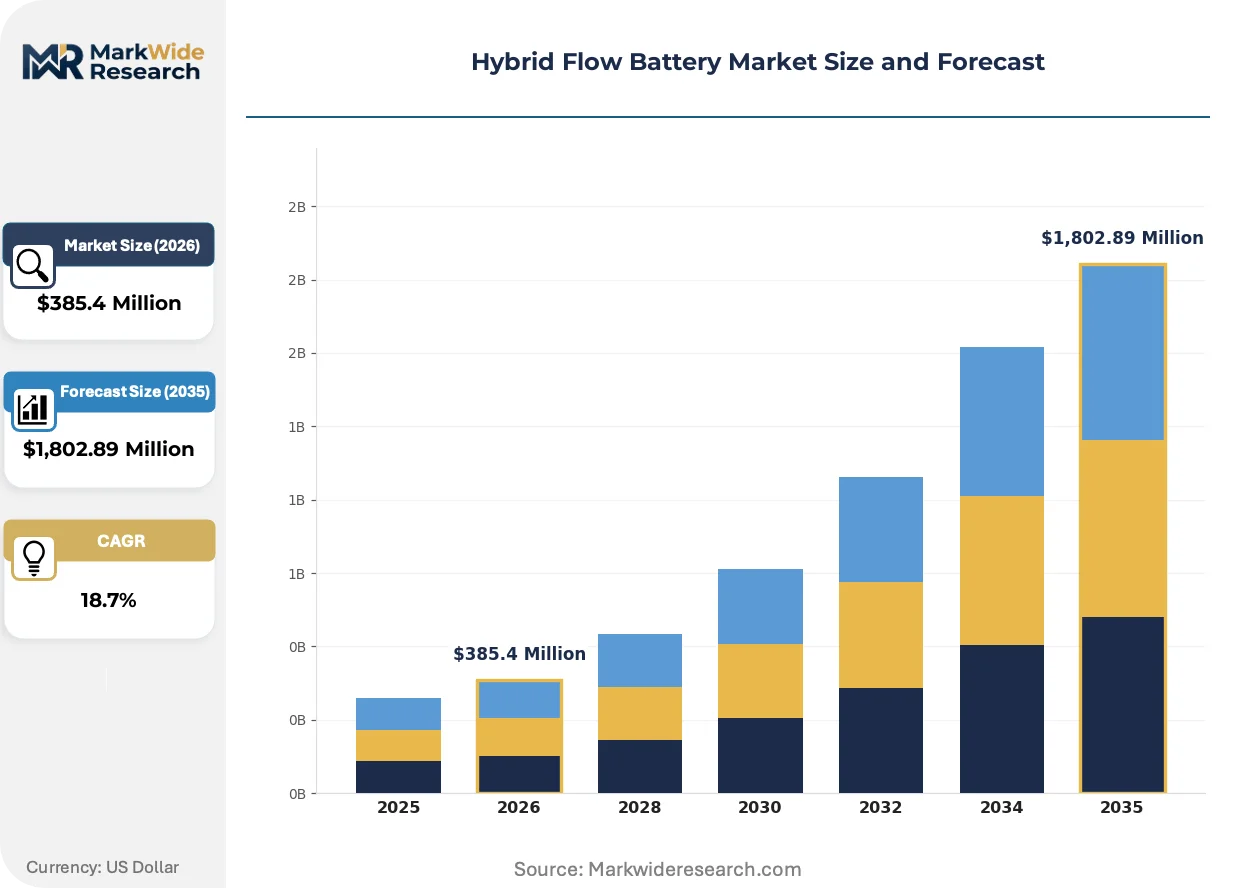
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,802.89 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Vanadium, Zinc-Bromine, Organic, Iron-Flow End User: Utilities, Commercial, Industrial, Residential Application: Energy Storage, Load Shifting, Renewable Integration, Backup Power Sales Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Primus Power, Gelion Technologies, Redflow Limited, Sumitomo Electric Industries, Invinity Energy Systems, ESS Tech, Inc., VRB Energy, Lockheed Martin Corporation, Gildemeister Energy Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Flow Battery Market Strategic Shifts & Innovations
This market is transitioning from niche technology pilots to scalable, bankable grid assets. The evolution is driven by maturing chemistries, supportive regulations, and utilities re-evaluating long-duration storage economics.
Zinc-bromine and all-iron chemistries provide lower-cost alternatives to traditional vanadium systems. Commercial and industrial users are adopting these modular systems for behind-the-meter storage applications. The availability of diverse chemistries is fragmenting the previously vanadium-dominated technology landscape, creating distinct segments for different use cases and budget profiles.
The EU Green Deal and its associated policies, like the Critical Raw Materials Act, are creating a strong push for energy independence and resilient supply chains. This regulatory framework incentivizes the development and deployment of energy storage technologies that utilize locally sourced or recycled materials. The utilities segment in member states like Germany and Spain is actively seeking non-lithium alternatives to meet these strategic objectives.
Utilities are shifting from fixed-price hardware procurement to long-term energy storage as a service (ESaaS) agreements. This model transfers performance and operational risk to the battery provider, replacing large capital outlays with predictable operational expenses for the end-user. The shift is most visible in North America and parts of Europe, where mature financial markets can underwrite such long-term contracts for grid infrastructure.
Hybrid Flow Battery Market Segmentation
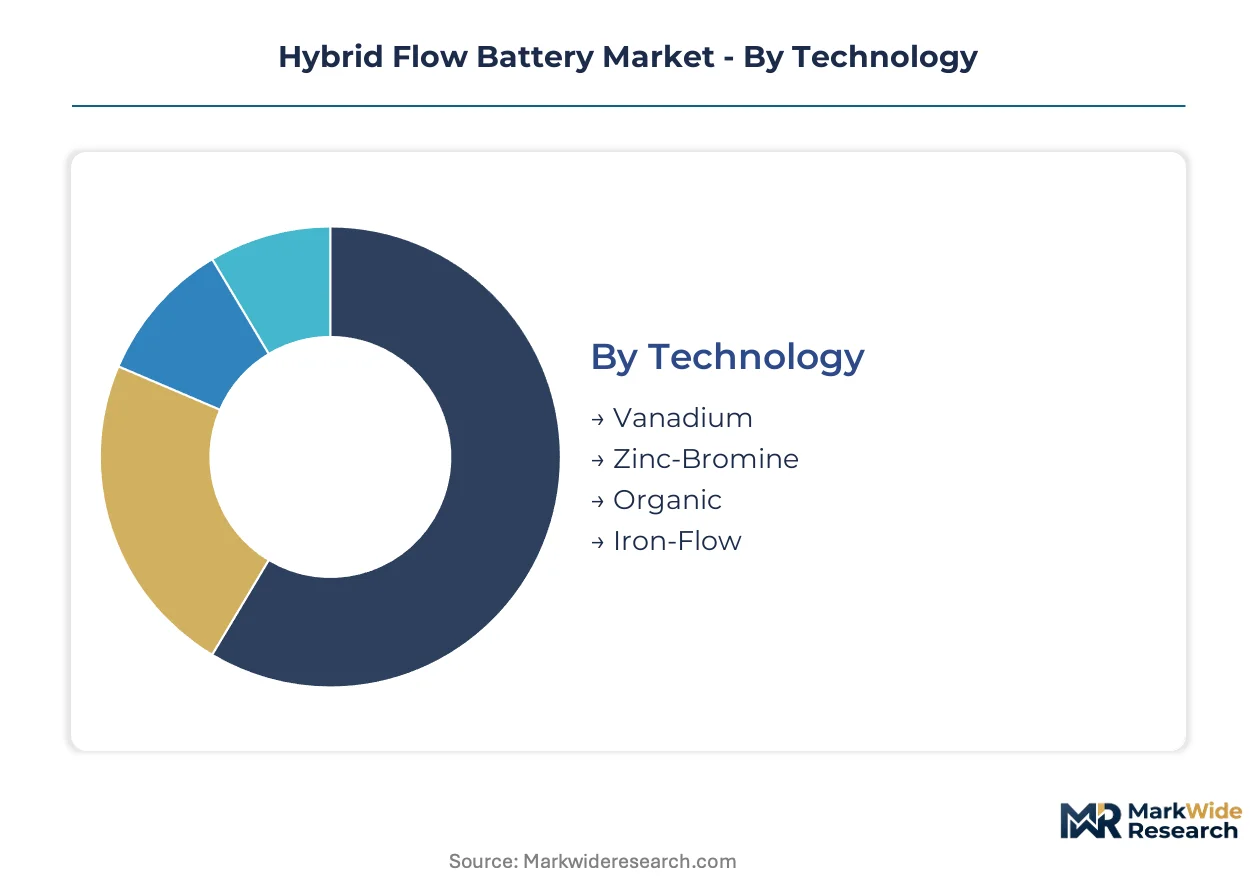
Understanding the hybrid flow battery market through detailed segmentation reveals distinct opportunities and challenges across various technology types, end-user groups, and application areas. This granular view assists stakeholders in identifying specific demand pockets and tailoring product development or market entry strategies. Market dynamics vary significantly between chemistries and the diverse requirements of grid-scale versus behind-the-meter deployments.
Technology:
The geographic adoption patterns for hybrid flow battery technologies vary, with some chemistries gaining traction in specific regions due to local resource availability or strategic priorities.
- Vanadium:These systems utilize vanadium ions in different oxidation states to store energy in liquid electrolytes, offering high cycling stability and long operational lifetimes. Demand concentrates in large-scale utility projects across North America and Asia, driven by the need for robust grid stabilization.
- Zinc-Bromine:Zinc-bromine batteries employ a zinc electrode and a bromine electrolyte, known for their modular design and lower material costs compared to vanadium. European utilities and commercial users are increasingly adopting these systems, influenced by policies like the EU Green Deal favoring non-lithium alternatives.
- Organic:Organic flow batteries leverage organic compounds as active materials for charge storage, offering potential for abundant and environmentally benign chemistries. Development efforts are primarily concentrated in academic research and pilot projects, targeting niche applications where sustainability is a primary concern.
- Iron-Flow:Iron-flow batteries use iron salts as the active material, providing a cost-effective solution with readily available inputs. Commercial and industrial applications in the United States, supported by the Inflation Reduction Act, are exploring these systems for their economic viability.
Vanadium technology holds the largest share; momentum sits with Iron-Flow systems.
End User:
Different end-user segments prioritize varying cost structures and performance metrics, influencing their adoption of hybrid flow battery solutions.
- Utilities:This segment comprises large-scale grid operators and power generators requiring long-duration energy storage for grid stability, renewable integration, and ancillary services. Utilities often prioritize system longevity and reliability over initial capital cost.
- Commercial:Commercial entities, including large businesses and data centers, deploy hybrid flow batteries for behind-the-meter applications such as peak shaving, demand charge management, and backup power. These users balance initial investment with operational savings and energy independence.
- Industrial:Industrial facilities utilize flow batteries for ensuring power quality, reducing energy costs, and providing uninterrupted power for critical processes. Their procurement decisions weigh heavily on system robustness and integration with existing industrial infrastructure.
- Residential:The residential segment involves homeowners seeking energy independence, solar self-consumption optimization, and backup power solutions. Cost-effectiveness and ease of installation are paramount for widespread adoption in this segment.
Utilities drive the primary volume, while Commercial applications show expanding potential.
Application:
The volume of demand for hybrid flow batteries varies significantly across different applications, reflecting diverse operational requirements and economic drivers.
- Energy Storage:This broad application encompasses the fundamental function of storing electrical energy for later use, serving as the core demand driver for the market. Grid-scale projects and large commercial installations represent the bulk of this application.
- Load Shifting:Load shifting involves storing energy during off-peak hours when electricity is cheaper and discharging it during peak demand periods to reduce costs. Commercial and industrial users frequently employ this application to optimize energy consumption.
- Renewable Integration:This application focuses on mitigating the intermittency of renewable energy sources like solar and wind by storing excess generation and releasing it when needed. Utility-scale projects in China and the US are heavily investing in this area.
- Backup Power:Hybrid flow batteries provide reliable backup power for critical infrastructure, commercial facilities, and residential properties during grid outages. Data centers and essential services represent key users for this application.
Renewable Integration applications command significant investment, with Energy Storage forming the foundational demand.
Sales Channel:
Sales channels cater to distinct customer profiles, reflecting the project scale, complexity, and technical expertise required for hybrid flow battery deployments.
- Direct Sales:This channel involves manufacturers selling directly to large-scale end-users, typically utilities or major industrial clients, for complex, customized projects. Direct engagement ensures tailored solutions and comprehensive support for high-value contracts.
- Distributors:Distributors serve as intermediaries, providing regional reach and logistical support for hybrid flow battery systems, often targeting commercial and smaller industrial customers. They offer a broader product portfolio and local installation services.
- Online Sales:Online platforms facilitate the sale of standardized or modular hybrid flow battery units, primarily appealing to smaller commercial entities or specialized integrators. This channel prioritizes convenience and competitive pricing.
- Retail:The retail channel focuses on consumer-grade or smaller commercial battery systems, often bundled with solar installations for residential or small business use. This channel emphasizes ease of purchase and installation for less complex solutions.
Direct Sales channels manage major project deployments, while Distributors extend market reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global hybrid flow battery market exhibits a complex dynamic in balancing domestic energy needs with securing critical raw materials. Regions are increasingly focused on developing local supply chains or fostering indigenous technology to reduce reliance on external dependencies. This strategic shift influences deployment patterns across major economies.
China
China's demand for grid stabilization and renewable integration drives significant hybrid flow battery deployments. Its national dual carbon goals mandate extensive energy storage, creating a massive market. The Yangtze River Delta region, with its industrial clusters, sees substantial investment in utility-scale projects.
United States
The United States prioritizes grid modernization and integrating intermittent renewable energy sources. The Inflation Reduction Act (IRA) provides substantial tax credits, accelerating project viability. California, a leader in renewable energy, actively deploys large-scale flow battery systems for grid support.
Germany
Germany's energy transition requires robust, long-duration storage solutions for grid balancing. The EU Green Deal incentivizes non-lithium alternatives, favoring technologies like zinc-bromine. Bavaria, a hub for industrial innovation, is a key area for hybrid flow battery installations in utility segments.
India
India's national push for grid modernization and renewable energy capacity expansion creates a significant new market. The country's energy policies support long-duration storage to stabilize its rapidly evolving grid. Karnataka, a technology and industrial center, is seeing early adoption and pilot projects.
Spain
Spain focuses on renewable energy integration and achieving greater energy independence. Policies under the EU Green Deal encourage the adoption of diverse energy storage technologies. Andalusia, with its abundant solar resources, is a prime location for combining solar generation with flow battery storage.
Hybrid Flow Battery Market Key Industry Players
Concentration sits with specialized technology developers and established industrial conglomerates in the hybrid flow battery market. The competitive landscape fragments across various chemistries and application niches, from utility-scale to commercial deployments. These players are actively pursuing technology maturation and strategic partnerships to enhance performance, reduce costs, and expand their geographic reach. Portfolio diversification, especially into different chemistries, is a key competitive move to address varied end-user requirements.
Specialized technology developers such as Sumitomo Electric Industries, known for its deep expertise in vanadium-based systems, anchor the utility-scale segment, particularly in Asian markets. ESS Tech, Inc. represents a key player in iron-flow battery technology, occupying a position in commercial and industrial applications, especially in the United States, driven by economic viability. Redflow Limited, with its unique zinc-bromine modular designs, sits within the providers of flexible, non-lithium solutions for diverse use cases, finding traction in European markets driven by specific policy incentives for material diversity.
| Leading Market Players |
|---|
| Primus Power |
| Gelion Technologies |
| Redflow Limited |
| Sumitomo Electric Industries |
| Invinity Energy Systems |
| ESS Tech, Inc. |
| VRB Energy |
| Lockheed Martin Corporation |
| Gildemeister Energy Solutions |
| Others |
Cost & Logistics Intelligence
Project-based contracts, common in utility-scale deployments, lock in both supply access and price visibility for hybrid flow battery systems. This structure helps mitigate the impact of raw material volatility on long-term project economics.
Pricing Analysis
Industrial OEM buyers anchor value-based pricing, which reflects system performance and integrated solution complexity rather than purely per-unit costs. Price differentiation stems from the specific chemistry type, such as vanadium versus iron-flow, and the level of system integration provided. Pricing softness reflects intense competition from established lithium-ion alternatives and the high initial capital outlay. Residential users exhibit the highest price sensitivity, while utilities prioritize long-term reliability and total cost of ownership.
Supply Chain Analysis
Extended lead times for critical raw materials often characterize hybrid flow battery supply chains, influencing project timelines. Geographic concentration of vanadium processing in China and primary vanadium mining in Australia creates specific vulnerabilities. Raw material dependencies include vanadium electrolyte, zinc, and bromine salts. Geopolitical instability affecting mineral extraction poses a significant structural risk to supply continuity. Distribution runs through direct sales channels for large utility projects and specialized integrators for commercial and industrial applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hybrid flow battery market is undergoing a platform-economics inflection, driven by the increasing demand for grid management systems interoperability. This shift necessitates strategic alignment across technology developers and project integrators.
For Market Incumbents: Secure long-term raw material supply agreements, particularly for vanadium, to mitigate commodity price volatility. Diversify chemistry portfolios beyond vanadium to include iron-flow or zinc-bromine systems, addressing the threat from cheaper emerging technologies. Invest in advanced electrolyte recycling technologies to reduce reliance on primary raw material extraction and enhance supply chain resilience. Pursue vertical integration into key component manufacturing to control quality and cost.
For New Entrants and Emerging Players: Lead with modular, scalable solutions targeting commercial and industrial behind-the-meter applications. Focus on underserved geographies with strong renewable energy mandates and favorable regulatory incentives for long-duration storage. Offer energy storage as a service (ESaaS) models to lower upfront capital barriers for customers. Target specific niche applications like green hydrogen production, which requires stable, continuous power. Develop robust integration capabilities for existing energy management systems.
For Investors and Strategic Acquirers: Specialized chemistry developers with unique intellectual property or robust manufacturing capabilities represent attractive acquisition targets. The market exhibits long-term viability, as hybrid flow batteries are essential for grid decarbonization over the next decade. A critical signal to watch is the successful deployment of large-scale projects achieving stated performance metrics and cost targets. Evaluate companies with strong intellectual property in non-vanadium chemistries for future growth potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyte Recycling Infrastructure | Reduces raw material cost volatility and enhances supply chain resilience for vanadium systems. |
| Energy Storage as a Service (ESaaS) Offerings | Lowers upfront capital expenditure barriers for utility and commercial customers. |
| Advanced Chemistry R&D Investment | Improves energy density and round-trip efficiency, making hybrid flow batteries more competitive. |
| Grid Interconnection Standardization Advocacy | Streamlines project deployment and reduces integration complexity for utilities. |
| Green Hydrogen Production Integration | Opens new application segments by providing stable power for electrolyzers. |
Research Approach
Initial hypotheses were tested against primary input from utility planning officers, battery manufacturers' R&D leads, project developers, and energy regulators, then refined through iterative processes. This involved extensive interviews with industry stakeholders and validation against secondary data sources. Secondary research included analysis of EIA data, IEA reports, company financial filings, and government energy policy documents from the US, China, and Germany. Bottom-up and top-down triangulation ensured data accuracy and consistency.
Variance decomposition framed the analytical framework across the analysis window, allowing for detailed understanding of market dynamics. Segmentation dimensions modeled included technology type, end-user segment, application area, sales channel, and regional regulatory environment. Compound annual growth rates were derived from historical trends, identified market drivers, and expert projections. Key industry-specific forecast inputs included projected renewable energy deployment rates and raw material price forecasts for vanadium and zinc.
Forecasts assume regulatory continuity in regimes like the US Inflation Reduction Act and China's dual carbon goals; material policy shifts would require re-modeling. These projections reflect assumptions regarding technological advancements and market adoption rates. Unforeseen technological breakthroughs or significant raw material supply disruptions represent specific risk factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Grid-Scale Flow Battery Stack Endurance Test Benches Market
Batteries
Water-Based Zinc-Ion Battery Market
Batteries
PVT Battery Panel Market
Batteries
Nickel Cadmium Battery Market
Batteries
Modular Battery Pack Platforms for Skateboard EVs Market
Batteries
Indonesia Battery Market
Batteries
Nuclear Battery Sales Market
Batteries
Li-Ion Pouch Battery Market
Batteries
Power Battery Cells Market
Batteries
Australia Battery Market
Batteries
Asia Pacific Electric Vehicle VRLA Batteries Market
Batteries
Zinc-Ion Battery Cells Market
Batteries
48 Volt Battery System Market
Batteries
Submarine Lead-Acid Battery Market
Batteries
France Rechargeable Battery Market
Batteries
Battery Simulator Market