
 Third Generation Solar Cell Sales Market | 2026-2036
Third Generation Solar Cell Sales Market Size, Share, and Industry Trends Forecast 2026-2036
Third Generation Solar Cell Sales Market Insights
Chinese perovskite module pilot lines is recalibrating capacity planning across the sector. Oxford Photovoltaics leverages its tandem silicon-perovskite architecture to anchor premium utility contracts in European markets. Heliatek sustains organic photovoltaic roll-to-roll production, dominating flexible building-integrated deployments. Greatcell Solar specializes in dye-sensitized cell formulations, competing on low-light efficiency for indoor and portable applications.
Third generation solar cells encompass emergent photovoltaic architectures—perovskite, organic, dye-sensitized, and quantum dot systems—that operate through excitonic charge separation or solution-processed heterojunctions rather than conventional p-n junction physics, with power conversion efficiencies now surpassing single-junction silicon in laboratory tandem configurations. Their primary purpose is enabling lightweight, flexible, or semitransparent energy harvesting in applications where crystalline silicon proves mechanically or economically unsuitable. Perovskite solar cells occupy the fastest-expanding product category as manufacturing yields improve and encapsulation protocols extend field durability. Organic photovoltaics lead in portable and wearable segments where mechanical flexibility outweighs absolute efficiency metrics. Building integrated photovoltaics represents the highest-margin application pool, commanding price premiums through architectural substitution for conventional cladding materials.
The US EPA and Department of Energy shape domestic deployment through efficiency certification protocols and manufacturing tax credit structures under the Inflation Reduction Act. China's MIIT and National Energy Administration enforce GB standards for module testing and grid interconnection, accelerating domestic perovskite commercialization timelines. India's MNRE and Bureau of Indian Standards administer domestic content requirements and performance guarantees for government-tendered solar parks. Stakeholders must monitor which regulatory framework first mandates recycling or end-of-life material recovery, as this will reshape supply chain geography and module cost structures.
Market Dynamics
Perovskite tandem cell commercialization is compressing technology adoption cycles as manufacturing yields cross viability thresholds and utility-scale procurement teams rewrite module specifications around dual-junction architectures.
Growth Catalysts
- IRA Manufacturing Tax Credits:The Inflation Reduction Act's advanced manufacturing production credit is anchoring domestic perovskite pilot line investments and reshoring thin-film deposition equipment procurement.
- BIPV Mandate Clusters:Bavaria's building code amendments requiring photovoltaic cladding on new commercial structures are creating captive demand for semitransparent organic modules.
- Encapsulation Protocol Advances:Barrier film lamination techniques extending field durability beyond 25 years are unlocking utility-scale warranty terms previously reserved for crystalline silicon.
Market Restraints
- Lead Content Regulations:REACH authorization procedures for lead-based perovskite formulations are creating compliance friction across European distribution channels.
- Specialized Deposition Equipment:Vacuum thermal evaporation systems for uniform perovskite layer formation concentrate among German and Japanese tool vendors, creating procurement bottlenecks.
- Crystalline Silicon Price Compression:Polysilicon oversupply from Chinese ingot capacity expansion is narrowing the effective cost window for third-generation alternatives.
Strategic Opportunities
- Indoor Photovoltaic Integration:Low-light dye-sensitized formulations are penetrating IoT sensor networks and wireless access point power harvesting where ambient illumination replaces dedicated wiring.
- Flexible Roll-to-Roll Production:Organic photovoltaic manufacturing on polymer substrates is converging with textile lamination processes for wearable energy harvesting garments.
- Agrivoltaic Dual-Use Deployment:Semitransparent perovskite modules are enabling photosynthesis-compatible shading structures in Gujarat's horticulture belts.
Industry Challenges
- Cross-Functional Talent Scarcity:The intersection of solution-processed semiconductor fabrication and photovoltaic system engineering lacks established training pipelines, constraining pilot line scaling.
- Bankability Certification Timelines:IEC 61215 adaptation for perovskite-specific degradation modes remains incomplete, delaying project finance closure for utility-scale deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Third Generation Solar Cell Sales Market |
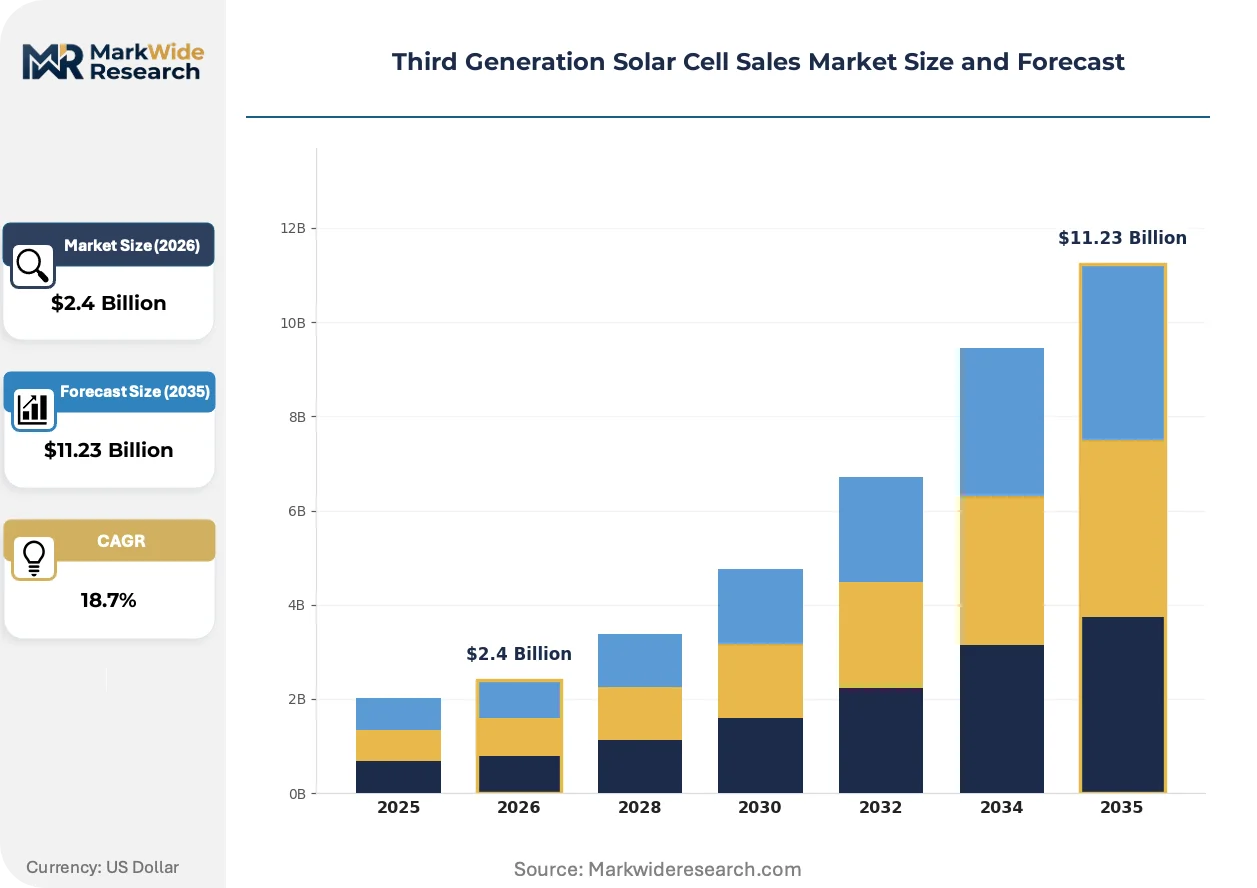
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $11.23 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Photovoltaics, Perovskite Solar Cells, Dye-Sensitized Cells, Quantum Dot Cells Technology: Thin-Film Technology, Printing Technology, Nanotechnology, Hybrid Technology End User: Residential Applications, Commercial Applications, Utility-Scale Plants, Aerospace Applications Application: Building Integrated Photovoltaics, Portable Devices, Grid-Tied Systems, Off-Grid Solutions |
| Companies Covered | 3GSolar, Showa Denko, Greatcell Solar, PECCELL Technologies, Solaronix, Heliatek, Fujikura Ltd, Solaris Nanosciences, Oxford Photovoltaics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Third Generation Solar Cell Sales Market Trends and Innovations
Solution-processed photovoltaic architectures are rewriting module form-factor assumptions as deposition chemistry advances unlock substrate flexibility and manufacturing energy intensity reductions.
Tandem silicon-perovskite cell stacking is converging with industrial coating techniques to enable dual-junction architectures on standard float-glass substrates. Automotive integrated photovoltaics teams at German OEMs are piloting roof-integrated modules for electric vehicle range extension. This convergence is compressing the efficiency gap between laboratory demonstrations and mass-production line averages.
China's MIIT perovskite commercialization roadmap is mandating gigawatt-scale pilot line commissioning by domestic equipment vendors. The directive is accelerating domestic supply chain localization for precursor materials and encapsulation films. European module assemblers are responding by securing alternative precursor sourcing from South Korean chemical suppliers.
Utility procurement specifications are unbundling performance warranties from module supply contracts. Independent power producers in India are negotiating separate degradation insurance through specialized underwriters rather than manufacturer guarantees. This behavioral shift is most visible in MNRE-tendered solar parks where domestic content requirements intersect with limited local bankability track records.
Third Generation Solar Cell Sales Market Segmentation
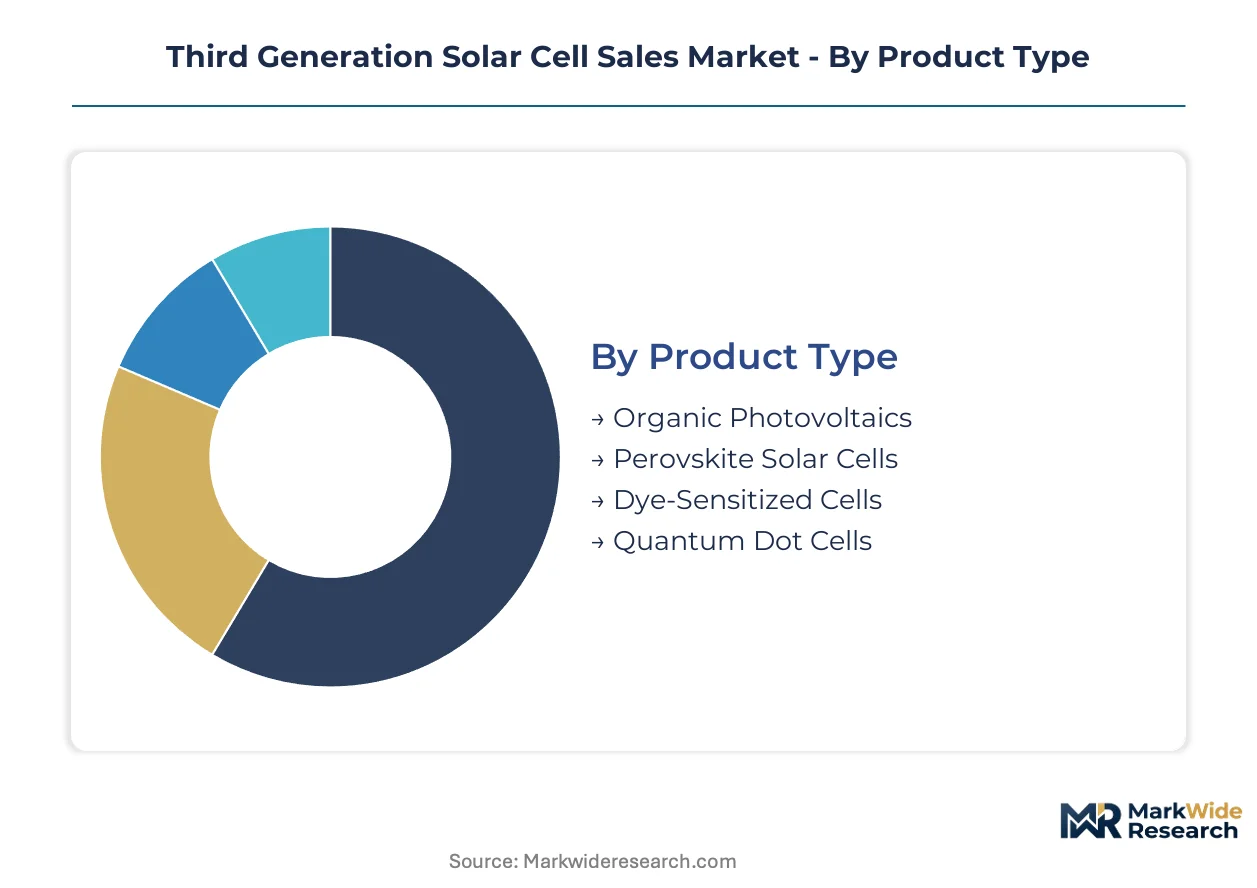
Third generation solar cell architectures fragment across four intersecting dimensions—product chemistry, manufacturing process, deployment scale, and integration context—each imposing distinct performance specifications and procurement economics on module suppliers.
Product Type:
Standardization dominates at the material stack level, yet customization proliferates in encapsulation and substrate selection as end-uses diverge across building-integrated, portable, and utility-scale contexts.
- Perovskite Solar Cells:Metal halide absorber layers deposited via solution processing achieve dual-junction efficiencies exceeding single-junction silicon in laboratory tandem configurations. Utility procurement teams in India and China are rewriting module specifications around perovskite-silicon architectures as manufacturing yields cross bankability thresholds.
- Organic Photovoltaics:Conjugated polymer-fullerene heterojunctions enable roll-to-roll manufacturing on flexible polymer substrates. Bavaria's building code amendments mandating photovoltaic cladding on new commercial structures are creating captive demand for semitransparent organic modules in European BIPV deployments.
- Dye-Sensitized Cells:Ruthenium-based sensitizers on titanium dioxide nanoparticle films optimize low-light quantum efficiency. Indoor IoT sensor networks and wireless access point power harvesting in ambient illumination conditions represent the primary demand concentration.
- Quantum Dot Cells:Colloidal semiconductor nanocrystals enable tunable absorption spectra through particle size control. Research-stage deployment concentrates in aerospace applications requiring radiation hardness and spectral flexibility.
Most installed capacity flows through Perovskite Solar Cells. Expansion is steepest in Organic Photovoltaics.
Technology:
Process selection maps directly to capital intensity and substrate compatibility, with thin-film methods anchoring utility-scale volume and printing techniques capturing flexible application niches.
- Thin-Film Technology:Vacuum thermal evaporation and chemical vapor deposition enable uniform perovskite layer formation on rigid glass substrates. German and Japanese tool vendors concentrate specialized deposition equipment supply, creating procurement bottlenecks for scaling pilot lines.
- Printing Technology:Slot-die and inkjet deposition of organic semiconductor formulations converge with textile lamination processes. Wearable energy harvesting garments and flexible building-integrated deployments drive roll-to-roll production investments.
- Nanotechnology:Self-assembled monolayers and quantum dot surface engineering optimize charge extraction interfaces. Dye-sensitized and quantum dot cell architectures depend on nanoscale morphology control for efficiency gains.
- Hybrid Technology:Combined solution-processed and vapor-deposited layers balance manufacturing throughput with performance optimization. Tandem silicon-perovskite architectures require hybrid process integration for dual-junction cell stacking.
Thin-Film Technology commands the dominant share of production investment. Printing Technology is gaining share fastest as flexible substrate demand accelerates.
End User:
Customer scale determines warranty structure, financing mechanism, and degradation insurance requirements, with utility-scale procurement unbundling performance guarantees from module supply contracts.
- Utility-Scale Plants:Gigawatt-scale deployments require IEC 61215 certification adaptation for perovskite-specific degradation modes. Independent power producers in India negotiate separate degradation insurance through specialized underwriters rather than manufacturer guarantees.
- Commercial Applications:Building-integrated and rooftop installations prioritize architectural substitution value over absolute efficiency metrics. BIPV mandates in Gujarat, Shanghai, and Bavaria concentrate demand for semitransparent and flexible module form factors.
- Residential Applications:Distributed generation deployments emphasize lightweight installation and aesthetic integration. Rooftop weight constraints and homeowner association approvals favor thin-film and organic alternatives to crystalline silicon.
- Aerospace Applications:Satellite and high-altitude platform power systems demand radiation hardness and power-to-weight ratio optimization. Quantum dot and perovskite architectures target specific orbital illumination spectra.
Utility-Scale Plants absorb the largest module volume. Commercial Applications show the steepest demand trajectory as BIPV mandates proliferate.
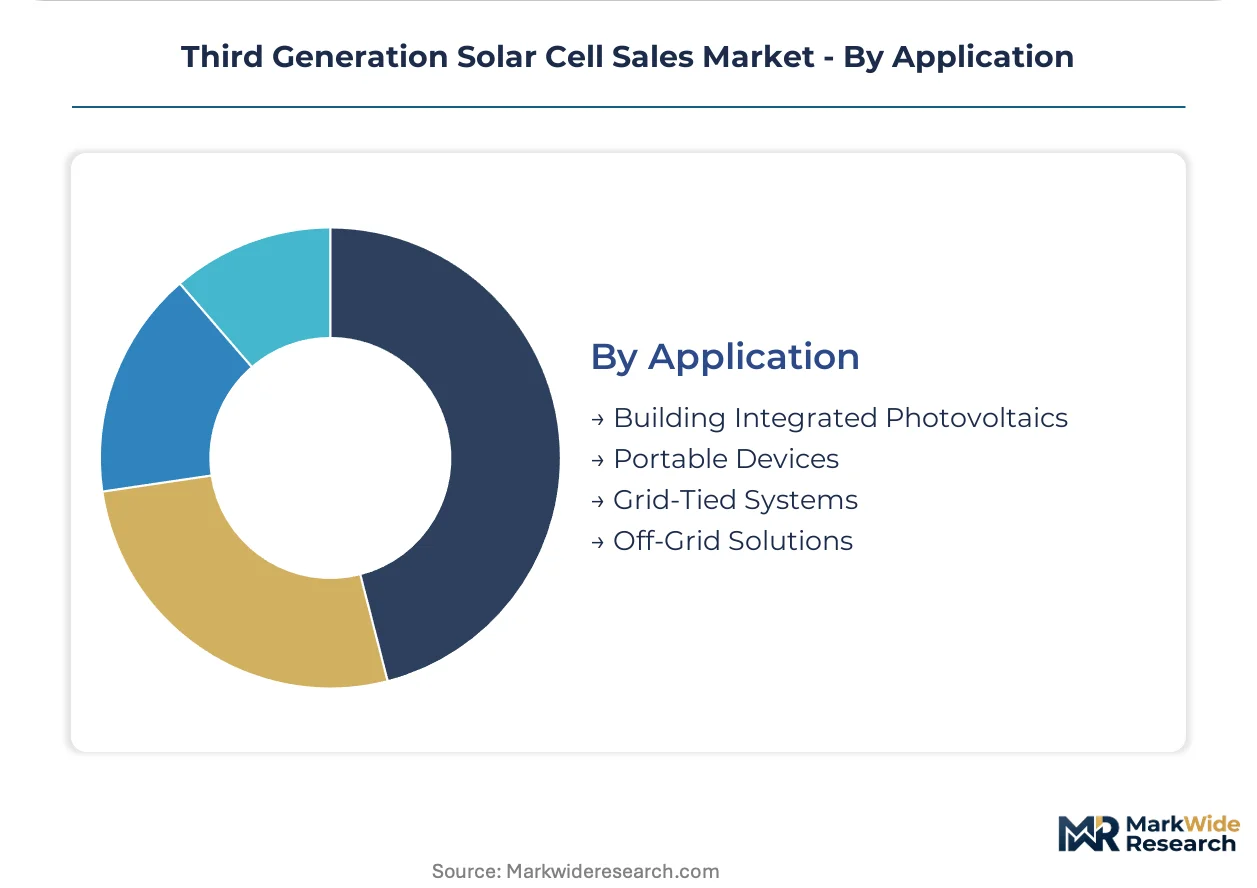
Application:
Integration context dictates form factor, electrical architecture, and value capture mechanism, with building-integrated deployments commanding architectural substitution premiums absent in commodity grid-tied supply.
- Building Integrated Photovoltaics:Semitransparent and colored modules replace conventional cladding materials in facades, skylights, and curtain walls. Bavaria's commercial building code amendments and Shanghai's industrial park mandates concentrate high-margin demand.
- Portable Devices:Lightweight flexible modules power consumer electronics, camping equipment, and emergency communication systems. Organic photovoltaic roll-to-roll production dominates mechanical flexibility requirements.
- Grid-Tied Systems:Utility-interconnected installations require inverter compatibility and grid code compliance. Crystalline silicon price compression from Chinese polysilicon oversupply narrows the effective cost window for third-generation alternatives.
- Off-Grid Solutions:Standalone power systems in remote locations prioritize reliability and minimal maintenance over capital cost minimization. Agrivoltaic dual-use deployment in Gujarat's horticulture belts applies semitransparent perovskite shading for photosynthesis-compatible structures.
Building Integrated Photovoltaics captures the highest margin per watt installed. Off-Grid Solutions are climbing the fastest as rural electrification programs accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as manufacturers relocate to jurisdictions with streamlined perovskite commercialization pathways and localized precursor supply chains. Cost-of-compliance gaps between REACH-regulated European markets and China's GB-standard environment are accelerating pilot line migration eastward.
China
MIIT's gigawatt-scale pilot line directive is concentrating domestic equipment vendor capacity around Shanghai and Yangzhou industrial corridors. The National Energy Administration's grid interconnection standards for perovskite modules are compressing commercialization timelines relative to European certification equivalents. Suzhou and Hefei clusters host the majority of domestic precursor material refining operations.
Germany
Bavaria's building code amendments mandating photovoltaic cladding on new commercial structures are generating captive BIPV demand for semitransparent organic modules. ECHA's REACH authorization procedures for lead-based perovskite formulations are creating compliance friction that advantages domestic lead-free research programs. Dresden and Leipzig industrial parks anchor specialized vacuum deposition equipment manufacturing.
India
MNRE's domestic content requirements for government-tendered solar parks are redirecting procurement toward locally assembled third-generation modules. Bureau of Indian Standards performance guarantee protocols are forcing adaptation of international encapsulation standards to tropical humidity conditions. Gujarat's horticulture belts are deploying semitransparent perovskite agrivoltaic structures around Anand and Vadodara.
United States
IRA advanced manufacturing production credits are anchoring domestic perovskite pilot line investments in Arizona and Texas. EPA efficiency certification protocols under Inflation Reduction Act implementation are creating parallel compliance tracks distinct from IEC frameworks. Greater Boston and Research Triangle Park clusters concentrate tandem cell research partnerships with national laboratory facilities.
Japan
METI's funding for flexible organic photovoltaic manufacturing is sustaining roll-to-roll production investments despite crystalline silicon price compression. JIS standards adaptation for building-integrated installations is creating technical barriers for imported module architectures. Osaka-Kobe industrial corridor hosts specialized barrier film lamination equipment suppliers serving regional encapsulation demand.
Third Generation Solar Cell Sales Market Competitive Landscape
Chinese producers anchor the scale-driven tier; European specialists hold premium BIPV and tandem architecture positions. The vendor base splits between integrated chemical conglomerates with precursor supply advantages and dedicated photovoltaic firms with solution-processing expertise. Three archetypes dominate: equipment-integrated material suppliers, architectural integration specialists, and research-stage technology licensors. Capacity expansion and strategic technology licensing represent the dominant competitive moves as firms seek to bridge laboratory efficiency demonstrations with bankable field performance.
Among European technology developers, Oxford Photovoltaics and Heliatek exemplify divergent commercialization strategies within the premium tier. Oxford Photovoltaics occupies a position anchoring tandem silicon-perovskite architecture development for utility-scale deployment. Heliatek sits within the flexible organic photovoltaic segment, representing roll-to-roll manufacturing approaches for building-integrated applications. Greatcell Solar, an Australian-registered entity, anchors the dye-sensitized specialization archetype targeting indoor and portable power harvesting niches where low-light efficiency metrics outweigh absolute power output.
| Leading Market Players |
|---|
| 3GSolar |
| Showa Denko |
| Greatcell Solar |
| PECCELL Technologies |
| Solaronix |
| Heliatek |
| Fujikura Ltd |
| Solaris Nanosciences |
| Oxford Photovoltaics |
| Others |
Pricing and Supply Chain Analysis
Solution-processed semiconductor fabrication specialists concentrated in Shanghai and Dresden drive labor-cost differentials that widen pricing-tier spreads between premium tandem architectures and economy organic modules. Perovskite-silicon dual-junction cells command architectural premiums in European utility contracts while roll-to-roll organic formulations compete on manufacturing throughput in Asian BIPV deployments.
Pricing Analysis
Distributor margins on third-generation modules compress as direct-to-OEM procurement teams in India and China negotiate volume discounts for gigawatt-scale pilot lines. Three-tier pricing structure across premium, standard, and economy levels separates IEC-certified tandem warranties from uncertified flexible substrates. Pricing pressure stems from crystalline silicon spot-market compression narrowing the effective cost window for perovskite alternatives. Utility-scale procurement teams exhibit lowest price sensitivity while residential rooftop installers face acute margin constraints.
Supply Chain Analysis
Reverse-logistics infrastructure for end-of-life perovskite recovery remains undeveloped, creating compliance liabilities under anticipated EU recycling mandates. Precursor material refining concentrates in China, South Korea, and Germany, with methylammonium iodide and lead halide salts drawing from chemical conglomerate supply chains. Single-source vulnerability pervades vacuum thermal evaporation equipment procurement from Japanese and German tool vendors. Distribution runs through specialized photovoltaic distributors serving EPC contractors and direct utility procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory mandate stacking, with Bavaria's BIPV building code amendments demonstrating how jurisdiction-specific deployment rules generate captive demand tiers.
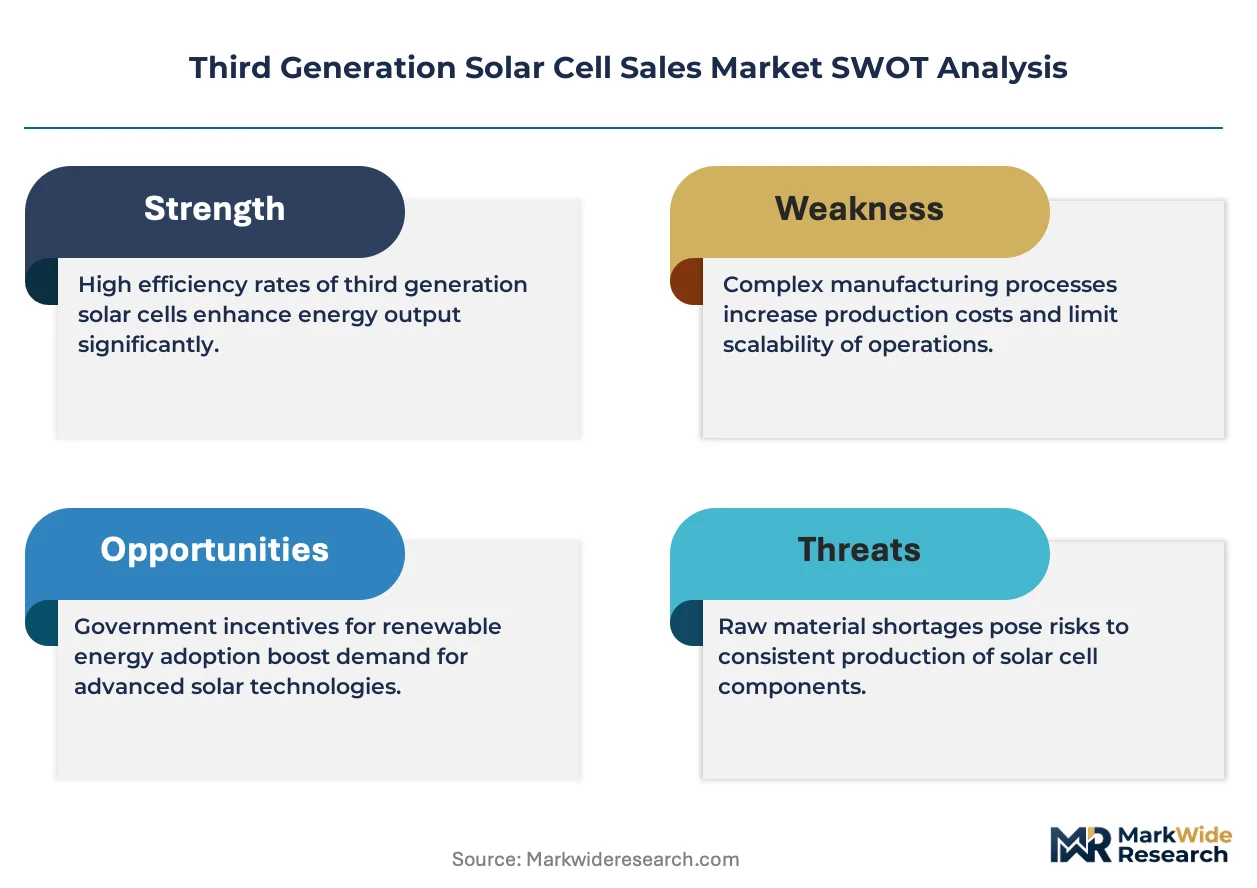
For Market Incumbents: Anchor bankability certification investments to outrun IEC 61215 adaptation timelines for perovskite-specific degradation modes. Defend against crystalline silicon price compression by deepening captive precursor supply through backward integration into Shanghai and Hefei chemical refining clusters. Prioritize encapsulation protocol R&D to extend field durability warranties beyond current 15-year benchmarks. For New Entrants and Emerging Players: The premium-to-economy tier price-point gap in Indian utility procurement creates white-space opportunity for domestically assembled modules meeting MNRE content requirements. Target Gujarat's agrivoltaic horticulture belts with semitransparent perovskite shading structures. Pursue textile lamination partnerships for wearable organic photovoltaic roll-to-roll production. For Investors and Strategic Acquirers: Chemical conglomerates with precursor supply advantages are the most active acquirer in this space, consolidating solution-processing expertise through technology licensing. Long-term viability hinges on which regulatory framework first mandates lead-free formulations or end-of-life material recovery. Monitor ECHA REACH authorization timelines for lead-based perovskite as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Perovskite Tandem Certification Investment | IEC 61215 adaptation unlocks project finance for utility-scale deployments in MNRE-tendered solar parks. |
| Backward Integration into Precursor Refining | Captive methylammonium iodide supply from Suzhou clusters insulates against South Korean chemical supplier pricing. |
| Flexible Substrate Roll-to-Roll Scale-Up | Textile lamination convergence enables wearable energy harvesting garments for Japanese METI-funded programs. |
| Agrivoltaic Dual-Use Deployment | Semitransparent shading structures penetrate Gujarat horticulture belts with photosynthesis-compatible configurations. |
| Lead-Free Formulation R&D | ECHA REACH compliance positioning captures European BIPV demand before authorization procedures tighten. |
Research Methodology
Multiple input streams — module procurement officers at Indian IPPs, deposition equipment vendors in Dresden and Osaka, and encapsulation film suppliers — were reconciled against customs records, MIIT pilot line disclosures, and FERC interconnection filings. Primary interviews with utility planning officers, EPC contractors, and BIPV facade engineers informed capacity expansion assumptions. Secondary validation drew from Bureau of Indian Standards performance protocols, ECHA REACH substance registrations, and Oxford Photovoltaics tandem cell efficiency disclosures. Bottom-up module shipment estimates and top-down renewable investment flow analysis were triangulated.
Historical deployment trajectories were cross-referenced against expert panel inputs from National Energy Administration officials and Bavarian building code enforcement teams. The analytical framework segmented across product chemistry, manufacturing process, deployment scale, and integration context throughout the forecast period. CAGRs were derived from logistic diffusion curves fitted to pilot line commissioning schedules and regulatory mandate implementation timelines. Key inputs included IRA manufacturing tax credit utilization rates and MIIT gigawatt-scale directive compliance trajectories.
Caveats apply where lead content regulatory shifts or polysilicon oversupply persistence could materially shift the outlook. Forecasts reflect assumptions on encapsulation durability improvements and certification timeline compression. Practitioners should monitor IEC 61215 adaptation completion and ECHA authorization rulings for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Carport Market
Solar Power Systems
Amorphous Silicon PV Market
Solar Power Systems
Rooftop Solar EPC Market
Solar Power Systems
Solar Panel Bracket Market
Solar Power Systems
Solar Panels for Home Market
Solar Power Systems
Hairy Solar Panels Market
Solar Power Systems
Building-Integrated Photovoltaic (BIPV) Skylights Market
Solar Power Systems
US Solar PV Market
Solar Power Systems
Solar Rack Market
Solar Power Systems
Single Axis Solar PV Tracker Market
Solar Power Systems
Solar Module Market
Solar Power Systems
Solar Cell Films Market
Solar Power Systems
Concentrated Photovoltaic System Market
Solar Power Systems
Residential Solar Inverter Market
Solar Power Systems
South America Solar Photovoltaic Market
Solar Power Systems
Dual Axis Solar Tracker Market